
 Global Smart Locomotive Market | 2026-2036
Global Smart Locomotive Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Locomotive Market Intelligence
China's state-backed expansion of domestic locomotive production capacity is reconfiguring the competitive landscape for established European and North American suppliers. CRRC Corporation Limited leverages its scale to dominate domestic and export markets in Asia and Africa. In contrast, Siemens Mobility GmbH differentiates through advanced signaling and automation systems integrated with its locomotives. Wabtec Corporation sustains its market position through a strong aftermarket and services portfolio in North America.
A smart locomotive incorporates onboard sensors and communication systems for real-time operational monitoring and control. Its core function is to optimize fuel efficiency, enable remote diagnostics, and enhance safety through systems like Positive Train Control (PTC). The technology stack is dominated by IoT integration and predictive maintenance algorithms. Freight transport applications constitute the largest market segment, driven by clear ROI from optimized asset utilization and reduced maintenance costs.
Mandates from the US Federal Railroad Administration (FRA) on Positive Train Control (PTC), the EU's Fourth Railway Package, and China's GB standards for railway equipment collectively define critical safety and interoperability requirements. These regulations create a baseline for digital system integration and market access. Future competitive advantage will depend on a vendor's ability to translate collected data into verifiable improvements in fleet efficiency and network capacity.
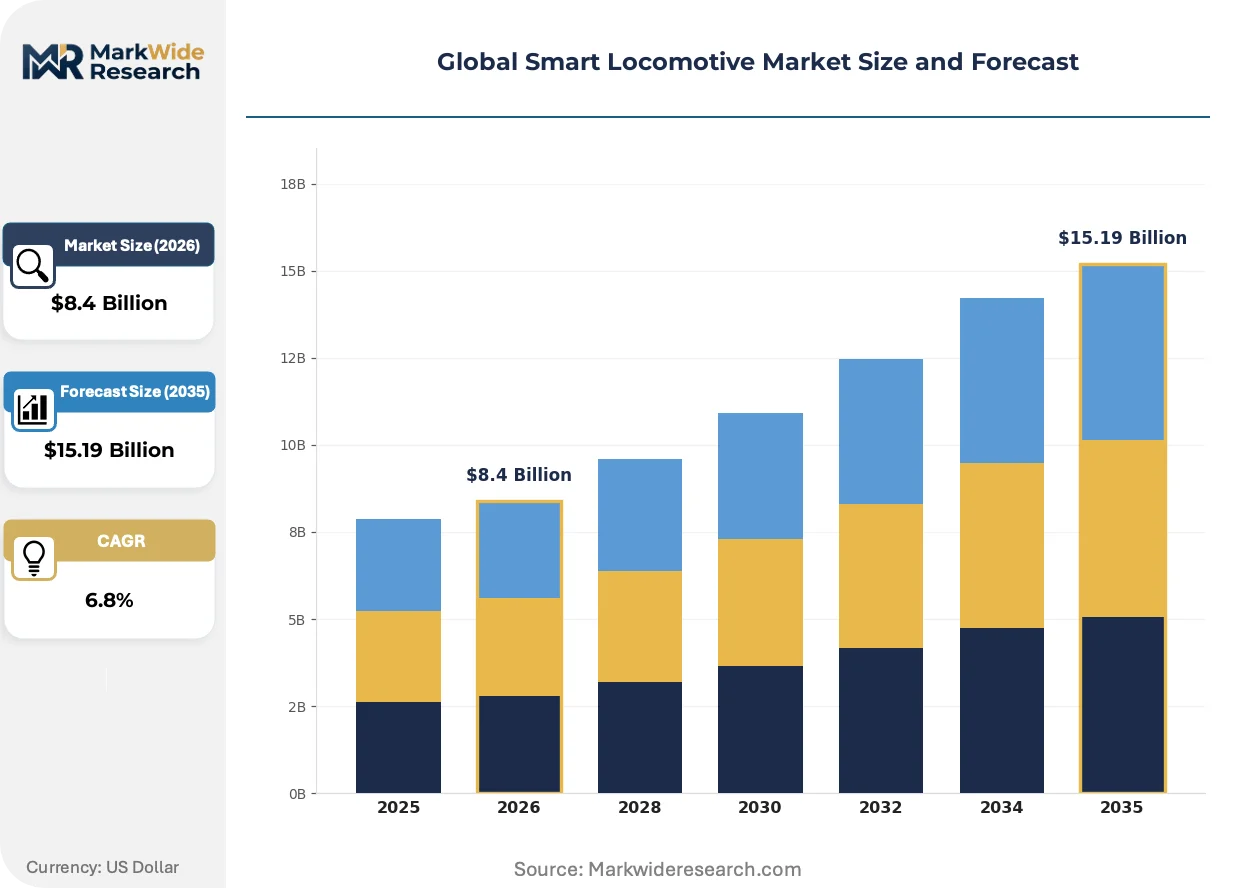
Market Dynamics
The convergence of IoT connectivity with stringent safety regulations defines the market's core tension. This dual pressure compels investment in digital systems for both operational efficiency gains and mandatory compliance with standards set by bodies like the US Federal Railroad Administration.
Growth Catalysts
- Regulatory Mandates:Requirements like the US Federal Railroad Administration's Positive Train Control (PTC) rules compel operators to invest in digital control and communication systems to enhance safety, creating a baseline demand for smart technology.
- Freight Efficiency Imperatives:The freight transport sector's focus on reducing fuel consumption and optimizing asset utilization provides a strong business case for adopting AI-based control systems and remote diagnostics, which deliver measurable ROI.
- National Infrastructure Projects:Large-scale railway modernization and expansion programs, particularly in China under its GB standards, create sustained, high-volume demand for new locomotives equipped with advanced digital capabilities.
Market Restraints
- High Capital Outlay:The significant upfront investment required to purchase new smart locomotives or to retrofit existing fleets with complex digital systems presents a major financial barrier for many rail operators, particularly smaller firms.
- Legacy System Integration:Integrating modern IoT platforms with decades-old signaling infrastructure and non-standardized mechanical systems creates substantial technical complexity and cost overruns across a network.
- Long Asset Lifecycles:Locomotives have operational lifespans of several decades, which slows the rate of fleet renewal and the adoption of new smart technologies compared to industries with shorter asset replacement cycles.
Strategic Opportunities
- Autonomous Train Operation (ATO):Developing higher grades of automation, moving toward fully autonomous operation in controlled environments like freight yards or dedicated lines, offers a new frontier for value creation.
- Decarbonization Technologies:Integrating smart controls with alternative propulsion systems, such as hydrogen fuel cells or battery-electric power, provides a path to capture demand driven by environmental regulations and corporate sustainability goals.
- Service Model Innovation:Shifting from equipment sales to offering data-driven maintenance and fleet optimization as a service creates recurring revenue streams and deeper customer relationships, particularly in markets like North America.
Industry Challenges
- Cybersecurity Vulnerabilities:Protecting increasingly connected and remotely controlled locomotives from cyber threats is a critical operational challenge, requiring specialized expertise to prevent safety incidents and service disruptions.
- Data Standardization and Ownership:A lack of universal standards for data formats and communication protocols among different manufacturers and rail operators hinders network-wide interoperability and creates disputes over data ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Locomotive Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Locomotive, Diesel-Electric Locomotive, Battery-Electric Locomotive, Hybrid Locomotive Technology: IoT Integration, Predictive Maintenance, AI-Based Control, GPS Tracking, Remote Diagnostics Application: Freight Transport, Passenger Transport, Mining Operations, Military Logistics End User: Railway Operators, Cargo Carriers, Mining Companies, Defense Agencies |
| Companies Covered | Wabtec Corporation, Stadler Rail AG, CRRC Corporation Limited, Hyundai Rotem Company, Kawasaki Heavy Industries Ltd., Siemens Mobility GmbH, Hitachi Rail Ltd., Bharat Heavy Electricals Limited, Alstom SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Locomotive Market Strategic Shifts & Innovations
A fundamental shift in value is occurring within the smart locomotive sector, moving from mechanical power toward software-defined performance and data analytics. This transition redefines how operational efficiency and asset lifecycle value are measured and achieved.
Onboard edge computing systems provide real-time processing of sensor data for immediate control adjustments and fault prediction. Freight rail operators are the primary adopters, seeking to optimize fuel burn and reduce in-field failures. Consequently, the source of competitive advantage is migrating from purely mechanical engineering excellence to the sophistication of a locomotive’s predictive algorithms and software stack.
The EU's Fourth Railway Package aims to create a single European railway area by harmonizing technical and safety rules. This legislation streamlines the process for authorizing locomotives for cross-border operation, reducing administrative burdens and costs for manufacturers. Freight operators in Europe are most affected, gaining flexibility to deploy unified fleets across multiple national networks.
Rail operators are increasingly favoring full-service leasing and availability-based contracts over direct capital purchases. This model transfers asset lifecycle and maintenance risks to the manufacturer, disrupting the traditional one-time sales channel. This preference for performance-guaranteed contracts is most visible in the North American Class I railroad market, where fleet uptime is paramount.
Global Smart Locomotive Market Segmentation
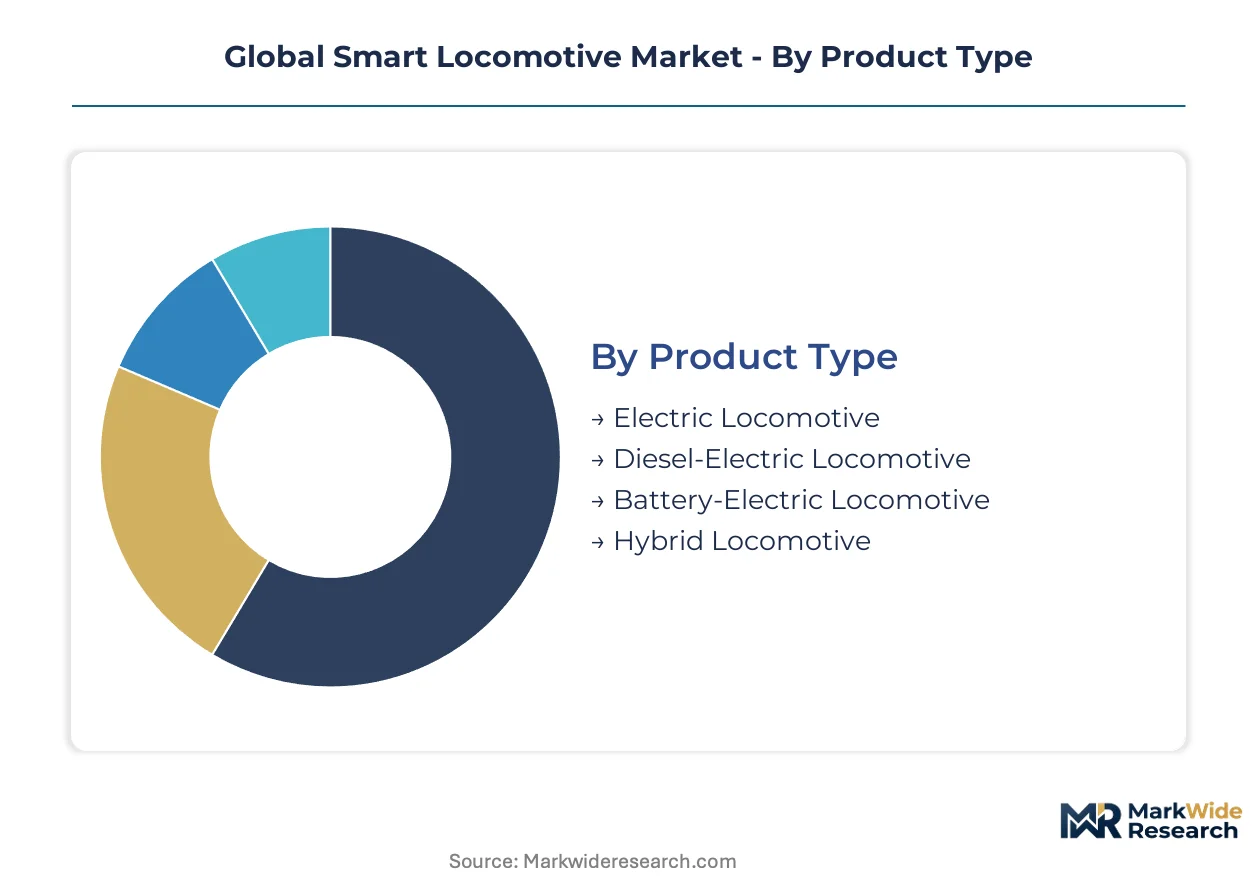
Segmentation within the smart locomotive market categorizes diverse offerings and applications, revealing where innovation is most impactful. Understanding these distinctions helps stakeholders identify areas of concentrated demand and technological advancement. This analysis dissects the market across key dimensions.
Product Type:
Product types reflect varying development cycles, from mature diesel-electric systems to rapidly evolving battery-electric solutions. The lifespan of these core locomotive platforms dictates the pace of technological integration and fleet renewal strategies.
- Diesel-Electric Locomotive:These locomotives combine a diesel engine with an electric generator, providing power to traction motors. Freight transport in North America and Australia heavily relies on these workhorses for their robust power and range.
- Electric Locomotive:Electric locomotives draw power from overhead lines or a third rail, offering zero-emission operation at the point of use. European and Chinese high-speed passenger networks extensively utilize these for their efficiency and speed.
- Battery-Electric Locomotive:These locomotives operate purely on battery power, targeting short-haul freight and shunting operations in emissions-sensitive areas.
- Hybrid Locomotive:Hybrid systems integrate diesel engines with batteries, optimizing fuel efficiency and reducing emissions during varied operational profiles.
Diesel-Electric Locomotive anchors the volume base while Battery-Electric Locomotive gains share at the steepest rate.
Technology:
Technology segmentation highlights the specific digital functionalities integrated into smart locomotives, ranging from foundational connectivity to advanced decision-making algorithms. These distinct technological layers address varied operational needs across the railway ecosystem.
- IoT Integration:This technology embeds sensors and communication modules for real-time data collection and exchange with central systems. Freight operators across China prioritize IoT for remote diagnostics and asset tracking.
- AI-Based Control:Artificial intelligence algorithms optimize locomotive performance, including fuel consumption and traction control, based on real-time conditions. European rail networks are increasingly deploying AI for enhanced operational efficiency and predictive scheduling.
- Predictive Maintenance:This system uses data analytics to forecast equipment failures, enabling proactive servicing and minimizing unplanned downtime.
- GPS Tracking:Global Positioning System technology provides precise location data for fleet management, route optimization, and safety compliance.
- Remote Diagnostics:This capability allows technicians to monitor locomotive health and identify issues from a central location, reducing field service costs.
IoT Integration forms the foundational layer, while AI-Based Control offers the most advanced operational gains.
Application:
Application segments categorize smart locomotive usage by the scale and nature of transport tasks, from high-volume freight to specialized military logistics. Each segment presents unique demands for power, automation, and ruggedness.
- Freight Transport:This segment involves moving goods over long distances, demanding high tractive effort and fuel efficiency from locomotives. North American Class I railroads are primary adopters, seeking optimized asset utilization and reduced operational costs.
- Passenger Transport:This application focuses on moving people, prioritizing speed, comfort, and precise scheduling with advanced signaling integration. European high-speed rail networks represent a significant market for smart passenger locomotives.
- Mining Operations:Locomotives in mining environments handle heavy loads over short distances, often in harsh conditions, requiring robust and specialized designs.
- Military Logistics:This niche application demands secure, reliable, and adaptable locomotives for transporting equipment and personnel in diverse operational theaters.
Freight Transport consistently drives the largest market volume, while Passenger Transport applications show consistent technological advancement.
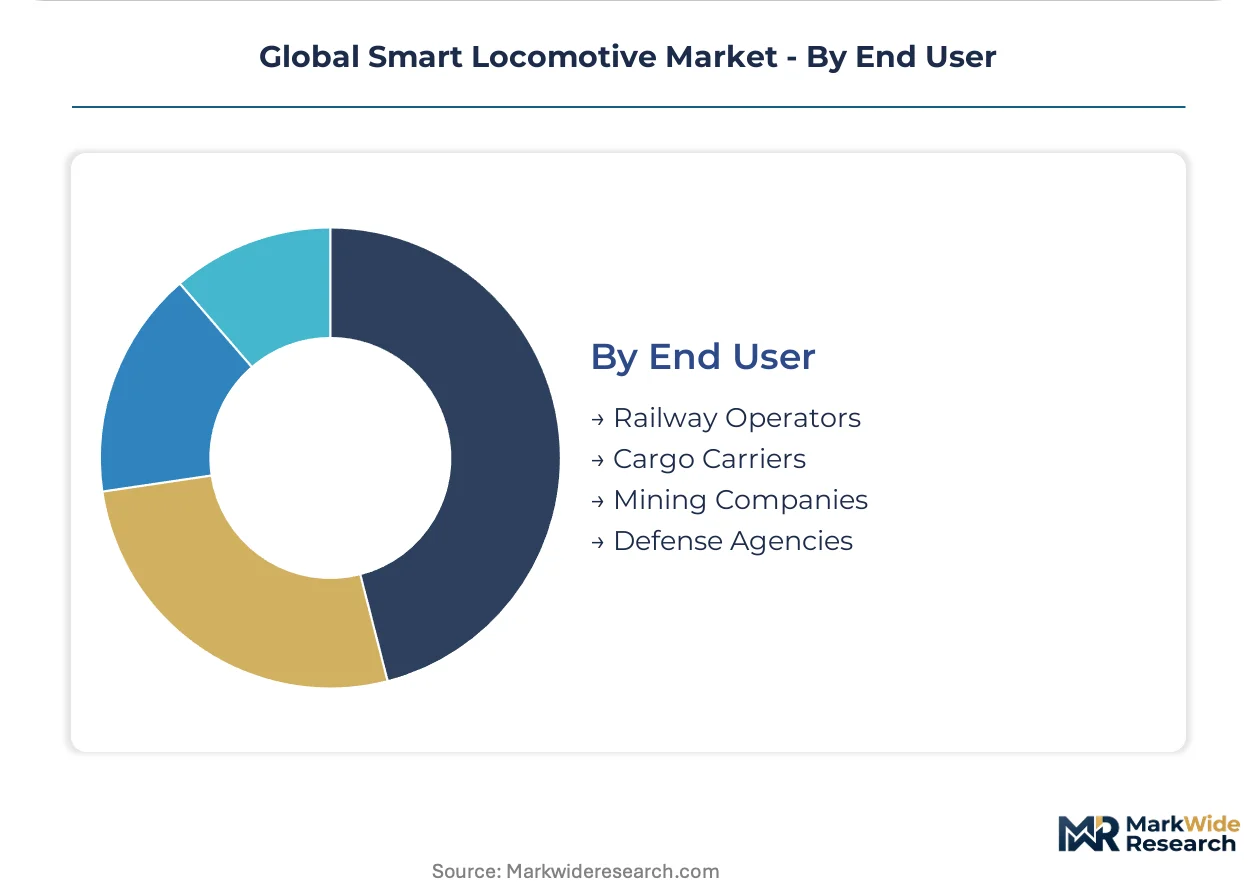
End User:
End-user categories differentiate smart locomotive purchasers based on their primary business models and operational priorities. These distinct customer groups influence product specifications, service requirements, and procurement strategies.
- Railway Operators:These entities manage and operate railway infrastructure and rolling stock for both freight and passenger services. China Railway and Deutsche Bahn are key examples, investing in smart fleets for network-wide efficiency.
- Cargo Carriers:Specialized companies focused solely on freight movement utilize smart locomotives to enhance supply chain predictability and reduce transit times. Major logistics firms in the United States increasingly demand advanced telematics for their rail assets.
- Mining Companies:These companies acquire smart locomotives for internal transport of raw materials within their mining sites, prioritizing durability and operational safety.
- Defense Agencies:Government defense departments procure specialized smart locomotives for strategic logistics and secure transport of military assets.
Railway Operators represent the largest customer base, with Cargo Carriers demonstrating strong demand for advanced digital features.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extensive rail networks underpin global smart locomotive market expansion, with modernization initiatives driving significant demand. Freight and passenger rail operators seek advanced solutions for efficiency and safety. This demand spans established and rapidly developing economies.
China
China's vast railway network modernization program drives substantial smart locomotive demand. The Ministry of Industry and Information Technology (MIIT) supports domestic production capacity through its GB standards. Cities like Zhuzhou in Hunan Province serve as manufacturing hubs for CRRC Corporation Limited, producing locomotives for domestic and export markets.
United States
Freight transport efficiency imperatives generate significant demand for smart locomotives in the United States. Mandates from the US Federal Railroad Administration (FRA) on Positive Train Control (PTC) compel digital system integration. North American Class I railroads, concentrated around major freight corridors, prioritize solutions for optimized asset utilization.
Germany
European railway infrastructure upgrades stimulate smart locomotive procurement in Germany. The EU's Fourth Railway Package streamlines authorization for cross-border operations, influencing design specifications. Siemens Mobility GmbH, with facilities in Munich, differentiates through advanced signaling and automation systems integrated with its locomotives.
India
India's ambitious railway expansion and electrification projects create sustained smart locomotive demand. The Ministry of Railways' 'Make in India' initiative promotes local manufacturing and technology transfer. Production facilities in Varanasi, Uttar Pradesh, contribute significantly to domestic locomotive supply for Indian Railways.
Australia
Heavy-haul freight operations across Australia's vast distances necessitate robust smart locomotive solutions. The Australian Rail Track Corporation (ARTC) focuses on network efficiency and safety upgrades. Mining regions in Western Australia rely on specialized designs for transporting bulk commodities, driving localized demand.
Global Smart Locomotive Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing critical digital and mechanical subsystems. The market exhibits a tiered structure, with a few large global players dominating integrated solutions. Strategic archetypes include diversified industrial conglomerates and specialized rail technology providers. Dominant competitive moves involve strategic partnerships for technology integration and portfolio diversification into service-based models.
At the scale-driven end, CRRC Corporation Limited, a Chinese state-backed entity, exemplifies a vertically integrated model, leveraging its domestic market base for global expansion. Siemens Mobility GmbH, a German industrial giant, occupies a position in advanced signaling and automation, differentiating its smart locomotive offerings. Wabtec Corporation, a US-based firm, represents a strong aftermarket and services portfolio, particularly in North America, sustaining its market presence through lifecycle support.
| Leading Market Players |
|---|
| Wabtec Corporation |
| Stadler Rail AG |
| CRRC Corporation Limited |
| Hyundai Rotem Company |
| Kawasaki Heavy Industries Ltd. |
| Siemens Mobility GmbH |
| Hitachi Rail Ltd. |
| Bharat Heavy Electricals Limited |
| Alstom SA |
| Others |
Cost & Logistics Intelligence
Single-source dependency for advanced digital components determines both pricing tier spreads and the geographic concentration of smart locomotive supply chains. This vulnerability influences how manufacturers structure their partnerships and where they source critical technology.
Pricing Analysis
Volume-discount tiering structures characterize smart locomotive pricing, particularly for large fleet purchases by national railway operators. Pricing models primarily involve contract-based long-term offtake, often bundling equipment with extensive after-sales service and maintenance. Customization levels for specific network requirements and advanced digital features drive price differentiation. Pricing softness stems from the high capital outlay and long asset lifecycles, pushing demand towards performance-guaranteed contracts; smaller rail operators exhibit the highest price sensitivity.
Supply Chain Analysis
Single-source vulnerability for advanced digital systems dominates the smart locomotive supply chain, particularly for high-performance AI-based control modules. Supply concentrates in countries like China, Germany, and the United States, reflecting the presence of major integrated manufacturers. The production of specialized digital components and heavy-duty steel represents key dependencies. Distribution runs primarily through direct sales channels to national railway operators and freight carriers, with an increasing shift towards performance-based service models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
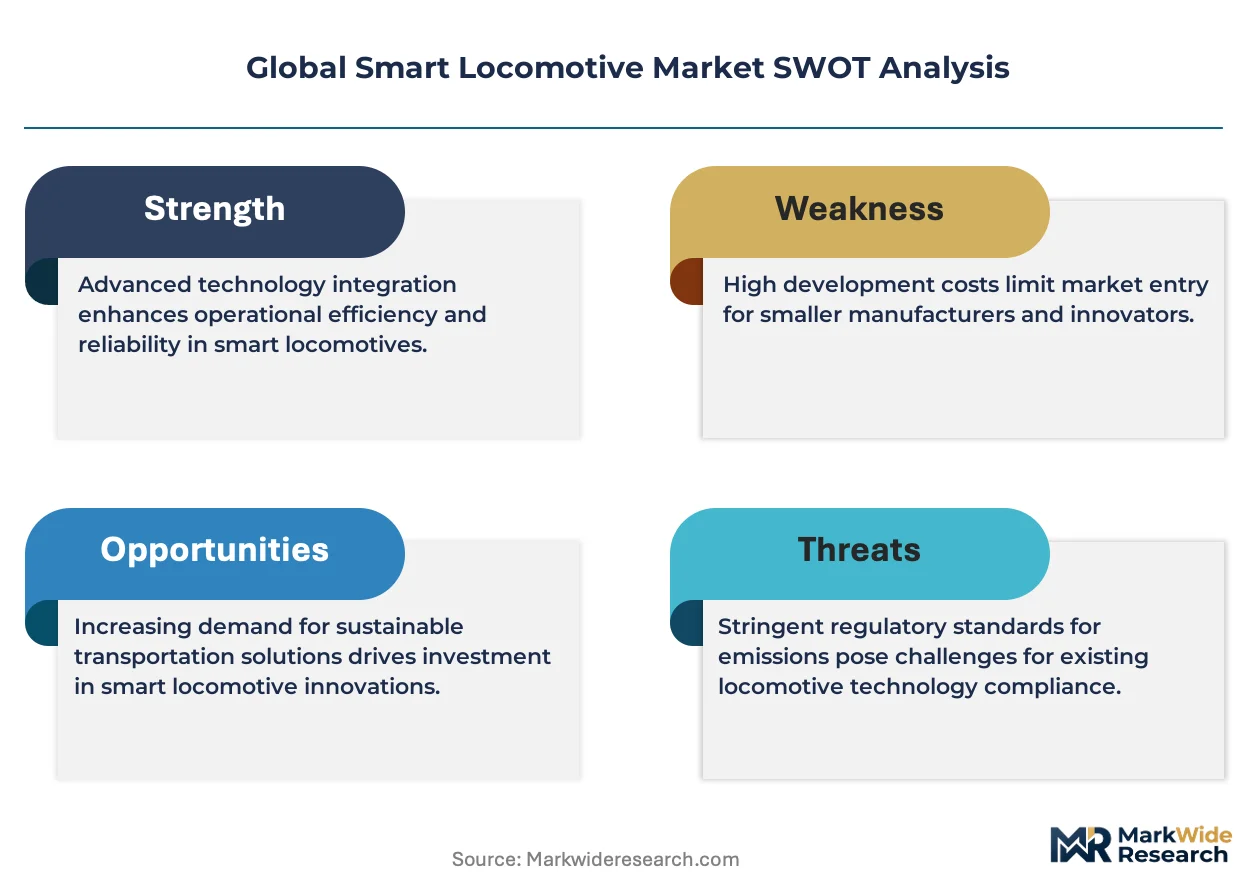
The smart locomotive market represents a high-growth disruption, driven by the convergence of IoT connectivity and stringent safety regulations. This inflection point compels significant investment in digital systems for both efficiency and compliance.
For Market Incumbents:
Build ecosystem moats by deeply integrating advanced signaling and automation systems with core locomotive platforms. Incumbents should expand their aftermarket and services portfolios, particularly in North America, to counter margin pressure from new digital technology specialists. Investing in AI-based control R&D and securing certifications for cross-border operations in Europe reinforces competitive positioning. This strategy mitigates threats from regulatory shifts towards decarbonization and interoperability.
For New Entrants and Emerging Players:
Build out specialized autonomous train operation (ATO) solutions for controlled environments like freight yards or mining operations. New entrants should target the short-haul freight and shunting segments with battery-electric locomotive solutions, addressing emissions-sensitive areas. A strong go-to-market angle involves offering data-driven maintenance and fleet optimization as a service, leveraging advanced predictive algorithms. This approach allows penetration into underserved niches with high ROI potential.
For Investors and Strategic Acquirers:
The market sits at a modernization phase that favors technology-centric consolidators with deep digital integration capabilities. Long-term viability over the next decade is strong, driven by sustained demand for operational efficiency and decarbonization across global rail networks. Acquisition targets should focus on specialized software providers for AI-based control and advanced component manufacturers for IoT integration. The adoption rate of higher automation grades, particularly in freight, serves as a critical signal to watch for accelerated market transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI-based Predictive Maintenance | Enhances fleet uptime for North American Class I railroads. |
| Develop Battery-Electric Locomotive Platforms | Captures demand from environmental regulations in European urban centers. |
| Secure Cross-Border Interoperability Certifications | Facilitates wider deployment of unified fleets across EU networks. |
| Expand Data-as-a-Service Offerings | Creates recurring revenue streams for global railway operators. |
| Form Partnerships for Cybersecurity Solutions | Protects connected locomotives from increasing cyber threats. |
Research Approach
A standing panel of railway operators, locomotive manufacturers, signaling system integrators, and freight logistics managers provided ongoing calibration. This approach combined primary interviews with extensive secondary validation. Secondary data sources included national railway administration reports, industry association publications, and manufacturer annual reports. Bottom-up and top-down triangulation ensured robust market sizing and trend analysis.
Scenario-bracketing established the forecast framework, accounting for varying levels of technological adoption and regulatory enforcement across the analysis window. The model segmented demand by product type, technology, application, end user, and regional infrastructure development. Compound annual growth rates derived from historical trends and projected investment levels. Key forecast inputs included railway network expansion plans and regulatory compliance schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed entities or disruptive tech firms would shift outcomes. Forecasts reflect assumptions regarding sustained infrastructure investment and regulatory stability; unforeseen geopolitical events or rapid shifts in global energy policy represent key risk factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Train Locomotive Suspension Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Global Hyperloop Train Market
Railway
Railway Overhead Catenary System Market
Railway
Railway Rolling Stock Market
Railway
Railway Horn Market
Railway
Automatic Train Supervision Market
Railway
Railway Automated Inspection Equipment Market
Railway
Light Rail Market
Railway
Rail Freight Slot and Path Optimization Platforms Market
Railway
Freight Wagon Market
Railway
Europe 40-Foot Platform Wagons Market
Railway
Sanitary Systems for Rail Transit Market
Railway
Train Suspension System Market
Railway
Automatic Train Control Market
Railway
France Rail Freight Transport Market