
 Corrosion Protective Coatings and Acid Proof Lining Market | 2026-2036
Corrosion Protective Coatings and Acid Proof Lining Market Size, Share, and Industry Trends Forecast 2026-2036
Corrosion Protective Coatings and Acid Proof Lining Market Analysis
Maintenance and recoating service contracts is expanding as a recurring revenue layer that shifts capital expenditure into operational budgets for asset owners. PPG Industries, Inc. leverages its protective and marine coatings portfolio to anchor long-term service agreements with offshore platform operators. Hempel A/S specializes in high-performance epoxy systems for chemical tank linings, sustaining technical credibility in aggressive acid environments. Akzo Nobel N.V. competes through its Intershield and Interzone product lines, dominating European marine and offshore maintenance cycles.
Corrosion protective coatings and acid proof lining comprise polymer-based barrier systems—epoxy, polyurethane, phenolic, or zinc-rich formulations—applied to steel, concrete, or composite substrates to prevent electrochemical degradation and chemical attack from acids, alkalis, and solvents. These systems typically achieve dry film thicknesses of 250–1000 microns and cure through ambient or heat-accelerated crosslinking to form impermeable membranes that extend asset service life in process industries. Epoxy coatings lead the product type landscape due to their adhesion strength and chemical resistance, while polyurethane coatings represent the fastest-growing category as flexibility requirements expand in thermal cycling applications. Chemical processing occupies the most entrenched end user position, though power generation is gaining share as flue gas desulfurization units require upgraded acid-resistant linings.
EPA standards under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based coating formulations in the United States, pushing manufacturers toward waterborne and high-solids alternatives. REACH registration requirements and the EU Green Deal's industrial emissions directives in Europe mandate disclosure of substance hazards, reshaping raw material sourcing for coating producers serving cross-border markets. India's BIS certification for corrosion protection materials adds a compliance layer for imports into its expanding refinery and chemical sectors. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance costs in one geography increasingly determine competitive viability in adjacent markets.
Market Dynamics
REACH compliance deadlines and EPA volatile organic compound thresholds are compressing formulation cycles, forcing coating producers to rebuild supply chains around waterborne chemistries while maintaining performance parity with legacy solvent systems.
Growth Catalysts
- Flue gas desulfurization retrofits:Coal plant scrubber upgrades across the United States and India mandate acid-resistant lining replacement cycles, sustaining demand for high-build epoxy phenolic systems in power generation.
- REACH substance disclosure mandates:ECHA registration requirements for corrosion inhibitors are accelerating raw material substitution toward bio-based alternatives, opening procurement channels for European formulators with certified green chemistry portfolios.
- Gujarat petrochemical corridor expansion:Refinery capacity additions and LNG terminal construction along India's western coast are shortening asset maintenance intervals, concentrating lining demand in high-throughput sulfuric acid handling facilities.
Market Restraints
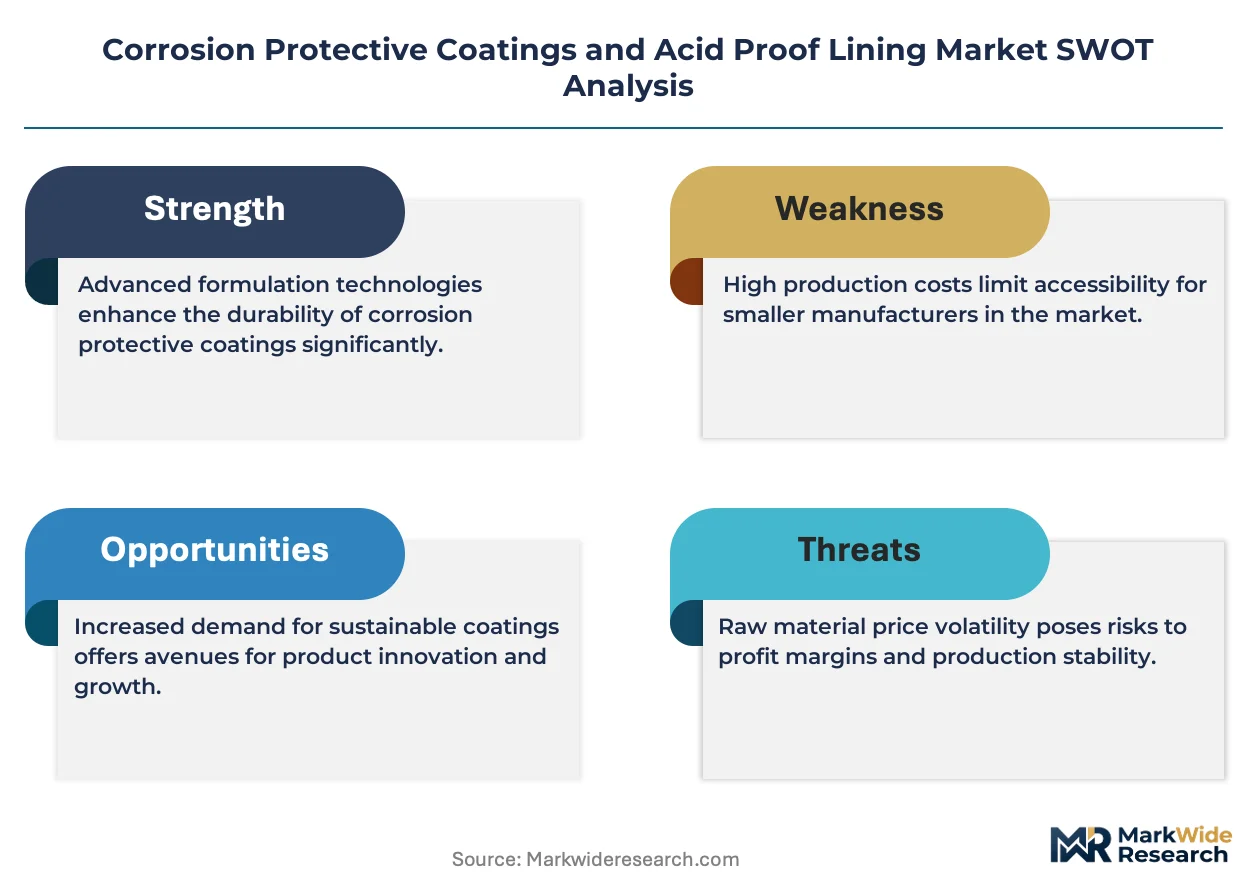
- Zinc raw material volatility:Zinc-rich primer formulations face input cost instability tied to concentrate supply disruptions from Australian and Peruvian mining operations, compressing margin predictability for protective coating manufacturers.
- Solvent-based formulation lock-in:Heavy industrial end-users in marine and offshore segments resist waterborne system transitions due to ambient cure reliability concerns in high-humidity environments, slowing regulatory compliance adoption.
- Polyurea spray substitution threat:Rapid-setting polyurea elastomers are displacing conventional epoxy tank linings in secondary containment applications, eroding addressable market for traditional acid proof systems in chemical storage.
Strategic Opportunities
- Carbon capture infrastructure:Amine-based CO2 absorption units require novel lining materials resistant to amine degradation and thermal cycling, creating specification white space for fluoropolymer-modified epoxy developers.
- EU Green Deal industrial emissions directives:Carbon border adjustment mechanisms and embodied carbon disclosure requirements are advantaging European coating producers with verified lifecycle data, creating procurement preference in cross-border chemical facility projects.
- Drone-enabled coating inspection:Ultrasonic thickness monitoring via unmanned aerial vehicles is unbundling maintenance contracts from application services, enabling predictive recoating models that shift revenue toward data-driven advisory fees.
Industry Challenges
- NACE coating inspector certification scarcity:Qualified inspectors for high-performance lining quality assurance are concentrated in mature markets, creating project execution bottlenecks for contractors expanding into India's refinery sector.
- Surface preparation capex intensity:Sa 2.5 blast cleaning specifications for offshore platform recoating require specialized containment and vacuum recovery equipment, elevating mobilization costs for maintenance service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrosion Protective Coatings and Acid Proof Lining Market |
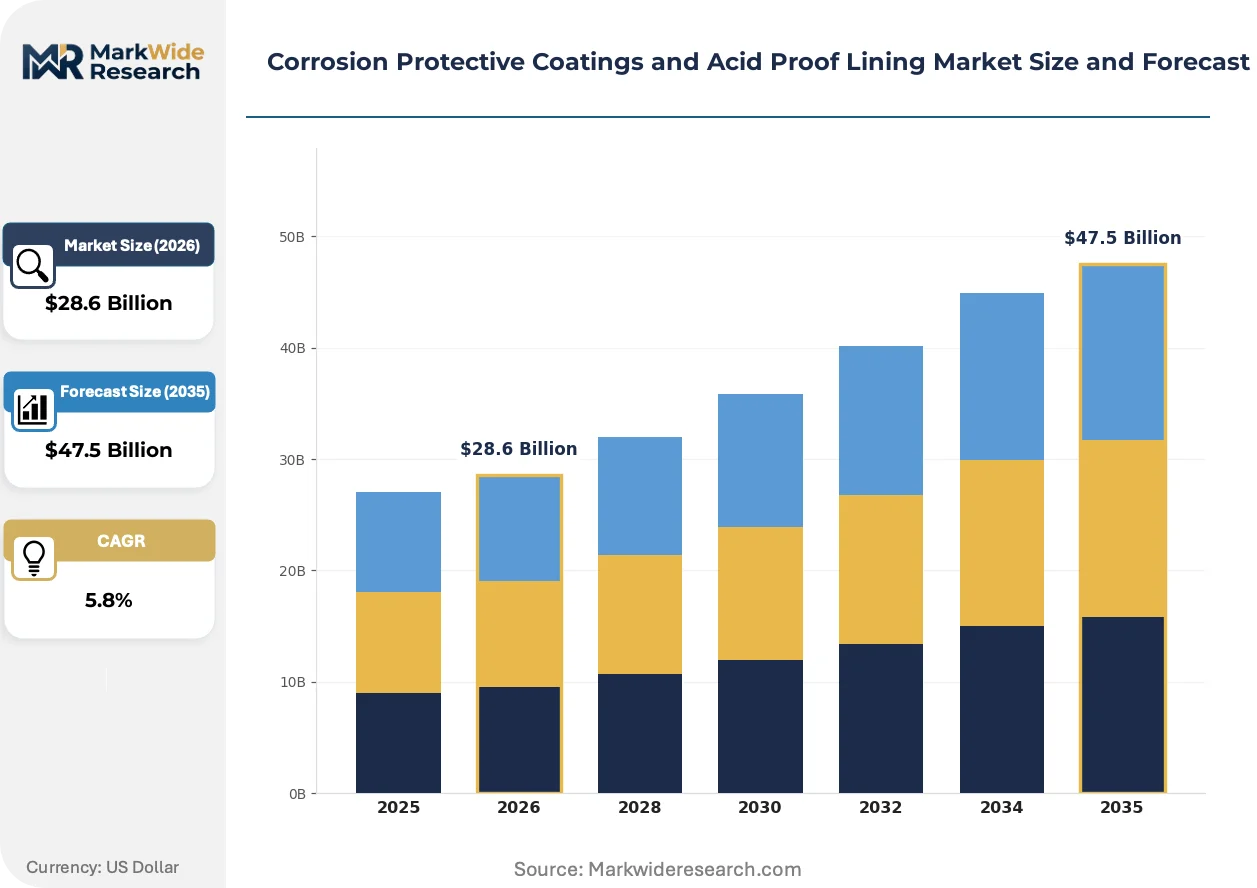
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Coatings, Polyurethane Coatings, Zinc Coatings, Phenolic Coatings End User: Chemical Processing, Oil & Gas, Marine, Power Generation Application: Industrial Equipment, Storage Tanks, Piping Systems, Infrastructure Technology: Spray Application, Brush Application, Roller Application, Electrostatic Application |
| Companies Covered | Akzo Nobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Hempel A/S, Jotun A/S, RPM International Inc., Carboline Company, Chugoku Marine Paints, Ltd., Tnemec Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrosion Protective Coatings and Acid Proof Lining Market Emerging Trajectories
Formulation chemistry and application methodology are converging around sustainability mandates and predictive asset management, compressing the traditional separation between material supply and lifecycle service provision.
Hybrid epoxy-silicate nanocomposite coatings are unifying barrier protection and self-healing functionality in single-layer systems. Chemical tank operators in the Netherlands and Belgium are piloting these materials for sulfuric acid storage vessels. The technology is unifying previously separate repair and prevention budget lines into unified asset integrity contracts.
EPA National Emission Standards for Hazardous Air Pollutants are constraining solvent-based coating use in marine drydocks and offshore fabrication yards. Formulators are accelerating high-solids and waterborne platform coating development to maintain shipyard qualification status. Gulf Coast fabricators are responding by consolidating procurement around suppliers with dual-chemistry portfolios and EPA Method 24 compliance documentation.
Asset owners are compressing recoating decision cycles through real-time corrosion monitoring embedded in lining systems. Offshore platform operators in the North Sea are displacing calendar-based maintenance with condition-triggered interventions. This behavioral shift is most visible in Norwegian and UK continental shelf assets where sensor-integrated linings now anchor performance-based service agreements.
Corrosion Protective Coatings and Acid Proof Lining Market Segmentation
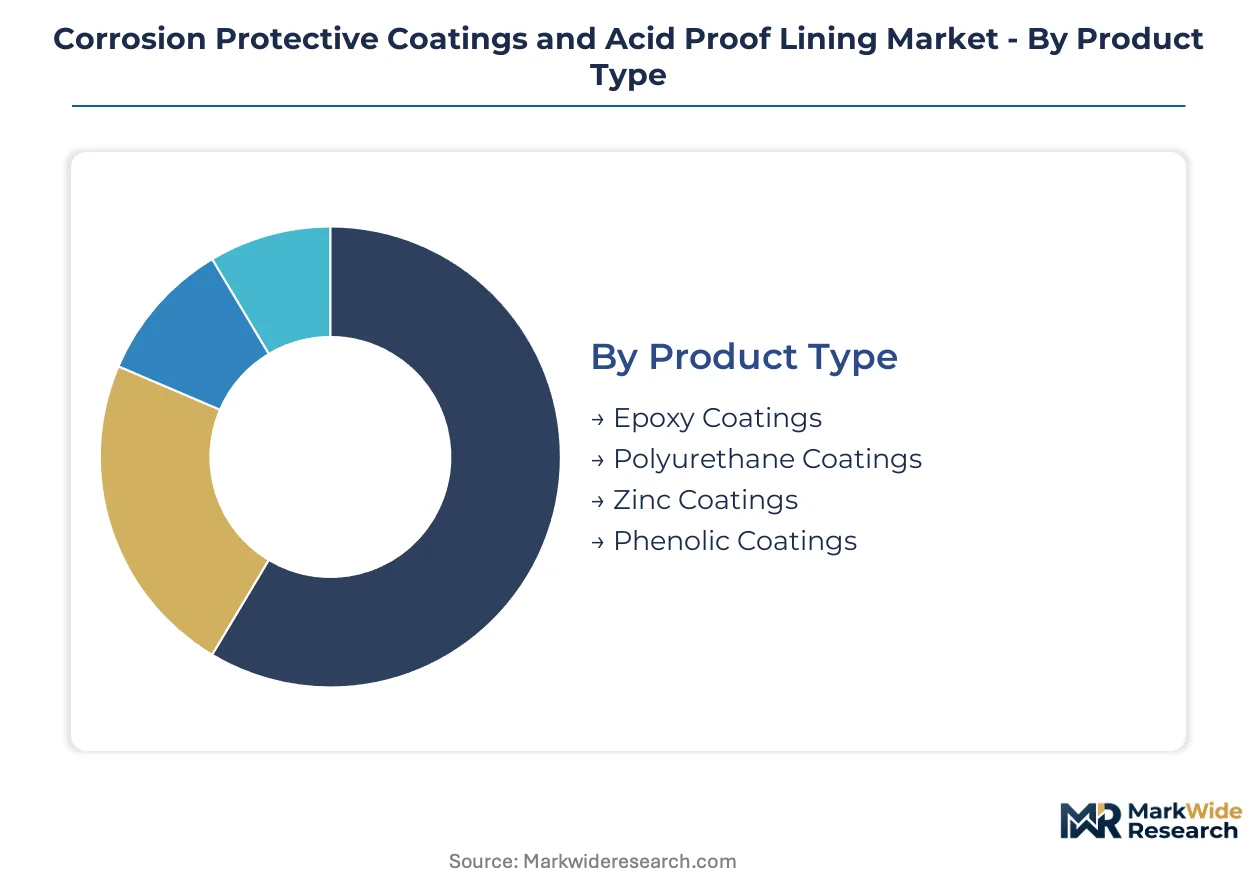
Corrosion protective coatings and acid proof lining markets fragment across material chemistry, end-use severity, and application methodology. Each segmentation axis carries distinct margin profiles and technical certification requirements that determine supplier positioning.
Product Type:
Volume concentrates in commodity epoxy formulations while premium pricing attaches to specialized systems with enhanced chemical resistance or thermal cycling performance.
- Epoxy Coatings:These two-component thermosetting systems achieve 250-1000 micron dry film thickness through amine or polyamide curing mechanisms. Chemical processing facilities in Gujarat's petrochemical corridor specify high-build epoxy phenolic variants for sulfuric acid storage vessels, driven by refinery capacity expansion and shortened maintenance intervals.
- Polyurethane Coatings:Aliphatic and aromatic polyurethane formulations deliver elastomeric flexibility for substrates undergoing thermal expansion. Power generation flue gas desulfurization units across the United States and India specify these systems for scrubber internals, where temperature cycling between ambient and 180°C demands crack-resistant barrier films.
- Zinc Coatings:Inorganic zinc silicate primers provide sacrificial cathodic protection for steel substrates in marine atmospheres.
- Phenolic Coatings:Acid-cured phenolic resins offer solvent resistance for tank linings handling aggressive hydrocarbons.
Mature deployment sits with epoxy systems. Newer deployment is concentrated in polyurethane formulations for thermal cycling applications.
End User:
Application severity determines specification grade, with immersion service in concentrated acids commanding the highest performance tiers and inspection protocols.
- Chemical Processing:Sulfuric acid, hydrochloric acid, and caustic soda handling facilities require lining systems resistant to pH extremes and solvent permeation. India's western coast refinery expansions and Netherlands-Belgium chemical tank terminals sustain demand for certified high-build systems with NACE-compliant application protocols.
- Oil & Gas:Offshore platform splash zones, subsea pipelines, and refinery process vessels demand coatings combining corrosion inhibition with mechanical abrasion resistance. North Sea operators are shifting toward sensor-integrated linings that enable condition-based maintenance under performance-based service agreements.
- Marine:Ballast tanks, cargo holds, and deck structures require coatings meeting IMO PSPC standards for saltwater immersion.
- Power Generation:Coal plant scrubber upgrades and amine-based carbon capture units require acid-resistant linings for flue gas desulfurization.
Specification authority concentrates with chemical processing. Fastest specification evolution is occurring in power generation as carbon capture infrastructure expands.
Application:
Access constraints and surface area geometry dictate application methodology selection, with confined space entry requirements elevating project costs for certain substrate categories.
- Industrial Equipment:Reactors, heat exchangers, and processing vessels require lining systems applied under controlled humidity and temperature conditions. Chemical plant turnaround schedules in the United States Gulf Coast compress application windows, favoring rapid-cure formulations that minimize production downtime.
- Storage Tanks:Aboveground and underground tank bottoms, shells, and roofs demand seamless membrane systems resistant to product-side chemical attack and soil-side corrosion. Hybrid epoxy-silicate nanocomposite coatings are piloting in Netherlands and Belgium facilities to unify barrier protection with self-healing functionality.
- Piping Systems:Internal diameter limitations and elbow geometries complicate spray application uniformity.
- Infrastructure:Bridges, wastewater treatment facilities, and marine piles require high-durability external protection.
Asset criticality peaks with storage tanks. Technical innovation is concentrating in industrial equipment as predictive maintenance models advance.
Technology:
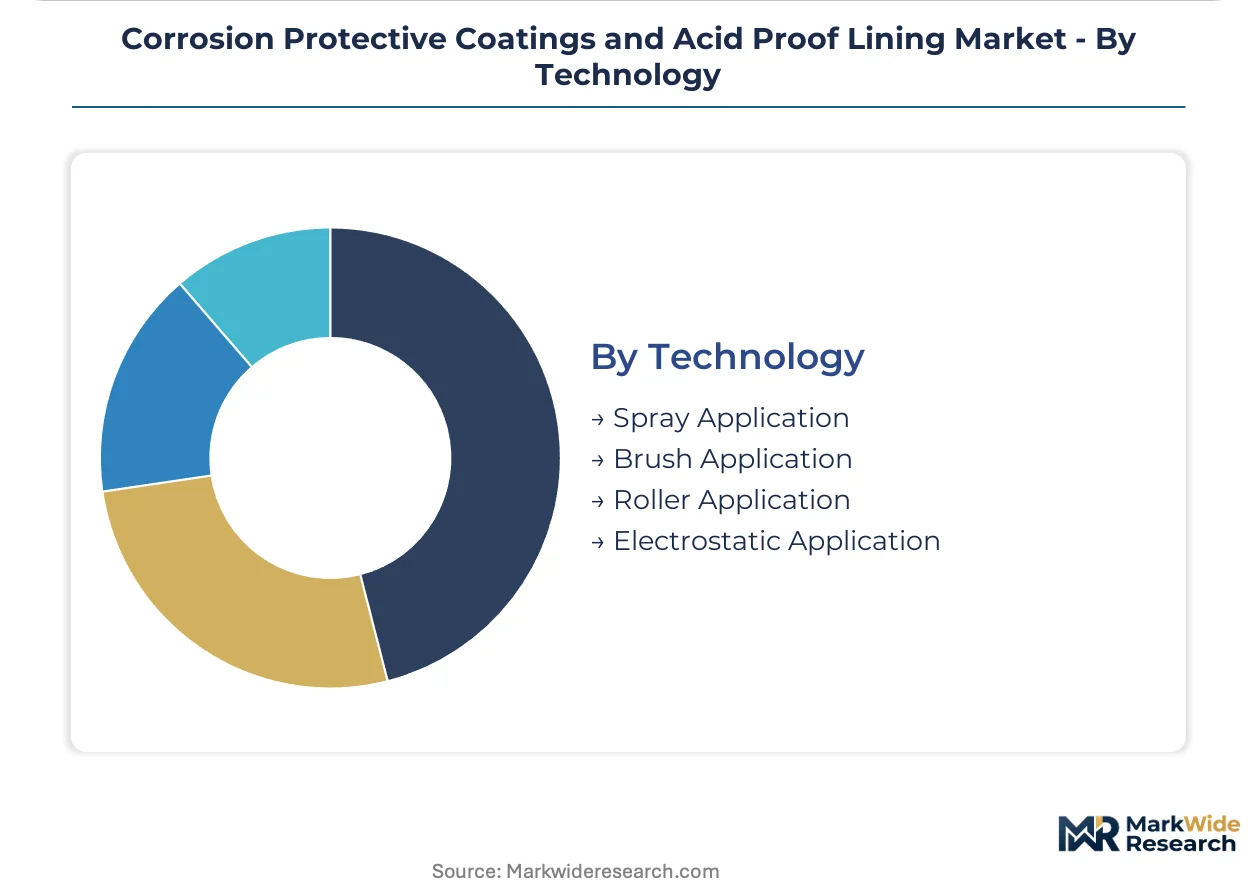
Capital investment in application equipment and operator certification creates tiered service provider capabilities that segment contract award patterns.
- Spray Application:Airless and conventional spray systems achieve high build rates for large surface areas, with plural-component proportioning equipment enabling on-site mixing of reactive chemistries. EPA National Emission Standards for Hazardous Air Pollutants are constraining solvent-based spray operations in United States marine drydocks, accelerating waterborne system qualification.
- Brush Application:Manual stripe coating and touch-up work addresses complex geometries and repair scenarios where spray masking is impractical.
- Roller Application:Large flat surfaces in tank bottoms and containment areas utilize roller systems for economical material deposition.
- Electrostatic Application:Charged particle deposition achieves uniform coverage on conductive substrates with minimal overspray.
Field-proven reliability sits with spray systems. Regulatory compliance investment is concentrating in electrostatic and automated alternatives as VOC thresholds tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Western Europe and East Asia, while consumption concentrates in industrializing coastal zones with heavy process industry investment. Regulatory divergence between REACH-compliant European suppliers and EPA-constrained American formulators shapes cross-border trade patterns. India's western petrochemical corridor emerges as the fastest-growing demand center as refinery expansions compress maintenance cycles.
United States
Coal plant scrubber retrofits and offshore platform maintenance sustain demand for high-build epoxy phenolic systems. EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-based formulations in Gulf Coast marine drydocks, accelerating waterborne chemistry qualification. Houston-Galveston petrochemical complexes and Louisiana refineries anchor procurement volume for acid-resistant tank linings.
Germany
Chemical processing facilities along the Rhine corridor require certified lining systems for sulfuric acid and aggressive solvent handling. ECHA REACH registration mandates for corrosion inhibitors accelerate raw material substitution toward bio-based alternatives. BASF's Ludwigshafen complex and Bayer's Leverkusen operations exemplify specification authority for high-performance coating systems.
India
Refinery capacity additions and LNG terminal construction along the Gujarat coast shorten asset maintenance intervals. BIS certification for corrosion protection materials adds compliance layers for imports into expanding chemical sectors. Dahej, Hazira, and Jamnagar industrial zones concentrate demand for high-throughput sulfuric acid handling facility linings.
China
Dual carbon goals and industrial emissions standards reshape coating procurement toward low-VOC formulations in coastal manufacturing zones. MIIT regulations on hazardous substance disclosure tighten supply chain transparency for cross-border chemical facility projects. Yangtze River Delta petrochemical clusters and Shandong refinery complexes drive specification volume for immersion-grade barrier systems.
Netherlands
Antwerp-Rotterdam-Amsterdam chemical tank terminals sustain demand for certified high-build systems with NACE-compliant application protocols. EU Green Deal industrial emissions directives advantage domestic producers with verified lifecycle data in cross-border procurement. Rotterdam port infrastructure and Zeeland refinery operations pilot hybrid epoxy-silicate nanocomposite coatings with self-healing functionality.
Corrosion Protective Coatings and Acid Proof Lining Market Vendor Landscape
Top-tier vendors anchor premium specification authority, while mid-scale formulators compete on regional compliance agility and service contract bundling. The vendor base stratifies across integrated multinationals with marine certification portfolios, specialized epoxy developers for chemical immersion service, and regional applicators with inspection capabilities. Three archetypes dominate: chemistry innovators with proprietary resin systems, service-integrated contractors with predictive maintenance platforms, and compliance-focused suppliers with jurisdiction-specific certification libraries. Competitive moves concentrate on portfolio diversification into carbon capture lining specifications and geographic expansion through drone-enabled inspection service networks.
Among European-headquartered multinationals, Akzo Nobel N.V., PPG Industries, Inc., and Hempel A/S exemplify distinct strategic positioning within the protective coatings segment. Akzo Nobel represents the diversified chemistry portfolio archetype with broad marine and industrial reach. PPG occupies a position emphasizing service-integrated long-term agreements with asset owners. Hempel exemplifies the specialized high-performance systems approach for aggressive chemical environments. These three entities collectively anchor the premium tier where specification authority determines contract award patterns across North Sea offshore assets and European chemical processing facilities.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Hempel A/S |
| Jotun A/S |
| RPM International Inc. |
| Carboline Company |
| Chugoku Marine Paints, Ltd. |
| Tnemec Company, Inc. |
| Others |
Supply Flow & Price Mechanics
Zinc concentrate price indices on the London Metal Exchange cascade through corrosion coating supply chains, compressing margin structures for zinc-rich primer manufacturers while amplifying pricing power for epoxy resin formulators with backward-integrated feedstock positions. Raw material volatility concentrates cost pressure on sacrificial protection tiers, forcing specification-grade suppliers to decouple pricing from commodity cycles through performance-based service contracts.
Pricing Analysis
Margin tightening in zinc-rich formulations reflects concentrate supply disruptions from Australian and Peruvian mining operations. Three-tier pricing structure across immersion-grade, atmospheric, and sacrificial protection tiers separates NACE-certified application protocols from standard industrial grades. Cost compression accelerates in marine segments as EPA Method 24 compliance documentation becomes mandatory for Gulf Coast drydock qualification. Chemical processing buyers exhibit lowest price sensitivity due to asset-criticality, while infrastructure contractors face acute budget constraints.
Supply Chain Analysis
Skilled applicator shortages in Germany and the Netherlands constrain high-performance lining deployment capacity during peak turnaround seasons. Resin production concentrates in Germany, China, and the United States, with epoxy hardener supply anchored in Asian manufacturing zones. Formulation chemistry draws from petrochemical feedstocks and bio-based alternatives undergoing REACH registration scrutiny. Single-source vulnerability sits with amine curing agents from concentrated Asian suppliers. Distribution runs through authorized applicator networks with NACE inspector certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into drone-enabled inspection services and predictive maintenance platforms is reshaping competitive positioning, as asset owners unbundle recoating decisions from application-only contracts. Incumbents and challengers alike must secure lifecycle data capabilities to anchor performance-based agreements.
For Market Incumbents: Anticipate polyurea spray substitution in secondary containment by accelerating fluoropolymer-modified epoxy development for carbon capture specifications. Defend specification authority through captive supply of NACE-certified inspection talent in India's Gujarat corridor. Prioritize backward integration into bio-based resin feedstocks to neutralize REACH-driven raw material substitution costs. For New Entrants and Emerging Players: Digital coating inspection platforms offer the most penetrable entry vector, enabling predictive recoating models that shift revenue toward advisory fees without heavy application asset bases. Target India's Dahej and Hazira industrial zones where BIS certification barriers filter out established European competitors. Lead with drone-enabled thickness monitoring bundled with maintenance scheduling software. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European formulators with verified EU Green Deal lifecycle data in Germany and the Netherlands. Long-term viability hinges on carbon capture lining specification authority and cross-border procurement preference in EU chemical facility projects. Watch amine-based CO2 absorption unit deployment rates as inflection signal for fluoropolymer-modified epoxy demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Resins | Neutralizes REACH registration costs for European formulators serving cross-border chemical projects. |
| Drone-Enabled Inspection Service Launch | Unbundles maintenance contracts from application services in North Sea offshore platform markets. |
| Carbon Capture Lining Specification Development | Captures white space in amine-resistant systems for thermal cycling CO2 absorption units. |
| NACE Certification Capacity Buildout | Resolves inspector scarcity bottlenecks constraining project execution in India's refinery sector. |
| Waterborne Chemistry Portfolio Expansion | Maintains shipyard qualification status under EPA National Emission Standards for Hazardous Air Pollutants. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving plant managers at chemical processing facilities, procurement leads at downstream refineries, distribution channel partners, and technical R&D directors at coating formulators. Bottom-up volume estimates from application-grade consumption patterns were triangulated against top-down value projections derived from maintenance contract disclosures and capital expenditure tracking across the analysis window.
Segmentation granularity extended to chemistry type, end-use severity tier, application methodology, and regional regulatory cluster, with CAGRs derived from regression analysis of historical replacement cycle data and projected capacity additions. Forecast inputs incorporated flue gas desulfurization retrofit schedules, refinery expansion timelines, and evolving VOC threshold compliance trajectories across jurisdictions.
The model holds under stable zinc concentrate supply and sustained REACH enforcement intensity; deviation in mining output disruptions or regulatory postponement would shift coating substitution patterns and margin structures. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market
Coatings
Polyurethane Powder Coatings Market
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
Global UV-Cured Coatings Market
Coatings
South Korea Marine Coatings Market
Coatings
Conductive Polymer Coatings Market
Coatings
Anti-Corrosion Nanocoatings Market
Coatings
Global Graphite Coatings Market
Coatings
Marking Coatings Market
Coatings
Europe Anti-Friction Coatings Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
Asia-Pacific Anti-Friction Coatings Market
Coatings
Polysiloxane Coatings Market
Coatings
Hull Coatings Market
Coatings
Germany Automotive OEM Coatings Market
Coatings
Canada Protective Coatings Market