
 Global Antiviral Coatings Market | 2026-2036
Global Antiviral Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antiviral Coatings Market Foresight
Direct distribution to healthcare procurement consortiums is narrowing as group purchasing organizations consolidate vendor panels across integrated delivery networks. PPG Industries leverages its architectural coatings infrastructure to sustain specification relationships with major hospital systems. Akzo Nobel N.V. competes through marine and protective coatings expertise that it extends into clinical-grade antimicrobial finishes. Nano-Care Deutschland AG anchors its position in Central European renovation contracts with silicone-based surface treatments.
Antiviral coatings constitute functional surface treatments engineered with biocidal active agents, typically metallic ions or photocatalytic compounds, that disrupt viral envelope proteins or nucleic acid replication upon contact; these formulations are manufactured through sol-gel processes or dispersion techniques that embed copper, silver, or titanium dioxide at concentrations sufficient to achieve logarithmic reduction in viral titer without compromising substrate adhesion. Metallic formulations dominate current specification volumes in healthcare infrastructure, while nanocomposite architectures command premium positioning due to dual-mode antiviral and mechanical durability performance. Polymer-based systems occupy the broadest addressable base across commercial building retrofits where cost-per-square-foot constraints govern procurement decisions.
The EPA in the United States regulates antiviral coating claims under FIFRA pesticide registration requirements, while the EU Biocidal Products Regulation mandates active substance approval through ECHA, creating divergent compliance pathways that fragment product portfolios across Atlantic markets. Japan's METI oversees industrial chemical safety assessments that constrain import formulations lacking JIS-standard toxicity documentation. Stakeholders must monitor evolving regulatory reciprocity agreements between EPA and ECHA frameworks to determine whether unified testing protocols will emerge or dual-registration costs will permanently bifurcate competitive positioning.
Market Dynamics
Post-pandemic building code hardening across OECD healthcare infrastructure is compressing specification cycles for certified biocidal surface treatments, forcing coating formulators to synchronize R&D pipelines with regulatory approval timelines rather than traditional construction procurement rhythms.
Growth Catalysts
- EPA FIFRA Registration Pathway:Accelerated review protocols for copper-ion formulations are compressing time-to-market for US healthcare infrastructure tenders.
- Photocatalytic Titanium Dioxide:Self-activating nanocomposite architectures are displacing passive metallic ion systems in high-touch transit environments.
- German Federal Infection Prevention Mandates:Hospital renovation cycles in North Rhine-Westphalia and Bavaria are specifying certified antiviral finishes as standard cladding.
Market Restraints
- Silver Price Volatility:Precious metal feedstock fluctuations are compressing margin structures for ion-exchange coating producers.
- Dual-Registration Burden:Divergent EPA FIFRA and ECHA BPR compliance pathways are fragmenting product portfolios across Atlantic markets.
- UV-C Disinfection Substitution:Room-scale ultraviolet sterilization systems are capturing specification share in ambulatory surgical centers.
Strategic Opportunities
- Indian Healthcare Infrastructure:Greenfield hospital construction under the Ayushman Bharat scheme is creating first-mover positioning for certified coating suppliers.
- Aviation Cabin Retrofit Cycles:IATA hygiene certification standards are mandating antiviral surface treatments for premium seating and galley surfaces.
- EU Green Deal Biocidal Reform:REACH authorization streamlining for low-toxicity active substances is reducing regulatory friction for silicone-based formulations.
Industry Challenges
- Formulation-Certification Synchronization:ECHA active substance approval timelines often misalign with hospital construction schedules, forcing speculative inventory positions.
- Legacy Substrate Compatibility:Sol-gel application chemistry requires surface preparation protocols that conflict with existing healthcare facility maintenance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antiviral Coatings Market |
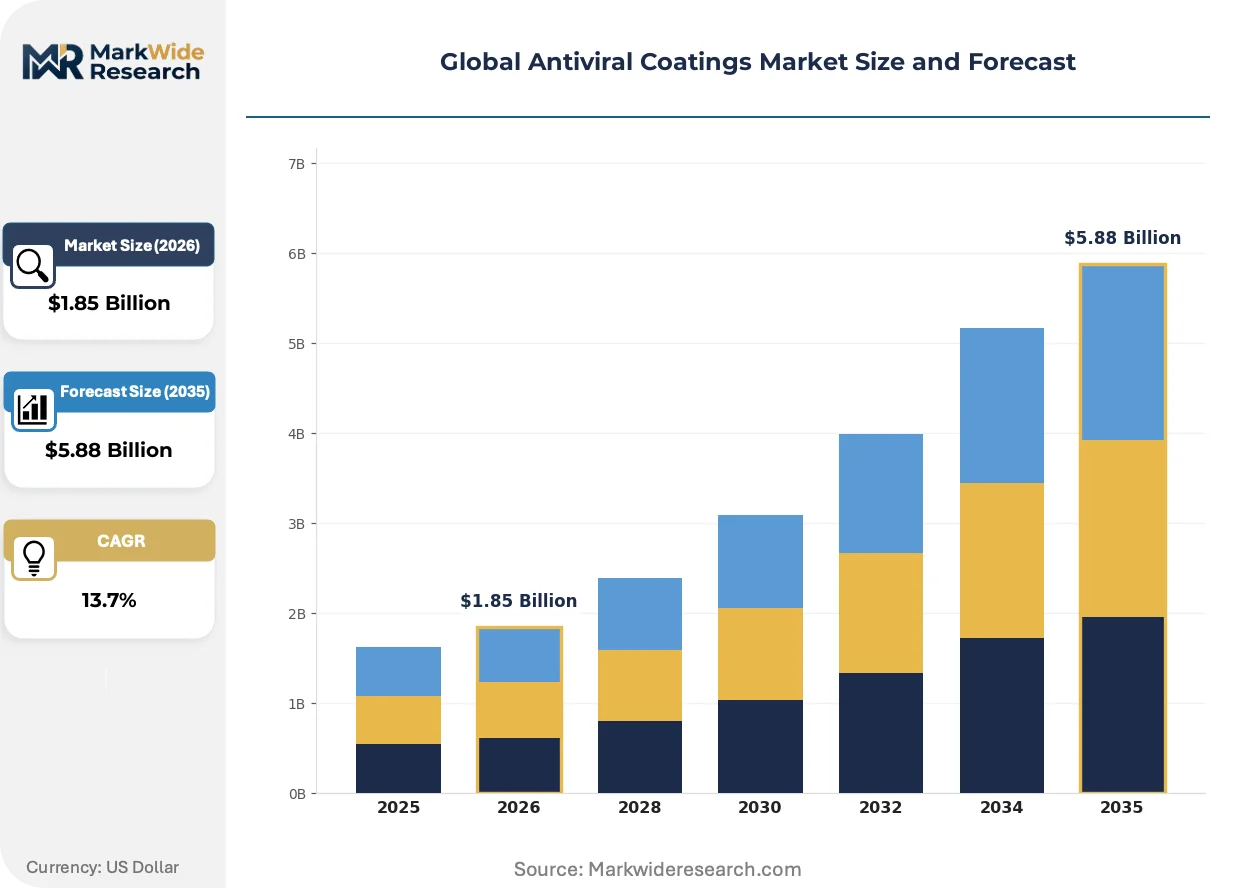
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic, Polymer-Based, Photocatalytic, Nanocomposite, Silicone Technology: Silver Ion, Copper Ion, Titanium Dioxide, Quaternary Ammonium, Zinc Oxide Application: Healthcare Facilities, Commercial Buildings, Public Transport, Educational Institutions, Food Processing End User: Hospitals, Corporate Offices, Transit Authorities, Schools, Food Manufacturers |
| Companies Covered | GrapheneCA, BioFence, Nano-Care Deutschland AG, Nippon Paint Holdings Co., Ltd., Arkema, Akzo Nobel N.V., PPG Industries, Sherwin-Williams, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antiviral Coatings Market Shifts & Advancements
Surface engineering is pivoting from passive biocidal leaching toward active mechanistic disruption, with formulation science converging on materials that combine viral envelope rupture with substrate durability.
Photocatalytic nanocomposite architectures incorporating titanium dioxide and doped metal oxides are achieving dual-mode antiviral action through ROS generation and physical surface disruption. Japanese rail operators and Singaporean airport authorities are specifying these systems for high-frequency touchpoint retrofits. The technology is digitizing specification workflows by enabling real-time efficacy monitoring through integrated sensor substrates.
ECHA's 2024 biocidal product regulation amendments are tightening acceptable toxicity thresholds for silver-ion leaching in clinical environments. Formulators are reformulating toward copper-zinc alloys and quaternary ammonium compounds to maintain registration eligibility. German and French hospital procurement consortiums are now requiring REACH-compliant certification as a mandatory bid qualification.
Group purchasing organizations across US integrated delivery networks are consolidating vendor panels from twelve to three approved coating suppliers per category. Architectural specification firms are losing influence to infection control committees with direct biocidal efficacy requirements. This concentration is most pronounced in Texas and Florida hospital systems where renovation volumes exceed national averages.
Global Antiviral Coatings Market Segmentation
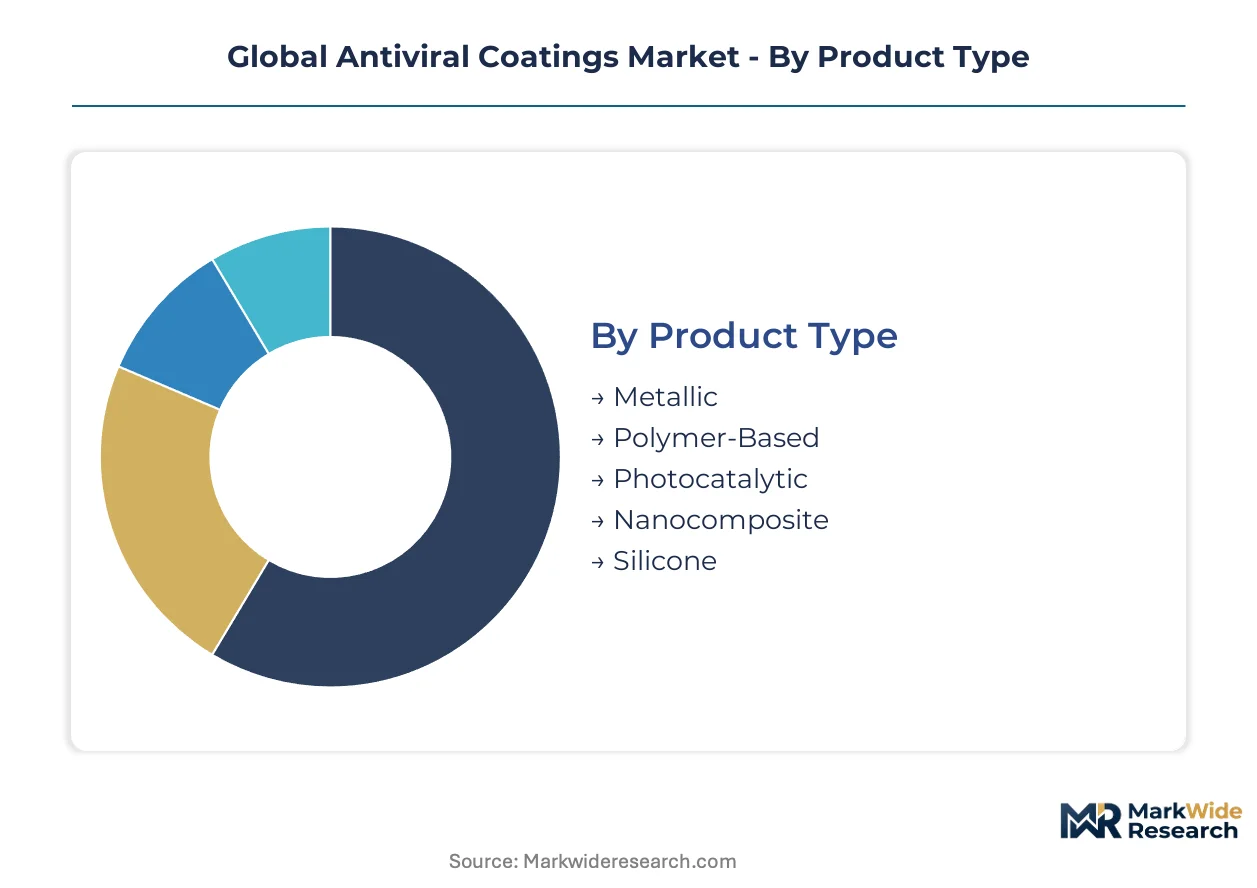
Segmentation in antiviral coatings reveals how formulation chemistry, activation mechanisms, and end-use environments create distinct competitive arenas with divergent margin structures and regulatory exposure. Understanding these boundaries clarifies where technology leadership translates into pricing power versus where procurement consolidation erodes differentiation.
Product Type:
Cost tier stratification separates commodity metallic systems from premium nanocomposite architectures with dual-mode efficacy.
- Metallic:Copper-ion and silver-ion formulations dominate hospital infrastructure procurement through EPA FIFRA registration pathways. German federal infection-prevention mandates specify these finishes as standard cladding in North Rhine-Westphalia and Bavaria renovation cycles.
- Photocatalytic:Titanium dioxide nanocomposites achieve self-activating antiviral action through ROS generation. Japanese rail operators and Singaporean airport authorities specify these systems for high-frequency touchpoint retrofits where passive metallic ion performance degrades.
- Polymer-Based:Broadest addressable base across commercial building retrofits governed by cost-per-square-foot constraints.
- Nanocomposite:Dual-mode antiviral and mechanical durability performance commands premium specification in critical care environments.
- Silicone:Central European renovation contracts favor silicone-based surface treatments for substrate compatibility and REACH compliance advantages.
Metallic formulations command the established base. The steepest expansion runs through photocatalytic architectures.
Technology:
Application chemistry determines activation mechanism, regulatory pathway, and substrate compatibility across divergent end-use environments.
- Silver Ion:Long-established biocidal efficacy faces ECHA toxicity threshold tightening. Formulators are reformulating toward copper-zinc alloys to maintain registration eligibility under amended biocidal product regulations.
- Copper Ion:Accelerated EPA review protocols compress time-to-market for US healthcare infrastructure tenders. Group purchasing organizations across Texas and Florida hospital systems concentrate procurement on copper-ion treated surfaces.
- Titanium Dioxide:Photocatalytic nanocomposite foundation for self-activating systems in transit and aviation applications.
- Quaternary Ammonium:Emerging reformulation target as silver-ion leaching restrictions tighten in clinical environments.
- Zinc Oxide:Alternative metallic system with lower regulatory friction for food processing surface applications.
Silver ion retains volume leadership. Copper ion is climbing the fastest as procurement shifts toward lower-toxicity alternatives.
Application:
End-use environment dictates performance requirements, revalidation protocols, and specification authority structures.
- Healthcare Facilities:Post-pandemic building code hardening across OECD infrastructure compresses specification cycles. Infection control committees with direct biocidal efficacy requirements displace architectural specification firms in procurement decisions.
- Public Transport:IATA hygiene certification standards mandate antiviral surface treatments for aviation cabin retrofit cycles. High-frequency touchpoint specifications favor photocatalytic systems with integrated sensor substrates for real-time efficacy monitoring.
- Commercial Buildings:Cost-per-square-foot procurement constraints favor polymer-based systems with lower capital intensity.
- Educational Institutions:Maintenance window limitations drive demand for durable finishes compatible with existing surface preparation protocols.
- Food Processing:FDA and FSSAI compliance requirements favor zinc oxide and quaternary ammonium formulations with established safety documentation.
Healthcare facilities anchor revenue concentration. Public transport represents the steepest expansion trajectory as aviation and rail retrofit cycles accelerate.
End User:
Customer type determines procurement scale, specification sophistication, and vendor consolidation exposure.
- Hospitals:Integrated delivery networks consolidate vendor panels from twelve to three approved suppliers per category. Greenfield construction under India's Ayushman Bharat scheme creates first-mover positioning for certified coating suppliers.
- Transit Authorities:Japanese METI industrial chemical safety assessments constrain import formulations lacking JIS-standard toxicity documentation.
- Corporate Offices:Commercial building retrofit demand concentrates in cost-constrained procurement with limited technical specification input.
- Schools:Maintenance budget limitations favor lower-cost metallic systems over premium nanocomposite alternatives.
- Food Manufacturers:Dual FDA and EFSA compliance requirements fragment product portfolios for multinational facility networks.
Hospitals dominate value capture. Transit authorities are gaining share fastest as IATA and rail operator mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA FIFRA registration pathways anchor US market expansion, while ECHA biocidal compliance frameworks reshape European formulation strategies. Divergent regulatory timelines across these jurisdictions fragment product portfolios and compress specification cycles for coating suppliers.
United States
Group purchasing organizations across Texas and Florida hospital systems consolidate vendor panels from twelve to three approved suppliers per category. EPA accelerated review protocols for copper-ion formulations compress time-to-market for healthcare infrastructure tenders. Houston and Miami metropolitan renovation clusters specify certified antiviral finishes as standard cladding in post-pandemic facility upgrades.
Germany
Federal infection-prevention mandates drive specification of certified antiviral finishes in North Rhine-Westphalia and Bavaria hospital renovation cycles. ECHA active substance approval timelines often misalign with construction schedules, forcing speculative inventory positions. Cologne and Munich procurement consortiums now require REACH-compliant certification as mandatory bid qualification.
Japan
METI industrial chemical safety assessments constrain import formulations lacking JIS-standard toxicity documentation. Japanese rail operators specify photocatalytic nanocomposite systems for high-frequency touchpoint retrofits. Tokyo and Osaka transit authorities mandate integrated sensor substrates for real-time efficacy monitoring in premium cabin environments.
India
Greenfield hospital construction under the Ayushman Bharat scheme creates first-mover positioning for certified coating suppliers. CDSCO and BIS compliance requirements favor zinc oxide and quaternary ammonium formulations with established safety documentation. Maharashtra and Karnataka state hospital procurement boards accelerate specification of biocidal surface treatments in public health infrastructure.
Singapore
Aviation cabin retrofit cycles under IATA hygiene certification standards mandate antiviral surface treatments for premium seating and galley surfaces. Changi Airport Authority specifications favor self-activating photocatalytic systems with dual-mode antiviral action. The city-state's procurement frameworks concentrate demand among three pre-qualified coating vendors per application category.
Global Antiviral Coatings Market Competitive Landscape
Specialized nanomaterial developers and diversified coatings conglomerates split the market between premium innovation and scale-driven specification relationships. The vendor base concentrates around three strategic archetypes: metallic ion specialists with EPA FIFRA registration expertise, photocatalytic nanocomposite innovators with aviation and transit credentials, and architectural coatings incumbents leveraging existing hospital system relationships. Dominant competitive moves include backward integration into active substance supply chains and technology licensing partnerships to compress dual-registration timelines across Atlantic markets.
Within the diversified coatings tier, PPG Industries and Akzo Nobel N.V. exemplify archetype positioning through architectural and protective coatings infrastructure. Nano-Care Deutschland AG occupies a specialized position among Central European silicone-based formulators. These three entities represent distinct strategic paths: scale-driven specification maintenance, cross-sector expertise extension, and regional renovation contract anchoring.
| Leading Market Players |
|---|
| GrapheneCA |
| BioFence |
| Nano-Care Deutschland AG |
| Nippon Paint Holdings Co., Ltd. |
| Arkema |
| Akzo Nobel N.V. |
| PPG Industries |
| Sherwin-Williams |
| BASF SE |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese titanium dioxide feedstock is compressing raw material costs for photocatalytic formulators while simultaneously eroding pricing power among commodity metallic-ion producers serving cost-constrained healthcare procurement.
Pricing Analysis
Trans-Atlantic price spreads of 15-25% separate EPA FIFRA-registered copper-ion formulations from their ECHA BPR-compliant European equivalents, with certification-grade tiering as the primary differentiation driver. Three-tier pricing structure across premium nanocomposite, standard metallic-ion, and economy polymer-based systems reflects performance certification levels and volume scale. Cost compression in the metallic-ion tier is intensifying because silver price volatility forces reformulation toward copper-zinc alloys. Corporate office retrofit buyers exhibit highest price sensitivity, while critical care hospital procurement committees prioritize efficacy documentation over per-square-foot economics.
Supply Chain Analysis
Extended payment terms of 90-120 days from German hospital procurement consortiums are forcing working capital restructuring among Central European coating formulators. Active substance production concentrates in Germany, Japan, and the United States, with biocidal ion manufacturing drawing from copper mining operations in Chile and silver refining capacity in Mexico. Single-source vulnerability around sol-gel precursor chemicals sourced from Chinese specialty chemical producers creates regulatory exposure under REACH authorization timelines. Distribution runs through architectural specification firms and direct GPO contracts to integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antiviral coatings are evolving toward service-attach models where real-time efficacy monitoring subscriptions and re-certification maintenance contracts expand faster than one-time surface treatment sales.
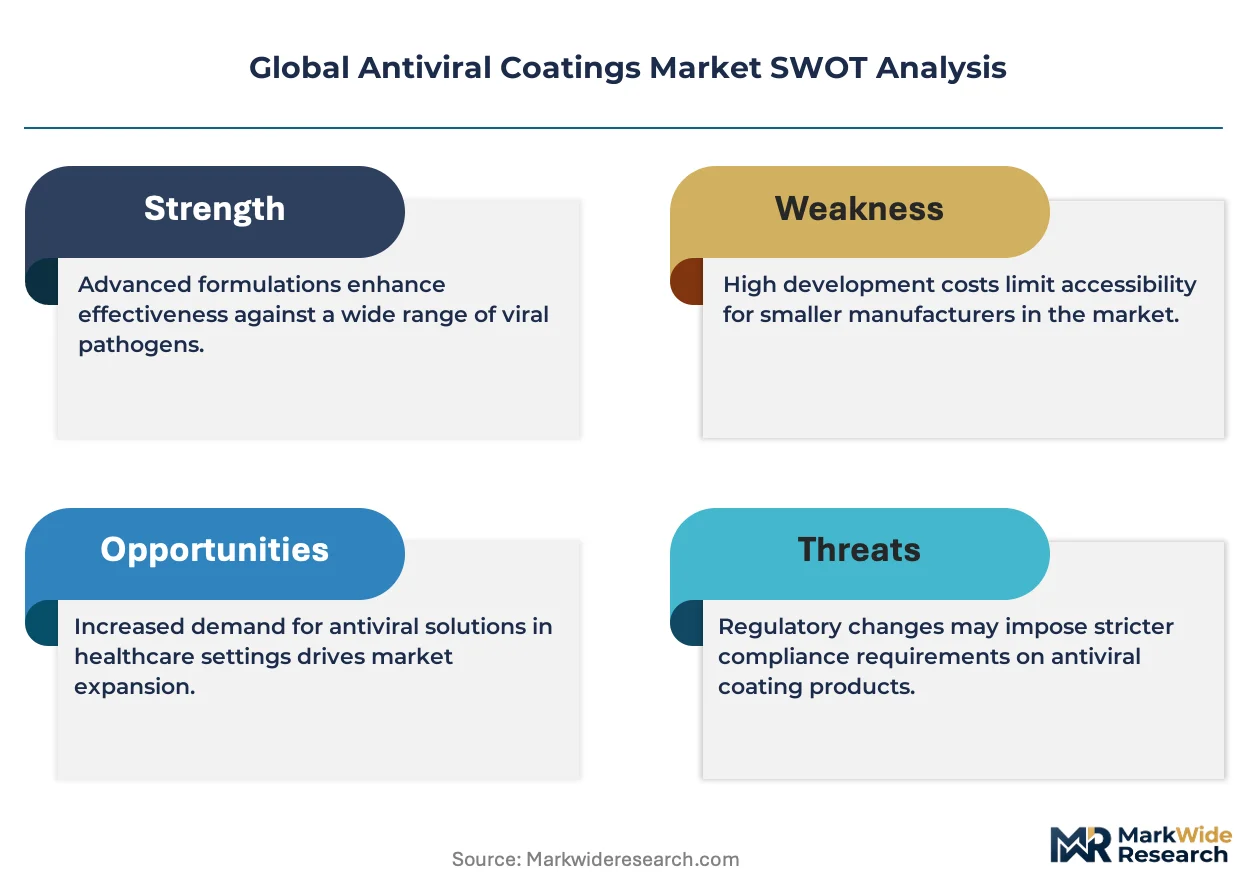
For Market Incumbents: Pre-empt UV-C disinfection substitution in ambulatory surgical centers by integrating sensor-enabled coatings with facility management software platforms. Backward integration into copper-zinc alloy active substance production defends margin structures against precious metal volatility. Accelerate dual-registration cost absorption through technology licensing partnerships that compress EPA-ECHA timeline misalignment.
For New Entrants and Emerging Players: Build out application-service capabilities targeting Indian greenfield hospital construction under Ayushman Bharat, where first-mover positioning remains unsecured. Aviation cabin retrofit cycles under IATA hygiene standards offer penetrable specification entry points against entrenched marine coatings incumbents. Pursue JIS-standard toxicity documentation partnerships with Japanese METI-registered testing laboratories to overcome import formulation barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across silicone-based formulation sub-segments as REACH authorization streamlining reduces regulatory compliance overhead. Acquisition targets should emphasize photocatalytic nanocomposite innovators with aviation and transit credentials rather than commodity metallic-ion scale players. Monitor ECHA-EPA reciprocity negotiation progress as the signal indicating whether dual-registration cost structures will persist or collapse.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Substances | Captive copper-zinc alloy production insulates margins from London Metal Exchange volatility. |
| Dual-Registration Technology Licensing | Partnerships with ECHA-approved laboratories compress Atlantic market entry timelines. |
| Sensor Substrate Integration | Real-time efficacy monitoring enables recurring revenue attach to hardware specifications. |
| Aviation Certification Fast-Track | IATA hygiene standard compliance opens premium cabin retrofit specification channels. |
| REACH-Compliant Silicone Reformulation | Low-toxicity active substance positioning captures German federal mandate procurement. |
Research Methodology
A standing panel of hospital infection control committee chairs, architectural specification firm principals, GPO contracts managers, and ECHA regulatory affairs consultants provided ongoing calibration throughout primary research. This practitioner input combined with secondary validation from EPA FIFRA registration databases, ECHA biocidal product dossiers, hospital procurement contract repositories, and customs trade data for titanium dioxide and copper-ion feedstock imports. Bottom-up volume estimates from facility-level specification tracking triangulated against top-down market sizing from coatings industry association reports.
Scenario-bracketing around regulatory reciprocity outcomes and silver price volatility bands bounded the projection range across the analysis window. Segmentation modeling incorporated formulation chemistry, activation mechanism, end-use environment, and geographic regulatory cluster dimensions. CAGRs derived from facility renovation cycle timing, aviation retrofit fleet schedules, and greenfield hospital construction pipeline data rather than extrapolated historical trends.
Sensitivities concentrate around ECHA active substance approval timeline delays, EPA FIFRA registration pathway modifications, and substitution acceleration from UV-C disinfection systems. Forecasts reflect documented assumptions regarding procurement consolidation trajectories and biocidal efficacy revalidation protocols. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Conformal Coatings Market
Coatings
United Arab Emirates Floor Coatings Market
Coatings
Coating Resins Market
Coatings
Superhydrophobic Coatings Market
Coatings
Global Metal Coatings Market
Coatings
Acrylic Coating Market
Coatings
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market
Coatings
Polyvinylidene Chloride (PVDC) Coated Films Market
Coatings
Rail Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Europe Coil Coatings Market
Coatings
South America Thermal Spray Market
Coatings
Thermal Insulation Coating Market
Coatings
Italy Protective Coatings Market
Coatings
Germany Protective Coatings Market
Coatings
Electronic Protection Device (EPD) Coatings Market