
 Transportation Coating Market | 2026-2036
Transportation Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Transportation Coating Market Outlook
High-performance aerospace-grade specification tiers is collapsing the gap between commercial automotive and aviation coating durability standards. PPG Industries leverages its vertical integration in aerospace resin technology to command premium positioning across both segments. BASF anchors its European operations with waterborne R&D intensity that meets tightening VOC thresholds. AkzoNobel dominates marine coating supply through channel control at major shipyard clusters in Northern Europe and East Asia.
Transportation coating encompasses chemically engineered film-forming systems applied to vehicles, vessels, and aircraft to prevent corrosion, reduce drag, and extend service life, typically formulated with polyurethane, epoxy, or fluoropolymer binders at dry-film thicknesses of 25–150 microns. Waterborne coatings technology leads product innovation as regulatory pressure on solvent emissions intensifies across manufacturing jurisdictions. Powder coatings occupies the fastest-expanding niche for rail undercarriage and chassis applications where zero-VOC curing aligns with depot sustainability mandates. Solventborne formulations retain margin concentration in marine newbuild segments where salt-spray resistance requirements exceed current waterborne performance ceilings.
The EPA enforces VOC content limits under 40 CFR Part 59 for automotive refinish operations, while REACH restricts hazardous substance use across coatings sold into the European Union. China's MEE implements national standards on industrial coating emissions that compel domestic manufacturers toward waterborne system conversion. Stakeholders must monitor the divergence between regional compliance timelines and the capital requirements of multi-technology coating lines.
Market Dynamics
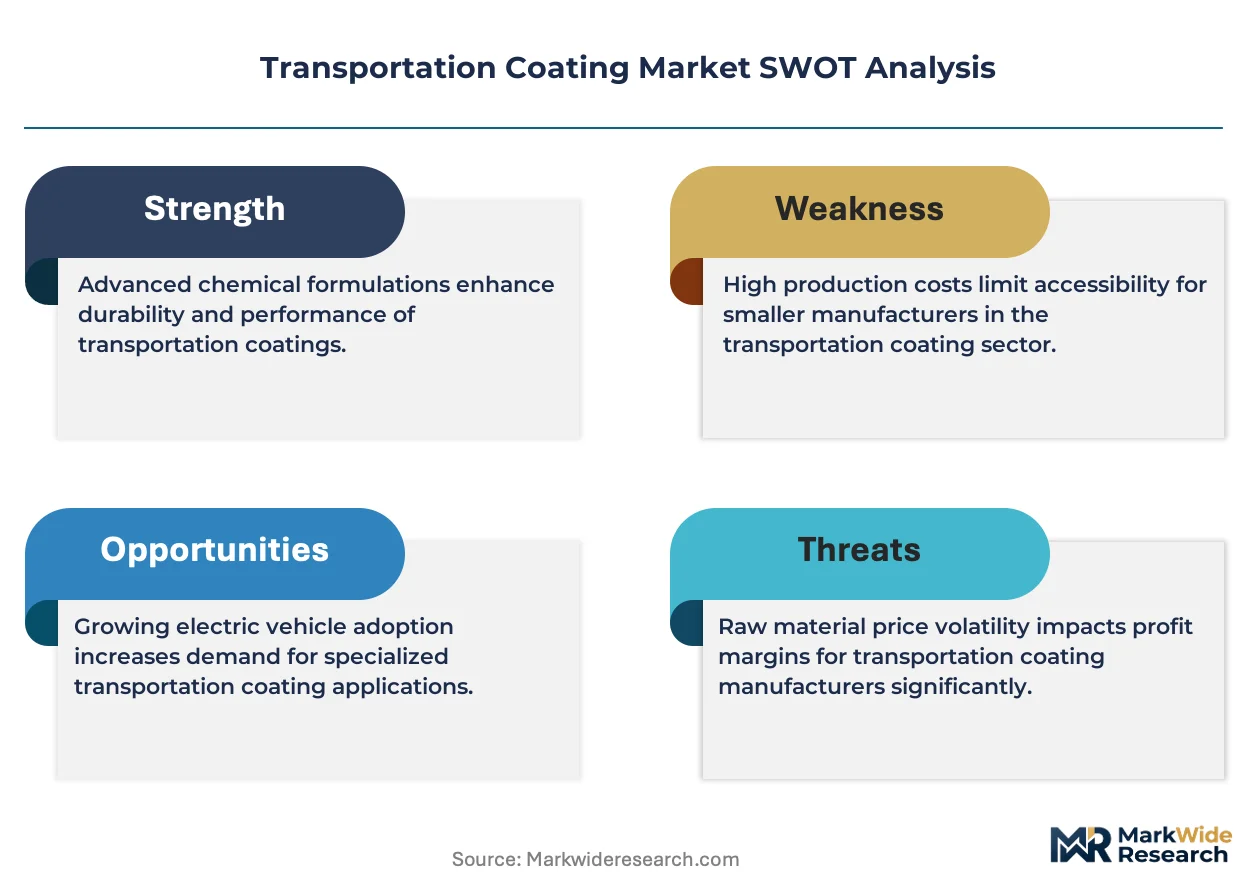
Europe's REACH regulation on volatile organic compounds is compressing the solventborne coating segment while forcing capital reallocation toward waterborne R&D infrastructure and multi-technology production lines.
Growth Catalysts
- REACH VOC thresholds:European automotive OEMs are accelerating waterborne system qualification to meet ECHA-mandated emission caps, pulling supplier R&D investment into compliant resin chemistry.
- Electric vehicle exterior durability specifications:EV manufacturers are expanding orders for high-performance finishes that withstand thermal cycling from battery proximity, creating specification tier upgrades.
- China automotive production scaling:Domestic vehicle output concentration in Shanghai and Guangzhou clusters is driving local coating capability upgrades and import substitution.
Market Restraints
- Epoxy resin supply concentration:Feedstock production clusters in Northeast Asia create input cost volatility and logistics exposure for marine coating formulators.
- Salt-spray performance ceiling:Waterborne polyurethane systems currently fail to match solventborne epoxy corrosion resistance for deep-sea vessel hull applications.
- Capital intensity of dual-line conversion:Coating manufacturers face stranded asset risk from legacy solventborne equipment as jurisdictions accelerate VOC compliance timelines.
Strategic Opportunities
- India automotive coating localization:Domestic OEM expansion under PLI scheme incentives creates white space for technical-grade waterborne supply partnerships.
- Photovoltaic-integrated railcar roof coatings:Convergence of anti-soiling fluoropolymer chemistry with solar panel mounting systems opens depot sustainability applications.
- China MEE emission standards:National industrial coating mandates are compelling domestic manufacturer conversion, creating technology licensing demand.
Industry Challenges
- Formulation chemist scarcity:Waterborne system expertise gaps in polymer rheology and humidity-controlled application are constraining regional expansion.
- OEM qualification timeline compression:Accelerated vehicle platform cycles are shortening coating validation periods for corrosion and weathering protocols.
- Legacy ERP integration friction:Waterborne inventory management requires humidity tracking modules incompatible with solventborne-dominant enterprise systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportation Coating Market |
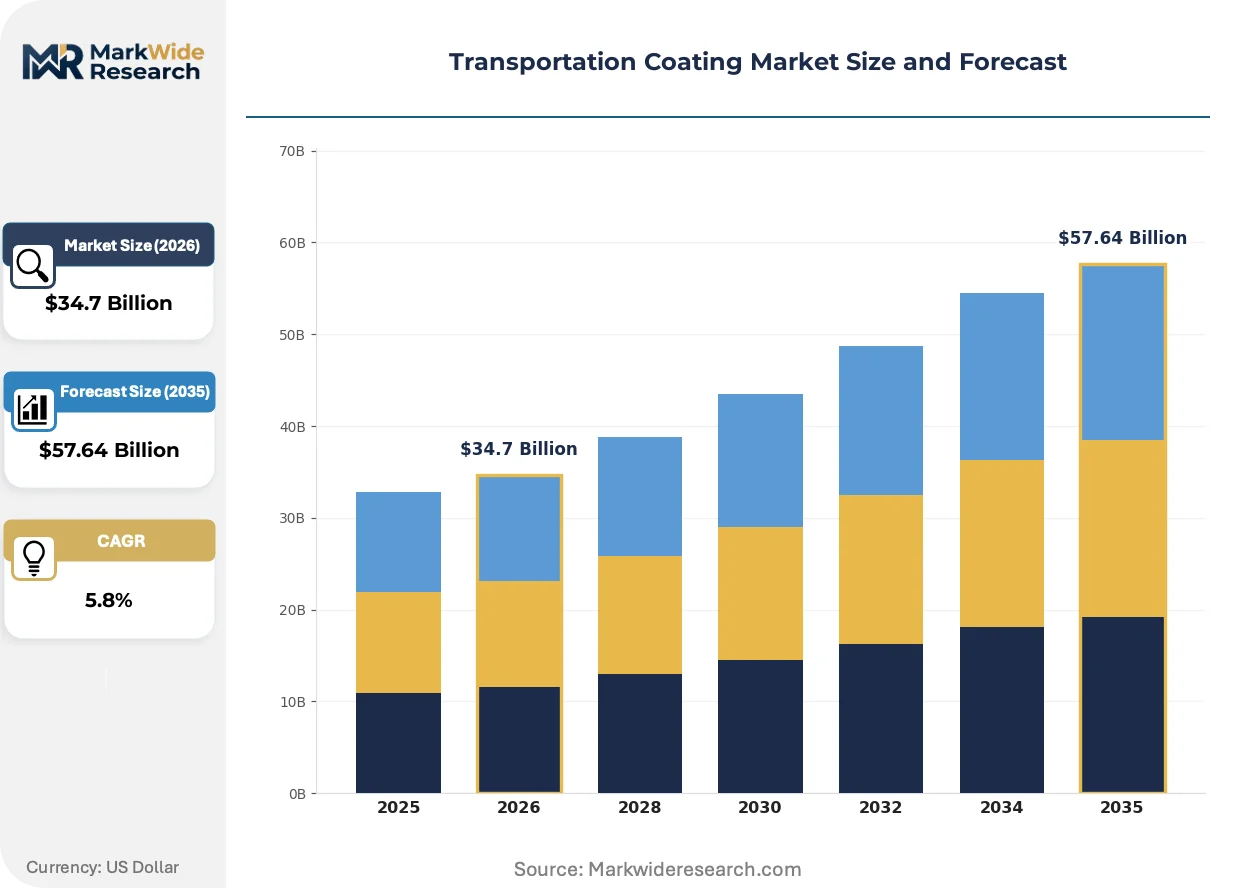
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $57.64 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automotive Paint, Marine Coating, Aerospace Coating, Rail Coating Application: Exterior Surfaces, Interior Finishes, Protecting Components, Decorative Elements Technology: Waterborne Coatings, Solventborne Coatings, Powder Coatings, UV-Cured Coatings End User: Automotive OEMs, Marine Manufacturers, Aircraft Producers, Rail Operators |
| Companies Covered | PPG Industries, AkzoNobel, BASF, Sherwin-Williams, Axalta Coating Systems, Nippon Paint Holdings, RPM International, Kansai Paint, Hempel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportation Coating Market Strategic Shifts
Coating chemistry is fragmenting across performance tiers as regulatory pressure and end-use specialization create divergent formulation pathways rather than consolidated technology standards.
Self-healing polyurethane clearcoat technology is fragmenting the automotive refinish segment. Tier-one German OEMs are qualifying microcapsule-based scratch recovery systems for premium vehicle lines. This capability divergence is compressing aftermarket pricing power for conventional two-component polyurethane suppliers unable to license capsule encapsulation IP.
REACH Annex XVII restrictions on chromium trioxide in aerospace pretreatments are forcing conversion to trivalent chromium and zirconium-based conversion coatings. Surface treatment suppliers serving Airbus and Safran supply chains are requalifying entire process lines. The transition imposes 18-24 month certification delays on coating system approvals for European aviation manufacturing.
Direct-to-fleet procurement contracts are consolidating buyer power in North American heavy-duty trucking. Large fleet operators with in-house refinishing capabilities are bypassing traditional distributor networks for volume coating supply. This channel compression is most advanced in Texas and California logistics corridors where 500-plus unit fleets negotiate system pricing directly with resin suppliers.
Transportation Coating Market Segmentation
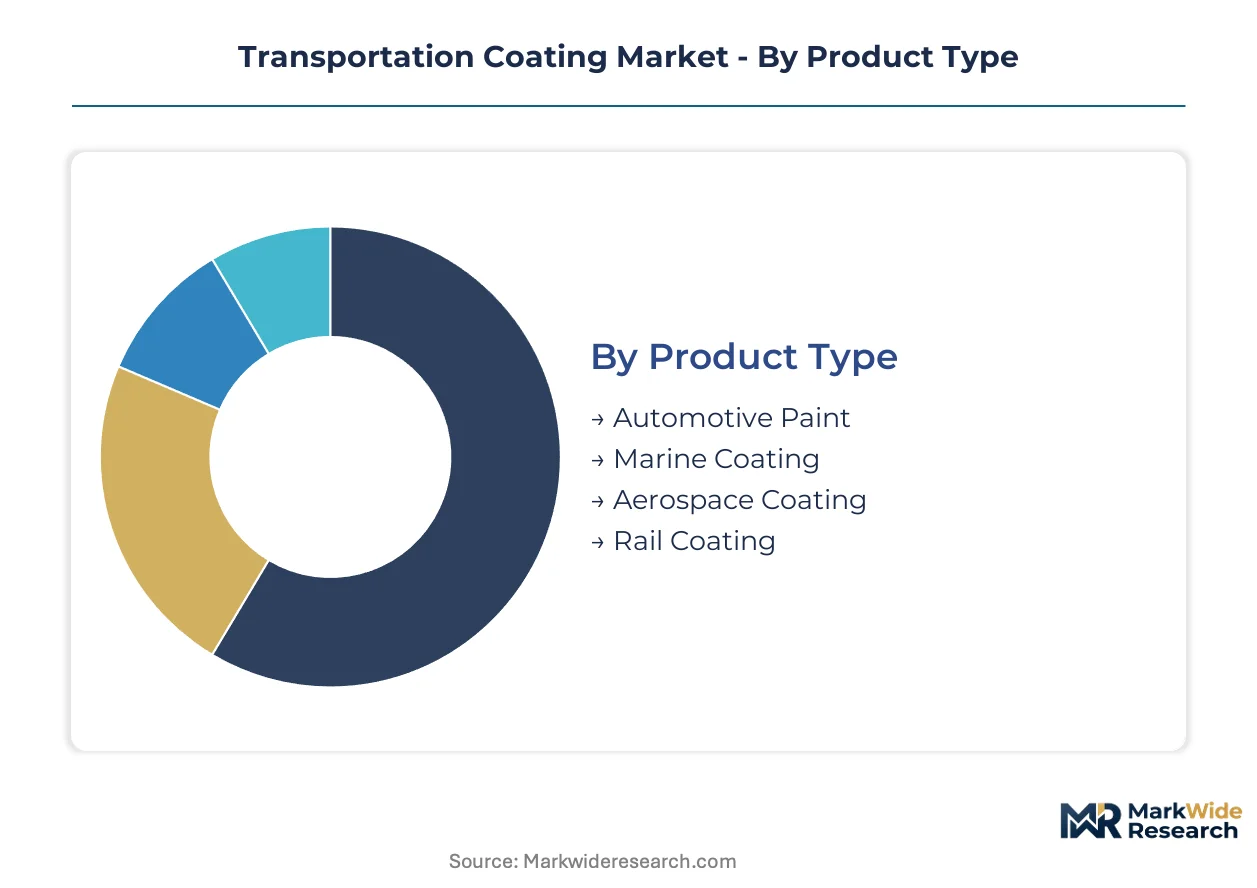
Transportation coating procurement channels diverge sharply by segment durability requirements and regulatory exposure. OEM direct contracts dominate aerospace and automotive exterior tiers, while marine and rail segments route through specialized distributor networks serving shipyard clusters and depot maintenance facilities.
Product Type:
Channel concentration varies by corrosion severity and application complexity, with aerospace and marine coatings commanding dedicated technical sales forces while automotive paint flows through high-volume integrated supply agreements.
- Automotive Paint:Polyurethane and basecoat-clearcoat systems formulated for thermal cycling resistance and chip protection. Demand concentrates at EV OEMs in China and Germany as battery-adjacent exterior durability specifications tighten. Waterborne conversion is compressing solventborne margins in refinish channels.
- Marine Coating:Epoxy-based anti-corrosive primers and antifouling topcoats engineered for salt-spray immersion environments. Shipyard clusters in South Korea and Northern Europe anchor procurement volumes. Solventborne formulations retain specification lock-in for deep-sea hull applications where waterborne performance remains subthreshold.
- Aerospace Coating:Fluoropolymer and polyurethane systems meeting FAA and EASA flame-resistance and weight-critical specifications.
- Rail Coating:Epoxy and alkyd formulations for undercarriage corrosion protection and interior fire safety compliance.
By volume, Automotive Paint leads. By growth pace, Aerospace Coating is ahead.
Application:
Cost tier stratification separates specification-grade exterior systems from commodity interior finishes, with protective component coatings occupying a technical middle ground driven by warranty liability exposure.
- Exterior Surfaces:High-build clearcoats and color coats facing UV, abrasion, and chemical exposure. Premium EV platforms in Germany and California are qualifying self-healing microcapsule technologies that command 40-60% price premiums over conventional two-component systems.
- Interior Finishes:Low-VOC waterborne systems for cabin aesthetics and tactile durability. Regulatory pressure from EPA 40 CFR Part 59 and REACH Annex XVII is accelerating waterborne penetration in passenger vehicle cabins.
- Protecting Components:Functional coatings for brake calipers, battery housings, and underhood thermal management.
- Decorative Elements:Accent coatings for wheels, trim, and branding applications.
Exterior Surfaces commands the highest absolute spend. Interior Finishes is climbing the fastest as cabin air quality regulations tighten.
Technology:
Application method and curing infrastructure create distinct customer profiles, with waterborne systems requiring humidity-controlled spray booths while powder coatings demand electrostatic application lines incompatible with liquid system assets.
- Waterborne Coatings:Acrylic and polyurethane dispersions with VOC content below regulatory thresholds. China's MEE national standards and REACH emission caps are pulling automotive OEM qualification timelines forward, stranding solventborne capital in European and Chinese manufacturing footprints.
- Solventborne Coatings:High-solids epoxy and polyurethane systems retaining performance advantages in marine immersion and chemical resistance applications. Salt-spray test protocols for deep-sea vessel hulls currently exceed waterborne polyurethane capability ceilings.
- Powder Coatings:Thermoset epoxy and polyester systems with zero-VOC curing via thermal or UV activation.
- UV-Cured Coatings:Acrylate oligomer systems enabling instant cure for high-throughput rail and automotive component lines.
Powder Coatings shows the steepest expansion trajectory in rail undercarriage and chassis segments. Waterborne Coatings holds the largest installed base.
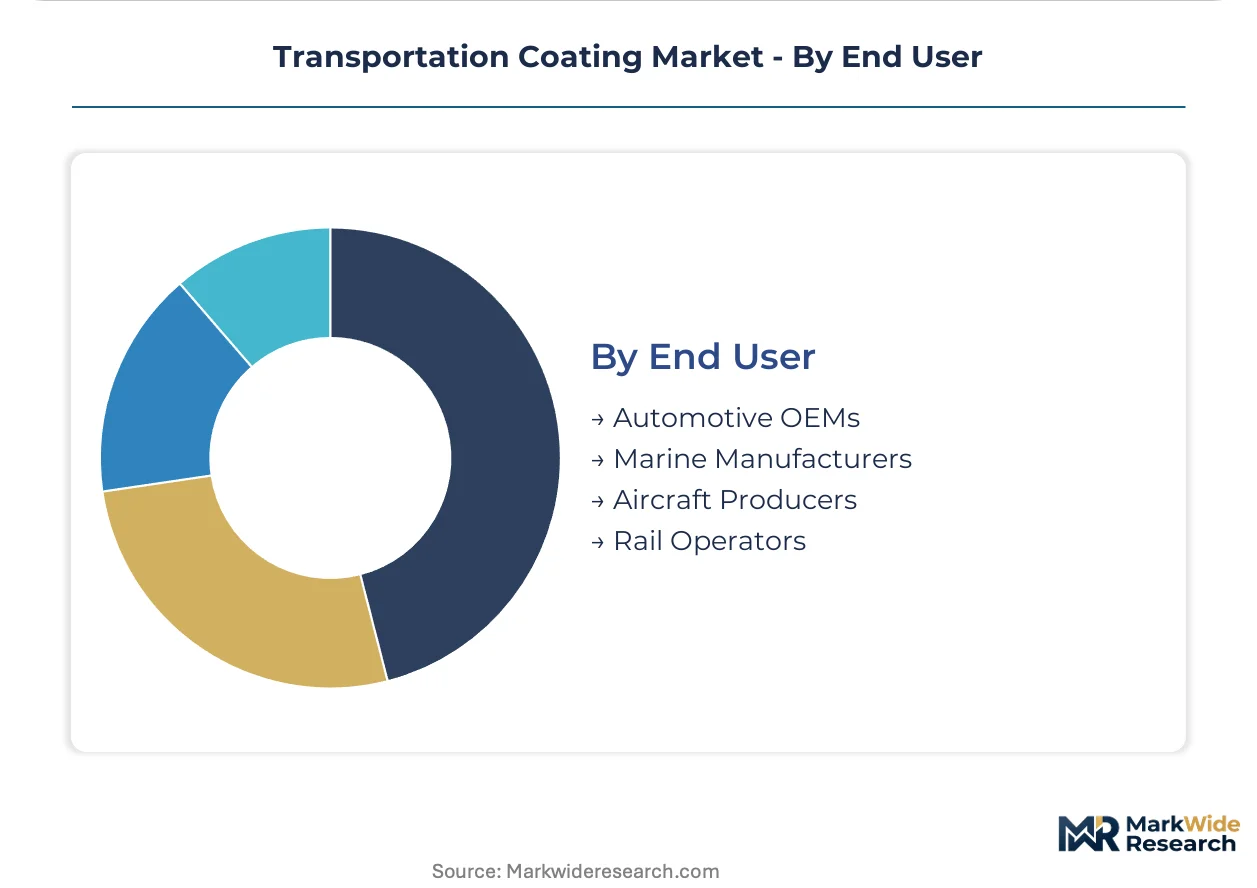
End User:
Procurement concentration patterns separate consolidated OEM direct negotiations from fragmented maintenance operator purchasing, with fleet scale determining access to resin supplier tier pricing.
- Automotive OEMs:Integrated vehicle manufacturers with platform-specific coating specifications and global supplier qualification programs. Direct-to-OEM contracts with PPG, BASF, and AkzoNobel dominate exterior system supply for premium and volume production lines.
- Marine Manufacturers:Shipyard operators and newbuild contractors with class society-certified coating specifications. Channel control concentrates at major shipyard clusters in South Korea, China, and Northern Europe where long-term supply agreements lock in epoxy and antifouling system volumes.
- Aircraft Producers:Airbus, Boeing, and tier aerostructures suppliers with EASA and FAA-mandated qualification protocols.
- Rail Operators:National and regional transit authorities with depot-based refinishing capabilities and sustainability procurement mandates.
Automotive OEMs generate the highest coating spend per unit produced. Aircraft Producers is expanding most quickly as narrowbody production rates recover and next-generation platforms enter qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports high-specification automotive coatings to Chinese EV manufacturers, establishing a trade corridor that channels European resin technology into Asian battery-electric vehicle assembly lines.
China
Domestic EV production scaling in Shanghai and Guangzhou clusters drives demand for high-durability exterior finishes. The MEE implements national industrial coating emission standards compelling waterborne system conversion. Local suppliers upgrade capabilities in Yangtze River Delta manufacturing zones to capture import substitution opportunities.
Germany
Premium automotive OEMs accelerate waterborne qualification timelines for battery-adjacent thermal cycling resistance. REACH Annex XVII VOC thresholds force capital reallocation from solventborne infrastructure. BASF anchors waterborne R&D intensity in Ludwigshafen operations to meet tightening ECHA-mandated emission caps.
United States
Heavy-duty trucking fleet operators consolidate procurement power through direct-to-fleet contracts in Texas and California logistics corridors. The EPA enforces VOC content limits under 40 CFR Part 59 for automotive refinish operations. PPG Industries leverages aerospace resin technology integration to command premium positioning across automotive and aviation segments.
South Korea
Shipyard clusters in Ulsan and Geoje anchor marine coating procurement volumes for deep-sea vessel newbuilds. Domestic formulators face epoxy resin supply concentration exposure from Northeast Asian feedstock clusters. Kansai Paint and Hempel compete for long-term supply agreements at Hyundai Heavy Industries and Samsung Heavy Industries facilities.
Japan
Aerospace coating qualification protocols for narrowbody production recovery drive specification-grade demand. METI industrial standards align with EASA and FAA flame-resistance mandates for next-generation platform entry. Nippon Paint Holdings occupies position in aviation supply chains serving tier aerostructures suppliers.
Transportation Coating Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and R&D scale dimensions. The market structure concentrates around multinational chemical conglomerates with integrated resin supply chains and regional specialists with shipyard channel control. Three archetypes dominate: aerospace-technology leveraged diversified coatings suppliers, waterborne R&D-focused European chemical majors, and marine-specialized distributors with shipyard cluster anchoring. Competitive moves center on multi-technology production line conversion and direct-to-fleet procurement contract capture.
Within the diversified multinational tier, PPG Industries and BASF exemplify scale-driven positioning. PPG represents the aerospace-technology leveraged archetype with vertical integration in resin chemistry. BASF anchors the waterborne R&D-focused European major archetype with Ludwigshafen-based operations. Among marine-specialized players, Hempel occupies the shipyard channel control position with Northern Europe and East Asia cluster penetration.
| Leading Market Players |
|---|
| PPG Industries |
| AkzoNobel |
| BASF |
| Sherwin-Williams |
| Axalta Coating Systems |
| Nippon Paint Holdings |
| RPM International |
| Kansai Paint |
| Hempel |
| Others |
Value Chain & Pricing Dynamics
Waterborne resin chemistry substitution for solventborne systems simultaneously concentrates supply geography in German and Chinese manufacturing clusters and compresses pricing economics across legacy equipment holders. This input transition rewards integrated suppliers with captive acrylic dispersion capacity while stranding distributors dependent on imported epoxy feedstocks.
Pricing Analysis
Three-generation pricing stratification separates next-generation self-healing microcapsule clearcoats from current waterborne basecoats and legacy solventborne refinish systems. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with OEM direct contracts commanding 40-60% premiums over aftermarket channels. Pricing pressure stems from REACH-mandated VOC compliance accelerating waterborne conversion timelines. Fleet operators with 500-plus unit scale exhibit lowest price sensitivity, while independent body shops face acute margin compression.
Supply Chain Analysis
Bohai Bay and Yangtze River Delta port congestion chokepoints expose marine coating formulators to epoxy resin delivery delays from Northeast Asian petrochemical clusters. China, Germany, and South Korea anchor global supply, with feedstock production drawing from Saudi aromatics and Korean bisphenol-A streams. Tariff exposure on acrylic acid imports from US Gulf Coast facilities threatens waterborne dispersion cost structures. Distribution runs through shipyard cluster direct contracts and automotive OEM integrated supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. REACH and EPA emission caps create switching costs that lock OEMs into qualified supplier relationships spanning 18-24 month certification cycles.
For Market Incumbents: Shield market position by accelerating waterborne R&D capacity in Ludwigshafen and Shanghai manufacturing zones to capture stranded solventborne assets. Deepen channel control at Hyundai Heavy Industries and Samsung Heavy Industries shipyard clusters before Korean formulators consolidate. Prioritize backward integration into acrylic dispersion resin supply to offset epoxy feedstock volatility from Northeast Asian petrochemical clusters.
For New Entrants and Emerging Players: Differentiate on humidity-controlled application technology for waterborne systems, targeting the India automotive coating localization white space under PLI scheme incentives. Penetrate technical-grade waterborne supply partnerships with domestic OEMs in Pune and Chennai manufacturing corridors. Lead with depot sustainability mandates for rail undercarriage powder coating conversions.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed marine coating distributors holding shipyard cluster relationships in Ulsan and Geoje. Long-term viability hinges on waterborne technology licensing revenue streams across the analysis window. Target acquisition archetype: regional formulators with MEE-compliant production lines and stranded solventborne equipment awaiting conversion capital. Monitor ECHA Annex XVII expansion timelines as inflection signal for accelerated consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne R&D Capacity Expansion | BASF's Ludwigshafen operations anchor European compliance with REACH VOC thresholds. |
| Shipyard Cluster Channel Control | Hempel's Ulsan and Geoje penetration locks in Korean newbuild coating volumes. |
| Direct-to-Fleet Procurement Capture | PPG's Texas and California logistics corridor contracts bypass distributor networks. |
| Backward Integration into Resin Supply | Captive acrylic dispersion production insulates margin from epoxy feedstock volatility. |
| Technology Licensing to Chinese Manufacturers | MEE emission standards compel domestic conversion, creating royalty revenue streams. |
Study Parameters
A spread of perspectives from coating formulators, OEM procurement directors, shipyard operations managers, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork with BASF technical R&D directors, PPG aerospace resin chemists, and Hempel marine sales engineers combined with secondary validation from ECHA REACH guidance documents, EPA 40 CFR Part 59 enforcement records, China MEE emission standard filings, and customs trade data on acrylic acid imports. Bottom-up coating volume estimates by vehicle class and vessel type triangulated against top-down chemical industry production data.
Segmentation dimensions modeled span product type, application surface, curing technology, and end-user procurement concentration across the analysis window. Automotive paint, marine coating, aerospace coating, and rail coating categories disaggregated by exterior, interior, component protection, and decorative element applications. Technology tiers separated waterborne, solventborne, powder, and UV-cured systems. CAGRs derived from production volume trajectories, regulatory compliance timeline acceleration, and OEM platform cycle timing without year-specific anchoring. EV thermal cycling specifications and MEE enforcement intensity served as demand-side forecast inputs.
Material uncertainties — epoxy resin supply disruptions, REACH Annex XVII expansion scope, and waterborne salt-spray performance breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory timeline adherence and OEM qualification cycle compression. Practitioners should keep alternative scenarios live as ECHA enforcement intensity and Chinese domestic supplier capability upgrades evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Sputter Coater Market
Coatings
Asia-Pacific Floor Coatings Market
Coatings
Morocco Automotive OEM Coatings Market
Coatings
Antimicrobial Coil Coating Market
Coatings
E-Coat Market
Coatings
Functional Coil Coating Market
Coatings
Biopolymer Coatings Market
Coatings
Global Anti Slip Coatings Market
Coatings
South Korea Protective Coatings Market
Coatings
Industrial Liquid Coating Market
Coatings
Italy Automotive OEM Coatings Market
Coatings
Concrete Floor Coatings Market
Coatings
Hull Coatings Market
Coatings
Global Performance Coating Market
Coatings
Europe Anti-Friction Coatings Market
Coatings
Textile Coatings Market