
 Packaging Coatings Market | 2026-2036
Packaging Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Coatings Market Intelligence
The direct-to-brand channel is fragmenting as multinational CPG companies diversify their coating suppliers across regions. BASF SE leverages its integrated polymer feedstock operations to secure cost advantages in water-based formulations. PPG Industries anchors North American beverage can coating supply through dedicated technical service teams. Kansai Paint Co. Ltd dominates Asian metal packaging lines with localized color-matching capabilities.
Packaging coatings are thin functional layers, typically 5–50 microns thick, applied to metal, plastic, or paper substrates to provide barrier protection, chemical resistance, and decorative finish; epoxy-phenolic and polyester-amine chemistries remain dominant in food-contact applications. Polymer coatings lead value contribution due to their versatility across rigid and flexible formats, while UV-cured material systems represent the fastest-expanding segment as converters target energy reduction and instant line speeds. Food packaging applications command the deepest margin pools because compliance burden and performance specifications limit supplier switching.
REACH and the EU F-Gas Regulation constrain solvent-based formulation in Europe, while FDA food-contact notification requirements govern migration limits in the United States. China's GB standards and SAMR oversight tighten domestic market entry for imported coating systems. Stakeholders must monitor regulatory divergence between jurisdictions when standardizing product platforms.
Market Dynamics
Water-based and UV-cured coating systems are displacing solvent-borne chemistries as energy costs and VOC regulations tighten across manufacturing geographies, forcing reformulation investments and line retrofits throughout the supply base.
Growth Catalysts
- Extended shelf-life mandates:Food brands in North America and Europe demand oxygen-barrier coatings for retort pouches and metal cans, expanding epoxy-phenolic specification volumes.
- REACH F-Gas constraints:The EU regulation accelerates converter migration from solvent-based to waterborne and powder systems in metal packaging lines.
- China's domestic packaging scale:SAMR oversight of GB food-contact standards drives localized coating production to serve beverage and processed food manufacturing clusters.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin and isocyanate price swings compress formulation margins, particularly for small-batch custom color matching.
- Specialized applicator concentration:Metal can coating lines in the United States depend on a limited base of qualified technical service providers, creating bottleneck risk.
- Cure-speed limitations:Water-based systems require extended drying tunnels versus UV-cured alternatives, constraining line throughput for high-volume converters.
Strategic Opportunities
- India packaging expansion:FSSAI food-contact compliance investments by domestic and multinational brands create specification openings for barrier coating suppliers.
- Mono-material recyclability:Polyethylene and polypropylene substrate coatings that enable mechanical recycling streams align with EU Green Deal circularity targets.
- Digital printing convergence:Inkjet-compatible overprint varnishes open short-run, customized packaging workflows for craft beverage and specialty food segments.
Industry Challenges
- Migration testing capacity:FDA food-contact notification and EU compliance studies require 12-18 month validation timelines, delaying new product commercialization.
- Legacy line retrofit costs:UV-cured system adoption demands capital expenditure on lamp arrays and nitrogen inerting equipment that mid-tier converters defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Coatings Market |
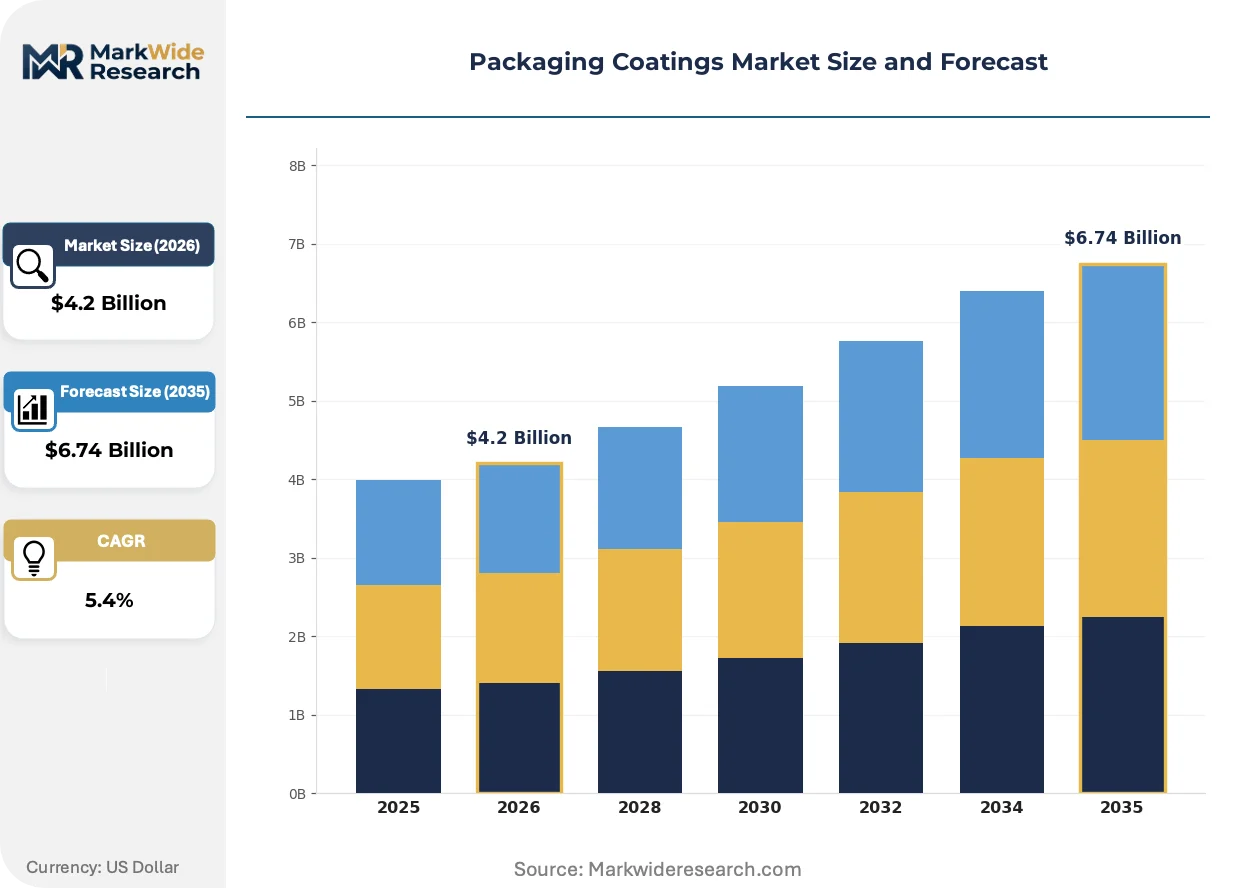
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $6.74 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Coatings, Spray Coatings, Liquid Coatings, Powder Coatings Application: Food Packaging, Beverage Packaging, Pharmaceutical Packaging, Personal Care Packaging Material: Water-Based, Solvent-Based, UV-Cured, Bio-Based End User: Consumer Goods, Healthcare, Automotive, Electronics |
| Companies Covered | BASF SE, Arkema Group, Akzo Nobel NV, Henkel AG & Co. KGaA, Evonik Industries AG, PPG Industries, The Sherwin-Williams Company, Kansai Paint Co. Ltd, Axalta Coating Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Coatings Market Strategic Shifts & Innovations
Coating functionality is expanding beyond passive barrier protection toward active and intelligent surface properties, while regulatory chemistry constraints and converter energy targets reshape material selection priorities.
UV-LED curing systems are rendering obsolete traditional mercury-arc lamp installations across folding carton and flexible packaging lines. European and Japanese converters retrofit presses to capture 50-70% energy reduction and instant on-off capability. The technology is rendering obsolete thermal drying infrastructure and enabling thinner film substrate handling that solvent-borne systems damage.
REACH authorization requirements for bisphenol-A derivatives are accelerating epoxy-novolac substitution in food-contact metal coatings. Formulators face dual notification burdens under FDA 21 CFR and EFSA migration limits, fragmenting product platforms. Beverage can interior lining specifications in Germany and France now exclude conventional epoxy-phenolic systems, forcing coating suppliers to validate polyester-amine and acrylic alternatives.
Brand-direct specification authority is consolidating procurement decisions previously dispersed through converter intermediaries. Nestlé and PepsiCo now mandate coating compliance documentation upstream from their can and film suppliers, compressing the value chain. This concentration is most visible in North American beverage packaging, where two beverage giants account for dominant volume allocation and drive harmonized global coating standards.
Packaging Coatings Market Segmentation
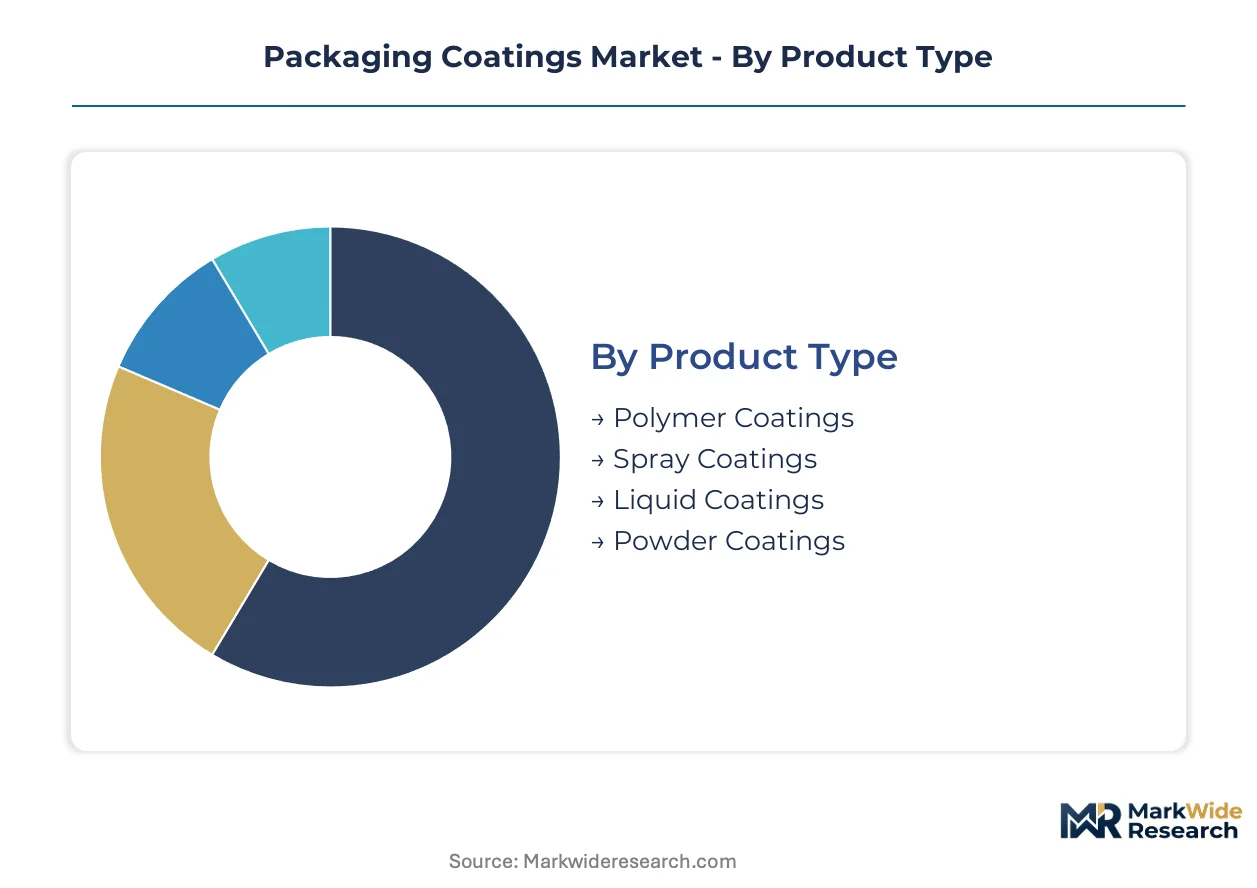
Packaging coatings segmentation reveals how formulation chemistry, substrate compatibility, and regulatory jurisdiction intersect to determine supplier margins and customer switching costs across distinct value pools.
Product Type:
After-sales service intensity varies sharply across product categories, with liquid and powder systems demanding dedicated technical support for line calibration and defect resolution.
- Polymer Coatings:These formulations employ epoxy-phenolic, polyester-amine, or acrylic resin backbones applied at 5–50 micron thickness to metal and plastic substrates. Demand concentrates in retort pouch and metal can applications across Germany and France, where REACH authorization constraints on bisphenol-A derivatives force continuous reformulation cycles.
- Spray Coatings:Atomized application systems deliver uniform coverage on complex geometries for industrial packaging components. Japanese automotive parts suppliers specify these for corrosion-resistant export packaging, driven by METI quality certification requirements.
- Liquid Coatings:Conventional solvent-borne and waterborne systems dominate established metal packaging lines.
- Powder Coatings:Thermoset polymer powders provide zero-VOC finishes for durable goods packaging.
Polymer coatings hold the largest share; momentum sits with powder coatings.
Application:
Application segmentation tracks how end-use performance specifications create tiered margin structures, with food-contact compliance burden acting as the primary pricing differentiator.
- Food Packaging:Oxygen-barrier and migration-resistant coatings for cans, pouches, and lidding films face the steepest regulatory validation requirements. Nestlé and PepsiCo now mandate upstream compliance documentation from coating suppliers, compressing procurement cycles in North American markets.
- Beverage Packaging:Interior linings for aluminum cans and crown corks demand taste-neutral, sulfur-resistant chemistries. German and French beverage can specifications now exclude conventional epoxy-phenolic systems, accelerating polyester-amine validation.
- Pharmaceutical Packaging:USP Class VI and FDA drug master file compliance govern blister packs and vial seals.
- Personal Care Packaging:Decorative and functional coatings for aerosol cans and cosmetic compacts emphasize shelf appeal and chemical resistance.
Food packaging commands the deepest margin pools; beverage packaging is climbing the fastest.
Material:
Material chemistry segmentation reflects energy cost pressures and VOC regulation divergence across manufacturing geographies.
- Water-Based:Acrylic and polyurethane dispersions serve folding carton and flexible packaging converters seeking EPA and ECHA compliance. Extended drying tunnel requirements constrain line throughput for high-volume operations, creating retrofit cost barriers for mid-tier converters.
- UV-Cured:Photoinitiator-activated systems cure instantly under mercury-arc or LED lamps, enabling 50-70% energy reduction. European and Japanese converters retrofit presses to capture instant on-off capability and thinner film handling.
- Solvent-Based:Traditional epoxy and alkyd systems retain share in corrosion-resistant industrial packaging.
- Bio-Based:Plant-derived resin precursors address EU Green Deal circularity targets and brand sustainability commitments.
Water-based formulations retain volume leadership; UV-cured systems are gaining share fastest.
End User:
End user segmentation maps how downstream industry requirements for barrier performance, sterilization compatibility, and aesthetic finish reshape coating specification priorities.
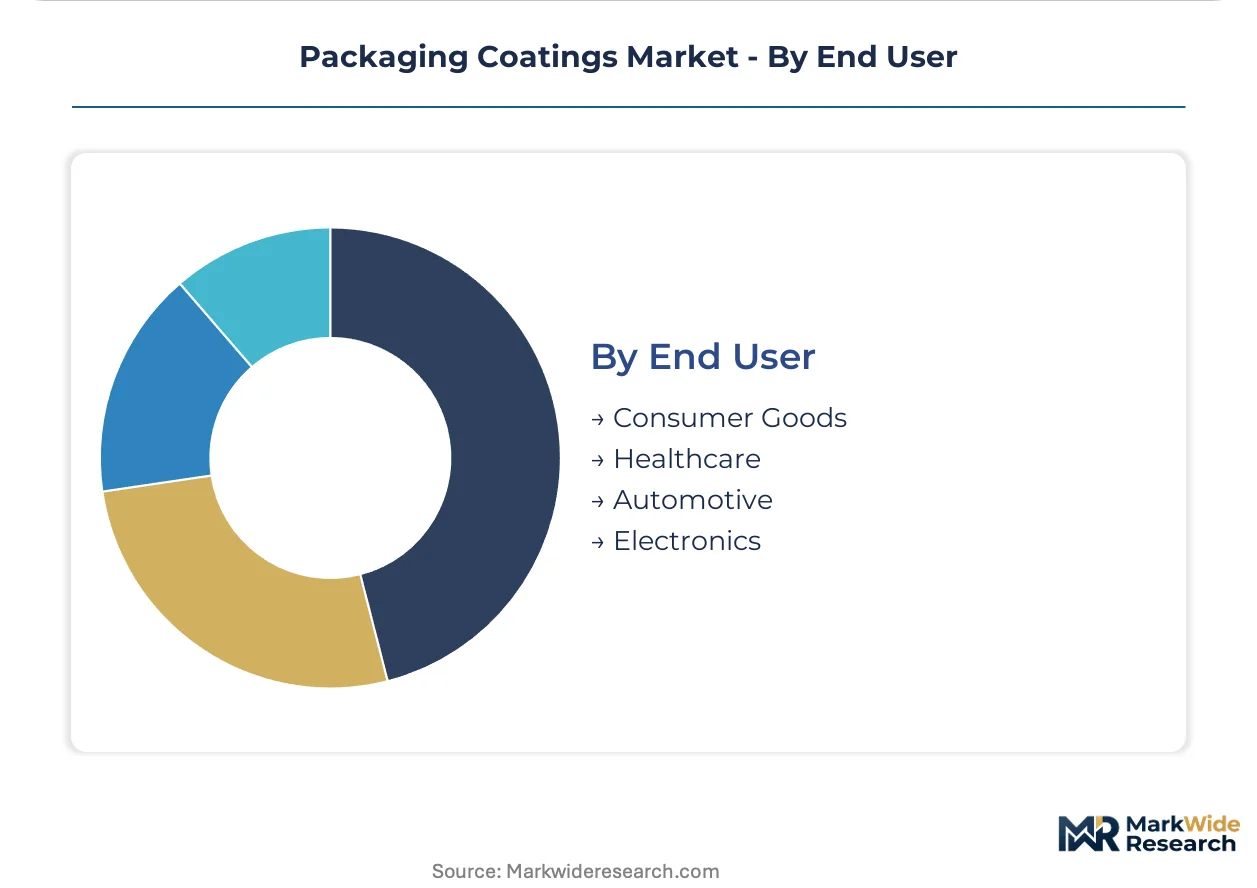
- Consumer Goods:Food, beverage, and personal care brands drive specification authority consolidation, with multinational CPG companies diversifying suppliers across regions while mandating harmonized global compliance standards.
- Healthcare:Pharmaceutical and medical device packaging demands sterilization-resistant, low-extractable coatings validated to FDA and EMA standards.
- Automotive:Corrosion-resistant coatings protect precision components in export packaging for global supply chains.
- Electronics:Moisture-barrier and anti-static coatings safeguard sensitive devices during distribution.
Consumer goods anchors demand volume; healthcare shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR oversight of GB food-contact standards anchors the dominant geography, driving localized production scale across beverage and processed food manufacturing clusters. FDA food-contact notification requirements and REACH authorization constraints reshape formulation requirements in secondary markets. Demand concentrates where domestic packaging production scales rapidly and regulatory compliance creates supplier switching costs.
China
Beverage can and processed food manufacturing clusters in Yangtze River Delta and Pearl River Delta drive coating specification volumes. SAMR enforcement of GB standards tightens market entry for imported systems. Zhejiang and Jiangsu provinces host domestic coating production facilities serving multinational CPG brands.
United States
Multinational beverage brands mandate upstream compliance documentation from coating suppliers, compressing procurement cycles. FDA 21 CFR migration limits govern retort pouch and metal can interior linings. Ohio and Pennsylvania metal packaging corridors depend on qualified technical service providers for line calibration.
Germany
REACH F-Gas Regulation accelerates converter migration from solvent-based to waterborne systems in metal packaging lines. EFSA migration limits fragment product platforms alongside FDA requirements. Bavaria and North Rhine-Westphalia beverage can specifications now exclude conventional epoxy-phenolic systems.
Japan
METI quality certification requirements govern corrosion-resistant export packaging for automotive parts suppliers. UV-LED curing retrofits capture energy reduction across folding carton and flexible packaging lines. Kansai and Chubu industrial corridors concentrate converter infrastructure for thinner film substrate handling.
India
FSSAI food-contact compliance investments by domestic and multinational brands create specification openings for barrier coating suppliers. Maharashtra and Gujarat packaging expansion targets mono-material recyclability for EU export alignment. Mumbai-Pune industrial belt concentrates mid-tier converter capacity seeking UV-cured system adoption.
Packaging Coatings Market Key Industry Players
Integrated chemical conglomerates and specialized coating formulators split the market between feedstock-advantaged scale players and application-focused technical specialists. The vendor base concentrates around three strategic archetypes: polymer feedstock integrators securing cost advantages in water-based formulations, regional technical service anchors with localized color-matching capabilities, and diversified coatings portfolios spanning industrial and packaging segments. Competitive moves center on backward integration into resin production and geographic co-location with high-volume converter clusters.
Within the feedstock-integrated tier, BASF SE and Evonik Industries AG exemplify chemical conglomerates leveraging captive polymer operations. PPG Industries occupies a position as the North American beverage can coating anchor through dedicated technical service infrastructure. Kansai Paint Co. Ltd represents the Asia-Pacific regional specialist archetype with localized formulation capabilities.
| Leading Market Players |
|---|
| BASF SE |
| Arkema Group |
| Akzo Nobel NV |
| Henkel AG & Co. KGaA |
| Evonik Industries AG |
| PPG Industries |
| The Sherwin-Williams Company |
| Kansai Paint Co. Ltd |
| Axalta Coating Systems |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese water-based coating production is compressing export pricing while elevating margin pressure on European and North American formulators who carry higher regulatory compliance costs. This utilization imbalance rewards integrated polymer producers with captive resin supply and punishes small-batch custom color houses dependent on spot epoxy purchases.
Pricing Analysis
Regional price spreads of 15-25% separate Asian export quotations from European domestic supply, with REACH F-Gas compliance costs and FDA food-contact notification burdens explaining the differential. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales technical service intensity. Cost compression in standard-grade waterborne systems is intensifying because Zhejiang and Jiangsu capacity additions outpace regional demand absorption. Mid-tier converters in India and Southeast Asia exhibit the highest price sensitivity, while multinational CPG brands in Germany and the United States prioritize compliance documentation over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning as coating formulators diversify resin sourcing to South Korea and Japan. Epoxy resin, isocyanate curing agents, and photoinitiator precursors draw from concentrated petrochemical feedstock regions in China, Germany, and the US Gulf Coast. Single-source vulnerability in qualified technical service providers for metal can line calibration creates bottleneck exposure in Ohio and Pennsylvania packaging corridors. Distribution runs through converter-direct relationships increasingly mandated by Nestlé and PepsiCo procurement policies, compressing traditional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and compliance documentation subscriptions are expanding faster than base coating volumes as brands outsource regulatory validation and line calibration expertise. This service-attach dynamic repositions coating suppliers toward recurring-revenue relationships with multinational CPG procurement teams.
For Market Incumbents: Harden defensible positions by securing backward integration into specialty resin production for epoxy-novolac alternatives, while embedding dedicated technical service teams within high-volume converter clusters in Yangtze River Delta and North Rhine-Westphalia. UV-LED curing retrofits threaten solvent-borne legacy lines; incumbents must accelerate waterborne and powder system validation to capture converter capital expenditure cycles. For New Entrants and Emerging Players: Build out specification authority in India's FSSAI compliance-driven market, where domestic and multinational brands seek barrier coating suppliers with validated migration testing capacity. Mono-material recyclability coatings for EU Green Deal alignment represent the most penetrable white space. A go-to-market angle anchored in digital printing convergence—inkjet-compatible overprint varnishes for craft beverage short runs—bypasses entrenched metal can incumbents. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional technical service specialists with embedded converter relationships and SAMR-certified Chinese production assets. Long-term viability over the next decade favors feedstock-integrated formulators with captive polymer operations and geographic co-location with high-volume beverage and food packaging clusters. The signal to watch is brand-direct procurement mandate expansion: further compression of converter intermediaries would accelerate supplier consolidation and elevate technical service contract valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | Captive epoxy-novolac production secures margin control as REACH bisphenol-A constraints tighten across German and French specifications. |
| UV-LED Curing Retrofit Partnerships | Converter energy reduction targets in Japan and Europe drive demand for instant on-off lamp installations and nitrogen inerting equipment. |
| SAMR-Certified Chinese Production Expansion | Localized GB standards compliance captures beverage and processed food manufacturing cluster growth in Zhejiang and Jiangsu provinces. |
| Technical Service Contract Standardization | Recurring line calibration and defect resolution subscriptions deepen switching costs with multinational CPG procurement teams. |
| Mono-Material Recyclability Validation | Polyethylene and polypropylene substrate coatings align with EU Green Deal circularity targets and mechanical recycling stream requirements. |
Research Approach
The analysis maps water-based, UV-cured, solvent-based, and bio-based coating sub-sectors, each validated through formulation chemists, converter procurement leads, and regulatory affairs directors at multinational CPG brands. Primary interviews with plant managers at metal packaging facilities, technical service heads, and SAMR compliance consultants combined with secondary validation from FDA food-contact notification databases, ECHA REACH authorization records, SEC 10-K filings by integrated chemical conglomerates, and Chinese customs trade data. Bottom-up coating volume estimates triangulated against top-down packaging production statistics across the analysis window.
Assumptions held fixed include current REACH F-Gas Regulation enforcement intensity, FDA migration limit notification timelines, and SAMR GB standards implementation pace; variables included petrochemical feedstock price volatility bands and UV-LED curing adoption curves. The forecast framework models by formulation chemistry, substrate compatibility, regulatory jurisdiction cluster, and end-use application tier. CAGRs derived from segment-level volume trajectories weighted by value-per-unit differentials. Industry-specific inputs encompassed retort pouch specification volumes and beverage can interior lining reformulation cycles.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-tier Asian formulators or accelerated brand-direct procurement consolidation by Nestlé and PepsiCo would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Electrical Appliance Coatings Market
Coatings
Industrial Coatings Market
Coatings
ASEAN Automotive OEM Coatings Market
Coatings
Antimicrobial Coil Coating Market
Coatings
Polyester Coatings Market
Coatings
Anti-Corrosion Nanocoatings Market
Coatings
Canada Automotive OEM Coatings Market
Coatings
Global Heat Resistant Coatings Market
Coatings
Egyptian Protective Coatings Market
Coatings
Electrocoat Market
Coatings
Japan Automotive OEM Coatings Market
Coatings
Australia Industrial Coatings Market
Coatings
Global Industrial Floor Coatings Market
Coatings
South Korea Marine Coatings Market
Coatings
Self-Cleaning Coatings Market
Coatings
Clear Coatings Market