
 Global Ajinomoto Build-Up Film Substrate Market | 2026-2036
Global Ajinomoto Build-Up Film Substrate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ajinomoto Build-Up Film Substrate Market Analysis
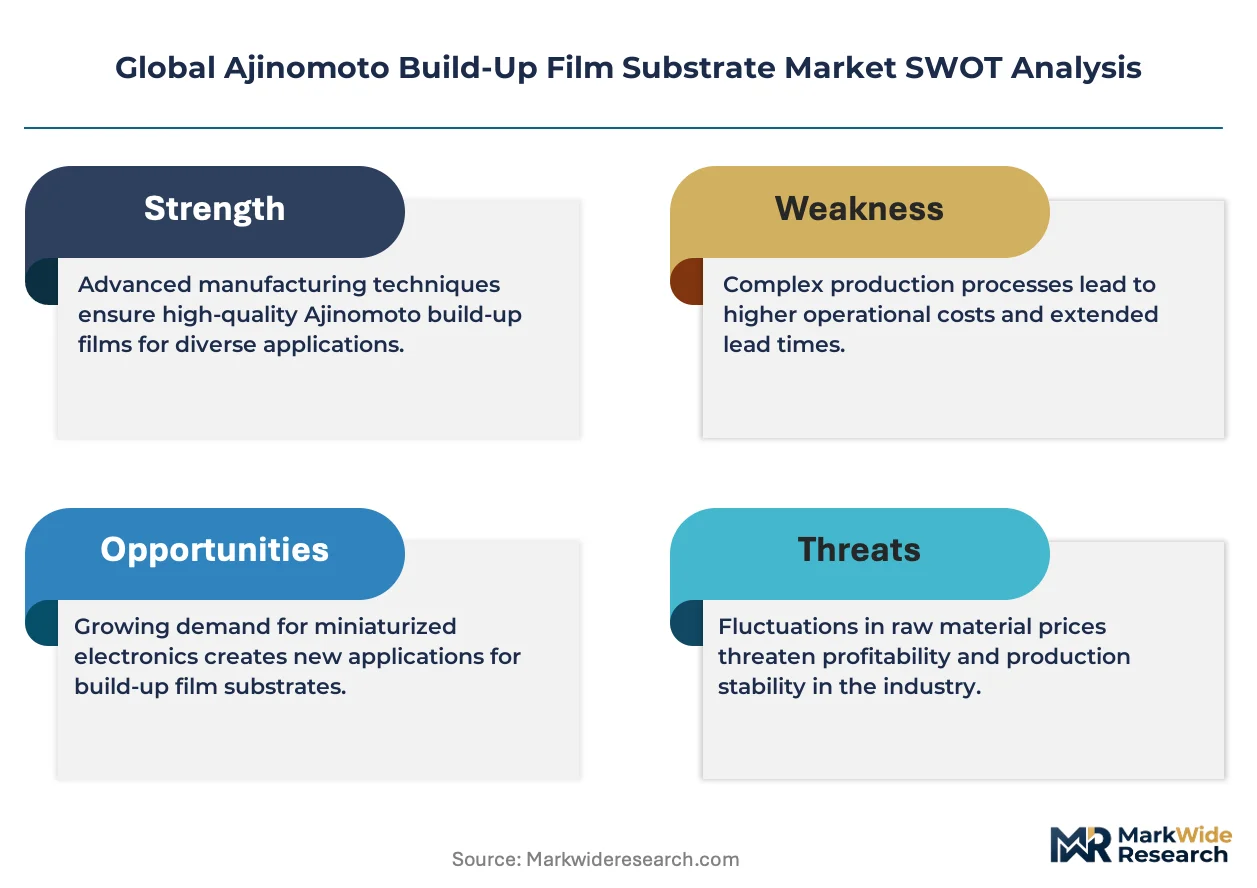
Modular substrate configurations is broadening buyer choice across the ABF ecosystem. Ajinomoto Co. leverages its integrated resin synthesis and substrate fabrication chain to dominate supply of high-layer-count panels. Unimicron Technology Corp anchors capacity expansion in Taiwan with aggressive capex into flip-chip ball grid array lines. Samsung Electro-Mechanics competes through captive demand from its parent's semiconductor division, reducing external procurement exposure.
Ajinomoto Build-Up Film Substrate refers to a multi-layered organic interposer material composed of epoxy resin-impregnated glass fiber and proprietary filler systems, engineered for fine-line lithography below 10 micrometers and thermal stability above 250 degrees Celsius in reflow conditions. Its primary purpose is to provide high-density routing between silicon dies and printed circuit boards in flip-chip packages for central processing units and graphics processors. Layered configurations command the deepest margin pools as server-grade processors push past 20 build-up layers, while Specialty substrates for chiplets represent the fastest-growing demand vector. Polyimide-based variants sustain premium positioning in aerospace and defense applications where thermal cycling tolerance exceeds standard epoxy formulations.
Japan's METI enforces chemical substance reporting under its Industrial Safety and Health Act, compelling substrate makers to document brominated flame retardant content across supply chains. The EU REACH regulation restricts candidate substances of very high concern in epoxy formulations, directly shaping material substitution timelines for exporters. EPA TSCA Section 6 rules in the United States impose pre-manufacture notification burdens on novel resin chemistries. Stakeholders must monitor divergence between Asian voluntary disclosure standards and binding European chemical restrictions when qualifying new substrate platforms for multinational semiconductor packaging houses.
Market Dynamics
Chiplet disaggregation in high-performance computing is forcing substrate layer counts past 20, concentrating procurement power among Taiwan and South Korea packaging houses while straining resin synthesis capacity in Japan's Kyushu corridor.
Growth Catalysts
- Advanced packaging architectures:Flip-chip ball grid array lines at Taiwanese OSATs are absorbing record volumes of high-layer-count panels for server-grade processors. These facilities now specify ABF substrates as standard for central processing unit interposers.
- EPA TSCA Section 6:Pre-manufacture notification rules for novel resin chemistries are accelerating material qualification cycles among compliant suppliers. Early movers gain preferred-supplier status with multinational semiconductor packaging houses.
- Japan's Kyushu cluster:Concentrated production capacity adjacent to downstream packaging ecosystems minimizes logistics friction and enables just-in-time resin-to-substrate conversion.
Market Restraints
- Epoxy resin input volatility:Bisphenol-A and specialty hardener supply swings transmit directly to substrate bill-of-materials costs. Producers lack pricing power to pass through acute spikes.
- Single-source synthesis risk:Proprietary filler systems and resin formulations concentrate in Ajinomoto Co.'s integrated chain. Disruption at any node propagates through the entire build-up film ecosystem.
- REACH candidate substance restrictions:Brominated flame retardant documentation burdens and substitution mandates compress formulation flexibility for European-bound exports.
Strategic Opportunities
- Polyimide-based variants:Aerospace and defense applications with thermal cycling requirements above standard epoxy tolerance offer premium positioning outside commodity server processor markets.
- India's semiconductor packaging incentives:PLI scheme disbursements for display and semiconductor manufacturing are attracting substrate qualification programs from first-tier OSATs.
- Glass core substrate convergence:Hybrid material stacks combining ABF dielectric layers with glass core mechanical stability are opening new architectural possibilities for ultra-high-density routing.
Industry Challenges
- Fine-line lithography talent scarcity:Sub-10 micrometer patterning expertise concentrates among veteran process engineers in Japan and Taiwan. Replication of this skill base in emerging packaging hubs proceeds slowly.
- Multi-regulatory qualification timelines:Parallel compliance tracks for Japan's Industrial Safety and Health Act, EU REACH, and EPA TSCA extend new substrate platform validation to 18-24 months.
- Legacy equipment integration friction:Advanced build-up film chemistries often require incompatible process parameters with existing lamination and laser drilling assets at mid-tier packaging facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ajinomoto Build-Up Film Substrate Market |
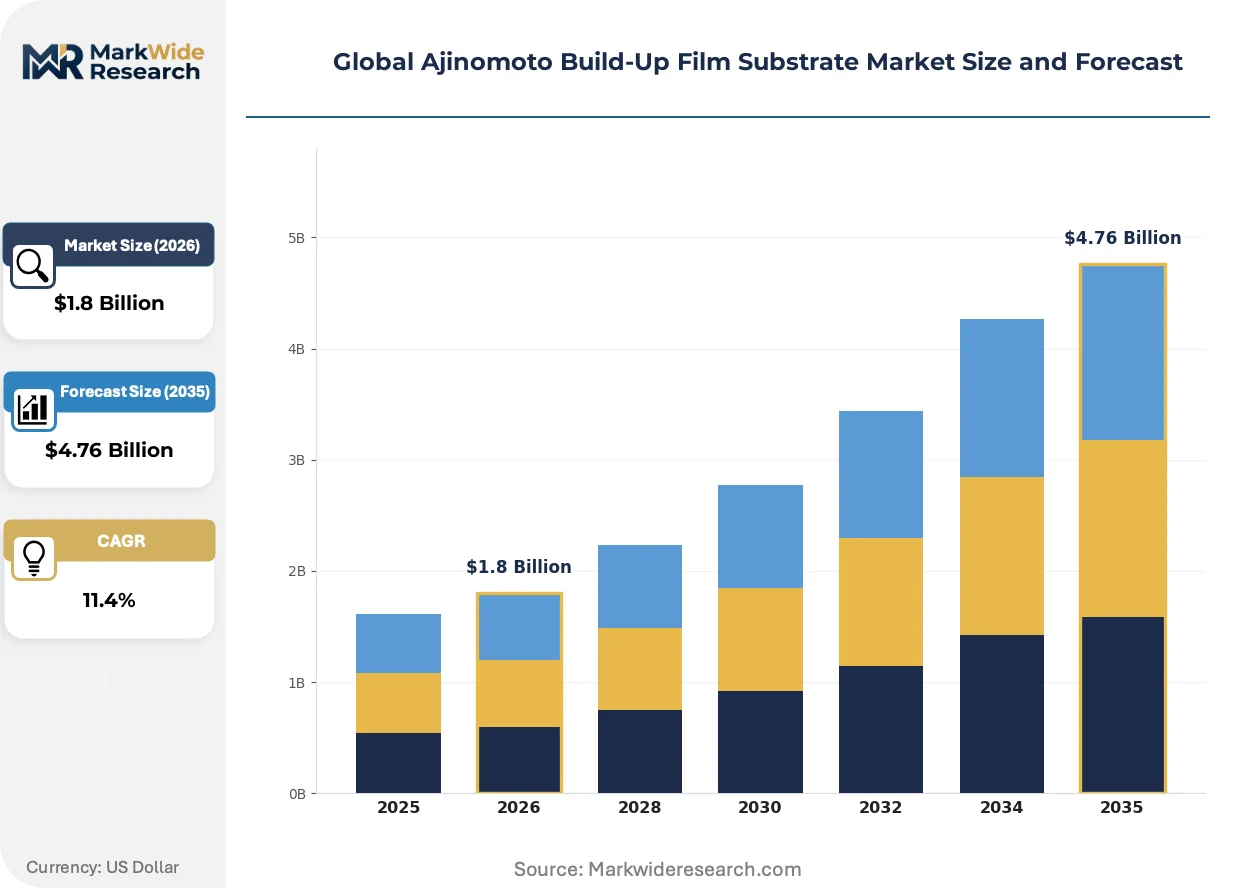
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Layered, Specialty Material: Polyimide, Polyethylene, Epoxy, Polyester Application: Consumer Electronics, Automotive Electronics, Telecommunications, Industrial Devices End User: OEMs, Tier-1 Suppliers, Manufacturers, Aftermarket Providers |
| Companies Covered | Ajinomoto Co., Inc., Unimicron Technology Corp, Ibiden Co., Ltd., Nan Ya Printed Circuit Board Corporation, AT & S, Samsung Electro-Mechanics, Shennan Circuit, Kyocera, TOPPAN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ajinomoto Build-Up Film Substrate Market Emerging Trajectories
Substrate architecture is fragmenting into configurable layer stacks as heterogeneous integration demands outpace monolithic scaling. This shift rewards suppliers with flexible resin synthesis and rapid prototyping capabilities.
Modular build-up film configurations are modularizing the traditional fixed-layer substrate paradigm. Server processor designers now specify variable layer counts and dielectric thicknesses per product generation rather than accepting standardized panel formats. This flexibility compresses time-to-market for chiplet-based designs but fragments production runs across substrate fabricators.
REACH substance-of-very-high-concern candidate list expansions are forcing epoxy formulation redesigns across European export supply chains. ECHA's brominated flame retardant scrutiny has triggered phosphorus-based and inorganic filler substitution programs. Japanese resin suppliers with pre-qualified halogen-free platforms capture accelerated qualification windows with EU-bound packaging houses.
Consolidated procurement at Taiwanese OSATs is compressing vendor counts and extending contract durations. Samsung Electro-Mechanics and Unimicron Technology Corp now negotiate multi-year supply agreements with resin-substrate integrators, displacing spot-market purchasing. This concentration is most visible in Hsinchu and Tainan science parks where captive demand from captive semiconductor divisions shapes supplier selection criteria.
Global Ajinomoto Build-Up Film Substrate Market Segmentation
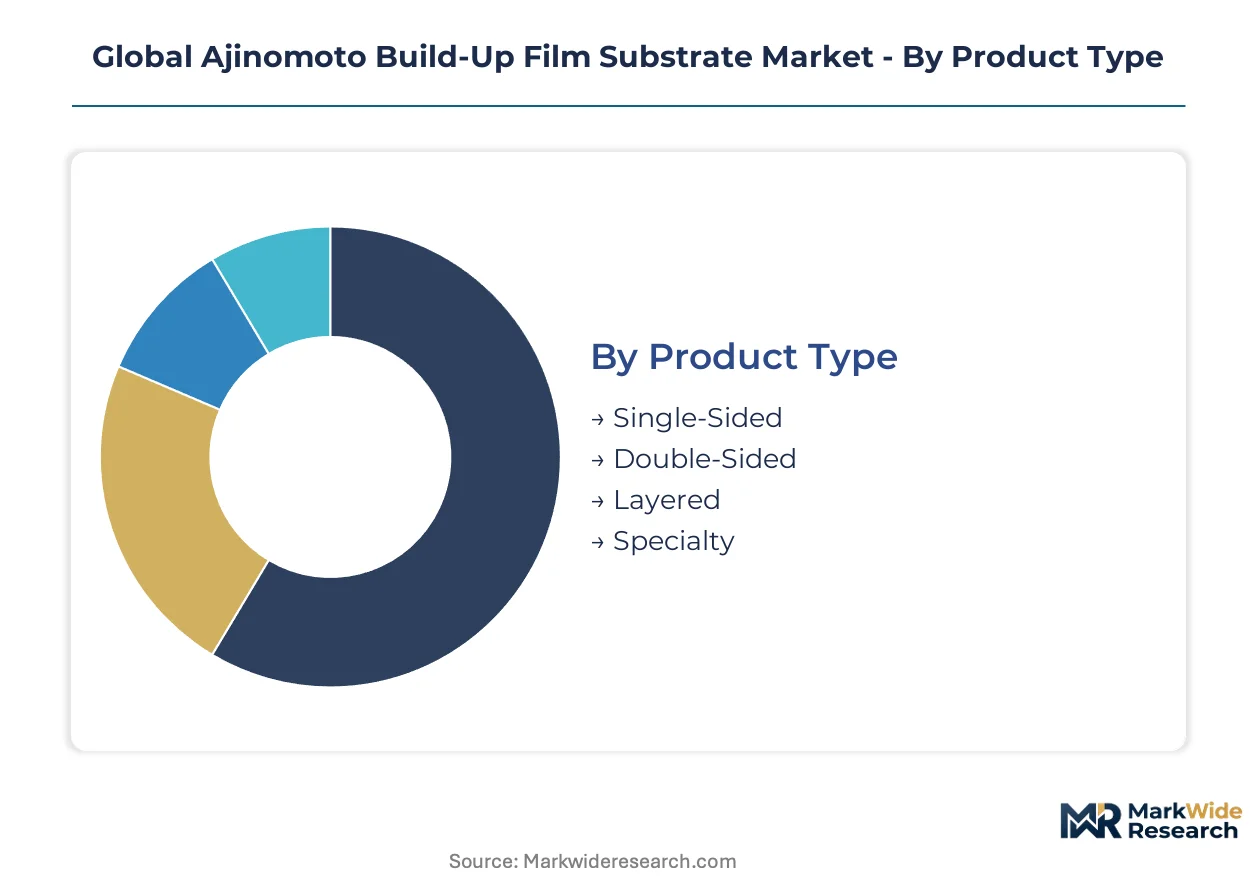
Substrate fabricators must align capital deployment with layer-count complexity and resin chemistry requirements. Each segmentation dimension carries distinct equipment and qualification burdens that reshape competitive positioning across the supply chain.
Product Type:
Layered configurations demand the heaviest upfront investment in sequential lamination and laser drilling assets. Single-sided variants require minimal capital outlay for entry-level packaging houses.
- Layered:Multi-stack dielectric architectures with 10-20+ build-up layers enable fine-line routing below 10 micrometers for server-grade central processing units. Procurement concentrates at Taiwanese OSATs in Hsinchu Science Park as chiplet disaggregation forces layer counts upward. Capital intensity peaks here due to sequential lamination cycles and yield management systems.
- Specialty:Custom-configured substrates for heterogeneous integration and glass-core hybrid stacks target aerospace defense applications with thermal cycling requirements exceeding standard epoxy tolerance. Demand from Kyushu-based packaging ecosystems is accelerating qualification timelines for polyimide-based variants.
- Single-Sided:Entry-level flip-chip packages with one build-up dielectric layer serve cost-sensitive consumer applications.
- Double-Sided:Symmetrical layer stacks on both sides of a core substrate balance routing density with panel utilization efficiency.
Most installed capacity flows through Layered configurations. Expansion is steepest in Specialty substrates.
Material:
Epoxy formulations dominate volume production due to established supply chains from Kyushu resin synthesis clusters. Polyimide commands the widest margin spreads.
- Epoxy:Bisphenol-A based thermoset systems with proprietary filler loadings achieve thermal stability above 250 degrees Celsius in reflow conditions. REACH candidate substance restrictions on brominated flame retardants are forcing phosphorus-based substitution programs among European-bound suppliers. Kyushu-based resin synthesis capacity anchors global epoxy substrate output.
- Polyimide:Aromatic heterocyclic polymer backbones sustain dimensional stability across extreme thermal cycling ranges. Aerospace and defense contractors in Japan and the United States specify polyimide for mission-critical avionics where epoxy degradation risks are unacceptable. Premium positioning reflects 3-4x material cost premiums over standard formulations.
- Polyethylene:Flexible substrate cores for wearable and foldable device applications where mechanical compliance exceeds thermal performance requirements.
- Polyester:Cost-competitive dielectric layers for commodity consumer electronics with moderate thermal and electrical performance thresholds.
Epoxy substrates carry the deepest revenue concentration. Polyimide is gaining share fastest in premium defense and aerospace verticals.
Application:
Telecommunications infrastructure demands the most stringent signal integrity specifications. Consumer electronics drives absolute volume throughput.
- Telecommunications:Baseband processors and network interface cards require ultra-low-loss dielectric materials for millimeter-wave signal propagation. South Korean packaging houses serving Samsung's network equipment division specify high-layer-count ABF substrates for 5G massive MIMO base stations. Thermal management specifications exceed consumer-grade thresholds by 40-60 degrees Celsius.
- Consumer Electronics:Smartphones, tablets, and wearable devices absorb the highest panel volumes through Taiwanese OSATs. Apple's A-series and M-series processor packaging at TSMC-adjacent facilities standardizes on ABF interposers. Layer counts remain constrained by cost targets rather than technical limits.
- Automotive Electronics:Advanced driver-assistance system processors and domain controllers require AEC-Q100 qualification for extended temperature ranges.
- Industrial Devices:Programmable logic controllers and motor drive inverters specify substrates with enhanced moisture resistance and long-term reliability.
Consumer electronics substrates represent the broadest installed base. Telecommunications applications are expanding most quickly as 5G infrastructure deployment accelerates.
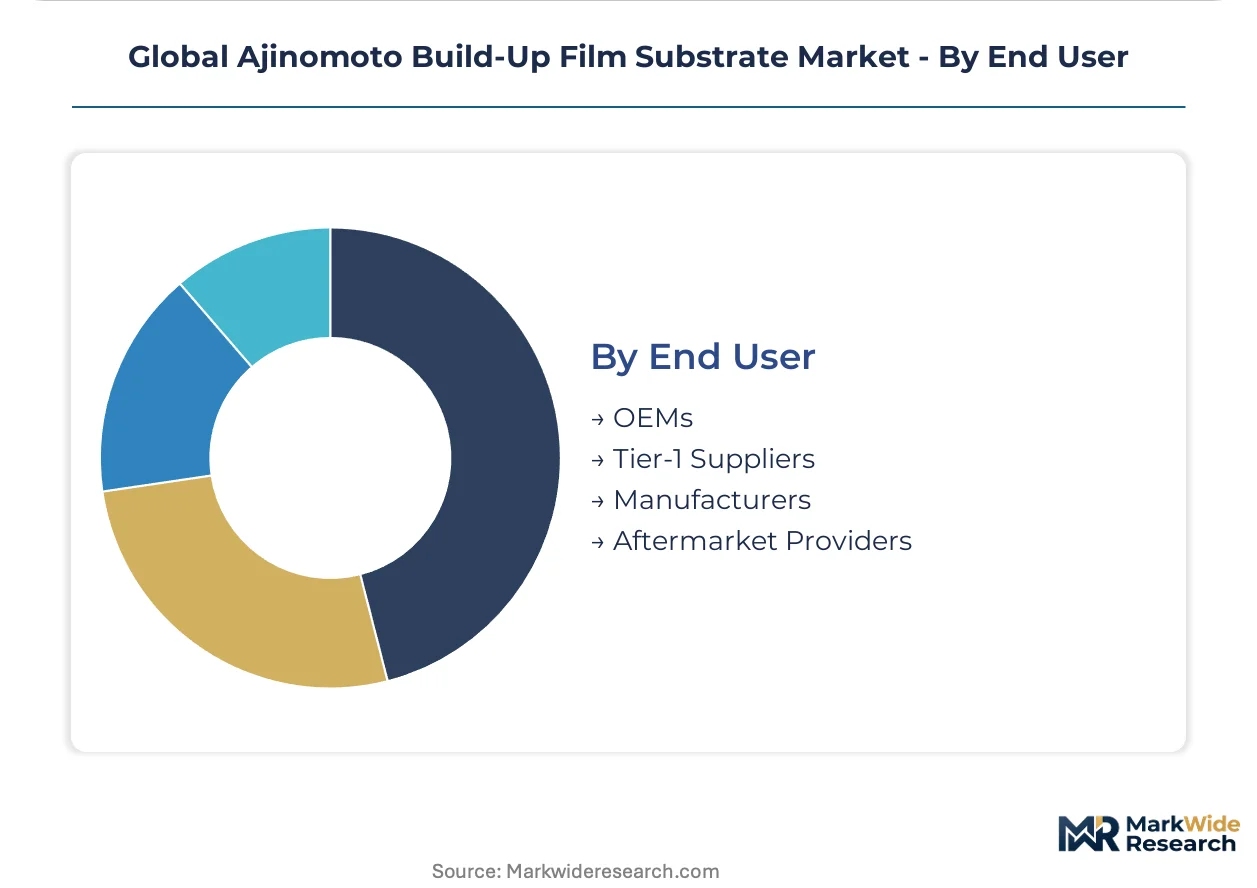
End User:
OEMs internalize the longest qualification cycles and captive substrate development programs. Aftermarket providers operate with minimal technical specification leverage.
- OEMs:Apple, AMD, and NVIDIA maintain direct substrate qualification teams that lock resin formulations and layer-stack configurations 18-24 months ahead of production ramp. These semiconductor designers specify ABF material sets rather than delegating to packaging subcontractors. Backward integration into substrate architecture definition constrains supplier negotiation leverage.
- Tier-1 Suppliers:Foxconn, Jabil, and Celestica manage substrate procurement across multiple OSAT relationships with consolidated volume aggregation. Multi-year supply agreements with Ajinomoto Co. and Unimicron Technology Corp displace spot-market purchasing. Contract durations now extend 3-5 years with price-volume banding mechanisms.
- Manufacturers:Substrate fabricators producing under contract for branded semiconductor packaging houses.
- Aftermarket Providers:Replacement substrate sourcing for legacy equipment maintenance and repair operations.
Tier-1 Suppliers channel the majority of qualified substrate volume. OEM direct procurement is climbing fastest as chiplet architectures demand co-design relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ajinomoto Co. pioneered commercial ABF substrate production in Japan's Kyushu region during the 1990s. The technology diffused to Taiwan and South Korea as flip-chip packaging scaled for personal computing. Today, substrate demand concentrates in East Asian packaging clusters serving high-performance computing and AI accelerators.
Japan
Kyushu's concentrated resin synthesis and substrate fabrication capacity anchors global ABF supply chains. METI's Industrial Safety and Health Act enforces brominated flame retardant documentation across chemical substance reporting. The Kagoshima-Kumamoto corridor hosts sequential lamination facilities supplying adjacent OSAT ecosystems with just-in-time material flows.
Taiwan
Hsinchu Science Park and Tainan packaging houses absorb record volumes of high-layer-count panels for server-grade processors. The National Development Council's semiconductor industry promotion programs subsidize advanced packaging capacity expansion. Unimicron Technology Corp anchors flip-chip ball grid array line investments in Taoyuan's industrial zones.
South Korea
Samsung Electro-Mechanics leverages captive demand from its parent's semiconductor division to reduce external procurement exposure. MFDS chemical substance regulations align with REACH substance restrictions for European-bound exports. The Giheung-Suwon corridor concentrates substrate qualification programs for 5G baseband and network processor packaging.
United States
Apple, AMD, and NVIDIA maintain direct substrate qualification teams that lock resin formulations 18-24 months ahead of production ramp. EPA TSCA Section 6 imposes pre-manufacture notification burdens on novel resin chemistries entering domestic supply chains. Greater Phoenix and Austin semiconductor packaging facilities source qualified ABF panels through consolidated Tier-1 supplier agreements.
India
PLI scheme disbursements for display and semiconductor manufacturing attract substrate qualification programs from first-tier OSATs. The Ministry of Electronics and Information Technology's production-linked incentive structure covers compound semiconductors and advanced packaging. Gujarat's Dholera Special Investment Region and Karnataka's Electronics City host emerging packaging infrastructure requiring ABF material qualification.
Global Ajinomoto Build-Up Film Substrate Market Vendor Landscape
Premium-margin players sit above commodity-margin players across layer-count complexity and resin chemistry specialization. The market structure concentrates among integrated resin-substrate fabricators and captive semiconductor packaging divisions. Three archetypes dominate: integrated chemical-substrate conglomerates, independent substrate fabricators with OSAT relationships, and captive packaging divisions of semiconductor OEMs. Capacity expansion and multi-year supply agreement extension constitute the dominant competitive moves as procurement consolidates at Taiwanese and South Korean packaging houses.
Within the integrated chemical-substrate tier, Ajinomoto Co., Inc. exemplifies proprietary filler system and resin formulation control spanning synthesis to panel fabrication. Unimicron Technology Corp and Samsung Electro-Mechanics occupy positions at opposite ends of the customer relationship spectrum—Unimicron as an independent fabricator serving multiple OSATs, Samsung Electro-Mechanics as a captive supplier with internal demand insulation. These three entities anchor the competitive structure through distinct vertical scope and customer access models.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Unimicron Technology Corp |
| Ibiden Co., Ltd. |
| Nan Ya Printed Circuit Board Corporation |
| AT & S |
| Samsung Electro-Mechanics |
| Shennan Circuit |
| Kyocera |
| TOPPAN |
| Others |
Supply Flow & Price Mechanics
Sub-10 micrometer lithography expertise concentrated among veteran process engineers in Japan and Taiwan creates labor-cost differentials that widen pricing-tier spreads between premium high-layer-count substrates and entry-level single-sided variants.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the ABF substrate market by layer-count complexity and thermal performance grade. Price differentiation rests on certification tier for REACH-compliant halogen-free formulations versus legacy brominated flame-retardant platforms, alongside volume-scale procurement commitments from Taiwanese OSATs. Cost compression in standard epoxy tiers is intensifying because bisphenol-A and specialty hardener supply swings transmit directly to substrate bill-of-materials costs. Consumer electronics packaging houses exhibit the highest price sensitivity due to cost-constrained smartphone processor applications, while aerospace defense contractors accept 3-4x material premiums for polyimide thermal cycling tolerance.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Apple, AMD, and NVIDIA, while consolidated Tier-1 supplier agreements aggregate volumes for Foxconn and Jabil. Geographic supply concentrates in Japan's Kyushu corridor for resin synthesis, Taiwan's Hsinchu-Tainan science parks for high-layer-count panel fabrication, and South Korea's Giheung-Suwon corridor for Samsung captive demand. Raw material dependencies draw from bisphenol-A feedstocks, proprietary filler systems, and glass fiber reinforcement networks. Single-source synthesis risk at Ajinomoto Co.'s integrated chain represents the dominant structural vulnerability, as disruption at any node propagates through the entire build-up film ecosystem. Distribution runs through multi-year supply agreements with price-volume banding mechanisms that displace spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: resin synthesis capacity in Japan's Kyushu region faces tighter METI chemical disclosure burdens than emerging substrate qualification programs in India's Dholera Special Investment Region, creating cost-structure differentials for new capacity deployment.
For Market Incumbents: Lock in captive resin-substrate integration by securing proprietary filler system supply chains against phosphorus-based halogen-free substitution programs triggered by ECHA REACH candidate list expansions. Add sequential lamination capacity in Taiwan's Taoyuan industrial zones to absorb record volumes from Hsinchu Science Park OSATs. Prioritize qualification timeline compression for multi-regulatory tracks spanning Japan's Industrial Safety and Health Act, EU REACH, and EPA TSCA Section 6.
For New Entrants and Emerging Players: The 3-4x price-point gap between polyimide aerospace defense tiers and standard epoxy consumer electronics tiers offers white-space entry through halogen-free platform qualification for European-bound exports. Target India's PLI scheme subsidy window for display and semiconductor manufacturing before first-tier OSATs consolidate supplier relationships. Pursue joint qualification programs with Gujarat's Dholera packaging infrastructure as a go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent substrate fabricators lacking captive resin synthesis, as integrated chemical-substrate conglomerates command scarcity premiums. Long-term viability over the next decade hinges on qualification speed for glass-core hybrid architectures combining ABF dielectric layers with glass core mechanical stability. Watch for inflection signals in multi-year supply agreement extensions at Taiwanese OSATs, which indicate procurement consolidation velocity and vendor count compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Proprietary filler system control insulates Ajinomoto Co. from bisphenol-A supply swings. |
| Capacity Expansion in Taiwan Science Parks | Unimicron Technology Corp anchors flip-chip ball grid array line investments serving TSMC-adjacent facilities. |
| Halogen-Free Platform Qualification | Phosphorus-based substitution programs capture accelerated qualification windows with EU-bound packaging houses. |
| Long-Term Supply Agreement Extension | Samsung Electro-Mechanics negotiates multi-year contracts displacing spot-market purchasing. |
| Glass-Core Hybrid Architecture Development | Hydbrid material stacks open ultra-high-density routing possibilities for chiplet disaggregation. |
Methodological Framework
Direct dialogue with substrate fabrication plant managers, resin synthesis technical directors, OSAT procurement leads, semiconductor packaging engineers, and regulatory compliance officers grounded this analysis. Secondary validation drew from METI chemical substance filings, ECHA REACH candidate substance databases, EPA TSCA Section 6 pre-manufacture notifications, SEC 10-K disclosures from listed substrate fabricators, and customs trade data for epoxy resin imports. Bottom-up panel shipment tallies and top-down semiconductor packaging capex trajectories were triangulated to calibrate market sizing.
Bottom-up volume modeling by layer-count tier, resin chemistry type, and end-use application across the analysis window was cross-checked against top-down semiconductor packaging capacity expansion announcements. Segmentation dimensions included product architecture, material formulation, application vertical, and end-user procurement archetype. CAGRs were derived from installed base erosion rates for legacy substrates and penetration curves for high-layer-count chiplet interposers. Forecast inputs incorporated OSAT capital expenditure disclosures and OEM direct qualification team hiring patterns.
Caveats apply where ECHA REACH substance-of-very-high-concern list expansions, EPA TSCA Section 6 rulemakings, or METI Industrial Safety and Health Act amendments could materially shift the outlook for epoxy formulation viability. Forecasts reflect assumptions about resin synthesis capacity expansion timelines and chiplet architecture adoption curves. Periodic stress-testing of base assumptions against regulatory pre-manufacture notification burdens and qualification cycle extensions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Talc Alternatives Market
Specialty Materials
Surface Technology Market
Specialty Materials
South America Polyether Ether Ketone (Peek) Market
Specialty Materials
Dysprosium Oxide Sputtering Target Market
Specialty Materials
Solar Control Films Market
Specialty Materials
UK Lab-Grown Diamonds Market
Specialty Materials
Solar Backsheet Films Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Europe Green Sic Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
Specialty Polyamides Market
Specialty Materials
Vegan Wax Market
Specialty Materials
Conductive Plastics Market
Specialty Materials
Absorbent Booms and Socks Market