
 Transparent Conductive Coatings Market | 2026-2036
Transparent Conductive Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Transparent Conductive Coatings Market Analysis
East Asian chemical producers is expanding thin-film deposition capacity to serve OLED and solar cell fabricators. PPG Industries leverages its automotive glass coatings heritage to compete in smart window applications. Corning anchors North American supply through fused silica substrates that integrate with conductive layers. Hitachi Chemical specializes in roll-to-roll processed films for touch panel manufacturers.
Transparent conductive coatings are thin, electrically conductive layers applied to glass or polymer substrates, typically achieving sheet resistances below 100 ohms per square while maintaining optical transmittance exceeding 80 percent. Their primary purpose is to enable current collection or electrostatic shielding without blocking visible light in displays, photovoltaics, and electrochromic devices. Indium tin oxide coatings still dominate installed capacity, though conductive polymer formulations are capturing flexible electronics applications where brittleness disqualifies ceramic alternatives. Metal mesh architectures command premium positioning in large-format touch screens where linear conductivity requirements exceed ITO capabilities.
FDA regulates conductive coatings in medical device displays through biocompatibility testing protocols, while EPA oversees indium compound waste streams under hazardous substance reporting rules. REACH restricts cadmium and lead additives in European-sourced formulations, forcing reformulation toward silver nanowire and graphene composites. China's SAMR enforces GB standards for electromagnetic shielding in consumer electronics, creating compliance costs for imported coatings. Stakeholders must track how evolving rare earth export controls and perfluorinated substance restrictions alter raw material economics and sourcing geography.
Market Dynamics
The indium supply concentration in Chinese refineries is forcing display manufacturers to accelerate silver nanowire and graphene composite adoption. Material substitution timelines have compressed from five-year R&D cycles to eighteen-month qualification windows as procurement teams dual-source conductive layers.
Growth Catalysts
- FCC electromagnetic shielding mandates:US consumer electronics OEMs must upgrade conductive layers in 5G-enabled devices, expanding specification requirements for transparent films.
- South Korea display cluster expansion:Samsung and LG supply chains are localizing thin-film deposition capacity, pulling coating vendors into Seoul and Gumi industrial zones.
- Silver nanowire inkjet printing:Roll-to-roll compatible deposition methods are reducing capital barriers for flexible OLED substrate production.
Market Restraints
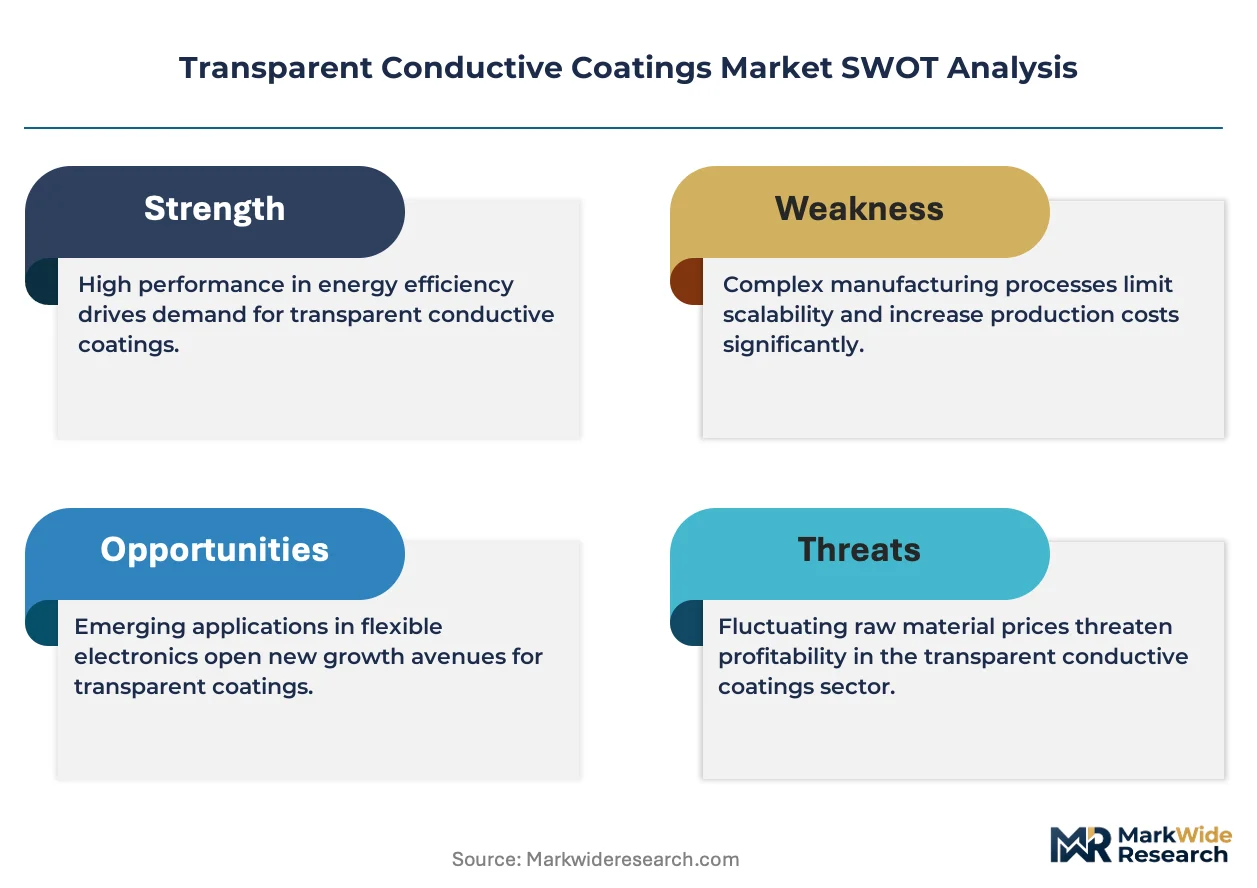
- Indium price volatility:Chinese rare earth export controls create input cost uncertainty for ITO-dependent fabricators.
- REACH cadmium restrictions:European-sourced formulations require complete reformulation, extending qualification timelines by twelve to eighteen months.
- Metal mesh linear conductivity limits:Fine-pitch architectures face yield degradation below 50 micrometer trace widths, capping resolution in premium touch panels.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for display fabs are creating first-mover advantages for conductive coating local production.
- Automotive smart glass integration:Electrochromic sunroofs and HUD windshields require specialized low-haze conductive layers at volumes absent from consumer electronics.
- EU Green Deal material passports:Circular economy compliance is creating premium pricing for recycled-content and bio-based conductive polymers.
Industry Challenges
- Thin-film deposition technician scarcity:Vacuum sputtering and atomic layer deposition expertise concentrates in East Asian equipment vendor training programs.
- Multi-layer stack integration complexity:Touch panel manufacturers face yield loss when bonding conductive coatings to anti-reflective and hardcoat films.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transparent Conductive Coatings Market |
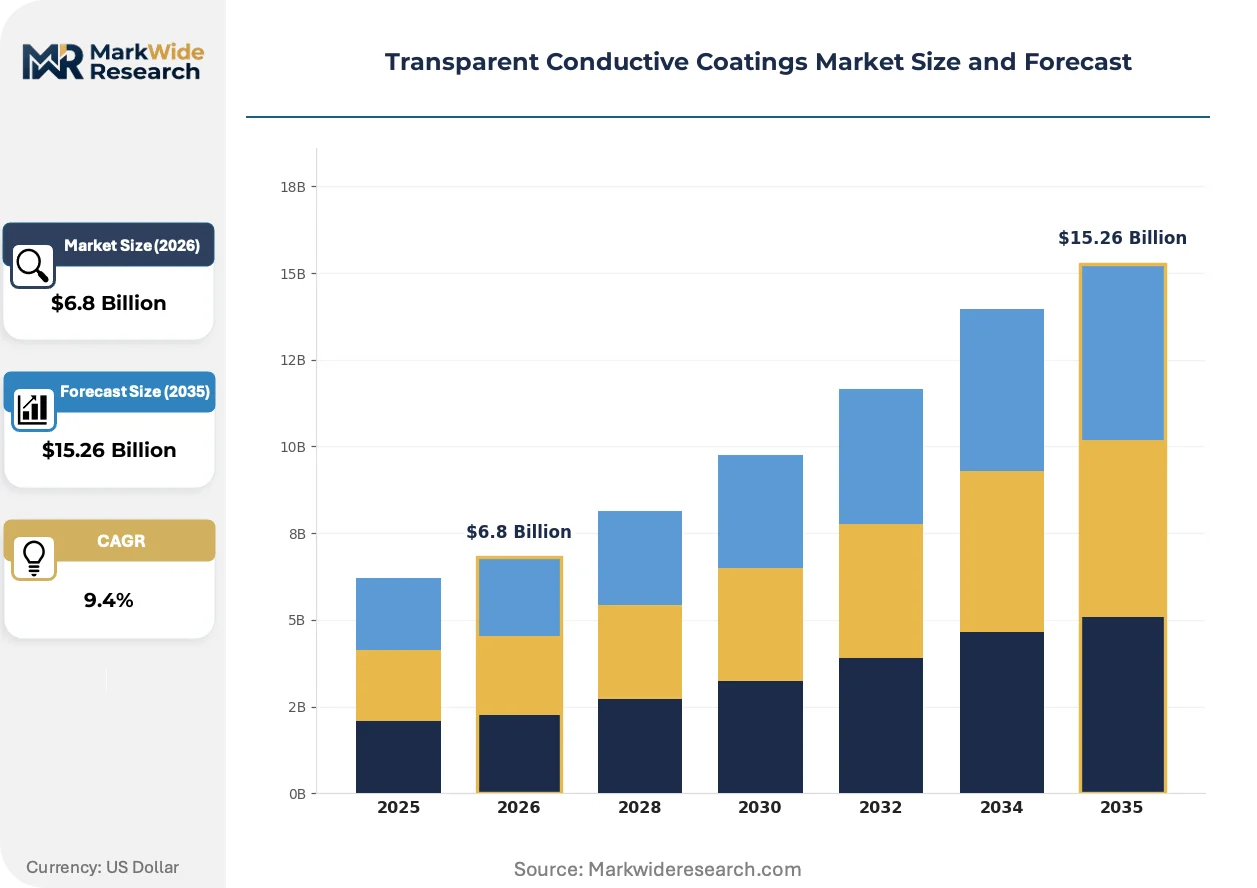
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indium Tin Oxide, Conductive Polymer, Metal Mesh, Graphene Application: Touch Screens, Solar Cells, OLED Displays, Smart Windows End User: Electronics, Automotive, Aerospace, Building & Construction Form: Films, Coatings, Sheets, Inks |
| Companies Covered | PPG Industries, Evonik Industries, 3M, Corning, Asahi Glass, Hitachi Chemical, Sumitomo Chemical, Dai Nippon Printing, Fujifim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transparent Conductive Coatings Market Emerging Trajectories
Silver nanowire dispersions are displacing ceramic oxide networks in applications demanding mechanical compliance. Regulatory pressure on indium supply chains and the mechanical failure modes of ITO on polymer substrates are accelerating materials innovation cycles.
Hybrid silver nanowire-graphene composites are consolidating technical validation across flexible display pilot lines. Korean panel makers have qualified these formulations for foldable smartphone cover windows. The technology is consolidating supplier relationships around inkjet deposition equipment vendors with proprietary dispersion chemistries.
China's SAMR enforcement of updated GB standards for electromagnetic interference in consumer electronics is tightening conductive coating performance specifications. Domestic OEMs must recertify existing ITO-supplied products or switch to alternative materials. Smartphone and tablet manufacturers in Shenzhen and Dongguan are accelerating silver nanowire supplier audits to maintain market access.
Automotive OEMs are unbundling conductive coating procurement from glass supplier contracts. Tier-1 glazing vendors previously specified coatings captive to their float glass supply agreements. European and North American electric vehicle programs now require direct coating vendor relationships to optimize electrochromic and HUD integration timelines.
Transparent Conductive Coatings Market Segmentation
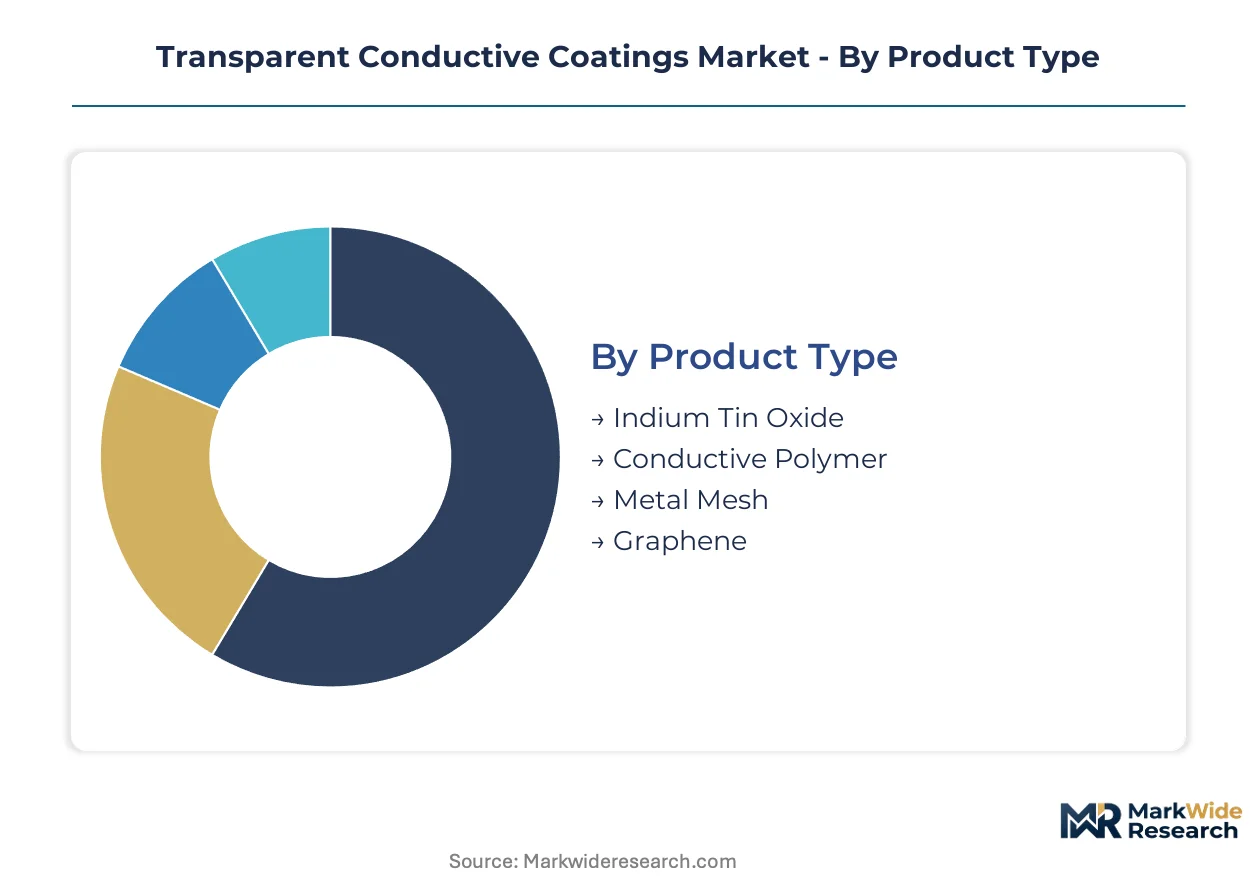
Transparent conductive coatings fragment across material chemistry, deposition format, and end-use performance requirements. Procurement teams configure specifications differently for foldable displays versus architectural glazing, creating distinct commercial segments with non-overlapping supplier bases.
Product Type:
Standardization dominates ceramic oxide formulations while polymer and carbon-based alternatives require extensive customization for substrate compatibility.
- Indium Tin Oxide:Sputtered ceramic oxide achieving sheet resistance below 15 ohms per square with optical transmittance exceeding 90 percent. Demand concentrates in South Korean OLED fabs where Samsung Display and LG Display specify ITO for rigid substrate production despite supply chain concentration risks.
- Metal Mesh:Copper or silver trace architectures embedded in polymer substrates, enabling linear conductivity beyond ceramic capabilities for large-format touch panels. Procurement from Chinese refineries faces EPA hazardous substance reporting requirements for indium waste streams, accelerating metal mesh qualification in North American automotive programs.
- Conductive Polymer:PEDOT:PSS formulations for flexible electronics where mechanical compliance exceeds conductivity requirements.
- Graphene:Single-layer carbon films for experimental transparent electrodes in next-generation solar cell prototypes.
Leading the category by volume: Indium Tin Oxide. Expanding most quickly: Metal Mesh.
Application:
Cost tiers separate consumer electronics specifications from architectural and energy applications with decade-long depreciation horizons.
- OLED Displays:Multi-layer conductive stacks integrating electron transport layers with transparent anodes, requiring atomic layer deposition precision. South Korean panel makers in Gumi and Paju industrial zones drive specification evolution for foldable and rollable form factors.
- Smart Windows:Electrochromic and thermochromic glazing for commercial buildings and automotive sunroofs, demanding low-haze conductive layers with 15-plus year durability warranties. European Green Deal material passport requirements are creating premium pricing for recycled-content conductive polymers in facade applications.
- Touch Screens:Projected capacitive layers for smartphones, tablets, and industrial interfaces.
- Solar Cells:Front electrode collection grids for thin-film photovoltaics and perovskite research cells.
Touch Screens dominates current procurement volume. Smart Windows climbs the fastest as automotive HUD integration accelerates.
End User:
Customer type determines margin structure, with aerospace and automotive programs accepting premium pricing for qualification documentation absent from electronics commodity purchasing.
- Electronics:Smartphone, tablet, and wearable OEMs specifying conductive layers through display module suppliers rather than direct coating procurement. Shenzhen and Dongguan manufacturers face SAMR GB standard recertification deadlines for electromagnetic interference compliance.
- Automotive:Tier-1 glazing vendors and direct OEM relationships for electrochromic sunroofs, HUD windshields, and heated windscreens. European electric vehicle programs in Germany and France require coating vendor direct relationships unbundled from glass supply agreements.
- Aerospace:De-icing and EMI shielding applications for flight deck displays and cabin windows.
- Building & Construction:Dynamic glazing for commercial facades and residential retrofits.
Electronics commands greatest volume. Automotive generates steepest expansion trajectory through smart glass integration.
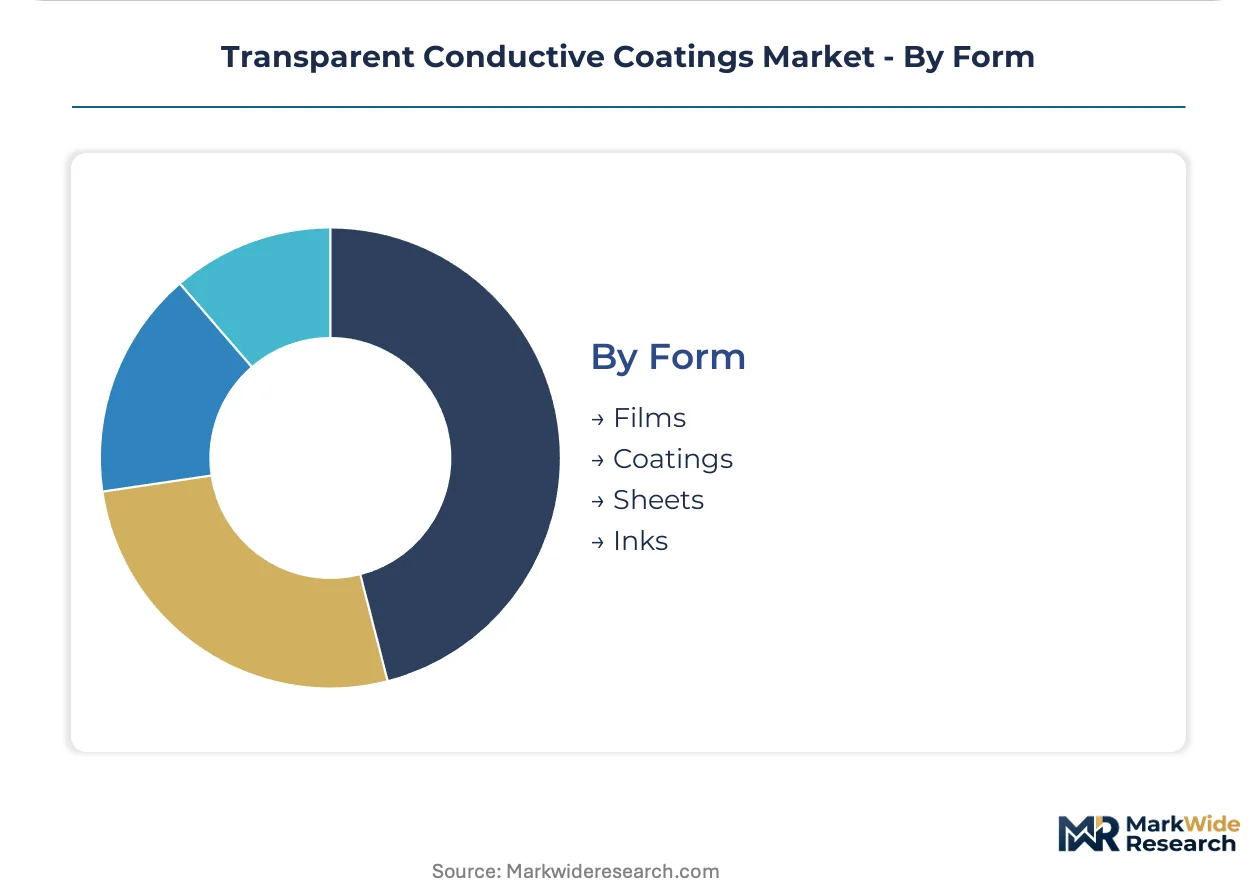
Form:
Supply concentration varies by manufacturing maturity, with film and coating formats consolidating around East Asian deposition equipment vendors while ink formulations fragment across specialty chemical suppliers.
- Films:Roll-to-roll processed PET and COP substrates with vacuum-sputtered or solution-coated conductive layers. Hitachi Chemical and Korean material suppliers dominate flexible film supply for touch panel laminators.
- Coatings:Liquid deposition for direct application to glass and polymer surfaces in captive OEM operations. PPG Industries leverages automotive glass coatings heritage for smart window conductive layer integration.
- Sheets:Rigid glass substrates with patterned conductive traces for display and photovoltaic applications.
- Inks:Silver nanowire and graphene dispersions for inkjet and screen printing deposition methods.
Films leads by volume. Inks gains share fastest as inkjet printing reduces capital barriers for flexible OLED substrate production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese indium refineries concentrate raw material supply for transparent conductive oxide networks. This geographic anchor shapes procurement patterns across display manufacturing clusters worldwide. Regional demand fragmentation follows the dispersion of OLED fabs and touch panel assembly operations.
South Korea
Samsung Display and LG Display operate integrated OLED production in Gumi and Paju industrial zones. The Ministry of Trade, Industry and Energy enforces local content requirements through supply chain certification programs. Seoul-based material suppliers are scaling atomic layer deposition capacity to serve foldable display pilot lines.
China
Shenzhen and Dongguan manufacturers face accelerated recertification deadlines for electromagnetic interference compliance. SAMR enforcement of updated GB standards is forcing silver nanowire supplier audits across consumer electronics OEMs. Yangtze River Delta deposition equipment vendors are consolidating inkjet printing process expertise.
United States
Automotive HUD and electrochromic sunroof programs are unbundling coating procurement from traditional glass supply agreements. EPA hazardous substance reporting rules govern indium compound waste streams from ITO-dependent fabricators. Michigan and Ohio electric vehicle assembly plants are qualifying direct coating vendor relationships.
Germany
European Green Deal material passport requirements are creating premium pricing tiers for recycled-content conductive polymers in facade applications. ECHA REACH restrictions on cadmium and lead additives force complete formulation reformulation for architectural glazing. Bavaria-based automotive OEMs are specifying low-haze conductive layers for smart windshield integration.
Japan
Hitachi Chemical anchors flexible film supply for touch panel laminators through roll-to-roll processing expertise. METI technology roadmaps prioritize graphene composite validation for next-generation solar cell prototypes. Chubu region material suppliers are expanding PET substrate coating capacity.
Transparent Conductive Coatings Market Vendor Landscape
Global majors compete with regional champions across deposition technology and substrate format specialization. The vendor base separates into ITO sputtering equipment incumbents, silver nanowire dispersion specialists, and automotive glazing integrators. Three archetypes dominate: ceramic oxide network providers, metal mesh architects, and polymer composite formulators. Capacity expansion and strategic technology licensing represent the primary competitive vectors.
Among diversified chemical conglomerates, PPG Industries and Evonik Industries exemplify coating heritage leverage into smart window and flexible electronics applications. Corning occupies a position anchoring North American supply through fused silica substrate integration. These three represent distinct strategic postures: automotive glazing extension, specialty chemical formulation, and materials science substrate anchoring.
| Leading Market Players |
|---|
| PPG Industries |
| Evonik Industries |
| 3M |
| Corning |
| Asahi Glass |
| Hitachi Chemical |
| Sumitomo Chemical |
| Dai Nippon Printing |
| Fujifim |
| Others |
Supply Flow & Price Mechanics
Automotive OEM unbundling of coating procurement from glass supply agreements is forcing deposition equipment vendors to reconfigure service contracts and warranty terms, compressing margin structures for suppliers lacking direct OEM qualification pathways. This demand-side restructuring cascades through material pricing tiers as silver nanowire and graphene composite suppliers compete for newly accessible specification windows.
Pricing Analysis
Warranty and service bundling separates premium coating vendors from commodity suppliers, with South Korean display cluster vendors demanding multi-year performance guarantees for foldable OLED applications while automotive programs unbundle installation support from material costs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with REACH-compliant and FDA-biocompatibility-tested formulations commanding substantial premiums. Cost compression in standard-grade ITO alternatives is intensifying because Chinese rare earth export controls feed input volatility into spot-market silver nanowire pricing. Electronics OEMs through Shenzhen and Dongguan manufacturing bases exhibit highest price sensitivity, whereas European automotive programs accept premium positioning for Green Deal material passport compliance.
Supply Chain Analysis
Regional distribution centers in South Korea, Japan, and Germany anchor hub-and-spoke patterns for deposition equipment spare parts and precursor chemicals, with Yangtze River Delta vendors consolidating inkjet printing process expertise for silver nanowire dispersions. Raw material flows draw from Chinese indium refineries, Japanese PET substrate manufacturers, and Korean atomic layer deposition equipment specialists. Single-source vulnerability concentrates in Chinese rare earth processing capacity, where export permit delays propagate through ITO-dependent fabricator scheduling. Distribution runs through display module suppliers for electronics applications and direct Tier-1 relationships for automotive glazing programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indium supply concentration and compressed eighteen-month qualification windows for alternative materials are forcing capital-constrained formulators into distressed exit scenarios, consolidating procurement relationships around deposition equipment vendors with captive dispersion chemistry expertise.
For Market Incumbents: Lock in foldable display pilot line relationships through exclusive inkjet deposition equipment partnerships, securing multi-year offtake commitments from Samsung Display and LG Display before silver nanowire qualification windows close. Backward integration into proprietary dispersion chemistry protects margin structures against commodity silver nanowire suppliers. Capacity addition in Gumi and Paju industrial zones reinforces local content certification requirements enforced by South Korea's Ministry of Trade, Industry and Energy. For New Entrants and Emerging Players: Inkjet-compatible silver nanowire-graphene composites offer the most penetrable wedge for flexible OLED substrate production, with Indian PLI scheme incentives for display fabs creating first-mover manufacturing advantages absent established Korean supplier relationships. Target automotive HUD and electrochromic sunroof specifications where European and North American electric vehicle programs require direct coating vendor relationships unbundled from glass supply agreements. Go-to-market positioning centers on low-haze conductive layer validation for smart windshield integration timelines. For Investors and Strategic Acquirers: The window for entry favors deposition equipment vendors with proprietary dispersion chemistries and established foldable display pilot line validations. Long-term viability across the analysis window rests on qualification speed for alternative materials as ITO substitution accelerates. Acquisition target archetype: roll-to-roll processing specialists with automotive glazing heritage and REACH-compliant formulation libraries. Watch for SAMR GB standard enforcement deadlines as inflection indicators for silver nanowire supplier audit acceleration across Shenzhen and Dongguan OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dispersion Chemistry | Captive silver nanowire formulation control protects margins against Chinese rare earth export volatility. |
| Automotive Direct OEM Qualification | Unbundling from glass supply agreements opens specification influence for electrochromic and HUD integration. |
| India PLI Manufacturing Footprint | First-mover display fab localization captures incentive-backed procurement relationships absent Korean incumbent density. |
| Green Deal Material Passport Certification | Premium pricing tiers for recycled-content conductive polymers in European facade applications justify reformulation investment. |
| Inkjet Deposition Equipment Partnership | Proprietary process integration with Korean panel makers locks in foldable display pilot line supplier status. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews involving thin-film deposition technicians, touch panel procurement leads, automotive glazing program managers, and conductive polymer R&D directors. Secondary validation drew from ECHA REACH substance restriction databases, SAMR GB standard enforcement notices, EPA hazardous substance reporting records, and South Korean Ministry of Trade local content certification documents. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across material chemistry and application dimensions.
Granularity-level modeling distinguished sputtered ceramic oxide, metal mesh, conductive polymer, and graphene composite formulations at the chemistry-substrate-format intersection, with application-level resolution across OLED displays, smart windows, touch screens, and solar cells. End-user segmentation captured electronics, automotive, aerospace, and building procurement patterns. CAGRs derived from replacement rate assumptions for ITO-dependent capacity, SAMR recertification deadline impacts, and automotive smart glass content-per-vehicle trajectories. Regional production cluster analysis incorporated South Korean OLED fab expansion schedules and Indian PLI scheme incentive disbursement timelines.
Several conditions sit outside the modeled scope, including unannounced rare earth export control escalations, breakthrough perovskite solar cell electrode architectures, and automotive OEM insolvency events restructuring glazing program commitments. Forecasts reflect documented assumptions around eighteen-month qualification window stability and REACH cadmium restriction enforcement consistency. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that silver nanowire supplier audit acceleration or foldable display yield breakthroughs could materially revise substitution timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Japan Architectural Coatings Market
Coatings
Coatings and Fillings Market
Coatings
Global Surface Protection Films Market
Coatings
Breathable Antimicrobial Coatings Market
Coatings
Global Low Friction Coatings Market
Coatings
Marking Coatings Market
Coatings
Asia-Pacific Radiation Curable Coatings Market
Coatings
Nigeria Protective Coatings Market
Coatings
Rail Coatings Market
Coatings
Global High-Performance Anti-Corrosion Coatings Market
Coatings
Saudi Arabia Industrial Coatings Market
Coatings
Protective and Marine Coatings Market
Coatings
Coating Agents for Synthetic Leather Market
Coatings
Global Abrasion Resistant Coatings Market
Coatings
Electrocoat Market
Coatings
Russia Protective Coatings Market