
 Acrylate Oligomer Market | 2026-2036
Acrylate Oligomer Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylate Oligomer Market Analysis
The capability gap between integrated petrochemical producers and specialty resin formulators is collapsing as raw material volatility compresses margins across the value chain. Covestro leverages its upstream isocyanate and polyol infrastructure to anchor acrylate oligomer supply security for European coating customers. Eternal Materials Co., Ltd. competes through specialized UV-curable formulations targeting Asian electronics laminators. Mitsubishi Chemical Corporation dominates aromatic urethane acrylate segments where Japanese automotive OEMs demand exacting color stability.
Acrylate oligomers are low-molecular-weight prepolymers terminated with acrylate or methacrylate functional groups, typically ranging from 500 to 10,000 Daltons in molecular weight, designed to crosslink rapidly under UV or electron beam radiation to form durable polymer networks. Their primary industrial purpose centers on enabling solvent-free curing in protective coatings, adhesives, and printed electronics where volatile organic compound emissions face strict limits. UV Curable product types command the deepest margin pools as electronics manufacturers prioritize instant-dry processing throughput, while Low Viscosity grades penetrate fastest into inkjet and digital printing applications where precise droplet control determines output quality. Liquid formulations sustain volume leadership across industrial coating lines, though Gel formats gain traction in medical device bonding where controlled flow prevents substrate contamination.
EPA oversight of hazardous air pollutants under the National Emission Standards for Hazardous Air Pollutants shapes US coating facility compliance investments, directly influencing oligomer selection toward lower volatility chemistries. REACH registration requirements and the EU Green Deal's decarbonization mandates compel European formulators to document substance safety and pursue bio-based acrylate feedstock pathways. China's MEE enforces increasingly stringent VOC limits in industrial coatings, accelerating domestic reformulation toward compliant oligomer systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D commitments.
Market Dynamics
Raw material volatility is compressing margins across the acrylate oligomer value chain, forcing specialty resin formulators to secure captive isocyanate and polyol supplies or cede ground to integrated petrochemical producers with upstream infrastructure.
Growth Catalysts
- REACH and RoHS compliance mandates:European coating manufacturers face tightening formulation standards for low-migration oligomers, accelerating reformulation investments toward compliant UV-curable systems.
- Electronics laminators:Asian manufacturers of printed circuit boards and display modules prioritize instant-dry processing throughput, deepening demand for high-reactivity acrylate oligomers in protective coatings.
- China's MEE VOC enforcement:Stricter industrial coating emissions limits drive domestic resin producers toward waterborne and solvent-free oligomer platforms.
Market Restraints
- Propylene oxide supply concentration:Feedstock availability tightens around integrated crackers in the US Gulf Coast and Middle Eastern petrochemical complexes, exposing formulators to price spike vulnerability.
- Photoinitiator technical limitations:Oxygen inhibition during UV curing restricts line speeds in high-volume automotive coating applications, capping throughput gains.
- Bio-based acrylate cost premiums:Plant-derived feedstock pathways command 15-40% raw material cost elevations versus petroleum-based equivalents, constraining mass-market penetration.
Strategic Opportunities
- Medical device bonding applications:Gel-format oligomers with controlled flow characteristics penetrate surgical instrument and diagnostic equipment assembly where substrate contamination prevention is critical.
- EU Green Deal decarbonization incentives:Bio-based acrylate feedstock documentation and carbon footprint verification unlock preferential procurement status with European automotive OEMs.
- Digital printing convergence:Low-viscosity oligomers formulated for precise droplet control capture share in inkjet and additive manufacturing segments as printhead resolution advances.
Industry Challenges
- Photochemistry skill scarcity:Formulation chemists with expertise in free-radical kinetics and radiation curing mechanisms remain concentrated among legacy UV coating specialists, constraining R&D expansion.
- Dual-registration compliance timelines:REACH substance registration and EPA TSCA premanufacture notification processes impose 18-36 month product commercialization delays for novel oligomer architectures.
- Legacy coating line retrofit costs:Solvent-based infrastructure conversion to UV-curable systems demands capital-intensive lamp installation and nitrogen inerting equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylate Oligomer Market |
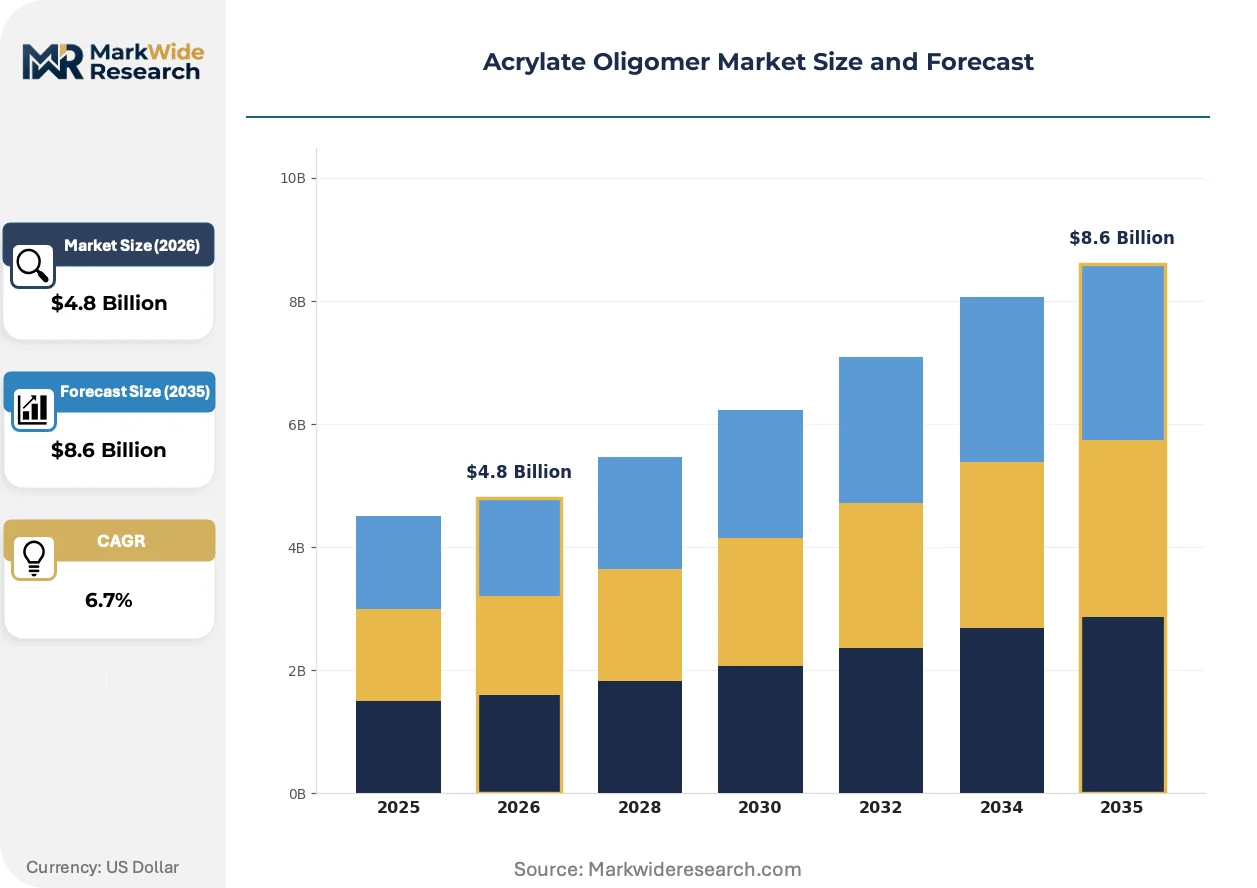
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Reactive, Low Viscosity, Thickening Agent, UV Curable End Use Industry: Coatings, Adhesives, Electronics, Inks Formulation: Liquid, Solid, Gel, Paste Application: 3D Printing, Protective Coatings, Surface Treatment, Sealants |
| Companies Covered | Covestro, IGM Resins, BASF SE, DIC Corporation, Toagosei Co., Ltd., Arkema, Evonik Industries AG, Eternal Materials Co., Ltd., Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylate Oligomer Market Emerging Trajectories
Formulation science is diverging along performance-specialization axes as end-users reject universal oligomer platforms in favor of application-tuned molecular architectures with calibrated viscosity, functionality, and cure response.
Hybrid oligomer chemistries combining urethane acrylate toughness with epoxy acrylate chemical resistance are fragmenting the traditional product-type taxonomy. Automotive refinish shops and industrial maintenance contractors adopt these intermediate-performance grades to reduce SKU complexity without sacrificing durability. The resulting specification proliferation is fragmenting supplier R&D priorities and compressing development cycles for dedicated single-chemistry platforms.
EPA National Emission Standards for Hazardous Air Pollutants enforcement is intensifying compliance investments at US coating facilities. The regulatory pressure redirects oligomer selection toward lower-volatility chemistries with reduced hazardous air pollutant content. Southern California and Texas Gulf Coast manufacturing clusters respond fastest due to state-level overlay requirements from South Coast AQMD and TCEQ.
Specification consolidation among multinational electronics contract manufacturers is compressing approved vendor lists for laminating adhesives and conformal coatings. Tier-1 assemblers in Taiwan and South Korea now mandate oligomer qualification through centralized global procurement functions rather than regional plant discretion. This buyer concentration shifts pricing leverage toward volume-committed suppliers with multi-site technical service capabilities.
Acrylate Oligomer Market Segmentation
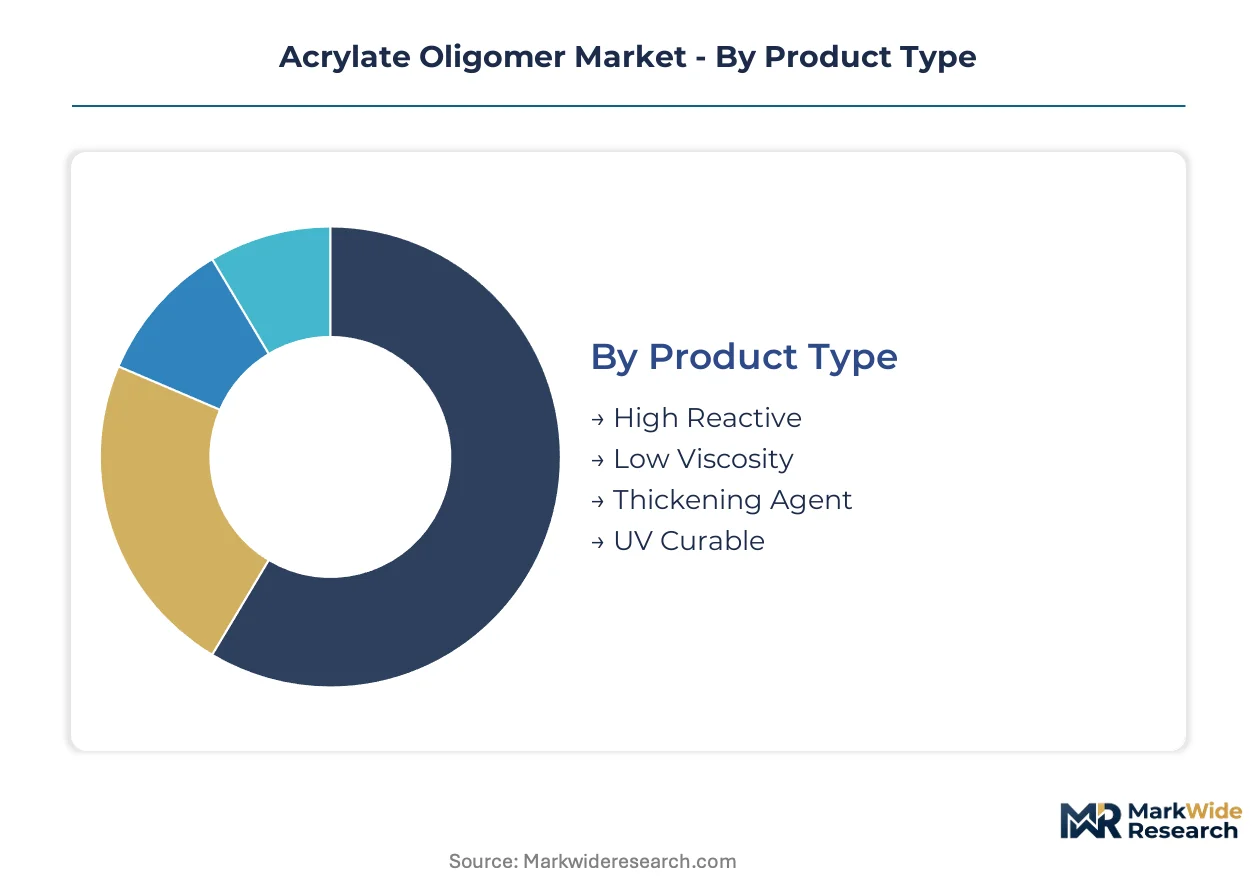
Acrylate oligomer suppliers configure product portfolios around curing kinetics and viscosity profiles that match specific manufacturing throughput requirements. Segmentation discipline separates commodity resin sales from specialty formulations commanding formulation service premiums and technical support retainers.
Product Type:
Margin pools concentrate in high-reactivity grades where electronics manufacturers pay premiums for instant-cure throughput, while low-viscosity segments compete on volume throughput to inkjet and digital printing OEMs.
- UV Curable:These oligomers crosslink within seconds under UV or electron beam radiation, eliminating thermal curing ovens and enabling inline processing. Demand concentrates among Asian electronics laminators in Taiwan and South Korea where printed circuit board and display module manufacturers prioritize production velocity and factory footprint reduction.
- Low Viscosity:Formulations below 500 centipoise enable precise droplet control in piezoelectric printheads. Inkjet printer OEMs in Japan and Germany specify these grades for high-resolution graphics and additive manufacturing applications where satellite-free deposition determines output quality.
- High Reactive:Multi-functional acrylate architectures achieve complete conversion at reduced photoinitiator loadings. Automotive refinish shops in the US and Germany adopt these systems to accelerate clearcoat throughput while meeting EPA and REACH VOC limits.
- Thickening Agent:Rheology-modifying oligomers build viscosity without solvent addition. Screen printing operations across China's Pearl River Delta integrate these grades to control paste flow in ceramic and solar cell metallization processes.
The dominant share belongs to UV Curable grades, while Low Viscosity formulations are closing the gap fastest as digital printing resolution standards advance.
End Use Industry:
Application-specific certification requirements fragment demand patterns, with electronics and coatings commanding divergent specification regimes around migration limits and weathering performance.
- Coatings:Protective and decorative film formers dominate industrial maintenance, automotive refinish, and wood finishing segments. German and Japanese automotive OEMs specify aromatic urethane acrylates for color stability under xenon arc exposure, driving formulation complexity and supplier qualification barriers.
- Electronics:Conformal coatings, solder masks, and display laminating adhesives require ultra-low ionic content and minimal extractables. Taiwan-based contract manufacturers centralize oligomer procurement through global approved vendor lists, compressing supplier margins while demanding multi-site technical service capabilities.
- Adhesives:Structural bonding applications in medical devices and transportation assembly favor controlled flow characteristics. Gel-format oligomers penetrate surgical instrument manufacturing where substrate contamination prevention overrides cure speed priorities.
- Inks:Graphic arts and packaging segments prioritize pigment wetting and adhesion to treated polyolefin films. Narrow-web label converters in Italy and the US specify oligomer systems compatible with LED-UV curing architectures to reduce energy consumption and lamp heat output.
Coatings maintains volume leadership, though Electronics is expanding most quickly as display and semiconductor packaging complexity intensifies.
Formulation:
Physical state selection determines processing equipment compatibility and storage stability, with liquid formats sustaining pipeline economics while gel and paste systems capture niche premiums.
- Liquid:Pumpable formulations dominate high-throughput industrial coating lines. Continuous stirred-tank reactor output in China's Shandong and Jiangsu provinces supplies these grades at scale, with domestic producers capturing share from European and Japanese imports.
- Gel:Thixotropic rheology prevents sag on vertical substrates and controlled flow in precision dispensing. Medical device assemblers in Massachusetts and Bavaria specify these systems for diagnostic equipment bonding where contamination control is critical.
- Solid:Flake or pellet formats enable hot-melt compounding and extended ambient storage. Powder coating manufacturers in India's Gujarat and Maharashtra states integrate solid oligomers into hybrid UV-thermal cure systems for heat-sensitive substrates.
- Paste:Highly filled formulations accommodate pigment and extender loading for screen printing and thick-film applications. Solar cell metallization paste producers in China's Jiangsu province utilize these grades to achieve fine-line silver deposition with controlled spread.
Liquid formulations hold the dominant position, while Gel systems are gaining share fastest in medical and precision assembly applications.
Application:
Performance requirements diverge sharply between additive manufacturing layer resolution demands and protective coating durability specifications, fragmenting R&D priorities across supplier technical centers.
- 3D Printing:Stereolithography and digital light processing systems demand oligomers with calibrated shrinkage control and green-state strength. Photopolymer resin formulators in the Netherlands and California compete on z-axis resolution and post-cure dimensional stability for dental and jewelry prototyping segments.
- Protective Coatings:Abrasion, chemical, and weathering resistance specifications vary by substrate and exposure environment. Industrial maintenance contractors in Texas and Rotterdam adopt hybrid urethane-epoxy acrylate grades to reduce SKU complexity without sacrificing performance.
- Surface Treatment:Functionalization of metals, plastics, and composites through grafting or thin-film deposition. Electronics manufacturers in South Korea apply these treatments to improve adhesion and corrosion resistance on flexible printed circuit substrates.
- Sealants:Gap-filling and environmental sealing applications in transportation and construction. Joint sealant formulators in France and Japan specify oligomers with balanced modulus and elongation to accommodate thermal cycling without cohesive failure.
Protective Coatings commands the largest share, while 3D Printing is climbing the fastest as vat photopolymerization throughput and material property breadth expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity, accepting formulation premiums for REACH-compliant and color-stable grades, while Chinese purchasers drive hard bargains as domestic resin capacity floods the market with standard UV-curable alternatives.
China
Electronics laminators in Jiangsu and Guangdong provinces consume high-reactivity oligomers for printed circuit board production, with display module manufacturers expanding conformal coating lines. MEE enforcement of VOC limits in industrial coatings accelerates reformulation toward waterborne and solvent-free systems. Shandong and Jiangsu province producers now supply liquid oligomers at scale, displacing European and Japanese imports.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify aromatic urethane acrylates for exterior clearcoats demanding xenon arc color stability. REACH registration requirements and EU Green Deal decarbonization mandates compel formulators to document substance safety and pursue bio-based feedstock pathways. The Cologne-Düsseldorf-Ruhr corridor anchors specialty resin formulation centers serving continental coating customers.
United States
Industrial maintenance contractors in Texas and Louisiana adopt hybrid urethane-epoxy acrylate grades to reduce SKU complexity without sacrificing chemical resistance. EPA National Emission Standards for Hazardous Air Pollutants enforcement redirects oligomer selection toward lower-volatility chemistries. Southern California manufacturing clusters respond fastest due to South Coast AQMD overlay requirements.
Japan
Piezoelectric printhead OEMs in Tokyo and Osaka prefectures specify low-viscosity oligomers below 500 centipoise for high-resolution graphics and additive manufacturing. METI industrial standards shape qualification protocols for electronics-grade materials. The Nagoya-Toyota industrial corridor drives demand for automotive refinish clearcoats with accelerated cure kinetics.
South Korea
Taiwan-based contract manufacturers now centralize oligomer procurement through Seoul-supervised global approved vendor lists for laminating adhesives. MFDS medical device regulations constrain extractables in diagnostic equipment bonding applications. The Busan-Ulsan petrochemical complex feeds downstream UV-curable formulation operations.
Acrylate Oligomer Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated petrochemical majors leveraging upstream isocyanate and polyol infrastructure against specialized formulators competing on application-specific molecular architectures. The vendor base stratifies into three tiers: multinational chemical conglomerates with captive raw material supplies, mid-cap regional specialists with deep UV-curing formulation expertise, and emerging Asian producers scaling commodity-grade output. Dominant competitive moves include backward integration into propylene oxide and polyol feedstocks, and strategic partnerships with electronics contract manufacturers seeking multi-site technical service capabilities.
Within the integrated petrochemical tier, Covestro and BASF SE exemplify archetypes anchoring supply security through upstream control over isocyanate and polyol infrastructure. Among Asia-Pacific specialists, Eternal Materials Co., Ltd. occupies a position representing the regional formulator archetype competing through UV-curable expertise. Mitsubishi Chemical Corporation sits within the premium-performance segment, exemplifying Japanese chemical conglomerates serving exacting automotive OEM specifications.
| Leading Market Players |
|---|
| Covestro |
| IGM Resins |
| BASF SE |
| DIC Corporation |
| Toagosei Co., Ltd. |
| Arkema |
| Evonik Industries AG |
| Eternal Materials Co., Ltd. |
| Mitsubishi Chemical Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Chinese electronics laminators and Shandong province resin producers lock in propylene oxide supply access while capping price visibility for European specialty formulators exposed to spot market volatility. This contract-structure asymmetry concentrates margin pressure on non-integrated players lacking captive polyol infrastructure.
Pricing Analysis
After-sales technical service retainers drive lifetime value for acrylate oligomer suppliers, with formulation support contracts commanding premiums equivalent to 15-25% of base resin value. Three-tier pricing structure across REACH-compliant specialty, standard UV-curable, and commodity industrial grades separates automotive OEM specifications from inkjet printing volumes. Cost compression in standard grades intensifies because domestic Chinese producers flood export markets with undifferentiated liquid formulations. Electronics contract manufacturers in Taiwan and South Korea demonstrate lowest price sensitivity, accepting formulation premiums for multi-site qualification, while Indian powder coating converters drive hardest bargain negotiations.
Supply Chain Analysis
Strait of Hormuz transit underwrites propylene oxide feedstock security for Middle Eastern crackers supplying Asian acrylate oligomer producers, exposing European formulators to logistics chokepoint vulnerability. Manufacturing concentrates in China, Germany, and Japan, with Shandong province liquid resin output, Cologne-Düsseldorf specialty formulation, and Nagoya-Toyota automotive supply anchoring regional hubs. Raw material dependencies center on propylene oxide, isocyanates, and photoinitiator packages. Single-source vulnerability concentrates around German aromatic urethane acrylate producers serving color-critical automotive clearcoats. Distribution runs through direct mill relationships for high-volume electronics laminators and specialty chemical distributors for fragmented coating applicators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Free-radical photochemistry expertise sits concentrated among legacy UV coating specialists, creating acquisition premiums for firms with documented formulation libraries and qualified customer relationships.
For Market Incumbents: Consolidate backward integration into propylene oxide and specialty polyol feedstocks to defend margin position against integrated petrochemical majors. Capture multi-site technical service contracts with Taiwan-based electronics contract manufacturers before procurement centralization locks out regional specialists. Prioritize REACH registration completion for novel bio-based architectures ahead of EU Green Deal procurement preference deadlines. For New Entrants and Emerging Players: Multi-site technical service gaps where incumbents under-serve present white-space entry points for mid-cap formulators with electronics laminator expertise. Target medical device bonding applications in Massachusetts and Bavaria where gel-format oligomer specifications remain underserved by commodity producers. Lead with formulation partnership models rather than resin commodity sales to bypass incumbent volume commitments. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated petrochemical majors with captive feedstock infrastructure over standalone formulators. Long-term viability over the next decade hinges on upstream supply security and regulatory qualification depth rather than R&D novelty alone. Watch for MEE enforcement acceleration in Jiangsu province as signal for Chinese domestic producer export push intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Covestro and BASF SE anchor supply security for European coating customers against feedstock volatility. |
| REACH Registration for Bio-Based Architectures | Documentation unlocks EU Green Deal preferential procurement status with German automotive OEMs. |
| Multi-Site Technical Service Expansion | Taiwan electronics contract manufacturers centralize vendor lists, demanding qualified global support. |
| Gel-Format Oligomer Development | Controlled flow characteristics penetrate Massachusetts surgical instrument bonding applications. |
| Joint Venture with Electronics Laminators | South Korean display module producers seek captive resin supply for conformal coating lines. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with coating formulators, electronics laminator procurement leads, resin plant managers, and UV equipment OEM technical directors. Secondary validation drew from customs trade data, ECHA REACH registration databases, SEC 10-K filings of listed chemical producers, and MEE enforcement disclosure records. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down resin production capacity assessments.
Across the projection horizon, the analytical framework modeled segmentation dimensions including curing kinetics tier, viscosity profile band, end-use industry certification requirements, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific forecast inputs incorporated photoinitiator technical limitation constraints and automotive OEM color stability specification evolution.
Forecasts assume regulatory continuity in REACH, EPA NESHAP, and China MEE regimes; material policy shifts would require re-modeling demand trajectories. Practitioners should keep alternative scenarios live as EU Green Deal decarbonization incentive structures and bio-based feedstock cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Waterproofing Admixture Market
Adhesives & Sealants
Asia-Pacific Epoxy Curing Agents Market
Adhesives & Sealants
Adhesive Equipment Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Wood Adhesives Market
Adhesives & Sealants
North America Construction Adhesives and Sealants Market
Adhesives & Sealants
Thailand Adhesives Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
Global Acrylic Adhesives Market
Adhesives & Sealants
Hot Glue Guns Market
Adhesives & Sealants
Europe, Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market