
 Self-Cleaning Coatings Market | 2026-2036
Self-Cleaning Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Cleaning Coatings Market Outlook
Buyer concentration across the construction sector is restructuring as commercial developers consolidate procurement through fewer national facade contractors. PPG Industries leverages its automotive OEM relationships to cross-sell self-cleaning variants into fleet maintenance programs. Akzo Nobel N.V. anchors European demand through marine and protective coatings distribution networks. Jotun Group dominates Middle East project specifications through direct specification relationships with EPC firms.
Self-cleaning coatings are functional surface treatments that exploit photocatalytic titanium dioxide or fluoropolymer chemistry to degrade organic matter or repel water and oils, typically achieving contact angles above 150 degrees in superhydrophobic grades. These formulations reduce maintenance cycles on exposed substrates ranging from curtain walls to vehicle clearcoats. Photocatalytic products lead volume due to maturity in construction glass applications, while superhydrophobic variants capture expanding margin pools in electronics moisture protection. Nanotechnology-based sol-gel deposition is displacing conventional spray methods in precision electronics as manufacturers seek sub-micron film uniformity.
EPA VOC regulations and REACH substance restrictions are tightening permissible solvent content in coating formulations, directly accelerating waterborne and powder-based self-cleaning development. ECHA evaluation of titanium dioxide classification has forced reformulation investments across European suppliers. China's MEE enforcement of GB standards on architectural coatings is reshaping import requirements. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments.
Market Dynamics
Photocatalytic titanium dioxide chemistry is forcing wholesale reformulation across architectural coatings as REACH substance restrictions and EPA VOC limits simultaneously tighten, compressing solvent-based product lifecycles while accelerating waterborne alternatives.
Growth Catalysts
- REACH Titanium Dioxide Classification:ECHA's carcinogen designation has triggered reformulation investments that favor compliant self-cleaning variants, redirecting R&D budgets toward photocatalytic alternatives.
- China Infrastructure Renewal:MEE enforcement of GB standards on architectural coatings is reshaping import requirements and prioritizing lifecycle cost reduction in facade procurement.
- Fleet Maintenance Programs:Automotive OEMs are cross-selling self-cleaning clearcoats into commercial vehicle aftercare, exploiting existing specification relationships.
Market Restraints
- Titanium Dioxide Supply Concentration:Feedstock production clusters in select Chinese provinces, exposing formulators to geographic concentration risk and input cost volatility.
- Fluoropolymer Cost Structure:Perfluorinated precursor chemistry carries premium raw material burdens that compress margins in superhydrophobic grades.
- Photocatalytic Substrate Limitation:UV-activation requirements restrict efficacy on north-facing facades and interior applications, narrowing addressable surface area.
Strategic Opportunities
- Electronics Moisture Protection:Superhydrophobic nanocoatings are penetrating smartphone and wearable assembly lines, capturing margin pools beyond construction saturation.
- Marine Hull Applications:Biofouling-resistant formulations align with tightening port authority discharge regulations in Mediterranean and Baltic jurisdictions.
- Sol-Gel Distribution Innovation:Precision electronics manufacturers are adopting direct dip-coating partnerships, bypassing conventional distributor markups.
Industry Challenges
- Formulation Chemist Scarcity:Cross-disciplinary expertise spanning photocatalysis and polymer science remains concentrated among aging specialist cohorts.
- Multijurisdictional Certification Timelines:Divergent substance notification requirements between EPA, ECHA, and China's MEE extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Cleaning Coatings Market |
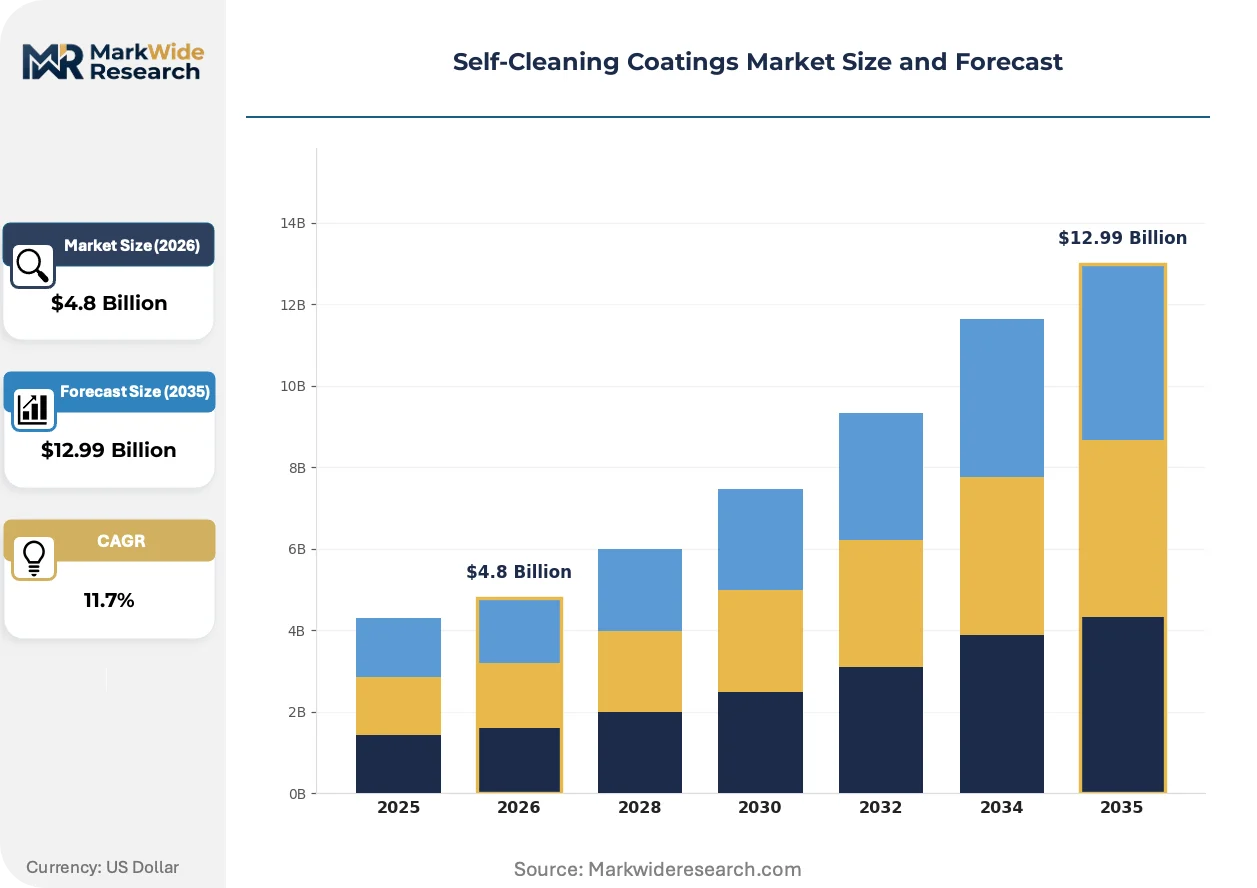
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrophobic, Hydrophilic, Photocatalytic, Superhydrophobic Application: Automotive, Construction, Electronics, Textiles Technology: Sol-gel, Spray Coating, Dip Coating, Nanotechnology End User: Residential, Industrial, Commercial, Institutional |
| Companies Covered | BASF SE, Nippon Paint Holdings Co., Ltd., PPG Industries, Inc., RPM International Inc., Axalta Coating Systems, Akzo Nobel N.V., 3M Company, Jotun Group, The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Cleaning Coatings Market Strategic Shifts
Nanotechnology deposition methods are compressing film thickness tolerances while regulatory chemistry restrictions are redirecting formulation priorities. Buyer specification authority is consolidating around fewer national facade contractors.
Sol-gel nanotechnology is automating sub-micron film uniformity in electronics manufacturing. Smartphone assemblers in East Asia are replacing spray booths with precision dip-coating lines. This transition is automating quality control and reducing coating material waste rates.
EPA VOC regulations are tightening permissible solvent content in architectural coatings, directly accelerating waterborne self-cleaning development. Formulators are eliminating aromatic hydrocarbon carriers to maintain specification eligibility. Commercial glazing contractors in the United States are responding by pre-qualifying low-VOC alternatives.
Consolidated procurement through national facade contractors is compressing supplier negotiation cycles. Regional specification architects are losing influence to centralized engineering teams. Germany and the United States exhibit this concentration most visibly, with single-source contracting now dominating premium commercial developments.
Self-Cleaning Coatings Market Segmentation
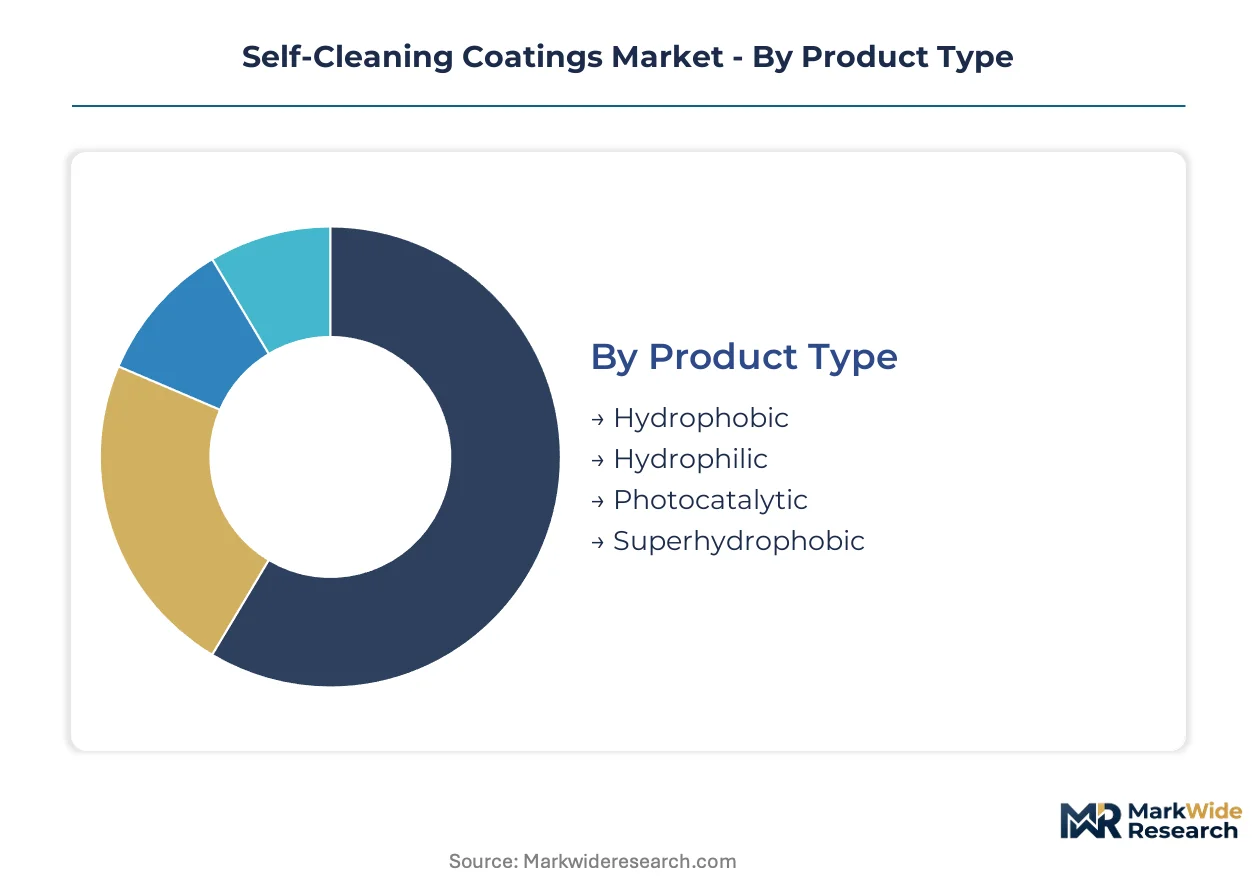
Self-cleaning coatings command divergent price premiums and technical specifications across end-use contexts. Procurement teams in construction, automotive, and electronics apply distinct performance thresholds that reshape supplier prioritization and R&D allocation.
Product Type:
Buyer selection hinges on substrate compatibility and activation requirements rather than chemistry alone.
- Photocatalytic:Titanium dioxide formulations degrade organic contaminants under UV exposure. Construction glazing contractors in Germany and China specify these for curtain wall systems facing lifecycle cost reduction mandates under ECHA REACH and China's MEE frameworks.
- Superhydrophobic:Fluoropolymer or silica-based surfaces achieve contact angles exceeding 150 degrees, repelling water and oils. Electronics manufacturers in East Asia adopt these for smartphone moisture protection, accepting premium raw material burdens for assembly-line reliability gains.
- Hydrophobic:Water-repellent coatings without extreme contact angles serve cost-sensitive architectural applications.
- Hydrophilic:Water-attracting surfaces enable uniform sheeting on optical and display substrates.
Volume sits with photocatalytic grades; growth tilts toward superhydrophobic formulations in electronics moisture protection.
Application:
End-use procurement cycles determine margin capture and specification authority concentration.
- Construction:Facade systems dominate procurement volumes as commercial developers consolidate through national contractors. Germany and the United States exhibit centralized specification authority, with single-source contracting now standard for premium commercial developments.
- Automotive:OEM clearcoat programs and fleet maintenance aftercare exploit existing supplier relationships. Cross-selling from automotive OEM channels accelerates specification velocity.
- Electronics:Smartphone and wearable assembly lines drive nanocoating adoption. Sol-gel deposition methods displace spray booths for sub-micron film uniformity.
- Textiles:Functional fabric treatments target sportswear and protective apparel segments.
Construction absorbs the heaviest procurement volumes; electronics applications climb the fastest as precision manufacturing tolerances tighten.
Technology:
Deposition method selection reflects substrate complexity and regulatory chemistry constraints.
- Sol-gel:Nanotechnology-based processes enable sub-micron film uniformity critical for electronics. East Asian smartphone assemblers automate quality control through precision dip-coating partnerships, bypassing conventional distributor markups.
- Spray Coating:Conventional application dominates architectural and automotive volumes where substrate scale outweighs precision requirements. EPA VOC regulations are accelerating waterborne formulation transitions.
- Dip Coating:Immersion methods serve complex geometries in marine and industrial protective applications.
- Nanotechnology:Emerging deposition approaches compress thickness tolerances beyond conventional spray capabilities.
Spray coating retains volume leadership; sol-gel processes gain share fastest in precision electronics manufacturing.
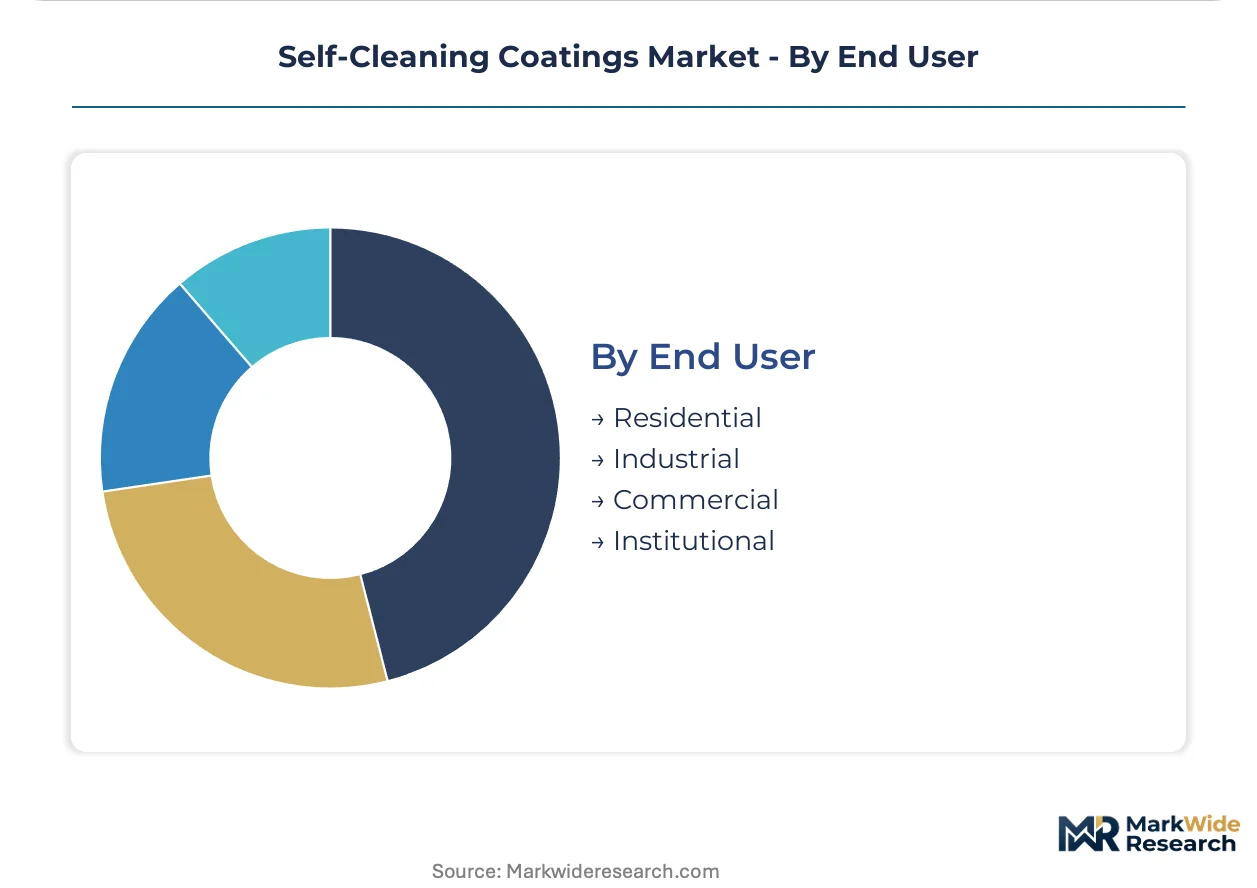
End User:
Facility type dictates maintenance cycle economics and specification complexity.
- Commercial:Office towers and retail developments prioritize lifecycle cost reduction in facade procurement. China's infrastructure renewal programs and Germany's commercial construction standards concentrate demand here.
- Industrial:Manufacturing facilities and logistics centers apply protective coatings for equipment longevity and corrosion resistance.
- Residential:Home construction applies self-cleaning treatments selectively to premium exterior surfaces.
- Institutional:Government and healthcare facilities follow extended procurement cycles with stringent certification requirements.
Commercial end users anchor current procurement volumes; industrial applications show steepest expansion trajectory as manufacturing automation spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial developers in China, Germany, and the United States are consolidating facade procurement through fewer national contractors, concentrating specification authority in these three markets while tightening lifecycle cost mandates reshape regional competitive dynamics.
United States
Commercial glazing contractors in Chicago and New York Metro are pre-qualifying low-VOC photocatalytic alternatives as EPA regulations tighten permissible solvent content in architectural coatings. The EPA's evolving VOC limits under 40 CFR Part 59 are accelerating waterborne formulation transitions. Dallas-Fort Worth developers now specify self-cleaning curtain wall systems through single-source national facade contractors.
Germany
Construction glass contractors in Bavaria and North Rhine-Westphalia specify titanium dioxide photocatalytic grades for lifecycle cost reduction on commercial towers. ECHA's REACH titanium dioxide carcinogen designation has forced reformulation investments across domestic suppliers. Stuttgart's automotive OEMs cross-sell self-cleaning clearcoats into fleet maintenance programs through existing specification relationships.
China
MEE enforcement of GB standards on architectural coatings is reshaping import requirements for facade systems in Shanghai and Beijing. Infrastructure renewal programs prioritize lifecycle cost reduction in curtain wall procurement. Pearl River Delta electronics assemblers adopt superhydrophobic nanocoatings for smartphone moisture protection, automating sol-gel dip-coating lines.
Japan
Smartphone manufacturers in Kanto and Kansai regions drive precision nanocoating adoption for wearable assembly lines. METI guidelines on chemical substance management influence coating formulation priorities. Nagoya's automotive supply base integrates self-cleaning treatments into clearcoat specifications for premium vehicle segments.
United Arab Emirates
EPC firms in Dubai and Abu Dhabi specify marine-grade self-cleaning formulations for coastal commercial developments facing biofouling challenges. MOHAP chemical registration requirements align with tightening port authority discharge regulations. Jotun Group maintains direct specification relationships with engineering-procurement-construction firms across Gulf Cooperation Council project pipelines.
Self-Cleaning Coatings Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue electronics nanocoating specialization through sol-gel deposition partnerships. The market exhibits moderate consolidation with multinational chemical conglomerates anchoring construction and automotive volumes while regional specialists capture precision electronics margins. Three archetypes dominate: diversified chemical majors with cross-sector coating portfolios, regional marine and protective coating specialists with EPC relationships, and nanotechnology-focused entrants targeting smartphone assembly lines. Competitive dynamics center on M&A activity consolidating national facade contractor relationships and technology licensing agreements accelerating waterborne photocatalytic development.
Among diversified chemical majors, BASF SE and Akzo Nobel N.V. represent the integrated formulation archetype spanning construction, automotive, and industrial protective applications. PPG Industries occupies a position exemplifying cross-sector leverage from automotive OEM channels into fleet maintenance aftercare. Jotun Group sits within the regional specialist tier, anchoring Middle East and marine market access through direct EPC firm specifications. These three company structures illustrate how geographic origin and historical sector focus shape competitive positioning without requiring equivalent resource scale.
| Leading Market Players |
|---|
| BASF SE |
| Nippon Paint Holdings Co., Ltd. |
| PPG Industries, Inc. |
| RPM International Inc. |
| Axalta Coating Systems |
| Akzo Nobel N.V. |
| 3M Company |
| Jotun Group |
| The Sherwin-Williams Company |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap coating specialists in Germany and Japan anchor supply discipline through captive titanium dioxide sourcing, translating feedstock security into pricing power over project-based architectural buyers while compressing margin volatility for electronics nanocoating entrants.
Pricing Analysis
Volume concentrates in photocatalytic architectural grades where three-tier pricing structure across premium, standard, and economy levels separates ECHA REACH-compliant formulations from legacy solvent-based alternatives. Price differentiation hinges on certification grade under EPA VOC limits and volume scale through national facade contractors. Cost compression in standard tiers is intensifying because waterborne reformulation investments are amortizing across thinner margin pools. Commercial glazing contractors exhibit highest price sensitivity; electronics OEMs accept premium burdens for sub-micron film uniformity.
Supply Chain Analysis
Direct-to-EPC channels handle hyperscale construction demand in the Middle East, while distributor networks serve fragmented automotive aftermarket buyers. Feedstock production clusters in China, Germany, and the United States, with titanium dioxide pigment and fluoropolymer precursors drawing from concentrated chemical processing hubs. Single-source vulnerability runs through Chinese provincial titanium dioxide suppliers exposed to environmental enforcement cycles. Distribution runs through marine coatings specialists with direct specification relationships in Mediterranean and Baltic port jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The self-cleaning coatings market is becoming a vertical-integration race as players pursue captive titanium dioxide supply to offset feedstock volatility and secure specification eligibility under tightening REACH and EPA frameworks.
For Market Incumbents: Anchor specification authority through direct EPC firm relationships in Gulf Cooperation Council project pipelines, defending against nanocoating specialists entering via sol-gel dip-coating partnerships. Deepen backward integration into titanium dioxide feedstock through offtake agreements with Chinese provincial producers, securing margin buffers against MEE environmental enforcement cycles that disrupt spot market availability.
For New Entrants and Emerging Players: Enter via precision electronics moisture protection, where smartphone assemblers in East Asia bypass conventional distributor markups through automated dip-coating line partnerships. Target marine hull applications in Mediterranean and Baltic jurisdictions facing tightening port authority discharge regulations, exploiting biofouling-resistant formulation gaps left by construction-focused incumbents.
For Investors and Strategic Acquirers: Distressed-cycle entries favor nanocoating specialists with sol-gel deposition capabilities in South Korea and Japan, where METI chemical substance management guidelines are accelerating precision manufacturing adoption. Long-term viability hinges on formulation chemist cohort depth spanning photocatalysis and polymer science; watch ECHA substance evaluation timelines as inflection indicators for stranded formulation risk across European supplier portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Dioxide Feedstock | Captive supply from Chinese provincial producers insulates margin volatility under MEE enforcement cycles. |
| Sol-Gel Dip-Coating Partnership Expansion | Precision electronics manufacturers in East Asia automate quality control while eliminating distributor markups. |
| EPC Direct Specification Relationship Deepening | Jotun Group's Gulf Cooperation Council model demonstrates margin capture through engineering-procurement-construction channel control. |
| Waterborne Formulation Certification Investment | EPA VOC compliance under 40 CFR Part 59 maintains eligibility for national facade contractor procurement pools. |
| Marine Biofouling-Resistant Portfolio Extension | Mediterranean and Baltic port authority discharge regulations create specification pull for hull coating alternatives. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant managers at coating formulation facilities, procurement leads at national facade contractors, distribution channel partners in marine and protective coatings, and technical R&D directors specializing in photocatalytic chemistry. ECHA substance evaluation databases, EPA VOC regulation dockets, and China MEE GB standard enforcement reports provided regulatory trajectory validation. Bottom-up project pipeline tracking across Gulf Cooperation Council commercial developments combined with top-down chemical industry production data for triangulation.
Segment-level modeling applied product type, application, technology, and end-user dimensions across the projection horizon, with photocatalytic versus superhydrophobic chemistry splits calibrated to ECHA REACH compliance investment cycles. CAGRs derived from regression analysis against construction sector procurement consolidation indices and electronics manufacturing automation penetration rates. Regional forecasts incorporated MEE enforcement intensity scoring and national infrastructure renewal program commitment levels.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA titanium dioxide classification revisions or abrupt Chinese environmental enforcement escalations. Periodic stress-testing of base assumptions is recommended, particularly regarding reformulation investment timelines and feedstock supply disruption scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Asia-Pacific Epoxy Powder Coatings Market
Coatings
United Kingdom Protective Coatings Market
Coatings
Middle-East and Africa Thermal Spray Market
Coatings
Corrosion Protective Coatings and Acid Proof Lining Market
Coatings
Industrial Coatings Market
Coatings
US Protective Coatings Market
Coatings
North America Superhydrophobic Coating Market
Coatings
Wood Sealer Market
Coatings
High Temperature Coatings Market
Coatings
US Concrete Floor Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
Trim Coatings Market
Coatings
Water Based Enamel Market
Coatings
Canada Industrial Wood Coatings Market
Coatings
Coating Binders Market
Coatings
Urethane Surface Coatings Market