
 Paper Drying Systems Market | 2026-2036
Paper Drying Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Drying Systems Market Analytics
The capital-intensity divergence between integrated OEMs and component suppliers is rotating competitive advantage toward full-system providers. Valmet Corporation leverages its captive foundry and automation portfolio to control lifecycle margins across pulp-to-paper lines. Andritz AG anchors its position through deep backward integration into steel fabrication and precision rolls. Kadant Inc. competes via specialized doctoring and cleaning subsystems that integrate into third-party dryer sections.
Paper drying systems encompass thermal, radiant, and vacuum-based equipment engineered to reduce sheet moisture from roughly 50% to 5-8% at web speeds exceeding 2,000 m/min. Convection dryers dominate installed capacity across newsprint and packaging grades where high-volume, steady-state operation prioritizes thermal efficiency over flexibility. Specialty paper and tissue segments favor infrared and microwave configurations for rapid moisture profiling and reduced fiber stress, concentrating margin pools in systems with zonal temperature control.
The EU F-Gas Regulation and EPA greenhouse gas standards for pulp and paper mills constrain refrigerant and combustion choices in new dryer installations. REACH compliance on coating chemistries and MEE air-quality protocols in China shape material selection for dryer fabrics and rolls. Buyers must weigh stranded-asset risk in thermal assets against the operational complexity of hybrid radiant-convection architectures.
Market Dynamics
Energy cost volatility and decarbonization mandates are compressing thermal dryer economics, forcing mills to evaluate heat recovery retrofits against full section replacements. The EU Green Deal's embedded carbon border adjustments now factor into equipment procurement decisions.
Growth Catalysts
- E-commerce packaging surge:Corrugated box demand from logistics networks drives installation of high-speed convection sections capable of 2,000+ m/min web speeds.
- EU F-Gas Regulation:Phase-down of high-GWP refrigerants accelerates adoption of CO2 heat pump dryers in European mills seeking compliance without capacity loss.
- Infrared profiling systems:Specialty paper producers deploy zonal radiant arrays to reduce fiber stress while maintaining moisture uniformity across tissue and release-liner grades.
Market Restraints
- Steel and alloy input costs:Dryer roll fabrication depends on nickel-bearing stainless grades subject to LME volatility and Russian supply disruption.
- German engineering concentration:Precision roll and bearing supply clusters heavily in Baden-Württemberg and Saxony, creating geographic single-point vulnerability.
- Natural gas price exposure:Convection systems retain 60-70% thermal dependence on fossil combustion, exposing operating margins to pipeline tariff spikes.
Strategic Opportunities
- India packaging expansion:Domestic containerboard capacity additions near Mumbai and Ahmedabad create demand for turnkey dryer sections with local fabrication partnerships.
- Biomass dryer integration:Nordic mills combine black liquor gasification with superheated steam drying to capture EU ETS credits and reduce Scope 1 emissions.
- Predictive maintenance platforms:IoT roll condition monitoring penetrates tissue installations where unplanned web breaks carry $50,000+ hourly cost.
Industry Challenges
- Heat transfer engineering talent scarcity:Computational fluid dynamics expertise for dryer hood design concentrates among retiring specialists in Finnish and Austrian technical universities.
- Legacy DCS integration complexity:1990s-era distributed control systems in North American newsprint mills resist seamless handshaking with modern zonal temperature controllers.
- REACH chemical compliance timelines:Coating chemistry substitutions for dryer fabrics require 18-24 month ECHA notification cycles that delay equipment commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Drying Systems Market |
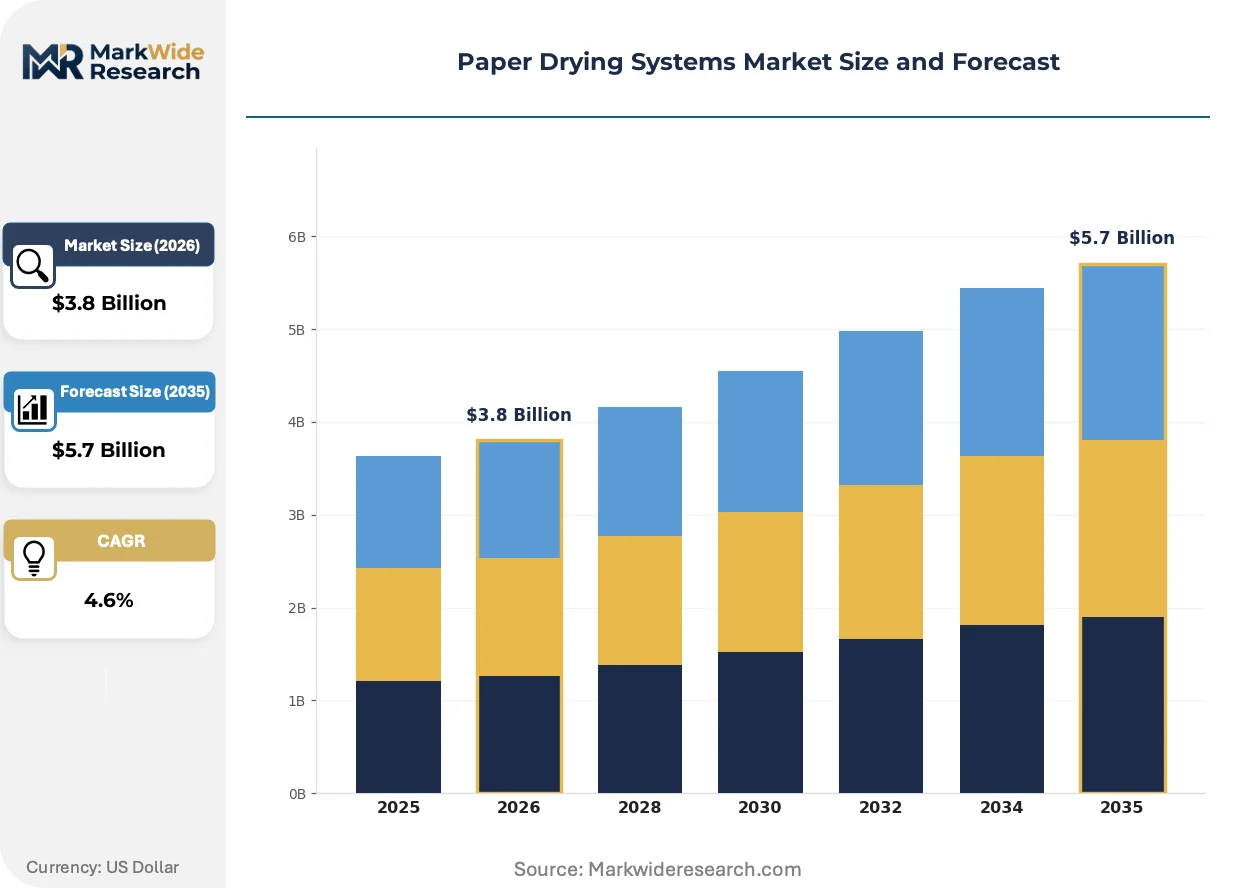
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Dryers, Infrared Dryers, Microwave Dryers, Vacuum Dryers End User: Pulp Mills, Paper Manufacturers, Packaging Companies, Printing Firms Technology: Convection, Conductive, Radiant, Indirect Application: Newsprint, Packaging Paper, Specialty Paper, Tissue Paper |
| Companies Covered | Valmet Corporation, Andritz AG, Voith GmbH, Kadant Inc., Forbes Marshall Ltd., Toscotec, Alfa Laval AB, A.Celli Paper S.p.A., R-V Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Drying Systems Market Evolving Landscape
Electrification of thermal processes and digital twin deployment are converging to redefine dryer section performance metrics. Equipment suppliers now compete on energy intensity per ton of dried paper rather than mechanical reliability alone.
Advanced infrared emitter arrays with silicon carbide elements is miniaturizing moisture profiling hardware for tissue machines. Japanese tissue producers near Fuji City deploy compact radiant modules in gap-forming sections where space constraints previously excluded thermal profiling. The technology is miniaturizing footprint requirements from 12-meter hood lengths to sub-4-meter installations while maintaining 95% radiant efficiency.
EPA greenhouse gas standards for pulp and paper mills tighten combustion emission limits on new dryer installations. US mills in the Southeast face MACT compliance deadlines that favor superheated steam systems over direct gas-fired hoods. Integrated producers in Georgia and Alabama accelerate heat recovery steam generator retrofits to avoid Title V permitting delays.
After-sales service unbundling disrupts traditional OEM maintenance contracts. Packaging converters in the Rhine-Ruhr region now procure roll grinding and bearing replacement through third-party specialists rather than captive service divisions. Independent service providers capture 35% of German dryer section maintenance spend by offering 48-hour response guarantees that match OEM coverage at 60% of annual contract value.
Paper Drying Systems Market Segmentation
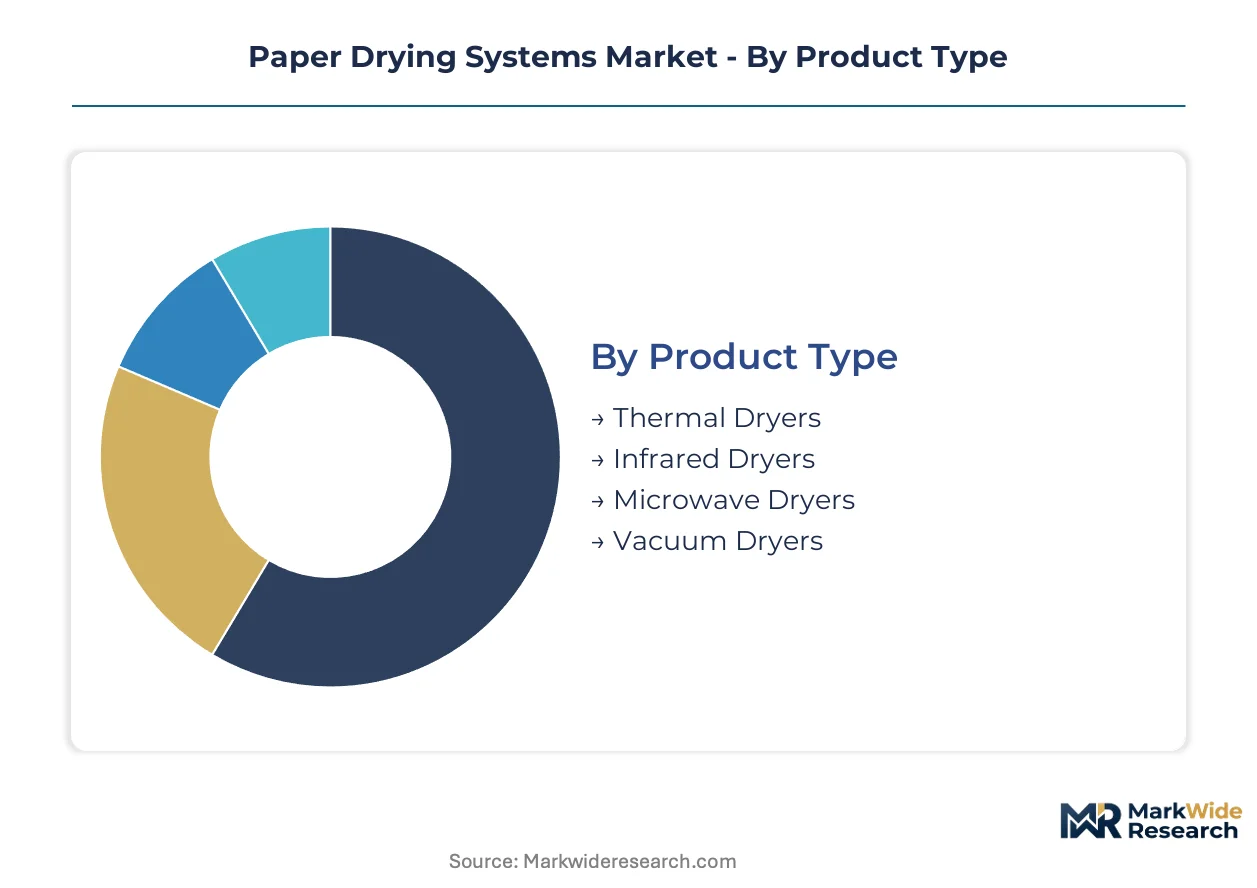
Paper drying systems segment across thermal physics, end-use chemistry, and web-speed requirements. Each dimension carries distinct regulatory footprints and capital-intensity profiles that reshape procurement priorities.
Product Type:
EU F-Gas Regulation and EPA greenhouse gas standards create divergent compliance burdens across thermal technologies. Equipment selection now hinges on refrigerant phase-down timelines and combustion emission limits.
- Thermal Dryers:Convection-based systems utilizing superheated steam or direct gas-fired hoods to reduce sheet moisture from 50% to 5-8%. Newsprint mills in Georgia and Alabama favor these for steady-state operation at web speeds exceeding 2,000 m/min, though natural gas price volatility compresses operating margins.
- Infrared Dryers:Silicon carbide emitter arrays deliver zonal temperature control with 95% radiant efficiency. Japanese tissue producers near Fuji City deploy compact modules in gap-forming sections where space constraints previously excluded thermal profiling.
- Microwave Dryers:Dielectric heating systems penetrate sheet cross-sections for rapid moisture profiling without fiber stress. Specialty paper grades in Nordic mills integrate these for EU ETS credit capture.
- Vacuum Dryers:Reduced-pressure thermal systems operating below boiling point for heat-sensitive substrates. Pharmaceutical release-liner producers specify these for coating uniformity requirements.
Established volume favors thermal dryers; emerging adoption favors infrared systems.
End User:
Customer scale determines service intensity and lifecycle contracting structures. Integrated producers negotiate turnkey installations while converters prioritize modular retrofits.
- Pulp Mills:Black liquor gasification integration with superheated steam drying captures Scope 1 emission reductions. Finnish and Swedish installations lead biomass dryer adoption for EU carbon border adjustment compliance.
- Paper Manufacturers:Containerboard producers in India near Mumbai and Ahmedabad demand turnkey dryer sections with local fabrication partnerships to avoid import duty exposure.
- Packaging Companies:Corrugated box demand from logistics networks drives high-speed convection section installation. E-commerce fulfillment networks specify 2,000+ m/min web speeds for throughput maximization.
- Printing Firms:Heatset web offset operations require precise moisture control for ink adhesion consistency. Publication gravure houses in Germany specify zonal profiling for coated mechanical grades.
Capital concentration sits with paper manufacturers; fastest expansion trajectory belongs to packaging companies.
Technology:
Heat transfer mechanism dictates energy intensity and emissions profile. Regulatory pressure on Scope 1 emissions accelerates conductive and radiant alternatives to fossil-dependent convection.
- Convection:Direct gas-fired or steam-heated air impingement dominates installed capacity across newsprint and packaging grades. US Southeast mills face MACT compliance deadlines that favor superheated steam over direct combustion.
- Conductive:Yankee dryer cylinders and press nips transfer thermal energy through direct surface contact. Tissue machines achieve peak dryness before creping through cast-iron shell conductivity optimization.
- Radiant:Electromagnetic energy transfer bypasses boundary layer resistance for rapid response. Infrared profiling arrays reduce fiber stress in specialty grades where mechanical property preservation matters.
- Indirect:Heat exchanger-mediated thermal transfer isolates combustion products from sheet environment. CO2 heat pump configurations gain traction in European mills seeking F-Gas Regulation compliance without capacity loss.
Convection retains volume dominance; indirect systems gain regulatory-driven share.
Application:
Sheet specification and end-use performance requirements determine drying intensity and uniformity tolerances. Premium grades command zonal control investments that commodity grades cannot justify.
- Newsprint:High-volume, low-basis-weight sheets tolerate higher moisture variation. North American mills with 1990s-era DCS systems resist seamless integration with modern zonal temperature controllers.
- Packaging Paper:Corrugated medium and linerboard demand maximum drying capacity per unit footprint. REACH compliance timelines on coating chemistries delay 18-24 month equipment commissioning cycles.
- Specialty Paper:Release liners, thermal papers, and filtration substrates require precise moisture profiling. Infrared arrays with sub-4-meter installations replace 12-meter hood lengths in constrained rebuilds.
- Tissue Paper:Creped products demand uniform dryness for softness and bulk optimization. IoT roll condition monitoring penetrates installations where unplanned web breaks carry substantial hourly costs.
Packaging paper commands capital deployment; specialty paper generates margin premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering clusters command 15-20% pricing premiums over Indian fabrication, while Southeast Asian mills absorb technology transfer costs to localize supply chains. This asymmetry reshapes procurement patterns across containerboard and tissue investments.
Germany
Baden-Württemberg and Saxony host precision roll and bearing manufacturing clusters that supply dryer sections worldwide. The EU F-Gas Regulation accelerates CO2 heat pump retrofits in mills near Stuttgart seeking refrigerant compliance without output loss. Voith GmbH anchors engineering capacity in Heidenheim, while Andritz AG maintains fabrication presence across multiple industrial zones.
United States
Southeastern containerboard mills in Georgia and Alabama face EPA MACT compliance deadlines that favor superheated steam over direct gas-fired hoods. Heat recovery steam generator retrofits dominate capital allocation as producers avoid Title V permitting delays. Integrated producers near Augusta and Mobile accelerate biomass dryer integration to capture emission reduction credits.
China
Containerboard capacity expansion near Shanghai and Guangzhou drives demand for high-speed convection sections exceeding 2,000 m/min web speeds. MEE air-quality protocols shape material selection for dryer fabrics and rolls in mills across the Yangtze Delta. Local fabricators compete on cost while European OEMs retain premium positioning for complex rebuilds.
India
Domestic containerboard investments near Mumbai and Ahmedabad create demand for turnkey dryer sections with local fabrication partnerships to mitigate import duty exposure. BIS certification requirements extend equipment commissioning timelines by 8-12 months. Packaging converters in Gujarat prioritize modular retrofits over greenfield installations given capital constraints.
Japan
Tissue producers near Fuji City deploy compact infrared radiant modules in gap-forming sections where space constraints previously excluded thermal profiling. METI efficiency standards push mills toward 95% radiant efficiency configurations. Silicon carbide emitter arrays from domestic suppliers dominate moisture profiling hardware for premium tissue grades.
Paper Drying Systems Market Competitive Landscape
Concentration sits with integrated engineering conglomerates that control captive foundry capacity and automation portfolios. Three strategic archetypes define competitive positioning: full-system providers with backward integration into steel fabrication, specialized subsystem suppliers focusing on doctoring and cleaning equipment, and regional fabricators competing on localized service response. M&A activity targets heat transfer engineering capabilities, while strategic partnerships with pulp mill operators lock in lifecycle service contracts.
Among European engineering groups, Valmet Corporation, Andritz AG, and Voith GmbH exemplify the full-system archetype through in-house production of precision rolls and control systems. Kadant Inc. occupies a specialized position emphasizing subsystem integration rather than complete dryer section supply. This tiering creates distinct competitive arenas: premium contracts requiring turnkey performance guarantees versus retrofit opportunities where modular specialists compete on response speed and cost structure.
| Leading Market Players |
|---|
| Valmet Corporation |
| Andritz AG |
| Voith GmbH |
| Kadant Inc. |
| Forbes Marshall Ltd. |
| Toscotec |
| Alfa Laval AB |
| A.Celli Paper S.p.A. |
| R-V Industries, Inc. |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts lock in both nickel-bearing stainless steel supply from Baden-Württemberg mills and price visibility for dryer roll fabricators, insulating OEMs from LME volatility while binding converters to minimum offtake commitments.
Pricing Analysis
The customization-premium spread separates turnkey dryer section pricing from standard modular configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales bundling intensity. Cost compression in standard convection systems is intensifying because Indian fabricators near Mumbai and Ahmedabad compete on localized fabrication partnerships. Packaging converters in Gujarat exhibit highest price sensitivity, while Nordic pulp mills integrating biomass dryers show lowest sensitivity due to EU ETS credit capture economics.
Supply Chain Analysis
Strategic stockpiling of nickel-bearing stainless grades dominates inventory strategy among German precision roll manufacturers facing Russian supply disruption. Geographic supply concentration centers on Germany, China, and India for fabrication capacity. Raw material dependencies draw from nickel-bearing stainless steel, silicon carbide emitter elements, and specialty coating chemistries. Single-source vulnerability in Baden-Württemberg bearing clusters creates structural risk. Distribution runs through OEM captive service divisions and third-party specialists competing on 48-hour response guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's refrigerant phase-down timeline compresses retrofit windows, creating high-growth disruption as mills accelerate CO2 heat pump adoption before compliance deadlines.
For Market Incumbents: Consolidate heat transfer engineering capabilities through targeted acquisition of Finnish and Austrian CFD specialists facing retirement pipelines. Anchor backward integration into steel fabrication to defend margin position against Indian cost competitors. Lock in lifecycle service contracts with Nordic pulp mills seeking EU carbon border adjustment compliance through biomass dryer integration. For New Entrants and Emerging Players: CE marking fast-track for compact infrared radiant modules opens white-space penetration in Japanese tissue installations where space constraints exclude legacy hood configurations. Target modular retrofit opportunities in North American newsprint mills with 1990s-era DCS systems resisting seamless integration with modern zonal controllers. Pursue local fabrication partnerships in Gujarat to bypass BIS certification delays and import duty exposure. For Investors and Strategic Acquirers: Capital is best deployed toward subsystem specialists with IoT-enabled predictive maintenance platforms penetrating tissue installations where unplanned web breaks carry substantial hourly costs. Long-term viability favors acquisition targets combining silicon carbide emitter technology with 95% radiant efficiency configurations. Watch METI efficiency standard tightening as inflection indicator for Japanese premium tissue demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Fabrication | Andritz AG and Voith GmbH control precision roll supply chains against nickel price volatility. |
| CO2 Heat Pump Retrofit Deployment | European mills achieve F-Gas Regulation compliance without output loss through thermal system replacement. |
| IoT Predictive Maintenance Platform Launch | Third-party specialists capture German maintenance spend through 48-hour response guarantees matching OEM coverage. |
| Local Fabrication Partnership in India | Mumbai and Ahmedabad containerboard investments demand turnkey sections mitigating BIS certification delays. |
| Silicon Carbide Emitter Miniaturization | Japanese tissue producers near Fuji City deploy sub-4-meter radiant modules in space-constrained gap-forming sections. |
Research Methodology
Cross-validation between mill engineering directors and secondary trade data anchors the qualitative findings. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads combined with customs records, SEC filings from listed suppliers, and ECHA REACH notification databases. Bottom-up equipment shipment tracking and top-down pulp and paper capacity expansion analysis triangulate market sizing.
Sensitivity analysis around natural gas price trajectories and EU carbon border adjustment implementation timelines shapes the analytical framework. Segmentation dimensions modeled include thermal technology type, end-use chemistry, web-speed requirement, and regional regulatory cluster. CAGRs derive from equipment order backlog analysis and capacity utilization trends across the projection horizon. Black liquor gasification integration rates and superheated steam drying adoption curves inform Nordic biomass dryer forecasts.
The analysis sits within stated boundaries; outcomes outside sustained EU ETS credit pricing and stable nickel supply from non-Russian sources would require recalibration. Forecasts reflect assumptions on MACT compliance deadlines and MEE air-quality protocol enforcement intensity. Revision becomes warranted when F-Gas Regulation phase-down timelines accelerate or German engineering cluster disruption crosses operational thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Drying Technologies
Lyophilization Services Market
Drying Technologies
Global Absorbent Pads Market
Drying Technologies
Filtration and Drying Equipment Market
Drying Technologies
Molecular Sieve Desiccants Market
Drying Technologies
Industrial Lyophilizer Market
Drying Technologies
Global Desiccant Wheel Market
Drying Technologies
Membrane Air Dryers Market
Drying Technologies
Dry Powder Refilling Machine Market
Drying Technologies
Sludge Dryer Machine Market
Drying Technologies
Coke Dry Quenching Market
Drying Technologies
Freeze-Dried Powder Market
Drying Technologies
Conical Vacuum Dryer Market
Drying Technologies
Chemical Absorbent Pads Market
Drying Technologies
Brine Concentration Technology Market
Drying Technologies
Regenerative Thermal Oxidizer [RTO] Market