
 Global Wood Coatings Market | 2026-2036
Global Wood Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wood Coatings Market Outlook
Color-matching software subscriptions and digital tinting services is consolidating how wood coatings get specified and sold, shifting value from bulk drums to precise, repeatable color systems. PPG Industries Inc. leverages its automated dispensing networks to control specification channels in North American retail. Akzo Nobel N.V. anchors European demand through its Sikkens brand strength in professional contractor segments. Nippon Paint Holdings Co., Ltd. dominates East Asian supply with manufacturing scale across Japan, China, and Southeast Asia.
Wood coatings are formulated films comprising resins, pigments, solvents, and additives that cure to protect and enhance wooden substrates against moisture, abrasion, and ultraviolet degradation; typical formulations specify solids content between 30% and 50% by weight and achieve hardness ratings measured by pencil scratch resistance. Aqueous technology leads volume in residential applications where odor and flammability restrictions apply most stringently. UV-cured systems command premium positioning in flooring and cabinetry where throughput speed determines factory economics. Solvent-borne finishes retain share in musical instruments where craftsmen prize hand-rubbed aesthetic depth and repairability.
The EPA regulates volatile organic compound emissions under 40 CFR Part 59 for architectural coatings, while REACH restricts hazardous substance use across European supply chains. China's MEE enforces GB standards on formaldehyde and VOC limits in finished wood products, directly filtering permissible coating chemistries. Stakeholders must monitor how diverging national chemical registries fragment formulation portfolios and force regional manufacturing duplication.
Market Dynamics
Waterborne formulation chemistry is compressing the competitive set as REACH and EPA VOC ceilings force solvent-borne producers into capital-intensive retooling or exit, concentrating supply among integrated resin-coating manufacturers with captive aqueous technology.
Growth Catalysts
- EU Green Deal decarbonization mandates:The framework's embedded carbon reporting requirements for construction materials are accelerating specification of low-VOC wood coatings in German and Dutch furniture exports.
- Guangdong furniture manufacturing cluster expansion:China's integrated production hubs in Foshan and Dongguan are scaling waterborne coating consumption as domestic brands penetrate Southeast Asian retail channels.
- UV-cured line speed economics:Flooring manufacturers in Vietnam are retrofitting solvent lines with UV systems to achieve 3-second cure cycles and eliminate drying rack footprint.
Market Restraints
- Epoxy acrylate resin supply concentration:Three Japanese chemical producers control 70% of photoinitiator and oligomer feedstock for UV coatings, exposing formulators to force majeure pricing volatility.
- REACH SVHC candidate list expansion:Bisphenol A and certain isocyanates face restriction timelines that force mid-size European coaters into dual-track formulation portfolios with 18-month validation cycles.
- Waterborne film performance gaps:Aqueous polyurethane systems still fail pencil hardness 2H benchmarks required for high-traffic commercial flooring, preserving solvent-borne share in specification-driven segments.
Strategic Opportunities
- Indonesian residential furniture export surge:Jepara and Semarang manufacturers are qualifying European coaters for FSC-certified supply chains as EU deforestation regulation enforcement tightens.
- Digital color specification platforms:Cloud-based spectrophotometry and tinting algorithms are enabling remote color matching for distributed cabinetry shops, collapsing the traditional distributor technical service layer.
- India PLI scheme for furniture manufacturing:Production-linked incentives for wood processing clusters in Gujarat and Tamil Nadu are attracting coating formulators to establish localized compounding operations.
Industry Challenges
- Formulation chemist talent scarcity:The specialized knowledge bridging polymer science and wood substrate interaction is concentrating at large integrated producers, constraining mid-tier R&D pipelines.
- Dual certification timeline compression:Simultaneous pursuit of LEED v4.1 and Blue Angel ecolabels requires divergent VOC testing protocols that extend product launch windows by 8-14 months.
- Legacy solvent line asset stranding:Coatings manufacturers face accelerated depreciation of spray booth and curing oven investments as regulatory phase-outs advance faster than equipment life cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wood Coatings Market |
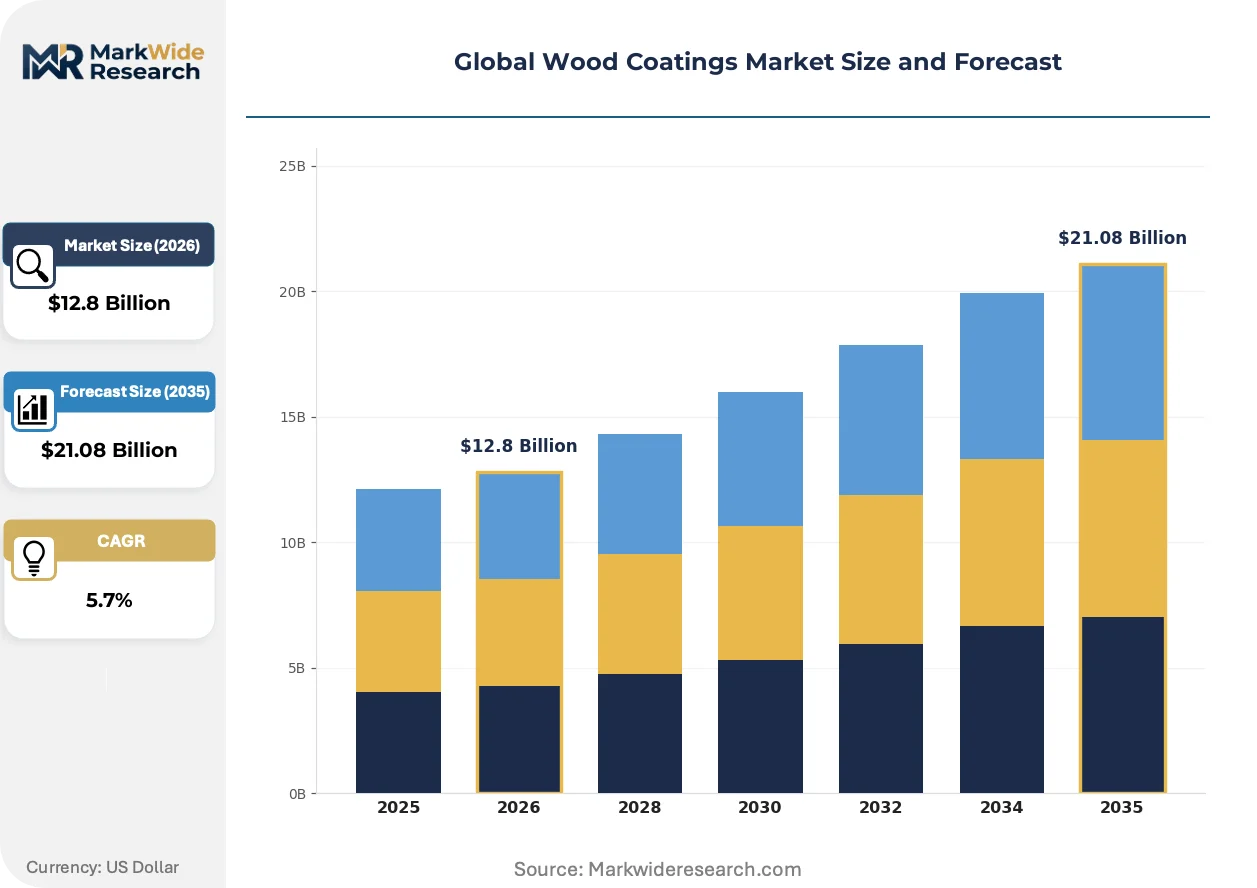
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Varnishes, Stains, Sealers, Finishes Application: Furniture, Flooring, Cabinets, Musical Instruments Technology: Aqueous, Solvent-Borne, UV-Cured, Powder Coatings End User: Manufacturers, Contractors, DIY Enthusiasts, Retailers |
| Companies Covered | The Sherwin-Williams Company, PPG Industries Inc., Akzo Nobel N.V., Axalta Coating Systems, RPM International Inc., Nippon Paint Holdings Co., Ltd., BASF SE, Asian Paints, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wood Coatings Market Strategic Shifts
Digital color systems and automated dispensing infrastructure are compressing the traditional specification chain, shifting technical value from bulk formulation chemistry to precise, repeatable color delivery and remote quality assurance protocols.
Hybrid waterborne-UV curing technology is unifying the application flexibility of aqueous systems with the instant throughput of ultraviolet radiation, enabling furniture manufacturers to process complex three-dimensional profiles without solvent flash-off delays. Italian kitchen cabinet producers are piloting these systems to maintain hand-finished aesthetic depth while achieving line speeds comparable to flat-line UV operations. The convergence is unifying previously separate equipment investments and collapsing the traditional technology-choice trade-off between quality and throughput.
China's MEE enforcement of GB 18581-2020 VOC limits in architectural coatings is forcing domestic wood coating producers to eliminate aromatic solvent carriers and accelerate aliphatic hydrocarbon substitution programs. The standard's 420 g/L ceiling for nitrocellulose lacquers has triggered facility closures among uncompounded regional manufacturers in Shandong and Jiangsu provinces. Flooring exporters to North American retail are responding by qualifying waterborne polyurethane alternatives that meet both Chinese emission standards and California Air Resources Board SCM 2007 thresholds.
Specification authority is migrating from coating manufacturers to retail private-label programs and large furniture OEMs with captive color development capabilities. Home improvement chains in the United States are consolidating wood finish purchasing through centralized color labs that dictate formulation parameters to approved suppliers, compressing traditional distributor technical service roles. This concentration is most visible in North American big-box retail, where specification decisions now rest with merchant teams rather than professional contractor segments.
Global Wood Coatings Market Segmentation
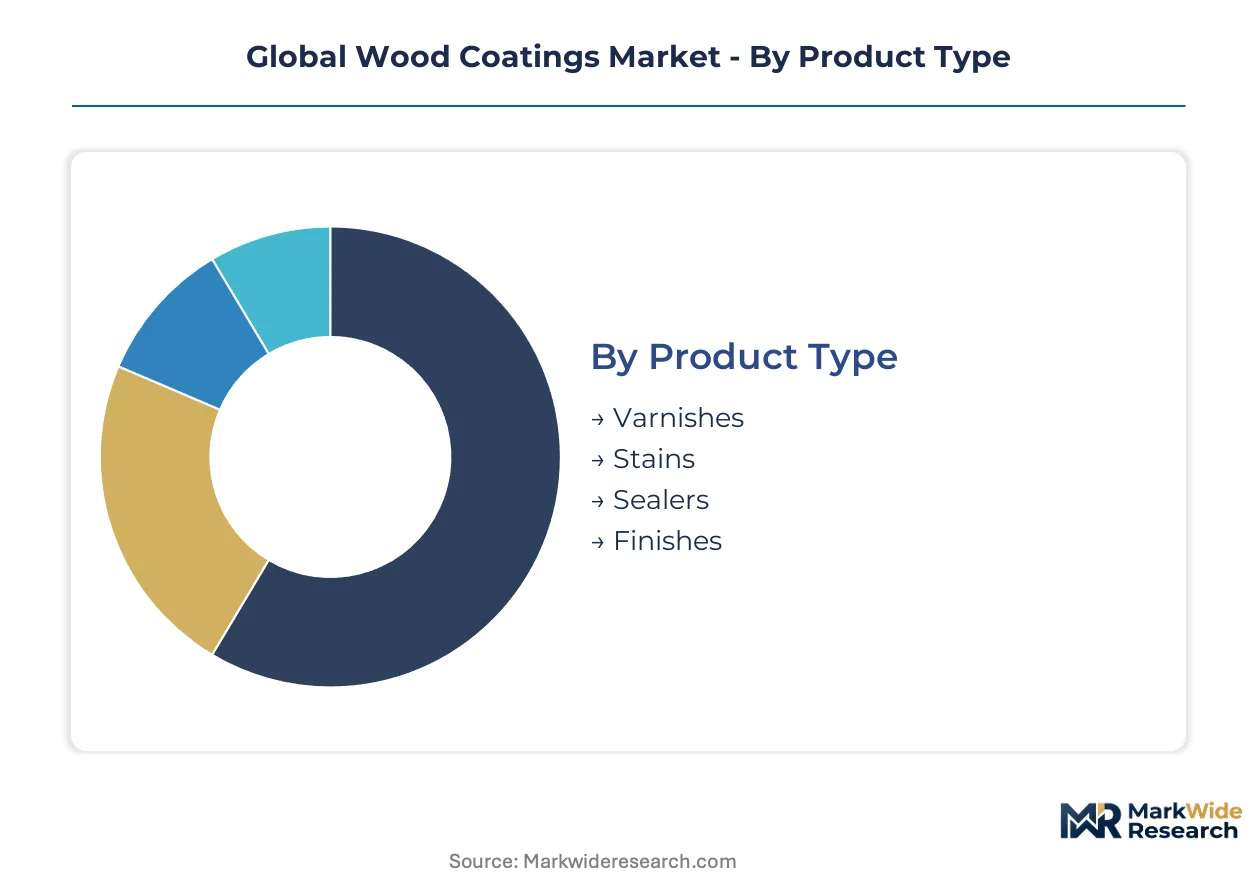
Wood coatings segmentation reveals how formulation chemistry, application environment, and buyer sophistication fragment demand into distinct specification channels. Each dimension carries different margin profiles and regulatory exposure, forcing suppliers to maintain parallel product architectures.
Product Type:
Volume concentrates in protective clear coats while color-bearing systems command formulation premiums through pigment complexity.
- Varnishes:Transparent film-forming systems based on alkyd or polyurethane resins that build durable surface layers. Guangdong furniture exporters specify high-solids varnishes for tropical hardwood protection against humidity cycling, though REACH aromatic solvent restrictions are forcing aliphatic reformulations with 12-month requalification timelines.
- Stains:Penetrating colorants combining dyes or pigments with low-viscosity carriers that accentuate wood grain without obscuring texture. Italian kitchen cabinet manufacturers in Brianza specify solvent-borne stains for depth consistency, but waterborne alternatives are gaining share in Scandinavian markets where indoor air quality certifications dominate specification.
- Sealers:Low-build primers that stabilize porous substrates and prevent topcoat absorption irregularities. Flooring mills in Vietnam apply sanding sealers as intermediate layers between stain and finish coats to accelerate line throughput.
- Finishes:Final protective layers including lacquers, shellacs, and conversion varnishes that establish wear resistance and gloss levels. Musical instrument craftsmen in Cremona and Mittenwald prize French polish shellac for acoustic neutrality and repairability.
Mature deployment sits with varnishes across mass furniture production. Newer deployment is concentrated in waterborne stain systems as EU indoor air quality standards tighten.
Application:
Factory-applied segments dominate volume; field-applied segments retain value through specification complexity.
- Furniture:Coatings for residential and commercial seating, tables, and case goods requiring balance of aesthetics and durability. Indonesian manufacturers in Jepara are qualifying FSC-certified waterborne systems for EU deforestation regulation compliance, with coating selection now gated by chain-of-custody documentation.
- Flooring:High-wear finishes for hardwood, engineered, and parquet surfaces subject to abrasion and chemical exposure. German industrial flooring producers specify UV-cured urethane acrylates for 3-second cure cycles that eliminate drying rack capital, though photoinitiator supply concentration creates input cost volatility.
- Cabinets:Moisture-resistant coatings for kitchen and bath storage facing steam, grease, and cleaning chemical exposure. North American big-box retail chains now dictate formulation parameters through captive color labs, collapsing traditional distributor technical service roles.
- Musical Instruments:Specialized finishes prioritizing acoustic transparency, hand-rubbed depth, and repairability over production speed. Violin makers in Cremona reject UV-cured systems for nitrocellulose lacquers that permit future touch-up and tonal maturation.
Factory-controlled application dominates flooring and cabinets. Field repairability requirements preserve solvent-borne share in musical instruments despite regulatory pressure.
Technology:
Aqueous systems lead residential volume; UV-cured commands industrial premium through throughput economics.
- Aqueous:Water-dispersed resins including acrylics, polyurethanes, and hybrid systems that eliminate flammable solvent handling. China's MEE enforcement of GB 18581-2020 has triggered Shandong facility closures among uncompounded regional manufacturers unable to meet 420 g/L nitrocellulose ceilings.
- Solvent-Borne:Traditional systems using hydrocarbon, ester, or ketone carriers that deliver superior flow, leveling, and substrate penetration. REACH SVHC candidate list expansion for bisphenol A and isocyanates is forcing European mid-size coaters into dual-track portfolios with extended validation cycles.
- UV-Cured:Photoinitiator-activated systems that polymerize instantly under ultraviolet exposure, enabling continuous processing. Vietnamese flooring manufacturers retrofitting solvent lines achieve cure cycles measured in seconds while eliminating drying footprint.
- Powder Coatings:Thermosetting dry films applied electrostatically to conductive substrates, limited in wood applications by substrate moisture and geometry constraints. MDF substrate preheating developments are expanding powder applicability in flat-panel furniture segments.
Established production infrastructure favors solvent-borne in craft segments. Steepest expansion trajectory belongs to UV-cured systems as Southeast Asian flooring capacity scales.
End User:
Procurement authority is migrating from coating manufacturers to large OEMs and retail private-label programs.
- Manufacturers:Industrial wood processors applying coatings in controlled factory environments with automated spray and cure lines. Integrated furniture clusters in Foshan and Dongguan source coatings at scale through consolidated procurement functions that negotiate formulation exclusivity.
- Contractors:Professional applicators serving residential and commercial construction with field-applied finishing services. European professional segments anchor demand for Akzo Nobel's Sikkens brand through specification loyalty and color-matching service dependencies.
- DIY Enthusiasts:Consumer purchasers applying coatings through retail channels for home refinishing projects. PPG's automated dispensing networks control North American retail specification by collapsing color-matching technical service into self-service digital platforms.
- Retailers:Home improvement chains and furniture stores specifying private-label coating programs. Centralized color labs at major US big-box operators now dictate formulation parameters to approved suppliers, compressing traditional distributor margins.
Volume concentration sits with manufacturer direct procurement. Specification authority is shifting fastest toward retailer-controlled private-label programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of global wood coatings output while Western Europe and North America consume premium formulations. This production-consumption divide shapes regional competitive dynamics and regulatory exposure across the value chain.
China
Guangdong province anchors Asian demand through integrated furniture clusters in Foshan and Dongguan that source coatings at consolidated procurement scale. MEE enforcement of GB 18581-2020 VOC limits has shuttered uncompounded regional manufacturers in Shandong and Jiangsu provinces. Flooring exporters in the Pearl River Delta are qualifying waterborne polyurethane alternatives that satisfy both Chinese emission standards and California Air Resources Board thresholds.
Germany
German industrial flooring producers specify UV-cured urethane acrylates for 3-second cure cycles that eliminate drying rack capital requirements. EU Green Deal embedded carbon reporting requirements for construction materials are accelerating specification of low-VOC wood coatings in German furniture exports. The country's chemical formulators in North Rhine-Westphalia face REACH SVHC candidate list expansion timelines for bisphenol A and isocyanates that force 18-month dual-track validation cycles.
United States
Home improvement chains consolidate wood finish purchasing through centralized color labs that dictate formulation parameters to approved suppliers. EPA regulation under 40 CFR Part 59 for architectural coatings constrains permissible solvent-borne chemistries in residential applications. PPG Industries leverages automated dispensing networks to control specification channels in North American retail, collapsing traditional distributor technical service roles.
Vietnam
Flooring manufacturers in Vietnam retrofit solvent lines with UV systems to achieve cure cycles measured in seconds while eliminating drying footprint. Domestic residential furniture producers are expanding waterborne coating adoption as export qualification requirements tighten. Integrated production hubs near Ho Chi Minh City source coatings through regional distributors serving the Southeast Asian furniture export corridor.
Indonesia
Jepara and Semarang manufacturers are qualifying European coaters for FSC-certified supply chains as EU deforestation regulation enforcement tightens. Indonesian residential furniture export growth is attracting coating formulators to establish localized technical service presence. The country's tropical hardwood processing clusters source protective clear coats for humidity cycling resistance in tropical export markets.
Global Wood Coatings Market Competitive Environment
Capital-heavy resin-coating manufacturers compete with asset-light specification and color service providers for margin capture in the value chain. The market structure concentrates supply among integrated producers with captive aqueous technology while mid-tier formulators face capital-intensive retooling or exit. Three strategic archetypes dominate: multinational chemical conglomerates with resin backward integration, regional specialists with specification channel control, and automated dispensing platform operators. Competitive moves center on M&A consolidation of resin supply and geographic expansion of color-matching infrastructure.
Among multinational coating conglomerates, PPG Industries Inc., Akzo Nobel N.V., and Nippon Paint Holdings Co., Ltd. represent the integrated scale tier. PPG occupies a position anchored in North American retail channel control through automated dispensing networks. Akzo Nobel exemplifies European professional segment strength through specification loyalty in contractor channels. Nippon Paint Holdings sits within East Asian manufacturing scale dominance across Japan, China, and Southeast Asian production bases.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries Inc. |
| Akzo Nobel N.V. |
| Axalta Coating Systems |
| RPM International Inc. |
| Nippon Paint Holdings Co., Ltd. |
| BASF SE |
| Asian Paints |
| Eastman Chemical Company |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal embedded carbon reporting requirements for construction materials gate both qualified supply and premium-tier pricing access, forcing coating manufacturers into dual-track formulation portfolios that stratify procurement eligibility across certification tiers.
Pricing Analysis
Cost compression in mid-tier aqueous polyurethane formulations accelerates as REACH SVHC candidate list expansion forces 18-month revalidation cycles that erode margin buffers. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified European supply from mass-market Asian production and regional commodity alternatives. Pricing pressure stems from photoinitiator supply concentration among Japanese chemical producers. DIY enthusiasts through North American retail channels exhibit highest price sensitivity; musical instrument craftsmen demonstrate lowest sensitivity due to repairability requirements.
Supply Chain Analysis
Regional distribution centers in Guangdong, Vietnam, and Germany anchor hub-and-spoke patterns serving furniture manufacturing clusters. Raw material dependencies center on epoxy acrylate resins, photoinitiators, and aliphatic hydrocarbon carriers. Single-source vulnerability concentrates in Japanese oligomer feedstock for UV-cured systems. Distribution runs through integrated procurement functions at Foshan and Dongguan furniture hubs alongside professional contractor channels in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH and EU Green Deal regulations create barrier-to-entry moats favoring integrated resin-coating manufacturers with captive aqueous technology and validated carbon reporting infrastructure.
For Market Incumbents: Anchor specification channel control through automated dispensing network expansion in North American retail and Sikkens-brand professional loyalty in European contractor segments. Defend against private-label compression by deepening backward integration into resin production. Prioritize dual certification investment for LEED v4.1 and Blue Angel ecolabels to extend qualification lead times for mid-tier competitors. For New Entrants and Emerging Players: Digital color-matching platforms as a service offer white-space entry into distributed cabinetry shops and remote tinting workflows underserved by legacy distributor technical service layers. Target Indonesian FSC-certified supply chain qualification as EU deforestation regulation enforcement tightens. Pursue hybrid waterborne-UV curing technology licensing to collapse the quality-throughput trade-off for Italian kitchen cabinet producers. For Investors and Strategic Acquirers: Shandong and Jiangsu facility closures under China's MEE enforcement of GB 18581-2020 is the leading indicator that domestic consolidation will accelerate market share capture by integrated aqueous technology holders. Long-term viability favors formulators with captive resin production and validated low-VOC portfolios across multiple regulatory jurisdictions. Monitor photoinitiator supply contract renegotiations as inflection signals for input cost volatility transmission.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive aqueous technology insulates against REACH reformulation mandates and secures margin control. |
| Dual Certification Investment | LEED v4.1 plus Blue Angel ecolabels extend product launch windows for competitors by 8-14 months. |
| Automated Dispensing Network Expansion | PPG-style platform control collapses distributor technical service roles in North American retail channels. |
| FSC-Certified Supply Chain Qualification | EU deforestation regulation enforcement gates Indonesian furniture export access for qualified coaters. |
| Hybrid Waterborne-UV Technology Licensing | Italian kitchen cabinet pilots demonstrate path to unify application flexibility with instant throughput economics. |
Study Parameters
Independent corroboration across coating formulator technical directors, furniture OEM procurement leads, regional distribution channel partners, and regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from EPA 40 CFR Part 59 filings, ECHA REACH registration databases, China MEE GB standard enforcement records, and customs trade data for resin and photoinitiator flows. Bottom-up volume modeling triangulates against top-down expenditure estimates across factory-applied and field-applied segments.
Rate-of-change decomposition separates volume drivers from value migration across the projection horizon. Segmentation dimensions span formulation chemistry, application environment, cure technology, and procurement authority archetype. CAGRs derive from regression-adjusted trend extrapolation incorporating regulatory phase-out schedules and equipment replacement cycles. Industry-specific inputs include UV line retrofit rates in Vietnamese flooring mills and waterborne qualification timelines for Indonesian FSC certification.
Forecast precision tightens around the base case; tail outcomes carry wider variance under photoinitiator supply disruption or accelerated REACH SVHC restriction timelines. Outputs reflect documented assumptions on regulatory enforcement intensity and technology substitution elasticities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
Italy Industrial Wood Coatings Market
Paints & Coatings
Paint Buckets Market
Paints & Coatings
India Paints and Coatings Market
Paints & Coatings
Wall Putty Powder Market
Paints & Coatings
South America Paints and Coatings Additives Market
Paints & Coatings
Global Exterior Architectural Coatings Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
Paint Curing Lamp Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
Interior Architectural Coatings Market
Paints & Coatings
Qatar Paints and Coatings Market
Paints & Coatings
Refinish Paint Market
Paints & Coatings
Global Thinners and Paint Strippers Market
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
India Industrial Coatings Market