
 Leisure Boat Marine Coatings Market | 2026-2036
Leisure Boat Marine Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Leisure Boat Marine Coatings Market Analysis
Specialty marine coatings distribution is reconfiguring as regional blending facilities displace bulk import reliance across Mediterranean and Southeast Asian supply chains. PPG Industries Inc. leverages captive resin technology to sustain margin control in premium topside formulations. Hempel A/S anchors its competitive position through specialized antifouling R&D pipelines serving superyacht yards. Jotun A/S differentiates via direct-to-yards technical service teams that bypass traditional distributor markups in Nordic waters.
Leisure boat marine coatings comprise formulated polymer systems—typically epoxy, polyurethane, acrylic, or vinyl resin bases—engineered to withstand saltwater immersion, UV degradation, and mechanical abrasion while controlling biofouling accumulation on submerged hull surfaces. Antifouling coatings command the largest product type position due to mandatory dry-dock reapplication cycles, though specialty coatings represent the fastest-expanding margin pool as ceramic and graphene-enhanced formulations penetrate superyacht segments. Epoxy primers dominate material demand by volume across recreational boat and sailboat applications, while polyurethane topside systems capture premium pricing in yacht refinishing where gloss retention and color stability determine specification.
EU REACH biocide restrictions and the F-Gas Regulation constrain traditional copper-based antifouling formulations, compelling manufacturers to validate silicone and biocide-free alternatives through ECHA compliance pathways. The US EPA and state-level Clean Water Act provisions in California and Florida similarly restrict tributyltin legacy chemistries and mandate water-quality monitoring near high-density marinas. Stakeholders must monitor regulatory divergence between EU and North American approval timelines for novel antifouling actives, as asynchronous authorization risks fragmenting product portfolios and stranding R&D investments in non-compliant chemistries.
Market Dynamics
EU REACH biocide restrictions are forcing wholesale reformulation of antifouling portfolios toward copper-free and silicone-based alternatives, compressing legacy product lifecycles while opening premium positioning for compliant chemistries.
Growth Catalysts
- Superyacht fleet expansion:Mediterranean yacht operators in Genoa and Viareggio are extending dry-dock maintenance cycles, driving recurring antifouling demand.
- ECHA compliance pathways:Accelerated validation timelines for novel biocide-free actives are rewarding first-mover manufacturers with early market access.
- Ceramic-enhanced formulations:Graphene-oxide hybrid coatings are penetrating high-value refinishing segments where gloss retention commands specification premiums.
Market Restraints
- Epoxy resin supply concentration:Captive production of specialty amine curing agents remains concentrated among three European chemical conglomerates, creating input vulnerability.
- Asynchronous regulatory authorization:Divergent ECHA and US EPA approval timelines for novel antifouling actives risk fragmenting product portfolios.
- Silicone raw material volatility:Organosilicon precursor costs fluctuate with semiconductor sector demand, squeezing margin stability for silicone-based coating lines.
Strategic Opportunities
- Southeast Asian maintenance clusters:Regional blending facilities in Thailand and Vietnam are displacing bulk import reliance, creating localized supply chain control.
- Direct-to-yard technical service:Bypassing traditional distributor markups through embedded application support teams captures margin from specification-sensitive superyacht builders.
- F-Gas Regulation tailwinds:EU restrictions on fluorinated greenhouse gases are accelerating solvent-free and waterborne system adoption in topside applications.
Industry Challenges
- Formulation chemist scarcity:Expertise in marine biocide compliance and polymer-silicone hybrid systems concentrates among retiring specialists in Northern European coating centers.
- Dry-dock scheduling compression:Peak-season yard capacity constraints in Mediterranean hubs force inventory pre-positioning and working capital intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leisure Boat Marine Coatings Market |
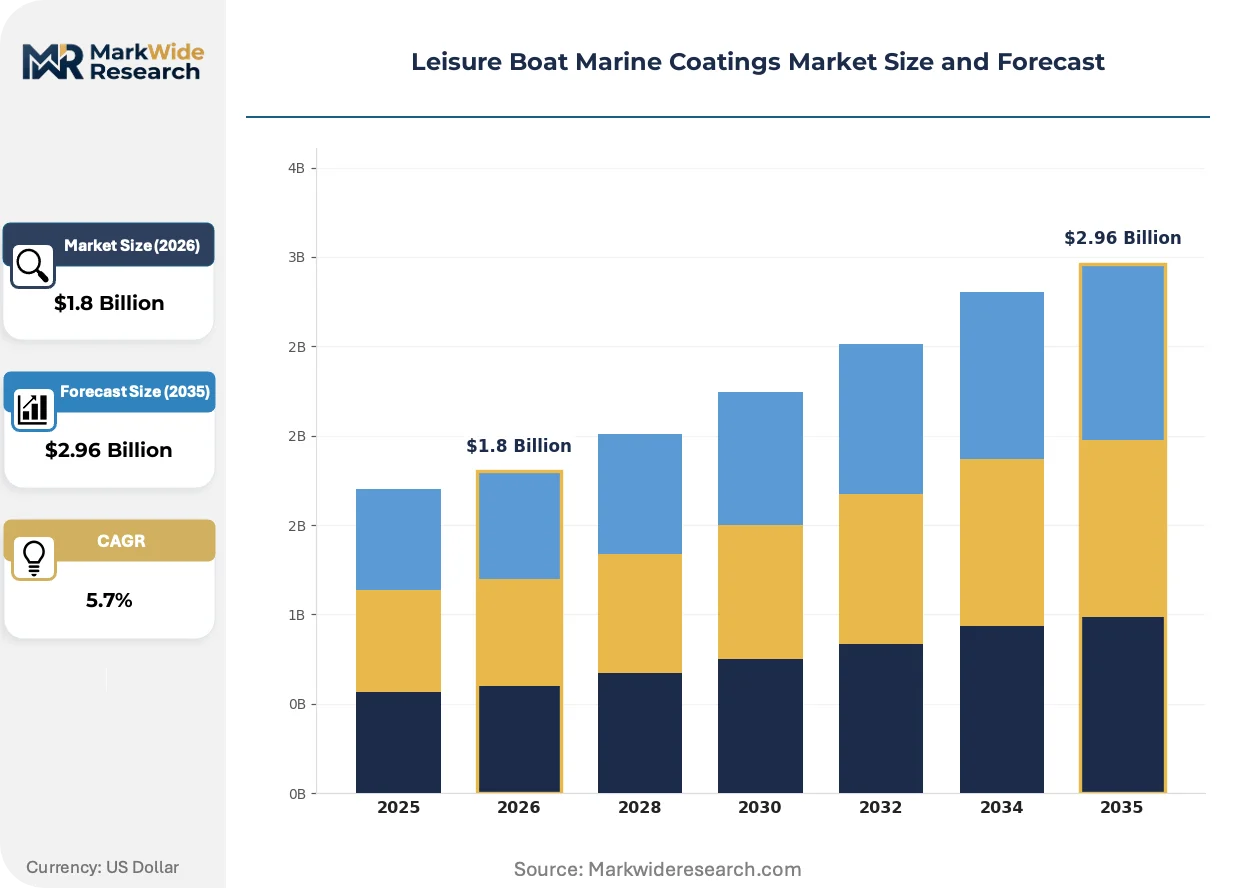
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifouling, Topside, Primer, Specialty Coatings Application: Recreational Boats, Personal Watercraft, Sailboats, Yachts Material: Epoxy, Polyurethane, Acrylic, Vinyl End User: Boat Manufacturers, DIY Enthusiasts, Maintenance Services, Repair Shops |
| Companies Covered | The Sherwin-Williams Company, PPG Industries Inc., AkzoNobel, Chugoku Marine Paints Ltd., Hempel A/S, Jotun A/S, Kansai Paint Co. Ltd., RPM International Inc., Nippon Paint Holdings Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leisure Boat Marine Coatings Market Emerging Trajectories
Reformulation pressure from biocide restrictions is compressing traditional product architectures while enabling premium pricing for compliant alternatives. Three concurrent shifts are reshaping competitive positioning.
Silicone-hydrogel antifouling systems are collapsing the performance gap between copper-based biocides and biocide-free alternatives. Superyacht yards in Monaco and Barcelona are specifying these formulations for 36-month immersion cycles. The technology is collapsing dry-dock frequency expectations and redirecting maintenance revenue toward higher-margin topside refinishing.
REACH authorization requirements for zinc pyrithione and copper oxide are forcing portfolio rationalization across European manufacturers. Industrial consequence includes stranded R&D investments in legacy chemistries awaiting non-renewal decisions. Yacht fleet operators in Italy and Spain are accelerating silicone system trials to preempt compliance-driven supply disruptions.
Embedded technical service teams are displacing independent distributor networks in specification-heavy segments. Nordic superyacht builders now require direct manufacturer presence during application protocol development. This pattern concentrates procurement authority with yards possessing in-house coating specification capability, marginalizing price-competitive spot buyers.
Leisure Boat Marine Coatings Market Segmentation
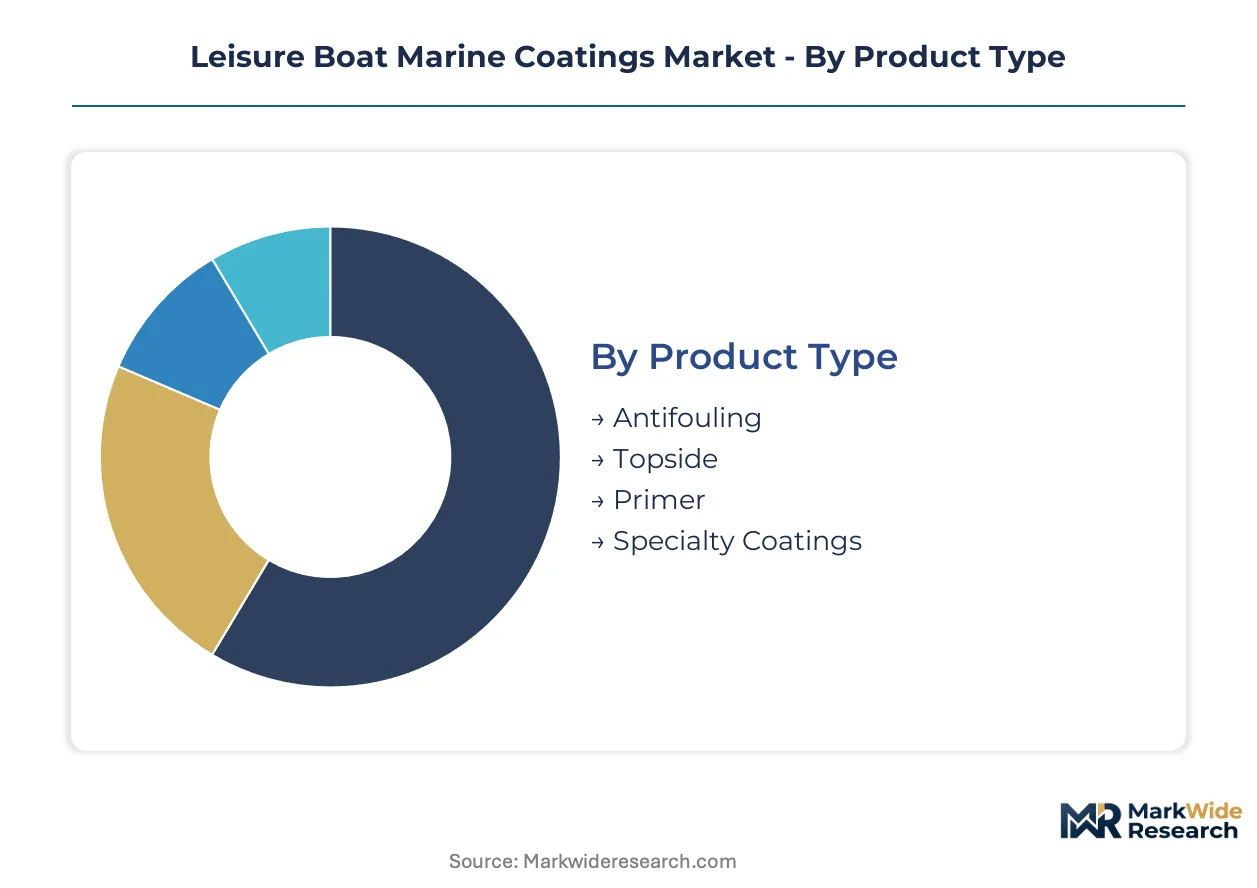
Leisure boat marine coatings segment along four distinct axes that determine formulation chemistry, application protocol, and procurement channel. Each dimension captures different margin pools and compliance exposure, from the biocide-driven regulatory pressure on antifouling systems to the specification authority concentrated in superyacht yards.
Product Type:
Application frequency and regulatory burden divide the product landscape into four tiers with diverging margin structures.
- Antifouling:Copper-based and silicone-hydrogel formulations engineered for submerged hull surfaces to control biofouling accumulation. Mediterranean fleet operators in Genoa and Viareggio drive recurring demand through mandatory dry-dock reapplication cycles. ECHA biocide restrictions are compressing legacy copper-oxide lifecycles while opening premium positioning for compliant silicone alternatives.
- Specialty Coatings:Ceramic and graphene-oxide hybrid systems penetrating superyacht refinishing segments where gloss retention and thermal management command specification premiums. Monaco and Barcelona yards are specifying these formulations for extended immersion cycles, redirecting maintenance revenue toward higher-margin topside work.
- Topside:Polyurethane and acrylic systems formulated for above-waterline protection against UV degradation and mechanical abrasion.
- Primer:Epoxy-based foundation layers dominating material demand by volume across recreational boat applications.
Antifouling holds installed capacity. Specialty coatings are rotating up the share rankings.
Application:
Vessel scale and operating pattern determine coating performance requirements and procurement authority concentration.
- Yachts:Superyacht and megayacht segments where specification authority rests with yard-based technical teams rather than spot buyers. Nordic builders now require direct manufacturer presence during application protocol development, bypassing traditional distributor markups and concentrating procurement with yards possessing in-house coating specification capability.
- Sailboats:Performance-oriented hull designs demanding lightweight antifouling systems with minimal surface roughness. Coastal Italy's dense maintenance clusters in Viareggio anchor recurring demand for high-performance refinishing cycles.
- Recreational Boats:Powerboats and day cruisers with standardized hull geometries and price-sensitive maintenance patterns.
- Personal Watercraft:Jet skis and small craft with abbreviated coating lifecycles and DIY-dominated procurement.
Yachts concentrate specification authority. Sailboats are gaining share fastest among premium application tiers.
Material:
Resin chemistry determines environmental resistance, application complexity, and raw material supply vulnerability.
- Epoxy:Amine-cured systems dominating primer applications and structural hull protection. Captive production of specialty curing agents concentrates among three European chemical conglomerates, creating input vulnerability for formulators without backward integration into resin supply.
- Polyurethane:Two-component systems capturing premium pricing in topside refinishing where gloss retention and color stability determine specification. PPG Industries leverages captive resin technology to sustain margin control in this tier.
- Acrylic:Single-component waterborne alternatives accelerating under F-Gas Regulation pressure on solvent-based systems.
- Vinyl:Legacy formulations retaining position in specific regional maintenance protocols.
Epoxy anchors volume throughput. Polyurethane is climbing the fastest among value-contributing resin tiers.
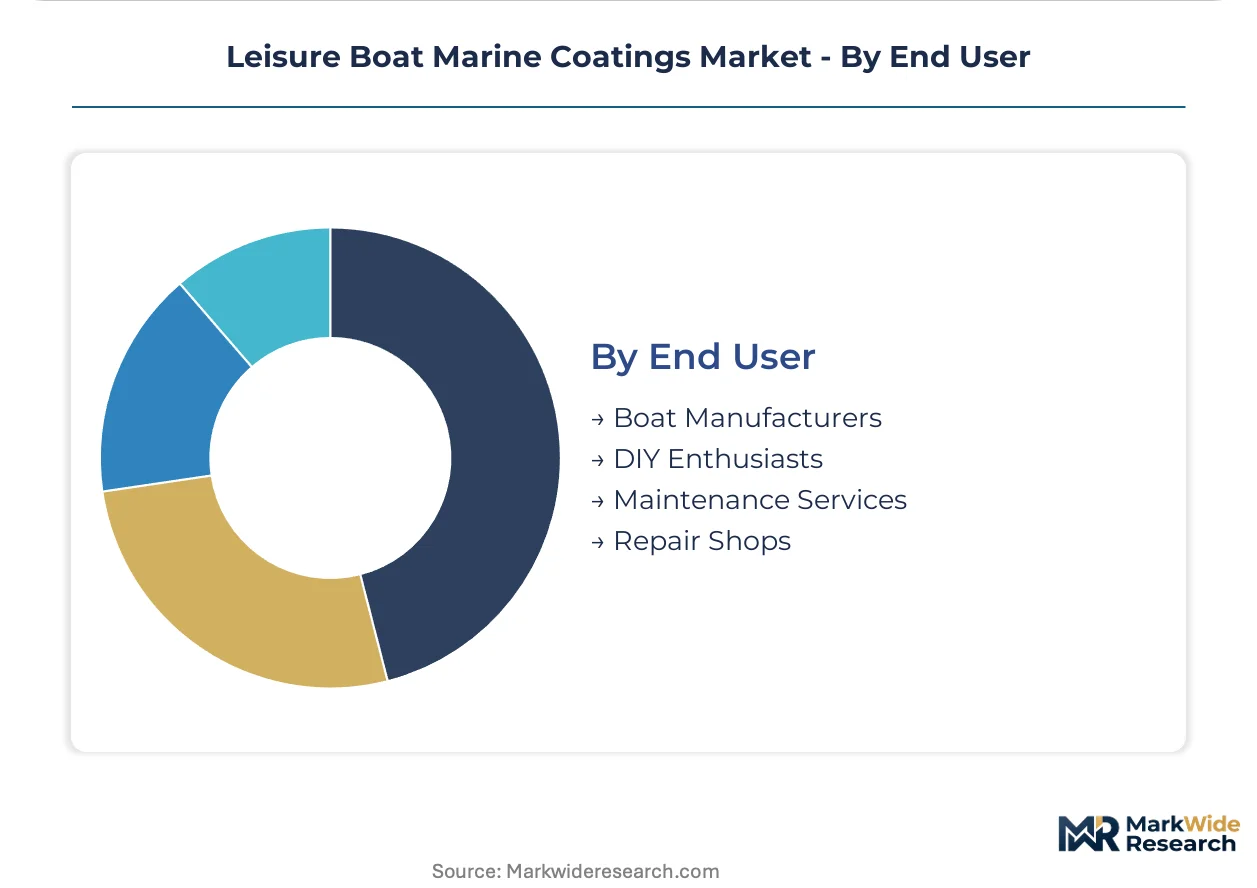
End User:
Procurement sophistication and technical capability separate four customer channels with diverging price elasticity.
- Maintenance Services:Professional fleet operators and contracted yard services managing scheduled dry-dock programs. Mediterranean yacht fleet operators are extending antifouling maintenance cycles, driving predictable recurring demand with embedded technical service requirements.
- Boat Manufacturers:OEM specification authority concentrated among superyacht builders with in-house coating engineering capability. Jotun A/S differentiates via direct-to-yards technical service teams that bypass traditional distributor networks in Nordic waters.
- Repair Shops:Independent facilities serving recreational boat owners with price-sensitive spot purchasing.
- DIY Enthusiasts:Consumer-channel procurement through marine retail with minimal technical support requirements.
Maintenance services hold contracted volume. Boat manufacturers are rotating up the share rankings through specification capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH biocide restrictions in Europe are compressing legacy copper-based antifouling lifecycles while opening premium positioning for compliant silicone alternatives. Regional demand concentrates in Mediterranean maintenance clusters where superyacht fleet expansion drives recurring refinishing cycles.
Italy
Genoa and Viareggio anchor Europe's densest pleasure-craft maintenance clusters, with yacht fleet operators extending antifouling reapplication programs. The Italian Ministry of Environment enforces EU REACH biocide restrictions through national implementation decrees, accelerating silicone-hydrogel formulation trials. Viareggio's superyacht yards now specify 36-month immersion cycles for compliant coatings.
United States
California and Florida marinas drive demand under state-level Clean Water Act provisions that restrict tributyltin legacy chemistries. The US EPA mandates water-quality monitoring near high-density boating corridors. Fort Lauderdale's yacht refit facilities concentrate procurement authority for premium topside polyurethane systems.
Spain
Barcelona superyacht yards are specifying ceramic-enhanced specialty coatings for extended immersion performance. Spain's national chemical regulator aligns with ECHA authorization timelines for novel antifouling actives. The Balearic Islands maintenance sector is accelerating silicone system adoption to preempt compliance-driven supply disruptions.
France
Monaco's megayacht fleet operators demand graphene-oxide hybrid formulations where gloss retention commands specification premiums. ANSM and CNIL oversight extends to environmental compliance verification for marine chemical applications. The Côte d'Azur refit cluster is embedding direct manufacturer technical service teams during application protocol development.
United Kingdom
Southampton and Portsmouth anchor recreational boat manufacturing with standardized hull geometries driving epoxy primer volume. The UK's Health and Safety Executive enforces REACH-derived biocide restrictions through domestic chemical regulations. Solent-based maintenance services are consolidating procurement through contracted fleet management programs.
Leisure Boat Marine Coatings Market Vendor Landscape
Integrated resin producers and specialized coating formulators split the market between captive supply control and technical service differentiation. The vendor base concentrates among European and Asian chemical conglomerates with backward integration into epoxy and polyurethane resin supply. Three archetypes dominate: diversified industrial coatings multinationals with captive technology, regional specialists with embedded yard relationships, and Asian scale producers serving standardized recreational segments. Competitive moves center on Southeast Asian blending facility investment and direct-to-yard technical service deployment that bypasses distributor markups.
Within the diversified multinational tier, PPG Industries Inc. and AkzoNobel occupy positions anchored by captive resin technology and broad industrial coatings portfolios. Among specialized marine operators, Hempel A/S and Jotun A/S exemplify the technical service archetype with direct yard relationships in Nordic and Mediterranean waters. Japanese and Korean scale producers including Chugoku Marine Paints Ltd. and Kansai Paint Co. Ltd. represent the Asia-Pacific supply efficiency segment serving high-volume recreational boat applications.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries Inc. |
| AkzoNobel |
| Chugoku Marine Paints Ltd. |
| Hempel A/S |
| Jotun A/S |
| Kansai Paint Co. Ltd. |
| RPM International Inc. |
| Nippon Paint Holdings Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Genoa and Viareggio's dense maintenance cluster capacity determines pricing power across Mediterranean antifouling markets. Silicone-hydrogel formulation premiums reflect captive resin control among three European chemical conglomerates.
Pricing Analysis
Price spreads between Italian superyacht yards and Southeast Asian recreational boat facilities capture a three-tier pricing structure across premium, standard, and economy levels. Certification grade under EU REACH biocide authorization and volume scale of fleet operator contracts drive price differentiation. Pricing pressure stems from organosilicon precursor cost volatility tied to semiconductor sector demand. DIY enthusiasts in consumer channels exhibit highest price sensitivity, while superyacht builders with in-house specification capability show lowest elasticity.
Supply Chain Analysis
Tariff exposure between European specialty amine producers and Asian epoxy resin processors dominates supply chain risk assessment. Raw material sourcing draws from Germany, Belgium, and China for curing agents, base resins, and organosilicon precursors. Single-source vulnerability concentrates in specialty amine curing agent production. Distribution runs through regional blending facilities in Thailand and Vietnam displacing bulk import reliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as superyacht fleet expansion in Mediterranean hubs drives recurring dry-dock maintenance demand.
For Market Incumbents: Harden backward integration into captive resin technology to defend margin control against silicone raw material volatility. Secure ECHA compliance pathway priority for novel biocide-free actives before regulatory non-renewal decisions strand legacy copper-oxide R&D investments. Expand direct-to-yard technical service teams in Nordic waters to bypass distributor markups. For New Entrants and Emerging Players: Build out regional blending capacity in Vietnam and Thailand to capture localized supply chain control from bulk import-dependent incumbents. Target recreational boat epoxy primer volume where specification authority remains fragmented and price sensitivity permits spot purchasing. Lead with waterborne acrylic alternatives under F-Gas Regulation solvent restriction pressure. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-premium play because regulatory divergence between ECHA and US EPA authorization timelines rewards first-mover validation investments. Acquisition targets should concentrate on specialized marine coating formulators with embedded yard relationships in Monaco and Barcelona. Monitor ECHA biocide renewal decisions for copper oxide and zinc pyrithione as inflection signals for silicone-hydrogel adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive amine curing agent production insulates margin control from European chemical conglomerate concentration. |
| ECHA Compliance Pathway Investment | Accelerated validation timelines for novel biocide-free actives secure early market access before regulatory deadlines. |
| Direct-to-Yard Technical Service Deployment | Embedded application support teams in Viareggio and Genoa bypass traditional distributor markups. |
| Southeast Asian Blending Facility Expansion | Regional production in Thailand and Vietnam displaces bulk import reliance for standardized recreational segments. |
| Silicone-Hydrogel R&D Pipeline | 36-month immersion cycle formulations redirect maintenance revenue toward higher-margin topside refinishing. |
Methodological Framework
A standing panel of superyacht yard technical directors, marine coating formulators, fleet maintenance procurement managers, and ECHA regulatory affairs specialists provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders and secondary validation through customs trade data, SEC 10-K filings of diversified coatings multinationals, and Cefic chemical industry reports. Bottom-up volume modeling across resin chemistry tiers and top-down value triangulation against disclosed segment revenues ensured cross-verification.
Scenario-bracketing around regulatory authorization timelines and raw material cost volatility informed projections across the analysis window. Segmentation dimensions modeled include product type tier, vessel application scale, resin chemistry base, and procurement channel sophistication. CAGRs derived from historical maintenance cycle frequencies and fleet expansion trajectories in named Mediterranean hubs. Silicone-hydrogel adoption curves and ECHA biocide renewal schedules served as industry-specific forecast inputs.
Practitioners should monitor ECHA non-renewal decisions for copper-based actives and semiconductor sector demand spikes affecting organosilicon pricing for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Solar Reflective Film Market
Coatings
Coating Pre-Treatment Market
Coatings
Waterborne Automobile Coating Market
Coatings
Tablet and Pellet Coating Systems Market
Coatings
Fillers and Coating Market
Coatings
Electrically Conductive Coating Market
Coatings
Water Based Enamel Market
Coatings
Global Waterborne Coatings Market
Coatings
Nigeria Protective Coatings Market
Coatings
Sustained Release Coatings Market
Coatings
Breathable Antimicrobial Coatings Market
Coatings
PU Coatings Market
Coatings
Hydrophilic Coatings Market
Coatings
Asia-Pacific Floor Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
Coated Casing Market