
 United Arab Emirates Floor Coatings Market | 2026-2036
United Arab Emirates Floor Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Floor Coatings Market Outlook
Aftermarket maintenance and refurbishment revenue is tilting toward specialized applicator networks as building owners extend asset lifecycles. Jotun leverages its coastal manufacturing presence to sustain rapid delivery across Gulf Cooperation Council projects. National Paints Factories Co Ltd anchors domestic supply through extensive distribution into Saudi Arabia and Oman. Hempel A/S differentiates through marine-grade epoxy expertise transferred into heavy industrial flooring.
Floor coatings comprise resin-based protective layers applied to concrete and cementitious substrates, typically formulated with epoxy, polyurethane, or polyaspartic polymers at film builds of 0.5 to 6 millimeters to resist abrasion, chemical attack, and moisture ingress. Epoxy formulations dominate commercial and industrial installations where chemical resistance and load-bearing capacity prove critical, while polyaspartic coatings command premium positioning in fast-track applications requiring return-to-service within hours. Polyurethane segments serve automotive and light industrial settings demanding thermal cycling flexibility and UV stability.
MOHAP oversees product registration and chemical safety compliance for coatings sold across the Emirates, while Dubai Municipality enforces Al Sa'fat green building standards that mandate low-emission interior materials. The Emirates Authority for Standardization and Metrology (ESMA) mandates conformity assessment for imported coating products, creating entry barriers for uncertified suppliers. Stakeholders must monitor evolving VOC thresholds and circular-economy material requirements as federal sustainability mandates tighten procurement specifications.
Market Dynamics
Green building mandates from MOHAP and Dubai Municipality are compressing specification cycles for low-VOC formulations, forcing applicators to requalify product portfolios ahead of tightened emission thresholds.
Growth Catalysts
- Al Sa'fat Green Building Standards:Dubai Municipality mandates low-emission interior materials across new commercial construction, pulling waterborne epoxy and polyurethane systems into specification pipelines.
- Logistics Corridor Expansion:Dubai's industrial zones are driving demand for abrasion-resistant high-build coatings in warehousing and distribution facilities.
- Polyaspartic Curing Chemistry:Fast-track polymerization enables return-to-service within hours, compressing downtime costs for operational facilities in Abu Dhabi's industrial clusters.
Market Restraints
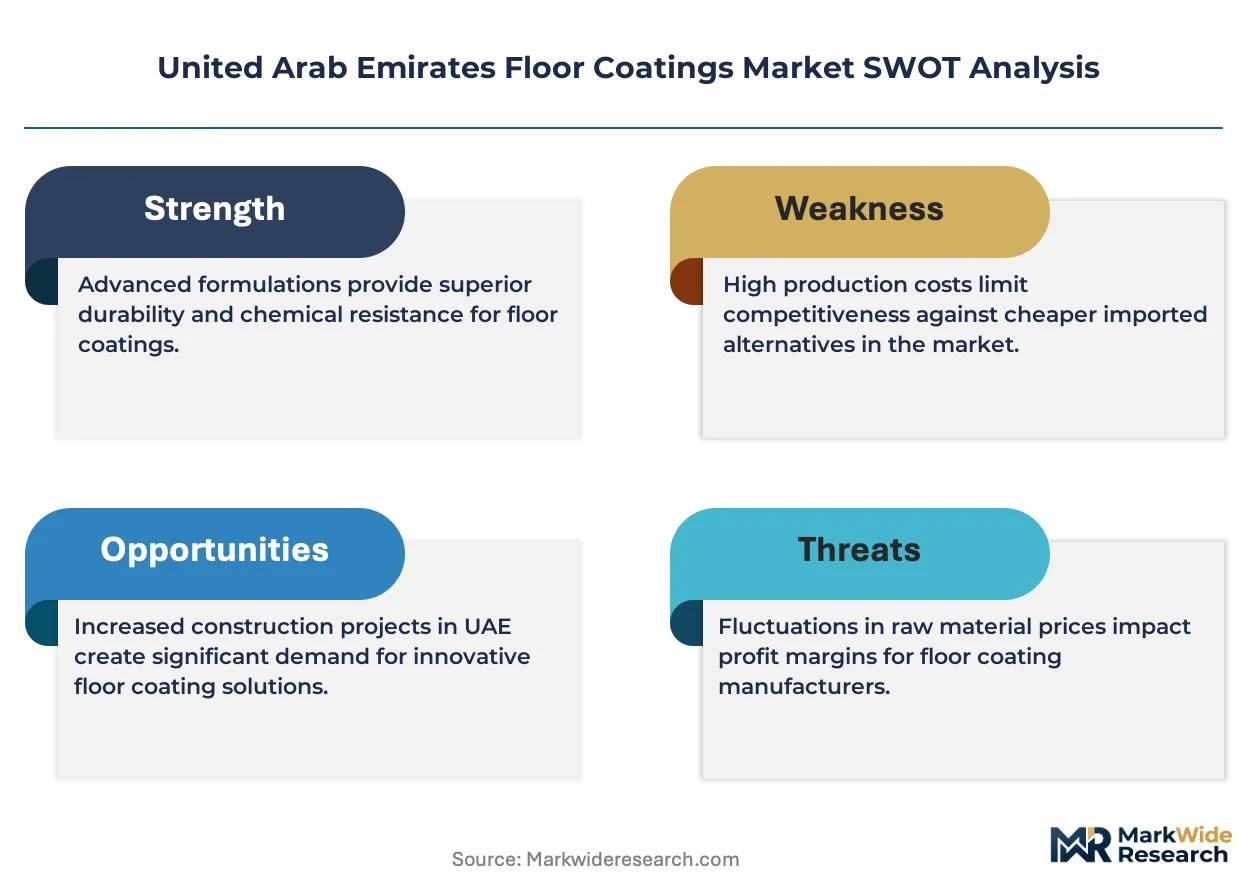
- Epoxy Resin Price Volatility:Bisphenol-A and amine hardener feedstock costs fluctuate with crude oil derivatives, squeezing applicator margins on fixed-price contracts.
- Import Concentration Risk:ESMA conformity assessment requirements favor established suppliers with certification infrastructure, limiting new entrant flexibility.
- Moisture Tolerance Limitations:Standard epoxy formulations require substrate moisture content below 4%, restricting application windows during humid Gulf summer months.
Strategic Opportunities
- Sharjah Manufacturing Zones:Underpenetrated industrial areas outside Dubai-Abu Dhabi corridor present first-mover positioning for localized coating services.
- Photocatalytic Self-Cleaning Formulations:Titanium dioxide additive integration enables air-purifying surfaces aligned with federal sustainability mandates.
- Certified Applicator Networks:Manufacturer-direct training programs bypass traditional distributor markups while locking in specification influence.
Industry Challenges
- Substrate Preparation Skill Shortage:Proper concrete profiling and moisture testing demands certified technicians, creating bottlenecks during peak construction windows.
- Multi-Layer System Integration:Compatibility failures between primer, body coat, and topcoat chemistries from different suppliers generate costly rework.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Floor Coatings Market |
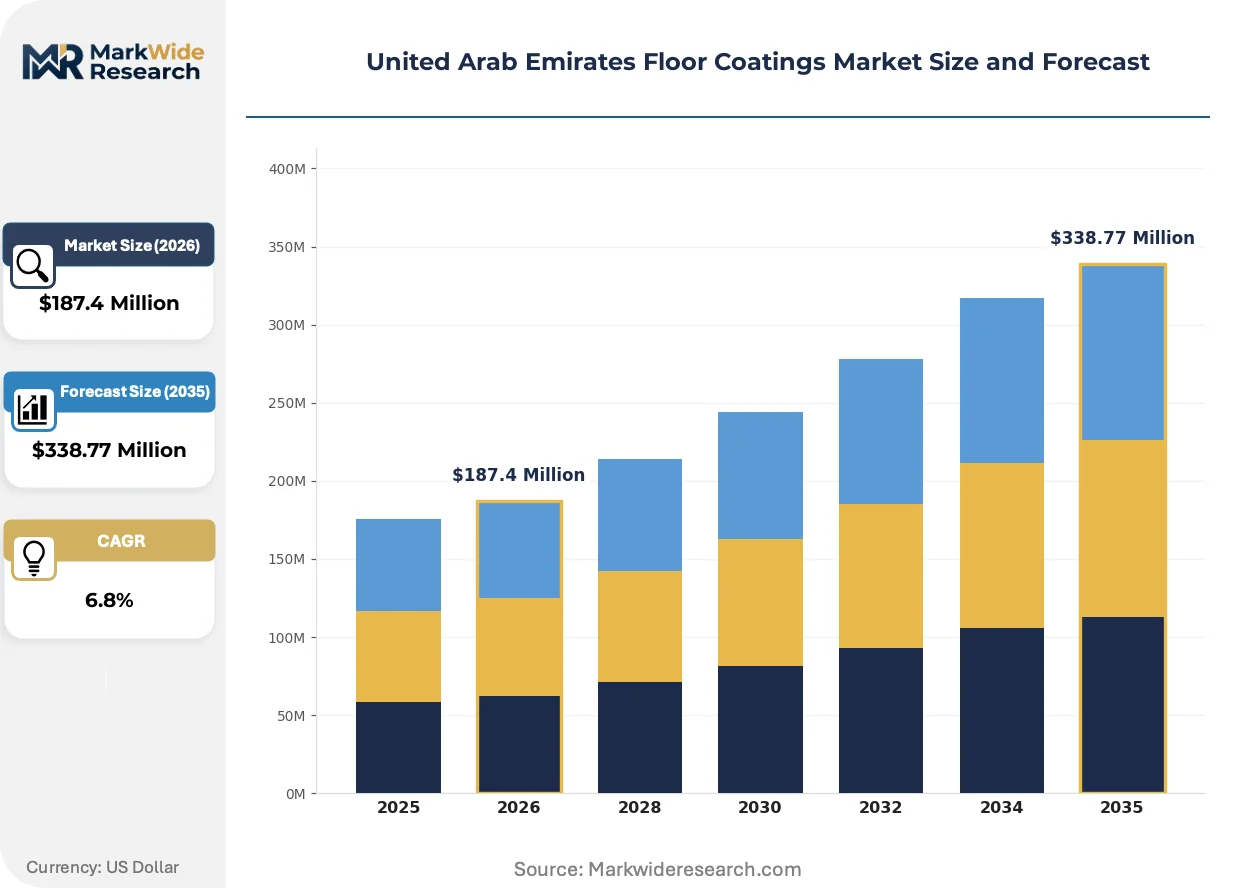
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Polyaspartic Application: Residential, Commercial, Industrial, Automotive End User: Construction, Renovation, Maintenance, Flooring Contractors Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | National Paints Factories Co Ltd, Hempel A/S, The Sherwin-Williams Company, Berger Paints Emirates Limited, Nippon Paint Holdings Co Ltd, Jotun, Akzo Nobel N V, Kansai Nerolac Paints Limited, Jazeera Paints, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Floor Coatings Market Strategic Shifts
Formulation chemistry and application methodology are converging around speed-to-service and environmental compliance, compressing traditional specification hierarchies.
Waterborne epoxy dispersions are replacing solvent-borne systems in commercial interiors. Facility managers in Dubai healthcare and education sectors specify these for occupied-space renovations. The technology is rendering obsolete multi-day shutdown protocols previously required for high-VOC curing cycles.
MOHAP's tightened VOC thresholds for interior architectural coatings are forcing reformulation investments. Manufacturers must resubmit product registrations with revised emission testing data. Industrial maintenance contractors face compressed qualification timelines as ESMA accelerates audit frequencies.
Building owners now unbundle coating procurement from single-source turnkey contracts. Specialized applicators in Abu Dhabi's petrochemical zones are capturing direct relationships with asset managers. This disintermediation concentrates in facilities with in-house engineering capabilities seeking material-only supply arrangements.
United Arab Emirates Floor Coatings Market Segmentation
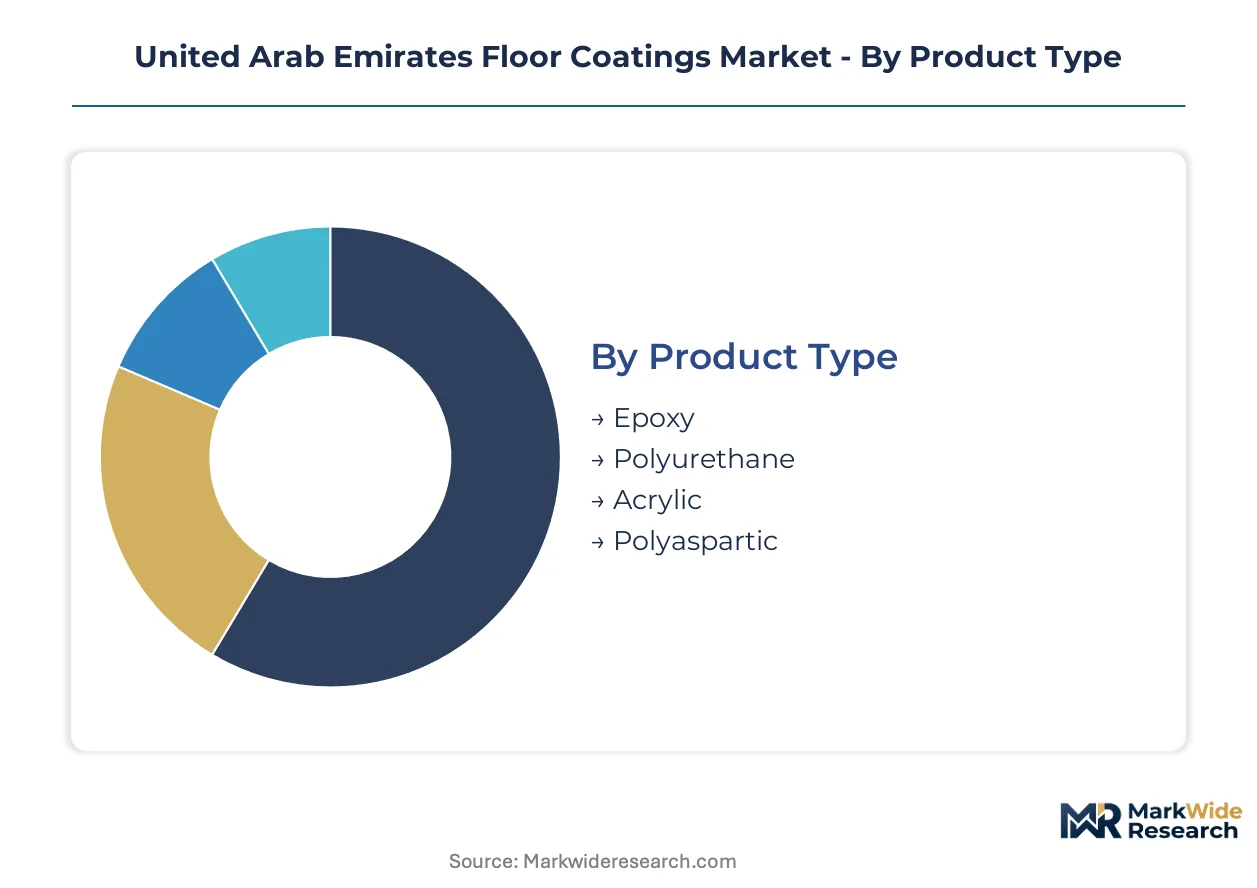
Segmentation in the UAE floor coatings market reveals divergent specification cycles across resin chemistries and end-use verticals. Contractors serving Dubai's logistics corridors prioritize rapid-cure systems that compress installation windows, while facility managers in Abu Dhabi's industrial zones emphasize chemical resistance over speed-to-service.
Product Type:
Cycle times vary dramatically by chemistry—polyaspartic formulations enable same-day return-to-service while epoxy systems demand multi-day curing protocols that extend project timelines.
- Epoxy:Two-component thermosetting systems formulated with bisphenol-A resins and amine hardeners deliver load-bearing capacity exceeding 50 MPa compressive strength. Demand concentrates in Abu Dhabi's petrochemical processing facilities where sulfuric acid and hydrocarbon exposure demands impermeable barrier protection. MOHAP's tightened VOC thresholds are forcing reformulation toward waterborne dispersions that trade some chemical resistance for emission compliance.
- Polyurethane:Aliphatic and aromatic isocyanate-cured systems provide thermal cycling flexibility across -30°C to 80°C operational ranges. Automotive service centers in Dubai's Al Quoz industrial district specify these for bay floors subject to hot tire pickup and thermal shock from steam cleaning. The chemistry commands premium positioning in applications where UV stability prevents yellowing degradation.
- Acrylic:Waterborne emulsion systems serve light-duty commercial interiors with lower capital budgets. Retail fit-outs in Sharjah's emerging commercial zones specify these for aesthetic refresh cycles.
- Polyaspartic:Polyurea-derived fast-cure aliphatic systems polymerize within 2-4 hours at ambient Gulf temperatures. Operational facilities across Dubai's logistics corridor adopt these to eliminate revenue-loss from extended shutdown windows.
Epoxy anchors the volume base while polyaspartic gains share at the steepest rate.
Application:
Cost tiers separate specification behavior—industrial installations prioritize lifecycle cost over first-cost, while residential and commercial segments remain price-sensitive.
- Residential:Decorative flake and metallic epoxy systems dominate villa basement and garage applications. Dubai's gated community developments specify these for aesthetic differentiation in amenity spaces.
- Commercial:High-solids epoxy and polyurethane systems serve healthcare, education, and retail environments where MOHAP indoor air quality standards mandate low-emission materials. Dubai Municipality's Al Sa'fat standards pull waterborne formulations into specification pipelines for occupied-space renovations.
- Industrial:High-build epoxy novolac and vinyl ester systems withstand concentrated chemical exposure in Abu Dhabi's Ruwais refining complex. These installations demand 3-6 millimeter film builds with embedded fiberglass reinforcement for secondary containment.
- Automotive:UV-stable polyurethane and polyaspartic systems resist hot tire pickup and brake fluid exposure. Service centers along Sheikh Zayed Road specify these for high-visibility customer areas.
Industrial applications absorb the highest per-square-meter material costs while commercial installations deliver the most consistent project pipeline.
End User:
Customer sophistication determines procurement patterns—engineered facilities with in-house technical staff unbundle material supply from installation, while smaller contractors favor turnkey arrangements.
- Construction:General contractors on Dubai's megaprojects specify coating systems during design development to align with Estidama green building point requirements. Early specification locks in approved product lists that constrain subcontractor substitution.
- Renovation:Facility managers in aging commercial stock prioritize low-odor, fast-cure systems that enable phased occupancy. Healthcare renovations in Abu Dhabi specify polyaspartic chemistries to minimize patient disruption.
- Maintenance:Asset managers in industrial facilities extend coating lifecycles through scheduled recoat programs. Predictive maintenance contracts in petrochemical zones bundle surface preparation and application into annual service agreements.
- Flooring Contractors:Specialized applicators in Sharjah's underpenetrated industrial zones build direct relationships with end users, bypassing traditional distributor markups through manufacturer-certified training programs.
Construction drives specification influence while maintenance contracts deliver the most predictable revenue recurrence.
Distribution Channel:
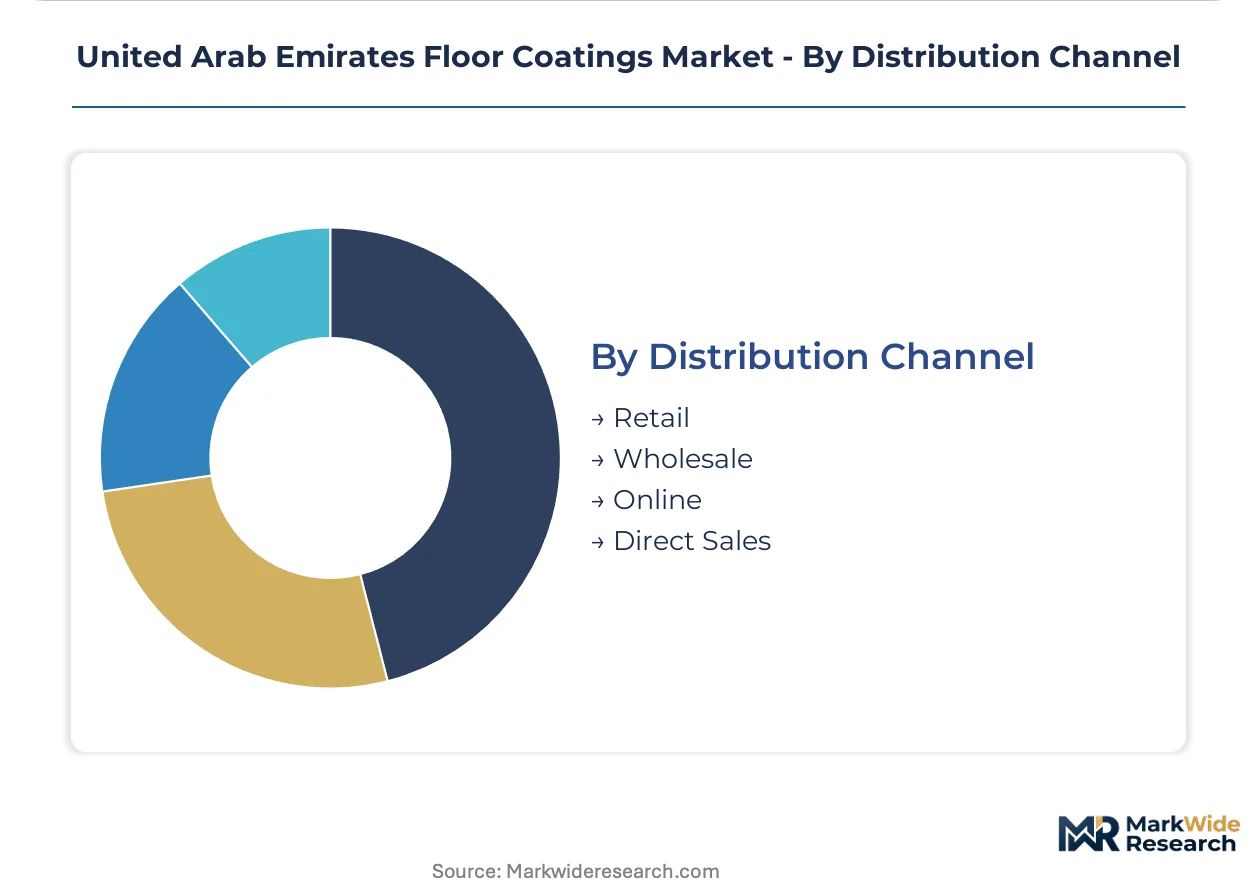
Channel selection correlates with project scale and technical complexity—complex industrial specifications demand direct technical support while standardized products flow through efficient wholesale networks.
- Retail:DIY-grade epoxy kits and decorative concrete stains serve residential renovation projects. Hardware chains in Dubai's Deira district stock limited color ranges for walk-in consumers.
- Wholesale:Distributors with ESMA certification infrastructure supply bulk formulations to contractor networks. Jotun's coastal manufacturing presence enables rapid replenishment across GCC projects through established wholesale relationships.
- Online:Emerging procurement channel serves small contractors seeking price transparency on standardized products. Limited penetration reflects ESMA conformity assessment requirements that favor physical documentation.
- Direct Sales:Manufacturers with technical service capabilities engage directly with petrochemical and logistics end users. National Paints Factories leverages domestic production to offer customized color matching and just-in-time delivery.
Wholesale channels dominate volume throughput while direct sales capture the highest-margin engineered specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Emirates diverge sharply between Dubai's fast-track commercial specifications and Abu Dhabi's heavy industrial durability requirements, with emerging sub-regions now adopting hybrid procurement approaches.
Dubai
Logistics corridor expansion along Sheikh Mohammed Bin Zayed Road drives specification of rapid-cure polyaspartic systems in warehousing and distribution facilities. Dubai Municipality's Al Sa'fat green building standards mandate low-VOC interior materials across new commercial construction, compressing qualification timelines for waterborne epoxy formulations. Jebel Ali Free Zone and Dubai South industrial clusters absorb premium coating volumes for multi-tenant facilities requiring minimal downtime.
Abu Dhabi
Petrochemical processing in Ruwais and downstream industrial zones demands high-build epoxy novolac systems with secondary containment capabilities. Estidama Pearl Rating System requirements accelerate specification of sustainable materials across government-backed developments. Khalifa Industrial Zone Abu Dhabi (KIZAD) anchors heavy industrial coating demand through integrated logistics and manufacturing tenant expansions.
Sharjah
Underpenetrated industrial areas outside the Dubai-Abu Dhabi corridor present first-mover opportunities for localized applicator networks. Sharjah Municipality's building code enforcement creates compliance entry points for ESMA-certified suppliers. Hamriyah Free Zone and Sharjah Airport International Free Zone (SAIF Zone) concentrate emerging manufacturing tenant demand for standard-duty industrial flooring.
Northern Emirates
Ras Al Khaimah's ceramics and cement manufacturing base generates steady maintenance coating demand for high-temperature processing environments. Fujairah's port and bunkering infrastructure requires specialized chemical-resistant systems for fuel handling areas. Federal infrastructure investments in Ajman and Umm Al Quwain are pulling basic commercial-grade epoxy specifications into retail and light industrial developments.
United Arab Emirates Floor Coatings Market Competitive Environment
Capability concentration sits with specialized applicator networks holding manufacturer certifications; scale advantage sits with coastal production assets serving GCC-wide project pipelines. The vendor base organizes around three strategic archetypes: domestic manufacturers with ESMA certification infrastructure, regional production hubs leveraging coastal logistics, and global formulators transferring technical expertise from adjacent industries. Dominant competitive moves include certified applicator network expansion and direct technical service engagement with petrochemical end users.
Within the domestic manufacturing tier, National Paints Factories Co Ltd anchors supply through extensive distribution reach into neighboring GCC markets. Jotun occupies a position exemplifying coastal production advantage with rapid replenishment capabilities across regional project corridors. Hempel A/S represents marine-grade technical specialization transferred into heavy industrial flooring applications. These three entities illustrate how geography and technical heritage shape competitive positioning without requiring identical strategic approaches.
| Leading Market Players |
|---|
| National Paints Factories Co Ltd |
| Hempel A/S |
| The Sherwin-Williams Company |
| Berger Paints Emirates Limited |
| Nippon Paint Holdings Co Ltd |
| Jotun |
| Akzo Nobel N V |
| Kansai Nerolac Paints Limited |
| Jazeera Paints |
| Others |
Value Chain & Pricing Dynamics
Bisphenol-A and amine hardener feedstock volatility compresses margin buffers across fixed-price project contracts, forcing tiered pricing spreads that separate ESMA-certified premium formulations from uncertified commodity imports while reshaping procurement toward coastal manufacturing hubs with rapid replenishment capabilities.
Pricing Analysis
Project-based contracting dominates the UAE floor coatings market, with general contractors locking material costs during design development to align with Estidama green building point requirements. Price differentiation rests on ESMA certification status and application-grade performance tiers, with certified waterborne epoxies commanding premiums over solvent-borne alternatives. Cost compression in standard-duty formulations is intensifying because applicators absorb feedstock fluctuations on fixed-price logistics corridor contracts. Small-scale renovation contractors exhibit the highest price sensitivity, while petrochemical facility managers prioritize lifecycle durability over first-cost.
Supply Chain Analysis
Extended payment terms from wholesale distributors to contractor networks anchor working capital flows, with manufacturer-direct supply-chain finance facilities emerging for large-scale Dubai megaprojects. Raw material sourcing draws from Saudi Arabia for epoxy resin feedstocks, India for specialty amine hardeners, and South Korea for polyurethane isocyanates. Single-source vulnerability concentrates in bisphenol-A derivatives tethered to crude oil derivative markets. Distribution runs through ESMA-certified wholesale networks serving contractor clusters in Jebel Ali Free Zone and KIZAD.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified applicator technician shortages constrain project throughput during peak construction windows, creating a structural bottleneck that rewards stakeholders investing in training infrastructure and manufacturer-direct qualification programs.
For Market Incumbents: Harden specification influence through certified applicator network expansion in Sharjah's underpenetrated industrial zones, while locking in coastal manufacturing capacity to defend against feedstock volatility on fixed-price Dubai logistics contracts. ESMA audit frequency acceleration threatens uncertified product portfolios, making certification infrastructure investment the critical defensive lever. For New Entrants and Emerging Players: Build out localized application service capabilities in Hamriyah Free Zone and SAIF Zone, where manufacturing tenant demand for standard-duty industrial flooring outpaces qualified applicator supply. Direct technical engagement with facility managers seeking material-only procurement arrangements bypasses entrenched wholesale markups and captures specification influence early in project development. For Investors and Strategic Acquirers: MOHAP's tightened VOC thresholds for interior architectural coatings reshapes the acquisition landscape toward formulators with waterborne dispersion capabilities and resubmitted product registrations. Viable targets include regional manufacturers with ESMA certification infrastructure and established wholesale reach into Oman and Saudi Arabia. Watch for applicator network consolidation signals as building owners accelerate unbundling of coating procurement from turnkey contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Applicator Network Expansion | Manufacturer-direct training programs lock specification influence while bypassing distributor markups in Sharjah industrial zones. |
| Waterborne Formulation Transition | MOHAP VOC compliance investments capture Al Sa'fat-mandated commercial interior specifications ahead of emission threshold tightening. |
| Coastal Manufacturing Scale-Up | Jebel Ali and KIZAD proximity enables rapid replenishment across GCC project corridors with compressed delivery windows. |
| Direct Technical Service Engagement | Petrochemical facility relationships in Ruwais secure high-margin engineered specifications with secondary containment requirements. |
| Photocatalytic Additive Integration | Titanium dioxide self-cleaning formulations align with federal sustainability mandates for air-purifying surface specifications. |
Study Parameters
A standing panel of coating applicators, facility managers at Dubai logistics facilities, procurement leads at Abu Dhabi petrochemical complexes, and ESMA certification specialists provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with wholesale distributors and manufacturer technical service directors against secondary validation through customs trade data, Dubai Municipality building permit records, and MOHAP product registration filings. Bottom-up project pipeline analysis triangulated against top-down resin consumption estimates from regional chemical industry associations.
Scenario-bracketing framed projections across low, base, and high-growth assumptions without year-specific anchoring. Segmentation dimensions modeled include resin chemistry tier, application grade, end-user procurement sophistication, and regional industrial cluster penetration. CAGRs were derived from elasticity-adjusted demand curves incorporating construction spend correlations and maintenance cycle frequencies. Forecast inputs captured Al Sa'fat green building adoption rates and polyaspartic cure chemistry penetration in operational facility renovations.
Stress conditions across epoxy resin feedstock volatility, ESMA audit enforcement intensity, and humid-season application window constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory trajectory and construction pipeline commitments. Macroeconomic contraction in Gulf commercial real estate, unanticipated MOHAP formulation bans, or breakthrough moisture-tolerant epoxy technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Hydrophobic Coating Market
Coatings
Paper Coating Binders Market
Coatings
Global Solar Panel Coatings Market
Coatings
China Marine Coatings Market
Coatings
Fillers and Coating Market
Coatings
Electrocoat Market
Coatings
Flexible Waterproof Coating Market
Coatings
Waterborne Wood Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
Leisure Boat Marine Coatings Market
Coatings
Industrial Liquid Coating Market
Coatings
2K Coatings Market
Coatings
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market
Coatings
Global Metal Coatings Market
Coatings
Global Intumescent Coatings Market
Coatings
Conductive Coatings Market