
 Carpet Back Coatings Market | 2026-2036
Carpet Back Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Carpet Back Coatings Market Outlook
Commercial flooring refurbishment across hospitality and office sectors is realigning procurement volumes toward higher-performance back coatings. Interface leverages its modular carpet expertise to anchor specification-driven demand in corporate interiors. Dow Chemical Company sustains technology leadership through advanced synthetic latex formulations with enhanced tuft-lock performance. Mohawk Industries dominates North American manufacturing scale, while Wacker Chemie specializes in silicone-modified polyurethane systems for moisture-resistant applications.
Carpet back coatings comprise polymer-based layers applied to the reverse side of woven or tufted carpet constructions, typically formulated from natural latex, synthetic latex, or polyurethane at coating weights ranging from 20 to 40 ounces per square yard to secure yarn tufts and provide dimensional stability. The primary industrial purpose centers on preventing edge raveling, improving lay-flat characteristics, and enabling secondary backing adhesion during installation. Synthetic latex formulations command the largest volume share due to cost efficiency and consistent cure profiles, though polyurethane segments attract premium positioning where moisture barriers and extended durability specifications dominate. Hot melt adhesive applications represent the fastest-growing category as manufacturers seek solvent-free processing with reduced energy curing requirements.
REACH compliance in Europe and evolving EPA VOC standards in the United States are elevating formulation requirements for low-emission latex systems, directly constraining legacy chemistries and accelerating water-based and bio-content substitutions. California's CARB regulations and Germany's Blue Angel certification create divergent compliance pathways that fragment formulation strategies across Atlantic supply chains. Stakeholders must monitor regulatory harmonization pressures between EU Green Deal timelines and state-level U.S. mandates while positioning R&D investments toward zero-VOC platforms that satisfy multiple jurisdiction requirements simultaneously.
Market Dynamics
Commercial flooring refurbishment cycles are compressing specification timelines, forcing coating suppliers to align R&D investments with accelerated project delivery demands from hospitality and corporate interior designers.
Growth Catalysts
- REACH Phase-Out Schedules:ECHA restrictions on SVHCs in latex formulations are compelling manufacturers to reformulate with bio-based styrene-butadiene alternatives, opening specification doors in German and Dutch commercial fit-outs.
- Modular Carpet Retrofit Intensity:Office-to-residential conversions across US urban cores are driving replacement demand for back-coated tile products with enhanced dimensional stability for repeated installation cycles.
- Hot Melt Processing:Solvent-free adhesive application systems are capturing specification share from conventional latex coating lines in high-volume tufting operations.
Market Restraints
- Styrene Price Volatility:Feedstock cost swings for synthetic latex precursors compress margin predictability for coating compounders serving price-locked contract flooring accounts.
- Belgian Chemicals Concentration:European SBR latex supply chains exhibit geographic clustering around Antwerp-Rotterdam port infrastructure, amplifying disruption risk from single-point logistics failures.
- Performance Trade-Offs:Water-based low-VOC formulations sacrifice tuft-lock strength versus solvent-borne equivalents, constraining adoption in heavy-traffic aviation and healthcare segments.
Strategic Opportunities
- India Commercial Real Estate:Bengaluru and Mumbai office absorption rates are outpacing domestic back-coating capacity, creating import substitution openings for polyurethane moisture-barrier systems.
- EU Green Deal Public Procurement:Mandatory environmental criteria in government building tenders are tilting specifications toward bio-content certified coatings with EPD documentation.
- Recyclable Monomaterial Construction:Single-polymer carpet designs compatible with closed-loop recycling are converging with compatible thermoplastic back coatings to unlock circular economy premiums.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in polymer rheology and cure kinetics for carpet applications is concentrating among retiring technical workforces in US and German manufacturing regions.
- Dual Certification Timelines:Simultaneous pursuit of Blue Angel and FloorScore credentials extends product qualification cycles by 8-14 months, delaying revenue recognition on reformulated lines.
- Legacy Equipment Retrofit Costs:Converting existing coating lines from solvent-based to water-based curing demands capital outlays for infrared drying arrays that mid-tier tufters defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carpet Back Coatings Market |
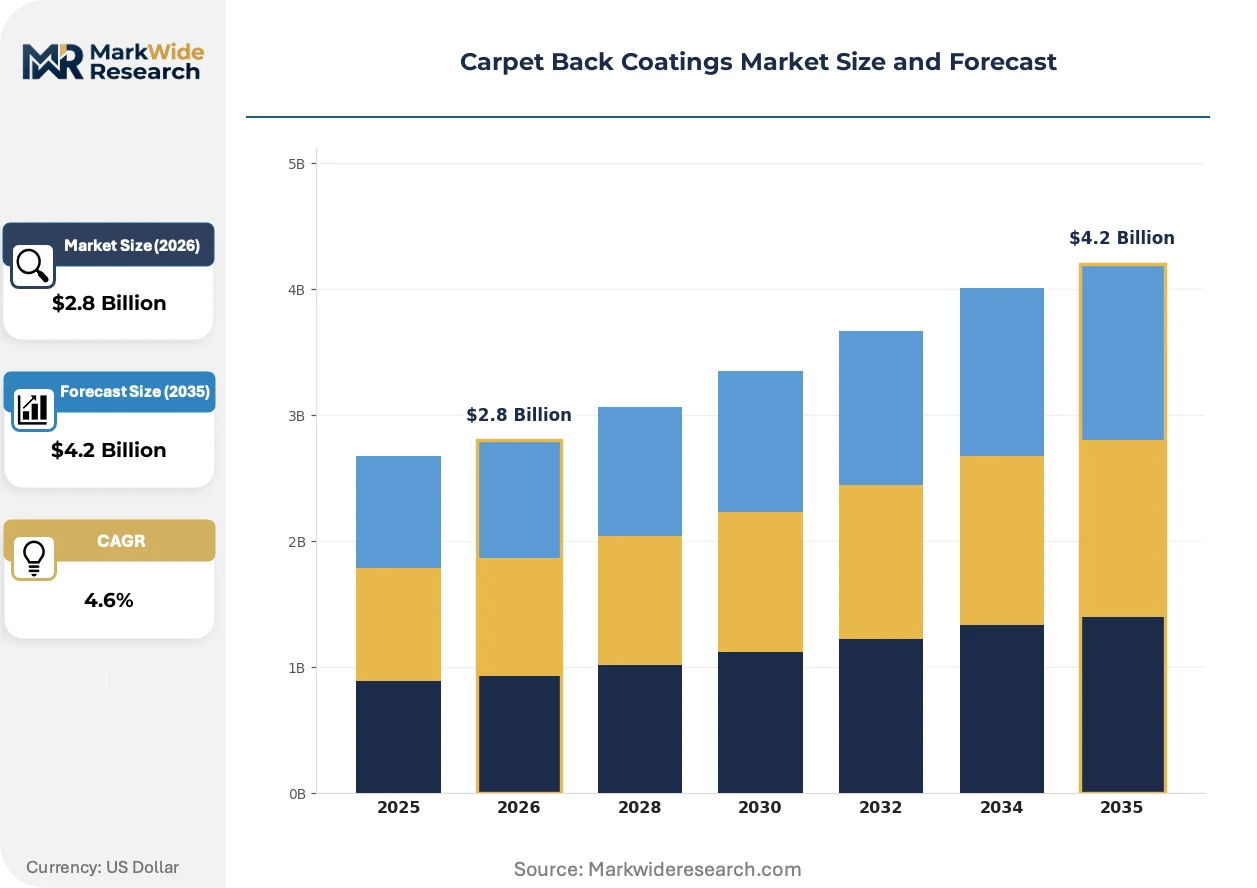
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Latex, Synthetic Latex, Polyurethane, Hot Melt Adhesives Application: Residential, Commercial, Automotive, Aerospace End User: Manufacturers, Installers, Distributors, Retailers Distribution Channel: Online, Offline, Direct Sales, Wholesale |
| Companies Covered | Interface, Dow Chemical Company, Shaw Industries Group, Wacker Chemie, BASF, Mohawk Industries, Beaulieu International Group, Trinseo, Tarkett, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carpet Back Coatings Market Strategic Shifts
Formulation chemistry and application equipment are converging to eliminate solvent content while preserving performance thresholds that specification architects demand for high-warranty installations.
Recyclable thermoplastic polyurethane back coatings are rewriting material recovery economics for commercial carpet tile. Hospitality chains with corporate sustainability mandates are specifying these systems for 10-15 year replacement cycles. The technology is compressing landfill diversion costs and enabling take-back program profitability that latex-bonded constructions cannot match.
EPA VOC emission standards under the National Emission Standards for Hazardous Air Pollutants are tightening permissible limits on styrene emissions from coating operations. US-based manufacturers face capital decisions on carbon bed capture systems versus process conversion. California's South Coast Air Quality Management District is advancing the most stringent district rules, pre-positioning compliant suppliers for statewide specification advantages.
Building certification systems are resequencing procurement authority within flooring decisions. LEED v4.1 and WELL Building Standard point structures now weight material ingredient transparency above first-cost considerations. Corporate real estate teams in Chicago, London, and Singapore are centralizing specification authority previously held by project architects, compressing vendor qualification to pre-approved lists with documented EPDs and HPDs.
Carpet Back Coatings Market Segmentation
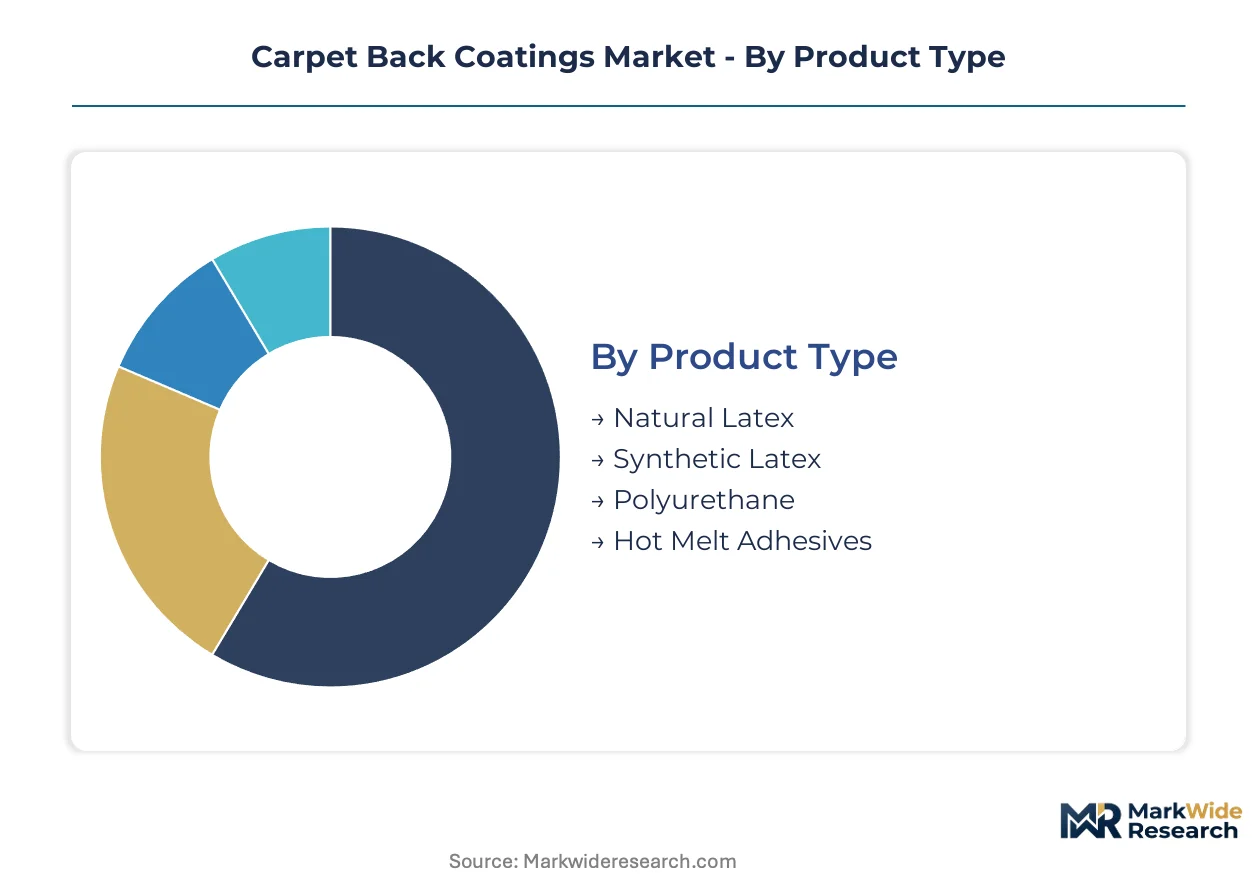
Coating selection in carpet manufacturing hinges on performance specifications, regulatory compliance thresholds, and installation method compatibility. Procurement patterns diverge sharply between volume-driven residential builders and specification-sensitive commercial fit-out contractors.
Product Type:
Cost-performance trade-offs dominate formulation decisions as buyers balance tuft-lock durability against emission compliance and energy curing requirements.
- Synthetic Latex:Styrene-butadiene rubber formulations deliver consistent cure profiles and cost efficiency for high-volume tufting operations. Demand concentrates in United States residential carpet manufacturing where price-locked builder contracts prioritize predictable unit economics over premium performance.
- Polyurethane:Moisture-cured and thermoplastic systems provide superior dimensional stability and vapor barrier properties. German commercial flooring specifications favor these formulations for healthcare and hospitality installations where extended warranties and recycled content credentials command specification priority.
- Natural Latex:Hevea brasiliensis-derived compounds serve niche sustainability positioning with bio-content advantages for LEED and Blue Angel certification pathways.
- Hot Melt Adhesives:Solvent-free thermoplastic application systems eliminate VOC emissions and reduce curing energy. These systems are gaining specification share in automotive carpet manufacturing where EPA emission standards constrain conventional coating lines.
Synthetic latex leads on scale; hot melt adhesives lead on momentum.
Application:
End-use durability requirements and replacement cycle intensity determine coating weight specifications and polymer selection priorities.
- Commercial:Office, hospitality, and institutional installations demand 30-40 oz/yd² coating weights with reinforced tuft-lock for rolling traffic. China and United States urban refurbishment cycles are compressing specification timelines and favoring suppliers with rapid formulation turnaround capabilities.
- Residential:Builder-grade and retail replacement segments prioritize cost efficiency over extended performance warranties. Demand clusters in United States single-family construction and German multifamily renovation activity.
- Automotive:Molded carpet assemblies for vehicle interiors require heat-resistant back coatings compatible with interior air quality standards. Formulation chemistry must withstand dashboard-level thermal cycling without plasticizer migration.
- Aerospace:Cabin flooring applications demand flame-retardant, low-smoke, low-toxicity coatings meeting FAA certification requirements. Specification authority rests with tier-one seat manufacturers and airframe integrators rather than carpet mills.
Commercial applications command specification premiums; automotive represents the steepest expansion trajectory.
End User:
Technical expertise depth and inventory carrying capacity determine channel preference and service level expectations.
- Manufacturers:Integrated tufting and coating operations in Belgium, United States, and China drive bulk compound procurement with formulation customization requirements. These buyers maintain captive R&D relationships with latex suppliers.
- Installers:Commercial flooring contractors specify pre-coated products but require secondary adhesive systems for seam sealing and edge treatment. Regional installer networks influence local distributor stocking decisions.
- Distributors:Inventory aggregation and just-in-time delivery capabilities serve mid-tier manufacturers without vertical integration into coating operations. Geographic coverage determines competitive positioning.
- Retailers:Big-box and specialty flooring channels demand finished goods with visible certification labels and warranty documentation. Consumer-facing sustainability claims increasingly influence product mix.
Manufacturers dominate volume procurement; installers drive specification influence.
Distribution Channel:
Order size, technical support requirements, and delivery urgency shape channel selection across buyer segments.
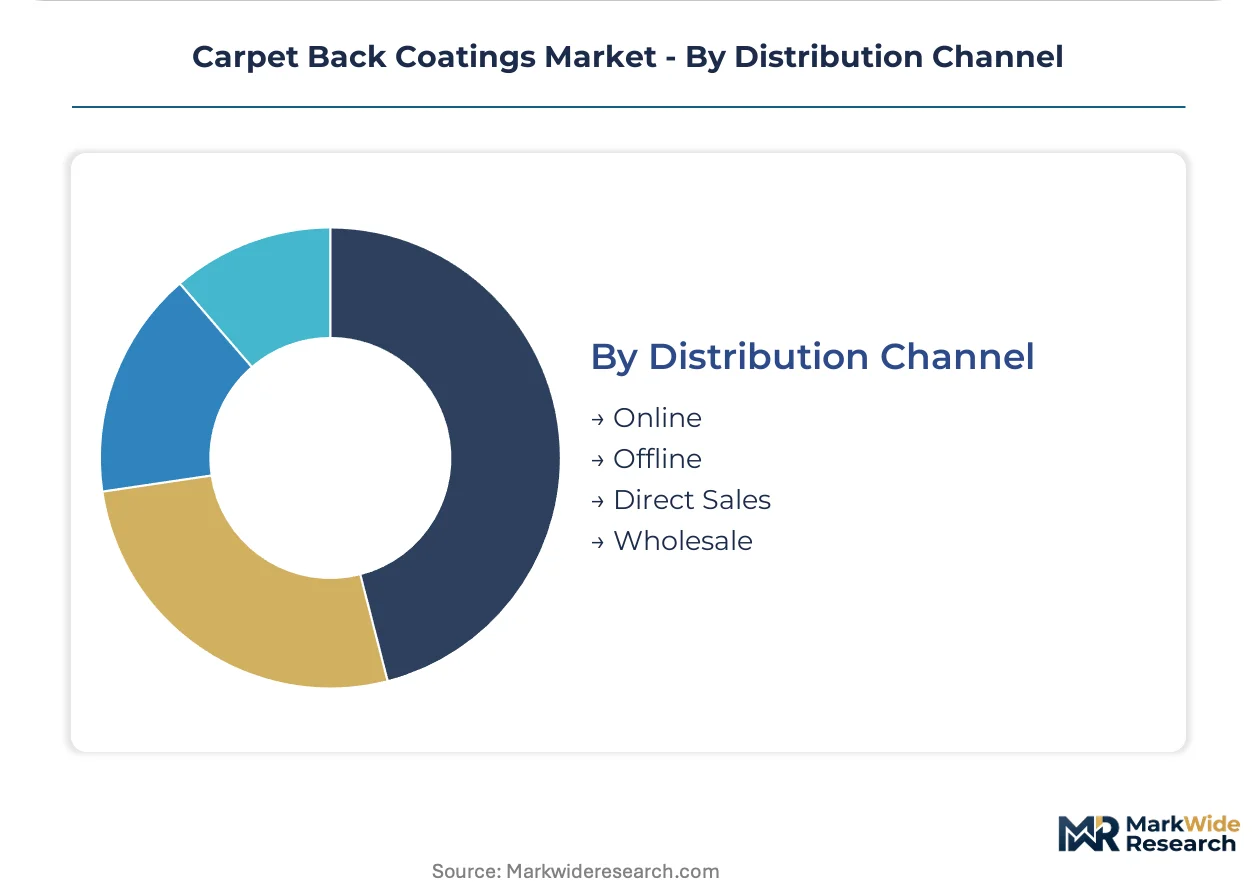
- Direct Sales:Large carpet manufacturers negotiate multi-year supply agreements with compounders for synthetic latex and polyurethane systems. These relationships lock in volume commitments and co-development roadmaps.
- Wholesale:Regional distributors serve smaller tufting operations with standard formulation inventories and credit terms. Belgian and Dutch chemical distributors maintain European SBR latex stocking positions.
- Offline:Traditional trade show and field sales engagement persists for specification-driven commercial segments where tactile sample evaluation and face-to-face technical consultation remain essential.
- Online:Digital procurement platforms capture commodity adhesive and ancillary product sales for smaller installers and maintenance contractors. Technical complexity limits online penetration for primary coating compounds.
Direct sales anchor volume concentration; online channels are expanding most quickly in aftermarket segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Antwerp-Rotterdam chemical corridor anchors European carpet back coating supply chains, while manufacturing demand concentrates across five national markets where refurbishment cycles and regulatory frameworks diverge sharply.
United States
Commercial office-to-residential conversions in Chicago and New York Metro are accelerating carpet tile replacement demand. EPA National Emission Standards for Hazardous Air Pollutants are tightening styrene emission limits from coating operations. The Dalton-Whitfield carpet manufacturing cluster in northwest Georgia maintains the highest concentration of integrated tufting and coating capacity.
Germany
Healthcare and hospitality fit-outs in Frankfurt and Munich are specifying moisture-barrier polyurethane systems with extended warranties. Blue Angel certification and EU Green Deal public procurement mandates are tilting specifications toward bio-content certified coatings. The Rhine-Ruhr industrial region hosts specialized compounders serving commercial flooring manufacturers.
China
Urban commercial refurbishment in Shanghai and Beijing is compressing specification timelines for coating suppliers. GB standards for indoor air quality are elevating formulation requirements for low-emission systems. The Yangtze River Delta carpet manufacturing belt is expanding polyurethane coating capacity for domestic and export markets.
Belgium
European SBR latex supply chains exhibit geographic clustering around Antwerp-Rotterdam port infrastructure, amplifying disruption risk from single-point logistics failures. REACH Phase-Out Schedules on SVHCs are compelling manufacturers to reformulate with bio-based alternatives. The Port of Antwerp chemical complex serves as the primary feedstock hub for continental coating compounders.
India
Bengaluru and Mumbai office absorption rates are outpacing domestic back-coating capacity, creating import substitution openings for moisture-barrier systems. BIS standards for building materials are evolving to address indoor air quality in commercial construction. The Maharashtra-Gujarat industrial corridor is attracting coating technology licensing agreements from European suppliers.
Carpet Back Coatings Market Competitive Environment
Capacity expansion dominates the current landscape as compounders scale water-based and hot melt production lines to capture specification share from legacy solvent systems. The vendor base organizes into three tiers: integrated chemical majors with captive latex production, specialized coating compounders serving regional tufting operations, and equipment-technology hybrids bundling application systems with formulation supply. Strategic archetypes include specification-driven premium positioning, cost-optimized volume supply, and sustainability-certified niche capture. M&A activity and geographic licensing agreements represent the dominant competitive moves as players seek backward integration into bio-based feedstocks.
Within the integrated chemical tier, Dow Chemical Company and BASF exemplify scale-driven formulation leadership, while Wacker Chemie occupies a specialist position in silicone-modified systems. Mohawk Industries anchors North American manufacturing scale through captive coating operations. Interface represents specification-driven demand capture in corporate interiors through modular carpet expertise.
| Leading Market Players |
|---|
| Interface |
| Dow Chemical Company |
| Shaw Industries Group |
| Wacker Chemie |
| BASF |
| Mohawk Industries |
| Beaulieu International Group |
| Trinseo |
| Tarkett |
| Others |
Value Chain & Pricing Dynamics
Blue Angel certification gates both qualified supply and premium-tier pricing access in German commercial flooring, compelling compounders to absorb reformulation costs for bio-based styrene-butadiene alternatives while capturing margin premiums through specification-locked contracts with healthcare and hospitality fit-out contractors.
Pricing Analysis
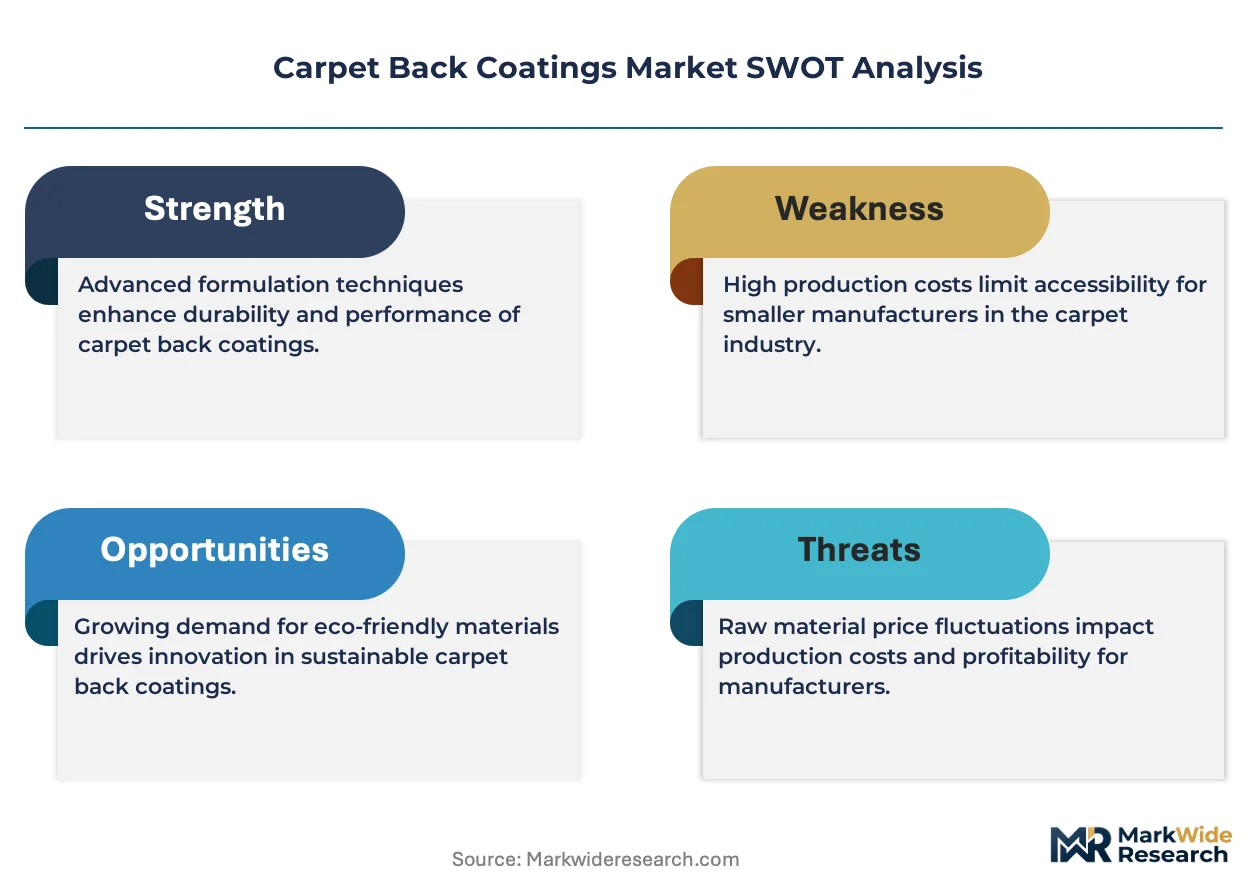
Distributor margins of 12-18% separate bulk compound procurement from specification-driven commercial channels, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and volume scale. Price differentiation stems from EPD documentation and moisture-barrier performance tiers, with cost compression in synthetic latex formulations intensifying because styrene feedstock volatility compresses margin predictability for coating compounders. Residential builder-grade buyers exhibit highest price sensitivity, while German healthcare specifiers demonstrate lowest sensitivity due to warranty-driven procurement.
Supply Chain Analysis
Dual-sourcing requirements from Mohawk Industries and Interface mandate multi-supplier qualification for SBR latex and polyurethane systems, fragmenting procurement across Belgian, German, and Chinese compounders. Geographic supply concentrates in Belgium, United States, and China, with raw material dependencies on styrene monomer, butadiene feedstock, and isocyanate precursors. Single-point vulnerability around Antwerp-Rotterdam port infrastructure amplifies disruption risk from logistics chokepoints. Distribution runs through direct sales for large manufacturers and regional wholesale distributors for mid-tier tufting operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA National Emission Standards for Hazardous Air Pollutants and REACH Phase-Out Schedules on SVHCs are compressing specification timelines and elevating demand for water-based and bio-content certified formulations.
For Market Incumbents: Anticipate margin compression from hot melt adhesive substitution by accelerating captive R&D in thermoplastic polyurethane systems and securing backward integration into bio-based feedstocks. Dow Chemical Company and BASF must defend specification share through rapid Blue Angel and FloorScore dual certification timelines, while Mohawk Industries leverages captive coating operations to lock in volume commitments from price-locked builder contracts. For New Entrants and Emerging Players: Begin with moisture-barrier polyurethane systems for Indian commercial real estate in Bengaluru and Mumbai, where domestic back-coating capacity lags office absorption rates. Target government building tenders under EU Green Deal public procurement mandates by leading with EPD-documented bio-content certified coatings, using specification consulting as the primary go-to-market angle to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for specialized coating compounders with silicone-modified polyurethane expertise because formulation chemist scarcity is concentrating among retiring technical workforces in US and German manufacturing regions. Over a 5-10 year viability window, prioritize acquisition targets with established Blue Angel credentials and licensing agreements in the Maharashtra-Gujarat industrial corridor. The signal to watch is regulatory harmonization pressure between EU Green Deal timelines and state-level US mandates, which would accelerate zero-VOC platform adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Water-based and hot melt production lines capture specification share from solvent systems in Dalton-Whitfield cluster. |
| Backward Integration | Bio-based feedstock control secures margin stability against styrene price volatility for SBR latex compounders. |
| Green Manufacturing Transition | Zero-VOC platform investments satisfy simultaneous EPA and ECHA compliance requirements. |
| Long-term Supply Agreement | Multi-year volume commitments with Interface anchor specification-driven demand in corporate interiors. |
| Joint Venture | Technology licensing agreements in Yangtze River Delta expand polyurethane coating capacity for export markets. |
Study Parameters
Multiple input streams — technical director interviews at compounders, procurement lead discussions at carpet manufacturers, and regulatory affairs consultations — were reconciled against customs data, SEC 10-K filings, and ECHA SVHC registration databases. Primary engagement spanned plant managers at Belgian and US coating facilities, distribution channel partners in German wholesale networks, and R&D directors specializing in polymer rheology. Secondary validation drew from ACC industry reports, EU Green Deal procurement documentation, and trade flow analysis across the Antwerp-Rotterdam chemical corridor. Bottom-up volume modeling and top-down market sizing were triangulated to converge estimates.
Historical shipment data was cross-referenced against expert panel inputs to construct analytical frameworks across the analysis window. Segmentation dimensions modeled include coating chemistry type, application durability tier, end-user channel, and regional regulatory cluster. CAGRs were derived from slope analysis of annual progression rates applied to base-year anchoring. Industry-specific forecast inputs incorporated REACH Phase-Out Schedule compliance timelines and commercial refurbishment cycle intensity in US urban cores.
Several conditions sit outside the modeled scope, including sudden feedstock price shocks, port infrastructure disruptions, and accelerated solvent-system bans beyond current regulatory trajectories. Deviation in EPA-ECHA regulatory harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Acrylic Surface Coating Market
Coatings
Coating Binders Market
Coatings
Coating Auxiliaries Market
Coatings
Tablet and Pellet Coating Systems Market
Coatings
Gelcoat Market
Coatings
Coating Equipment Market
Coatings
Acrylic Protective Coating Market
Coatings
Global Low Temperature Powder Coatings Market
Coatings
Cool Roof Coatings Market
Coatings
Tablet Coatings Market
Coatings
Conductive Coatings Market
Coatings
Global Anti Slip Coatings Market
Coatings
Consumer Appliance Coatings Market
Coatings
Global Automotive Specialty Coatings Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Global Smart Coating Market