
 Quantum Dots Market | 2026-2036
Quantum Dots Market Size, Share, and Industry Trends Forecast 2026-2036
Quantum Dots Market Intelligence
PhD-level colloidal chemists and quantum materials specialists is redrawing competitive boundaries across the industry. Samsung Electronics leverages captive semiconductor fabrication expertise to dominate QLED display integration. Nanosys Inc. anchors its position through sustained cadmium-free quantum dot chemistry leadership. Merck KGaA competes via vertical control over precursor chemical supply chains.
Quantum dots are nanoscale semiconductor crystals typically two to ten nanometers in diameter that emit precise wavelengths of light when excited, with composition tunable through particle size adjustment during colloidal synthesis. Their primary commercial purpose centers on converting broad-spectrum backlight into narrow-band emission for enhanced color gamut in displays and photovoltaic efficiency gains. InP quantum dots now lead product type migration as manufacturers abandon cadmium-based CdSe formulations under regulatory pressure. Display panels command the dominant application share while photovoltaics represents the fastest-expanding margin pool for specialized suppliers.
EPA hazardous substance rules and EU REACH cadmium restrictions directly shape material selection and cross-border market access for quantum dot formulations. ECHA substance evaluation protocols force reformulation timelines that favor InP and perovskite chemistries over legacy CdSe architectures. China's SAMR national standards and MIIT optoelectronics directives create parallel compliance requirements for domestic production and import channels. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which chemistries secure long-term production approval.
Market Dynamics
Material substitution away from cadmium-based CdSe quantum dots toward InP and perovskite alternatives is compressing established supply chains while creating first-mover advantages for reformulation-ready suppliers. This chemistry transition intersects with tightening REACH substance restrictions and display OEM qualification timelines.
Growth Catalysts
- RoHS cadmium exemptions expiration:EU electronics manufacturers face mandatory reformulation deadlines that accelerate InP quantum dot adoption for QLED backlight units.
- Photovoltaic efficiency mandates:National renewable portfolio standards in multiple jurisdictions drive tandem cell architectures incorporating quantum dot light-harvesting layers.
- Colloidal synthesis automation:Continuous-flow reactor deployment reduces batch-to-batch optical variability, enabling display panel OEMs to tighten color gamut specifications.
Market Restraints
- Indium supply concentration:Primary indium refining capacity clusters in Chinese smelters, exposing InP quantum dot manufacturers to export quota volatility.
- Perovskite stability limitations:Moisture and thermal degradation of lead-halide perovskite quantum dots restrict outdoor and high-temperature application viability.
- ECHA authorization timelines:Protracted substance evaluation protocols delay new chemistry market entry, extending payback periods for R&D-intensive reformulation programs.
Strategic Opportunities
- India display manufacturing:PLI scheme incentives for semiconductor and display fabrication create localized quantum dot formulation demand from emerging panel fabs.
- Agrivoltaic spectral management:Quantum dot luminescent downshifting layers optimize photosynthetically active radiation transmission in combined solar-agriculture installations.
- Biomedical imaging probes:Near-infrared-emitting InAs quantum dots enable deep-tissue fluorescence microscopy, opening diagnostic applications beyond display-centric revenue pools.
Industry Challenges
- PhD-level colloidal chemist scarcity:Synthesis optimization and surface ligand engineering require specialized expertise that outpaces academic pipeline output.
- OEM qualification cycle duration:Display panel manufacturers impose 18-24 month reliability testing protocols that delay new quantum dot chemistry commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quantum Dots Market |
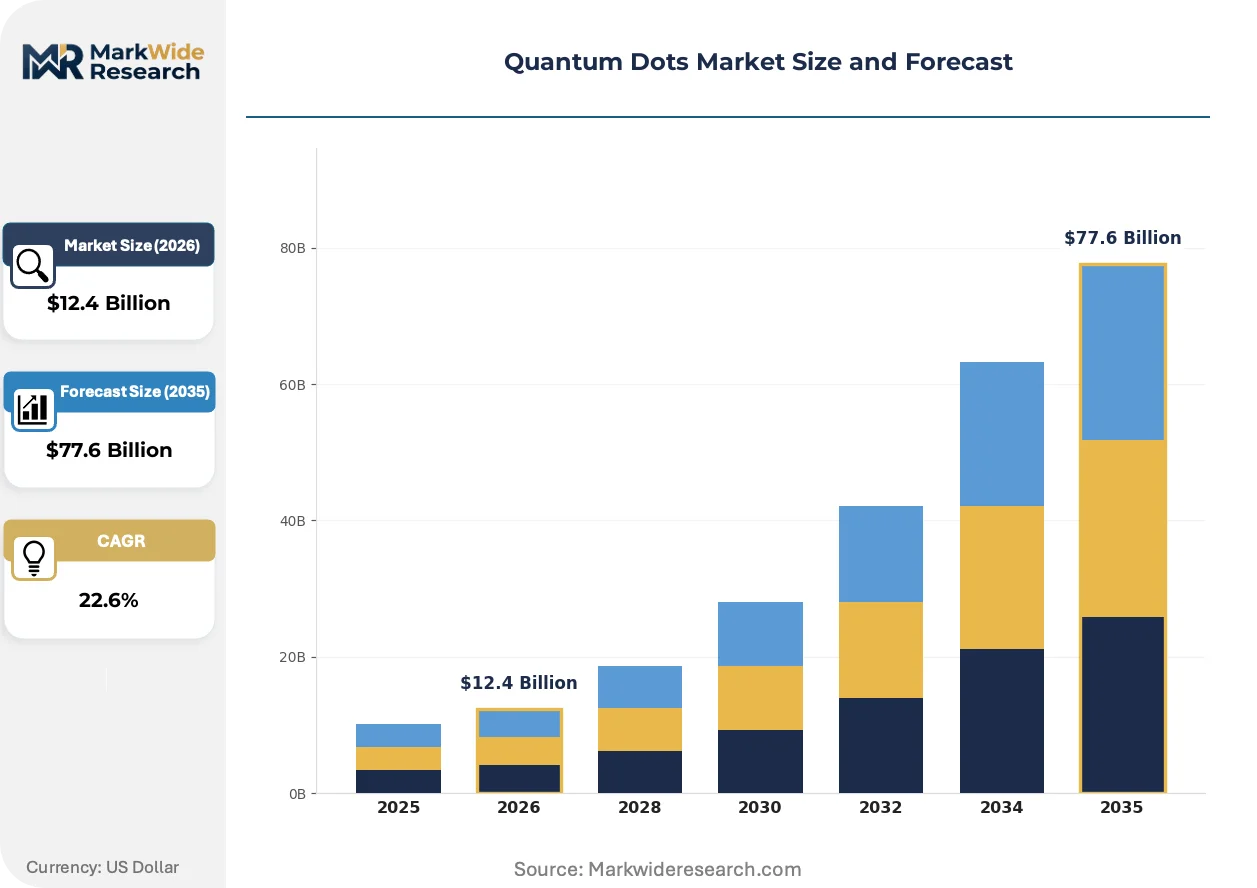
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $77.6 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CdSe Quantum Dots, InP Quantum Dots, PbS Quantum Dots, Perovskite Quantum Dots, Carbon Quantum Dots Technology: Colloidal Synthesis, Epitaxial Growth, Lithography, Chemical Vapor Deposition, Atomic Layer Deposition Application: Display Panels, Photovoltaics, Bioimaging, Lighting, Sensors, Security Ink End User Industry: Consumer Electronics, Semiconductor Fabricators, Research Institutions, Telecommunications, Optoelectronics |
| Companies Covered | Samsung Electronics Co., Ltd., Nanosys Inc., LG Display Co., Ltd., BOE Technology Group Co., Ltd., Nanoco Group plc, AUO Corporation, Merck KGaA, TCL China Star Optoelectronics Technology Co., Ltd., Shoei Chemical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quantum Dots Market Strategic Shifts & Innovations
Competitive advantage in quantum dot supply is migrating from raw material access to precision synthesis control and surface chemistry engineering. Technical differentiation now centers on emission linewidth narrowing and photostability enhancement rather than basic composition shifts.
Perovskite quantum dot synthesis is fragmenting across multiple ligand-exchange and encapsulation approaches as researchers address intrinsic moisture sensitivity. Display manufacturers in South Korea and China are piloting these materials for narrow-band green emitters where CdSe alternatives face regulatory sunset. The technology is fragmenting competitive positioning between vapor-deposition and solution-processed integration routes, forcing equipment suppliers to support divergent manufacturing footprints.
REACH substance evaluation protocols are forcing reformulation roadmaps that favor InP and perovskite architectures over legacy CdSe chemistries. ECHA authorization requirements compress decision timelines for display OEMs selecting quantum dot suppliers. European electronics brands now specify cadmium-free alternatives in procurement contracts, shifting supplier qualification criteria toward regulatory pre-certification rather than post-hoc compliance documentation.
Display panel OEMs are consolidating quantum dot procurement around fewer qualified suppliers capable of multi-chemistry portfolios. Long-term supply agreements with volume commitments are displacing spot purchasing for high-volume QLED television programs. This concentration is most visible in Chinese and South Korean manufacturing clusters where vertically integrated display groups internalize formulation expertise or lock in dedicated external supply.
Quantum Dots Market Segmentation
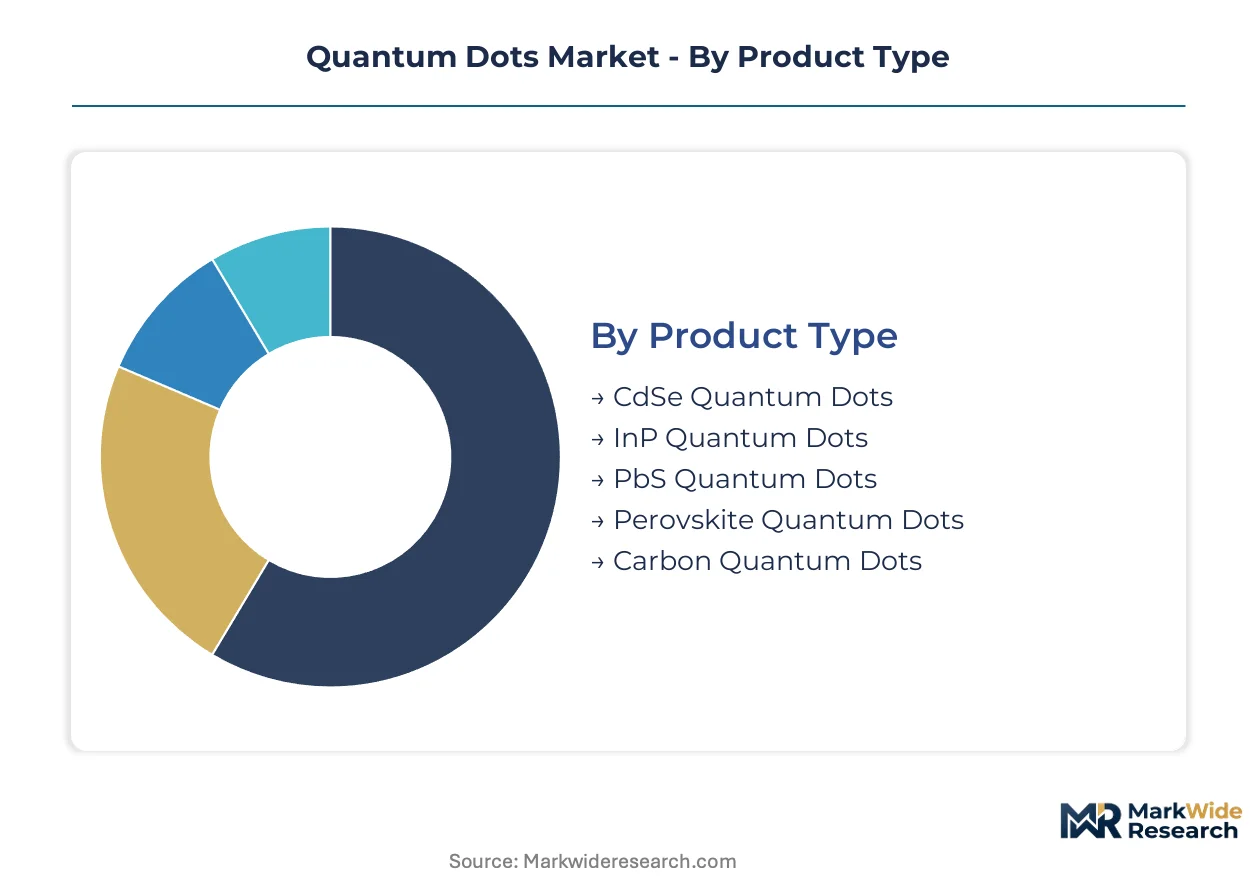
Segmentation in quantum dots reveals how regulatory chemistry mandates and display manufacturing geography reshape supplier portfolios. Each dimension exposes distinct margin pools, qualification barriers, and technology migration timelines that determine competitive survival.
Product Type:
Domestic production of cadmium-free alternatives concentrates in South Korea and China, while CdSe legacy supply still serves export markets with deferred regulatory deadlines.
- InP Quantum Dots:These indium phosphide nanocrystals emit precise wavelengths through quantum confinement without heavy metal content. Display manufacturers in Suwon and Shenzhen specify InP formulations for QLED panels bound for European markets facing REACH cadmium restrictions. Indium supply exposure through Chinese smelter concentration creates procurement risk that qualified suppliers hedge through long-term offtake agreements.
- Perovskite Quantum Dots:Lead-halide perovskite structures achieve narrow emission linewidths for high-purity green and red display primaries. South Korean panel OEMs pilot these materials for next-generation QLED where CdSe faces regulatory sunset, though moisture sensitivity limits outdoor application scope. Encapsulation chemistry differentiation separates qualified suppliers from laboratory-scale competitors.
- CdSe Quantum Dots:Cadmium selenide formulations retain cost advantages in non-European display markets with extended RoHS exemption timelines.
- PbS Quantum Dots:Lead sulfide variants target near-infrared photodetection and solar harvesting layers where bandgap tunability matters more than visible emission purity.
- Carbon Quantum Dots:Biocompatible carbon-core nanomaterials serve bioimaging and sensing applications requiring non-toxic probe alternatives.
InP formulations command the established base in premium display supply chains. The steepest expansion runs through perovskite chemistry as moisture-stability engineering matures.
Technology:
Cost tier stratification separates high-volume solution processing from precision vapor deposition for specialized photonic integration.
- Colloidal Synthesis:Solution-phase nucleation and growth in organic solvents enables batch or continuous-flow manufacturing at scale. This approach dominates display quantum dot production due to compatibility with roll-to-roll coating and inkjet deposition equipment. Surface ligand engineering expertise determines emission efficiency and photostability in finished formulations.
- Epitaxial Growth:Molecular beam epitaxy builds crystalline quantum dot layers with atomic precision for telecommunications lasers and single-photon sources. Foundries in Japan and the United States maintain captive capacity for defense and quantum communication applications where defect tolerance approaches zero. Capital intensity and throughput limitations restrict this method to highest-value photonic devices.
- Lithography:Patterning techniques define quantum dot placement for integrated photonic circuits and quantum computing architectures.
- Chemical Vapor Deposition:Gas-phase precursor delivery enables conformal coating of complex substrates for sensor and photovoltaic applications.
- Atomic Layer Deposition:Self-limiting surface reactions achieve angstrom-scale thickness control for encapsulation and barrier layers.
Colloidal synthesis anchors volume manufacturing across consumer-facing applications. Epitaxial growth claims the highest margin tier in defense and quantum information end uses.
Application:
Application concentration tracks display manufacturing cluster geography, with emerging demand from solar and biomedical segments diversifying beyond panel-centric revenue pools.
- Display Panels:Quantum dot enhancement films and on-chip color converters transform blue LED backlight into narrow-band red and green emission for expanded color gamut. Samsung Electronics and TCL China Star Optoelectronics integrate these layers in QLED televisions manufactured in Tangjeong and Shenzhen. Panel OEMs impose 18-24 month reliability qualification cycles that freeze supplier rosters.
- Photovoltaics:Quantum dot light-harvesting layers enable tandem and multi-junction cell architectures exceeding single-junction efficiency limits. Research programs in the United States and Australia test lead sulfide and perovskite quantum dots for spectral management in agrivoltaic installations. National renewable portfolio standards in multiple jurisdictions accelerate pilot deployment timelines.
- Bioimaging:Near-infrared-emitting probes enable deep-tissue fluorescence microscopy for surgical navigation and diagnostic imaging.
- Lighting:Quantum dot down-conversion improves color rendering index in high-CRI architectural and automotive interior illumination.
- Sensors:Photodetector sensitivity enhancement targets LiDAR, environmental monitoring, and industrial process control applications.
- Security Ink:Covert emission signatures enable anti-counterfeiting features for currency and high-value document protection.
Display panels concentrate the largest revenue base through television and monitor manufacturing scale. Photovoltaics is climbing the fastest as tandem cell architectures exit laboratory demonstration.
End User Industry:
Customer type segmentation reveals procurement pattern divergence between high-volume display integrators and specification-driven research buyers.
- Consumer Electronics:Television, monitor, and mobile device manufacturers specify quantum dot formulations through qualified supplier programs with volume commitments and joint development agreements. Chinese and South Korean brands dominate procurement volume, with emerging Indian display fabs creating new qualification opportunities under PLI scheme incentives.
- Semiconductor Fabricators:Foundries and IDMs integrate quantum dot photonics for on-chip light sources, detectors, and quantum information processing elements. TSMC and Intel pilot silicon-compatible quantum dot processes for co-integrated photonics. Process thermal budget constraints favor atomic layer deposition and selective area growth techniques.
- Research Institutions:Academic and national laboratory buyers prioritize optical performance over manufacturing scalability, sustaining demand for exploratory chemistries.
- Telecommunications:Network equipment vendors source quantum dot lasers and amplifiers for datacenter interconnect and coherent optical transmission.
- Optoelectronics:Specialized component manufacturers serving medical, industrial, and defense markets require customized emission specifications.
Consumer electronics commands procurement volume through display manufacturing scale. Semiconductor fabricators represent the fastest-climbing customer category as quantum photonics integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: European manufacturers prioritize cadmium-free InP formulations under REACH pressure, while Asian producers still blend legacy CdSe supply for deferred-regulation markets. This chemistry split reshapes supplier qualification and procurement geography.
China
MIIT optoelectronics directives and SAMR national standards create dual compliance layers for domestic production and export channels. TCL China Star Optoelectronics anchors manufacturing capacity in Shenzhen, while indium refining concentration in Chinese smelters exposes InP quantum dot supply chains to export quota volatility.
South Korea
Samsung Electronics drives QLED display integration from Tangjeong and Suwon manufacturing clusters, leveraging captive semiconductor fabrication expertise. The country's display OEMs impose 18-24 month reliability testing protocols that freeze supplier rosters and favor reformulation-ready partners.
United States
EPA hazardous substance rules intersect with state-level renewable portfolio standards to accelerate quantum dot photovoltaic applications. Nanosys Inc. maintains cadmium-free chemistry leadership from California, serving consumer electronics brands specifying perovskite and InP alternatives for next-generation panels.
Germany
ECHA substance evaluation protocols and RoHS cadmium exemption expirations force mandatory reformulation deadlines for electronics manufacturers. Merck KGaA competes through vertical control over precursor chemical supply chains from Darmstadt, supplying display OEMs with regulatory pre-certified formulations.
India
PLI scheme incentives for semiconductor and display fabrication create localized quantum dot formulation demand from emerging panel fabs in Gujarat and Tamil Nadu. Domestic production of cadmium-free alternatives remains nascent, opening qualification opportunities for reformulation-capable suppliers.
Quantum Dots Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with competitive advantage migrating from raw material access to precision synthesis control and surface chemistry engineering. The market structure concentrates around display manufacturing geography, with South Korean and Chinese firms internalizing formulation expertise or locking in dedicated external supply. Three archetypes dominate: vertically integrated display OEMs with captive quantum dot programs, independent formulation specialists with multi-chemistry portfolios, and precursor chemical suppliers extending downstream. Dominant competitive moves include long-term supply agreements with volume commitments displacing spot purchasing, and strategic partnerships between equipment suppliers and formulation houses to support divergent manufacturing footprints.
Among South Korea-based integrated electronics groups, Samsung Electronics Co., Ltd. exemplifies the captive-fabrication archetype, while LG Display Co., Ltd. occupies a parallel position in the display OEM tier. Within the independent specialist tier, Nanosys Inc. and Nanoco Group plc represent reformulation-ready suppliers capable of multi-chemistry portfolios. Merck KGaA anchors the precursor-supplier archetype from its German base. These named entities collectively illustrate how competitive positioning fragments across vertical integration strategies, with chemistry transition timelines and regulatory pre-certification serving as the primary qualification filters.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Nanosys Inc. |
| LG Display Co., Ltd. |
| BOE Technology Group Co., Ltd. |
| Nanoco Group plc |
| AUO Corporation |
| Merck KGaA |
| TCL China Star Optoelectronics Technology Co., Ltd. |
| Shoei Chemical, Inc. |
| Others |
Cost & Logistics Intelligence
Continuous-flow reactor scale economies in South Korean and Chinese manufacturing clusters compress unit economics for cadmium-free quantum dot formulations while simultaneously concentrating supply-side pricing power among qualified suppliers. This scale concentration elevates price floors for InP and perovskite chemistries facing REACH-mandated reformulation deadlines, locking out batch-process competitors from display OEM procurement rosters.
Pricing Analysis
Long-term offtake agreements with volume commitments displace spot purchasing for high-volume QLED television programs, with Samsung Electronics and TCL China Star Optoelectronics locking in multi-year supply contracts. Price differentiation separates REACH pre-certified formulations from post-hoc compliance documentation, with European-bound panels commanding premium tiers. Cost compression in standard-grade InP supply is intensifying because Chinese smelter indium concentration enables backward-integrated producers to undercut formulation specialists. Research institutions and emerging Indian display fabs exhibit highest price sensitivity, while South Korean panel OEMs prioritize reliability qualification over unit cost.
Supply Chain Analysis
China and South Korea anchor quantum dot formulation capacity, with Nanosys Inc. in the United States maintaining specialized cadmium-free production for premium display brands. Indium phosphide precursors draw from Chinese smelter concentration, while surface ligand engineering expertise clusters in Darmstadt and Silicon Valley. Single-source vulnerability in indium refining exposes InP manufacturers to export quota volatility from Chinese regulatory authorities. Distribution runs through qualified supplier programs directly to Tangjeong and Shenzhen panel fabrication clusters, bypassing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quantum dot formulation services including reliability testing support and regulatory pre-certification consulting are expanding faster than base material supply, creating attach-rate opportunities that exceed hardware margin profiles. This service-layer expansion justifies repositioning around chemistry-transition advisory and OEM qualification acceleration.
For Market Incumbents: Shield formulation margins by securing long-term indium offtake agreements before Chinese export quota tightening accelerates. Deepen backward integration into colloidal synthesis automation equipment to reduce batch-to-batch optical variability that triggers OEM rejection. Perovskite moisture-stability limitations and PhD-level colloidal chemist scarcity constitute dual threats requiring captive R&D investment in encapsulation chemistry.
For New Entrants and Emerging Players: Technical qualification support for Indian PLI-scheme display fabs represents an underserved service layer where incumbents under-serve due to geographic focus on East Asian manufacturing clusters. Agrivoltaic spectral management applications in Australia and the United States offer penetrable white-space demand outside display-centric procurement. Pursue joint development agreements with emerging panel OEMs rather than direct qualification against frozen South Korean supplier rosters.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors reformulation-ready specialists with multi-chemistry portfolios over legacy CdSe-dependent suppliers facing regulatory sunset. Long-term viability across the analysis window hinges on regulatory pre-certification capabilities and surface ligand engineering patent positions. Watch ECHA authorization timeline acceleration as the inflection indicator for chemistry transition speed and stranded asset risk in legacy formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Samsung Electronics locks in indium phosphide volume commitments through 2030 qualification cycles. |
| Backward Integration | Merck KGaA extends precursor chemical control into finished quantum dot formulation supply. |
| Regulatory Pre-certification | ECHA REACH compliance documentation accelerates OEM procurement decisions for European-bound panels. |
| Joint Development Agreement | Equipment suppliers partner with formulation houses to support divergent vapor-deposition and solution-processed routes. |
| Capacity Expansion | TCL China Star Optoelectronics scales Shenzhen manufacturing to capture Indian PLI-scheme display demand. |
Research Approach
Desk research of ECHA substance evaluation protocols, MIIT optoelectronics directives, and SEC filings from display OEMs preceded structured interviews with colloidal synthesis R&D directors, quantum dot procurement managers at panel manufacturers, and regulatory affairs leads at formulation suppliers. Secondary validation drew from customs trade data for indium phosphide precursors, patent filings in surface ligand engineering, and SAMR national standards documentation. Bottom-up capacity estimates from continuous-flow reactor installations were triangulated against top-down display panel production forecasts.
Variance decomposition across chemistry type, application segment, and manufacturing geography anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include product chemistry, synthesis technology, display versus photovoltaic application, and end-user industry procurement pattern. CAGRs were derived from installed capacity buildout trajectories and OEM qualification pipeline visibility. Indium price volatility assumptions and RoHS exemption expiration schedules constituted industry-specific forecast inputs.
Underlying assumptions cover sustained REACH cadmium restriction enforcement and continuous-flow reactor yield improvements, with deviation risk concentrated in perovskite stability breakthroughs and Chinese indium export policy shifts. Recalibration cycles align with ECHA authorization timeline updates and display OEM reliability test completion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
Smart Compact Projectors Market
Optoelectronics
Infrared Emitter and Receiver Market
Optoelectronics
Optical Pulse Sensor Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
2-Ethyl-3,4-Ethylenedioxythiophene Market
Optoelectronics
Laser Projection Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
Thermophotovoltaics Market
Optoelectronics
Gaas Wafer and Epiwafer Market
Optoelectronics
Green Laser Diode Market
Optoelectronics
Light Projector Market