
 Thermophotovoltaics Market | 2026-2036
Thermophotovoltaics Market Size, Share, and Industry Trends Forecast 2026-2036
Thermophotovoltaics Market Analytics
The premium emitter-filter stack is rebalancing away from commodity bulk silicon substrates as efficiency thresholds harden. Microlink Devices, Inc. leverages epitaxial lift-off processes to dominate high-performance cell architectures. Antora Energy anchors utility-scale thermal battery integration with embedded TPV conversion. General Electric sustains aerospace and defense channel control through Spectrolab, Inc., which leads concentrated photovoltaic heritage into thermal spectrum applications.
Thermophotovoltaics converts infrared radiation from heated emitters into electricity through low-bandgap semiconductor junctions, typically operating between 1000°C and 1500°C with gallium antimonide or indium gallium arsenide absorbers matched to selective emitter spectra. The technology serves industrial waste heat recovery and portable power generation where thermal sources outrank photon flux. Bulk Semiconductor technology occupies mature defense and space niches with proven reliability but plateauing efficiency curves. Nanostructured architectures compete for industrial adoption through photonic crystal emitters that sharpen spectral selectivity. Hybrid Systems extend into grid-storage coupling where thermal batteries bridge dispatch gaps.
EPA emissions standards for industrial heat sources shape waste heat recovery deployment timelines in US manufacturing corridors. REACH compliance in Europe constrains gallium and antimony supply chains for emitter fabrication. ISO 9001 and IEC 61215 certification requirements filter market access for commercial and utility entrants. Stakeholders must monitor emitter material substitution pathways and thermal storage pairing economics as efficiency benchmarks climb.
Market Dynamics
The transition from bulk semiconductor architectures to nanostructured emitter-filter stacks is compressing technology cycles and rewiring competitive advantage around spectral engineering capabilities rather than manufacturing scale.
Growth Catalysts
- Industrial Emissions Mandates:Germany's Federal Immission Control Act (BImSchG) forces manufacturers to capture exhaust heat from steel and cement operations, creating captive demand for on-site TPV conversion systems.
- Photonic Crystal Fabrication:Advances in silicon-compatible nanolithography are lowering emitter production costs while sharpening wavelength selectivity, opening industrial adoption pathways beyond defense heritage markets.
- Waste Heat Density:Glass and ceramics manufacturing corridors in the Ruhr region concentrate thermal streams above 1000°C, matching TPV operating windows without supplementary fuel input.
Market Restraints
- Gallium-Antimony Supply Concentration:China controls 80% of global gallium refining capacity, exposing cell fabricators to export restriction risks and price volatility in low-bandgap absorber materials.
- Epitaxial Lift-Off Yield Limits:Substrate reuse rates in thin-film GaSb processing plateau below 90%, constraining throughput scaling for cost-sensitive industrial buyers.
- Mechanical Vibration Tolerance:Micron-scale emitter-cavity alignment degrades under industrial equipment vibration, limiting deployment to stationary heat sources and excluding mobile or heavy-machinery applications.
Strategic Opportunities
- India PLI Scheme Extension:The country's production-linked incentive framework for solar manufacturing is expanding to cover thermal energy harvesting, inviting TPV module assembly investments for industrial park deployments.
- Thermal Battery Hybridization:Pairing TPV conversion with latent heat storage systems enables dispatchable power output from intermittent industrial heat streams, addressing grid integration barriers.
- Carbon Border Adjustment Mechanism:The EU CBAM creates compliance value for embedded emission reductions, positioning waste heat recovery TPV as a qualifying technology for import-exposed steel and aluminum producers.
Industry Challenges
- Multiphysics Simulation Talent:The intersection of thermal radiation, semiconductor physics, and photonic design requires specialists fluent in COMSOL and Lumerical platforms, with European universities producing fewer than 200 relevant graduates annually.
- IEC 61215 Adaptation Timeline:Photovoltaic certification standards lack thermal cycling protocols matched to TPV operating temperatures, forcing manufacturers to fund bespoke testing regimes and delaying commercial insurance coverage.
- Emitter-Filter Stack Integration:Achieving sub-micron gap tolerance between tungsten photonic crystals and cold-side filters at 1500°C demands cleanroom assembly protocols alien to conventional solar module fabs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermophotovoltaics Market |
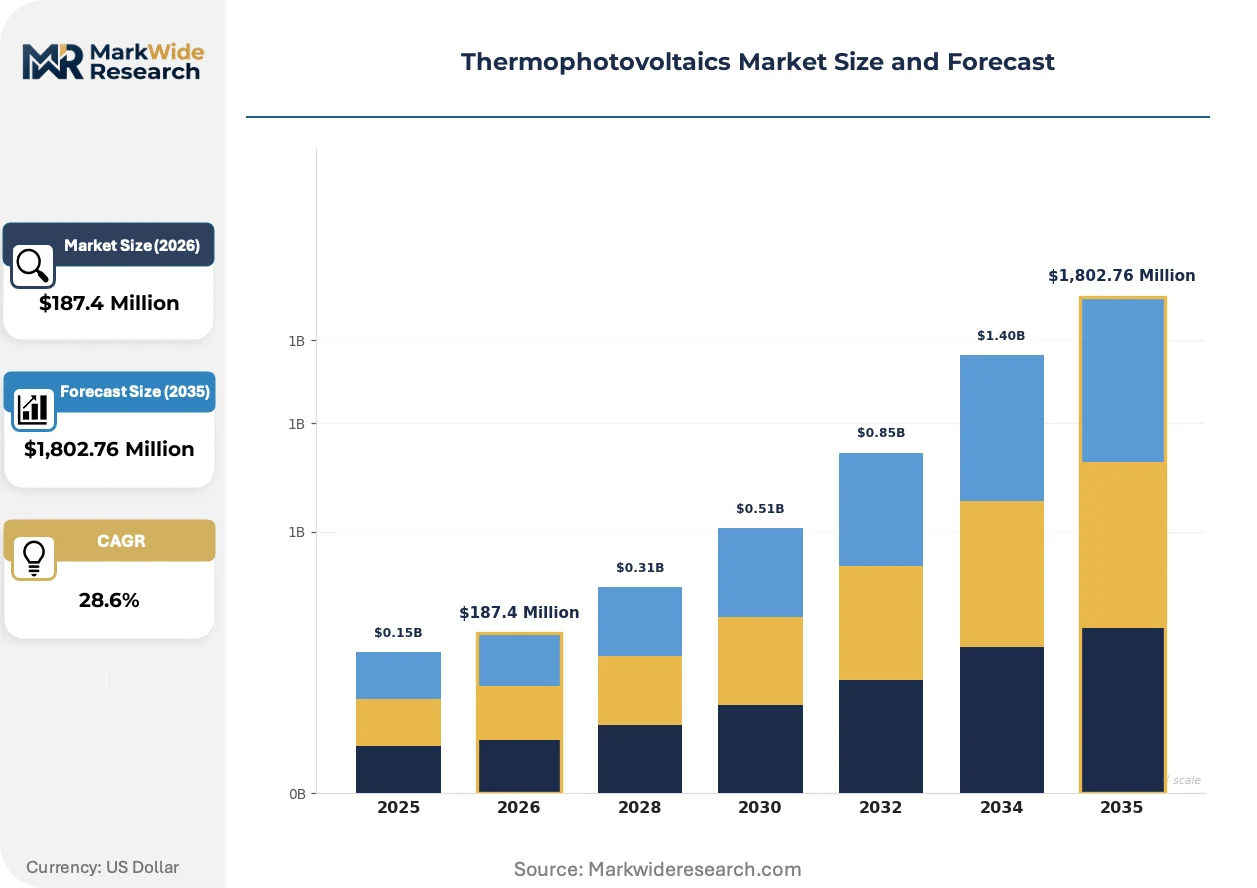
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Substrate, Absorber, Emitter, Optical Filter Technology: Bulk Semiconductor, Quantum Dot, Nanostructured, Hybrid Systems End User: Utilities, Industrial, Residential, Commercial Application: Power Generation, Heating, Cooling, Waste Heat Recovery |
| Companies Covered | Microlink Devices, Inc., TPV Technology Inc., Antora Energy, General Electric, Schott AG, JX Crystals Inc., General Atomics, Curtiss-Wright Corporation, Spectrolab, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermophotovoltaics Market Evolving Landscape
Active spectral control is displacing passive thermal management as the central design priority, with engineering resources shifting toward emitter engineering and away from conventional cell optimization.
Monolithic tungsten-silica photonic crystal emitters are unifying wavelength selectivity with structural stability at 1400°C operating temperatures. Steel producers in Germany's Duisburg corridor are piloting these architectures for blast furnace off-gas recovery. The technology is unifying previously separate thermal and optical design functions into single-material solutions, collapsing subsystem count and assembly complexity.
The EU F-Gas Regulation is phasing down fluorinated greenhouse gases used in alternative heat-to-power conversion systems, indirectly elevating TPV's competitive position in industrial decarbonization roadmaps. Manufacturing facilities subject to the EU Emissions Trading System are accelerating waste heat recovery project timelines to capture carbon credit value before allowance price escalations. Process heat-intensive segments in Belgium and the Netherlands are prioritizing TPV over organic Rankine cycle alternatives due to maintenance simplicity and absence of working fluid leakage risks.
Steelmakers are consolidating equipment procurement decisions at the corporate level rather than delegating to individual plant engineering teams, compressing vendor qualification cycles and favoring suppliers with multi-site deployment track records. This concentration is displacing fragmented local integrator networks that historically mediated technology adoption. The shift is most visible in Germany, where ThyssenKrupp and Salzgitter AG have centralized energy recovery technology selection under dedicated decarbonization procurement functions.
Thermophotovoltaics Market Segmentation
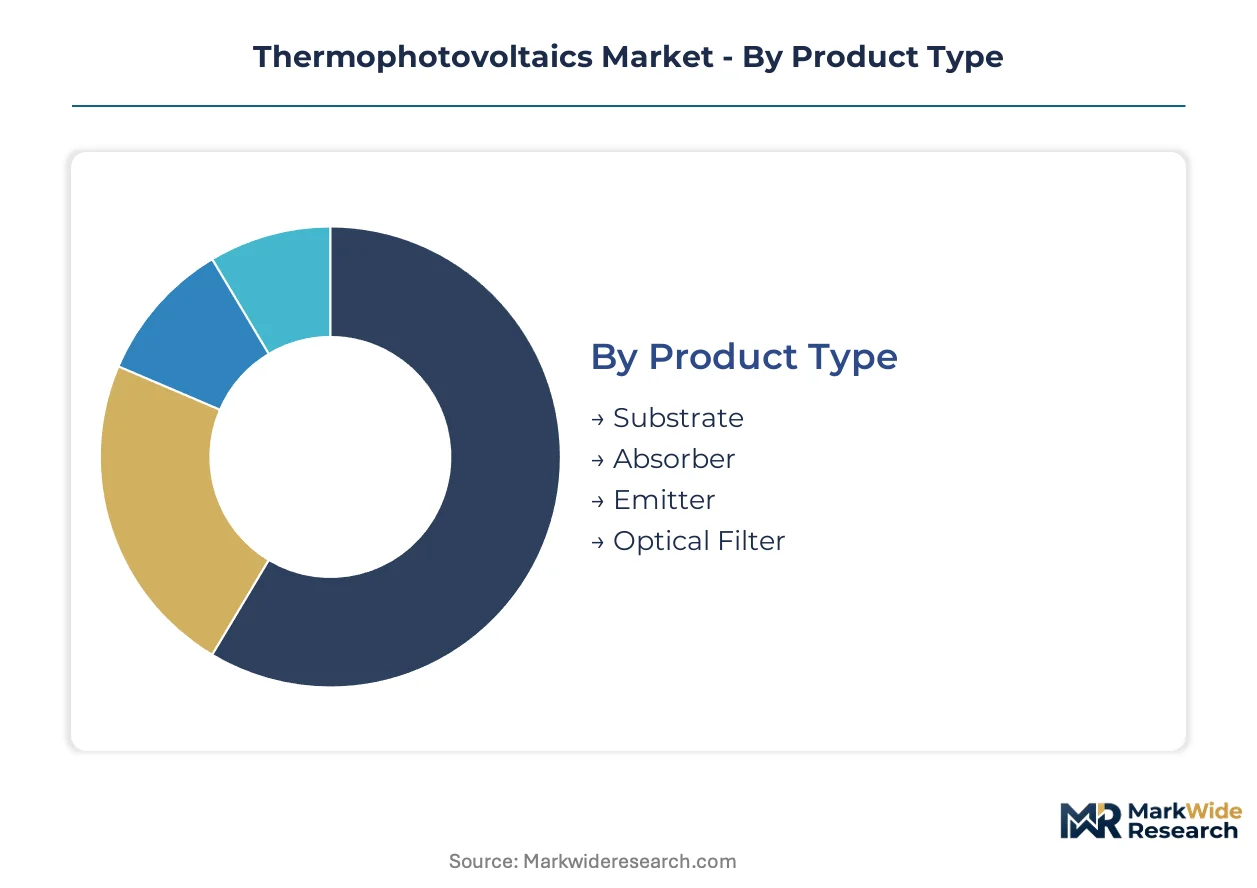
TPV market segmentation reveals distinct certification burdens across product layers, with emitter-filter stacks demanding IEC 61215 thermal cycling protocols while substrate materials navigate REACH gallium-antimony compliance. Technology choices determine whether manufacturers pursue ISO 9001 quality systems or bespoke aerospace heritage qualifications.
Product Type:
ISO 9001 certification governs substrate and optical filter manufacturing, while IEC 61215 thermal cycling protocols apply specifically to absorber and emitter stacks exposed to sustained high-temperature operation.
- Substrate:Silicon and sapphire wafers provide mechanical foundation for epitaxial GaSb growth, with Germany's Fraunhofer Institute clusters driving demand for 6-inch diameter formats in blast furnace off-gas recovery pilots. REACH compliance constrains gallium sourcing for III-V buffer layers, forcing dual-supplier qualification.
- Absorber:Gallium antimonide and indium gallium arsenide junctions convert infrared radiation at bandgaps between 0.5 eV and 0.7 eV, matching selective emitter spectra. German steelmakers in the Ruhr region specify absorber thickness tolerances below 500 nanometers for waste heat density above 1000°C.
- Emitter:Tungsten photonic crystals and rare-earth oxide coatings operate between 1000°C and 1500°C, requiring cleanroom assembly protocols alien to conventional solar fabs.
- Optical Filter:Dielectric stacks and plasma-enhanced chemical vapor deposition coatings recycle sub-bandgap photons back to the thermal source, improving system efficiency.
Substrate sits at the top of the volume ranking, with absorber climbing the fastest.
Technology:
Cost tiers separate mature defense-qualified architectures from emerging nanostructured platforms competing for industrial adoption through spectral engineering premiums.
- Bulk Semiconductor:Established GaSb and InGaAs cell architectures dominate aerospace and defense channels with proven reliability but plateauing efficiency curves near 30% spectral conversion. Antora Energy and utility-scale thermal battery integrators bypass this tier for higher-temperature nanostructured alternatives.
- Quantum Dot:Colloidal lead sulfide and indium arsenide nanocrystals enable tunable absorption edges through size control, with research demand concentrating at MIT and ETH Zurich laboratories exploring sub-1000°C emitter matching.
- Nanostructured:Silicon-compatible photonic crystal fabrication sharpens wavelength selectivity while lowering production costs, opening industrial pathways beyond heritage markets.
- Hybrid Systems:TPV conversion embedded within latent heat thermal batteries bridges dispatch gaps for intermittent industrial heat streams.
Bulk semiconductor commands the revenue base, though nanostructured architectures are gaining share fastest.
End User:
Application maturity varies sharply across customer types, with industrial facilities accepting 5-year payback periods while utilities demand 20-year operational warranties.
- Utilities:Grid-scale thermal battery hybridization requires dispatchable output guarantees and 25-year degradation warranties, with Antora Energy anchoring pilot deployments.
- Industrial:Steel, cement, and glass manufacturers under Germany's BImSchG emissions mandates drive captive demand for on-site waste heat recovery.
- Residential:Micro-cogeneration applications remain pre-commercial due to emitter-cavity alignment sensitivity.
- Commercial:Data center waste heat recovery pilots in Frankfurt and Amsterdam test TPV against organic Rankine alternatives.
Industrial end users sit at the top of the volume ranking, with utilities climbing the fastest.
Application:
Customer procurement patterns diverge between thermal-first applications requiring mechanical integration expertise and electricity-first applications prioritizing power conditioning compatibility.
- Power Generation:Standalone TPV systems convert dedicated fuel input to electricity for remote military and aerospace missions, with Spectrolab heritage dominating concentrated photovoltaic channel extensions.
- Heating:Cogeneration configurations prioritize thermal output with parasitic electricity production, finding niche demand in off-grid industrial process heat.
- Cooling:Thermally driven refrigeration through TPV-powered vapor compression remains experimental, with laboratory demonstrations at NREL and Fraunhofer ISE.
- Waste Heat Recovery:Exhaust stream conversion from 1000°C-plus industrial sources represents the primary commercialization pathway, with Germany's Federal Immission Control Act forcing deployment timelines.
Waste heat recovery sits at the top of the volume ranking, with power generation climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates industrial TPV deployment through emissions mandates, while the United States channels investment through defense heritage programs and emerging thermal battery platforms. National regulatory frameworks and industrial cluster density determine adoption velocity across key markets.
Germany
Steel and cement manufacturers under the Federal Immission Control Act (BImSchG) drive captive demand for waste heat recovery systems. The country's national emissions regulator enforces exhaust capture requirements that accelerate TPV procurement timelines. The Ruhr region's glass and ceramics manufacturing corridors concentrate thermal streams above 1000°C, enabling pilot deployments without supplementary fuel input.
United States
Defense aerospace channels and utility-scale thermal battery integration anchor demand across dual application streams. EPA emissions standards for industrial heat sources shape waste heat recovery deployment timelines in manufacturing corridors. The Department of Energy's national laboratory network supports emitter-filter stack development through Sandia and NREL facilities in New Mexico and Colorado.
China
Gallium refining concentration creates supply-side leverage over global low-bandgap absorber material flows. The Ministry of Ecology and Environment (MEE) monitors industrial emissions intensity, creating indirect pressure for heat recovery technology adoption. Yangtze River Delta manufacturing clusters evaluate TPV against organic Rankine alternatives for high-temperature process streams.
India
Production-linked incentive frameworks for solar manufacturing are expanding to cover thermal energy harvesting applications. The Central Electricity Authority (CEA) oversees grid integration standards that will govern dispatchable power output from thermal battery hybrids. Gujarat and Maharashtra industrial parks host pilot module assembly investments targeting captive waste heat recovery.
Japan
Precision manufacturing heritage and materials science capabilities support photonic crystal emitter fabrication development. METI directs industrial decarbonization funding toward high-efficiency heat-to-power conversion technologies. Kansai region research institutes collaborate with steelmakers on blast furnace off-gas recovery system design.
Thermophotovoltaics Market Competitive Landscape
Top-tier vendors anchor defense and aerospace heritage channels, while mid-scale specialists compete for industrial adoption through spectral engineering capabilities. The vendor base stratifies across epitaxial lift-off process holders, thermal battery integrators, and photonic crystal fabrication specialists. Three archetypes dominate: heritage defense contractors with proven reliability records, venture-backed thermal storage hybridizers, and nanofabrication specialists leveraging silicon-compatible lithography. Competitive moves concentrate on backward integration into emitter material supply and strategic partnerships with industrial heat source operators.
Among heritage defense contractors, General Electric and Spectrolab, Inc. occupy positions exemplifying concentrated photovoltaic channel extension into thermal spectrum applications. Within the thermal battery hybridization tier, Antora Energy anchors utility-scale deployment archetypes. These three entities represent distinct competitive vectors: aerospace heritage reliability, utility-scale storage integration, and emerging industrial adoption pathways.
| Leading Market Players |
|---|
| Microlink Devices, Inc. |
| TPV Technology Inc. |
| Antora Energy |
| General Electric |
| Schott AG |
| JX Crystals Inc. |
| General Atomics |
| Curtiss-Wright Corporation |
| Spectrolab, Inc. |
| Others |
Value Network & Pricing Analysis
Gallium metal spot prices on the Shanghai Metals Market cascade through epitaxial wafer costs into three-tier pricing stratification across defense heritage, industrial adoption, and thermal battery integration tiers. China's export licensing regime for refined gallium tightens cost pass-through mechanics for cell fabricators serving German steelmakers under BImSchG compliance deadlines.
Pricing Analysis
Capacity additions in India's Gujarat industrial corridor are reshaping price floors for module assembly operations targeting captive waste heat recovery. Pricing stratifies across premium, standard, and economy tiers keyed to IEC 61215 thermal cycling certification, emitter-filter stack spectral selectivity, and volume procurement commitments from multi-site steel producers. Cost compression in the standard tier intensifies as epitaxial lift-off yield improvements narrow the efficiency gap with nanostructured alternatives. Industrial end users exhibit highest price sensitivity due to 5-year payback thresholds, while utilities accepting 25-year degradation warranties absorb premium positioning.
Supply Chain Analysis
Single-source vulnerability sits with China's gallium refining concentration, which feeds 80% of global low-bandgap absorber material flows for GaSb and InGaAs junction fabrication. Raw material dependencies center on tungsten photonic crystal substrates, rare-earth oxide coatings, and sapphire wafers sourced from Japan, Germany, and the United States. Tariff exposure on III-V compound semiconductor imports threatens cost structures for European cell fabricators. Distribution runs through direct OEM partnerships with steel and cement producers rather than conventional solar channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in thermophotovoltaics rests on photonic crystal fabrication cost-down curves and the premium-tier shift toward nanostructured emitter-filter stacks displacing bulk semiconductor heritage architectures.
For Market Incumbents: Deepen backward integration into tungsten photonic crystal substrate supply through partnerships with German precision metallurgy suppliers, insulating against REACH gallium-antimony compliance disruptions. Lock multi-site deployment track records with ThyssenKrupp and Salzgitter AG procurement functions before centralized vendor qualification cycles close to new entrants. Anchor defense channel control through Spectrolab heritage while funding IEC 61215 thermal cycling protocol adaptation to accelerate commercial insurance coverage. For New Entrants and Emerging Players: Digital-channel routes through industrial decarbonization software platforms offer low-friction customer acquisition paths for thermal battery hybridization pilots. Target data center waste heat recovery in Frankfurt and Amsterdam as the most penetrable commercial segment, where maintenance simplicity advantages over organic Rankine cycles shorten sales cycles. Pursue direct EPC contractor partnerships rather than fragmented local integrator networks displaced by corporate-level procurement consolidation. For Investors and Strategic Acquirers: Asymmetric upside sits with nanofabrication specialists holding silicon-compatible photonic crystal lithography capabilities and cleanroom assembly protocols alien to conventional solar fabs. Long-term viability over the next decade hinges on spectral engineering talent pipelines and thermal storage pairing economics rather than manufacturing scale alone. Watch for emitter material substitution pathways—specifically silicon-germanium alloys or quantum dot absorbers—as the signal for technology cycle compression and portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Crystal Fabrication Scale-Up | Silicon-compatible nanolithography lowers emitter production costs while sharpening wavelength selectivity for industrial adoption. |
| Thermal Battery Hybridization | Pairing TPV conversion with latent heat storage enables dispatchable power output from intermittent industrial heat streams. |
| Backward Integration into Tungsten Supply | Captive substrate supply insulates against photonic crystal material cost volatility and REACH compliance disruptions. |
| IEC 61215 Thermal Cycling Certification | Bespoke testing regimes for high-temperature operation unlock commercial insurance coverage and utility procurement eligibility. |
| Multi-Site Steel Producer Partnerships | Corporate-level procurement consolidation at ThyssenKrupp and Salzgitter AG compresses vendor qualification cycles and displaces fragmented integrators. |
Research Methodology
Direct dialogue with TPV cell fabrication engineers, steel plant energy recovery managers, photonic crystal research leads at Fraunhofer Institute clusters, and thermal battery integration specialists anchored qualitative grounding. Secondary validation drew from EPA emissions filings, BImSchG enforcement records, ECHA REACH substance restrictions, IEC standards documentation, and customs trade data for gallium and antimony flows. Bottom-up unit economics modeling triangulated against top-down market sizing across emitter-filter stack, absorber, and substrate product layers.
Segment-level outputs across the analysis window reflect technology archetype splits between bulk semiconductor, nanostructured, and hybrid system architectures, crossed with end-user categories spanning utilities, industrial facilities, and defense channels. CAGRs derived from deployment timeline acceleration under Germany's Federal Immission Control Act, India's PLI scheme extension for thermal energy harvesting, and EU CBAM carbon border adjustment compliance value for embedded emission reductions. Forecast inputs incorporated epitaxial lift-off yield trajectories, photonic crystal fabrication cost curves, and thermal storage pairing economics.
Export restriction escalations on gallium refining, IEC 61215 protocol adaptation delays, and mechanical vibration tolerance breakthroughs are the dominant revision risks that could compress or extend commercialization timelines. Forecasts reflect documented assumptions on spectral conversion efficiency thresholds, cleanroom assembly protocol transferability, and industrial procurement centralization velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Photoluminescent Film Market
Optoelectronics
Smart Compact Projectors Market
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
Gunn Diode Market
Optoelectronics
Laser Diode Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Europe Wigig Market
Optoelectronics
China Optoelectronics Market
Optoelectronics
Optocoupler IC Market
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
3D Projector Market
Optoelectronics
Integrated Circuit Optocouplers Market
Optoelectronics
Optical Pulse Sensor Market
Optoelectronics
Quantum Dot Lasers Market