
 Europe Optoelectronics Market | 2026-2036
Europe Optoelectronics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Optoelectronics Market Foresight
Germany's photonics manufacturing corridor is narrowing the capability gap with Asian supply bases for high-power laser diodes and precision optical sensors. Infineon Technologies AG leverages its Dresden fab complex to sustain captive production of gallium-nitride optoelectronic components for automotive LiDAR modules. Osram Licht AG anchors European LED supply through its Regensburg epitaxy operations, while STMicroelectronics competes in time-of-flight sensor arrays for smartphone and industrial automation customers.
Optoelectronics encompasses devices that source, detect, and control light across the ultraviolet, visible, and infrared spectra, typically fabricated from III-V compound semiconductors such as gallium arsenide, indium phosphide, and gallium nitride on silicon or sapphire substrates, with critical parameters including quantum efficiency, spectral linewidth, and thermal stability determining performance in precision applications. The primary commercial purpose spans illumination, optical data transmission, image capture, and environmental sensing across industrial, consumer, automotive, and healthcare systems. LED product lines retain the largest revenue share but face margin compression as commoditization advances in general lighting, whereas laser diode segments command premium pricing in medical devices and telecommunications where beam coherence and power density requirements exclude lower-tier suppliers. Photodetector demand concentrates in automotive safety systems and industrial machine vision where silicon photomultipliers and avalanche photodiodes replace legacy sensor technologies.
CE marking under the EU Medical Device Regulation and RoHS substance restrictions shape product design cycles and material selection for optoelectronic components sold into European medical and consumer channels. The EU AI Act's risk-classification framework for automated decision systems is creating compliance obligations for optoelectronic sensing modules deployed in autonomous vehicle perception stacks. REACH chemical registration requirements constrain epoxy and phosphor chemistries used in LED packaging, pushing manufacturers toward alternative encapsulant formulations. Stakeholders must monitor how the F-Gas Regulation's phase-down of fluorinated greenhouse gases affects cooling systems for high-power laser installations and datacenter optical interconnects.
Market Dynamics
The EU Green Deal's energy-efficiency mandates are forcing rapid recalibration of LED and laser diode procurement specifications across European industrial and automotive supply chains, compressing legacy product lifecycles while elevating gallium-nitride and silicon-carbide component standards.
Growth Catalysts
- Automotive LiDAR mandates:Advanced driver-assistance system requirements from Germany's KBA and similar national transport authorities are pulling precision optical sensors into European OEM supply chains at accelerating volumes.
- CE marking under EU MDR:The Medical Device Regulation's tightened conformity assessment procedures are filtering out lower-tier LED and photodetector suppliers from European medical imaging channels, concentrating demand on qualified manufacturers.
- Industrial photonics clusters:Germany's Jena-Munich corridor is capturing disproportionate demand from semiconductor lithography equipment makers seeking proximity to precision optics fabrication capabilities.
Market Restraints
- Substrate supply concentration:High-purity sapphire and silicon-carbide wafer supply concentrates in Asian refining operations, exposing European epitaxy houses to input cost volatility and logistics disruption.
- REACH chemical constraints:ECHA registration requirements for epoxy and phosphor chemistries used in LED packaging are extending material qualification timelines and constraining formulation flexibility.
- Technical wavelength limitations:Indium-phosphide-based laser diodes face power-density ceilings in mid-infrared applications that silicon photonics alternatives are beginning to erode in datacenter interconnects.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Finland's industrial automation sectors show below-average penetration of time-of-flight sensor arrays compared to German benchmarks, presenting expansion white space for qualified suppliers.
- F-Gas Regulation phase-down:The EU's fluorinated greenhouse gas restrictions are creating replacement demand for thermoelectric cooling systems in high-power laser installations and hyperscale datacenter optical interconnects.
- EU AI Act compliance services:The risk-classification framework for automated decision systems is generating adjacent revenue streams for optoelectronic module vendors offering certified perception-stack components with documented algorithmic transparency.
Industry Challenges
- Compound semiconductor talent scarcity:European universities produce insufficient gallium-nitride and indium-phosphide process engineers to staff expansion at Dresden, Regensburg, and Crolles fabrication complexes.
- Multi-standard certification complexity:Concurrent CE marking, RoHS substance compliance, and REACH chemical registration create overlapping documentation burdens that extend product launch timelines by 8-14 months for cross-border component sales.
- Legacy system integration friction:Machine vision retrofits in established European automotive assembly plants require costly optical interface adaptation to marry new photodetector outputs with decades-old programmable logic controller architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Optoelectronics Market |
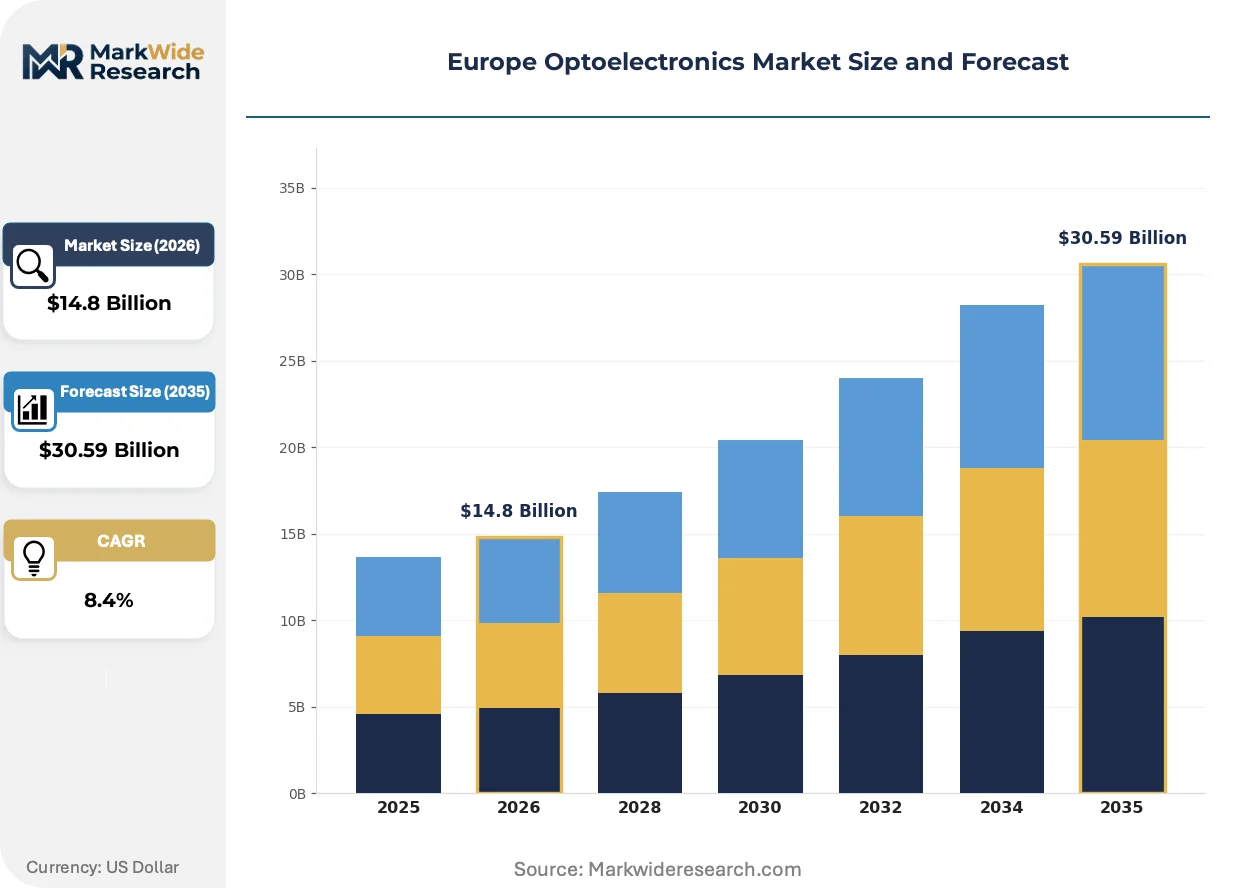
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Laser Diode, Photodetector, Optical Fiber End Use Industry: Consumer Electronics, Telecommunications, Automotive, Medical Devices Technology: Analog Optoelectronics, Digital Optoelectronics, Sensor Technology, Display Technology Application: Lighting, Imaging, Data Communication, Sensing |
| Companies Covered | Infineon Technologies AG, NXP Semiconductors, Osram Licht AG, Panasonic Corporation, Texas Instruments Inc., Osram Opto Semiconductors, STMicroelectronics, Mitsubishi Electric, Koninklijke Philips NV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Optoelectronics Market Shifts & Advancements
Solid-state lighting architectures are converging with precision sensing modalities, creating hybrid optoelectronic platforms that simultaneously illuminate, detect, and communicate across industrial and mobility applications.
Silicon photonics is digitizing optical interconnect density in European datacenter and telecommunications infrastructure. Co-packaged optics using CMOS-compatible waveguides are displacing discrete transceiver assemblies. Deutsche Telekom and similar carriers are accelerating deployment timelines for coherent optical engines, compressing procurement cycles for traditional indium-phosphide discrete components.
REACH substance restrictions are reshaping material selection across LED packaging supply chains. ECHA's expanded candidate list for Substances of Very High Concern is forcing reformulation of epoxy encapsulants and phosphor suspensions. German and Dutch lighting manufacturers are responding with accelerated qualification of bio-based and halogen-free alternatives ahead of 2027 authorization deadlines.
Automotive tier-one suppliers are consolidating optoelectronic vendor relationships around vertically integrated module providers capable of delivering camera-LiDAR-radar fusion units. Continental and Bosch procurement organizations are reducing qualified supplier lists from 12-15 discrete component vendors to 3-4 subsystem integrators. This concentration is most visible in Stuttgart and Munich engineering centers, where specification authority has shifted from OEM lighting divisions to centralized autonomous driving divisions.
Europe Optoelectronics Market Segmentation
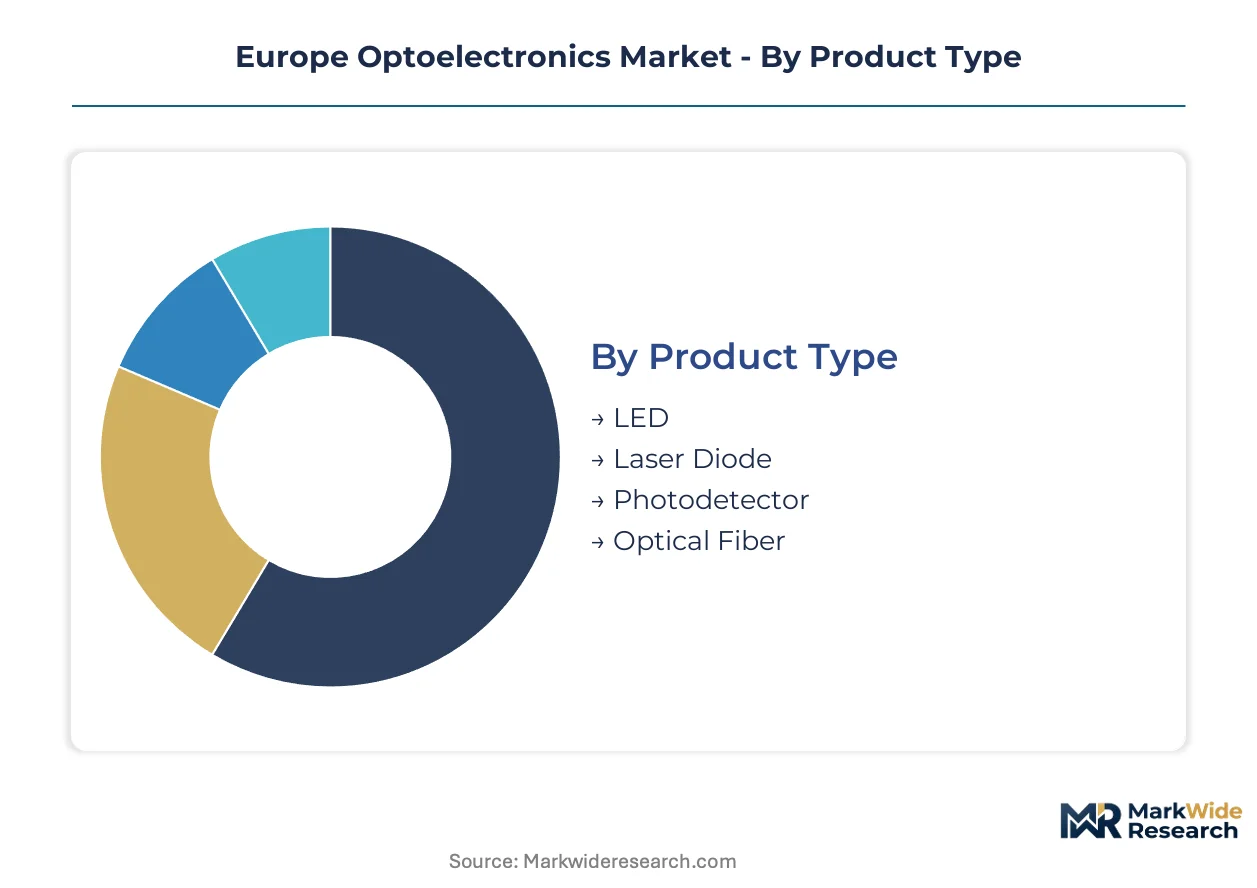
Optoelectronics procurement cycles vary dramatically across device categories, with consumer-facing components refreshing every 12-18 months while industrial and medical systems demand decade-long supply commitments. Understanding these velocity mismatches helps suppliers align inventory strategies with actual consumption patterns across European industrial clusters.
Product Type:
LED modules turn inventory fastest through general lighting channels, whereas laser diodes and specialty photodetectors sit on longer automotive and medical qualification timelines.
- LED:Solid-state emitters fabricated from gallium-nitride on sapphire or silicon substrates dominate general illumination and display backlighting. German municipalities and Dutch greenhouse operators are replacing legacy sodium vapor installations under EU Green Deal retrofit mandates, compressing procurement cycles for mid-power packages.
- Laser Diode:Coherent light sources spanning visible through infrared wavelengths, constructed from indium-phosphide or gallium-arsenide heterostructures. Stuttgart automotive LiDAR engineering centers and Jena medical device manufacturers are pulling edge-emitting and vertical-cavity designs through multi-year qualification pipelines.
- Photodetector:Silicon photomultipliers and avalanche photodiodes convert optical signals to electrical output across safety and measurement systems.
- Optical Fiber:Doped silica waveguides enable high-bandwidth data transmission across telecommunications backbone and sensing networks.
LED anchors the volume base while laser diode gains share at the steepest rate.
End Use Industry:
Automotive and medical segments command margin premiums through certification burdens, whereas consumer electronics and telecommunications compete on scale economies.
- Consumer Electronics:Smartphone time-of-flight modules and wearable optical sensors require sub-millimeter form factors and extreme power efficiency. French and Italian mobile OEMs are consolidating vendor lists around integrated camera-LiDAR fusion suppliers.
- Telecommunications:Coherent optical transceivers and datacenter interconnects demand precision wavelength stability across temperature extremes. Deutsche Telekom infrastructure deployments are accelerating silicon photonics displacement of discrete indium-phosphide assemblies.
- Automotive:Advanced driver-assistance perception stacks combine multiple optical modalities under KBA and similar national type-approval frameworks.
- Medical Devices:Imaging and diagnostic equipment requires CE marking under EU MDR with extended material traceability documentation.
Consumer electronics generates the highest unit volumes while automotive commands the steepest price escalation through subsystem integration requirements.
Technology:
Analog architectures retain dominance in precision measurement applications, but digital integration is compressing component counts in consumer and communications platforms.
- Analog Optoelectronics:Continuous-signal photonic devices preserve linearity for scientific instrumentation and medical imaging. Swiss and Austrian precision equipment manufacturers specify these architectures for fluorescence microscopy and spectroscopy systems.
- Digital Optoelectronics:Discrete-signal processing enables direct CMOS integration and software-defined functionality. Nordic fabless design houses are leveraging these capabilities for industrial machine vision edge devices.
- Sensor Technology:Environmental and proximity detection modules combine emitter and detector in packaged assemblies.
- Display Technology:Micro-LED and OLED microdisplay architectures target augmented reality and automotive head-up applications.
Analog optoelectronics holds the revenue base while sensor technology climbs the fastest through automotive safety mandate proliferation.
Application:
Lighting applications commoditize most aggressively, whereas sensing and imaging retain differentiation through software integration and calibration IP.
- Lighting:General and specialty illumination systems face severe margin compression as LED efficacy plateaus and Asian manufacturing scales. Polish and Romanian assembly plants are absorbing transferred production from higher-cost Western European facilities.
- Imaging:Medical, industrial, and scientific image capture demands optical precision and thermal stability. Munich medical imaging clusters and Leuven semiconductor metrology operations specify custom lens-photodetector assemblies.
- Data Communication:Optical interconnects span intra-rack, inter-facility, and submarine cable applications.
- Sensing:Proximity, gesture, and environmental detection modules proliferate across mobility and automation platforms.
Lighting retains the installed base while sensing expands most quickly through autonomous system deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor and Germany's dense autobahn freight network underpin Central Europe's dominance in optoelectronics component distribution. High-voltage grid interconnectors between France, Germany, and the Nordics sustain power-hungry epitaxy and lithography operations.
Germany
Stuttgart's automotive LiDAR engineering centers and Munich's semiconductor lithography equipment makers pull precision optical sensors through multi-year qualification pipelines. KBA type-approval mandates for advanced driver-assistance systems filter component suppliers into tier-one relationships. The Jena-Munich photonics corridor concentrates gallium-nitride epitaxy and precision optics fabrication for medical imaging OEMs.
France
Paris-Saclay research clusters and Grenoble's microelectronics ecosystem drive demand for silicon photonics in telecommunications infrastructure. ANSM oversight of medical device registrations shapes photodetector specifications for diagnostic imaging channels. The Grenoble-Isère valley anchors CMOS-compatible optical sensor development for industrial automation applications.
Netherlands
Eindhoven's high-tech systems sector and Rotterdam port logistics sustain LED module assembly for European greenhouse and municipal lighting retrofits. REACH chemical registration requirements for epoxy encapsulants extend material qualification timelines at Dutch packaging houses. The Brainport Eindhoven region concentrates time-of-flight sensor design for consumer electronics OEMs.
Sweden
Volvo and Scania engineering centers in Gothenburg pull automotive-grade photodetectors into heavy vehicle safety systems. The country's national transport authority aligns with EU Green Deal mandates for energy-efficient LED retrofits across public infrastructure. Kista Science City hosts fabless design houses specializing in industrial machine vision edge devices.
Italy
Turin's automotive design studios and Milan's fashion-technology crossover create niche demand for micro-LED displays in wearable applications. CE marking under EU MDR concentrates medical imaging component procurement on qualified photodetector suppliers. The Lombardy-Trentino corridor supports specialty LED packaging for architectural and horticultural lighting systems.
Europe Optoelectronics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a structure that rewards vertical scope. The vendor base stratifies across three tiers: multinational semiconductor conglomerates with captive optoelectronics divisions, mid-cap photonics specialists with regional fab assets, and fabless design houses licensing process technology. Consolidation pressure runs highest where automotive LiDAR procurement is consolidating vendor lists from twelve discrete suppliers to four subsystem integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves as epitaxy houses secure substrate supply agreements.
Among German-based fabricators, Infineon Technologies AG and Osram Licht AG exemplify the vertically integrated archetype with captive gallium-nitride production and epitaxy operations respectively. STMicroelectronics occupies a position bridging European design capabilities with foundry partnerships for time-of-flight sensor arrays. These three anchors represent distinct strategic postures: captive semiconductor manufacturing, specialty lighting dominance, and fabless-plus-foundry hybridization.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| NXP Semiconductors |
| Osram Licht AG |
| Panasonic Corporation |
| Texas Instruments Inc. |
| Osram Opto Semiconductors |
| STMicroelectronics |
| Mitsubishi Electric |
| Koninklijke Philips NV |
| Others |
Supply & Pricing Matrix
Sapphire and silicon-carbide wafer supply concentrates in Asian refining corridors, anchoring margin capture at the epitaxy tier while European packaging houses absorb downstream cost pressure from REACH compliance burdens. This upstream concentration funnels pricing power toward substrate suppliers and tier-one automotive integrators, squeezing mid-tier LED and photodetector vendors.
Pricing Analysis
CE marking under the EU MDR dictates the pricing tier structure across medical-grade photodetector channels, separating qualified suppliers from commodity competitors. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with CE-MDR tier commanding multiples over uncertified alternatives. Cost compression in general illumination LED modules is intensifying because Asian manufacturing scales and efficacy plateaus eliminate differentiation. Automotive OEMs exhibit lowest price sensitivity due to KBA type-approval switching costs, while municipal lighting procurement shows highest sensitivity to unit economics.
Supply Chain Analysis
Export-control regimes on high-purity compound semiconductor substrates and epitaxial equipment constrain flows from established Asian suppliers to European fabrication complexes. Taiwan, South Korea, and Japan anchor wafer supply for gallium-nitride and indium-phosphide platforms. European epitaxy houses draw from these sources for sapphire, silicon-carbide, and III-V compound feedstocks. Single-source vulnerability concentrates around high-power laser diode substrates. Distribution runs through Stuttgart and Munich automotive engineering centers for qualified component integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe optoelectronics market sits at a platform-economics inflection where automotive perception-stack consolidation is collapsing discrete component vendor lists into fused camera-LiDAR-radar subsystem providers. Interoperability requirements under the EU AI Act's risk-classification framework are accelerating this ecosystem concentration.
For Market Incumbents: Insulate qualified supplier status through captive gallium-nitride epitaxy investments and accelerated REACH-compliant material qualification ahead of 2027 authorization deadlines. Defend against silicon photonics substitution in datacenter interconnects by deepening indium-phosphide laser diode performance differentiation. Prioritize KBA relationship maintenance as tier-one automotive procurement consolidates around 3-4 subsystem integrators. For New Entrants and Emerging Players: Nordic industrial automation sectors in Sweden and Finland represent the most penetrable entry point for time-of-flight sensor arrays, with penetration gaps of 20-30 points below German benchmarks. EU AI Act compliance services for perception-stack algorithmic transparency documentation offer adjacent revenue streams with lower capital barriers than component fabrication. Pursue fabless design partnerships with Grenoble CMOS-compatible optical sensor foundries for rapid prototyping. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive LiDAR module specialists facing tier-one consolidation pressure. Five-to-ten year viability hinges on vertical integration depth into epitaxy or software-defined calibration IP. Watch KBA type-approval timeline acceleration as the signal for inflection in qualified supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Gallium-Nitride Epitaxy Capacity Expansion | Dresden and Regensburg fab investments secure captive substrate supply for automotive LiDAR qualification pipelines. |
| REACH-Compliant Material Qualification | German and Dutch packaging houses accelerate bio-based encapsulant validation ahead of ECHA authorization deadlines. |
| Silicon Photonics Platform Integration | Deutsche Telekom infrastructure deployments displace discrete indium-phosphide assemblies with CMOS-compatible coherent engines. |
| Automotive Perception-Stack Certification | EU AI Act risk-classification documentation creates defensible positioning for tier-one subsystem integrators. |
| Nordic Industrial Automation Partnership | Swedish and Finnish machine vision OEMs offer expansion white space for qualified time-of-flight sensor suppliers. |
Research Methodology
A standing panel of epitaxy process engineers, automotive Tier 1 procurement directors, medical device regulatory affairs leads, and industrial automation R&D heads provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA REACH registration databases, KBA type-approval filings, EU Medical Device Regulation CE marking records, and semiconductor capital expenditure disclosures. Bottom-up component demand modeling triangulated against top-down macroeconomic scenario brackets.
Scenario bracketing around EU Green Deal implementation pace, automotive LiDAR mandate acceleration, and silicon photonics substitution timelines anchored the analytical framework across the projection horizon. Segmentation dimensions spanned device category, end-use industry, technology architecture, and application modality. CAGRs derived from regression analysis against historical qualification cycle lengths and procurement volume elasticities, with specific inputs including KBA approval velocity and ECHA authorization timeline risk.
Stress conditions across substrate supply disruption, REACH authorization delays, and automotive OEM consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology substitution curves. Material shifts in EU AI Act enforcement intensity or F-Gas Regulation phase-down acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
Laser Projection Market
Optoelectronics
Taiwan Optoelectronics Market
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
Laser Projector Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
Thermophotovoltaics Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Gunn Diode Market
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
China Optoelectronics Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Gaas Photodiode Market
Optoelectronics
EPON ONU Market