
 Gallium Arsenide Gaas Wafer Market | 2026-2036
Gallium Arsenide Gaas Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Gallium Arsenide Gaas Wafer Market Analysis
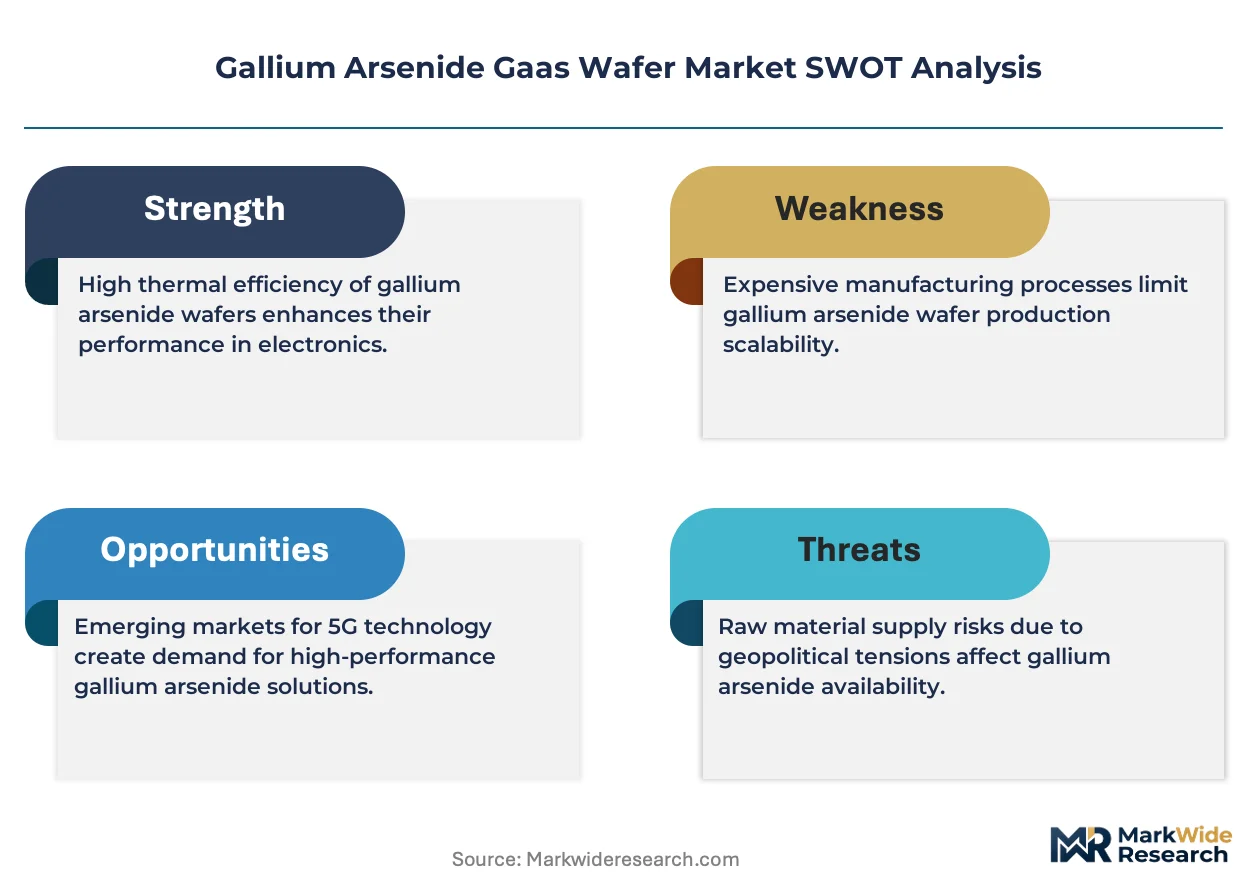
Aftermarket epitaxial foundry services is reshaping margin distribution across the GaAs value chain. IQE PLC leverages its molecular beam epitaxy platform to dominate outsourced epi-wafer supply. Freiberger Compound Materials GmbH sustains its position through captive crystal growth and substrate finishing. WIN Semiconductors Corp. anchors the pure-play foundry segment with GaAs pHEMT and HBT process leadership.
Gallium Arsenide (GaAs) wafers are compound semiconductor substrates composed of gallium and arsenic in a zincblende crystal structure, typically manufactured via liquid encapsulated Czochralski pulling or vertical gradient freeze methods to achieve dislocation densities below 500 cm⁻² for microwave and optoelectronic applications. The material delivers superior electron mobility and direct bandgap properties that enable efficient power amplification at frequencies above 3 GHz. Wafer and epitaxial layer segments command premium positioning as RF front-end module complexity rises in smartphones and defense radar systems. Substrate demand from telecommunications applications leads volume consumption, while metal organic chemical vapor deposition technology dominates epitaxial growth for LED and solar cell manufacturing.
REACH substance restrictions in Europe, RoHS hazardous substance limits, and China's GB semiconductor material standards collectively govern arsenic handling, wafer export classifications, and fab environmental compliance. The US EPA and Japan's METI enforce parallel reporting thresholds for gallium arsenide processing waste. Stakeholders must monitor regulatory divergence on per- and polyfluoroalkyl substance bans that threaten wet etching chemistries across major manufacturing jurisdictions.
Market Dynamics
Epitaxial foundry consolidation is redistributing margin capture across the GaAs value chain, as substrate manufacturers surrender upstream value to specialized epi-wafer suppliers serving RF module makers.
Growth Catalysts
- 5G infrastructure deployment:Massive MIMO antenna arrays in base stations require GaAs pHEMT power amplifiers, concentrating substrate orders with Taiwan and South Korea foundry clusters.
- REACH substance restrictions:European chemical compliance is filtering out marginal substrate suppliers, tightening supply discipline and elevating pricing power for qualified manufacturers.
- Defense radar modernization:Active electronically scanned array systems in airborne and naval platforms specify GaAs for X-band and Ku-band operation, sustaining premium demand independent of commercial cycles.
Market Restraints
- Arsenic supply concentration:Metallurgical-grade arsenic refining concentrates in China, exposing substrate manufacturers to export license volatility and dual carbon policy disruptions.
- Silicon carbide substitution:4H-SiC substrates are capturing frequency bands above 6 GHz in base station applications, compressing GaAs addressable market at the high-performance boundary.
- Capital intensity of VGF crystal growth:Vertical gradient freeze furnaces require multi-year depreciation cycles, constraining capacity expansion responsiveness to demand spikes.
Strategic Opportunities
- India PLI scheme for semiconductors:Domestic compound semiconductor fabs under the production-linked incentive program create captive substrate demand as ecosystem anchor tenants.
- GaAs-on-silicon integration:Heterogeneous bonding techniques enable RF front-end module miniaturization, opening smartphone OEM design-in opportunities previously reserved for SOI alternatives.
- China NMPA medical device standards:Diagnostic imaging equipment mandates are accelerating GaAs photodetector adoption in CT and PET scanner manufacturing.
Industry Challenges
- Molecular beam epitaxy technician scarcity:Foundry expansion in Taiwan and South Korea outpaces trained MBE operator supply, elongating equipment qualification timelines.
- RoHS hazardous substance documentation:Multi-jurisdiction material declaration requirements impose compliance overhead on substrate shipments to European module assemblers.
- Dislocation density certification:Defense prime contractors demand sub-500 cm⁻² etch pit density guarantees with lot-level traceability, rejecting standard commercial-grade material.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gallium Arsenide Gaas Wafer Market |
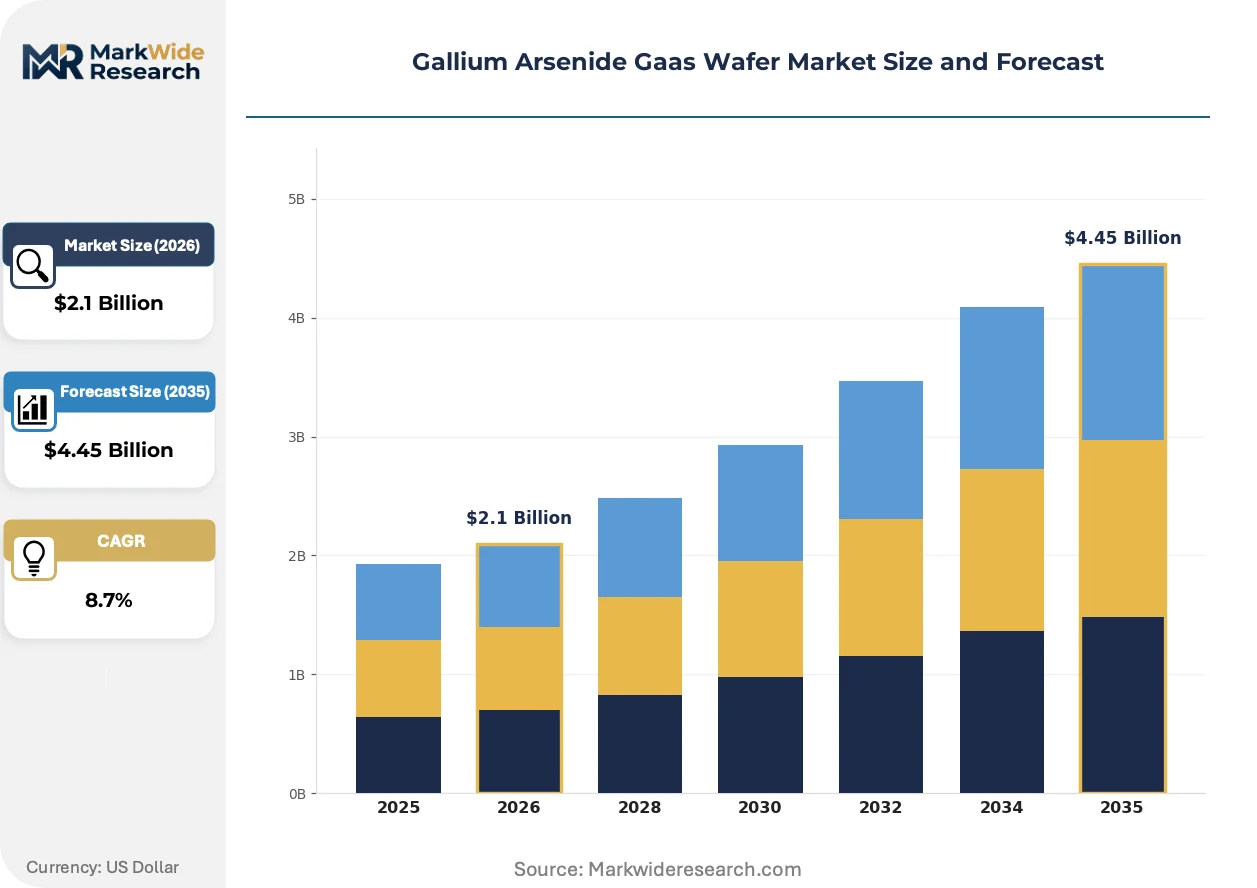
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ingot, Wafer, Substrate, Epitaxial Layer Application: Telecommunications, Solar Cells, LEDs, RF Devices End User: Consumer Electronics, Aerospace, Automotive, Industrial Technology: Molecular Beam Epitaxy, Liquid Phase Epitaxy, Metal Organic Chemical Vapor Deposition, Others |
| Companies Covered | Sumitomo Electric Industries, Freiberger Compound Materials GmbH, AXT Inc., IQE PLC, WIN Semiconductors Corp., Xiamen Powerway Advanced Material Co., Ltd., DOWA Electronics Materials Co., Ltd., Semiconductor Wafer Inc., Qorvo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gallium Arsenide Gaas Wafer Market Emerging Trajectories
Process convergence between substrate manufacturing and epitaxial growth is compressing traditional value chain boundaries, as equipment makers deliver integrated crystal-pull-to-epi platforms.
6-inch GaAs substrate migration is collapsing 4-inch equipment depreciation schedules and forcing foundry customers to redesign reticle sets. Smartphone RF front-end module suppliers in South Korea and Taiwan are accelerating 6-inch qualification timelines to secure die-cost advantages. This dimensional transition is collapsing legacy 4-inch supply commitments and stranding smaller substrate manufacturers without furnace upgrade capital.
China's GB semiconductor material standards are tightening arsenic purity specifications for export-classified substrates, compelling crystal growers to install additional zone-refining capacity. The NMPA and MIIT joint enforcement of these standards is elevating compliance costs for metallurgical-grade feedstock processors. European module assemblers are responding by dual-sourcing from Freiberg and AXT to reduce single-origin exposure.
Aftermarket epitaxial service contracts are displacing captive epi-wafer production among integrated device manufacturers. Pure-play foundries now specify substrate source and epi-layer stack as a bundled procurement unit, reversing historical arm's-length purchasing. This consolidation is most visible in Taiwan, where WIN Semiconductors and Advanced Wireless Semiconductor Company have established preferred substrate vendor lists with volume-commitment pricing.
Gallium Arsenide Gaas Wafer Market Segmentation
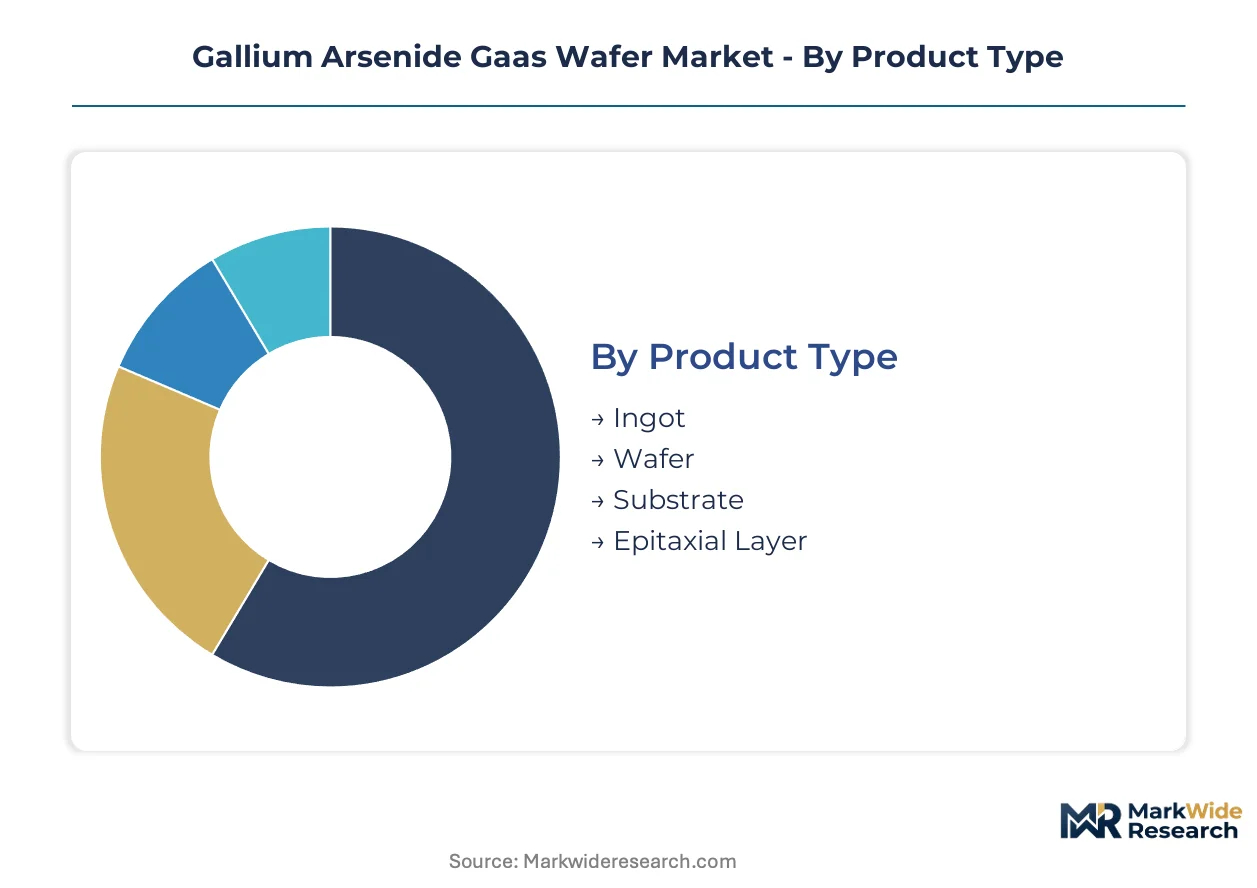
GaAs wafer segmentation reveals divergent margin structures across the value chain. Substrate manufacturers compete on crystal purity and diameter migration, while epitaxial specialists capture premium positioning through process integration with RF module makers.
Product Type:
Mature ingot and wafer segments anchor volume production, while epitaxial layers command the steepest value expansion as foundry outsourcing accelerates.
- Ingot:Polycrystalline GaAs cylinders grown via vertical gradient freeze or liquid encapsulated Czochralski methods serve as feedstock for substrate slicing. Demand concentrates with Freiberg and AXT crystal growth facilities in Germany and the United States, constrained by multi-year furnace depreciation cycles that limit capacity responsiveness.
- Wafer:Sliced and lapped discs undergo chemical-mechanical polishing to achieve epi-ready surface roughness below 0.5 nm. Taiwan and South Korea foundry clusters drive 6-inch diameter qualification timelines, collapsing legacy 4-inch equipment schedules and stranding manufacturers without upgrade capital.
- Substrate:Finished wafers with specified dislocation density below 500 cm⁻² for defense and commercial RF applications.
- Epitaxial Layer:MBE-grown or MOCVD-deposited crystalline films enabling pHEMT and HBT device structures.
Ingot retains volume leadership; epitaxial layer holds the steepest expansion curve.
Application:
Cost tier differentiation separates high-frequency RF devices from commodity LED and solar absorption.
- Telecommunications:5G massive MIMO base stations and smartphone front-end modules specify GaAs pHEMT power amplifiers for efficient operation above 3 GHz. Orders concentrate with Taiwan foundry clusters serving South Korean RF module suppliers, driven by 5G infrastructure deployment timelines.
- RF Devices:Defense radar systems and satellite communications exploit GaAs electron mobility for X-band and Ku-band power amplification. Active electronically scanned array modernization programs in the United States and Japan sustain premium demand independent of commercial smartphone cycles.
- LEDs:Red and infrared emitters for automotive and industrial sensing applications.
- Solar Cells:III-V multi-junction photovoltaics for satellite power systems.
Telecommunications commands the largest revenue pool; RF devices deliver the most resilient pricing through defense qualification barriers.
End User:
Customer type stratification distinguishes high-specification aerospace procurement from price-sensitive consumer electronics volume.
- Consumer Electronics:Smartphone OEMs in South Korea and Taiwan specify GaAs pHEMT and HBT dies for RF front-end module miniaturization. Design-in opportunities are expanding through GaAs-on-silicon heterogeneous bonding techniques previously reserved for SOI alternatives.
- Aerospace:Prime contractors demand sub-500 cm⁻² etch pit density guarantees with lot-level traceability, rejecting standard commercial-grade material. Defense radar and satellite programs in the United States and Japan specify GaAs for thermal stability in high-reliability environments.
- Automotive:Emerging LiDAR and radar sensor applications for advanced driver assistance systems.
- Industrial:Process control and diagnostic equipment utilizing GaAs photodetectors.
Consumer electronics generates the highest unit volumes; aerospace maintains the strictest material certification requirements and associated premium capture.
Technology:
Supply concentration in MBE equipment and operator training creates bottlenecks distinct from the capital-light liquid phase epitaxy segment.
- Molecular Beam Epitaxy:Ultra-high vacuum deposition enables atomic-layer precision for pHEMT and HBT structures with superior high-frequency performance. Taiwan and South Korea foundry expansion outpaces trained MBE operator supply, elongating equipment qualification timelines and tightening outsourced epi-wafer availability.
- Metal Organic Chemical Vapor Deposition:Reactor-scale production dominates LED and solar cell manufacturing with throughput advantages over MBE. China-based capacity expansion for solid-state lighting applications is absorbing regional MOCVD tool shipments, though RF device specifications favor MBE precision.
- Liquid Phase Epitaxy:Lower-cost growth method for photodetector and solar cell applications with relaxed thickness uniformity requirements.
- Others:Hydride vapor phase epitaxy and atomic layer deposition for specialized optoelectronic structures.
MOCVD retains the installed base advantage for commodity applications; MBE claims the steepest expansion trajectory in RF-specific foundry services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement in Japan and the United States absorbs price premiums without volume elasticity, while Chinese LED manufacturers drive razor-thin margin competition at the commodity end.
United States
Defense radar modernization programs at Raytheon and Lockheed Martin sustain premium substrate demand for X-band and Ku-band applications. The EPA enforces arsenic processing waste reporting thresholds that elevate compliance costs for domestic crystal growers. Silicon Valley RF module designers specify GaAs pHEMT dies from Taiwan foundries, concentrating procurement through West Coast distribution channels.
Germany
Automotive LiDAR sensor developers in Stuttgart and Munich specify GaAs photodetectors for advanced driver assistance systems. ECHA REACH substance restrictions filter marginal suppliers from European qualification lists, tightening supply discipline. Freiberg anchors continental substrate production with captive vertical gradient freeze capacity serving defense and satellite communications prime contractors.
China
Metallurgical-grade arsenic refining concentrates domestic supply, exposing substrate manufacturers to export license volatility under dual carbon policies. NMPA and MIIT joint enforcement of GB semiconductor material standards tightens purity specifications for medical imaging equipment. Xiamen and Shanghai foundry clusters absorb regional MOCVD tool shipments for solid-state lighting epitaxial production.
Taiwan
Pure-play foundry expansion at WIN Semiconductors and Advanced Wireless Semiconductor Company outpaces trained MBE operator supply. The island's Ministry of Economic Affairs coordinates compound semiconductor ecosystem development under national technology initiatives. Hsinchu Science Park concentrates epitaxial service contracts that bundle substrate sourcing with process integration.
South Korea
Samsung and LG smartphone OEMs accelerate 6-inch GaAs substrate qualification timelines to secure RF front-end module die-cost advantages. The MFDS regulates photodetector materials for diagnostic imaging equipment under converging standards with China NMPA. Seoul metropolitan area foundry clusters specify substrate source and epi-layer stack as unified procurement units.
Gallium Arsenide Gaas Wafer Market Vendor Landscape
Captive crystal growers and outsourced epitaxial specialists split the market along vertical integration fault lines. Substrate manufacturers compete on furnace scale and diameter migration, while foundry service providers capture upstream value through process integration. Three archetypes dominate: integrated compound semiconductor divisions, pure-play epitaxial foundries, and independent substrate merchants. Capacity expansion and strategic vendor list consolidation represent the dominant competitive vectors as 6-inch qualification timelines compress.
Among European crystal growth specialists, Freiberger Compound Materials GmbH exemplifies the captive integration archetype with in-house VGF capacity and substrate finishing operations. IQE PLC occupies the outsourced epitaxial tier, supplying MBE-grown epi-wafers to RF module manufacturers without substrate manufacturing exposure. WIN Semiconductors Corp. anchors the pure-play foundry segment, representing the convergence of substrate specification authority with process technology leadership in pHEMT and HBT platforms.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| Freiberger Compound Materials GmbH |
| AXT Inc. |
| IQE PLC |
| WIN Semiconductors Corp. |
| Xiamen Powerway Advanced Material Co., Ltd. |
| DOWA Electronics Materials Co., Ltd. |
| Semiconductor Wafer Inc. |
| Qorvo Inc. |
| Others |
Supply Flow & Price Mechanics
Metallurgical-grade arsenic refining concentrates in China, anchoring feedstock costs and transmitting volatility directly to substrate manufacturers' margin pools downstream. Foundry outsourcing to Taiwan and South Korea is redistributing value capture toward epitaxial specialists who bundle substrate sourcing with process integration contracts.
Pricing Analysis
Aftermarket epitaxial service contracts drive lifetime value through multi-year foundry agreements that lock in substrate-eplayer stack pricing. Three-tier pricing structure across defense-qualified, commercial-grade, and commodity LED tiers separates lot-traceable material from standard commercial specifications. Cost compression in commodity LED substrates is intensifying because China-based MOCVD capacity expansion absorbs regional tool shipments. Smartphone RF module makers in South Korea exhibit lowest price sensitivity due to die-cost advantages from 6-inch qualification, while industrial photodetector buyers face highest pressure.
Supply Chain Analysis
Extended payment terms from Taiwan foundry clusters are squeezing working capital for German and US substrate manufacturers. Geographic supply concentrates in China for arsenic refining, Germany for VGF crystal growth, and Taiwan for epitaxial foundry services. Raw material dependencies span metallurgical-grade arsenic, high-purity gallium, and pyrolytic boron nitride crucibles. Single-source vulnerability in Chinese arsenic export licensing threatens feedstock security. Distribution runs through West Coast channels for US defense primes and Hsinchu Science Park procurement offices for Taiwan foundries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as 5G massive MIMO deployment accelerates pHEMT power amplifier adoption ahead of silicon carbide substitution thresholds.
For Market Incumbents: Entrench through captive VGF furnace scale and 6-inch diameter migration ahead of customer qualification deadlines. Defense radar modernization programs at Raytheon and Lockheed Martin sustain premium demand independent of commercial cycles. Backward integration into zone-refining capacity addresses tightening China GB arsenic purity standards. Foundry vendor list consolidation in Taiwan compresses supplier slots and rewards early volume-commitment pricing. For New Entrants and Emerging Players: Establish a beachhead in India PLI scheme compound semiconductor fabs as ecosystem anchor tenants. Automotive LiDAR sensor specifications in Germany and South Korea represent the most penetrable white-space as advanced driver assistance systems expand. NMPA-aligned medical imaging photodetector standards in China offer regulatory-convergent entry. Go-to-market through preferred substrate vendor list applications with Taiwan pure-play foundries. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed epitaxial foundry specialists in Taiwan and South Korea facing MBE operator scarcity constraints. Long-term viability hinges on heterogeneous integration roadmaps and defense qualification moats. Acquisition targets center on captive crystal growers with uncommitted 6-inch furnace capacity. Watch silicon carbide base station penetration rates as substitution inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| 6-Inch Substrate Qualification | Collapses 4-inch equipment depreciation and secures foundry vendor list slots with WIN Semiconductors. |
| Zone-Refining Capacity Addition | Addresses China GB arsenic purity tightening and maintains export-classified substrate eligibility. |
| MBE Operator Training Programs | Elongates equipment qualification timelines and tightens outsourced epi-wafer availability. |
| India PLI Scheme Partnership | Creates captive substrate demand as domestic compound semiconductor fabs anchor ecosystem development. |
| GaAs-on-Silicon Heterogeneous Bonding | Opens smartphone OEM design-in opportunities previously reserved for SOI alternatives. |
Methodological Framework
Operator-level perspectives from crystal growth engineers, foundry procurement managers, MBE equipment specialists, and defense prime contractor materials scientists anchored the qualitative base. Primary interviews combined with secondary validation from EPA arsenic processing reports, ECHA REACH substance restriction filings, Taiwan Ministry of Economic Affairs technology initiative disclosures, and China MIIT GB standard publications. Bottom-up substrate capacity modeling triangulated against top-down RF module demand forecasts.
Scenario-bracketing around silicon carbide substitution timelines and China dual carbon policy disruption anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology platform. CAGRs derived from equipment depreciation cycle analysis and foundry capacity expansion schedules. Forecast inputs incorporated MBE operator supply constraints and 6-inch qualification timeline compression.
Sensitivities concentrate around arsenic export license volatility, silicon carbide base station capture rates, and MBE technician training pipeline expansion. Forecasts reflect documented assumptions on substrate diameter migration and epitaxial foundry consolidation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
2-Ethyl-3,4-Ethylenedioxythiophene Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
Gaas Photodiode Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
Laser Diode Market
Optoelectronics
Infrared Emitter and Receiver Market
Optoelectronics
Americas Optoelectronics Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
Cadmium Telluride Photovoltaic Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
China Optoelectronics Market
Optoelectronics
Global Optocoupler Market
Optoelectronics
Ingaas Avalanche Photodiode Market