
 Gaas Wafer and Epiwafer Market | 2026-2036
Gaas Wafer and Epiwafer Market Size, Share, and Industry Trends Forecast 2026-2036
Gaas Wafer and Epiwafer Market Insights
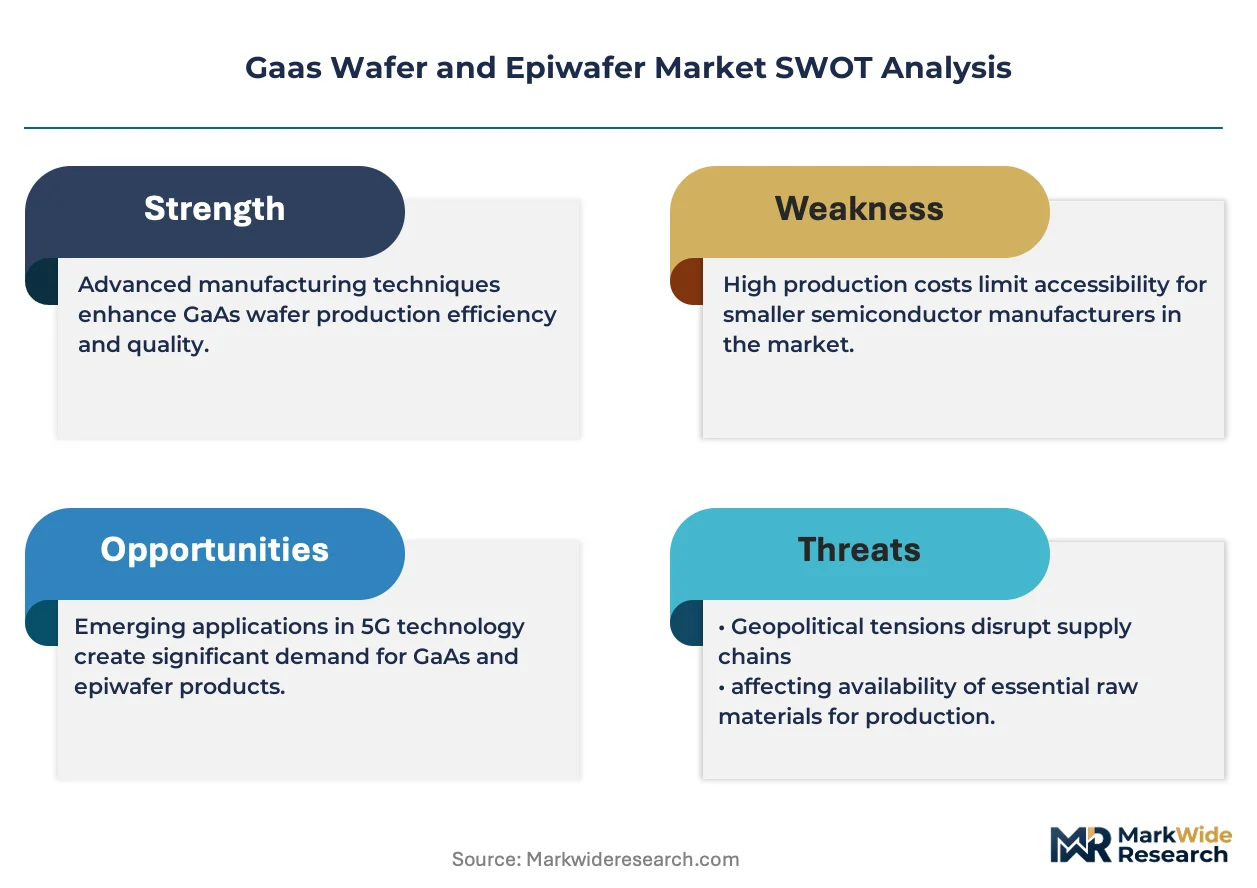
A shortage of trained epitaxial growth engineers is unwinding capacity expansion timelines at several foundries. Freiberger Compound Materials leverages its captive crystal-pulling operations to secure ingot supply for RF-grade substrates. IQE sustains technology leadership in molecular beam epitaxy for defense and satellite communications. Sumitomo Electric Industries dominates vertical integration from VGF-grown crystals through polished epi-ready wafers.
GaAs wafers and epiwafers are compound semiconductor substrates manufactured from gallium arsenide crystals grown via vertical gradient freeze or liquid-encapsulated Czochralski methods, with epitaxial layers deposited to precise thickness tolerances for electron mobility optimization in high-frequency applications. Epiwafers command premium positioning in RF device supply chains where carrier concentration uniformity determines amplifier performance. Molecular beam epitaxy leads in defense-aerospace applications demanding atomic-layer precision, while metal-organic chemical vapor deposition anchors LED and laser diode production at scale. Telecommunication end-users drive volume absorption as base station deployments multiply.
REACH compliance in Europe restricts hazardous substance use in semiconductor manufacturing processes, while China's MEE enforces wastewater discharge standards affecting wet-etching operations. The US EPA regulates perfluorinated compound emissions from CVD tool exhaust streams, raising abatement costs for domestic foundries. Stakeholders must monitor regulatory divergence across manufacturing geographies to anticipate cost pass-through structures and qualification burdens.
Market Dynamics
Epitaxial capacity bottlenecks are tightening as foundry clusters in Taiwan and South Korea absorb substrate supply faster than ingot producers can expand crystal-pulling operations. RF device manufacturers now face 18-24 month qualification timelines for new epiwafer sources.
Growth Catalysts
- 5G base station deployment:Massive MIMO architectures multiply power amplifier demand, pulling 6-inch semi-insulating GaAs substrates into cellular infrastructure buildouts.
- China's dual carbon goals:Beijing's emissions intensity mandates redirect state procurement toward suppliers employing lower-temperature epitaxial growth methods.
- Defense communications modernization:SATCOM terminal upgrades in NATO member states specify molecular beam epitaxy wafers for millimeter-wave phased arrays.
Market Restraints
- Arsenic trioxide feedstock volatility:Refining capacity concentration in Chinese smelters exposes substrate pricing to export quota fluctuations.
- VGF crystal growth equipment lead times:German and Japanese furnace manufacturers operate 14-month backlogs, capping ingot expansion velocity.
- Silicon-germanium substitution in sub-6 GHz:BiCMOS processes at leading foundries erode GaAs market position in mid-band RF front-ends.
Strategic Opportunities
- India's compound semiconductor PLI scheme:Subsidies for fabs in Gujarat and Karnataka create first-mover advantages for epiwafer qualification programs.
- Space-qualified solar cell demand:Satellite constellation operators seek radiation-hardened GaAs-on-Ge structures for electric propulsion arrays.
- Automotive radar at 77 GHz:Tier-1 suppliers in Germany and Japan evaluate GaAs pHEMTs for next-generation adaptive cruise control modules.
Industry Challenges
- Epitaxial growth engineer scarcity:Universities in Japan and the US graduate fewer than 150 compound semiconductor specialists annually against foundry hiring needs.
- REACH registration burdens:European chemical substance dossiers for gallium precursors consume 18-24 months and seven-figure compliance expenditures.
- Legacy 3-inch tool compatibility:Defense contractors maintain qualified processes on obsolete wafer sizes, fragmenting production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaas Wafer and Epiwafer Market |
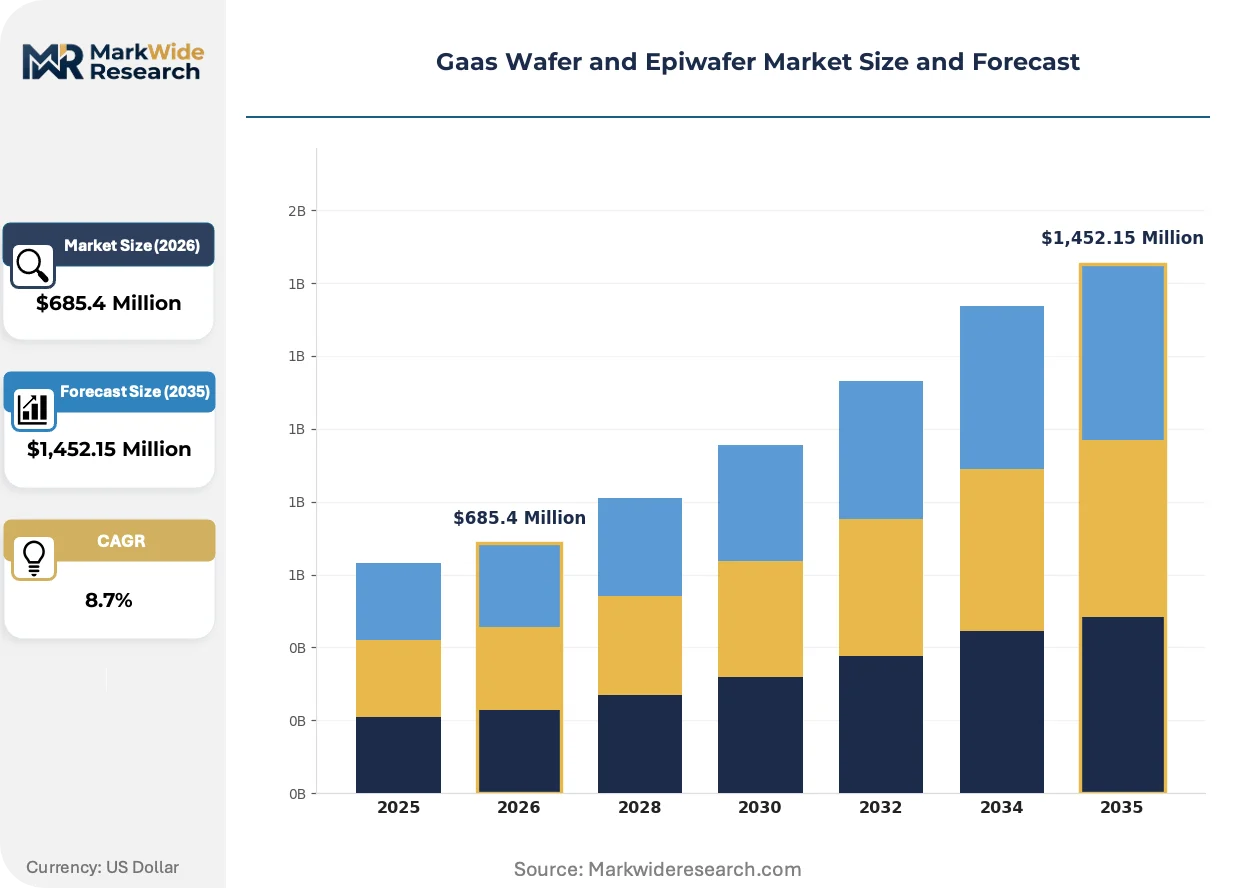
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gaas Wafers, Epiwafers, Substrates, Templates Technology: Molecular Beam Epitaxy, Metal-Organic Chemical Vapor Deposition, Liquid Phase Epitaxy, Chemical Vapor Deposition Application: LEDs, Laser Diodes, Solar Cells, RF Devices End User: Telecommunication, Automotive, Consumer Electronics, Industrial |
| Companies Covered | Sumitomo Electric Industries, Freiberger Compound Materials, AXT, IQE, Xiamen Powerway Advanced Material, VPEC, China Crystal Technologies, DOWA Electronics Materials, Wafer Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaas Wafer and Epiwafer Market Trends and Innovations
Wafer processing is converging with carbon-accounting requirements as scope 3 emissions reporting penetrates semiconductor supply chains. Buyers now request lifecycle assessments alongside traditional technical specifications.
Atomic layer deposition of aluminum oxide passivation layers is displacing thermal oxide processes in high-reliability RF device manufacturing. Defense contractors in the US and Japan have accelerated adoption since 2023. This displacement compresses thermal budget requirements and enables thinner epi structures without performance degradation.
REACH restrictions on perfluorinated compounds are tightening wet-etching process windows for European substrate manufacturers. ECHA's 2023 amendment to Annex XVII limits PFOA derivatives in semiconductor cleaning chemistries. German and French foundries are qualifying fluorine-free alternatives at 15-20% throughput penalty.
Consolidated procurement by East Asian foundry clusters is compressing supplier negotiation cycles from quarterly to monthly rhythms. Tier-2 epiwafer vendors in Taiwan and South Korea now face 60-day payment terms and blanket order commitments. This concentration is most visible in RF power amplifier supply chains serving smartphone OEMs.
Gaas Wafer and Epiwafer Market Segmentation
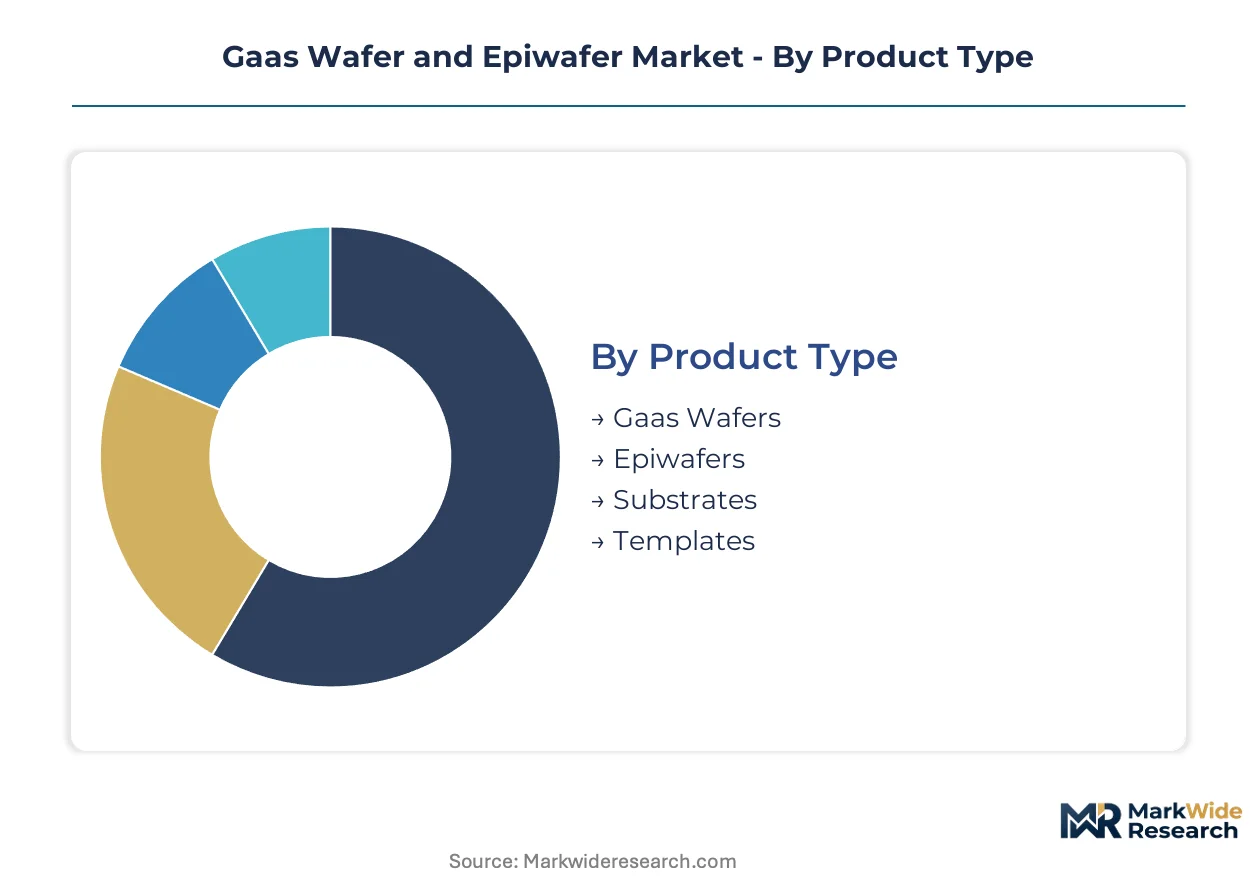
Segmentation reveals how margin pools concentrate in epitaxial processing and RF device applications. Understanding these splits helps suppliers align capacity investments with the highest-return technology-application combinations.
Product Type:
Margin capture concentrates in epitaxial layers where atomic-precision deposition commands premium pricing over raw substrates.
- Epiwafers:Multi-layer structures with precisely controlled carrier concentration profiles enable high-electron-mobility transistor performance. Defense contractors in the US and satellite operators in Japan absorb supply for millimeter-wave phased arrays under NATO SATCOM modernization programs. Molecular beam epitaxy variants for aerospace applications sustain the steepest price premiums.
- GaAs Wafers:Semi-insulating substrates grown via vertical gradient freeze methods form the base material for RF power amplifiers. Taiwan and South Korean foundry clusters pull 6-inch diameters for 5G massive MIMO base station builds. VGF furnace backlogs from German and Japanese equipment makers constrain ingot expansion velocity.
- Substrates:Polished epi-ready surfaces serve LED and photonics manufacturers.
- Templates:Reusable carrier wafers reduce epitaxial growth costs in high-volume LED production.
The dominant share belongs to Epiwafers, while GaAs Wafers is closing the gap fastest.
Technology:
Equipment utilization rates diverge sharply between atomic-layer precision systems and high-throughput deposition tools.
- Molecular Beam Epitaxy:Ultra-high vacuum deposition achieves monolayer thickness control for defense-aerospace applications. US contractors specify MBE wafers for radiation-hardened satellite communications under FCC frequency allocation rules. Tool throughput limitations restrict supply to qualified vendors.
- Metal-Organic Chemical Vapor Deposition:Scalable precursor delivery enables LED and laser diode manufacturing at wafer volumes exceeding MBE by orders of magnitude. China MEE wastewater discharge standards affect wet-etching operations at MOCVD-equipped foundries. Dual carbon goals redirect state procurement toward lower-temperature reactor designs.
- Liquid Phase Epitaxy:Melt-based growth suits thick-layer structures for magneto-optical devices.
- Chemical Vapor Deposition:Halide transport methods serve specialty optoelectronics with moderate precision requirements.
MOCVD holds the volume lead, with MBE expanding most quickly in value terms.
Application:
End-use pricing power tracks directly to reliability specifications and qualification burdens.
- RF Devices:Power amplifiers and low-noise amplifiers for cellular infrastructure and defense systems. 5G base station deployments in Taiwan and South Korea multiply substrate consumption for massive MIMO architectures. 18-24 month qualification timelines lock in supplier relationships.
- LEDs:Solid-state lighting and display backlights drive wafer volume through MOCVD production scale. REACH Annex XVII restrictions on perfluorinated compounds tighten wet-etching windows for European manufacturers.
- Laser Diodes:Optical communications and sensing applications require precise wavelength control.
- Solar Cells:Space-qualified GaAs-on-Ge structures serve satellite electric propulsion arrays.
RF Devices commands the dominant revenue position, with Solar Cells gaining share fastest on constellation deployment schedules.
End User:
Procurement sophistication varies from commodity spot purchasing to multi-year qualification programs.
- Telecommunication:Base station OEMs and network equipment providers specify epiwafer performance for 5G infrastructure. Taiwan and South Korean foundry clusters consolidate procurement into monthly negotiation cycles with 60-day payment terms. India's PLI scheme for compound semiconductor fabs creates new qualification opportunities.
- Automotive:Tier-1 suppliers in Germany and Japan evaluate GaAs pHEMTs for 77 GHz radar modules in adaptive cruise control systems.
- Consumer Electronics:Smartphone RF front-end modules absorb high volumes of semi-insulating substrates.
- Industrial:Laser processing and sensing equipment manufacturers source wafers for specialized applications.
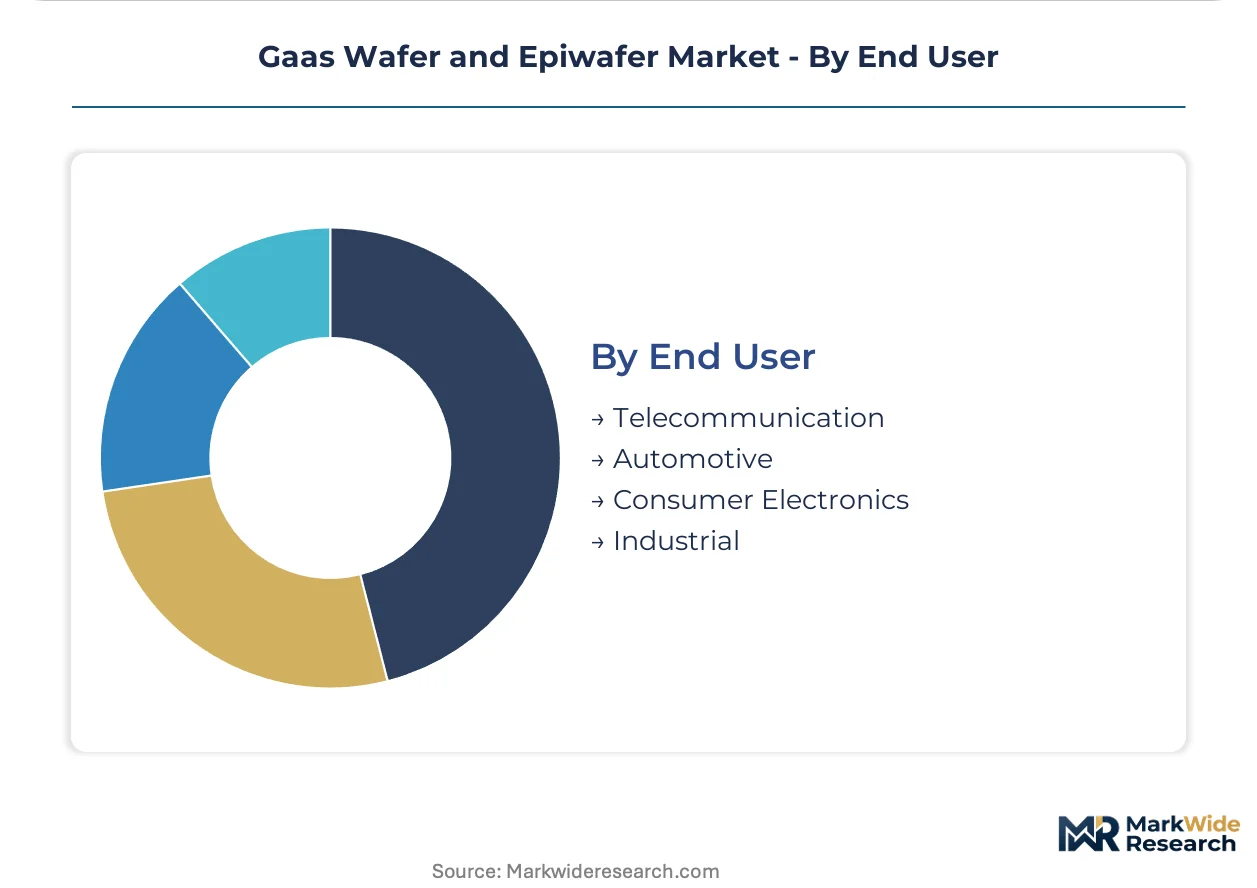
Telecommunication holds the dominant share, while Automotive is closing the gap fastest on radar penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT and the dual carbon goals anchor China's regulatory framework for compound semiconductor manufacturing. The country's emissions intensity mandates redirect state procurement toward lower-temperature epitaxial growth methods. Foundry clusters in Taiwan and South Korea absorb substrate supply faster than ingot producers can expand.
China
Beijing's MEE enforces wastewater discharge standards affecting wet-etching operations at MOCVD-equipped foundries. The dual carbon goals mandate emissions intensity reductions that favor lower-temperature reactor designs. Yangtze River Delta foundries in Shanghai and Suzhou scale 6-inch semi-insulating substrate consumption for 5G massive MIMO builds.
United States
FCC frequency allocation rules drive demand for radiation-hardened satellite communications components. EPA regulations on perfluorinated compound emissions from CVD tool exhaust streams raise abatement costs for domestic foundries. Defense contractors in California and Arizona specify molecular beam epitaxy wafers under NATO SATCOM modernization programs.
Japan
METI standards govern precision requirements for millimeter-wave phased arrays in aerospace applications. Satellite operators absorb supply for radiation-hardened structures under national space policy directives. Kyushu-based compound semiconductor facilities concentrate molecular beam epitaxy capacity for defense-aerospace end-users.
South Korea
MFDS-aligned industrial standards intersect with export control frameworks for defense-grade substrates. State-backed memory-to-logic diversification programs channel capital into compound semiconductor foundry capacity. Seoul Capital Area clusters pull 6-inch diameters for 5G base station deployments at monthly procurement cycles.
Germany
ECHA's 2023 REACH amendment to Annex XVII limits PFOA derivatives in semiconductor cleaning chemistries. German foundries qualify fluorine-free wet-etching alternatives at throughput penalties. Bavarian precision engineering centers evaluate GaAs pHEMTs for 77 GHz automotive radar modules.
Gaas Wafer and Epiwafer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the GaAs wafer and epiwafer market. Crystal-pulling operations and epitaxial deposition capabilities separate the upper tier from substrate-only suppliers. The market recognizes three archetypes: vertically integrated Japanese conglomerates, German precision materials specialists, and epitaxial technology pure-plays. Competitive moves center on captive ingot supply security and qualification program acceleration for defense-aerospace customers.
Among integrated materials conglomerates, Sumitomo Electric Industries exemplifies the vertical-control archetype spanning VGF-grown crystals through polished epi-ready wafers. Freiberger Compound Materials anchors the European specialist tier with captive crystal-pulling operations securing ingot supply for RF-grade substrates. IQE occupies a position in the epitaxial technology pure-play segment, with molecular beam epitaxy capabilities serving defense and satellite communications requirements.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| Freiberger Compound Materials |
| AXT |
| IQE |
| Xiamen Powerway Advanced Material |
| VPEC |
| China Crystal Technologies |
| DOWA Electronics Materials |
| Wafer Technology |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Taiwan foundry clusters and Japanese ingot suppliers lock in both substrate supply access and multi-quarter price visibility against arsenic trioxide feedstock volatility. These contracts concentrate procurement power among East Asian buyers while insulating qualified vendors from spot market fluctuations.
Pricing Analysis
Geographic price spreads widen between German furnace-manufactured VGF substrates and Chinese liquid-encapsulated Czochralski alternatives, reflecting equipment lead time differentials and REACH compliance burdens. Three-tier pricing structure across defense-aerospace, telecommunications, and LED commodity tiers separates molecular beam epitaxy premiums from metal-organic chemical vapor deposition volumes. Pricing pressure stems from silicon-germanium substitution in sub-6 GHz RF front-ends, compressing mid-band GaAs margins. Consumer electronics smartphone OEMs exhibit highest price sensitivity through consolidated 60-day payment terms, while defense contractors absorb premiums for radiation-hardened qualification.
Supply Chain Analysis
Inventory buffers at South Korean foundries have compressed to 6-8 weeks against 14-month VGF furnace backlogs from German and Japanese equipment makers. Crystal-pulling operations concentrate in China, Japan, and Germany, while epitaxial processing clusters in Taiwan and South Korea draw from ingot supply. Arsenic trioxide feedstock rests on Chinese smelter refining capacity exposed to export quota volatility. Single-source vulnerability concentrates in qualified molecular beam epitaxy vendors serving NATO SATCOM programs. Distribution runs through East Asian foundry procurement hubs with monthly negotiation cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epitaxial growth engineering services and qualification program management represent faster-expanding recurring revenue layers than substrate hardware sales, as foundry customers outsource scarce technical talent for process transfer.
For Market Incumbents: Shield qualified supplier relationships through accelerated certification investments for India's compound semiconductor PLI scheme before subsidy windows narrow. Deepen backward integration into captive arsenic trioxide refining to offset Chinese export quota volatility. Vertical integration of molecular beam epitaxy capacity insulates against engineer scarcity threatening competitor expansion timelines. For New Entrants and Emerging Players: EASA and FAA dual-certification fast-tracks for space-qualified solar cells open white-space in satellite constellation supply chains underserved by incumbent defense-focused vendors. Target automotive radar evaluation programs at German Tier-1 suppliers where GaAs pHEMT qualification for 77 GHz modules remains underpenetrated. Lead with lifecycle carbon accounting bundled into technical specifications to differentiate against legacy suppliers. For Investors and Strategic Acquirers: Epitaxial technology pure-plays with molecular beam epitaxy defense-aerospace customer concentrations offer acquisition exposure to NATO SATCOM modernization budgets. Long-term viability hinges on qualification timeline compression and engineer pipeline development rather than pure capacity scale. Watch India's PLI scheme disbursement velocity as inflection signal for foundry cluster geographic diversification.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Crystal-Pulling Capacity Expansion | Secures ingot supply against VGF furnace backlogs from German equipment makers. |
| Molecular Beam Epitaxy Qualification Acceleration | Compresses 18-24 month defense-aerospace approval timelines for NATO SATCOM vendors. |
| Carbon-Accounted Epitaxial Growth Methods | Aligns with China's MEE emissions intensity mandates redirecting state procurement. |
| India PLI Scheme Fab Partnership | Captures first-mover subsidies in Gujarat and Karnataka compound semiconductor clusters. |
| Fluorine-Free Wet-Etching Process Qualification | Addresses ECHA REACH Annex XVII restrictions on PFOA derivatives in European manufacturing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade data, and EPA emission disclosures to anchor substrate pricing and capacity expansion assumptions. Interviews with epitaxial growth engineers, foundry procurement managers, and defense contractor qualification officers combined with bottom-up wafer demand modeling and top-down RF device shipment analysis. Secondary validation drew from ECHA REACH dossiers, MIIT dual carbon policy documents, and FCC frequency allocation records.
Segmentation dimensions modeled span product type, epitaxial technology, application end-use, and geographic foundry cluster across the analysis window. CAGRs derive from triangulated wafer area consumption, equipment utilization rates, and qualification pipeline velocity. Forecast inputs incorporate VGF furnace delivery schedules, arsenic trioxide refining capacity, and molecular beam epitaxy tool installation backlogs without year-specific milestones.
Decision-makers should treat outputs as directional under sustained 5G infrastructure deployment and stable Chinese export quota regimes; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Optoelectronic Development Tools Market
Optoelectronics
Taiwan Optoelectronics Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market
Optoelectronics
Americas Optoelectronics Market
Optoelectronics
3D Projector Market
Optoelectronics
Laser Diode Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
Optoelectronics Market
Optoelectronics
Light Projector Market
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
Photoluminescent Film Market
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
China Optical Detector Market
Optoelectronics
Europe Wigig Market