
 Optical Emission Spectroscopy Market | 2026-2036
Optical Emission Spectroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Emission Spectroscopy Market Intelligence
The capital investment divergence between developing high-throughput bench-top systems and ruggedized portable spectrometers is unwinding the traditional market structure. Thermo Fisher Scientific leverages its extensive R&D budget to lead in the high-end laboratory segment. In contrast, specialized firms like SPECTRO Analytical Instruments GmbH differentiate through deep focus on metal analysis applications. Bruker Corporation competes by offering advanced solutions across both research and industrial quality control.
Optical emission spectroscopy is an analytical technique used to determine the elemental composition of a material. It functions by exciting a sample with a source like a spark or plasma and measuring the characteristic wavelengths of light emitted by the elements within. The primary industrial purpose is the rapid, quantitative analysis of metals and alloys for quality assurance. While bench-top spectrometers provide the highest precision for quality control labs, portable spectrometers represent the fastest-growing product type for on-site verification in applications like scrap metal sorting.
Regulatory frameworks are a significant demand catalyst. EPA regulations in the United States and the EU's RoHS directive create consistent requirements for elemental analysis in electronics and consumer goods. Similarly, China's GB standards for material purity and environmental compliance mandate precise testing across manufacturing supply chains. Instrument vendors must navigate the strategic choice between supporting centralized, high-precision laboratory workflows and enabling decentralized, on-site material verification.
Market Dynamics
The primary structural force is the bifurcation of investment between high-precision laboratory systems for R&D and rugged, portable units for on-site verification. This divergence is driven by distinct quality control requirements within the metallurgy and recycling sectors.
Growth Catalysts
- Regulatory Mandates:The EU's RoHS directive restricting hazardous substances in electronics compels manufacturers to use OES for verifying the absence of lead, cadmium, and mercury in components and solder alloys.
- Aerospace Requirements:The need for precise elemental analysis of superalloys and titanium in jet engines drives demand for high-performance spark OES systems to ensure material integrity and component safety.
- Industrialization in China:Expansion in automotive and heavy manufacturing across China necessitates adherence to stringent GB standards for material purity, creating sustained demand for quality control instrumentation.
Market Restraints
- High Capital Cost:The significant initial investment required for high-performance Inductively Coupled Plasma (ICP-OES) systems creates a barrier for small and medium-sized enterprises, such as smaller foundries or metal fabricators.
- Technical Limitations in Portability:While portable units are improving, they often exhibit lower precision for light elements like carbon and sulfur compared to bench-top systems, limiting their use in high-specification alloy grading.
- Component Supply Bottlenecks:The supply of critical high-purity argon gas and specialized optical components like diffraction gratings is concentrated, creating vulnerability to price volatility and supply chain disruptions.
Strategic Opportunities
- Battery Material Recycling:The growing electric vehicle market creates an opportunity for OES in recycling facilities to rapidly analyze and sort battery materials, identifying valuable elements like lithium, nickel, and cobalt from processed black mass.
- AI and Machine Learning Integration:Applying machine learning algorithms to OES spectral libraries can enable predictive grade identification and automated quality flagging, creating new software-as-a-service revenue streams.
- Food Safety Analysis:OES presents an opportunity for analyzing nutrient content and detecting heavy metal contaminants in soil, fertilizers, and food products, aligning with stricter global food safety standards.
Industry Challenges
- Specialized Skills Scarcity:A persistent shortage of trained metallurgists and analytical chemists who can develop custom calibration curves and interpret complex spectral interferences hinders the effective deployment of advanced OES systems.
- Data System Integration:Connecting OES output with enterprise-level Laboratory Information Management Systems (LIMS) and Quality Management Systems (QMS) is often complex, creating interoperability challenges for plant-wide data management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Emission Spectroscopy Market |
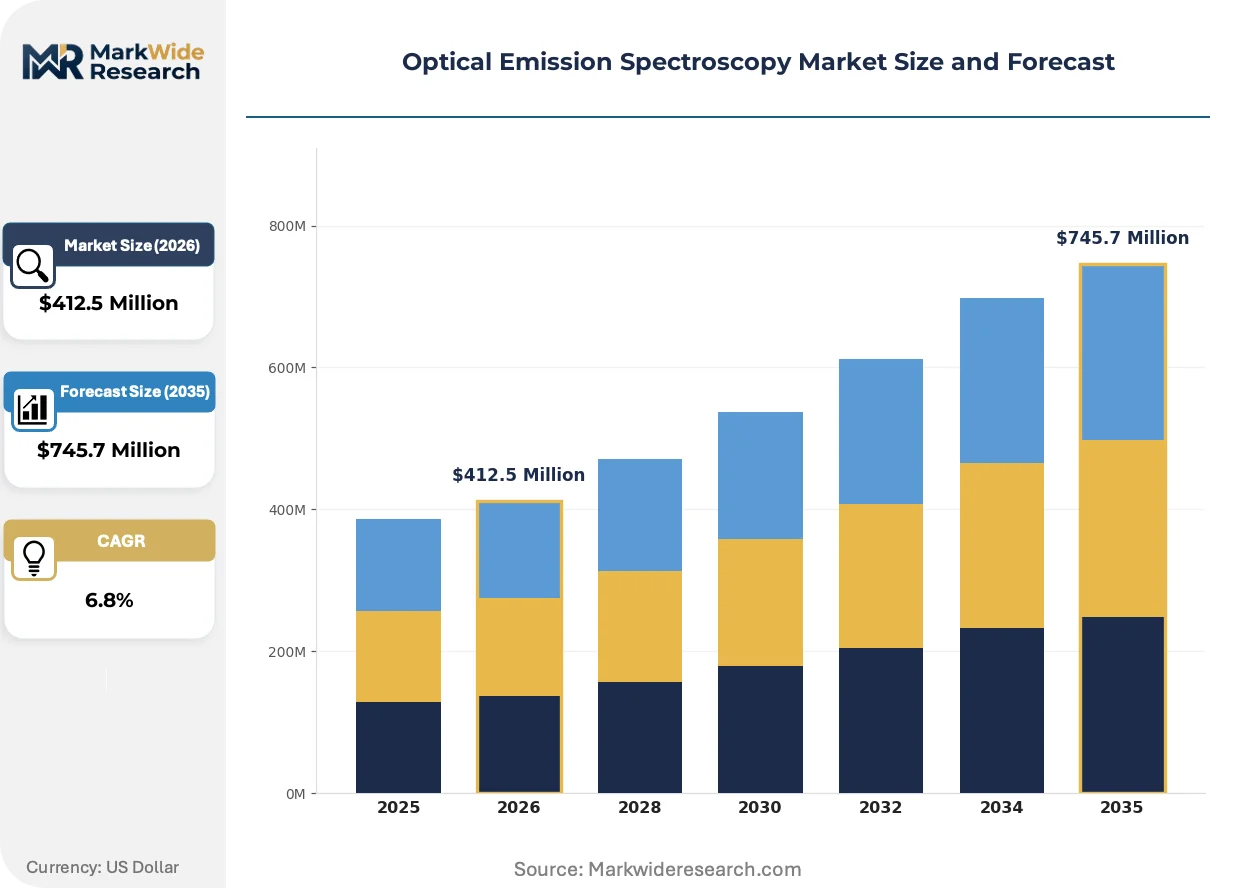
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sequential Spectrometer, Simultaneous Spectrometer, Portable Spectrometer, Bench-Top Spectrometer Application: Metallurgy Analysis, Environmental Monitoring, Pharmaceutical Testing, Food Quality Control, Chemical Analysis End User: Research Laboratories, Manufacturing Units, Quality Control Labs, Academic Institutions Technology: Inductively Coupled Plasma, Direct Current Arc, Spark Discharge, Laser-Induced Breakdown |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies Inc., PerkinElmer Inc., Horiba Ltd., Bruker Corporation, Ametek Inc., Shimadzu Corporation, Hitachi High-Tech Corporation, SPECTRO Analytical Instruments GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Emission Spectroscopy Market Strategic Shifts & Innovations
The evolution of optical emission spectroscopy is defined by a fundamental shift from centralized, lab-based analysis to decentralized material verification at the point of use. This transition pressures instrument design toward greater portability, connectivity, and operational simplicity.
Modern OES systems increasingly use solid-state CMOS detectors instead of traditional photomultiplier tubes. Industrial labs and portable instrument manufacturers are adopting this technology for its compact size and cost-effectiveness. This substitution is decomposing the rigid performance tiers, enabling mid-range systems to achieve analytical capabilities once exclusive to premium laboratory instruments.
China's enforcement of GB standards for material composition creates a significant compliance driver across its manufacturing sector. This forces industries from steel to electronics to implement rigorous elemental analysis for raw materials and finished goods. The automotive supply chain is particularly affected, investing in OES to meet purity requirements for lightweight alloys.
A shift in acquisition models is occurring, with users preferring subscription arrangements over direct capital purchase. This model disrupts the one-time sale by bundling instrumentation with ongoing calibration and software services into an operational expense. The trend is most prominent in North American and European industrial manufacturing where optimizing cash flow is a priority.
Optical Emission Spectroscopy Market Segmentation
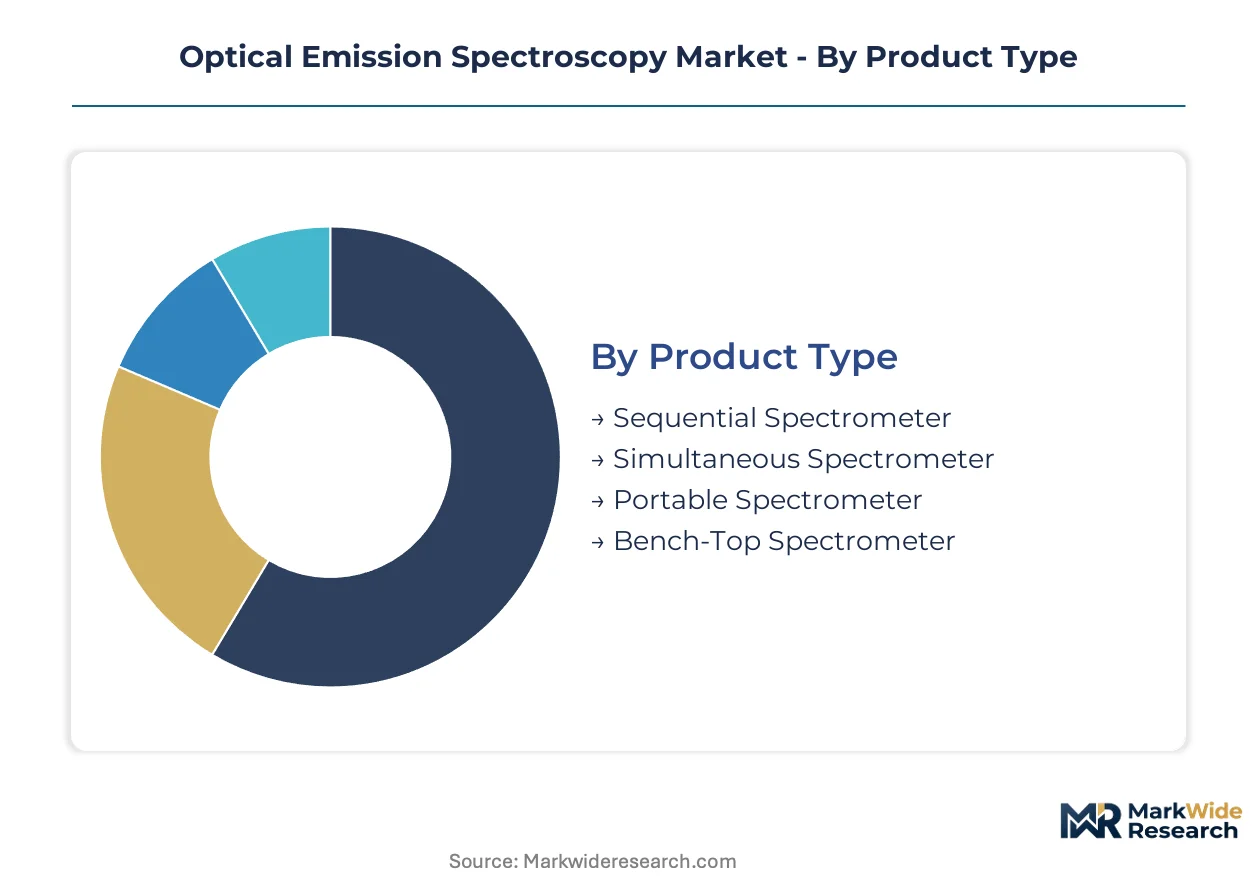
The Optical Emission Spectroscopy market's segmentation reflects diverse analytical needs across industries. Understanding these segments clarifies where specialized solutions drive value and where broad utility systems compete. This analysis delineates market structure by product type, application, end user, and underlying technology.
Product Type:
Margin pools within the product type category are increasingly influenced by the balance between analytical precision and operational flexibility.
- Bench-Top Spectrometer:These stationary laboratory instruments offer the highest analytical precision for elemental composition, utilizing advanced optics and stable environments. Demand concentrates in quality control labs within German and US automotive manufacturing, driven by stringent material specifications for lightweight alloys.
- Portable Spectrometer:These compact, handheld devices enable rapid, on-site elemental analysis, sacrificing some precision for immediate results. Their demand accelerates in China's recycling sector for scrap metal sorting and in North America for construction material verification.
- Sequential Spectrometer:This system measures elements one after another, offering high flexibility for diverse elemental analysis in research settings.
- Simultaneous Spectrometer:These instruments measure multiple elements concurrently, providing faster analysis for high-throughput industrial quality control.
Bench-Top Spectrometer holds installed capacity. Portable Spectrometer is rotating up the share rankings.
Application:
Application segmentation highlights where the largest analytical volumes are processed across diverse industrial and environmental contexts.
- Metallurgy Analysis:This application precisely determines elemental composition in metals and alloys, ensuring material integrity and performance in critical components. Demand for this application is strong in Germany's specialized steel production and in China's heavy manufacturing industry.
- Environmental Monitoring:This involves detecting heavy metals and contaminants in samples like water, soil, and air, complying with regulatory standards. EPA regulations in the United States and the EU's RoHS directive compel consistent elemental analysis in various waste streams.
- Pharmaceutical Testing:OES verifies elemental impurities and active pharmaceutical ingredients in drug formulations, meeting strict regulatory guidelines.
- Food Quality Control:This application identifies heavy metals and nutrient content in food products, aligning with global food safety standards.
- Chemical Analysis:OES provides elemental identification and quantification for various chemical compounds, supporting process control and product development.
Metallurgy Analysis continues to command the largest share. Environmental Monitoring exhibits a steep expansion trajectory.
End User:
The end user segmentation reveals distinct cost tiers and operational requirements for OES instrumentation across various organizational structures.
- Manufacturing Units:These industrial facilities integrate OES for real-time process control and material verification on production lines, ensuring consistent product quality. Demand is strong in China's automotive supply chain, driven by GB standards for material purity in lightweight alloys.
- Quality Control Labs:These dedicated laboratories perform precise elemental analysis to certify material compliance with specifications and regulatory mandates. North American aerospace manufacturers rely on OES in these labs for superalloy and titanium component validation.
- Research Laboratories:Academic and industrial research institutions utilize OES for fundamental material science studies and new alloy development.
- Academic Institutions:Universities and technical colleges employ OES for educational purposes and basic scientific investigations into elemental composition.
Manufacturing Units drive consistent volume. Quality Control Labs are rapidly expanding their analytical capabilities.
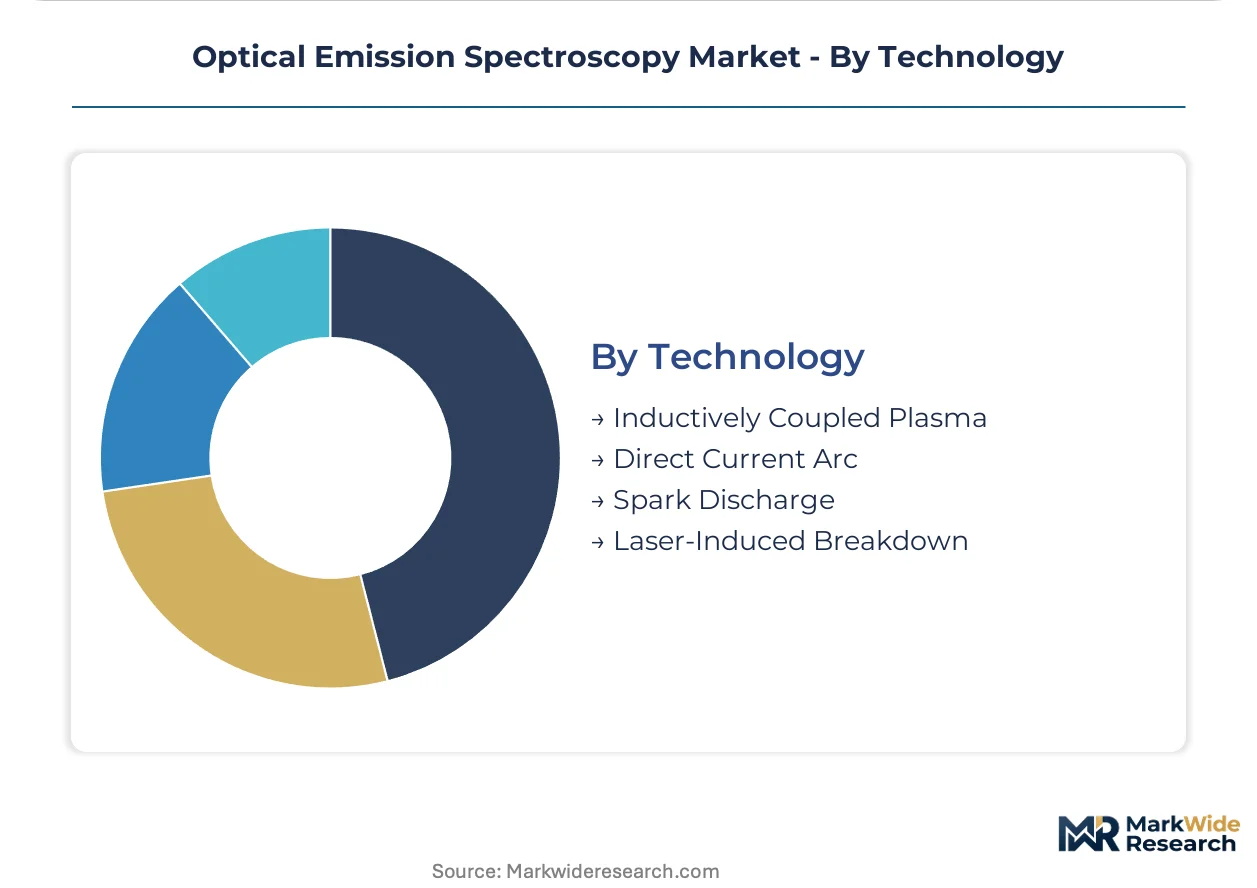
Technology:
Technology segmentation highlights the varying maturity levels and analytical capabilities offered by different OES excitation methods.
- Inductively Coupled Plasma:ICP-OES utilizes a high-temperature plasma to excite samples, providing exceptional detection limits and multi-element analysis across diverse matrices. This technology sees significant demand in environmental monitoring applications across Europe due to stringent heavy metal regulations.
- Spark Discharge:Spark OES uses an electrical spark to ablate and excite solid metal samples, offering rapid, direct elemental analysis for alloys. Its precision is critical for metallurgy analysis in the US and German automotive and aerospace industries.
- Direct Current Arc:This method employs a DC arc to vaporize and excite samples, suitable for refractory materials and powder analysis.
- Laser-Induced Breakdown:LIBS technology uses a pulsed laser to create plasma, enabling fast, non-contact elemental analysis on various surfaces.
Spark Discharge technology maintains a dominant position. Laser-Induced Breakdown methods are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly across the global optical emission spectroscopy market. Some industrial sectors prioritize cost-effective, high-throughput systems for volume production, while others require exceptional precision for critical material verification.
United States
United States demand for OES systems stems from aerospace manufacturing and stringent environmental monitoring. EPA regulations on heavy metals compel consistent elemental analysis across various waste streams. North American aerospace manufacturers in Seattle rely on OES for superalloy and titanium component validation.
Germany
German industrial sectors drive demand for high-precision OES in specialized steel production. The EU's RoHS directive influences material compliance in electronics and consumer goods. Industrial manufacturing centers in Baden-Württemberg utilize bench-top systems for stringent material specifications.
China
China's expanding automotive supply chain fuels significant OES demand for material purity. GB standards for manufacturing materials mandate precise elemental analysis across production lines. Yangtze River Delta manufacturing hubs integrate OES for quality control in lightweight alloys.
Japan
Japanese advanced manufacturing and electronics industries require OES for material research and quality assurance. JIS standards for industrial materials ensure product reliability and performance. Tokyo's research institutions and automotive suppliers utilize OES for alloy development and component testing.
India
India's growing industrial base and infrastructure projects increase demand for material verification. BIS standards for metal and alloy purity guide quality control processes in various sectors. Pune's automotive and general manufacturing sectors integrate OES for incoming material inspection.
Optical Emission Spectroscopy Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the optical emission spectroscopy market. This structure exhibits a tiered consolidation, where a few large players offer comprehensive portfolios across various technologies and applications. Archetypes include general analytical instrument providers, specialized metal analysis firms, and advanced solution providers spanning both research and industrial quality control. Dominant competitive moves involve strategic partnerships to expand market reach and continuous research and development investment to enhance system capabilities.
Within the high-end laboratory segment, Thermo Fisher Scientific Inc. represents a global leader, leveraging an extensive research and development budget to maintain its position in advanced instrumentation. SPECTRO Analytical Instruments GmbH, a German-based firm, exemplifies specialization through its deep focus on metal analysis applications, catering to the precise needs of metallurgy and quality assurance. Bruker Corporation, operating as a US-based entity, occupies a position offering advanced solutions across both research and industrial quality control settings, addressing a broad customer base with its diverse technology offerings. These companies collectively anchor different competitive vectors, from broad portfolio offerings to highly specialized expertise.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| PerkinElmer Inc. |
| Horiba Ltd. |
| Bruker Corporation |
| Ametek Inc. |
| Shimadzu Corporation |
| Hitachi High-Tech Corporation |
| SPECTRO Analytical Instruments GmbH |
| Others |
Cost & Logistics Intelligence
Lead-time variability for specialized optical components significantly influences pricing power within the Optical Emission Spectroscopy market, often dictating instrument availability and cost to end-users. This variability is directly linked to the concentrated supply chain for these high-precision inputs.
Pricing Analysis
After-sales service contracts, including calibration, maintenance, and software updates, represent a crucial revenue tier driving lifetime value for OES instrument providers. The dominant pricing model is a hybrid, combining per-unit transactional sales for hardware with evolving subscription arrangements for software and ongoing services. Price differentiation stems from analytical precision for high-end laboratory systems and the level of customization offered for specific industrial applications. Pricing pressure intensifies in the mid-range segment due to the influx of cost-effective CMOS detector technology. Small and medium-sized enterprises exhibit higher price sensitivity compared to large aerospace or automotive manufacturers.
Supply Chain Analysis
Strategic stockpiling of critical high-purity argon gas and specialized optical components helps mitigate supply chain risks for OES manufacturers. Geographic supply concentration for finished instruments centers in Germany and the United States, while China increasingly contributes to lower-cost portable unit manufacturing. Raw material dependencies include highly purified gases, diffraction gratings, and advanced solid-state detectors. Single-source vulnerability for these specialized optical components presents a structural supply chain risk. Distribution runs through a combination of direct sales channels for large industrial clients and specialized distributors for smaller laboratories and emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Optical Emission Spectroscopy market is experiencing a cyclical recovery, driven by renewed industrial investment in quality control and the expansion of manufacturing sectors globally.
For Market Incumbents:Compound R&D investment in AI/Machine Learning for spectral analysis and advanced detector technologies to counter emerging specialized firms. Form strategic partnerships to expand geographic reach, especially in industrializing regions like India and China. Invest in vertical integration for critical optical components to mitigate supply chain disruptions. This proactive approach helps defend against margin erosion from lower-cost portable units.
For New Entrants and Emerging Players:Anchor in niche applications like battery material recycling or food safety analysis where OES is underutilized. Target the portable spectrometer segment in rapidly industrializing regions such as India for on-site material verification. Offer flexible subscription models bundling hardware with AI-driven software for grade identification. This strategy leverages underpenetrated segments and addresses capital cost barriers for smaller buyers.
For Investors and Strategic Acquirers:Carve-out targets emerge from larger analytical instrument conglomerates seeking to divest non-core OES assets. The market's long-term viability remains strong over the next decade due to persistent quality control and regulatory needs. Focus on acquiring specialized firms with proprietary detector technology or advanced software integration capabilities. Monitor venture capital funding rounds for AI-powered spectral analysis startups as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-Integrated OES Systems | Enhances analytical capabilities and creates new software revenue streams for quality control applications. |
| Geographic Expansion: India and Southeast Asia | Captures demand from industrialization and increasingly stringent material purity standards. |
| Strategic Partnership: Specialized Component Suppliers | Secures critical supply of specialized optical components and mitigates potential bottlenecks. |
| Subscription Model Introduction: Hardware-as-a-Service | Aligns with user preference for operational expenses and lowers capital cost barriers for adoption. |
| R&D Investment: Advanced Portable Spectrometers | Addresses the fastest-growing product segment for decentralized and on-site material verification. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation. Interviews included metallurgists, quality control managers, instrument procurement leads, and R&D directors across manufacturing and research. Secondary sources comprised regulatory documents like EPA guidelines, EU RoHS directives, China GB standards, and relevant company financial reports. This approach ensured bottom-up market sizing and top-down validation.
The analytical framework projected market dynamics across the analysis window, integrating historical data with forward-looking indicators. Segmentation dimensions modeled included product type, application, end user, technology, and regional adoption patterns. Compound Annual Growth Rates were derived from these granular forecasts. Key industry-specific inputs included anticipated regulatory compliance timelines and projected industrial manufacturing output in major economies.
Decision-makers should treat outputs as directional under current macroeconomic stability and regulatory frameworks; material deviation would warrant model refresh. Forecasts reflect assumptions regarding industrial investment cycles and the pace of technological adoption. Revision becomes warranted when critical component supply chain stability or major regulatory shifts cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Optical Pulse Sensor Market
Optoelectronics
Taiwan Optoelectronics Market
Optoelectronics
Europe Wigig Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
Green Laser Diode Market
Optoelectronics
China Optical Detector Market
Optoelectronics
2-Ethyl-3,4-Ethylenedioxythiophene Market
Optoelectronics
EPON ONU Market
Optoelectronics
Heterojunction Solar Cell Market
Optoelectronics
Light Projector Market
Optoelectronics
Laser Projector Market
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Laser Projection Market
Optoelectronics
United States Optoelectronics Market
Optoelectronics
3D Projector Market