
 Automotive Optoelectronics Market | 2026-2036
Automotive Optoelectronics Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Optoelectronics Market Analysis
Software-defined lighting subscription tiers is rebalancing how suppliers monetize exterior illumination beyond hardware shipments. Valeo SA leverages its full-stack adaptive headlamp architecture to sustain recurring revenue streams from OEM customers. ams OSRAM AG anchors photonic component supply for premium sensor fusion platforms across European and Asian vehicle programs.
Automotive optoelectronics encompasses semiconductor-based light generation and detection devices—LEDs, laser diodes, photonic sensors, and infrared imagers—operating across wavelengths from visible to near-infrared with response times below microsecond thresholds, deployed to enable vision, signaling, ranging, and cabin interface functions in vehicles. Photonic sensors dominate unit volumes as safety-system mandates expand, while LiDAR technology captures the fastest growth trajectory amid autonomous-driving validation cycles. LED applications retain margin concentration in exterior lighting through thermal management and optical design IP, whereas OLED interior display systems occupy premium positioning in cockpit digitization roadmaps.
NHTSA FMVSS 108 lighting standards, Euro NCAP pedestrian safety protocols, and China's GB/T vehicle sensor specifications collectively dictate photonic performance thresholds and homologation pathways for market access. ECE R48 and R87 regulations further constrain beam pattern geometry and intensity distribution across European type approvals. Stakeholders must monitor harmonization gaps between federal motor vehicle standards and emerging camera-perception performance benchmarks to anticipate certification bottlenecks.
Market Dynamics
LiDAR-to-vehicle integration timelines are compressing as Euro NCAP pedestrian-detection thresholds tighten ahead of 2026 enforcement, forcing Tier 1 suppliers to accelerate photonic sensor validation cycles.
Growth Catalysts
- Euro NCAP pedestrian safety protocols:Mandated automatic emergency braking with nighttime pedestrian detection is pulling infrared imagers into mass-market vehicle platforms.
- China's GB/T sensor specifications:Homologation requirements for advanced driver-assistance systems are standardizing LiDAR performance benchmarks across domestic EV programs.
- Silicon photonics fabrication:Foundry-scale manufacturing of coherent LiDAR-on-chip devices is collapsing unit economics for solid-state ranging modules.
Market Restraints
- InP wafer supply concentration:Indium phosphide substrate production clusters in Japanese and Chinese foundries, exposing LiDAR makers to single-source fragility.
- ECE R48 beam pattern compliance:European type-approval complexity for adaptive driving beams extends development timelines by 8-14 months.
- Thermal management cost stack:High-power LED and laser diode arrays require active cooling subsystems that consume 12-18% of module bill-of-materials.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives for advanced electronics manufacturing are attracting optoelectronic module assembly investments.
- Cabin monitoring fusion:Driver attention tracking and occupant detection are converging infrared imagers with radar into unified interior sensing platforms.
- Software-defined lighting subscriptions:OEMs are unbundling adaptive headlamp feature activation into over-the-air monetization tiers.
Industry Challenges
- Photonic packaging talent scarcity:Micro-optical assembly and fiber-alignment engineering expertise concentrates in German and Japanese precision manufacturing clusters.
- Multi-sensor calibration complexity:LiDAR-camera-radar fusion demands sub-millimeter spatial alignment that legacy vehicle electrical architectures struggle to accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Optoelectronics Market |
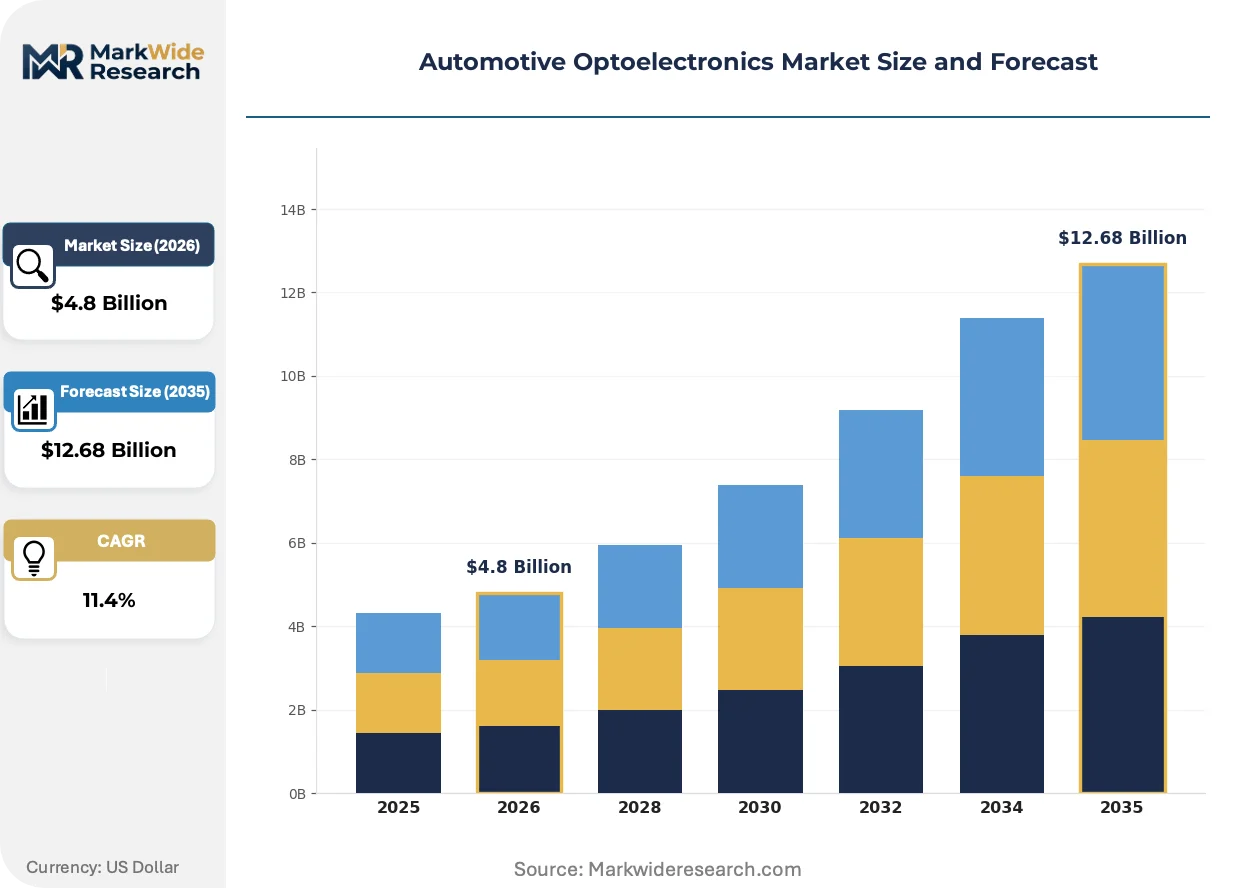
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, Laser Diodes, Photonic Sensors Technology: Adaptive Lighting, Infrared Imaging, Display Systems, LiDAR End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Interior Lighting, Exterior Lighting, Safety Systems, User Interface |
| Companies Covered | Valeo SA, STMicroelectronics, ams OSRAM AG, Hyundai Mobis Co., Ltd., Hella GmbH & Co. KGaA, Samsung Electronics Co., Ltd., ON Semiconductor Corporation, Sony Group Corporation, Nichia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Optoelectronics Market Emerging Trajectories
Automotive optoelectronics is pivoting from discrete component supply toward subsystem integration, with photonic sensors, illumination modules, and processing units collapsing into unified perception stacks.
Micro-LED display technology is expanding into augmented-reality head-up displays, projecting navigation and hazard alerts directly onto windshields. German premium OEMs are adopting 25,000-nit brightness panels for daylight-readable overlays. This expansion is compressing the traditional instrument cluster supply chain as virtual image planes replace physical gauges.
NHTSA FMVSS 108 updates are mandating adaptive driving beam functionality for five-star safety ratings. The regulation forces headlamp suppliers to embed matrix LED or DLP projection engines. North American light-truck platforms are absorbing the highest compliance costs due to larger beam pattern coverage requirements.
Fleet operators are unbundling sensor maintenance from vehicle purchase contracts, creating subscription-based calibration and replacement programs. Commercial vehicle leasing channels in the United States are piloting per-mile sensing service fees. This model is most visible in long-haul trucking where LiDAR degradation from road debris demands predictable lifecycle cost structures.
Automotive Optoelectronics Market Segmentation
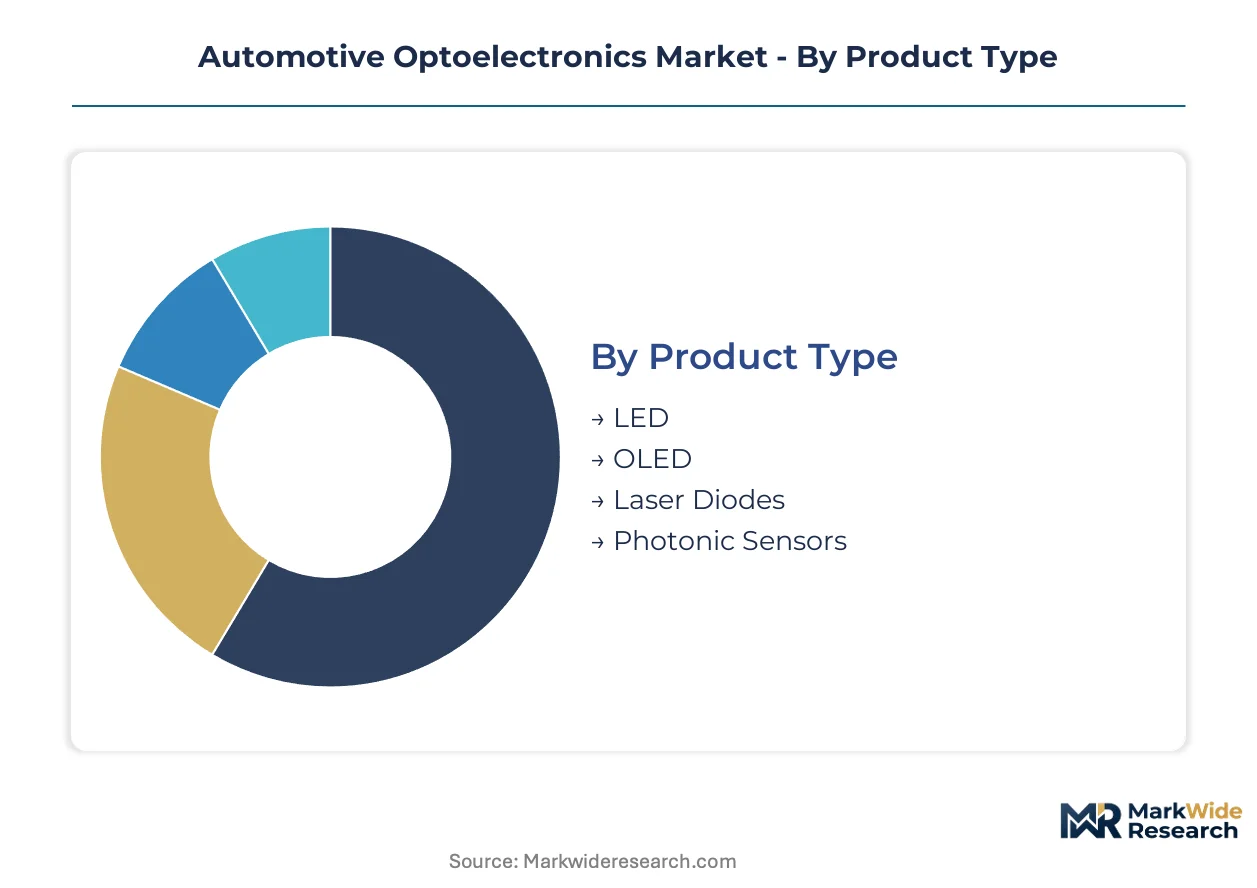
Automotive optoelectronics segmentation reveals how photonic technologies fragment across cost tiers, functional domains, and supply chain positions. LED and photonic sensor volumes dominate unit economics, while LiDAR and OLED command premium positioning amid safety mandates and cockpit digitization roadmaps.
Product Type:
LED modules anchor mass-market volumes through exterior lighting standardization, whereas laser diodes and photonic sensors capture margin concentration in ranging and detection applications.
- LED:Solid-state emitters operating across visible wavelengths with thermal management IP determining supplier differentiation. Exterior headlamp and taillight programs in Germany and China absorb the highest volumes as NHTSA FMVSS 108 and ECE R87 tighten beam pattern requirements.
- Photonic Sensors:Semiconductor detectors spanning near-infrared spectra with sub-microsecond response times for safety-critical ranging. Nighttime pedestrian detection mandates under Euro NCAP protocols are pulling infrared imagers into mass-market vehicle platforms from Stuttgart to Shanghai.
- Laser Diodes:Coherent light sources enabling long-range LiDAR with spectral purity above 905nm or 1550nm wavelengths.
- OLED:Organic emitters enabling conformable interior displays with pixel-level dimming control.
Today's leader: LED. Tomorrow's challenger: Photonic Sensors.
Technology:
Adaptive lighting and LiDAR command development investment intensity, while display systems and infrared imaging scale through manufacturing replication.
- LiDAR:Time-of-flight and frequency-modulated coherent ranging systems with solid-state beam steering. Silicon photonics fabrication in Chinese and Japanese foundries is collapsing unit economics for automotive-grade modules.
- Adaptive Lighting:Matrix LED and DLP projection engines with dynamic beam shaping. Euro NCAP five-star thresholds are forcing German premium OEMs to embed pixel-level control across their vehicle portfolios.
- Infrared Imaging:Thermal and near-infrared imagers for pedestrian detection and cabin monitoring.
- Display Systems:Micro-LED and OLED panels for instrument clusters and augmented-reality head-up displays.
LiDAR climbs the fastest in development priority. Adaptive Lighting holds the revenue base.
End User:
Tier-1 suppliers concentrate photonic subsystem integration expertise, while OEMs retain specification control over safety-critical perception stacks.
- Tier-1 Suppliers:Subsystem integrators combining photonic components with thermal management and optical design. Valeo SA and ams OSRAM AG dominate European and Asian sourcing channels through full-stack adaptive headlamp and sensor fusion architectures.
- OEMs:Vehicle manufacturers specifying performance thresholds and validation protocols. Software-defined lighting subscriptions are rebalancing how OEMs monetize exterior illumination beyond hardware procurement.
- Vehicle Assemblers:Contract manufacturers executing platform production with optoelectronic module integration.
- Aftermarket Providers:Independent channels for replacement lighting and sensor calibration services.
Tier-1 Suppliers capture the integration margin. OEMs control the feature roadmap.
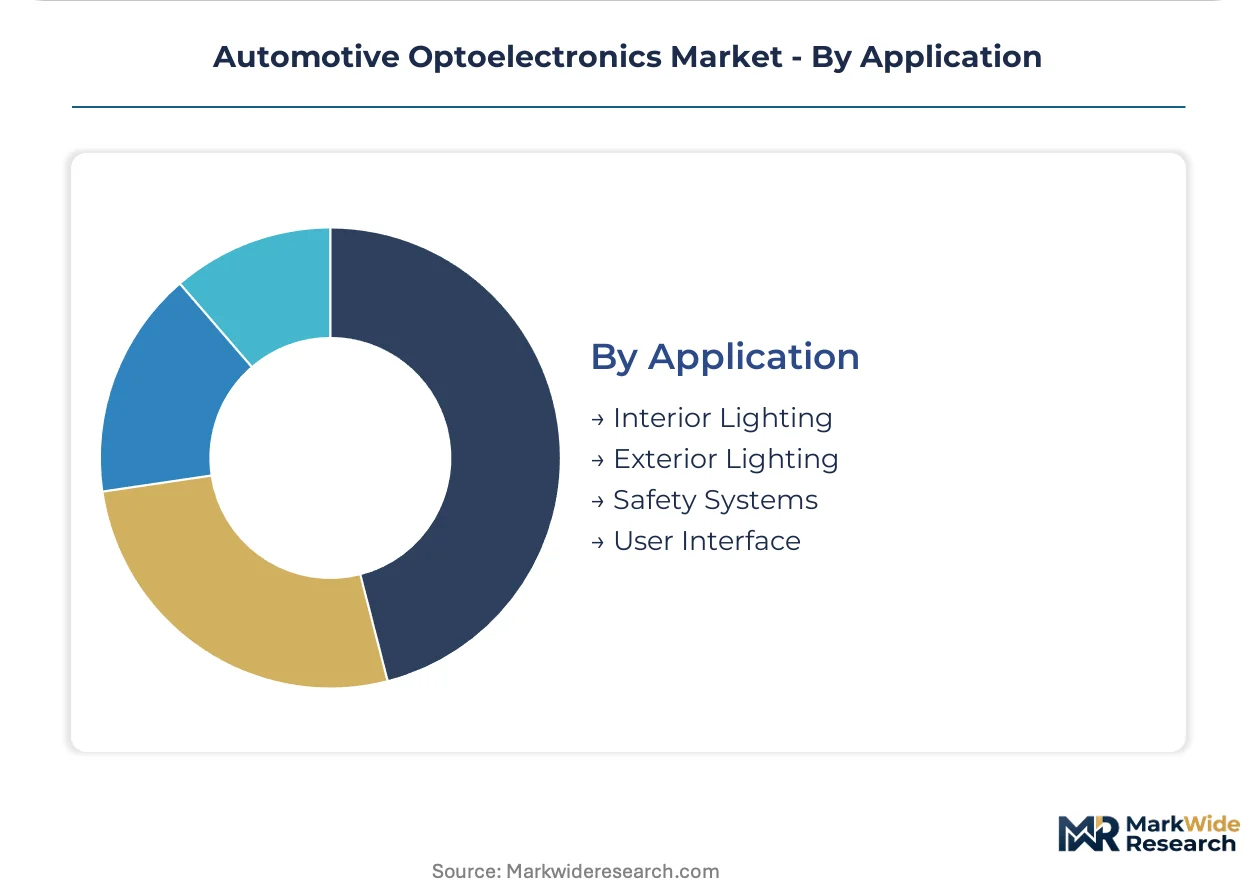
Application:
Safety systems and exterior lighting concentrate regulatory compliance costs, while interior lighting and user interface applications scale through design differentiation.
- Safety Systems:Automatic emergency braking, pedestrian detection, and occupant monitoring through fused photonic sensing. China's GB/T sensor specifications are standardizing LiDAR performance benchmarks across domestic EV programs.
- Exterior Lighting:Headlamps, taillights, and signature lighting with adaptive functionality. NHTSA FMVSS 108 updates are mandating adaptive driving beam capability for five-star safety ratings in North American light-truck platforms.
- Interior Lighting:Ambient and task illumination with color-temperature control.
- User Interface:Touch surfaces, gesture detection, and augmented-reality displays.
Safety Systems drive regulatory pull. Exterior Lighting holds the replacement cycle value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Tier-1 supplier density contrasts with China's vertically integrated EV manufacturing, while the United States concentrates LiDAR validation infrastructure and India attracts assembly investments through production incentives.
China
Domestic EV programs from BYD to NIO are standardizing LiDAR across mass-market price tiers. GB/T sensor specifications from MIIT mandate performance benchmarks for advanced driver-assistance systems. The Yangtze River Delta hosts silicon photonics foundries collapsing unit economics for solid-state ranging modules.
Germany
Premium OEMs in Stuttgart and Munich embed matrix LED and DLP projection engines for Euro NCAP five-star compliance. ECE R48 and R87 regulations constrain beam pattern geometry across European type approvals. Bavaria and Baden-Württemberg concentrate precision manufacturing clusters for micro-optical assembly.
United States
NHTSA FMVSS 108 updates mandate adaptive driving beam functionality for top safety ratings. Light-truck platforms absorb the highest compliance costs due to larger beam pattern coverage requirements. Michigan and California host autonomous-driving validation fleets compressing LiDAR-to-vehicle integration timelines.
Japan
Indium phosphide substrate production clusters expose LiDAR makers to single-source fragility in optoelectronic supply chains. METI coordinates national semiconductor strategies targeting automotive photonics. Kyushu and Chubu regions anchor precision component fabrication for infrared imagers.
India
Production-linked incentives for advanced electronics manufacturing are attracting optoelectronic module assembly investments. The PLI scheme from the Ministry of Heavy Industries targets component localization for domestic EV programs. Tamil Nadu and Gujarat emerge as contract manufacturing hubs for Tier-1 suppliers.
Automotive Optoelectronics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-stack subsystem integrators commanding premium positioning in adaptive lighting while component suppliers capture scale in photonic sensors. The vendor base organizes around three strategic archetypes: European full-stack lighting architects, Asian semiconductor-scale component houses, and precision Japanese material specialists. Consolidation pressure concentrates in LiDAR modules and silicon photonics fabrication. Capacity expansion and strategic partnerships dominate competitive moves as foundry partnerships reshape supply relationships.
Among European full-stack specialists, Valeo SA and ams OSRAM AG occupy positions exemplifying the integrated lighting-and-sensor architecture archetype, while Hella GmbH & Co. KGaA represents the precision German engineering tier in exterior illumination systems.
| Leading Market Players |
|---|
| Valeo SA |
| STMicroelectronics |
| ams OSRAM AG |
| Hyundai Mobis Co., Ltd. |
| Hella GmbH & Co. KGaA |
| Samsung Electronics Co., Ltd. |
| ON Semiconductor Corporation |
| Sony Group Corporation |
| Nichia Corporation |
| Others |
Supply Flow & Price Mechanics
Silicon photonics fabrication migration to foundry-scale production is collapsing unit economics for solid-state LiDAR modules while simultaneously concentrating supply leverage within Chinese and Japanese wafer processing clusters. This dual compression of cost curves and supplier geography is reshaping how Tier 1 integrators negotiate component sourcing and pass through margin pressure.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for photonic sensors and LED modules. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal management IP depth and Euro NCAP certification tier. Cost compression in mass-market infrared imagers is intensifying because domestic Chinese EV programs are standardizing pedestrian-detection hardware. Fleet operators show highest price sensitivity due to per-mile lifecycle cost modeling, while German premium OEMs absorb premium tiers for matrix LED compliance.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Detroit anchor hub-and-spoke patterns for optoelectronic module fulfillment. Manufacturing concentrates in Germany, China, and Japan, with InP wafer fabrication and precision micro-optical assembly anchoring supply. The chain draws from indium phosphide substrates, high-brightness LED dies, and silicon photonics wafers. Single-source vulnerability in Japanese InP foundries exposes LiDAR makers to disruption. Distribution runs through Tier 1 subsystem integrators holding optical design IP and thermal management expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive optoelectronics functions as a stable compounder where regulatory safety mandates create non-discretionary demand pull through successive Euro NCAP and NHTSA protocol updates.
For Market Incumbents: To counter silicon photonics cost compression from Chinese foundries, incumbents should deepen backward integration into precision micro-optical assembly clusters in Bavaria and Baden-Württemberg while securing captive supply of InP substrates through long-term offtake agreements with Japanese wafer producers.
For New Entrants and Emerging Players: Aftermarket calibration service providers represent the most penetrable buyer archetype, as fleet operators unbundle sensor maintenance from vehicle purchase contracts. New entrants should target commercial vehicle leasing channels in the United States with subscription-based per-mile sensing service models, leveraging white-label partnerships with established Tier 1 distributors.
For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturing specialists in India's Tamil Nadu and Gujarat production corridors. Long-term viability rests on PLI scheme duration and domestic EV program scale-up. The signal to watch is Tier 1 supplier announcements of module assembly investments in South Asian contract manufacturing hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Partnership | Chinese and Japanese wafer partnerships collapse unit economics for solid-state LiDAR modules. |
| Software-Defined Lighting Subscription Launch | Valeo SA's adaptive headlamp architecture enables recurring revenue streams from OEM customers. |
| Euro NCAP Certification Investment | Matrix LED and DLP projection engines secure five-star pedestrian safety ratings for German OEMs. |
| India PLI Manufacturing Footprint | Tamil Nadu and Gujarat assembly investments localize optoelectronic module production for domestic EV programs. |
| Cabin Monitoring Fusion Platform | Unified interior sensing platforms converge infrared imagers with radar for driver attention tracking. |
Methodological Framework
Multiple input streams — Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and silicon photonics foundry operators — were reconciled with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA FMVSS 108 filings, and Euro NCAP technical protocols. Bottom-up component demand modeling and top-down vehicle content analysis triangulated market sizing across LED, photonic sensor, laser diode, and OLED product categories.
Data-stream reconciliation anchored the analytical framework across the analysis window, with segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from installed base projections and technology penetration curves, incorporating LiDAR-to-vehicle integration timelines and adaptive lighting regulatory compliance thresholds as industry-specific forecast inputs.
Inputs from Tier 1 procurement systems and foundry capacity announcements were available through the study window; gaps in commercial fleet subscription pricing data introduce uncertainty bands around service revenue projections. Forecasts reflect documented assumptions regarding Euro NCAP enforcement timelines and NHTSA rulemaking schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Quantum Dot Lasers Market
Optoelectronics
EPON ONU Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Light Projector Market
Optoelectronics
United States Optoelectronics Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Infrared Emitter and Receiver Market
Optoelectronics
3D Projector Market
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
Global Optoelectronic Components Market
Optoelectronics
Gunn Diode Market
Optoelectronics
Quantum Dots Market
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
Optoelectronics Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Optical Pulse Sensor Market