
 Quantum Dot Display Market | 2026-2036
Quantum Dot Display Market Size, Share, and Industry Trends Forecast 2026-2036
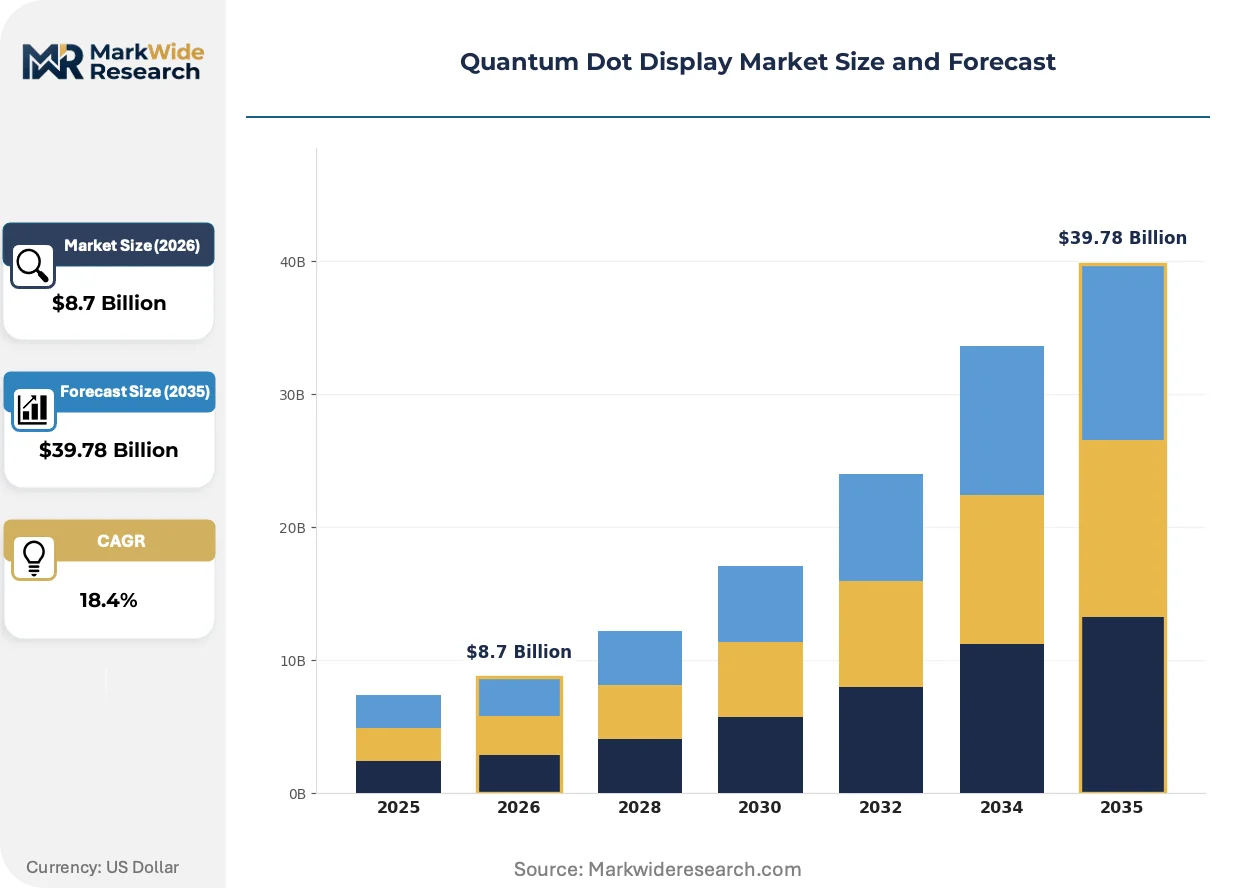
Quantum Dot Display Market Outlook
Software-defined color calibration and subscription-based display tuning services is realigning how panel makers monetize quantum dot hardware. Samsung Display leverages its captive semiconductor supply chain to dominate high-volume QD-OLED production. Nanosys sustains technology leadership in heavy-metal-free quantum dot materials for environmentally restricted markets. BOE Technology Group anchors mainland China's display ecosystem through massive Gen 10.5 fab investments.
Quantum dot displays employ semiconductor nanocrystals measuring 2-10 nanometers that emit precise wavelengths when excited by blue LED backlighting, achieving over 90% Rec. 2020 color gamut coverage for professional and consumer visualization. The technology dimension spans LCD quantum dot enhancement film, QD-OLED hybrid architectures, and emerging electroluminescent approaches where cadmium-free formulations command regulatory preference. Televisions absorb the dominant volume share while automotive displays represent the fastest-growing application as cabin digitization intensifies.
EPA restrictions on cadmium content, EU REACH substance regulations, and China's GB standards for electronic product pollution control collectively constrain material choices and accelerate RoHS-compliant quantum dot chemistry development. South Korea's Ministry of Trade, Industry and Energy promotes domestic QD supply chain independence through targeted industrial policy. Stakeholders must monitor electroluminescent quantum dot maturity against existing photoluminescent architectures to time capital redeployment.
Market Dynamics
The transition from photoluminescent quantum dot enhancement films toward electroluminescent architectures is redistributing capital allocation across the display value chain. Cadmium-free chemistry mandates from multiple regulatory jurisdictions are forcing simultaneous material substitution and process retooling.
Growth Catalysts
- EU REACH substance restrictions:RoHS-compliant quantum dot formulations gain preferential access to European consumer electronics channels, accelerating heavy-metal-free chemistry adoption.
- Automotive cabin digitization:Tier-1 suppliers integrate quantum dot displays into instrument clusters and passenger entertainment systems as vehicle electrification intensifies screen density.
- South Korean industrial policy:Targeted subsidies for domestic QD-OLED supply chain independence reduce import dependency for critical precursor materials.
Market Restraints
- Indium phosphide precursor volatility:Cadmium-free quantum dot manufacturing depends on indium supply concentrated in Chinese smelting operations, creating input cost instability.
- QD-OLED deposition equipment oligopoly:Vacuum thermal evaporation systems for hybrid architectures source from a limited vendor base in Japan and South Korea, constraining capacity expansion timing.
- Blue LED efficiency ceiling:Photoluminescent architectures remain tethered to gallium nitride backlight performance limits that cap overall system efficacy gains.
Strategic Opportunities
- India display manufacturing incentives:PLI scheme subsidies for semiconductor and display fabs attract quantum dot material suppliers to establish local formulation facilities.
- Medical imaging calibration services:Subscription-based color accuracy management for surgical and diagnostic displays creates recurring revenue streams beyond hardware shipment.
- Micro-LED convergence:Quantum dot color conversion layers hybridize with micro-LED emitters to bypass individual die wavelength tuning complexity.
Industry Challenges
- Thin-film encapsulation yield:Electroluminescent quantum dot displays require moisture barrier performance below 10^-6 g/m²/day, demanding atomic layer deposition expertise scarce in existing LCD fabrication workforces.
- Cross-licensing complexity:Quantum dot synthesis patents, display driving algorithms, and manufacturing equipment IP fragment across university spinouts, chemical conglomerates, and equipment vendors, complicating freedom-to-operate assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quantum Dot Display Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Televisions, Monitors, Smartphones, Tablets Technology: LCD, OLED, MicroLED, MiniLED Application: Consumer Electronics, Digital Signage, Automotive Displays, Gaming End User: Residential, Commercial, Industrial, Entertainment |
| Companies Covered | Samsung Display, Nanosys, LG Display, BOE Technology Group, Nanoco Group, AUO Corporation, TCL China Star Optoelectronics Technology, Sharp Corporation, Merck Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quantum Dot Display Market Strategic Shifts
Software-defined color management and electroluminescent material maturation are converging to decouple display performance from fixed hardware specifications. These shifts enable service-layer monetization and challenge incumbent photoluminescent architectures.
Perovskite quantum dot emitters are expanding into narrow-band green and red conversion layers for LCD backlights and emerging electroluminescent prototypes. Chinese panel makers adopt perovskite formulations for cost-sensitive television segments despite stability concerns. The technology is expanding into applications previously reserved for cadmium-based materials, compressing the performance gap between compliant and legacy chemistries.
EPA cadmium content restrictions and EU RoHS substance thresholds are tightening enforcement timelines for consumer electronics. Manufacturers must certify quantum dot films below 100 ppm cadmium threshold to maintain market access. Professional visualization equipment faces accelerated compliance deadlines as California DTSC aligns state-level hazardous substance rules with federal thresholds.
Fleet procurement of calibrated display systems is displacing individual unit purchasing in broadcast and post-production verticals. Major streaming platforms negotiate enterprise color accuracy contracts directly with panel makers, bypassing traditional distribution. This concentration is most visible in Los Angeles and London post-production clusters where shared calibration infrastructure reduces per-seat hardware expenditure.
Quantum Dot Display Market Segmentation
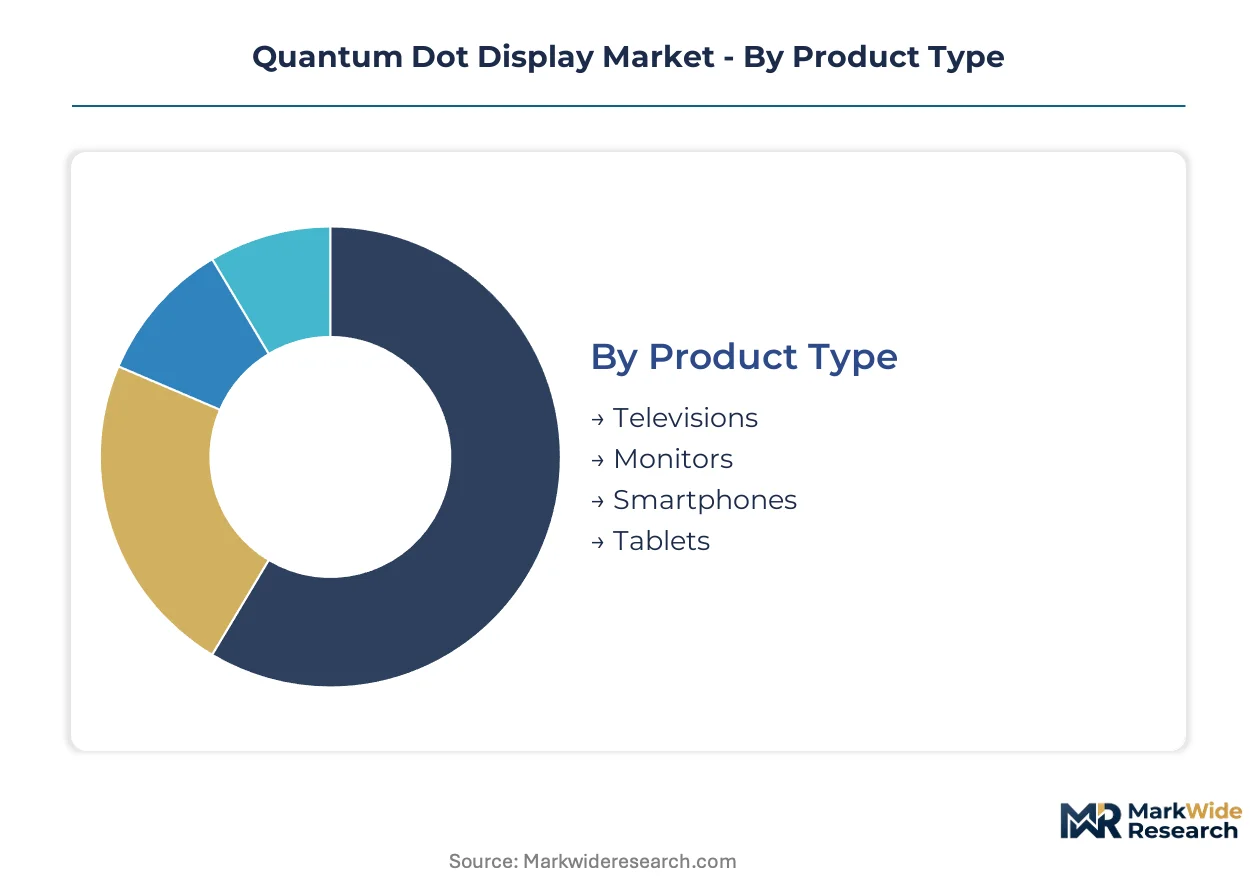
Segmentation in quantum dot displays tracks how cadmium-free chemistry mandates and electroluminescent maturation are redistributing procurement budgets across form factors and use environments. Upgrade cycles vary dramatically: television replacement spans 7-9 years while automotive displays refresh with each vehicle platform.
Product Type:
Television replacement cycles are compressing as 8K resolution and QD-OLED hybrid architectures trigger earlier trade-ins of LCD-based sets.
- Televisions:65-inch and larger QD-OLED panels dominate living room upgrades, with South Korean and Chinese manufacturers capturing volume through Gen 8.5 and Gen 10.5 fab output. Residential demand clusters in premium segments above $2,500 retail as consumers prioritize Rec. 2020 color gamut coverage for streaming content.
- Monitors:Professional visualization workstations drive 27-inch and 32-inch quantum dot adoption for broadcast color grading and medical imaging calibration. Post-production facilities in Los Angeles and London negotiate fleet procurement contracts directly with panel makers, bypassing traditional distribution channels.
- Smartphones:Mini-LED quantum dot backlights penetrate flagship tiers as brands differentiate on HDR performance.
- Tablets:Cadmium-free quantum dot films remain rare in this form factor due to cost constraints and shorter replacement cycles.
Volume placements concentrate in Televisions; the faster expansion belongs to Monitors.
Technology:
Cost tiers separate photoluminescent enhancement films from emerging electroluminescent architectures requiring atomic layer deposition expertise.
- LCD:Quantum dot enhancement films (QDEF) attach to blue LED backlights in mature manufacturing flows, achieving 90%+ DCI-P3 coverage at mid-range price points. Chinese panel makers BOE and CSOT dominate volume production through massive Gen 10.5 investments serving cost-sensitive television markets.
- OLED:QD-OLED hybrids stack quantum dot color conversion layers atop blue OLED emitters, eliminating color filter losses for peak luminance above 2,000 nits. Samsung Display anchors supply through captive semiconductor precursor sourcing and vacuum thermal evaporation equipment partnerships.
- MicroLED:Quantum dot color conversion layers bypass individual die wavelength tuning, reducing micro-LED manufacturing complexity.
- MiniLED:Dense backlight zones with quantum dot films enable localized dimming competitive with OLED black levels at lower burn-in risk.
Revenue concentration sits with OLED; steepest expansion trajectory belongs to MicroLED as convergence with quantum dot conversion matures.
Application:
Customer type determines tolerance for cadmium content and calibration service bundling.
- Consumer Electronics:Television and monitor sales absorb the dominant volume share as EPA cadmium thresholds and EU RoHS enforcement tighten material certification requirements. Retail channels demand sub-100 ppm cadmium documentation for market access.
- Automotive Displays:Instrument clusters and passenger entertainment systems integrate quantum dot films as cabin digitization intensifies screen density per vehicle. Tier-1 suppliers face accelerated compliance timelines as California DTSC aligns state hazardous substance rules with federal thresholds.
- Digital Signage:Outdoor brightness requirements favor quantum dot-enhanced LCD over OLED for durability.
- Gaming:High refresh rate monitors with quantum dot color saturation target esports and enthusiast segments.
Procurement volume clusters in Consumer Electronics; climbing the fastest is Automotive Displays as electrification drives screen proliferation.
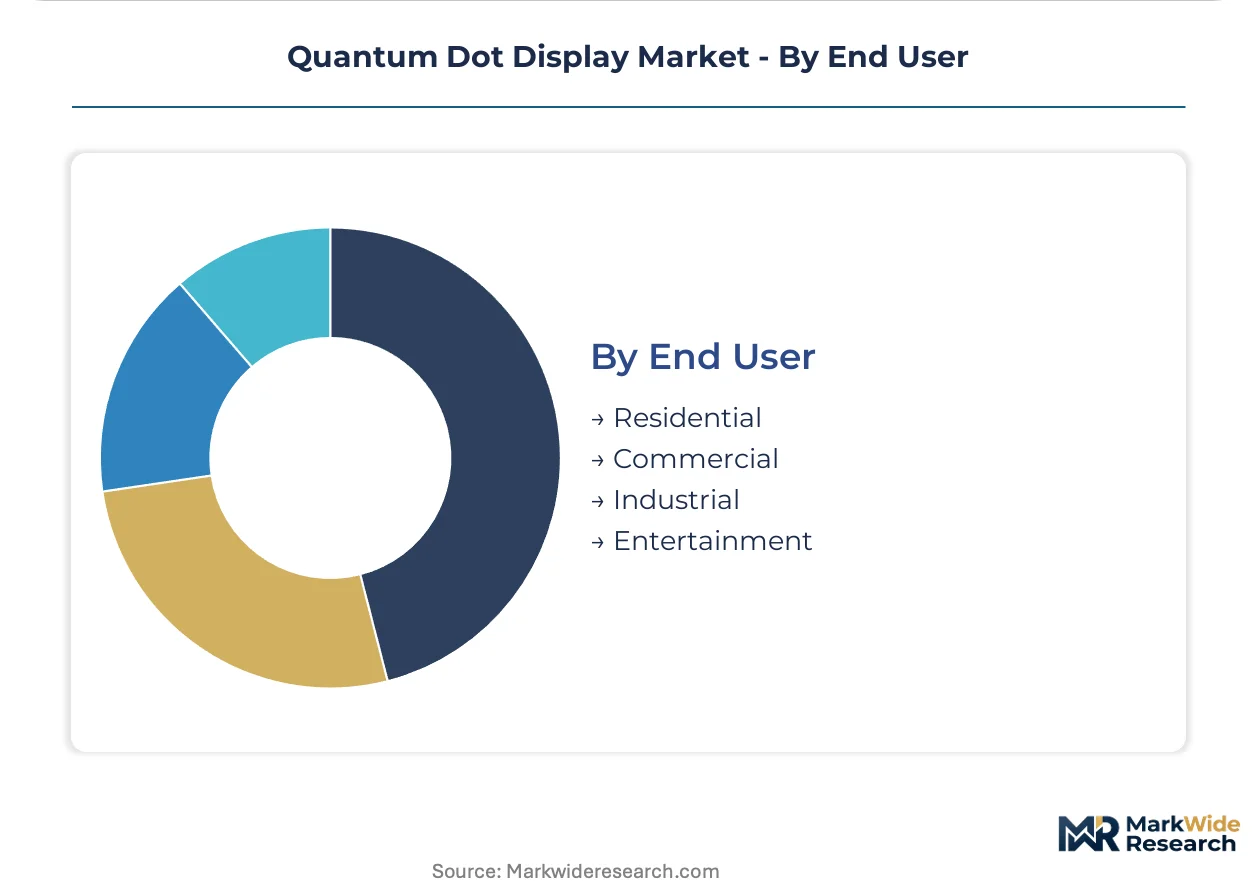
End User:
Margin structures vary by calibration requirements and replacement predictability.
- Residential:Individual purchasers prioritize screen size and streaming app compatibility over color accuracy specifications, compressing margins in mass-market tiers. Subscription-based display tuning services remain underpenetrated in this segment.
- Commercial:Corporate procurement of calibrated display fleets for conference rooms and digital signage demands enterprise color accuracy contracts with direct panel maker relationships.
- Industrial:Medical imaging and broadcast post-production require surgical-grade calibration with recurring service revenue.
- Entertainment:Cinema and live event venues experiment with quantum dot projection and direct-view displays for premium experiences.
Shipment volume concentrates in Residential; gaining share fastest is Commercial as fleet purchasing displaces individual unit acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suwon anchors quantum dot display production through Samsung Display's integrated QD-OLED fabrication complex, drawing precursor chemicals from captive semiconductor supply chains and vacuum thermal evaporation equipment partnerships.
United States
Post-production facilities in Los Angeles negotiate fleet procurement contracts for calibrated quantum dot monitors directly with panel makers. EPA cadmium content restrictions below 100 ppm threshold tighten enforcement timelines for consumer electronics market access. Austin and Boston harbor medical imaging visualization clusters demanding surgical-grade color accuracy.
South Korea
The Ministry of Trade, Industry and Energy subsidizes domestic QD-OLED supply chain independence to reduce import dependency for critical precursor materials. REACH-compliant quantum dot formulations gain preferential positioning in European export channels. Gumi and Paju concentrate Gen 8.5 fab output for premium television segments.
China
BOE Technology Group anchors mainland display ecosystems through massive Gen 10.5 fab investments serving cost-sensitive television markets. GB standards for electronic product pollution control constrain material choices and accelerate RoHS-compliant quantum dot chemistry development. Hefei and Wuhan cluster quantum dot enhancement film manufacturing for LCD backlight integration.
Japan
QD-OLED deposition equipment vendors concentrate vacuum thermal evaporation system production, constraining capacity expansion timing for hybrid architectures. METI industrial policy supports display equipment supply chain resilience. Nagoya and Osaka house precision coating equipment specialists serving atomic layer deposition requirements.
Germany
Merck Group anchors European quantum dot material supply through heavy-metal-free chemistry portfolios aligned with EU REACH substance restrictions. ECHA enforcement of RoHS thresholds accelerates cadmium-free formulation adoption across consumer electronics channels. Frankfurt and Darmstadt cluster specialty chemical R&D for electroluminescent architectures.
Quantum Dot Display Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the quantum dot display value chain. Foundry-scale panel makers with captive semiconductor supply chains dominate QD-OLED volume, while material specialists concentrate heavy-metal-free chemistry development. Three archetypes define competitive positioning: integrated display conglomerates with in-house quantum dot synthesis, independent quantum dot material suppliers licensing to multiple panel makers, and equipment vendors controlling deposition system supply. Capacity expansion and strategic patent cross-licensing constitute the dominant competitive moves as electroluminescent architectures mature.
Among South Korea-based integrated producers, Samsung Display and LG Display occupy positions defining QD-OLED hybrid architecture supply. Within the heavy-metal-free material tier, Nanosys and Nanoco Group exemplify specialists navigating EPA and EU regulatory compliance requirements. Chinese fabricators BOE Technology Group and TCL China Star Optoelectronics Technology represent scale-driven competitors leveraging Gen 10.5 fab investments for cost-sensitive television segments.
| Leading Market Players |
|---|
| Samsung Display |
| Nanosys |
| LG Display |
| BOE Technology Group |
| Nanoco Group |
| AUO Corporation |
| TCL China Star Optoelectronics Technology |
| Sharp Corporation |
| Merck Group |
| Others |
Value Chain & Pricing Dynamics
Tier-1 automotive suppliers concentrate procurement of quantum dot display modules for instrument cluster integration, locking in contract-based long-term offtake agreements that insulate panel makers from spot price volatility in indium phosphide precursors. Fleet purchasers in broadcast post-production verticals negotiate enterprise color accuracy contracts directly with Samsung Display and BOE Technology Group, compressing margins for distributors bypassed in the procurement chain.
Pricing Analysis
Value-based pricing anchored to Rec. 2020 color gamut coverage and surgical-grade calibration accuracy dominates professional visualization segments. Three-tier pricing structure across premium QD-OLED, standard QDEF-enhanced LCD, and economy cadmium-free panels separates certification grades under EPA and EU REACH thresholds. Cost compression in mid-range television tiers intensifies as Chinese Gen 10.5 fab output floods cost-sensitive markets. Residential consumers exhibit highest price sensitivity, while medical imaging facilities prioritize calibration service bundling over unit cost.
Supply Chain Analysis
Regional distribution centers in Suwon, Hefei, and Austin coordinate hub-and-spoke patterns for quantum dot precursor chemicals and finished panels. Manufacturing concentrates in South Korea, China, and Japan, with vacuum thermal evaporation equipment sourcing tethered to Japanese vendors. Indium phosphide, gallium nitride blue LEDs, and heavy-metal-free quantum dot formulations constitute critical input dependencies. Single-source vulnerability in deposition equipment constrains QD-OLED capacity expansion timing. Distribution runs through direct OEM partnerships for automotive and broadcast verticals, supplemented by electronics retail channels for residential demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quantum dot display supply remains constrained by vacuum thermal evaporation equipment oligopoly, propping pricing power for integrated panel makers with captive precursor sourcing. Capacity bottlenecks in atomic layer deposition expertise for electroluminescent architectures extend lead times for premium tier fulfillment.
For Market Incumbents: Extend patent cross-licensing coverage into electroluminescent synthesis methods before university spinouts consolidate freedom-to-operate positions. Deepen backward integration into indium phosphide precursor production to offset Chinese smelting concentration risks. Samsung Display and LG Display should accelerate Gen 8.5 capacity additions in Gumi and Paju to defend share against Chinese Gen 10.5 scale plays. For New Entrants and Emerging Players: EU REACH substance restrictions in Europe open a window for heavy-metal-free quantum dot formulation specialists to capture share in premium consumer electronics channels. Target medical imaging calibration services in Austin and Boston clusters where subscription-based color accuracy management remains underpenetrated. Pursue white-label supply agreements with Tier-1 automotive suppliers facing accelerated California DTSC compliance timelines for instrument cluster integration. For Investors and Strategic Acquirers: The window for entry favors heavy-metal-free material specialists with RoHS-compliant chemistry portfolios and established panel maker offtake relationships. Electroluminescent quantum dot maturity against photoluminescent incumbent architectures signals the inflection point for capital redeployment timing. Long-term viability hinges on atomic layer deposition equipment access and thin-film encapsulation yield improvement trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Patent Cross-Licensing Expansion | Resolves freedom-to-operate fragmentation across Nanosys, Nanoco Group, and university spinout IP portfolios. |
| Backward Integration into Precursor Chemicals | Samsung Display's captive semiconductor supply chain reduces indium phosphide cost volatility exposure. |
| Atomic Layer Deposition Capability Buildout | Enables electroluminescent quantum dot manufacturing yield improvement for moisture barrier performance below 10^-6 g/m²/day. |
| Subscription-Based Calibration Service Launch | Transforms BOE Technology Group and LG Display hardware shipments into recurring revenue streams for broadcast and medical verticals. |
| Automotive Tier-1 Supply Agreement | Locks in platform-level procurement for cabin digitization as vehicle electrification intensifies screen density per vehicle. |
Study Parameters
SEC 10-K filings, ECHA REACH substance registration databases, and Korean Ministry of Trade, Industry and Energy industrial policy announcements formed the secondary backbone for supply chain mapping and regulatory timeline identification. Primary interviews with display panel procurement directors, quantum dot material R&D leads, and automotive Tier-1 supplier engineering heads combined with secondary validation to triangulate capacity expansion plans and technology adoption trajectories. Bottom-up and top-down approaches converged on segment-level demand estimates.
Bottom-up modeling of Gen 8.5 and Gen 10.5 fab output, QD-OLED deposition equipment installation schedules, and cadmium-free quantum dot formulation capacity anchored volume projections across the analysis window. Segmentation dimensions spanned product type, technology architecture, application vertical, and end-user procurement pattern. CAGRs derived from equipment supplier order backlogs, panel maker capex disclosures, and replacement cycle compression factors in television and automotive segments.
The model assumes a particular technology adoption path; alternative pathways for electroluminescent quantum dot maturity would alter the outlook if atomic layer deposition yield improvement lags photoluminescent incumbent cost reduction. Forecasts reflect documented assumptions regarding EPA cadmium threshold enforcement timelines and South Korean industrial policy subsidy continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Video Wall Display Market
Display Technologies
Electronic Display Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Global OLED Market
Display Technologies
Touch Screen Display Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
Computer Monitor Market
Display Technologies
PMOLED Display Market
Display Technologies
Global Monochrome Display Market
Display Technologies
Global 4K Display Resolution Market
Display Technologies
LCD Panel Market
Display Technologies
Display Port Market
Display Technologies
Thin Display Technology Market
Display Technologies
Tablets and Notebook Display Market
Display Technologies
Electrochromic Window Market
Display Technologies
DLP Projector Market