
 Laser Projection Market | 2026-2036
Laser Projection Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Projection Market Intelligence
The rise of industrial marking and simulation systems is restructuring the laser projection market's traditional reliance on entertainment venues. Barco specializes in high-fidelity projectors for simulation centers and large-scale event applications. Panasonic leverages its extensive electronics portfolio to compete across multiple end-user segments. Epson sustains a strong position in the education and corporate presentation spaces with its accessible laser projection technologies.
Laser projection is a display technology that creates images by scanning modulated laser beams or by illuminating an imaging chip. These systems utilize technologies like DLP or LCOS to achieve superior brightness and color gamut compared to lamp-based projectors. Solid-state laser projectors are displacing older gas laser models due to their longer operational life and lower maintenance requirements. Within the technology segment, DLP laser projection continues to command a significant share, particularly in high-volume applications like commercial cinemas and large entertainment venues.
Product safety and market access are governed by a matrix of international and national regulations. The FDA's CDRH in the United States and the CE marking framework in Europe, referencing IEC 60825-1, set critical safety and performance standards for laser-illuminated projectors. Stakeholders must navigate the trade-off between achieving higher lumen output and complying with evolving energy efficiency mandates, such as the EU's Ecodesign requirements.
Market Dynamics
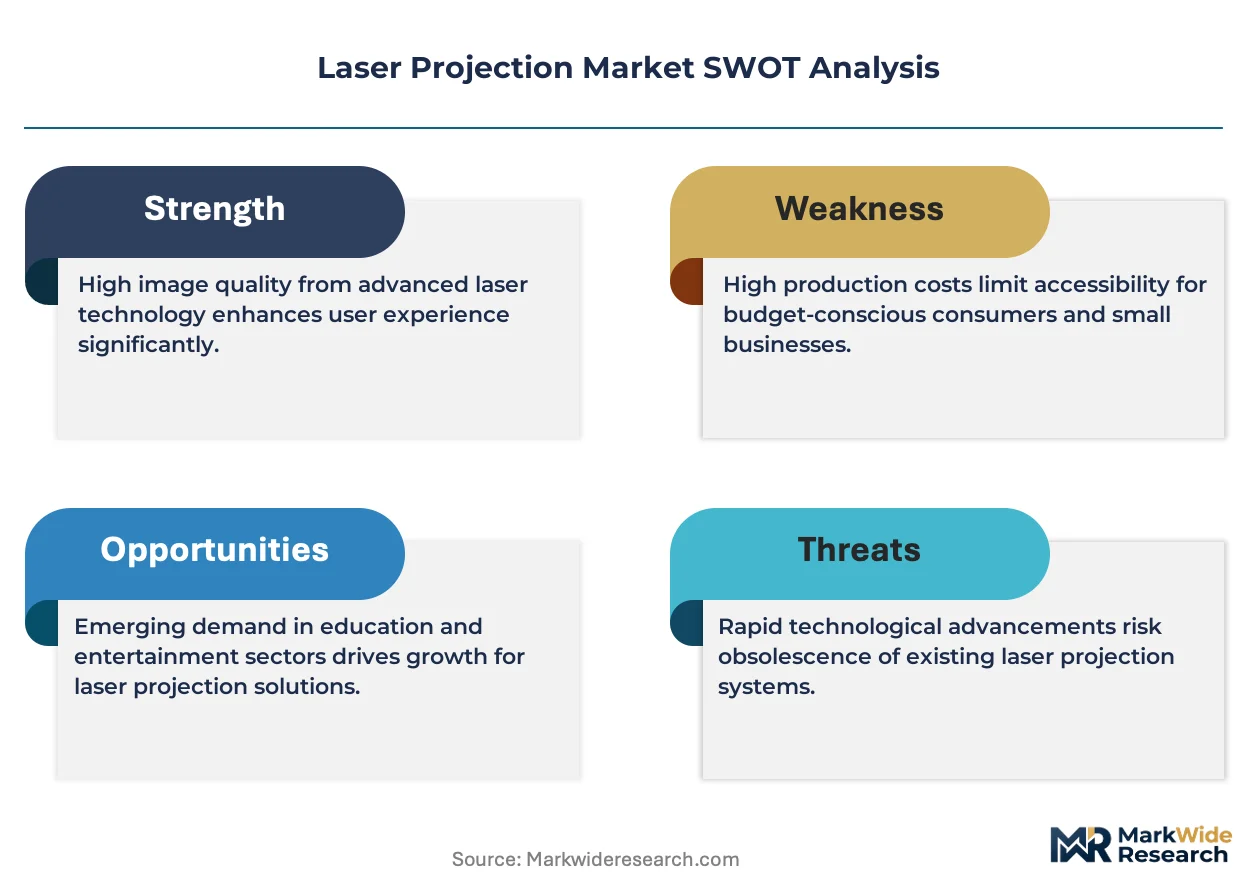
The laser projection market's structure is defined by a dual demand pull from industrial automation and high-fidelity entertainment. This creates distinct development paths for projectors optimized for manufacturing precision versus those designed for cinematic color and brightness, influencing technology choices and regional investment.
Growth Catalysts
- Higher-Resolution Content:The media industry's transition to native 4K and 8K production pipelines necessitates upgraded projection systems in commercial cinemas and home theaters to deliver the intended visual fidelity.
- Advanced Manufacturing Integration:Industrial marking applications in sectors like electronics and automotive use laser projectors for precise, non-contact guidance and verification, driven by Industry 4.0 initiatives for automation.
- Digital Cinema Expansion:Rapid construction of new multiplexes and large-format event venues, particularly within China, creates sustained demand for high-lumen, digital laser projection hardware for new installations.
Market Restraints
- High Initial Capital Outlay:The upfront acquisition cost of solid-state laser projectors remains significantly higher than traditional lamp-based systems, presenting a budget barrier for smaller enterprises, educational institutions, and independent cinemas.
- Stringent Safety Regulations:Compliance with laser safety standards, such as IEC 60825-1 referenced in Europe's CE marking and the FDA's CDRH regulations in the US, adds complexity and cost to product development and market access.
- Energy Efficiency Mandates:Evolving ecodesign regulations, especially in the European Union, create a technical trade-off for manufacturers who must balance the market's demand for higher brightness with strict power consumption limits.
Strategic Opportunities
- Immersive Simulation Systems:Untapped demand exists for high-fidelity laser projection in specialized training and simulation for aerospace, defense, and automotive design, where visual realism is critical for effective outcomes.
- Augmented Reality Convergence:Combining laser projection with sensor technology offers opportunities to create interactive displays for retail advertising, museum exhibits, and collaborative industrial design without requiring head-mounted devices.
- Emerging Market Entertainment Venues:Developing economies in Southeast Asia and Latin America represent new growth frontiers for deploying laser projection in newly built entertainment complexes, theme parks, and corporate event spaces.
Industry Challenges
- Legacy System Integration:Retrofitting older venues with modern laser projectors often requires substantial and costly overhauls of existing electrical, cooling, and signal distribution infrastructure, slowing down the replacement cycle.
- Critical Component Sourcing:The supply of key technologies like DLP and LCOS imaging chips is concentrated among a few specialized manufacturers, creating potential bottlenecks and pricing volatility for projector OEMs.
- Standardization of Metrics:A lack of uniform standards for measuring and reporting key performance indicators like color gamut and brightness consistency over time can create confusion for buyers and complicate direct product comparisons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Projection Market |
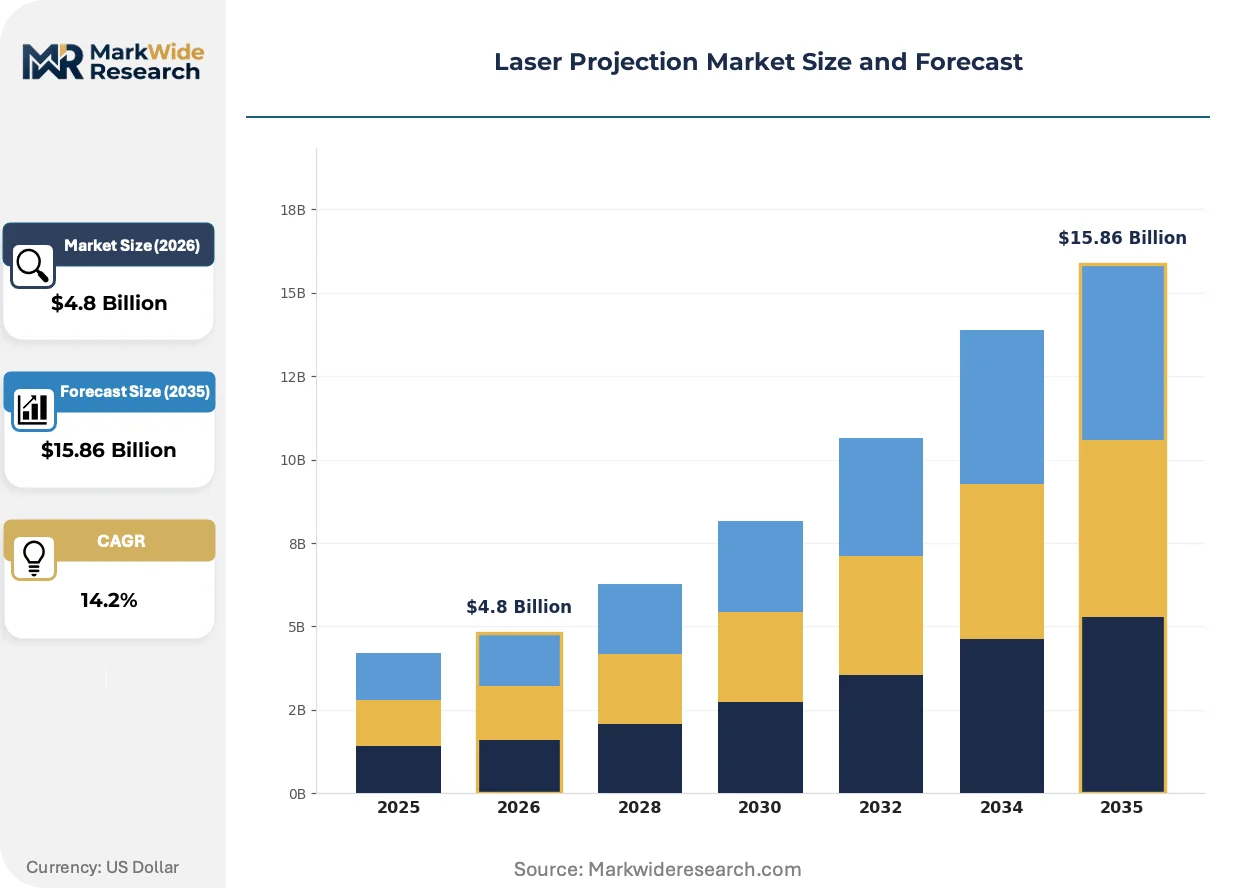
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Laser Projector, Diode Laser Projector, Gas Laser Projector, Solid-state Laser Projector, Fiber Laser Projector Technology: Scanning Laser Display, Laser Phosphor, LCOS Laser Projection, DLP Laser Projection, Laser TV Application: Entertainment Venues, Simulation Systems, Industrial Marking, Advertising Displays, Education Presentations End User: Theaters, Simulation Centers, Manufacturing Plants, Retail Chains, Academic Institutions |
| Companies Covered | Sony, Panasonic, Barco, Canon, Delta Electronics, NEC Display Solutions, Epson, Christie Digital Systems, Dell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Projection Market Strategic Shifts & Innovations
Technological advancements are pushing laser projection towards greater operational longevity and integration with networked systems. This evolution is occurring alongside a regulatory push for greater energy efficiency and a demand-side shift towards more holistic, service-oriented procurement models in key verticals.
Solid-State Light Source Adoption
Solid-state laser phosphor light sources provide a key alternative to legacy gas lasers and replaceable lamps. Commercial and educational buyers are adopting these systems at a steady pace to reduce maintenance cycles and total cost of ownership. This hardware evolution is converging with the integration of on-board processing and network connectivity, transforming projectors into intelligent, remotely managed endpoints within an organization's IT infrastructure.
Ecodesign and Power Efficiency Standards
The European Union’s Ecodesign Directive is imposing stricter limits on the standby and operational power consumption of electronic displays, including projectors. This regulatory pressure compels manufacturers to invest in more efficient laser diodes, power supplies, and cooling systems without compromising on light output. The high-brightness segment, used in large venues, is most affected, driving innovation in thermal management and light engine design to meet performance and compliance goals.
Shift to Integrated Solution Bundles
A notable behavioral change is the move away from standalone hardware purchases towards acquiring complete, integrated solutions. This trend disrupts traditional reseller channels, as large clients in corporate and live event sectors now often prefer contracting directly with manufacturers for packages that include installation, content management software, and long-term service agreements. This demand for bundled offerings is most prominent in North America's advanced digital signage and themed entertainment markets.
Laser Projection Market Segmentation
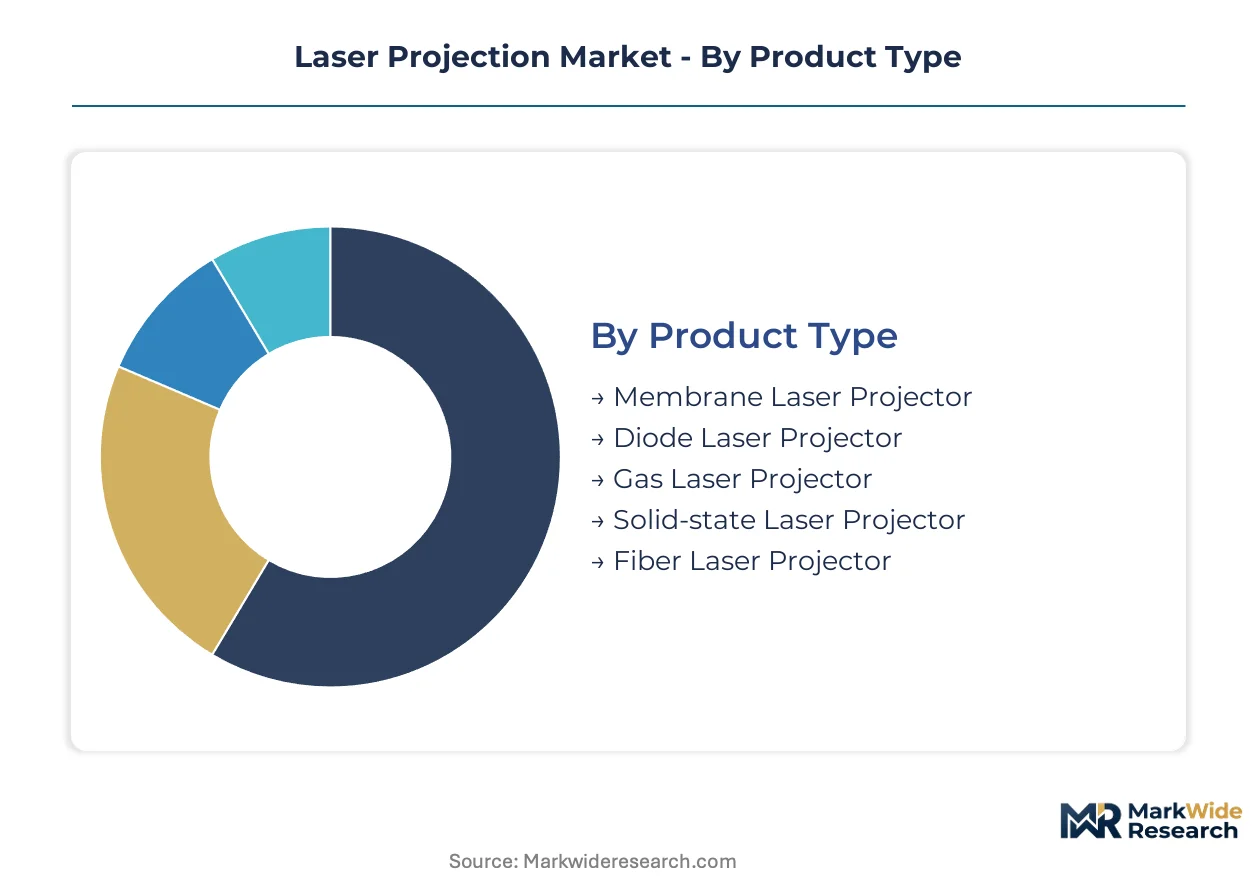
The laser projection market's segmentation reveals distinct demand patterns and technological preferences across various end-use sectors. Understanding these categories is crucial for manufacturers to tailor product development and market strategies effectively. This analysis delineates the core segments driving market evolution.
Product Type:
The transition from older lamp-based systems drives significant upgrade and replacement cycles within product type segmentation.
- Solid-state Laser Projector:Solid-state laser projectors use durable, long-life laser diodes or arrays as their light source, eliminating the need for frequent lamp replacements. Commercial cinemas and large event venues in China are increasingly adopting these systems to reduce operational costs and enhance visual consistency for 4K and 8K content.
- Diode Laser Projector:Diode laser projectors utilize individual laser diodes to generate light, offering precise color control and high efficiency. Educational institutions and corporate presentation spaces in Europe are increasingly selecting these units for their lower maintenance and extended operational lifespan.
- Membrane Laser Projector:Membrane laser projectors incorporate a flexible membrane for image modulation, finding niche applications in specialized display environments.
- Gas Laser Projector:Gas laser projectors, using noble gases for light generation, represent an older technology with higher maintenance and are largely being phased out.
- Fiber Laser Projector:Fiber laser projectors leverage optical fibers to deliver coherent light, offering robustness for industrial and scientific imaging tasks.
Solid-state Laser Projector sits at the top of the volume ranking, with Diode Laser Projector climbing the fastest.
Technology:
Technology choices within laser projection directly influence the system's suitability for specific application requirements, from color fidelity to brightness output.
- DLP Laser Projection:DLP (Digital Light Processing) laser projection employs micromirror arrays to create images, known for high contrast and brightness. Commercial cinemas globally, particularly in emerging markets like Southeast Asia, rely on DLP for its robust performance in large-screen environments and for rendering high-resolution content.
- Laser Phosphor:Laser Phosphor technology combines blue lasers with a yellow phosphor wheel to generate a broad spectrum of colors, balancing performance and cost. Corporate meeting rooms and educational auditoriums across North America are increasingly using laser phosphor for its longevity and consistent brightness without frequent maintenance.
- Scanning Laser Display:Scanning laser displays create images by rapidly scanning modulated laser beams, often used in specialized augmented reality and heads-up displays.
- LCOS Laser Projection:LCOS (Liquid Crystal on Silicon) laser projection offers high resolution and superior color accuracy, favored in high-fidelity simulation and professional visualization systems.
- Laser TV:Laser TV refers to ultra-short throw projectors designed for home entertainment, providing large screen experiences with minimal installation complexity.
DLP Laser Projection continues to dominate high-volume installations, while Laser Phosphor technology demonstrates expanding adoption in commercial and educational segments.
Application:
Different customer types prioritize distinct performance characteristics, shaping the demand for laser projection systems across various applications.
- Industrial Marking:Industrial marking applications use laser projectors for precise, non-contact guidance, inspection, and verification on manufacturing lines. The automotive and electronics sectors in Germany and Japan are driving demand for these systems, aligning with Industry 4.0 initiatives for enhanced automation and quality control.
- Entertainment Venues:Entertainment venues utilize laser projection for large-scale, immersive visual experiences in cinemas, theme parks, and concerts. The rapid expansion of digital cinemas in China and new multiplexes in India fuels sustained demand for high-lumen, color-accurate systems for 4K and 8K content delivery.
- Simulation Systems:Simulation systems employ laser projection for highly realistic visual environments in aerospace training and architectural visualization, requiring extreme fidelity.
- Advertising Displays:Advertising displays leverage laser projection for dynamic, eye-catching visuals in retail environments and public spaces, enhancing brand engagement.
- Education Presentations:Education presentations benefit from laser projectors' brightness and longevity, improving classroom engagement and reducing maintenance in academic institutions.
Industrial Marking applications are experiencing rapid expansion, while Entertainment Venues maintain a significant, established demand base.
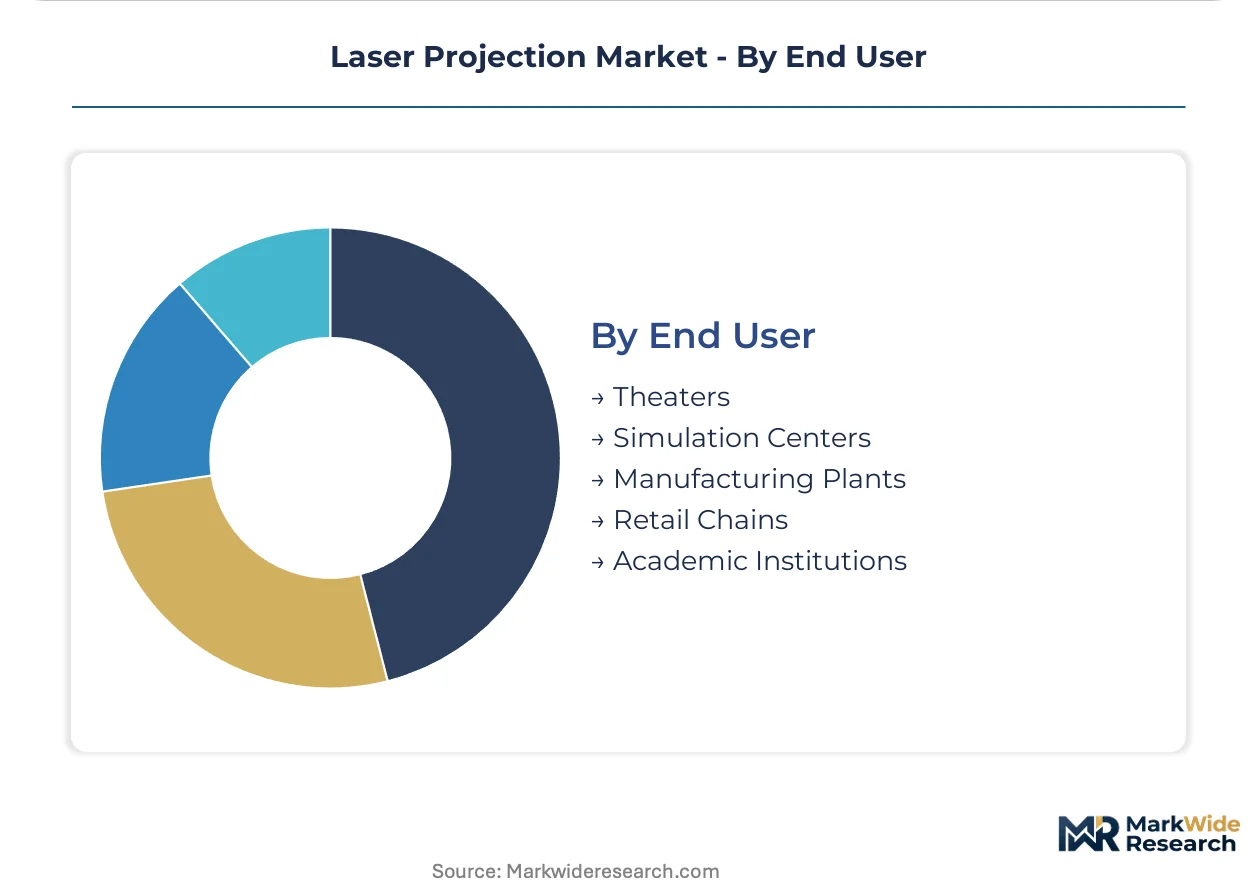
End User:
Profitability considerations and operational scale significantly influence the procurement decisions of different end-user segments within the market.
- Manufacturing Plants:Manufacturing plants integrate laser projectors for process guidance, quality control, and assembly verification, critical for precision industries. Automotive and aerospace manufacturers in the United States increasingly deploy these systems to streamline production workflows and minimize errors in complex assembly operations.
- Theaters:Theaters, including multiplexes and independent cinemas, deploy laser projectors for cinematic exhibition, demanding high brightness, contrast, and color accuracy. Operators in Europe are upgrading to laser systems to provide superior visual fidelity for premium large format screens and reduce long-term operational costs compared to lamp-based alternatives.
- Simulation Centers:Simulation centers require specialized laser projectors for realistic visual training environments in defense, aviation, and healthcare sectors.
- Retail Chains:Retail chains use laser projection for captivating in-store advertising and interactive customer experiences, enhancing brand presence.
- Academic Institutions:Academic institutions adopt laser projectors for lecture halls and classrooms, valuing their durability, low maintenance, and bright image output.
Manufacturing Plants prioritize integration and reliability, while Theaters focus on delivering immersive and visually stunning experiences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage drives shifts in laser projection manufacturing, as companies seek optimal compliance and cost structures across different regions. This dynamic influences investment in diverse regional markets for both production and consumption. Key markets balance strict safety standards with growing demand for advanced display technologies.
China
China's rapid digital cinema expansion and advanced manufacturing initiatives fuel demand for high-lumen laser projectors. GB standards guide product specifications for domestic market access and energy efficiency. The Yangtze River Delta region sees significant investment in manufacturing facilities for these advanced systems and large event venues.
United States
The United States market sees demand from manufacturing plants for precise industrial marking and aerospace simulation systems. FDA's CDRH regulations govern laser product safety and market entry for all laser-illuminated products. Automotive and aerospace manufacturers in Detroit and Seattle drive specialized projection system procurement.
Germany
Germany's advanced manufacturing sector drives demand for industrial marking and high-fidelity simulation systems. The CE marking framework, referencing IEC 60825-1, ensures product safety and market compliance for all laser devices. Bavaria and North Rhine-Westphalia concentrate automotive and machinery firms utilizing laser projection for quality control.
Japan
Japan's electronics and automotive industries require laser projection for precise industrial guidance and verification. METI policies support technological innovation and export competitiveness for advanced display solutions. Tokyo and Nagoya serve as hubs for R&D and manufacturing of specialized laser projection components and systems.
India
India's burgeoning entertainment sector and academic institutions create demand for cost-effective laser projection solutions. BIS standards ensure product quality and safety for imported and domestically produced hardware across various applications. Mumbai's expanding multiplexes and Bangalore's educational campuses drive new installation volumes.
Laser Projection Market Key Industry Players
Capacity expansion dominates the current landscape, as manufacturers scale to meet diverse application needs across industrial and entertainment sectors. The market structure is tiered, with premium providers focusing on high-fidelity simulation and large-venue entertainment, alongside mid-market specialists serving corporate and educational segments. Strategic archetypes include specialized simulation integrators, large-format display solution providers, and industrial automation enablers. Portfolio diversification, strategic partnerships, and geographic expansion into emerging markets are dominant competitive moves.
Among established electronics conglomerates, Panasonic exemplifies a broad portfolio approach, leveraging its extensive electronics capabilities across multiple end-user segments, including both consumer and professional markets. Barco, conversely, represents a specialized high-fidelity provider, focusing on simulation centers and large-scale event applications where visual precision and color accuracy are paramount. Epson occupies a strong position within the accessible laser projection technologies, particularly for education and corporate presentation spaces, offering durable and low-maintenance solutions.
| Leading Market Players |
|---|
| Sony |
| Panasonic |
| Barco |
| Canon |
| Delta Electronics |
| NEC Display Solutions |
| Epson |
| Christie Digital Systems |
| Dell Technologies |
| Others |
Cost & Logistics Intelligence
Solid-state laser projector adoption simultaneously reshapes cost economics and supply concentration within the laser projection market. This transition drives higher initial capital outlay but significantly reduces long-term operational expenses for end-users.
Pricing Analysis
Distributor margins significantly influence the final acquisition cost of laser projection systems for many end-users. The dominant pricing model remains per-unit transactional for accessible technologies, while project-based contracts govern large-scale entertainment and simulation installations. Price differentiation stems from customization levels for simulation systems and the inclusion of extensive after-sales service packages. Pricing softness reflects evolving Ecodesign mandates, compelling manufacturers to balance performance with power consumption. Educational institutions and independent cinemas exhibit the highest price sensitivity, contrasting with aerospace simulation centers.
Supply Chain Analysis
Direct-to-OEM channels and specialized integrators manage the procurement for large-scale laser projection projects, while reseller networks serve corporate and educational segments. Geographic supply concentration for critical components centers on Taiwan and South Korea for DLP and LCOS imaging chips, with significant manufacturing facilities located in China. The supply chain draws from specialized optical components and high-power laser diodes. Single-source vulnerability for advanced imaging chips represents a structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laser projection market presents a margin expansion story, driven by the shift towards premium 4K and 8K projection systems in entertainment and simulation. This evolution allows for higher average selling prices and improved profitability per installation.
For Market Incumbents:Deepen vertical integration into specialized optical component manufacturing to mitigate supply chain vulnerabilities and control input costs. Expand long-term service agreements for large installations, securing recurring revenue streams against emerging low-cost manufacturers. Invest in R&D for advanced thermal management systems to meet evolving energy efficiency mandates without compromising lumen output. Pursue strategic acquisitions of niche technology providers to broaden portfolio capabilities in simulation and industrial marking.
For New Entrants and Emerging Players:Enter via niche application segments such as interactive advertising displays or specialized industrial guidance tools where current solutions are fragmented. Target the education presentation and small-to-medium corporate meeting room segments with accessible, low-maintenance diode laser projectors. A strong go-to-market angle involves offering integrated solution bundles that include installation, content management software, and long-term support. Focus on demonstrating superior total cost of ownership compared to lamp-based alternatives.
For Investors and Strategic Acquirers:Valuations sit cheapest among mid-cap specialists with strong intellectual property in LCOS or scanning laser display technologies. The market demonstrates long-term viability from sustained demand in advanced manufacturing and high-fidelity entertainment over the next decade. Acquisition targets should include integrators focused on immersive simulation systems or firms developing novel augmented reality projection platforms. Increased M&A activity in critical component manufacturing serves as a key signal for market consolidation and future growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | Meets burgeoning demand from digital cinemas and large event venues. |
| R&D in Thermal Management | Addresses Ecodesign mandates while maintaining high lumen output. |
| Strategic Partnership with Chip Manufacturer | Secures supply of critical DLP and LCOS imaging components. |
| Development of Integrated Solution Bundles | Catters to corporate and live event sectors seeking holistic procurement. |
| Geographic Expansion into Southeast Asia | Captures growth from new entertainment venues in developing economies. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the analysis. This involved extensive interviews with R&D directors, procurement leads at manufacturing plants, cinema operators, and simulation center managers. Secondary validation drew from IEC 60825-1 standards, FDA CDRH guidelines, company annual reports, and industry association publications. Bottom-up data from specific projects and top-down market sizing were triangulated for robust insights.
Rate-of-change decomposition segments market expansion drivers by technology adoption cycles and end-user investment patterns. The analytical framework modeled volume and value across the analysis window, considering product type, technology, application, end-user, and regional regulatory impact. Compound annual growth rates were derived from historical trend analysis and future demand projections. Key industry-specific forecast inputs included 4K and 8K content production volumes and industrial automation investment levels.
Inputs from industry reports, regulatory databases, and company disclosures were available through the study window; gaps in granular regional investment data introduce uncertainty bands. Forecasts reflect assumptions regarding technological stability and regulatory consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
2-Ethyl-3,4-Ethylenedioxythiophene Market
Optoelectronics
3D Projector Market
Optoelectronics
Smart Compact Projectors Market
Optoelectronics
Laser Diode Market
Optoelectronics
Optoelectronic Development Tools Market
Optoelectronics
Taiwan Optoelectronics Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Ingaas Avalanche Photodiode Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
South Korea Optoelectronics Market