
 Near-Infrared Spectroscopy Market | 2026-2036
Near-Infrared Spectroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Near-Infrared Spectroscopy Market Intelligence
Pharmaceutical quality control is realigning toward inline process monitoring, pulling capital from offline laboratory setups into integrated production-line spectroscopy. Bruker dominates high-resolution pharmaceutical installations through its R&D intensity in Fourier-transform architectures. FOSS anchors food and beverage applications with specialized dairy and grain analyzers. Thermo Fisher Scientific extends its position through channel control across North American and European distribution networks.
Near-infrared spectroscopy measures molecular absorption between 780 and 2500 nanometers, exploiting overtones and combinations of C-H, O-H, and N-H vibrational bonds to quantify moisture, fat, protein, and active pharmaceutical ingredients without sample destruction. FT-NIR instruments lead the product type landscape due to superior signal-to-noise ratios and wavelength precision in regulated environments. Handheld technology represents the fastest-growing deployment mode, driven by field analysis demand in agriculture and remote chemical screening. Desktop systems retain the deepest margin pools in pharmaceutical research and development applications where validation protocols and software compliance command premium pricing.
FDA process analytical technology guidance and EMA quality risk management frameworks compel pharmaceutical manufacturers to deploy validated spectroscopic methods for real-time release testing. EPA and OSHA exposure monitoring requirements in chemical processing facilities further expand industrial adoption of portable NIR systems. Stakeholders must weigh capital intensity against regulatory enforcement trajectories when prioritizing geographic expansion or application segment entry.
Market Dynamics
Pharmaceutical manufacturers are redirecting capital from offline quality laboratories into integrated production-line spectroscopy systems as FDA process analytical technology enforcement tightens real-time release testing mandates. This structural reallocation is compressing traditional benchtop demand while amplifying inline deployment.
Growth Catalysts
- FDA Process Analytical Technology:Real-time release testing mandates compel pharmaceutical facilities to install validated inline NIR systems for active ingredient verification during manufacturing.
- Asia-Pacific agricultural testing:Grain procurement networks in India and China deploy handheld units for field-level moisture and protein analysis, bypassing centralized laboratory bottlenecks.
- MEMS-based detector miniaturization:Solid-state architectures reduce instrument footprint and power requirements, enabling battery-operated deployment in remote chemical screening applications.
Market Restraints
- Indium gallium arsenide detector costs:InGaAs array pricing volatility constrains margin expansion for portable instrument manufacturers dependent on III-V semiconductor supply.
- Reference standard scarcity:Certified NIST-traceable calibration materials for pharmaceutical applications face extended lead times from limited qualified suppliers.
- Mid-infrared competition:Quantum cascade laser systems encroach on moisture and fat quantification applications where NIR previously held cost advantages.
Strategic Opportunities
- Brazilian sugarcane ethanol:ANVISA-aligned biofuel certification creates demand for portable sucrose and fiber analyzers across decentralized crushing facilities.
- EU Green Deal carbon accounting:Embedded spectroscopic sensors enable real-time biomass composition tracking for renewable fuel lifecycle assessments.
- Cloud-native chemometric platforms:Subscription-based model development tools reduce customer capital barriers while locking in recurring revenue streams.
Industry Challenges
- Chemometrician talent scarcity:Multivariate calibration expertise required for method development outpaces university training pipeline output.
- 21 CFR Part 11 validation timelines:Electronic records compliance documentation extends pharmaceutical installation cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Near-Infrared Spectroscopy Market |
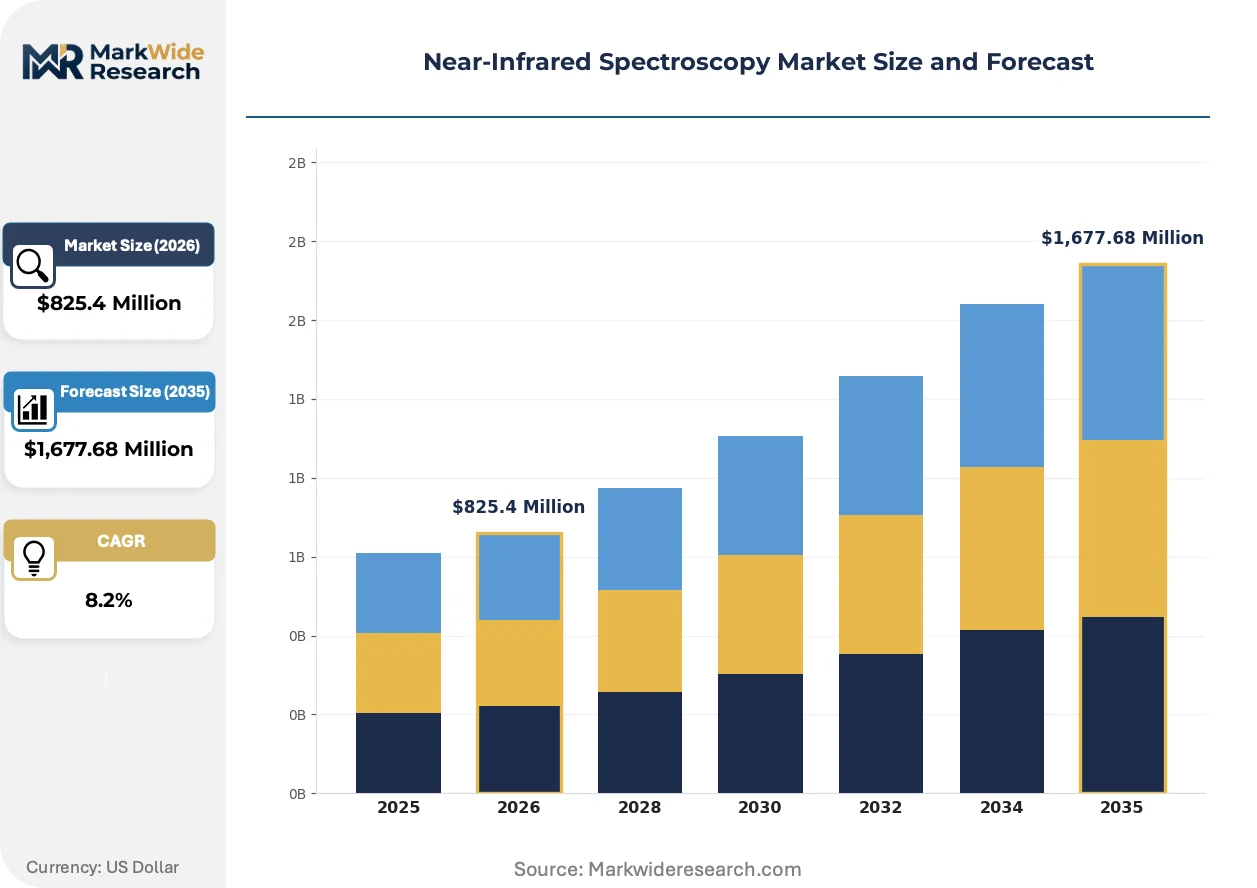
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,677.68 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FT-NIR, Dispersive NIR, Filter NIR, Hybrid NIR End User: Pharmaceuticals, Food & Beverage, Agriculture, Chemicals Application: Quality Control, Process Monitoring, Research & Development, Field Analysis Technology: Optical Fiber, Imaging, Handheld, Desktop |
| Companies Covered | Agilent Technologies, Metrohm, Thermo Fisher Scientific, BUCHI Labortechnik, Shimadzu Corporation, Bruker, FOSS, HORIBA, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Near-Infrared Spectroscopy Market Strategic Shifts & Innovations
Instrumentation architecture is bifurcating between laboratory-grade precision systems and field-deployable miniaturized units, with software-defined spectroscopy eroding hardware differentiation across both tiers.
Hyperspectral imaging arrays spanning 900-1700 nanometers are rewriting quality control economics in pharmaceutical tablet coating operations. Contract manufacturers in Ireland and Singapore deploy these systems for spatially resolved active ingredient distribution mapping. The technology is compressing batch release timelines from hours to minutes while eliminating destructive sampling.
EMA quality risk management frameworks now mandate continuous verification for critical process parameters in sterile injectable manufacturing. European facilities respond by retrofitting lyophilization chambers with fiber-optic NIR probes for residual moisture monitoring. This regulatory compression is accelerating replacement cycles for offline Karl Fischer titration infrastructure.
Equipment-as-a-service contracts displace capital purchase models among mid-tier North American food processors. Third-party providers retain instrument ownership while charging per-sample fees for protein and fat analysis. Dairy cooperatives in Wisconsin and Minnesota lead this transition, preferring operational expenditure treatment for tax and balance-sheet flexibility.
Near-Infrared Spectroscopy Market Segmentation
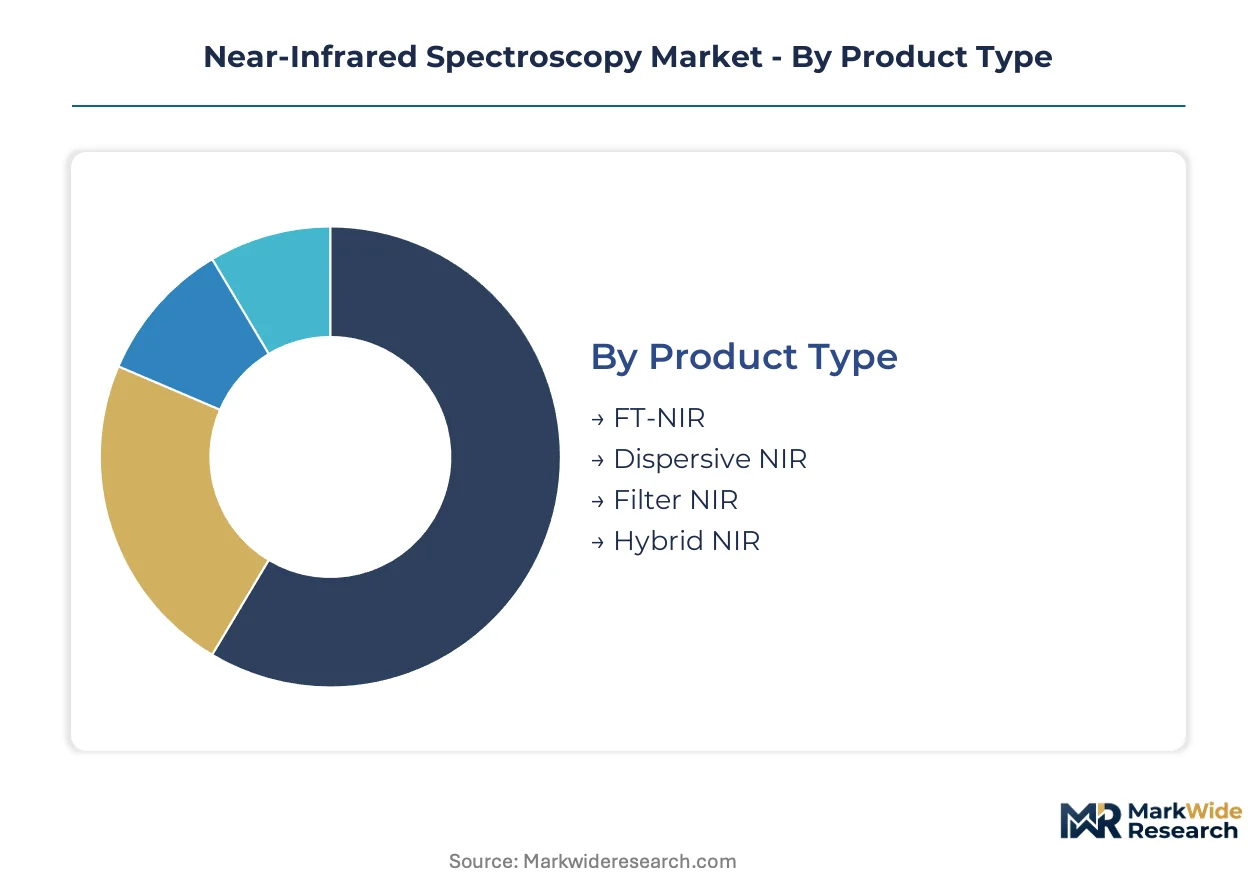
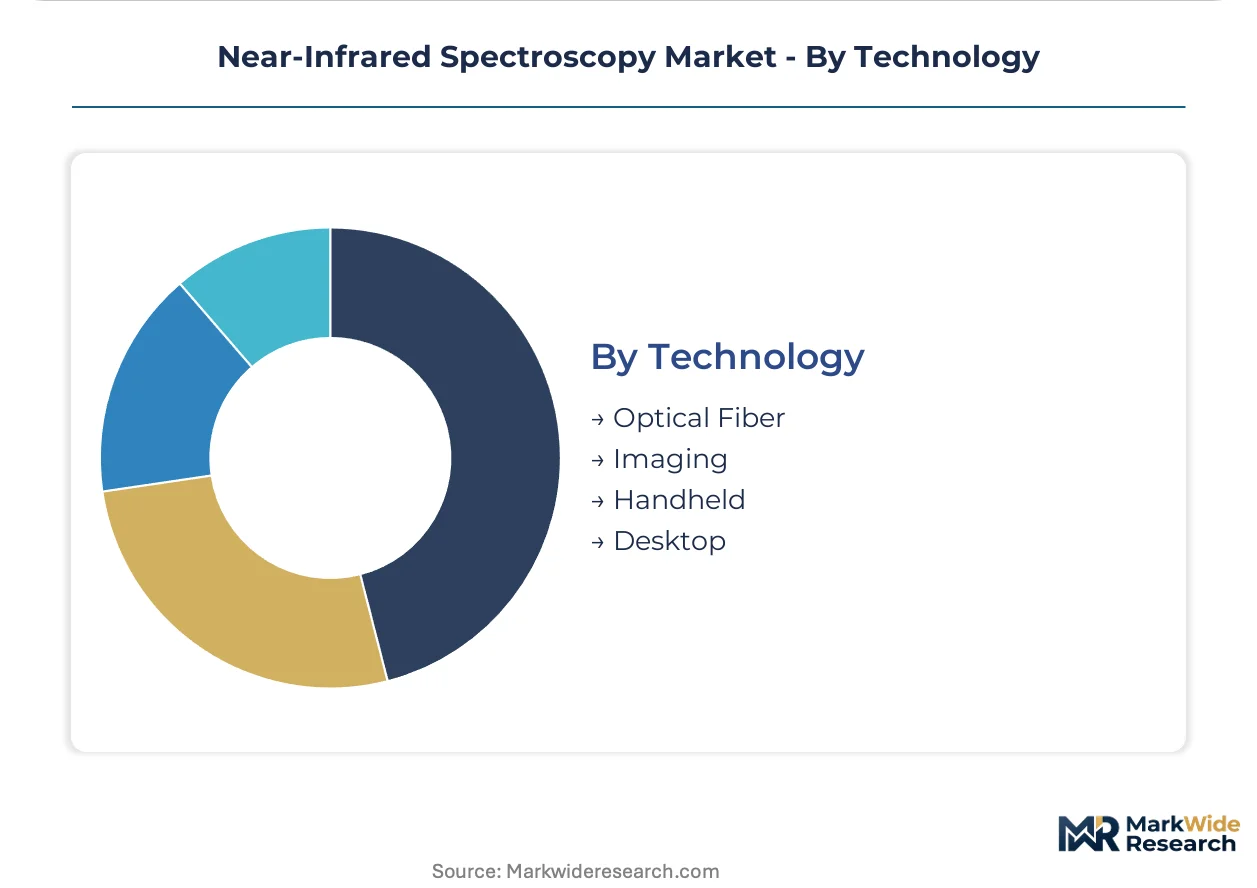
Near-infrared spectroscopy vendors must align instrument architectures with distinct validation requirements and deployment environments. Each segmentation axis reveals divergent margin structures, procurement cycles, and competitive dynamics that reshape portfolio prioritization.
Product Type:
Capital allocation intensity and regulatory validation burden separate buyers across this category.
- FT-NIR:Fourier-transform architectures deliver superior signal-to-noise ratios and wavelength precision through interferometer-based detection. Pharmaceutical manufacturers in the United States deploy these systems for FDA-compliant real-time release testing, absorbing premium pricing for validated software ecosystems and 21 CFR Part 11 documentation packages.
- Dispersive NIR:Grating-based wavelength separation enables cost-efficient multichannel detection for routine compositional analysis. Food processors in Wisconsin and Minnesota favor dispersive systems for inline moisture and fat monitoring, trading absolute precision for throughput economics and simpler maintenance protocols.
- Filter NIR:Discrete wavelength selection via interference filters suits dedicated applications with fixed analyte targets. Grain elevators deploy these units for rapid protein screening at procurement points.
- Hybrid NIR:Combined architectures merge FT precision with dispersive speed for flexible method development. Contract research organizations value the dual-mode capability for client method transfer.
FT-NIR leads volumes today; handheld-enabled filter configurations are gaining share fastest in agricultural field deployment.
End User:
Compliance architecture and sample throughput demands fragment procurement patterns across verticals.
- Pharmaceuticals:Active pharmaceutical ingredient verification and excipient characterization drive demand for validated inline systems. EMA quality risk management frameworks now mandate continuous verification for sterile injectable manufacturing, accelerating fiber-optic probe retrofitting in Irish and Singaporean facilities.
- Food & Beverage:Compositional analysis for moisture, fat, protein, and carbohydrate content dominates procurement. Dairy cooperatives shift toward equipment-as-a-service contracts to convert capital expenditure into operational flexibility.
- Agriculture:Field-level grain testing for moisture and protein bypasses centralized laboratory bottlenecks. Indian and Chinese procurement networks deploy battery-operated units at village collection points.
- Chemicals:EPA and OSHA exposure monitoring requirements expand portable NIR adoption for hazardous material identification. Petrochemical facilities integrate probes for polymerization endpoint detection.
Pharmaceuticals commands the deepest margin pools; agriculture is expanding most quickly through handheld miniaturization.
Application:
Method validation rigor and deployment location separate buyers seeking laboratory precision from those prioritizing speed.
- Quality Control:Laboratory-based batch release testing with full method validation and documentation. Pharmaceutical QC laboratories face compressed timelines as capital redirects toward inline alternatives.
- Process Monitoring:Real-time spectroscopic integration within manufacturing lines for active ingredient verification. FDA process analytical technology enforcement tightens mandates for continuous verification during production.
- Research & Development:Method development and spectral library construction for novel analyte quantification. Academic and industrial R&D groups demand flexible software platforms for chemometric model building.
- Field Analysis:Battery-operated deployment for remote chemical screening and agricultural testing. MEMS-based detector miniaturization reduces power requirements and instrument footprint for portable units.
Quality Control retains installed base dominance; process monitoring is climbing the fastest as regulatory enforcement tightens.
Technology:
Physical form factor and connectivity architecture determine deployment flexibility and maintenance burden.
- Optical Fiber:Remote sampling through fiber-optic probes enables hazardous environment monitoring and lyophilization chamber integration. European sterile injectable manufacturers retrofit fiber systems for residual moisture verification.
- Imaging:Hyperspectral arrays spanning 900-1700 nanometers deliver spatially resolved active ingredient distribution. Pharmaceutical tablet coating operations in Ireland deploy imaging for batch release compression from hours to minutes.
- Handheld:Solid-state architectures with InGaAs detectors enable single-operator field screening. Supply volatility for III-V semiconductor arrays constrains manufacturer margin expansion.
- Desktop:Laboratory-grade precision with thermal stability and vibration isolation for reference method development. Validation protocols and software compliance sustain premium pricing tiers.
Desktop systems anchor current revenue; handheld units are expanding most quickly through Asia-Pacific agricultural penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical manufacturing clusters in Hesse and Baden-Württemberg anchor near-infrared spectroscopy demand through EMA-aligned sterile injectable production. FDA process analytical technology enforcement in the United States and ANVISA biofuel certification in Brazil reshape procurement patterns across distinct regulatory environments.
United States
Pharmaceutical manufacturers in Massachusetts and New Jersey redirect capital toward inline process monitoring systems. FDA process analytical technology guidance tightens real-time release testing mandates for active ingredient verification. Greater Boston contract manufacturing organizations deploy fiber-optic probe systems for lyophilization chamber retrofitting.
Germany
Chemical processing facilities in Ludwigshafen and Leverkusen integrate portable NIR systems for EPA-aligned exposure monitoring. EMA quality risk management frameworks mandate continuous verification for critical process parameters. Bavarian dairy cooperatives shift toward equipment-as-a-service contracts for protein and fat analysis.
China
Grain procurement networks in Henan and Shandong provinces deploy handheld units at village collection points for moisture screening. NMPA pharmaceutical manufacturing standards accelerate inline spectroscopy adoption for generic drug production. Yangtze River Delta contract research organizations demand hybrid architectures for flexible method development.
Brazil
Sugarcane ethanol crushing facilities in São Paulo and Minas Gerais states require portable sucrose analyzers for ANVISA-aligned biofuel certification. Decentralized testing bypasses centralized laboratory infrastructure. Equipment-as-a-service models gain traction among mid-tier processors seeking operational expenditure flexibility.
India
Agricultural procurement networks in Punjab and Haryana deploy battery-operated handheld units for field-level grain testing. CDSCO pharmaceutical manufacturing guidelines drive inline system adoption for active pharmaceutical ingredient verification. Gujarat-based generic drug manufacturers retrofit production lines with fiber-optic probe configurations.
Near-Infrared Spectroscopy Market Key Industry Players
Strategic partnerships dominate the current landscape as instrument manufacturers align with cloud-native chemometric platform developers. The vendor base concentrates around three tiers: precision-focused laboratory specialists, field-deployable miniaturization leaders, and diversified analytical conglomerates with channel control across multiple geographies. Two strategic archetypes define competitive positioning: Fourier-transform architecture specialists serving regulated pharmaceutical environments, and handheld system developers targeting agricultural field deployment. Portfolio diversification and geographic expansion through distribution partnerships represent the dominant competitive vectors.
Among diversified analytical conglomerates, Thermo Fisher Scientific occupies a position exemplifying channel control across North American and European distribution networks. Bruker represents the precision-architecture archetype through its R&D intensity in interferometer-based detection systems. FOSS anchors the application-specialist tier with dedicated food and beverage analytical solutions. These three companies collectively illustrate how competitive positioning stratifies across validation burden, deployment environment, and customer capital preference.
| Leading Market Players |
|---|
| Agilent Technologies |
| Metrohm |
| Thermo Fisher Scientific |
| BUCHI Labortechnik |
| Shimadzu Corporation |
| Bruker |
| FOSS |
| HORIBA |
| PerkinElmer |
| Others |
Cost & Logistics Intelligence
Captive integration into InGaAs detector fabrication anchors both supply security and pricing power for portable instrument manufacturers facing III-V semiconductor volatility. Pharmaceutical buyers absorb premium pricing for validated FT-NIR systems with 21 CFR Part 11 documentation, while agricultural procurement networks in India and China drive cost compression through volume tenders for handheld filter units.
Pricing Analysis
Input-cost pass-through from InGaAs array volatility constrains margin expansion for handheld manufacturers dependent on III-V semiconductor supply. Three-tier pricing structure across pharmaceutical-grade, industrial-standard, and field-economy levels separates buyers by validation burden and software ecosystem depth. Cost compression in agricultural-tier units intensifies because Chinese and Indian procurement networks consolidate village-level purchasing into volume tenders. Dairy cooperatives and grain elevators exhibit highest price sensitivity; sterile injectable manufacturers demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese InGaAs foundries and German interferometer component suppliers for precision FT-NIR architectures. Manufacturing concentration in the United States, Germany, and China shapes regional availability of validated pharmaceutical systems versus cost-optimized agricultural units. Raw material dependencies include indium gallium arsenide detector arrays, precision optical gratings, and fiber-optic probe assemblies. Tariff exposure on III-V semiconductor imports from Taiwan threatens portable instrument cost structures. Distribution runs through specialized analytical instrument distributors with regulatory compliance expertise in North America and Europe, and direct manufacturer relationships in Asia-Pacific agricultural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Near-infrared spectroscopy functions as a geographic-arbitrage play between FDA-enforced pharmaceutical premium pricing in the United States and cost-optimized agricultural volume procurement in Asia-Pacific. Regulatory compliance burden differentials create margin expansion opportunities for manufacturers with dual certification capabilities.
For Market Incumbents: Deploy equipment-as-a-service contracts to convert capital expenditure preferences among mid-tier food processors into recurring revenue streams. Backward integration into InGaAs detector supply buffers margin compression from III-V semiconductor pricing volatility. Channel control investments in North American distribution networks defend position against emerging cloud-native chemometric platform competitors. For New Entrants and Emerging Players: Brazilian sugarcane ethanol testing cooperatives represent an underserved buyer archetype seeking ANVISA-aligned portable sucrose analyzers without centralized laboratory infrastructure. Cloud-native chemometric subscription models penetrate mid-tier pharmaceutical contract manufacturers lacking in-house multivariate calibration expertise. Geographic expansion through equipment-as-a-service partnerships with dairy cooperatives in Wisconsin and Minnesota offers lowest customer acquisition friction. For Investors and Strategic Acquirers: Roll-up economics work for regional analytical instrument distributors with regulatory compliance expertise because EMA and FDA validation requirements create sticky customer relationships resistant to price competition. Acquisition targets include hybrid-architecture specialists serving contract research organizations and MEMS-based miniaturization firms enabling battery-operated field deployment. Watch for inflection when ANVISA biofuel certification mandates expand beyond São Paulo state to northern crushing facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Supply | Captive InGaAs fabrication insulates margins from III-V semiconductor pricing volatility. |
| Equipment-as-a-Service Launch | Per-sample pricing converts agricultural buyer capital constraints into recurring revenue. |
| Cloud-Native Chemometric Platform | Subscription model development tools reduce pharmaceutical customer validation timelines. |
| Fiber-Optic Probe Retrofit Partnership | Lyophilization chamber integration captures EMA-mandated sterile injectable monitoring demand. |
| ANVISA Certification Investment | Biofuel testing alignment opens Brazilian sugarcane ethanol procurement networks. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical quality control directors, food processing plant managers, agricultural procurement officers, and analytical instrument distributors with secondary validation against FDA guidance documents, EMA quality risk management frameworks, NIST calibration standard references, and SEC filings from publicly traded instrument manufacturers. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates.
Comparable-period anchoring used historical pharmaceutical capital expenditure patterns and agricultural procurement cycle data to bound projection uncertainty across the analysis window. Segmentation modeling incorporated product type architecture, end-user vertical compliance requirements, application validation rigor, and technology deployment form factor. CAGRs derived from instrument shipment tracking and replacement cycle analysis, with pharmaceutical real-time release testing mandates and MEMS miniaturization trajectories serving as primary demand drivers.
Underlying measurement precision varies by segment; pharmaceutical inline process monitoring carries tighter precision than agricultural field testing due to regulatory documentation requirements. Forecasts reflect assumptions about FDA enforcement continuity, InGaAs supply stability, and chemometric talent pipeline expansion that could shift if semiconductor fabrication capacity reallocates or university training output accelerates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
3D Touch Probe Market
Analytical Instruments
Microanalysis Sample Preparation Systems Market
Analytical Instruments
Global Ultrapycnometer Market
Analytical Instruments
Seawater Refractometers Market
Analytical Instruments
Digital Multichannel Analyzer Market
Analytical Instruments
Signaling Analyzer Market
Analytical Instruments
Elemental Analyzer Market
Analytical Instruments
Europe Handheld Spectrum Analyzer Market
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
Europe Dissolved Gas Analyzer Market
Analytical Instruments
AFM Probe Market
Analytical Instruments
Spectroscopy Software Market
Analytical Instruments
Coating Thickness Measurement Instruments Market
Analytical Instruments
ICP-MS System Market
Analytical Instruments
Trace Chemical Detector Market
Analytical Instruments
Benchtop Ph Meters Market