
 Light Projector Market | 2026-2036
Light Projector Market Size, Share, and Industry Trends Forecast 2026-2036
Light Projector Market Outlook
Software-defined brightness calibration and cloud-connected maintenance subscriptions is pivoting how projector vendors monetize hardware over time. Seiko Epson Corporation leverages its proprietary 3LCD manufacturing infrastructure to sustain component cost advantages. Hisense anchors large-format laser projection demand through cinema and commercial display channels. XGIMI competes aggressively in portable smart projector segments with integrated streaming platforms.
A light projector is an optoelectronic device that modulates an illumination source through a spatial light modulator to cast magnified images onto a surface, with luminance typically measured in ANSI lumens and contrast ratios exceeding 1000:1 in professional-grade units. Its primary purpose spans visual presentation, entertainment display, and immersive environmental projection across institutional and consumer settings. DLP and laser segments command premium positioning due to color accuracy and lamp-free operational lifespans, while LCD occupies volume-driven education procurement channels. Ultra short throw technology concentrates growth in residential home theater applications where spatial constraints dominate purchase criteria.
FCC equipment authorization requirements govern radio-frequency emissions from smart projectors sold in the United States, while CE marking under EU RoHS and REACH directives restricts hazardous substances in optical assemblies and power electronics exported to Europe. Japan's METI enforces energy efficiency standards that shape thermal management and solid-state illumination design priorities for manufacturers targeting that market. Stakeholders must monitor how fragmented regulatory compliance costs across multiple jurisdictions influence regional product variant strategies and margin structures.
Market Dynamics
Laser phosphor and solid-state illumination architectures are compressing replacement cycles while METI energy efficiency mandates in Japan force thermal redesigns that cascade through global product lineups. Vendors now face simultaneous pressure to extend operational lifespan and reduce power draw.
Growth Catalysts
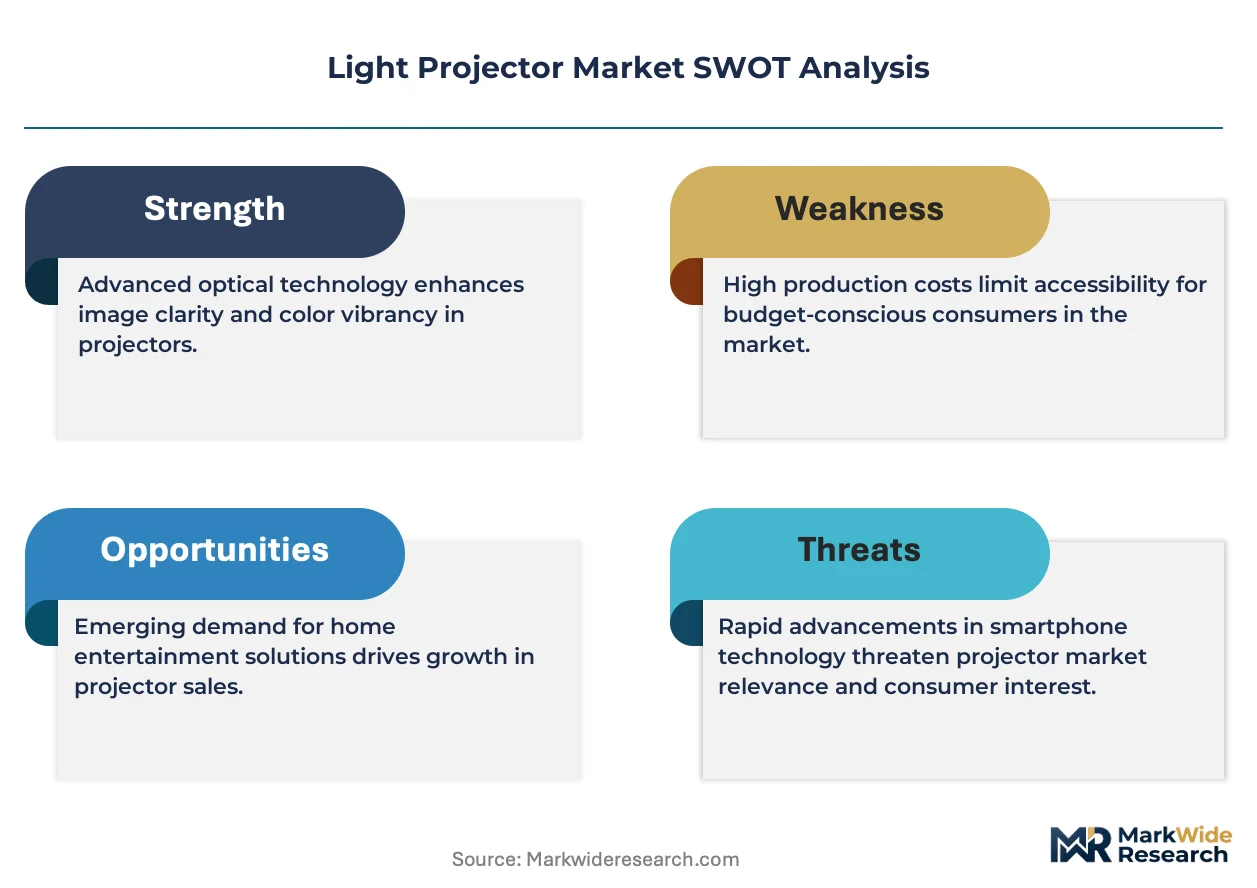
- Ultra short throw form factors:Residential home theater installations in spatially constrained urban apartments across China and Japan favor throw ratios below 0.25:1, eliminating ceiling mounting requirements.
- REACH substance restrictions:EU RoHS and ECHA hazardous substance limits on mercury-containing lamps accelerate solid-state light source transitions in optical assemblies exported to Europe.
- Cloud-connected firmware ecosystems:Over-the-air brightness calibration and predictive maintenance subscriptions create recurring revenue streams that improve hardware margin profiles.
Market Restraints
- DMD chip supply concentration:Texas Instruments maintains captive production of digital micromirror devices, creating single-source vulnerability for DLP-based projector manufacturers.
- Rare earth phosphor cost volatility:Cerium-doped yttrium aluminum garnet and europium-doped nitride phosphors face price swings tied to Chinese export quotas on rare earth elements.
- Ambient light interference:Uncontrolled illumination environments in commercial education deployments limit perceived contrast ratios and compress effective ANSI lumen requirements.
Strategic Opportunities
- Immersive environmental projection:Museums, themed entertainment venues, and corporate experience centers in the United States deploy edge-blended multi-projector arrays for 360-degree visual environments.
- India BIS certification alignment:Harmonized safety and electromagnetic compatibility standards reduce technical barriers for manufacturers entering Indian education and government procurement channels.
- Laser-RGB tri-color convergence:Discrete red, green, and blue laser diodes eliminate color wheels and phosphor wheels, enabling wider color gamut coverage for cinema-grade applications.
Industry Challenges
- Optical engineer talent scarcity:Specialized expertise in freeform lens design and thermal management for high-lumen density engines remains concentrated in Japanese and German industrial clusters.
- FCC equipment authorization timelines:Radio-frequency emissions testing for smart projectors with embedded Wi-Fi and Bluetooth modules extends time-to-market by 8-14 weeks for United States launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Projector Market |
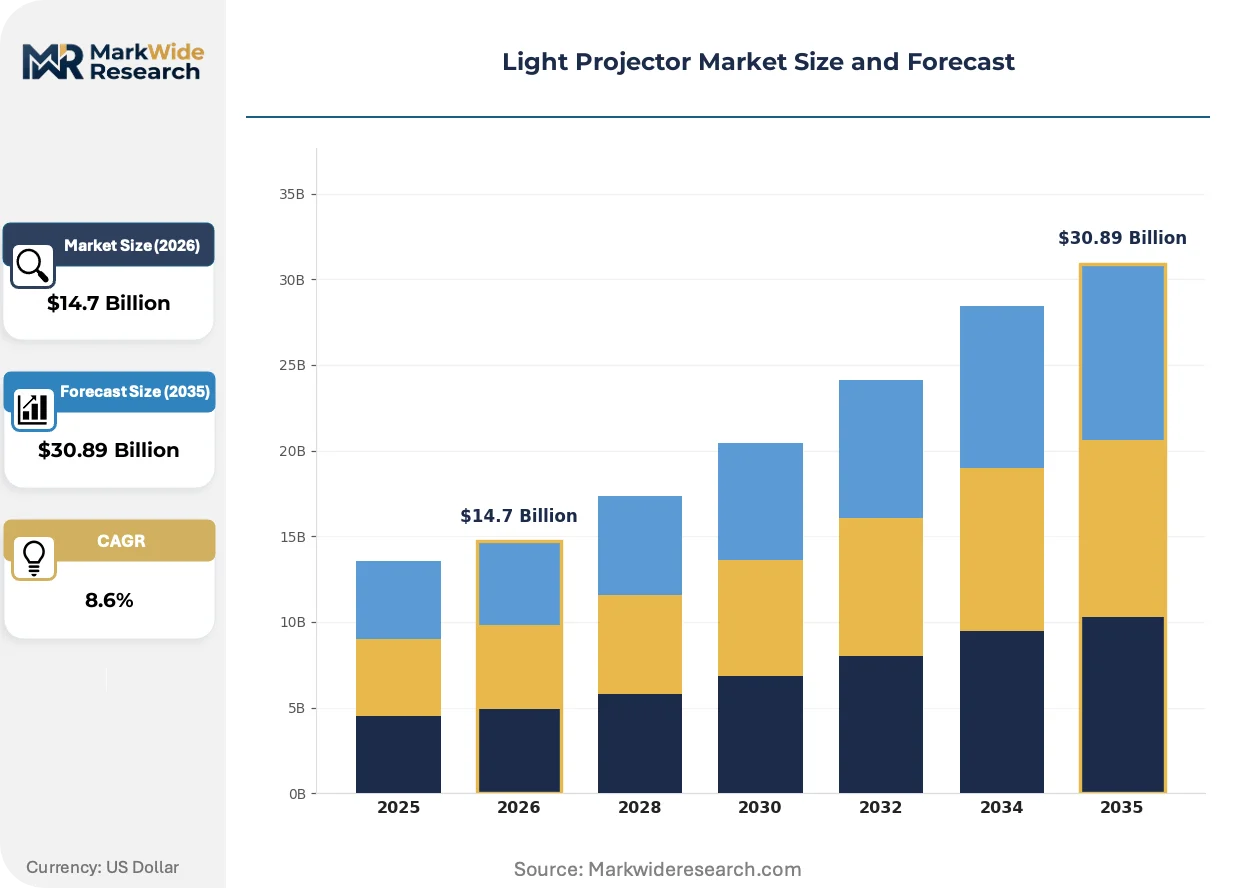
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DLP, LCD, LED, Laser Application: Education, Home Theater, Corporate, Events End User: Schools, Businesses, Entertainment Venues, Households Technology: 3D Projection, High Definition, Short Throw, Ultra Short Throw |
| Companies Covered | Optoma Technology Corp, JMGO, Seiko Epson Corporation, XGIMI, ViewSonic Corporation, Sony Group Corporation, Hisense, Mitsubishi Electric Corporation, BenQ Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Projector Market Strategic Shifts
Software-defined functionality and solid-state illumination are collapsing the traditional hardware-refresh cycle while regulatory pressure on hazardous substances accelerates technology transitions.
RGB laser diode arrays are converging with phosphor-converted laser architectures in mid-lumen professional projectors. Cinema exhibitors and large-venue installers adopt hybrid approaches that balance color purity against cost. This convergence is compressing the premium segment's price floor while extending performance differentiation downward.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases affect cooling system designs for high-brightness projectors above 10,000 ANSI lumens. Manufacturers substitute heat pipe assemblies and vapor chamber thermal solutions for traditional refrigerant-based cooling. Professional installation and rental markets in Germany and France absorb compliance costs through extended service contracts.
Enterprise and education buyers unbundle hardware acquisition from maintenance and lamp replacement contracts. Procurement teams favor total-cost-of-ownership models that capture 10-year operational expenses. This behavioral shift concentrates purchasing authority with facility management departments rather than IT or AV specialists, particularly visible in United States K-12 and higher education verticals.
Light Projector Market Segmentation
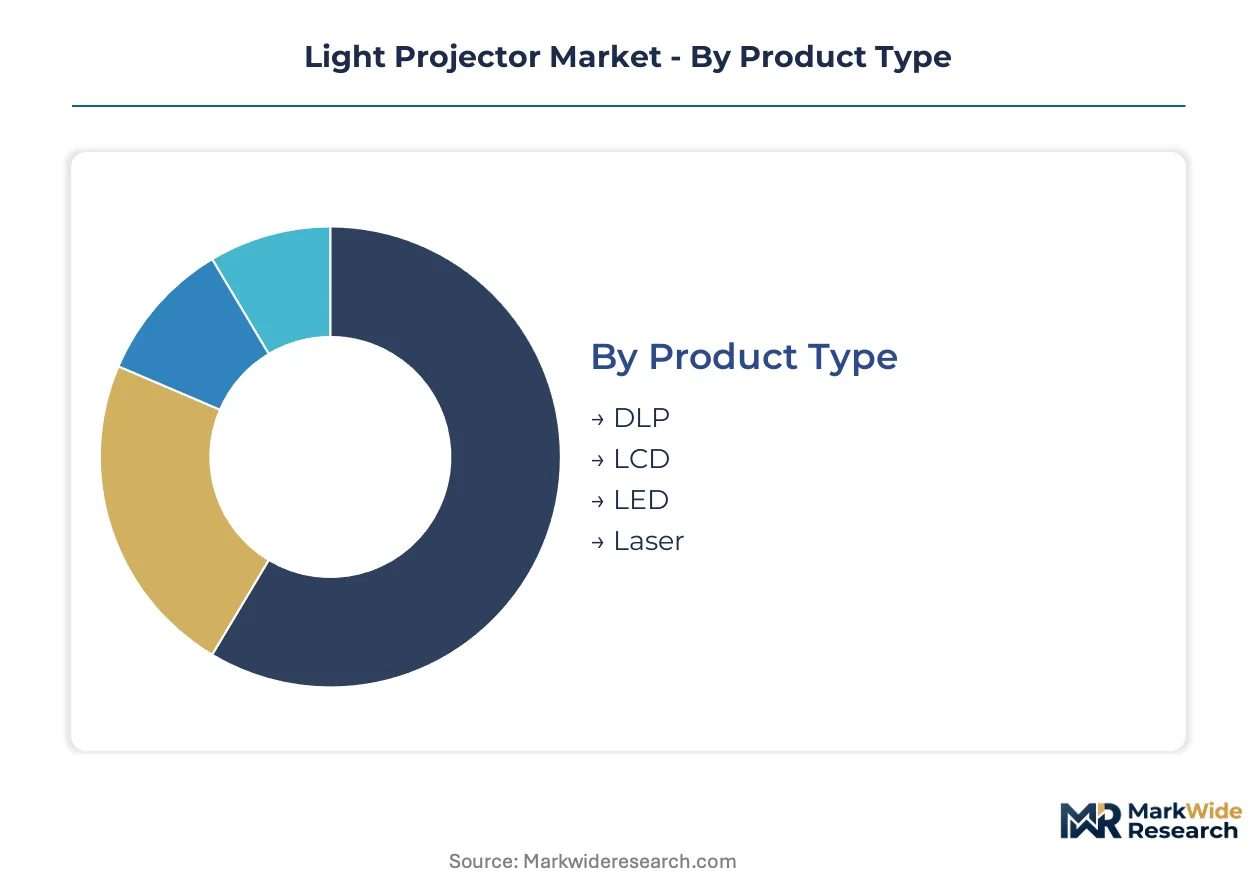
Segmentation in the light projector market reveals how technical specifications, deployment environments, and user requirements fragment demand across distinct procurement channels. Understanding these divisions exposes where margin concentration and volume scale diverge.
Product Type:
Laser and LED architectures command premium positioning through solid-state reliability, while DLP and LCD technologies dominate procurement volume in institutional channels.
- Laser:Phosphor-converted and RGB tri-color diode configurations eliminate lamp replacement cycles and deliver color gamut coverage exceeding Rec. 709 standards. Cinema exhibitors in the United States and commercial installation firms in Germany absorb higher upfront costs for 20,000-hour operational lifespans. Newer deployment is concentrated in laser architectures as mercury lamp restrictions tighten.
- DLP:Texas Instruments' digital micromirror device technology enables high native contrast ratios through mechanical light modulation. Education procurement in China and India favors DLP for portable classroom applications where dust-sealed optical engines reduce maintenance. Mature deployment sits with DLP.
- LCD:3LCD and single-panel LCOS architectures from Japanese manufacturers deliver color brightness parity with white brightness. Corporate conference room installations in Japan and South Korea specify LCD for presentation clarity under fluorescent ambient conditions.
- LED:Discrete RGB LED arrays serve pico-projector and embedded applications where thermal budgets constrain engine size. Portable entertainment devices targeting Chinese and Indian consumer segments exploit LED's instant-on capability and minimal power draw.
Price stratification separates laser from LED at the premium extreme, with DLP and LCD occupying overlapping mid-market territory.
Application:
Residential and institutional use cases impose divergent constraints on brightness, connectivity, and form factor specifications.
- Home Theater:Ultra short throw ratios below 0.25:1 eliminate ceiling mounting in spatially constrained urban apartments across Tokyo, Shanghai, and New York. Integrated streaming platforms and automated keystone correction reduce installation friction for non-technical users. This segment is expanding most quickly.
- Education:K-12 and higher education procurement in the United States favors 3,000-5,000 ANSI lumen models with network management capabilities. District-level purchasing authorities negotiate volume discounts while standardizing on interchangeable lamp modules.
- Corporate:Enterprise AV departments specify wireless presentation systems and HDMI-CEC compatibility for hybrid meeting rooms. Facility management teams in German and French multinationals prioritize 10-year total cost of ownership models over acquisition price.
- Events:Rental and staging companies deploy 10,000+ lumen large-venue projectors for temporary outdoor installations and immersive mapping projections. Edge-blending and geometric correction software licenses represent recurring revenue streams distinct from hardware.
Procurement authority concentrates with IT departments in corporate settings, while education buyers increasingly report to facilities operations.
End User:
Budget cycles and technical sophistication vary sharply across institutional versus consumer purchasers.
- Households:Urban apartment dwellers in China and Japan drive demand for compact laser projectors with built-in Android TV platforms. Seasonal purchasing peaks align with entertainment hardware upgrade cycles.
- Schools:Public education systems in India and the United States operate on fiscal year procurement calendars with formal bidding requirements. BIS certification alignment reduces technical barriers for manufacturers entering Indian government channels.
- Businesses:Small and medium enterprises favor all-in-one projector-speaker combinations for huddle spaces. Large corporations standardize on fleet management software for remote monitoring across distributed offices.
- Entertainment Venues:Museums and themed attractions in the United States deploy multi-projector arrays for 360-degree immersive environments. Extended service contracts absorb compliance costs for F-Gas Regulation thermal system redesigns.
Consumer segments exhibit shortest replacement cycles, while institutional buyers extend hardware lifespans through maintenance contracts.
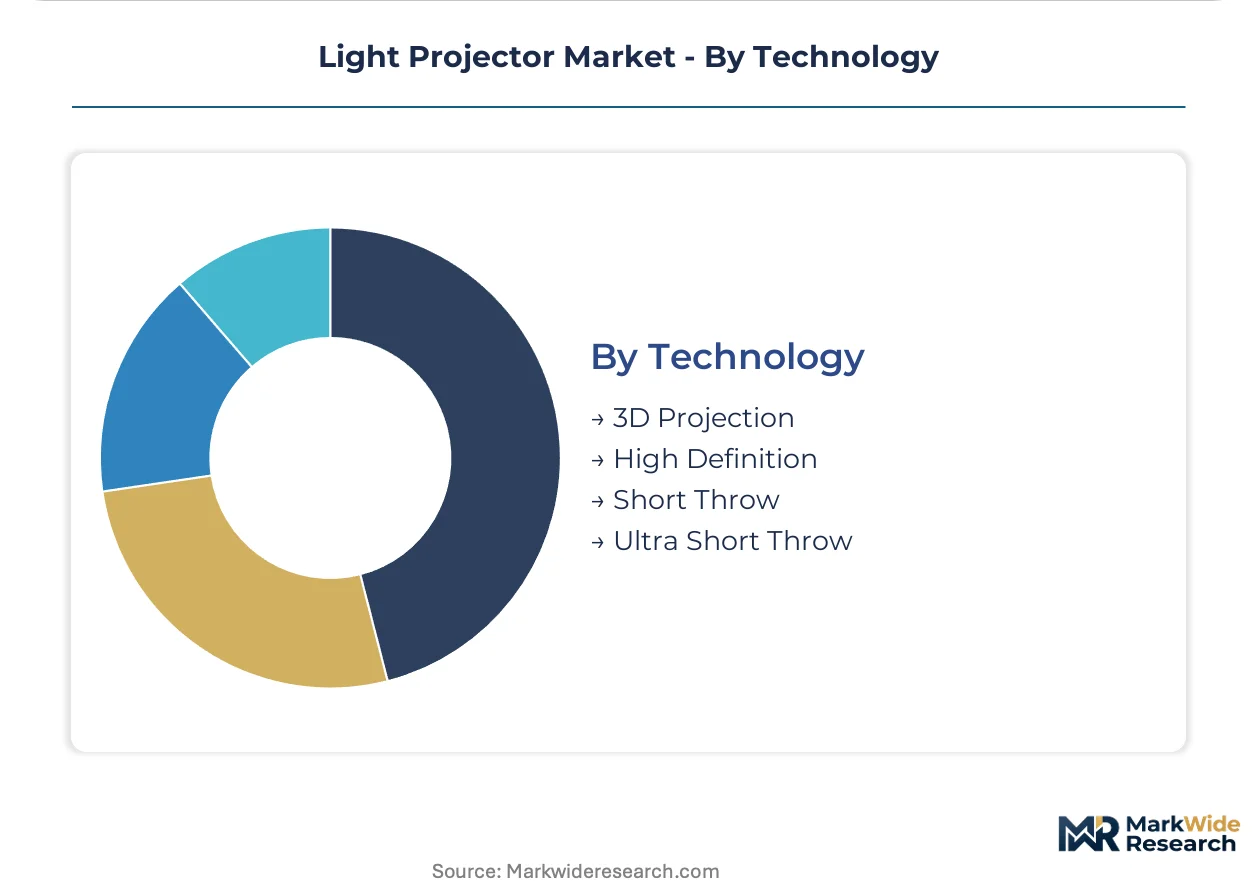
Technology:
Throw distance specifications and dimensional rendering capabilities differentiate premium from baseline offerings.
- Ultra Short Throw:Periscope-style lens assemblies and curved mirror systems project 100-inch images from inches away from the screen surface. Residential installations in space-constrained Asian metropolitan markets favor this configuration.
- Short Throw:0.4-0.8 throw ratios suit classroom and conference room tables where presenter shadow interference must be eliminated. Education procurement in Europe specifies short throw for interactive whiteboard pairing.
- High Definition:1080p and 4K UHD resolution panels serve home theater and professional review applications where pixel density affects perceived image quality. Content streaming services drive resolution upgrade cycles in consumer segments.
- 3D Projection:Active and passive stereoscopic systems persist in specialized simulation and visualization markets. Medical training centers and architectural design firms in Germany and Japan maintain demand for depth-capable displays.
Resolution upgrades diffuse from premium home theater into institutional channels, while throw distance innovations concentrate in residential and education verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, Japan, and the United States concentrate the bulk of light projector manufacturing capacity, while Germany and India emerge as critical demand centers with divergent procurement patterns and regulatory frameworks.
United States
Home theater installations in New York and Los Angeles metro areas drive premium laser projector demand. FCC equipment authorization requirements govern radio-frequency emissions from smart projectors sold nationwide. Texas and California host the largest concentration of commercial AV integration firms serving corporate and entertainment venue verticals.
China
Urban apartment dwellers in Shanghai and Shenzhen favor ultra short throw form factors with integrated streaming platforms. MIIT certification standards and GB standards for electromagnetic compatibility shape product design for domestic consumption. Guangdong and Jiangsu provinces anchor the majority of global projector assembly and optical component manufacturing.
Japan
METI energy efficiency standards force thermal management redesigns that cascade through global product lineups. JIS standards compliance remains mandatory for domestic market entry. Tokyo and Osaka metropolitan clusters concentrate both precision optical engineering talent and high-end residential demand for 4K laser home theater systems.
Germany
EU F-Gas Regulation restrictions on fluorinated greenhouse gases affect cooling system designs for high-brightness projectors above 10,000 ANSI lumens. REACH substance restrictions and CE marking requirements under RoHS directives restrict hazardous substances in optical assemblies. Bavaria and Baden-Württemberg host the largest concentration of museum and themed entertainment venues deploying immersive multi-projector arrays.
India
Public education systems in Maharashtra and Karnataka operate on fiscal year procurement calendars with formal bidding requirements for classroom projector deployments. BIS certification alignment reduces technical barriers for manufacturers entering government procurement channels. Tamil Nadu and Telangana emerge as regional hubs for commercial AV distribution serving South Asian institutional markets.
Light Projector Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the light projector market, creating a tiered structure where integrated optical engine manufacturers face specialized assembly houses. The vendor base separates between captive component producers and modular system integrators. Three archetypes dominate: Japanese precision optical conglomerates with in-house 3LCD fabrication, Chinese smart hardware platforms with integrated content ecosystems, and Taiwanese-German display specialists focused on commercial installation channels. Competitive moves concentrate on backward integration into solid-state illumination sources and strategic partnerships with streaming platform operators.
Among Japanese precision optical conglomerates, Seiko Epson Corporation exemplifies the vertically integrated archetype with proprietary 3LCD manufacturing infrastructure. Hisense anchors large-format laser projection demand through cinema and commercial display channels. XGIMI occupies a position within the portable smart projector segment, competing aggressively with integrated streaming platforms.
| Leading Market Players |
|---|
| Optoma Technology Corp |
| JMGO |
| Seiko Epson Corporation |
| XGIMI |
| ViewSonic Corporation |
| Sony Group Corporation |
| Hisense |
| Mitsubishi Electric Corporation |
| BenQ Corporation |
| Others |
Value Chain & Pricing Dynamics
Optical engineering talent concentration in Osaka and Nagoya drives labor-cost differentials that widen spreads between premium laser cinema systems and entry-level portable units. Japanese precision manufacturing clusters command wage premiums that cascade into pricing tiers, while Guangdong assembly operations absorb cost-down pressure for volume education procurement.
Pricing Analysis
Margin tightening in mid-lumen professional tiers reflects phosphor-converted laser diode cost compression and Texas Instruments DMD chip pricing power. Three-tier pricing structure across premium RGB-laser cinema, standard phosphor-laser corporate, and economy LED portable levels separates buyers by operational lifespan requirements. Education procurement teams in India and the United States exhibit highest price sensitivity, while museum immersive installation buyers absorb premium positioning for color gamut coverage.
Supply Chain Analysis
Refurbishment flows for mercury-lamp legacy units create secondary parts markets that extend service revenue for incumbents with captive logistics networks. Manufacturing concentrates in China, Japan, and Taiwan, with Guangdong province anchoring final assembly and Osaka feeding precision optical components. Rare earth phosphor supply draws from Chinese export quotas, creating single-source vulnerability for cerium-doped yttrium aluminum garnet. Distribution runs through AV integrators in corporate channels and direct-to-consumer platforms in residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive control over solid-state illumination sources and spatial light modulators determines margin capture. Players pursue backward integration into laser diode fabrication and phosphor wheel manufacturing to escape supplier pricing power.
For Market Incumbents: To counter Texas Instruments' DMD supply concentration, Seiko Epson and Sony should deepen captive 3LCD and LCOS fabrication capacity while securing long-term phosphor supply agreements with Chinese rare earth processors. METI efficiency mandates and EU F-Gas thermal redesign requirements favor incumbents with existing compliance infrastructure over new entrants facing certification timelines. For New Entrants and Emerging Players: Enter via unbundled software-defined brightness calibration subscriptions that attach to commodity hardware, targeting price-sensitive education procurement in India where BIS certification alignment lowers technical barriers. Portable smart projector segments with integrated Android TV platforms offer the most penetrable white space against XGIMI and JMGO, particularly in Chinese and Indian consumer markets where seasonal upgrade cycles accelerate replacement. For Investors and Strategic Acquirers: The window for entry favors optical engine specialists with freeform lens design capabilities and thermal management IP concentrated in German and Japanese industrial clusters. Long-term viability hinges on solid-state illumination transitions and cloud-connected maintenance revenue models. Monitor FCC equipment authorization timeline extensions and rare earth export quota announcements as inflection indicators for supply-constrained pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Diode Backward Integration | Captive RGB and phosphor-converted supply reduces Texas Instruments dependency and secures margin. |
| Cloud-Connected Firmware Ecosystem | Over-the-air calibration subscriptions transform hardware margins into recurring revenue streams. |
| Ultra Short Throw Lens Assembly | Periscope optics and curved mirrors unlock space-constrained residential demand in Asian metros. |
| EU F-Gas Thermal Redesign | Heat pipe and vapor chamber adoption enables 10,000+ lumen projector compliance in Germany and France. |
| India BIS Certification Alignment | Harmonized EMC and safety standards reduce technical barriers for education and government procurement. |
Study Parameters
Multi-period observation of laser diode cost curves, phosphor wheel pricing, and projector shipment volumes anchored the trend analysis, supplemented by interviews with optical engineers at Japanese precision manufacturers, procurement directors at U.S. K-12 districts, and AV integration specialists in Germany. Secondary validation drew from MIIT certification databases, FCC equipment authorization filings, EU ECHA substance restriction notices, and trade flow data through Chinese customs. Bottom-up segment sizing triangulated against top-down manufacturer revenue disclosures.
Input-output matrices mapped illumination source technologies to end-use applications across home theater, education, corporate, and entertainment venue segments. The projection framework modeled laser, DLP, LCD, and LED product types against ultra short throw, short throw, and standard throw distance specifications. CAGRs derived from installed base replacement cycles, solid-state illumination adoption curves, and regional regulatory compliance timelines. Forecast inputs included METI efficiency standard phase-ins and REACH mercury lamp restriction enforcement.
Revisions become necessary when rare earth export quotas tighten, Texas Instruments DMD allocation shifts, or immersive environmental projection demand accelerates beyond museum and themed entertainment into corporate experience centers. Practitioners should monitor FCC authorization backlog durations and phosphor-converted laser diode yield improvements for early signals of supply constraint easing or tightening.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
Gallium Arsenide Market
Optoelectronics
Quantum Dot Lasers Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Taiwan Optoelectronics Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
Americas Optoelectronics Market
Optoelectronics
3D Projector Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market
Optoelectronics
EPON ONU Market
Optoelectronics
Heterojunction Solar Cell Market
Optoelectronics
Ingaas Avalanche Photodiode Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market