
 Photonics Sensor Market | 2026-2036
Photonics Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Photonics Sensor Market Analytics
China's domestic photonics foundry build-out is narrowing the historical supply gap against Japanese and European sources. Hamamatsu Photonics K.K. leverages its vertical integration across scintillator crystals and photodiode arrays to sustain premium positioning in medical imaging. ams-OSRAM AG anchors its competitive stance through captive LED and laser chip fabrication for automotive LiDAR. Sony Group Corporation dominates CMOS image sensor architectures, while Keyence Corporation differentiates through integrated software-hardware bundles for factory-floor deployment.
Photonics sensors detect, measure, and convert light signals into electrical output using semiconductor junctions, fiber Bragg gratings, or interferometric architectures, with spectral sensitivity ranging from ultraviolet through mid-infrared wavelengths. These devices serve precision measurement, communications, and environmental surveillance functions where electromagnetic alternatives fail. Imaging sensors command the largest installed base due to smartphone and automotive camera proliferation, yet fiber optic sensors represent the fastest-expanding margin pool as oilfield and structural health monitoring applications multiply. Quantum dot technology is displacing conventional epitaxial approaches in biomedical fluorescence detection, while industrial automation absorbs the highest volume of laser displacement sensors for robotic positioning.
FDA device classification rules and EPA emissions monitoring mandates in the United States, alongside REACH substance restrictions and CE marking requirements in Europe, compel sensor vendors to validate biocompatibility and environmental durability before market entry. Japan's METI subsidizes domestic photonics R&D through national technology roadmaps that prioritize quantum sensing commercialization. Stakeholders must weigh regulatory compliance timelines against the acceleration of foundry partnerships in East Asia to secure capacity for next-generation spectroscopic and interferometric platforms.
Market Dynamics
Photonics sensor procurement is concentrating around automotive LiDAR and semiconductor metrology as buyers consolidate vendor lists to secure supply chain resilience against foundry capacity constraints in East Asia.
Growth Catalysts
- EU F-Gas Regulation:Mandates for fluorinated gas phase-down in industrial cooling and HVAC systems are forcing facility operators toward non-dispersive infrared sensors for leak detection, opening replacement demand across German chemical plants and French food processing sites.
- Automotive assembly automation:Tier-1 suppliers in Stuttgart's manufacturing corridor are deploying laser displacement sensors for sub-millimeter robotic positioning in electric vehicle battery module assembly.
- Quantum dot fluorophores:Cadmium-free quantum dots are displacing conventional organic dyes in biomedical imaging workflows, shortening assay development cycles for diagnostic instrument manufacturers.
Market Restraints
- Indium phosphide substrate costs:Epitaxial wafer prices for telecom-grade photodetectors fluctuate with indium mining output concentrated in Chinese and Canadian extraction sites.
- Single-source scintillator supply:High-purity cesium iodide crystal growth capabilities remain captive to three Japanese suppliers, exposing medical imaging OEMs to allocation risk.
- REACH substance restrictions:Cadmium and lead content limits in photonic coatings are forcing reformulation of legacy infrared detector architectures, extending qualification timelines.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for semiconductor and component manufacturing are attracting photonics packaging investments in Gujarat and Tamil Nadu.
- Quantum sensing commercialization:METI-funded roadmaps in Japan are accelerating atomic interferometer deployment for geophysical surveying and underground infrastructure mapping.
- Edge AI inference integration:On-sensor neural processing units are enabling real-time defect classification in factory-floor inspection systems without cloud dependency.
Industry Challenges
- Multi-physics simulation expertise:Shortage of engineers trained in opto-electro-thermal coupled modeling is delaying custom sensor development cycles for aerospace applications.
- CE-MDR dual certification:Medical device manufacturers face overlapping documentation requirements between CE marking and Medical Device Regulation technical file submissions.
- Legacy PLC integration:Fiber optic sensor deployments in brownfield industrial sites require protocol translation layers for Modbus and Profibus networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photonics Sensor Market |
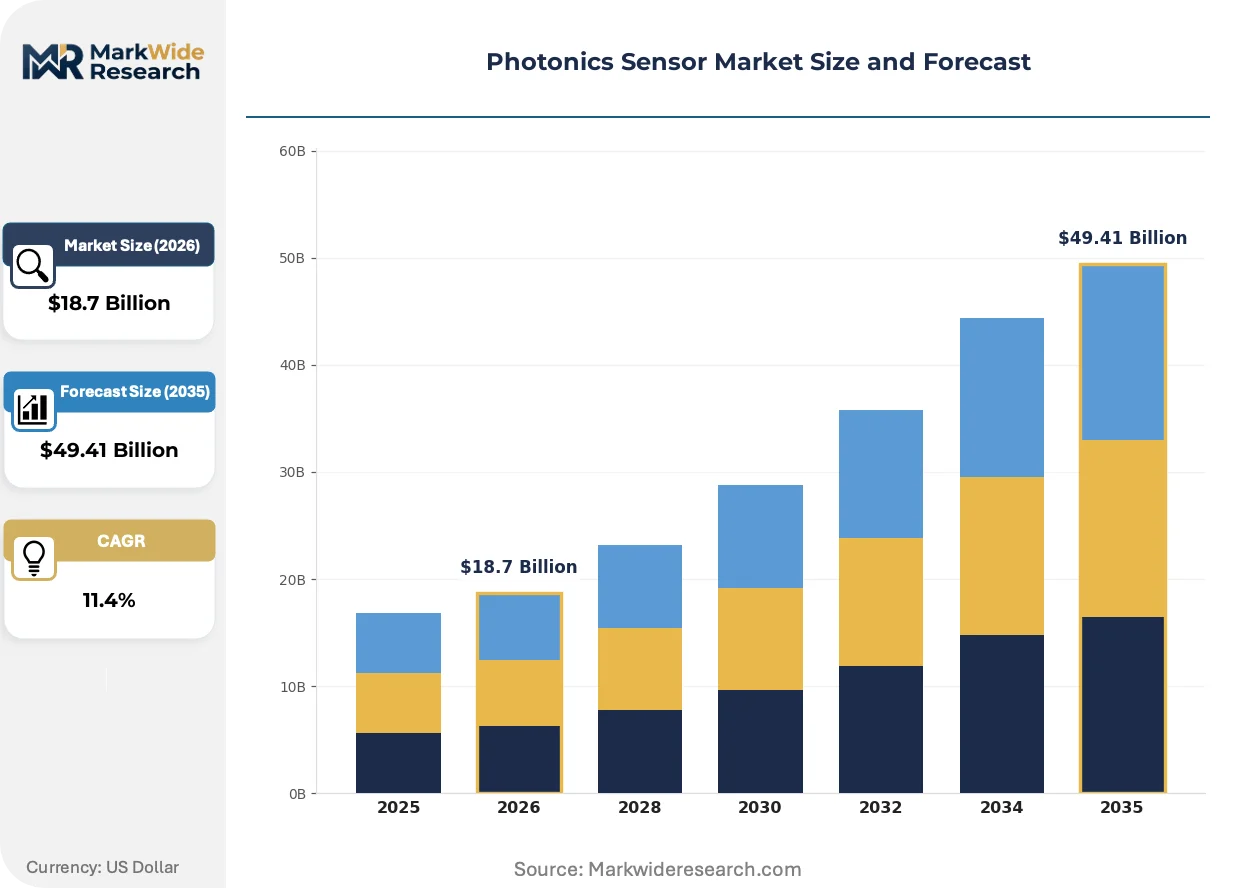
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Sensors, Laser Sensors, Imaging Sensors, Fiber Optic Sensors Technology: Quantum Dots, Surface Plasmon Resonance, MEMS, Photonic Crystal Application: Telecommunications, Environmental Monitoring, Medical Diagnostics, Industrial Automation End User: Aerospace, Automotive, Electronics, Healthcare |
| Companies Covered | Hamamatsu Photonics K.K., Motorola Solutions, ams-OSRAM AG, Keyence Corporation, Omron Corporation, BAE Systems, Sony Group Corporation, Thorlabs, Inc., L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photonics Sensor Market Evolving Landscape
Solid-state architectures are compressing form factors while computational photonics is shifting signal processing from external ASICs onto the sensor die itself.
Swept-source optical coherence tomography is rendering obsolete time-domain systems in ophthalmic diagnostics. German university hospitals are standardizing on Fourier-domain engines for retinal imaging. The technology is compressing examination duration from minutes to seconds while improving axial resolution.
The EU AI Act's high-risk system classification is mandating explainability documentation for photonics-based quality inspection in automotive manufacturing. Tier-1 suppliers must now maintain algorithmic audit trails for defect detection decisions. German machine builders are responding by embedding interpretable feature extraction layers in their vision systems.
Buyer consolidation among semiconductor fabs is compressing vendor qualification cycles from 18 months to under 9 months. Integrated device manufacturers are demanding turnkey calibration and metrology data packages upfront. This pattern is most visible in Dutch and Taiwanese lithography equipment supply chains where sensor specification sheets now require embedded uncertainty budgets.
Photonics Sensor Market Segmentation
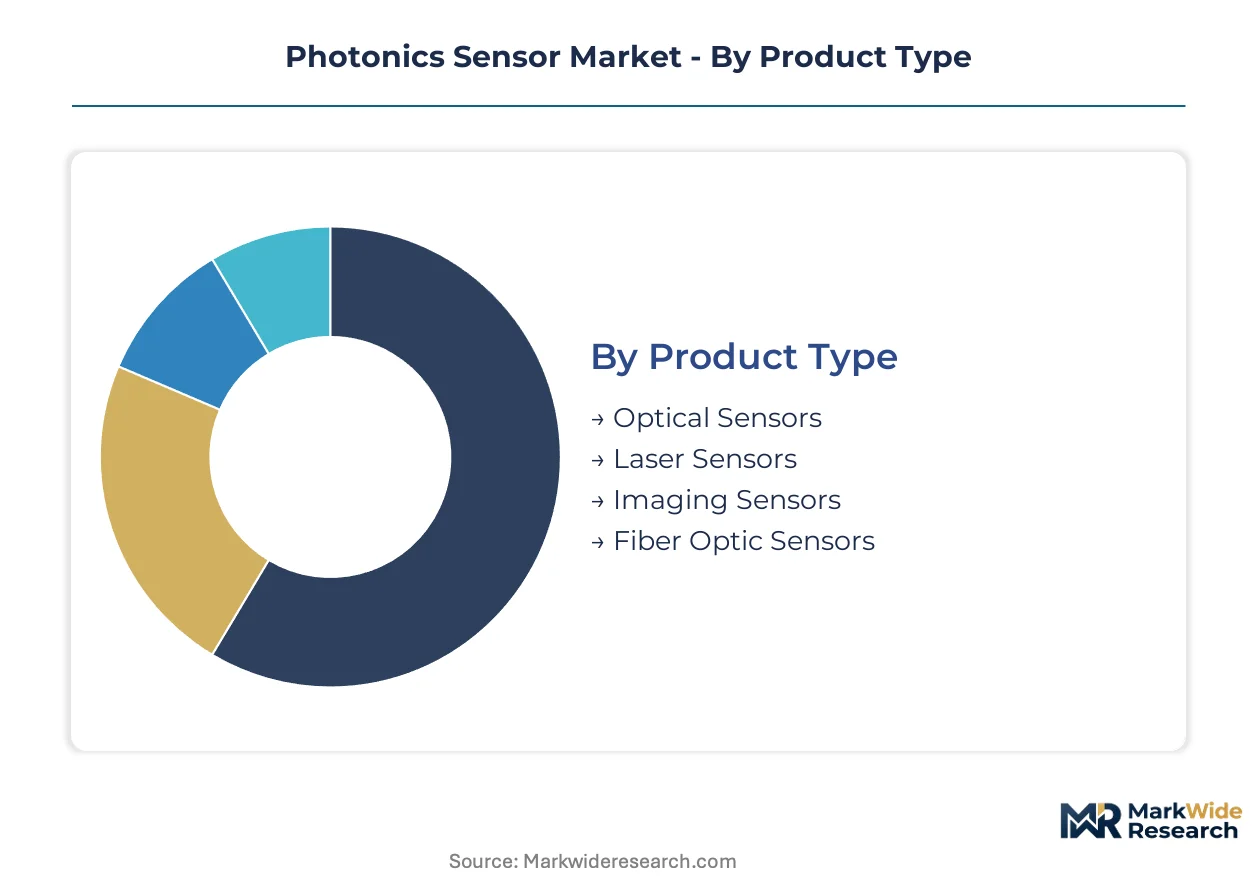
Photonics sensor procurement patterns diverge sharply across product architectures and end-use requirements. Buyers prioritize spectral precision in medical settings versus ruggedized packaging for factory-floor deployment.
Product Type:
Mature CMOS-based imaging platforms dominate unit volumes while emerging fiber architectures reshape margin structures.
- Optical Sensors:Semiconductor junction devices convert incident photons into electrical signals across ultraviolet through near-infrared wavelengths. Automotive assembly lines in Stuttgart's manufacturing corridor deploy these for paint defect detection. REACH substance restrictions on cadmium-based coatings are forcing reformulation of legacy detector architectures.
- Imaging Sensors:CMOS and CCD architectures capture two-dimensional light fields for machine vision and consumer electronics. Sony Group Corporation's stacked BSI designs anchor smartphone camera supply chains. Medical imaging OEMs face allocation risk from single-source scintillator supply concentrated among Japanese crystal growers.
- Laser Sensors:Time-of-flight and triangulation modules measure displacement with sub-micron precision for robotic positioning.
- Fiber Optic Sensors:Fiber Bragg grating and interferometric designs enable distributed strain and temperature monitoring in oilfield and civil infrastructure applications.
Imaging sensors retain volume leadership; fiber optic sensors hold the steepest expansion curve.
Technology:
Cost tier separation runs from commodity MEMS to premium quantum architectures requiring specialized foundry partnerships.
- Quantum Dots:Nanocrystal fluorophores tunable across the visible spectrum through size-dependent quantum confinement. Cadmium-free formulations are displacing conventional organic dyes in biomedical fluorescence workflows. FDA device classification rules compel diagnostic instrument manufacturers to validate biocompatibility before assay deployment.
- MEMS:Micro-electromechanical systems integrate movable optical elements on silicon substrates for tunable filters and switching matrices. Chinese domestic photonics foundry build-out is narrowing historical supply gaps against Japanese sources. Consumer electronics buyers absorb the highest volumes for smartphone autofocus actuators.
- Surface Plasmon Resonance:Evanescent wave biosensors detect molecular binding events without fluorescent labels for pharmaceutical screening.
- Photonic Crystal:Periodic dielectric structures manipulate light propagation through bandgap engineering for high-Q resonators.
MEMS technology retains volume leadership; quantum dots hold the steepest expansion curve.
Application:
Geography dictates deployment patterns with EU regulatory pressure accelerating environmental monitoring adoption.
- Industrial Automation:Laser displacement and vision systems enable sub-millimeter robotic positioning in electric vehicle battery module assembly. Tier-1 suppliers in Germany's precision manufacturing corridor are consolidating vendor lists to secure supply chain resilience. The EU AI Act's high-risk system classification mandates explainability documentation for quality inspection algorithms.
- Medical Diagnostics:Spectroscopic and imaging platforms support point-of-care testing and surgical navigation. Swept-source optical coherence tomography is compressing ophthalmic examination duration from minutes to seconds. CE-MDR dual certification creates overlapping documentation requirements between marking and technical file submissions.
- Telecommunications:Photodetectors and modulators anchor fiber optic network infrastructure.
- Environmental Monitoring:Non-dispersive infrared and UV-DOAS sensors track emissions compliance.
Industrial automation retains volume leadership; medical diagnostics holds the steepest expansion curve.
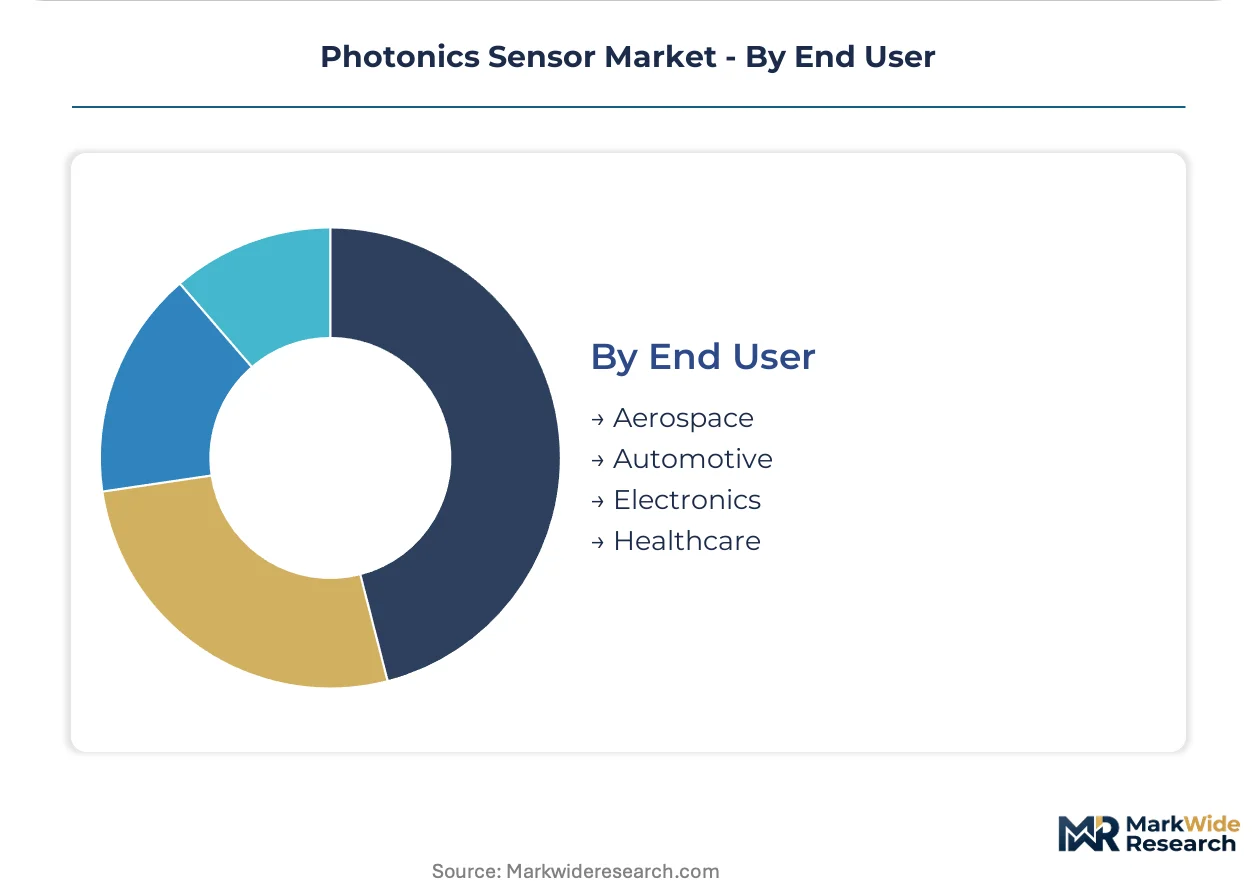
End User:
Customer type determines specification stringency from aerospace qualification to consumer electronics cost targets.
- Automotive:LiDAR and camera modules enable advanced driver-assistance systems and autonomous navigation. ams-OSRAM AG anchors supply through captive LED and laser chip fabrication. NHTSA and KBA type-approval processes extend qualification timelines for safety-critical photonic components.
- Healthcare:Imaging and spectroscopic instruments serve diagnostic, surgical, and monitoring functions. German university hospitals are standardizing on Fourier-domain optical coherence tomography engines. Japan's METI subsidizes domestic photonics R&D through national technology roadmaps prioritizing quantum sensing commercialization.
- Electronics:Smartphones, tablets, and wearables absorb CMOS image sensors in massive volumes.
- Aerospace:Fiber optic gyroscopes and structural health monitoring systems operate in radiation-hardened environments.
Electronics retains volume leadership; automotive holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese crystal growers and German precision manufacturers command disproportionate influence over photonics sensor supply chains. Chinese domestic foundry expansion is eroding historical import dependence. Regulatory divergence between EPA emissions mandates and EU F-Gas phase-down rules is fragmenting certification requirements.
United States
Automotive LiDAR procurement and semiconductor metrology equipment absorb the highest sensor volumes. EPA emissions monitoring mandates compel industrial facilities to deploy non-dispersive infrared detectors for leak detection compliance. Austin and Phoenix anchor concentrated demand from electric vehicle battery assembly and advanced packaging fabs.
Germany
Stuttgart's manufacturing corridor drives laser displacement sensor procurement for robotic positioning in electric vehicle module assembly. EU F-Gas Regulation phase-down requirements force chemical plants toward optical leak detection systems. Munich precision engineering clusters standardize on sub-micron inspection protocols for automotive Tier-1 suppliers.
China
Domestic photonics foundry build-out narrows supply gaps against Japanese and European sources. MIIT industrial policy prioritizes captive LED and laser chip fabrication for automotive applications. Yangtze River Delta concentration spans Shanghai packaging facilities and Suzhou metrology equipment demand.
Japan
High-purity cesium iodide crystal growth capabilities remain concentrated among domestic suppliers serving medical imaging OEMs. METI subsidizes quantum sensing commercialization through national technology roadmaps. Hamamatsu and Nagoya industrial zones sustain vertical integration across scintillator and photodiode production.
India
Production-linked incentives for electronics manufacturing attract photonics packaging investments in Gujarat and Tamil Nadu. BIS certification requirements extend qualification timelines for imported sensor modules. Bangalore and Hyderabad clusters emerge as design centers for fiber optic sensing applications.
Photonics Sensor Market Competitive Landscape
Vertically integrated conglomerates and specialized component fabricators split the market into distinct capability tiers. Consolidation pressure concentrates around automotive LiDAR and medical imaging where qualification barriers exclude new entrants. Three archetypes dominate: captive foundry operators controlling epitaxial wafer supply, software-hardware integrators bundling factory-floor deployment systems, and precision optics specialists commanding scintillator crystal markets. Competitive moves center on foundry partnership securing and M&A targeting quantum dot assay portfolios.
Among Japanese precision manufacturers, Hamamatsu Photonics K.K. and Keyence Corporation exemplify divergent strategic positions—one anchoring medical imaging supply chains through crystal growth capabilities, the other occupying factory-floor integration through bundled vision systems. Sony Group Corporation sits within the imaging sensor tier where stacked CMOS architectures command smartphone and automotive camera supply chains. These three represent how geographic clustering around Nagoya, Osaka, and Tokyo reinforces distinct competitive moats.
| Leading Market Players |
|---|
| Hamamatsu Photonics K.K. |
| Motorola Solutions |
| ams-OSRAM AG |
| Keyence Corporation |
| Omron Corporation |
| BAE Systems |
| Sony Group Corporation |
| Thorlabs, Inc. |
| L3Harris Technologies |
| Others |
Value Network & Pricing Analysis
Yokohama-to-Rotterdam maritime freight corridors transmit cost volatility from Asian photonics foundries to European precision manufacturers, amplifying price differentiation between captive-source and merchant-market sensor tiers while compressing margins for distributors without direct foundry partnerships.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across environmental monitoring sensor portfolios. Three-tier pricing separates IECEx-certified explosion-proof units for chemical plants from standard industrial grades and economy-tier HVAC leak detectors. Price differentiation hinges on REACH substance compliance documentation and calibration traceability to NIST or PTB standards. Cost compression in the economy tier is intensifying because Chinese domestic foundry expansion is flooding spot markets with unbranded infrared detectors. Automotive OEMs exhibit the lowest price sensitivity due to NHTSA type-approval switching costs, while commercial building operators drive hard volume negotiations.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk assessments for photonics component sourcing. Epitaxial wafer fabrication concentrates in Japan, Taiwan, and the United States, while precision optical coating draws from German and Swiss specialty chemical suppliers. Raw material dependencies center on indium phosphide substrates, high-purity cesium iodide crystals, and cadmium-free quantum dot precursors. Single-source vulnerability persists for medical-grade scintillator supply held by Japanese crystal growers. Distribution runs through authorized distributor networks serving semiconductor fabs and Tier-1 automotive suppliers, with direct OEM relationships commanding preferred allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photonics sensor demand is recovering from cyclical lows in industrial capital expenditure, with electric vehicle battery assembly automation and EU emissions compliance mandates providing the demand floor.
For Market Incumbents: Pre-empt margin erosion from Chinese foundry expansion by deepening backward integration into epitaxial wafer supply through partnerships with Taiwan and Japan sources. Lock in multi-year offtake agreements with German automotive Tier-1 suppliers before vendor consolidation cycles complete. METI-funded quantum sensing roadmaps represent the priority R&D lane to defend against substitution by atomic interferometer startups. For New Entrants and Emerging Players: Mid-market fiber optic sensing for Indian civil infrastructure monitoring represents the most penetrable entry point, given BIS certification bottlenecks that slow multinational incumbents. Quantum dot assay portfolios for point-of-care diagnostics offer whitespace before FDA device classification rules tighten. A channel partnership with Gujarat-based electronics packaging facilities provides the fastest route to commercial scale without captive foundry investment. For Investors and Strategic Acquirers: Precision optics specialists with captive scintillator crystal growth capabilities command scarcity premia in medical imaging supply chains. Long-term viability rests on quantum sensing commercialization timelines and automotive LiDAR qualification cycles. Watch for METI roadmap acceleration signals as the inflection indicator for atomic sensor deployment rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Wafer Supply | Secures indium phosphide capacity against mining output volatility from Chinese and Canadian extraction sites. |
| Quantum Sensing R&D Partnership | Aligns with METI-funded roadmaps accelerating atomic interferometer deployment for geophysical surveying. |
| CE-MDR Dual Certification Investment | Opens hospital procurement channels in Germany where university hospitals standardize on Fourier-domain engines. |
| Edge AI Inference Integration | Enables real-time defect classification under EU AI Act explainability mandates for automotive Tier-1 suppliers. |
| India PLI Scheme Localization | Captures production-linked incentives for photonics packaging in Gujarat and Tamil Nadu electronics corridors. |
Research Methodology
Operator-level perspectives from photonics foundry engineers, automotive Tier-1 procurement directors, medical imaging OEM technical leads, and semiconductor metrology equipment specialists anchored the qualitative base. Secondary validation drew from EPA emissions monitoring filings, ECHA REACH substance restriction updates, METI technology roadmap publications, and SEMI equipment market data. Bottom-up segment sizing triangulated against top-down industry association aggregates across product type, technology, application, and end-user dimensions.
Scenario-bracketing around foundry capacity expansion rates and EU regulatory enforcement timelines shaped the analytical framework across the projection horizon. Segmentation modeling spanned optical, imaging, laser, and fiber optic architectures by MEMS, quantum dot, surface plasmon resonance, and photonic crystal technologies, further split across industrial automation, medical diagnostics, telecommunications, and environmental monitoring applications. CAGRs derived from regression against historical capital expenditure cycles and patent filing velocity in quantum sensing. Industry-specific inputs included indium phosphide substrate price indices and automotive LiDAR design win conversion rates.
Practitioners should monitor METI funding allocation shifts, EU F-Gas Regulation enforcement intensity, and Chinese foundry yield improvement announcements for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Europe Laser Interferometer Market
Optics
Fiber Optic Receiver Market
Optics
Electro Optics Market
Optics
Optical Profilometer Market
Optics
Photonics Market
Optics
APAC Smart Glass Market
Optics
AR and VR Lens Market
Optics
Solid State Lasers Market
Optics
Photostimulation Lasers Market
Optics
Fiber Optical Receivers Market
Optics
Optical Imaging Market
Optics
Smart Photochromic Lenses Market
Optics
Optical Gratings Market
Optics
Fiber-Optic Filters Market
Optics
Global Super Hi Vision Market
Optics
US Photonics Market