
 Optical Pulse Sensor Market | 2026-2036
Optical Pulse Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Pulse Sensor Market Outlook
OEM-direct procurement channels for optical biometric modules is rewriting how component suppliers reach end-device manufacturers. Texas Instruments leverages its analog front-end portfolio to sustain design-win momentum in medical-grade pulse detection. ROHM Co Ltd anchors Japanese supply chains through specialized LED-photodiode packaging for compact wearable integration.
An optical pulse sensor detects volumetric changes in blood flow using light-based measurement, typically operating in the red to near-infrared spectrum between 600 and 940 nanometers to penetrate tissue and capture cardiovascular signals. Photoplethysmography dominates the technology landscape due to its low power profile and compatibility with CMOS integration, though infrared sensors command premium positioning in clinical settings where motion artifact rejection carries higher stakes. Medical devices represent the most regulated and highest-margin application tier, while fitness trackers drive volume through consumer electronics supply chains.
FDA 510(k) clearance requirements and the EU MDR framework impose stringent biocompatibility and electromagnetic compatibility standards on optical pulse sensors destined for patient monitoring. China's NMPA has accelerated review timelines for wearable medical devices, reshaping how manufacturers structure multi-market registration strategies. Stakeholders must monitor divergence between consumer wellness and regulated medical classifications, as this boundary determines pricing power, liability exposure, and channel access across healthcare and sports performance segments.
Market Dynamics
The optical pulse sensor market faces intensifying pressure from FDA's tightening pulse oximeter accuracy thresholds, which compress design cycles and force module suppliers to recalibrate optical front-end architectures for simultaneous clinical-grade precision and consumer-scale manufacturability.
Growth Catalysts
- Photoplethysmography module procurement:Wearable device manufacturers across China are expanding orders for smartwatch-integrated optical biometric modules, creating sustained demand pull through East Asian EMS clusters.
- NMPA accelerated review timelines:China's medical device regulator has compressed approval windows for wearable health monitors, enabling faster multi-market registration strategies for optical sensor vendors.
- LED-photodiode packaging specialization:Japanese suppliers have developed compact multi-wavelength emitter-detector assemblies that reduce board space requirements for fitness tracker integration.
Market Restraints
- Near-infrared LED supply concentration:High-performance emitters operating at 940 nanometers depend on limited Japanese and Taiwanese foundry capacity, creating input cost volatility during demand spikes.
- Motion artifact rejection limitations:Photoplethysmography signals degrade under physical activity, restricting clinical adoption outside static monitoring scenarios despite algorithmic compensation efforts.
- EU MDR biocompatibility certification friction:The expanded scope of Europe's medical device regulation imposes extended testing timelines for optical sensors with skin-contacting components, delaying market entry.
Strategic Opportunities
- Remote patient monitoring penetration:Chronic disease management programs in Germany and the Netherlands are integrating prescription-grade pulse oximetry into home-based care protocols, opening regulated reimbursement channels.
- Multi-parameter sensor fusion:Convergence of optical pulse detection with galvanic skin response and temperature sensing is enabling single-module vital sign platforms for hospital-at-home deployments.
- Direct-to-OEM module supply:Component suppliers are bypassing traditional distribution layers to establish design-in relationships with wearable device engineering teams, capturing margin and accelerating specification cycles.
Industry Challenges
- Optical modeling expertise scarcity:The intersection of biomedical signal processing, CMOS analog design, and tissue optics requires specialized talent pools concentrated in Boston and Eindhoven innovation clusters.
- FDA 510(k) predicate device strategy:Evolving guidance on pulse oximeter accuracy claims complicates regulatory filing pathways, forcing extended clinical validation studies that strain development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Pulse Sensor Market |
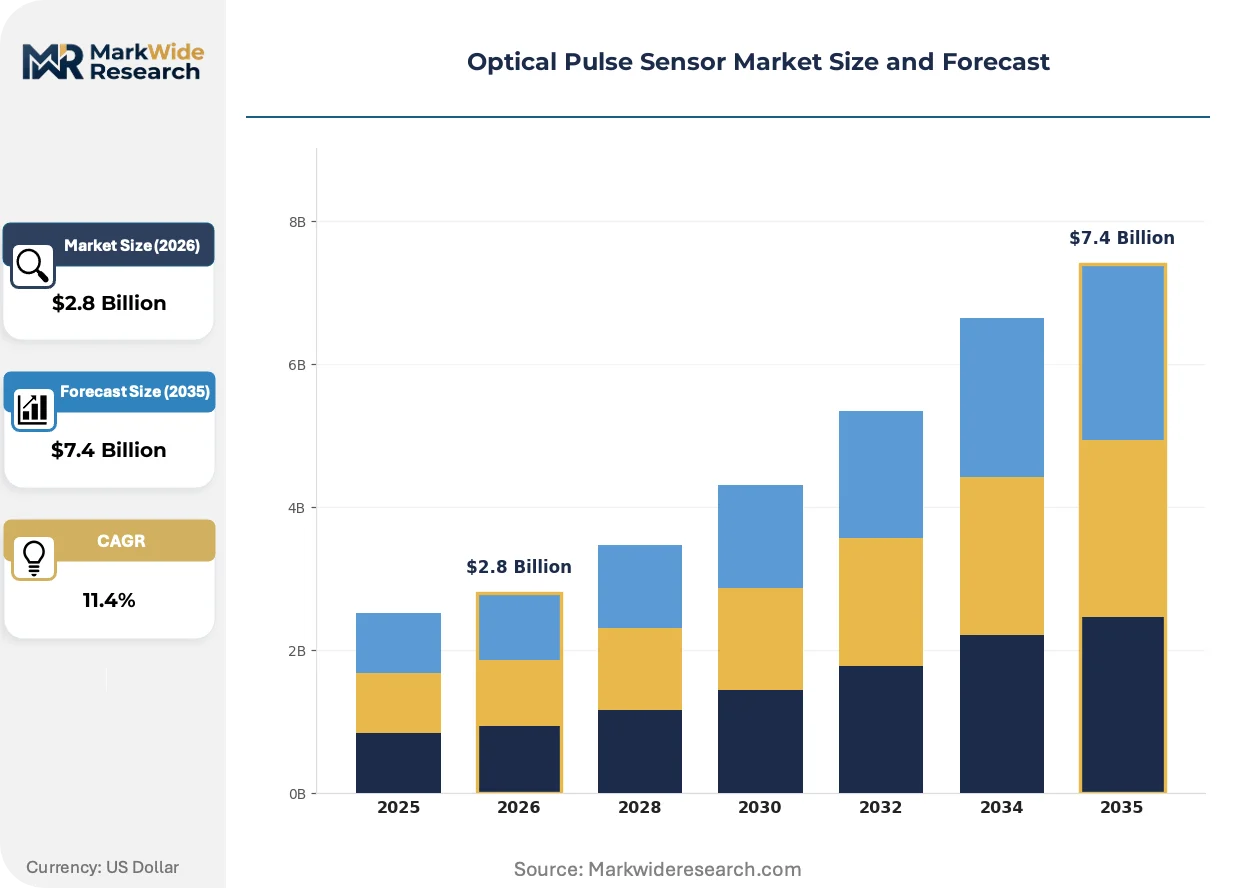
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wristband, Smartwatch, Medical Devices, Fitness Tracker End User: Healthcare Providers, Sports Organizations, Consumers, Research Institutions Technology: Photoplethysmography, Infrared Sensors, Optical Devices, Laser Technology Application: Patient Monitoring, Fitness Tracking, Research Studies, Sports Performance |
| Companies Covered | Maxim Integrated Products Inc, Osram Licht AG, ROHM Co Ltd, Texas Instruments Inc, Silicon Laboratories Inc, Valencell Inc, TE Connectivity Ltd, Microchip Technology Inc, ams-OSRAM AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Pulse Sensor Market Strategic Shifts
Optical pulse sensing architectures are fragmenting across performance tiers as clinical-grade specifications migrate downward into consumer wearables while wellness applications demand medical-adjacent credibility. This convergence pressure is accelerating module-level integration and forcing suppliers to maintain dual qualification tracks.
Multi-wavelength photoplethysmography is hybridizing green, red, and infrared emitters into single-package solutions that enable SpO2 and perfusion index measurement from wrist-worn devices. Medical device OEMs are qualifying these fused architectures for spot-check monitoring applications. The technology is hybridizing formerly distinct clinical and consumer sensor categories into unified module platforms that compress supplier development overhead.
Europe's MDR framework is tightening post-market surveillance requirements for optical sensors claiming diagnostic utility, mandating systematic clinical follow-up data collection. Manufacturers must now maintain quality management systems capable of traceable adverse event reporting across distributed wearable deployments. Class IIa pulse oximetry devices face the steepest compliance burden, with notified body capacity constraints extending certification timelines by eight to fourteen months.
Hospital procurement departments are consolidating optical sensor vendors through single-source contracts for multi-parameter patient monitors, displacing fragmented component purchasing. This concentration favors suppliers offering validated interoperability with existing telemetry infrastructure. The shift is most visible in US health system purchasing cooperatives, where GPO-negotiated agreements now specify optical module performance thresholds that exceed FDA minimums.
Optical Pulse Sensor Market Segmentation
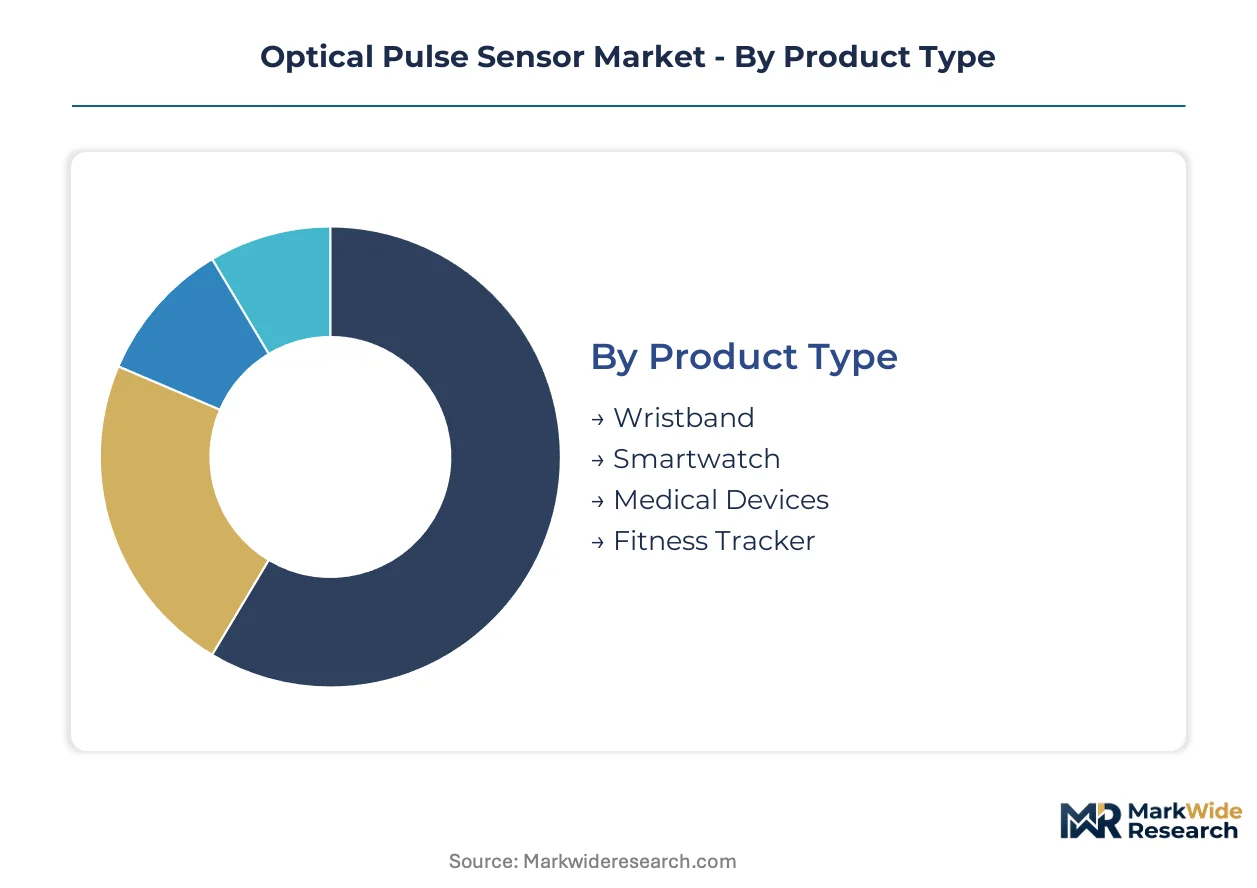
Optical pulse sensor procurement patterns diverge sharply across device categories, with medical certification requirements and consumer price elasticity creating distinct specification tiers. Understanding these segment boundaries enables suppliers to align optical front-end architectures with margin structures and regulatory pathways.
Product Type:
Use-case spectrum spans prescription-grade patient monitors to disposable fitness accessories, with each tier demanding different LED-photodiode configurations and algorithmic compensation.
- Medical Devices:Pulse oximeters and bedside monitors integrate multi-wavelength emitters with FDA 510(k) clearance requirements. German hospital procurement groups specify performance thresholds exceeding FDA minimums for chronic disease management programs.
- Smartwatch:Green and infrared LED combinations enable continuous heart rate and SpO2 spot-checking from wrist-worn platforms. Chinese OEMs dominate procurement volume through East Asian EMS clusters co-located with component suppliers.
- Wristband:Single-wavelength photoplethysmography modules prioritize battery efficiency over clinical accuracy. Demand concentrates in entry-level wellness segments where algorithmic heart rate estimation suffices.
- Fitness Tracker:Cost-optimized optical stacks sacrifice motion artifact rejection for manufacturing scale. Japanese LED-photodiode packaging specialists supply compact assemblies to reduce board space requirements.
The dominant share belongs to Smartwatch, while Medical Devices is closing the gap fastest as clinical-grade specifications migrate into consumer wearables.
End User:
Customer procurement authority determines pricing power, with institutional buyers extracting performance guarantees that consumer channels cannot enforce.
- Healthcare Providers:Hospital systems and clinics demand validated interoperability with existing telemetry infrastructure. US health system purchasing cooperatives consolidate vendors through GPO-negotiated agreements specifying optical module performance thresholds.
- Consumers:Individual purchasers prioritize device aesthetics and battery life over clinical accuracy. Direct-to-OEM module supply relationships are bypassing traditional distribution layers to capture margin from this price-sensitive segment.
- Sports Organizations:Professional teams and athletic programs require motion-robust pulse detection for training load management. Algorithmic compensation for physical activity artifacts drives specification requirements.
- Research Institutions:Academic and clinical research groups source specialized optical configurations for cardiovascular signal studies. NMPA accelerated review timelines in China enable faster multi-market registration for study-grade sensors.
Healthcare Providers command the highest average selling prices, though Consumers generate absolute volume that shapes component supplier capacity planning.
Technology:
Technical maturity and CMOS integration compatibility determine which architectures penetrate cost-sensitive versus performance-critical applications.
- Photoplethysmography:Light-based volumetric blood flow detection dominates through low power consumption and foundry compatibility. Green wavelengths serve fitness tracking; red and infrared enable SpO2 measurement.
- Infrared Sensors:Near-infrared emitters at 940 nanometers penetrate tissue deeply for perfusion index measurement. Clinical settings absorb premium pricing where motion artifact rejection carries higher stakes.
- Optical Devices:Broad category encompassing discrete LED-photodiode pairs and integrated analog front-ends. Texas Instruments sustains design-win momentum through analog front-end portfolio breadth.
- Laser Technology:Coherent light sources enable speckle-based perfusion imaging for research and specialized clinical applications. Higher cost structures restrict penetration beyond laboratory and reference equipment.
Photoplethysmography holds installed base leadership, yet Infrared Sensors is expanding most quickly as wrist-worn SpO2 functionality proliferates.
Application:
Regulatory classification boundaries separate reimbursable diagnostic use from wellness-adjacent fitness tracking, determining channel access and liability exposure.
- Patient Monitoring:Continuous or spot-check pulse oximetry for clinical decision support. EU MDR biocompatibility certification friction extends timelines for skin-contacting optical sensors.
- Fitness Tracking:Recreational heart rate and activity estimation without diagnostic claims. Volume manufacturing in Shenzhen and Dongguan EMS clusters serves global consumer electronics brands.
- Sports Performance:Real-time physiological load monitoring for athlete training optimization. Motion artifact rejection limitations restrict adoption to static or controlled-activity scenarios.
- Research Studies:Controlled data collection for cardiovascular signal processing algorithm development. Optical modeling expertise scarcity in Boston and Eindhoven innovation clusters constrains supplier talent acquisition.
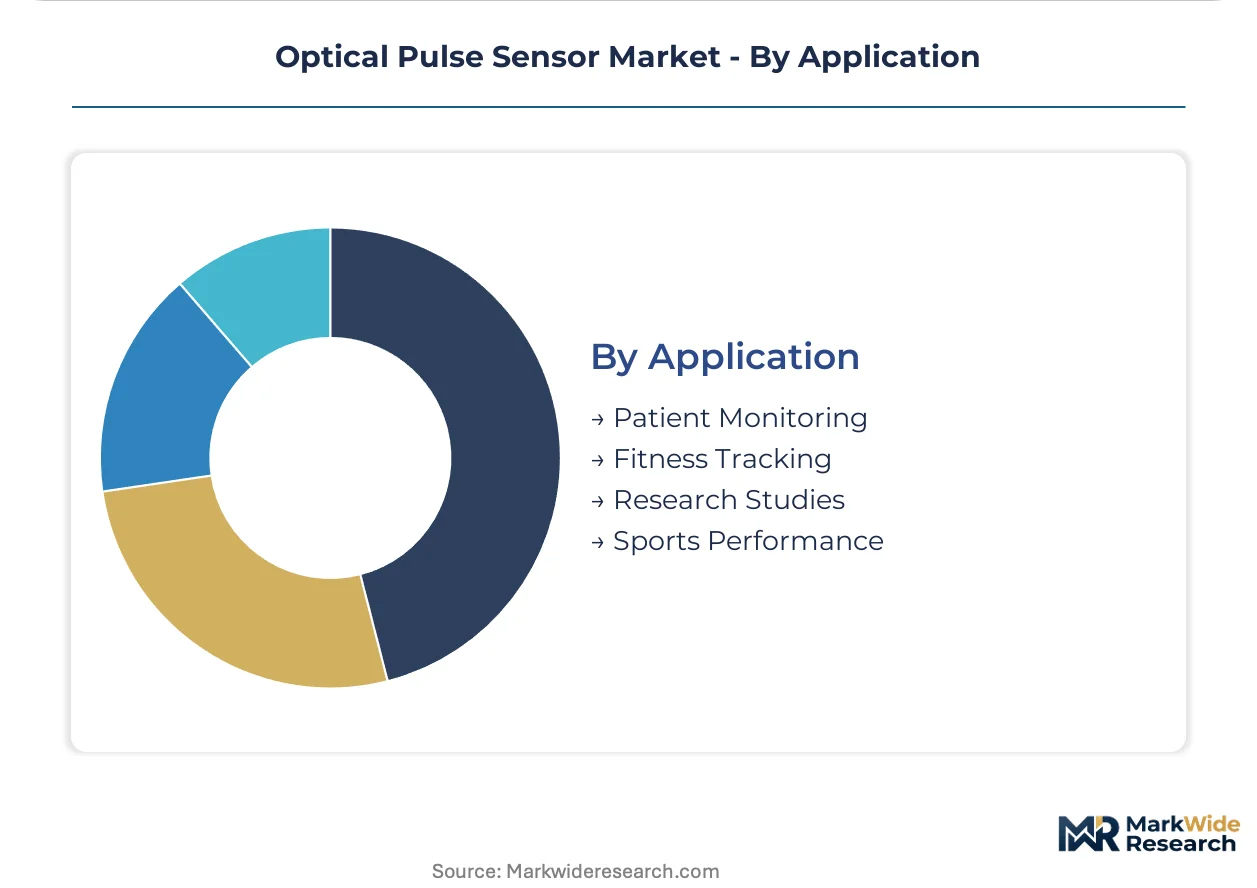
Patient Monitoring captures premium pricing, while Fitness Tracking is gaining share fastest through smartwatch integration and consumer electronics supply chain scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's evolving pulse oximeter guidance anchors United States regulatory influence over optical pulse sensor design standards worldwide. Chinese NMPA accelerated review timelines and Japanese LED-photodiode packaging specialization shape East Asian manufacturing dominance. German hospital procurement specifications and Dutch remote patient monitoring programs drive European clinical adoption.
United States
Hospital purchasing cooperatives and GPO-negotiated agreements consolidate vendor selection for multi-parameter patient monitors. FDA 510(k) clearance requirements impose stringent biocompatibility and electromagnetic compatibility thresholds on optical sensor submissions. Greater Boston innovation clusters concentrate optical modeling expertise for biomedical signal processing algorithm development.
China
Wearable device manufacturers across Shenzhen and Dongguan expand procurement of photoplethysmography modules for smartwatch integration. NMPA compressed approval windows for wearable health monitors enable faster multi-market registration strategies. Yangtze River Delta manufacturing clusters co-locate component suppliers with EMS providers serving global consumer electronics brands.
Japan
Specialized LED-photodiode packaging for compact wearable integration anchors domestic supply chain competitiveness. METI industrial policy supports near-infrared emitter foundry capacity expansion at 940 nanometer wavelengths. Tokyo-Osaka industrial corridors concentrate multi-wavelength emitter-detector assembly production for fitness tracker board space reduction.
Germany
Chronic disease management programs integrate prescription-grade pulse oximetry into home-based care protocols with regulated reimbursement channels. EU MDR biocompatibility certification requirements impose extended testing timelines for skin-contacting optical sensors. Bavarian medical device engineering clusters develop validated interoperability specifications for hospital telemetry infrastructure.
Netherlands
Remote patient monitoring penetration for elderly care creates demand for clinical-grade optical pulse detection in non-hospital settings. EMA oversight of Class IIa pulse oximetry devices coordinates with notified body capacity constraints extending certification timelines. Eindhoven innovation clusters concentrate CMOS analog design talent for tissue optics algorithm development.
Optical Pulse Sensor Market Competitive Environment
Analog semiconductor specialists and optical component fabricators split the market across divergent margin structures and qualification requirements. Consolidation pressures intensify as hospital procurement departments enforce single-source contracts specifying performance thresholds exceeding regulatory minimums. Three archetypes dominate: integrated analog front-end providers, specialized LED-photodiode packagers, and multi-parameter sensor fusion platforms. Competitive moves concentrate on direct-to-OEM design-in relationships and backward integration into emitter foundry capacity.
Within the analog front-end tier, Texas Instruments Inc and Silicon Laboratories Inc represent design-win momentum anchored by portfolio breadth in medical-grade pulse detection signal conditioning. ROHM Co Ltd exemplifies the Japanese packaging specialist archetype, occupying a position tied to compact multi-wavelength assemblies for wearable integration. Among diversified optical component providers, ams-OSRAM AG sits within the converged emitter-detector platform segment following corporate combination.
| Leading Market Players |
|---|
| Maxim Integrated Products Inc |
| Osram Licht AG |
| ROHM Co Ltd |
| Texas Instruments Inc |
| Silicon Laboratories Inc |
| Valencell Inc |
| TE Connectivity Ltd |
| Microchip Technology Inc |
| ams-OSRAM AG |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta manufacturing clusters concentrate photoplethysmography module capacity for smartwatch integration, compressing procurement timelines while amplifying price leverage for volume buyers in consumer electronics supply chains. Near-infrared LED foundry constraints in Japan and Taiwan create input cost volatility that propagates through tiered supplier pricing structures.
Pricing Analysis
Chinese OEMs command 15-25% price discounts versus German hospital procurement specifications for equivalent optical front-end architectures. Three-tier pricing structure across FDA-cleared medical, CE-marked wellness, and uncertified fitness tiers separates reimbursement-eligible devices from consumer accessories. Cost compression in entry-level fitness trackers is intensifying because Shenzhen EMS providers consolidate orders across multiple wearable brands. Consumer segments exhibit highest price sensitivity, while German hospital purchasing cooperatives enforce performance premiums exceeding regulatory minimums.
Supply Chain Analysis
Extended payment terms from Japanese LED-photodiode packagers to Taiwanese foundry partners illustrate supply-chain finance dependencies anchoring East Asian component flows. Manufacturing concentrates in China, Japan, and Taiwan, with Yangtze River Delta and Tokyo-Osaka corridors housing multi-wavelength emitter-detector assembly production. Raw material dependencies include 940-nanometer near-infrared epitaxial wafers, CMOS analog front-end silicon, and biocompatible encapsulation resins. Single-source vulnerability around Japanese near-infrared LED capacity creates disruption exposure during demand spikes. Distribution runs through direct-to-OEM module supply relationships bypassing traditional component distribution layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized talent pools for tissue optics algorithm development remain concentrated in Greater Boston and Eindhoven innovation clusters, constraining supplier scaling and consolidating competitive advantage among incumbents with established recruitment networks.
For Market Incumbents: Entrench design-win relationships with Chinese smartwatch OEMs through co-located application engineering support in Shenzhen and Dongguan manufacturing corridors. Backward integration into 940-nanometer emitter foundry capacity secures input supply against Japanese and Taiwanese capacity constraints. FDA 510(k) predicate device strategy complications threaten margin structures through extended clinical validation timelines; prioritize dual-track qualification for both US and China NMPA pathways to amortize regulatory investment. For New Entrants and Emerging Players: Mid-tier wellness wearables in European markets with simplified CE self-certification routes represent the most penetrable entry point for optical pulse sensor module suppliers lacking FDA clearance infrastructure. Research-grade multi-parameter sensor fusion platforms for academic cardiovascular signal studies offer lower regulatory barriers and higher margin per unit than consumer fitness tracker supply. Direct-to-OEM technical sales engagement with wearable device engineering teams bypasses entrenched distribution relationships and accelerates specification cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors analog front-end semiconductor specialists with medical-grade pulse detection signal conditioning portfolios over pure-play optical component fabricators facing commoditization pressure. Long-term viability hinges on convergence toward single-module vital sign platforms integrating optical pulse detection with temperature and galvanic skin response sensing. Acquisition target archetype: LED-photodiode packaging specialists with compact multi-wavelength assembly capabilities and existing design-in relationships with Japanese wearable OEMs. Signal to watch: NMPA approval timeline compression for wearable medical devices indicating regulatory pathway maturation that would validate multi-market registration strategy investments.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Dual-Track Submission | Simultaneous US and China NMPA pathways amortize clinical validation costs across regulatory jurisdictions. |
| Emitter Foundry Capacity Expansion | Captive 940-nanometer near-infrared LED production insulates against Japanese and Taiwanese supply concentration. |
| Hospital System GPO Partnership | Validated interoperability with US health system purchasing cooperatives secures multi-parameter monitor contracts. |
| Multi-Parameter Sensor Fusion Platform | Single-module vital sign integration targets German and Dutch remote patient monitoring reimbursement channels. |
| Direct-to-OEM Technical Sales Force | Shenzhen-based application engineering accelerates design-in cycles with Chinese smartwatch manufacturers. |
Study Parameters
Initial hypotheses were tested against primary input from biomedical engineers at wearable device OEMs, GPO contracts managers at US health system purchasing cooperatives, regulatory affairs leads at optical sensor module suppliers, and analog front-end semiconductor product managers, then refined against secondary validation from FDA 510(k) clearance databases, NMPA approval registries, hospital procurement contract disclosures, and EMS provider capacity reports. Bottom-up unit shipment estimates triangulated with top-down market value reconstructions across the analysis window.
Demand-supply-balance framing anchored the analytical framework, modeling volume and value outputs across product type, end user, technology, and application segmentation dimensions throughout the forecast period. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in adjacent wearable sensor categories. Industry-specific forecast inputs included NMPA review timeline trajectories and EU MDR notified body capacity constraints affecting Class IIa pulse oximetry certification timelines.
Practitioners should monitor FDA pulse oximeter accuracy guidance evolution, EU MDR biocompatibility testing timeline extensions, and near-infrared LED foundry capacity utilization for early signals of forecast revision triggers. Forecasts reflect assumptions about regulatory pathway stability and component supply continuity. Macroeconomic demand contraction in consumer electronics, regulatory reclassification of wellness devices as medical products, or breakthrough alternative sensing modalities would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
Integrated Circuit Optocouplers Market
Optoelectronics
2-Ethyl-3,4-Ethylenedioxythiophene Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
Green Laser Diode Market
Optoelectronics
United States Optoelectronics Market
Optoelectronics
Optocoupler IC Market
Optoelectronics
Optoelectronic Development Tools Market
Optoelectronics
EPON ONU Market
Optoelectronics
3D Projector Market
Optoelectronics
Laser Diode Market
Optoelectronics
Light Projector Market
Optoelectronics
Global Shortwave Infrared (SWIR) Market