
 Global Opto-Isolator Market | 2026-2036
Global Opto-Isolator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Opto-Isolator Market Outlook
Project finance for captive semiconductor foundries is tilting competitive dynamics toward firms with balance-sheet capacity for multi-year wafer supply commitments. Broadcom Inc. leverages vertical integration across III-V compound semiconductor fabrication to secure gallium arsenide die supply for high-speed isolators. Infineon Technologies anchors European automotive qualification pathways with AEC-Q100 certified phototransistor modules. Toshiba Corporation dominates discrete photodiode output through legacy optoelectronic packaging scale in Japan.
An opto-isolator transfers electrical signals between isolated circuits using light, typically employing an LED emitter and photodetector pair separated by a transparent dielectric barrier with isolation voltages from 2.5 kV to 10 kV; its primary purpose is breaking ground loops and protecting sensitive logic from high-voltage transients in switched-mode power supplies and motor drives. Phototransistor modules retain the largest revenue share due to their cost-positioning in industrial automation motor controllers, while integrated circuit isolators with CMOS-compatible outputs capture the fastest growth from telemetry and battery management system designers. Fiber optic technology commands premium positioning in medical imaging and aerospace applications where electromagnetic immunity requirements exceed standard plastic package capabilities.
FDA 21 CFR Part 820 quality system regulations for medical devices incorporating patient-contact isolation, plus IEC 60601-1 medical electrical safety standards, compel manufacturers to maintain traceable die-attach and encapsulation processes. The EU AI Act and Machinery Directive in Europe are extending functional safety documentation requirements to isolators embedded in autonomous system signal chains. Stakeholders must monitor how China's GB 4943.1 information technology safety standards and evolving SAMR certification timelines reshape market access for imported opto-isolator modules.
Market Dynamics
Project finance for captive semiconductor foundries is tilting competitive dynamics toward firms with balance-sheet capacity for multi-year wafer supply commitments. Electric vehicle powertrain electrification by OEMs in Germany, Japan, and the United States is accelerating demand for high-voltage isolation components.
Growth Catalysts
- Powertrain electrification:OEMs in Germany, Japan, and the United States are accelerating demand for high-voltage isolation components in electric vehicle architectures.
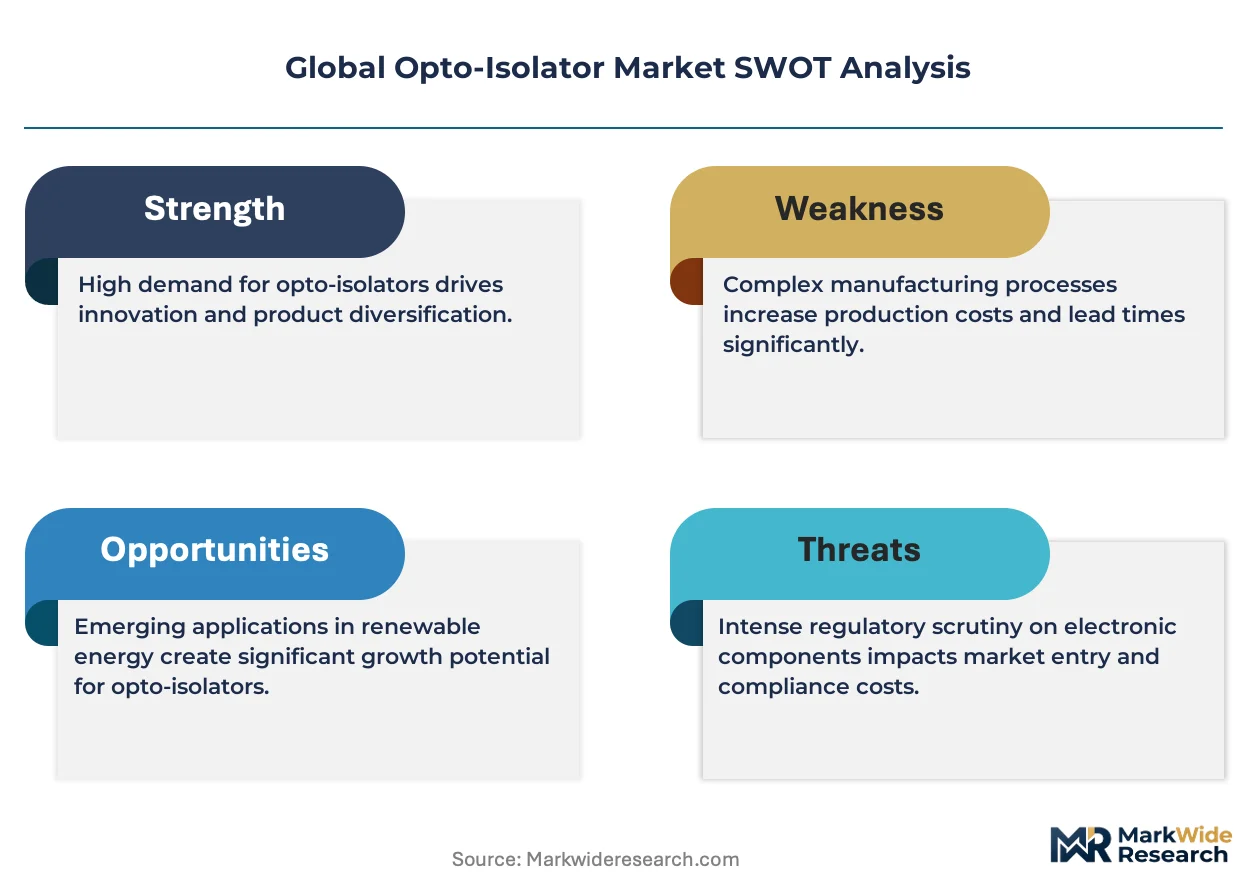
- IEC 60747 standards:Tightening safety standards for reinforced insulation are elevating qualification thresholds and filtering marginal suppliers from certification pathways.
- China's industrial automation corridor:Concentrated demand around Shenzhen and Shanghai is pulling phototransistor module volumes for motor controller integration.
Market Restraints
- III-V compound semiconductor supply concentration:Gallium arsenide die availability depends on limited foundry capacity in Japan and the United States.
- UL 1577 certification friction:Reinforced insulation testing timelines extend product qualification cycles by 8-14 months for new entrants.
- Magnetic isolator substitution:Capacitive and inductive coupling technologies are capturing share in sub-5 kV applications where EMI tolerance permits.
Strategic Opportunities
- India's manufacturing incentives:PLI scheme benefits for electronics components are attracting module assembly investments serving industrial automation demand.
- FDA 21 CFR Part 820 alignment:Medical device quality system regulations create premium positioning for traceable die-attach processes in patient-contact isolation.
- CMOS-compatible IC isolators:Integration of silicon photonics with standard CMOS foundry processes is opening telemetry and battery management system design wins.
Industry Challenges
- AEC-Q100 automotive qualification:Phototransistor modules require extended temperature cycling validation that strains R&D timelines and capital allocation.
- Legacy system integration:Fiber optic isolators face mechanical incompatibility with existing PCB footprints in retrofit industrial controller deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Opto-Isolator Market |
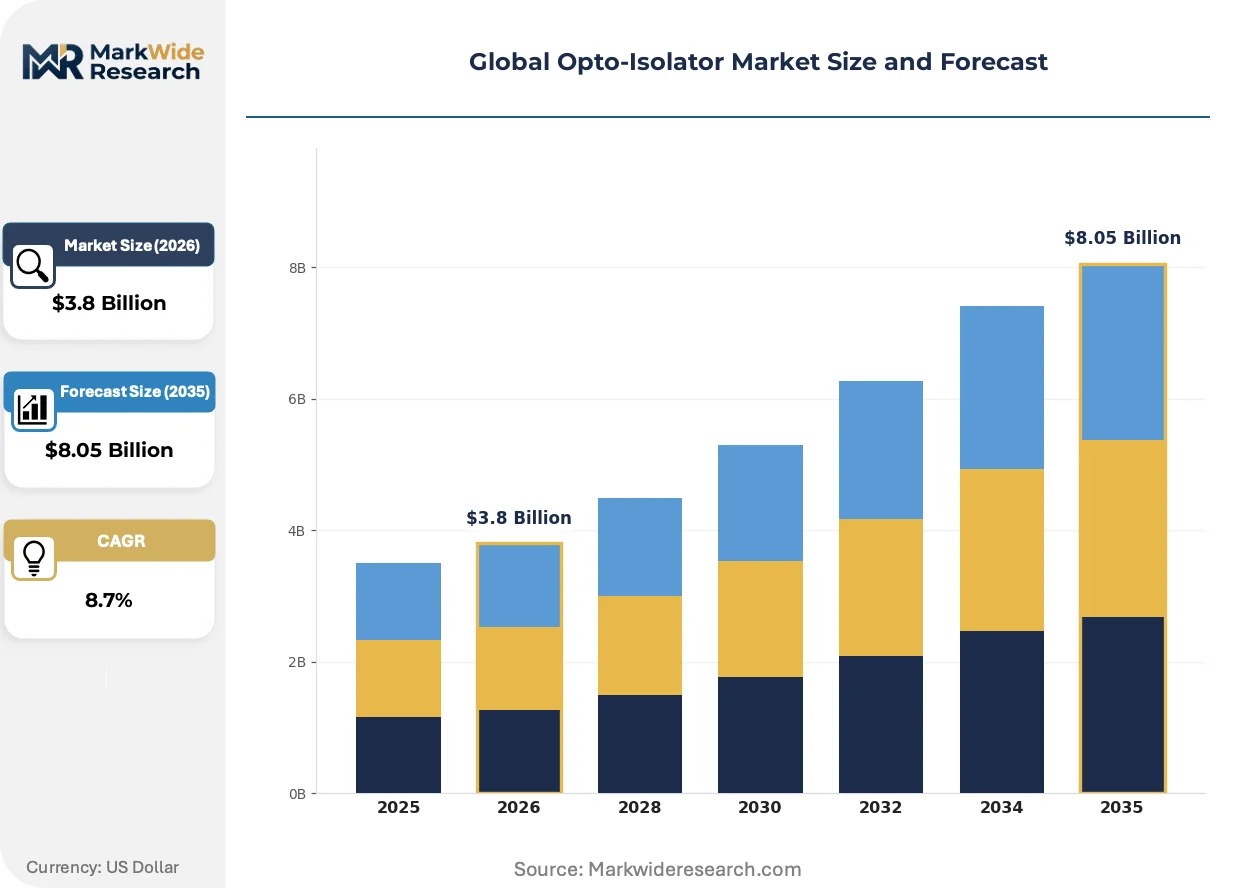
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Phototransistor, Photodiode, Phototransistor Module, Integrated Circuit Technology: Silicon, Gallium Arsenide, Plastic Opto-Isolators, Fiber Optic Application: Consumer Electronics, Telecommunications, Automotive, Industrial Automation End User: OEMs, Aftermarket Providers, Telecommunications Firms, Electronics Manufacturers |
| Companies Covered | Broadcom Inc., Infineon Technologies, Toshiba Corporation, Semiconductor Components Industries, LLC, Littelfuse, Inc., Texas Instruments Incorporated, Analog Devices, Inc., Corning Optical Communications, Edmund Optics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Opto-Isolator Market Strategic Shifts
Digital isolation architectures are compressing the traditional LED-photodetector paradigm. Three distinct vectors are reshaping component specifications and procurement patterns across automotive, medical, and industrial verticals.
Silicon-based digital isolators with integrated CMOS output stages are virtualizing the optoelectronic conversion layer. Battery management system designers in the United States and Germany are adopting these devices for high-voltage cell monitoring. This virtualization is compressing board area requirements and enabling 150 Mbps signal rates that phototransistor modules cannot match.
EU AI Act compliance requirements are extending functional safety documentation to isolators embedded in autonomous system signal chains. Machinery Directive harmonization demands traceable failure-mode analysis for safety-critical isolation barriers. Automotive Tier-1 suppliers in Germany are restructuring component qualification workflows to satisfy dual regulatory coverage.
Direct material pass-through contracts are displacing fixed-price annual agreements in industrial procurement. Motor drive manufacturers in China's Pearl River Delta are negotiating gallium arsenide die cost escalation clauses with packaging partners. This reconfiguration is most visible in high-volume automation corridors where spot market exposure for III-V substrates has compressed margin predictability.
Global Opto-Isolator Market Segmentation
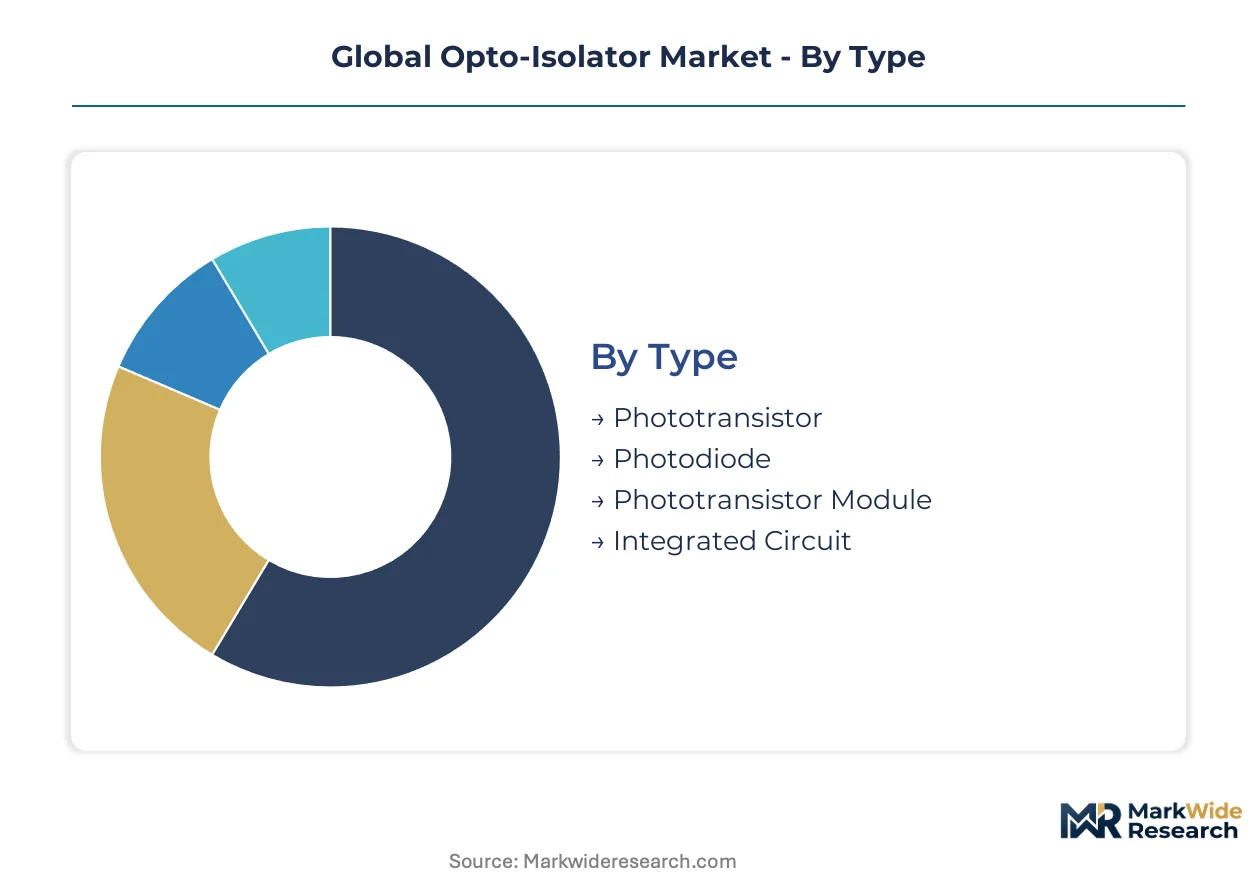
Opto-isolator procurement patterns diverge sharply across technical specifications and end-use requirements. Component selection hinges on isolation voltage ratings, switching speed demands, and the regulatory burden of target applications.
Type:
Cost tier differentiation separates commodity phototransistor outputs from precision-engineered integrated circuit isolators.
- Phototransistor:Darlington-pair configurations dominate low-speed switching below 100 kHz. Motor drive manufacturers in China's Pearl River Delta absorb volume shipments for variable frequency controller feedback loops.
- Photodiode:PIN structures deliver nanosecond response times for high-speed data links. Telecommunications infrastructure deployment in Germany pulls hermetic metal-can packages for central office equipment.
- Phototransistor Module:Pre-assembled emitter-detector pairs with molded isolation barriers. Industrial automation integrators in Japan specify these for PLC I/O isolation.
- Integrated Circuit:CMOS-compatible digital outputs with integrated signal conditioning. Battery management system designers in the United States specify these for high-voltage cell monitoring arrays.
Phototransistor modules hold installed capacity. Integrated circuit isolators are rotating up the share rankings.
Technology:
Supply concentration for compound semiconductor substrates creates tiered availability across material platforms.
- Silicon:Standard CMOS foundry processes enable cost scaling for digital isolator architectures. Foundry capacity in Taiwan and the United States supports volume expansion for automotive telemetry applications.
- Gallium Arsenide:Direct bandgap properties optimize infrared emitter efficiency at 850-940 nm. Epitaxial wafer supply from Japanese and American producers constrains availability for high-reliability aerospace programs.
- Plastic Opto-Isolators:Molded epoxy packages with 2.5-5 kV isolation ratings. Consumer electronics assemblers in Vietnam and Mexico specify these for switched-mode power supply feedback.
- Fiber Optic:Silica waveguides with immunity to electromagnetic interference exceeding 100 V/m. Medical imaging OEMs in the United States and Switzerland mandate these for MRI-compatible patient isolation.
Plastic opto-isolators hold installed capacity. Fiber optic variants are rotating up the share rankings.
Application:
Customer type intensity varies from high-volume consumer electronics to qualification-heavy automotive programs.
- Consumer Electronics:Charger and adapter designs require sub-dollar isolation for 3-5 kV withstand. Contract manufacturers in Dongguan and Shenzhen drive procurement consolidation.
- Telecommunications:Central office and base station equipment demands 50+ year operational life. NEBS compliance in the United States and ETSI standards in Europe filter supplier qualification.
- Automotive:AEC-Q100 Grade 1 temperature cycling from -40°C to 125°C. Powertrain electrification by German and Japanese OEMs accelerates high-voltage isolation component demand.
- Industrial Automation:Motor drive and PLC applications tolerate wider parameter variation. System integrators in China's industrial corridor around Shanghai specify phototransistor modules for cost-sensitive controller designs.
Consumer electronics holds installed capacity. Automotive applications are rotating up the share rankings.
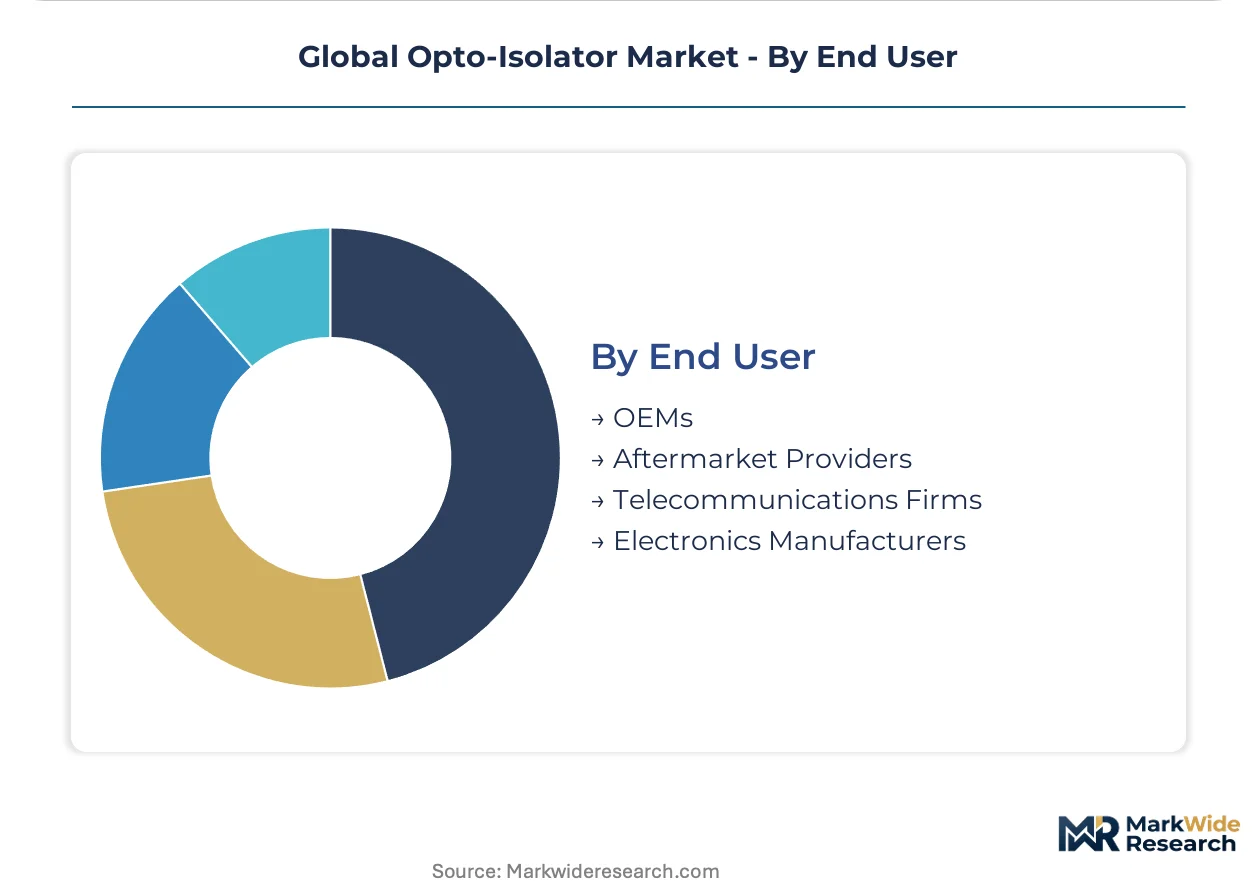
End User:
Volume scale and technical specification authority concentrate differently across procurement archetypes.
- OEMs:Original equipment manufacturers with captive design authority and multi-year production forecasts. Automotive OEMs in Germany and Japan negotiate direct wafer supply agreements for gallium arsenide die.
- Aftermarket Providers:Repair and refurbishment channels with fragmented demand patterns. Industrial maintenance distributors in the United States stock phototransistor modules for legacy controller replacement.
- Telecommunications Firms:Network operators with centralized procurement and stringent qualification protocols. Tier-1 carriers specify IEC 60747-compliant reinforced insulation for central office power systems.
- Electronics Manufacturers:Contract assemblers and EMS providers with variable mix flexibility. Module assembly investments in India under PLI scheme benefits serve automation demand.
OEMs hold installed capacity. Electronics manufacturers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government manufacturing incentives and industrial electrification mandates are reshaping geographic demand patterns for opto-isolator components. National semiconductor strategies in Germany, Japan, China, India, and the United States are channeling investment toward high-voltage isolation supply chains.
United States
Powertrain electrification by Detroit-area OEMs accelerates procurement of AEC-Q100 certified phototransistor modules for battery management systems. FDA 21 CFR Part 820 quality system regulations compel traceable die-attach processes for medical device isolators. The Southwest semiconductor corridor around Austin and Phoenix concentrates CMOS-compatible digital isolator design activity.
Germany
Automotive Tier-1 suppliers restructure qualification workflows to satisfy EU AI Act functional safety documentation requirements for autonomous system signal chains. Machinery Directive harmonization demands traceable failure-mode analysis for safety-critical isolation barriers. Industrial automation clusters in Bavaria and Baden-Württemberg specify reinforced insulation components for motor drive integration.
China
GB 4943.1 information technology safety standards and evolving SAMR certification timelines reshape market access for imported opto-isolator modules. Dual carbon goals accelerate industrial automation deployment in manufacturing corridors. The Pearl River Delta around Shenzhen concentrates phototransistor module demand for variable frequency controller feedback loops.
Japan
METI semiconductor supply chain resilience initiatives support domestic gallium arsenide epitaxial wafer production for high-reliability aerospace programs. JIS standards compliance filters supplier qualification for telecommunications infrastructure. Legacy optoelectronic packaging scale in Tokyo-Osaka industrial corridors maintains discrete photodiode output dominance.
India
PLI scheme benefits for electronics components attract module assembly investments serving industrial automation demand. BIS certification requirements for information technology equipment create qualification pathways for domestic isolator sourcing. Gujarat and Maharashtra industrial zones concentrate contract manufacturing capacity for switched-mode power supply feedback applications.
Global Opto-Isolator Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply chain positions. Consolidation concentrates around III-V compound semiconductor fabrication capacity and automotive qualification pathways. Three archetypes dominate: vertically integrated III-V fabricators, CMOS-digital isolator specialists, and legacy optoelectronic packaging houses. Capacity expansion and strategic wafer supply agreements represent the dominant competitive moves as project finance requirements filter marginal participants.
Among American semiconductor conglomerates, Broadcom Inc. and Texas Instruments Incorporated occupy positions anchored by balance-sheet capacity for multi-year supply commitments. Infineon Technologies AG exemplifies European automotive qualification specialists with AEC-Q100 certified module portfolios. Toshiba Corporation represents Japanese legacy packaging scale in discrete photodiode segments. These three anchors illustrate how geographic fabrication concentration and end-market certification requirements stratify competitive positioning across the component spectrum.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Infineon Technologies |
| Toshiba Corporation |
| Semiconductor Components Industries, LLC |
| Littelfuse, Inc. |
| Texas Instruments Incorporated |
| Analog Devices, Inc. |
| Corning Optical Communications |
| Edmund Optics Inc. |
| Others |
Value Chain & Pricing Dynamics
Gallium arsenide epitaxial wafer supply from Japanese and American producers concentrates upstream margin capture for high-reliability opto-isolator tiers, while downstream pricing power fragments across certification-grade boundaries and volume-scale procurement archetypes.
Pricing Analysis
Certification level creates the primary spread between AEC-Q100 automotive-grade modules and consumer electronics plastic packages. Contract-based long-term offtake agreements dominate OEM procurement for high-voltage isolation components, with spot-market exposure concentrated in industrial automation corridors. Price differentiation hinges on UL 1577 reinforced insulation validation timelines and gallium arsenide die cost escalation clauses. Cost compression in standard phototransistor tiers is intensifying because magnetic isolator substitution erodes share in sub-5 kV applications, making consumer electronics assemblers most price-sensitive while medical device OEMs absorb premium positioning for traceable die-attach processes.
Supply Chain Analysis
Gallium arsenide epitaxial wafers feed from limited foundry capacity in Japan and the United States, with silicon CMOS processes anchoring digital isolator cost scaling in Taiwan. Raw material dependencies span III-V compound semiconductor substrates, molded epoxy isolation barriers, and hermetic metal-can packages for telecommunications infrastructure. Single-source vulnerability concentrates in Japanese gallium arsenide epitaxial supply for aerospace-grade fiber optic isolators. Distribution runs through direct wafer supply agreements between automotive OEMs and vertically integrated fabricators, supplemented by contract manufacturers in India and Vietnam for consumer electronics feedback applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital isolation architectures are collapsing the traditional LED-photodetector paradigm into CMOS-compatible platform economics, with silicon photonics integration creating interoperability standards that reshape component procurement across automotive, medical, and industrial ecosystems.
For Market Incumbents: Insulate AEC-Q100 certification pathways against magnetic isolator substitution by deepening backward integration into gallium arsenide epitaxial wafer supply. Expand captive III-V fabrication capacity in Japan or the United States to secure die availability for high-reliability aerospace and medical tiers. Prioritize FDA 21 CFR Part 820 quality system alignment for patient-contact isolation premium positioning. For New Entrants and Emerging Players: Pursue CMOS-compatible IC isolator design wins in battery management system telemetry where phototransistor modules cannot match 150 Mbps signal rates. Target India's PLI scheme benefits for module assembly investments serving industrial automation demand. Lead with direct material pass-through contract structures that displace fixed-price agreements in China's Pearl River Delta motor drive procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive qualification specialists lacking silicon photonics integration capabilities. Five-to-ten year viability hinges on platform standardization around CMOS-digital architectures versus legacy optoelectronic packaging. Watch for EU AI Act functional safety documentation requirements extending to isolators in autonomous system signal chains as inflection indicator for qualification-heavy asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into III-V Fabrication | Captive gallium arsenide epitaxial supply secures die availability for aerospace and automotive qualification pathways. |
| CMOS-Compatible Digital Isolator Development | Silicon photonics integration enables 150 Mbps telemetry rates that phototransistor modules cannot match. |
| FDA 21 CFR Part 820 Quality System Alignment | Traceable die-attach processes create premium positioning in patient-contact medical device isolation. |
| India PLI Scheme Module Assembly Investment | Contract manufacturing capacity serves industrial automation demand with BIS certification pathway access. |
| EU AI Act Functional Safety Documentation | Traceable failure-mode analysis satisfies Machinery Directive harmonization for autonomous system signal chains. |
Study Parameters
A standing panel of automotive Tier-1 supplier procurement directors, industrial automation system integrators, medical device quality assurance leads, and semiconductor foundry planning officers provided ongoing calibration. Primary interviews combined with secondary validation from IEC standard documentation, FDA 510(k) filings, SEC 10-K supply chain disclosures, and customs trade data for III-V compound semiconductor substrates. Bottom-up component demand modeling triangulated against top-down OEM electrification capex projections.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning isolation technology type, output device architecture, application vertical, and regional regulatory cluster. CAGRs derived from weighted average of OEM platform electrification timelines and industrial automation deployment curves. Industry-specific forecast inputs included AEC-Q100 qualification pipeline visibility and SAMR certification timeline evolution for China market access.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or automotive production schedules would shift the trajectory. Forecasts reflect documented assumptions about gallium arsenide epitaxial wafer supply expansion and IEC 60747 standard harmonization timelines. Cross-checking against IHS Markit vehicle electrification content forecasts and SEMI wafer capacity announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
2-Ethyl-3,4-Ethylenedioxythiophene Market
Optoelectronics
3D Projector Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
Infrared Emitter and Receiver Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Gaas Wafer and Epiwafer Market
Optoelectronics
United States Optoelectronics Market
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
Thermophotovoltaics Market
Optoelectronics
Optocoupler IC Market
Optoelectronics
Global Shortwave Infrared (SWIR) Market
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
Global Optocoupler Market
Optoelectronics
Light Projector Market
Optoelectronics
China Optoelectronics Market