
 Smart Compact Projectors Market | 2026-2036
Smart Compact Projectors Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Compact Projectors Market Insights
4K resolution capability is redrawing the competitive boundary between premium and mass-market smart compact projectors. XGIMI leverages its laser-autofocus R&D pipeline to sustain product refresh velocity in the home entertainment tier. Epson anchors the professional portable segment through its heritage in 3LCD color brightness engineering. BenQ competes on short-throw lens architecture, differentiating its gaming-oriented lineup from conventional throw-distance designs.
Smart compact projectors are self-contained display devices integrating solid-state light engines, wireless connectivity modules, and onboard operating systems within sub-2kg form factors, typically delivering 100-500 ANSI lumens through DLP or LCD microdisplay architectures for projection surfaces up to 120 inches. DLP technology dominates the portable tier due to Texas Instruments' chipset ecosystem and compact optical train requirements, while LCD variants retain cost advantages in fixed classroom installations where color accuracy standards matter more than mobility. Gaming applications represent the fastest-expanding demand pool as low-input-lag modes below 16ms attract console and PC users seeking immersive large-format play without dedicated screen infrastructure.
FCC Part 15 emissions compliance governs wireless radio integration for US-bound units, while EU REACH and RoHS frameworks restrict hazardous substances in optical coatings and circuit assemblies. China's GB standards for audio-visual equipment, administered by MIIT, mandate energy labeling and electromagnetic compatibility certification for domestic sales. Stakeholders must monitor divergence between regional connectivity protocols as Matter and Wi-Fi 7 adoption timelines create fragmentation in streaming ecosystem integration.
Market Dynamics
Resolution escalation toward 4K native panels is compressing mid-tier margins while laser phosphor illumination architectures displace legacy lamp engines across portable form factors. Shenzhen-based manufacturing clusters accelerate cost curves for DLP optical trains.
Growth Catalysts
- EU Ecodesign energy efficiency mandates:These frameworks accelerate LED and laser engine adoption by phasing out high-wattage lamp-based systems in consumer electronics categories.
- Home entertainment system integration:Cinema-grade projection demand in sub-50 square meter apartments drives 100-300 ANSI lumen product development for ambient-light viewing.
- Texas Instruments DLP chipset ecosystem:Compact optical train requirements enable sub-1kg portable designs with automated keystone correction for mobile deployment.
Market Restraints
- Texas Instruments DLP monopoly:Single-source dependency for micro-mirror array chipsets creates supply vulnerability and pricing power concentration in semiconductor fabrication.
- Optical engine thermal management:Passive cooling constraints in sub-2kg enclosures limit sustained brightness output below 500 ANSI lumens for extended gaming sessions.
- FCC Part 15 emissions certification:Radio frequency testing timelines for integrated Wi-Fi 6E modules extend product launch cycles by 8-14 weeks for US market entry.
Strategic Opportunities
- India residential real estate densification:Mumbai and Bangalore apartment construction favors space-efficient display solutions over conventional television panels above 65 inches.
- Wi-Fi 7 and Matter protocol convergence:Seamless smart home ecosystem integration enables projector-as-hub positioning in unified entertainment control architectures.
- Outdoor camping and vanlife segments:Battery-powered portable units with 2-4 hour runtime capture recreational vehicle and wilderness hospitality applications.
Industry Challenges
- Optical design talent scarcity:Compound lens system engineering expertise concentrates in legacy camera and microscope industries, not consumer electronics.
- Multi-regional certification parallelism:Simultaneous FCC, CE marking, and MIIT GB standard compliance requires redundant testing protocols for identical hardware variants.
- Software-hardware integration complexity:Android TV and proprietary OS fragmentation demands separate engineering tracks for streaming codec optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Compact Projectors Market |
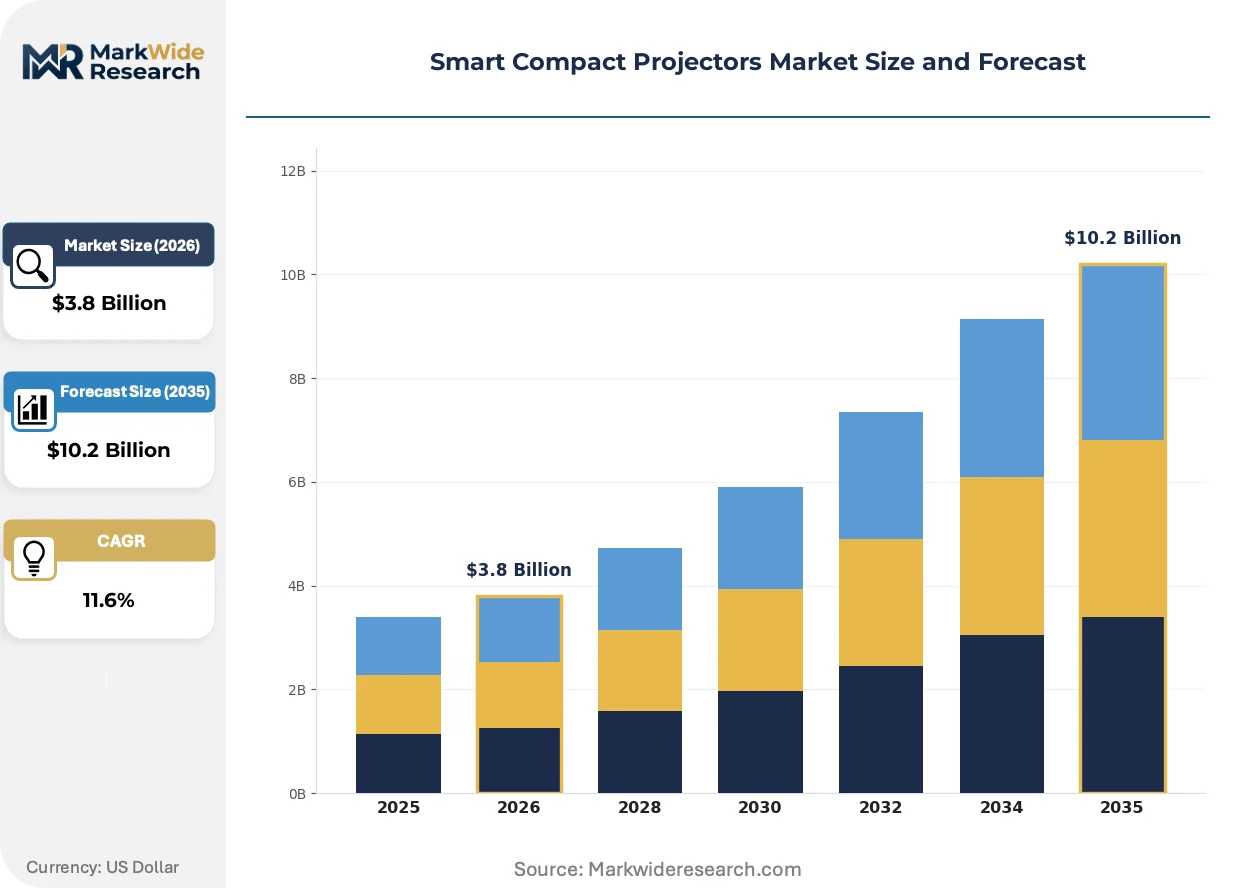
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Projectors, Portable Projectors, Fixed Projectors, Short-Throw Projectors Technology: DLP, LCD, LED, LCoS Application: Home Entertainment, Business Presentations, Education, Gaming End User: Consumers, Corporates, Educational Institutions, Event Organizers |
| Companies Covered | Anker Nebula, XGIMI, LG Electronics, Epson, ViewSonic, BenQ, Sony, Optoma, AAXA Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Compact Projectors Market Trends and Innovations
Laser-based solid-state illumination is redrawing technical boundaries between professional and consumer portable projection tiers. Three interconnected developments are compressing product cycles and reshaping competitive positioning.
RGB triple-laser architectures are decomposing the traditional brightness-cost tradeoff in sub-2kg enclosures. Gaming-oriented buyers now demand 300+ ANSI lumen output for daylight-visible competitive play. This capability compression eliminates the historical segmentation between portable convenience and fixed-installation performance.
EU REACH restrictions on hazardous substances in optical coatings are forcing reformulation of dichroic mirror production processes. Manufacturers must substitute cadmium-free quantum dot phosphors while maintaining color gamut coverage. Professional calibration services in Germany and France report extended turnaround times for recertified optical assemblies.
Direct-to-consumer channel expansion is fragmenting traditional electronics retail dependence in North America and Western Europe. Brand-owned storefronts and subscription-based hardware financing displace big-box showroom placement for premium tier products. This shift concentrates customer relationship data with manufacturers rather than retail intermediaries.
Smart Compact Projectors Market Segmentation
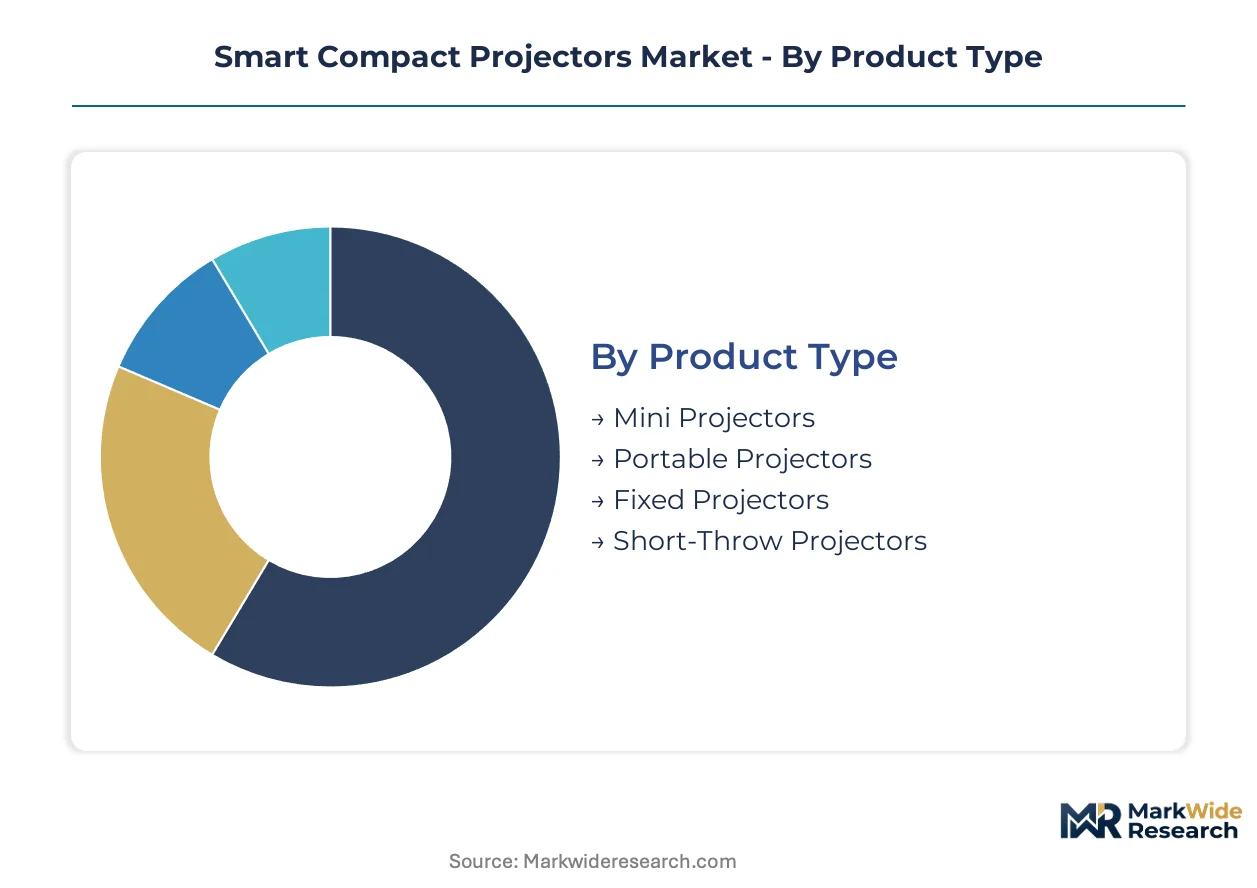
Segmentation in the Smart Compact Projectors Market reveals how form factor, illumination technology, and use case interact to create distinct competitive arenas. Manufacturers optimize optical engines and connectivity bundles differently for mobile versus fixed deployment scenarios.
Product Type:
Mini and portable variants dominate export flows from Shenzhen manufacturing clusters, while fixed and short-throw installations concentrate in domestic Chinese and North American home theater markets.
- Mini Projectors:Sub-500g enclosures with integrated batteries deliver 100-200 ANSI lumens through single-chip DLP architectures. Demand clusters in India's metro apartment segments where wall-mounting constraints eliminate television alternatives.
- Portable Projectors:500g-2kg designs with automated keystone correction and Wi-Fi 6E modules target camping and vanlife recreational users across Germany, France, and the US Pacific Northwest. Battery runtime extension to 4+ hours drives R&D allocation.
- Fixed Projectors:Ceiling-mounted installations with laser phosphor engines serve dedicated home cinema rooms in suburban US and Australian markets.
- Short-Throw Projectors:Ultra-short-throw lens assemblies project 100-inch images from 30cm distances, eliminating shadow interference in Japan's compact living spaces.
Portable projectors hold the largest share; momentum sits with mini projectors.
Technology:
Illumination and display architectures separate premium laser-DLP combinations from cost-optimized LCD-LED configurations in volume manufacturing.
- DLP:Texas Instruments' micromirror chipsets enable sub-1kg optical trains with high native contrast ratios. Gaming applications in South Korea and the US drive demand for sub-16ms input lag implementations.
- LCD:Three-panel liquid crystal architectures deliver superior color accuracy for classroom installations in France and Germany where sRGB coverage standards exceed 95%.
- LED:Solid-state RGB LED engines dominate entry-level portable segments with 20,000-hour lifespans eliminating lamp replacement costs.
- LCoS:Liquid crystal on silicon microdisplays enable native 4K resolution in premium home theater tiers with minimal screen door effect.
DLP captures the volume base; LCoS posts the steepest expansion trajectory in premium tiers.
Application:
End-use concentration varies sharply by geography, with gaming and home entertainment pulling volume in East Asia and North America while education drives institutional procurement in Europe.
- Home Entertainment:Streaming-optimized projectors with Android TV and Netflix certification serve sub-50 square meter apartments in Mumbai, Shanghai, and São Paulo where 65-inch television placement is structurally impossible.
- Business Presentations:Brightness-optimized 300+ ANSI lumen units with instant-on laser engines target corporate road warriors in London, Frankfurt, and New York financial districts.
- Education:Dust-sealed optical engines with 5-year lamp-free operation meet total cost-of-ownership requirements for K-12 deployments in Italy and Spain.
- Gaming:Low-latency modes below 16ms attract console and PC users in Tokyo, Seoul, and Los Angeles seeking immersive 120-inch play without dedicated screen infrastructure.
Home entertainment commands installed base; gaming gains share fastest among application segments.
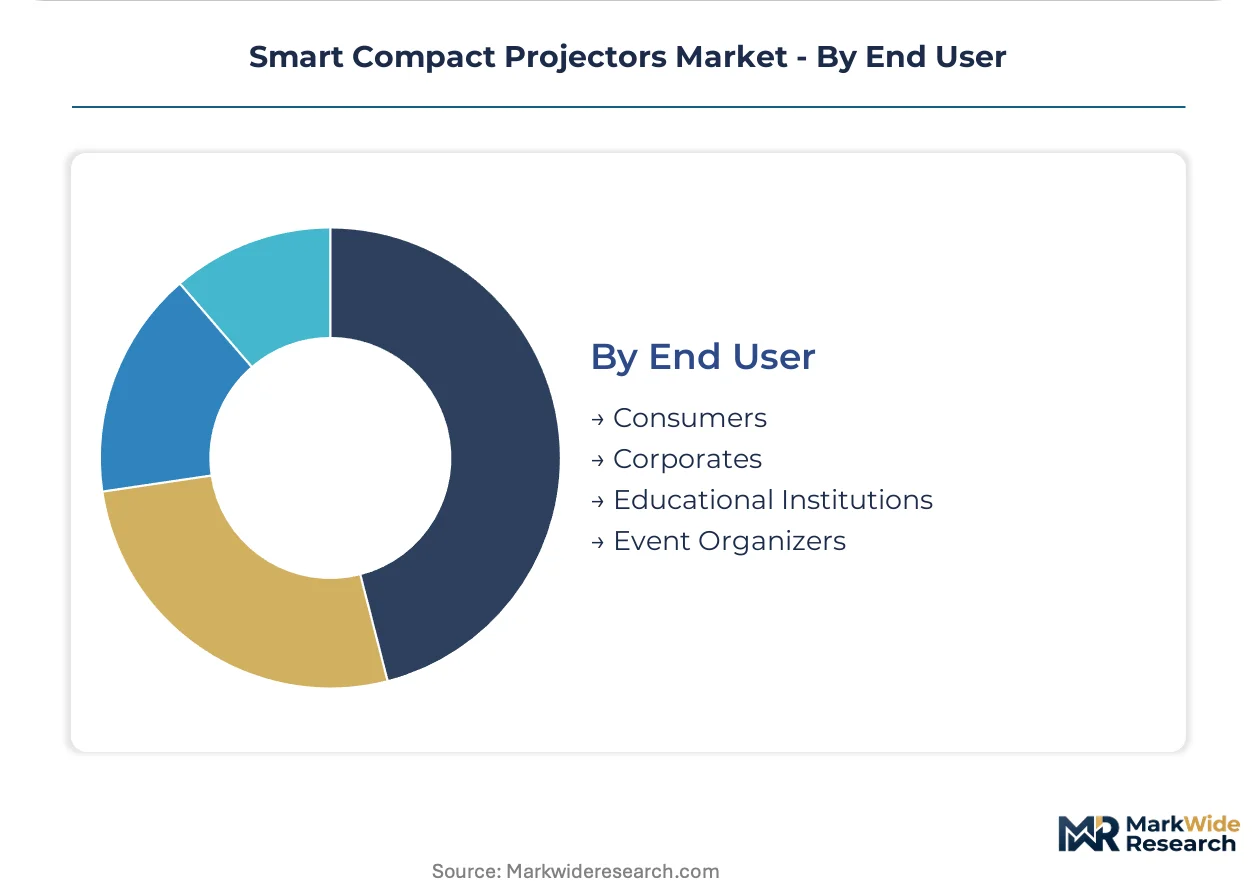
End User:
Procurement patterns diverge between direct-to-consumer channels and institutional tender processes with extended certification requirements.
- Consumers:Individual purchasers through Amazon, JD.com, and brand-owned storefronts prioritize portability and streaming app integration over raw brightness specifications.
- Corporates:IT procurement departments in US and German multinationals standardize on fleet-deployable units with centralized device management and 3-year warranty terms.
- Educational Institutions:Ministry of Education tenders in China and state-level purchasing cooperatives in Texas and California mandate ENERGY STAR compliance and minimum 10,000-hour light source longevity.
- Event Organizers:Rental and staging companies in Dubai, Singapore, and Las Vegas require rapid-deployment units with interchangeable lens options for temporary projection mapping installations.
Consumers represent the largest addressable base; event organizers climb the fastest as experiential marketing budgets recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and Dongguan electronics clusters compress production costs for DLP optical trains, while demand fragmentation pulls finished goods toward distinct national consumption patterns shaped by housing density and regulatory frameworks.
China
Apartment downsizing in Shanghai and Beijing accelerates demand for sub-50 square meter cinema solutions. MIIT-administered GB standards mandate electromagnetic compatibility certification for domestic sales. Dongguan manufacturing corridors iterate laser-autofocus modules at 6-month refresh cycles.
United States
Suburban home theater installations in Texas and Florida drive fixed-projector demand for dedicated cinema rooms. FCC Part 15 emissions compliance extends Wi-Fi 6E product launch timelines by 8-14 weeks. Seattle and Portland recreational users pull battery-powered portable units into vanlife applications.
Germany
Professional calibration services report extended turnaround times for REACH-compliant optical assemblies. EU Ecodesign frameworks accelerate laser engine displacement of legacy lamp systems. Munich and Stuttgart corporate procurement departments standardize on fleet-deployable presentation units.
India
Mumbai and Bangalore residential densification eliminates 65-inch television placement in new apartment construction. BIS energy labeling requirements shape import specifications for LED illumination tiers. Delhi-NCR consumers prioritize Android TV integration over raw brightness specifications.
Japan
Ultra-short-throw lens architectures eliminate shadow interference in Tokyo's compact living spaces. METI efficiency guidelines align with laser phosphor adoption timelines. Osaka gaming users demand sub-16ms input lag implementations for console and PC play.
Smart Compact Projectors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium positioning depends on optical engineering heritage and mass-market penetration relies on Shenzhen manufacturing integration. The vendor base separates into three strategic archetypes: heritage imaging conglomerates with LCD color brightness legacies, consumer electronics specialists leveraging DLP chipset ecosystems, and vertically integrated Chinese manufacturers controlling optical train assembly. Dominant competitive moves include direct-to-consumer channel expansion displacing retail intermediaries, and laser phosphor illumination licensing accelerating product cycle compression.
Among heritage imaging specialists, Epson and Sony occupy positions anchored in professional display engineering traditions. XGIMI exemplifies the vertically integrated Chinese archetype, leveraging proximity to Shenzhen manufacturing clusters for rapid product iteration. Anker Nebula sits within the consumer electronics specialist tier, representing the DLP ecosystem-dependent model focused on portability and streaming integration.
| Leading Market Players |
|---|
| Anker Nebula |
| XGIMI |
| LG Electronics |
| Epson |
| ViewSonic |
| BenQ |
| Sony |
| Optoma |
| AAXA Technologies |
| Others |
Pricing and Supply Chain Analysis
Sixty-day DLP chipset lead times from Texas Instruments concentrate pricing power in semiconductor fabrication while compressing margin buffers for downstream assemblers. This inventory exposure forces manufacturers to absorb cost volatility or pass through to retail tiers.
Pricing Analysis
EU Ecodesign dictates the pricing tier structure by phasing out lamp-based engines and elevating laser-LED premium positioning. Three-tier pricing separates laser-autofocus flagships from LED portables and entry-level mini units. Price differentiation hinges on ANSI lumen certification grade and Texas Instruments DLP chipset tier. Cost compression in mid-tier LCD variants is intensifying because Shenzhen manufacturing clusters accelerate optical train iteration. Educational institutions exhibit highest price sensitivity due to total cost-of-ownership mandates, while gaming enthusiasts tolerate premium positioning for sub-16ms latency specifications.
Supply Chain Analysis
Container availability fluctuations on the Shenzhen-Los Angeles trade lane inject inbound logistics cost volatility into landed component pricing. Manufacturing gravity centers on China, Taiwan, and South Korea for DLP micromirror arrays, laser diode modules, and optical glass substrates. The supply chain draws from Texas Instruments single-source chipsets, dichroic mirror coatings, and lithium-ion battery cells. Single-source vulnerability in DLP semiconductor fabrication creates systemic exposure to allocation constraints. Distribution runs through direct-to-consumer brand storefronts, Amazon marketplace intermediaries, and big-box electronics retail in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in Texas Instruments' DLP chipset network effects, which erect switching costs against alternative display technology migration.
For Market Incumbents: Shield market position by deepening backward integration into laser phosphor engine production and securing multi-year DLP chipset allocation agreements. Emerging Chinese manufacturers threaten margin compression through rapid 6-month product refresh cycles. Certification investment in FCC Part 15 and EU REACH compliance creates regulatory entrenchment against undercapitalized entrants. For New Entrants and Emerging Players: Anchor in India's Mumbai-Bangalore residential densification corridor where 65-inch television placement constraints eliminate conventional display competition. Battery-powered portable units for vanlife and camping applications represent the most penetrable white-space segment. Pursue direct-to-consumer channel control with Android TV-integrated SKUs to bypass established retail gatekeepers. For Investors and Strategic Acquirers: Long-term, this sits as a component-dependency play because optical engine and semiconductor supply concentration creates durable margin capture opportunities. Acquisition target archetype: vertically integrated Chinese manufacturers with captive Shenzhen-Dongguan manufacturing corridors and established MIIT GB certification pathways. Monitor Wi-Fi 7 and Matter protocol adoption velocity as inflection indicator for smart home ecosystem integration premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Phosphor Engine Licensing | Accelerates product cycle compression while sidestepping Texas Instruments DLP supply constraints. |
| Direct-to-Consumer Channel Expansion | Concentrates customer relationship data with manufacturers rather than retail intermediaries. |
| Wi-Fi 7 Module Integration | Enables projector-as-hub positioning in Matter-protocol smart home architectures. |
| Battery Runtime Extension R&D | Captures vanlife and wilderness hospitality demand in Germany's Pacific Northwest corridor. |
| Short-Throw Lens Architecture Patenting | Differentiates gaming-oriented lineups from conventional throw-distance designs in Japan's compact spaces. |
Research Methodology
Initial hypotheses were tested against primary input from optical engineering directors, consumer electronics procurement managers, retail category buyers, and regulatory compliance officers, then refined through secondary validation. Sources included SEC 10-K filings from imaging conglomerates, MIIT GB standard certification databases, FCC equipment authorization registries, and EU Ecodesign directive implementation reports. Bottom-up volume triangulation across product tiers converged with top-down market sizing through manufacturer shipment disclosures.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within each segmentation dimension. The analytical framework models resolution tier, illumination technology, application use case, and regional regulatory cluster throughout the forecast period. CAGRs were derived from logistic adoption curve fitting for laser engine displacement and linear extrapolation for mature LED segments. Industry-specific inputs include Texas Instruments DLP chipset allocation forecasts and EU REACH reformulation timelines for cadmium-free quantum dot phosphors.
Material uncertainties — Texas Instruments supply allocation shifts, EU Ecodesign phase-out acceleration, and Wi-Fi 7 certification timeline delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about optical engine thermal management constraints and regional connectivity protocol convergence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Laser Projector Market
Optoelectronics
Laser Projection Market
Optoelectronics
Thermophotovoltaics Market
Optoelectronics
Infrared Emitter and Receiver Market
Optoelectronics
Photoluminescent Film Market
Optoelectronics
EPON ONU Market
Optoelectronics
Europe Wigig Market
Optoelectronics
Opto-Electronics Device Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market
Optoelectronics
Global Optocoupler Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
China Optoelectronics Market