
 2-Ethyl-3,4-Ethylenedioxythiophene Market | 2026-2036
2-Ethyl-3,4-Ethylenedioxythiophene Market Size, Share, and Industry Trends Forecast 2026-2036
2-Ethyl-3,4-Ethylenedioxythiophene Market Analytics
Specialty monomer synthesis is reshaping margin distribution across the conductive polymer value chain. Merck KGaA leverages its pharmaceutical-grade chemical infrastructure to dominate high-purity EDOT derivative supply. Suzhou Yacoo Science Co., Ltd. anchors Chinese domestic production through integrated thiophene chemistry capabilities. TCI Chemicals extends its catalog breadth into electropolymerization-grade monomers for research-scale buyers.
2-Ethyl-3,4-ethylenedioxythiophene (EEDOT) is a thiophene-derived monomer bearing an ethyl substituent at the 2-position and an ethylenedioxy bridge across the 3,4 carbons, polymerizing via electrochemical or oxidative routes into low-bandgap conjugated polymers with tunable electrochromic and charge-transport properties. Its primary commercial purpose centers on functional layers in organic field-effect transistors, electrochromic displays, and biosensor interfaces where processable analogs of PEDOT are required. The solution segment commands premium pricing due to batch-to-batch consistency demands from inkjet-printed electronics manufacturers, while the film segment competes on thickness uniformity for roll-to-roll coating lines in flexible display backplanes. Organic electronics technology leads end-use adoption, though nanoelectronics applications in molecular-scale sensing platforms represent the fastest-expanding demand node.
REACH registration requirements in Europe mandate full toxicological dossiers for monomer imports above one-tonne thresholds, elevating compliance costs for non-EU suppliers. The EPA Toxic Substances Control Act governs new chemical notifications for modified thiophene derivatives entering US commerce, creating pre-market review timelines that favor established registrants. Stakeholders must monitor convergence between semiconductor material purity standards and emerging EU battery-regulation chemical restrictions that could reclassify certain conductive polymer precursors.
Market Dynamics
Electrochemical polymerization scale-up bottlenecks are compressing margin structures across the EEDOT value chain, forcing specialty chemical producers to recalibrate batch consistency protocols for inkjet-printed electronics manufacturers.
Growth Catalysts
- Flexible display backplane demand:South Korean panel manufacturers are expanding roll-to-roll coating capacity for electrochromic smart windows, pulling high-purity monomer volumes through dedicated supply agreements.
- REACH Article 33 disclosure mandates:ECHA's Substances of Very High Concern list expansions are accelerating substitution of legacy conductive polymers with EEDOT-derived alternatives in EU medical device applications.
- Organic field-effect transistor commercialization:Japanese semiconductor research corridors are translating laboratory-scale electropolymerization into pilot-line manufacturing for low-bandgap polymer semiconductors.
Market Restraints
- Thiophene feedstock volatility:Crude oil derivative pricing swings directly transmit to 3,4-ethylenedioxythiophene intermediate costs, destabilizing contract pricing for electropolymerization-grade monomers.
- East Asian supply concentration:Overreliance on Chinese thiophene chemistry infrastructure exposes buyers to export license delays and regional environmental enforcement shutdowns.
- Batch-to-batch reproducibility limits:Molecular weight distribution control in oxidative polymerization remains technically constrained, disqualifying EEDOT from certain aerospace sensor specifications.
Strategic Opportunities
- Indian electronics manufacturing incentives:PLI scheme allocations for semiconductor packaging are creating first-mover openings for conductive polymer precursor suppliers establishing local formulation capabilities.
- Biosensor interface miniaturization:Glucose monitoring patch manufacturers are specifying EEDOT-PSS formulations for electrochemical signal transduction layers in wearable metabolite sensors.
- EU Battery Regulation precursor reclassification:Anticipated restrictions on certain conductive additives in lithium-ion electrodes could redirect demand toward EEDOT-derived polymer binders for solid-state cell architectures.
Industry Challenges
- Electropolymerization process engineering talent scarcity:Universities are producing insufficient specialists in conjugated polymer synthesis for industrial-scale reactor design and control systems implementation.
- ISO 10993 biocompatibility certification timelines:Extended cytotoxicity and sensitization testing protocols for implantable device applications are stretching product qualification cycles beyond typical contract windows.
- Multi-step synthesis IP thickets:Overlapping patent estates covering ethylenedioxy bridge formation and regioselective ethylation are complicating freedom-to-operate analyses for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-Ethyl-3,4-Ethylenedioxythiophene Market |
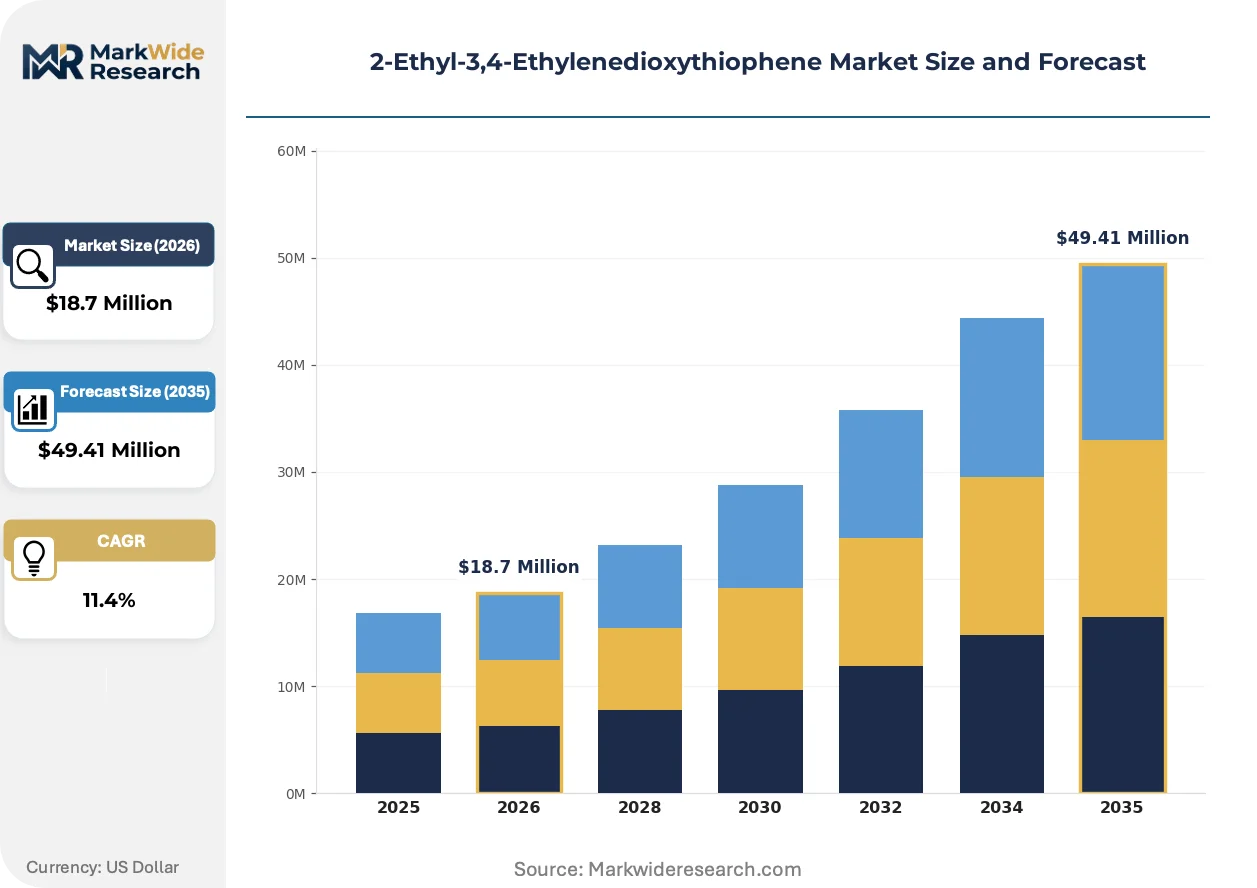
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $49.41 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Solution, Film, Coating Application: Electronics, Optoelectronics, Sensors, Conductive Polymers End Use Industry: Consumer Electronics, Automotive, Aerospace, Renewable Energy Technology: Organic Electronics, Flexible Electronics, Nanoelectronics, Photovoltaics |
| Companies Covered | Suzhou Yacoo Science Co., Ltd., Chem-Impex International, Inc., Merck KGaA, Tokyo Chemical Industry Co., Ltd., 3M Company, Sigma-Aldrich Corporation, Qingdao Fuqiang New Material Technology Co., Ltd., TCI Chemicals, Ossila Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Ethyl-3,4-Ethylenedioxythiophene Market Evolving Landscape
Digital manufacturing integration is compressing development cycles for specialty monomer suppliers, while regulatory chemistry disclosure requirements and end-user specification consolidation are simultaneously elevating technical barriers and concentrating procurement authority.
Flow electrochemistry for continuous EEDOT polymerization is digitizing quality control protocols through in-line spectroscopic monitoring and automated feedback loops. German specialty chemical producers are retrofitting batch reactors with modular flow cells to reduce solvent waste and improve polydispersity indices. This technology is digitizing process analytical technology adoption across conductive polymer precursor manufacturing, enabling real-time release testing that compresses batch release timelines from weeks to hours.
REACH Annex XVII restrictions on perfluorinated substances are redirecting formulation development toward EEDOT-based alternatives in EU medical electronics. ECHA's 2023-2024 restriction proposals for PFAS in healthcare applications are forcing device manufacturers to qualify new conductive polymer systems for electrodes and biosensor substrates. Cardiac monitoring device producers in Germany and France are accelerating supplier audits to secure compliant material streams ahead of anticipated enforcement dates.
Consolidated procurement by inkjet-printed electronics OEMs is compressing supplier qualification to single-source agreements with embedded technical service provisions. Korean display material buyers are mandating dedicated application laboratories within supplier facilities for formulation co-development. This concentration is most visible in Suwon and Gumi industrial clusters, where panel manufacturers are integrating monomer suppliers into quarterly technology roadmap planning cycles.
2-Ethyl-3,4-Ethylenedioxythiophene Market Segmentation
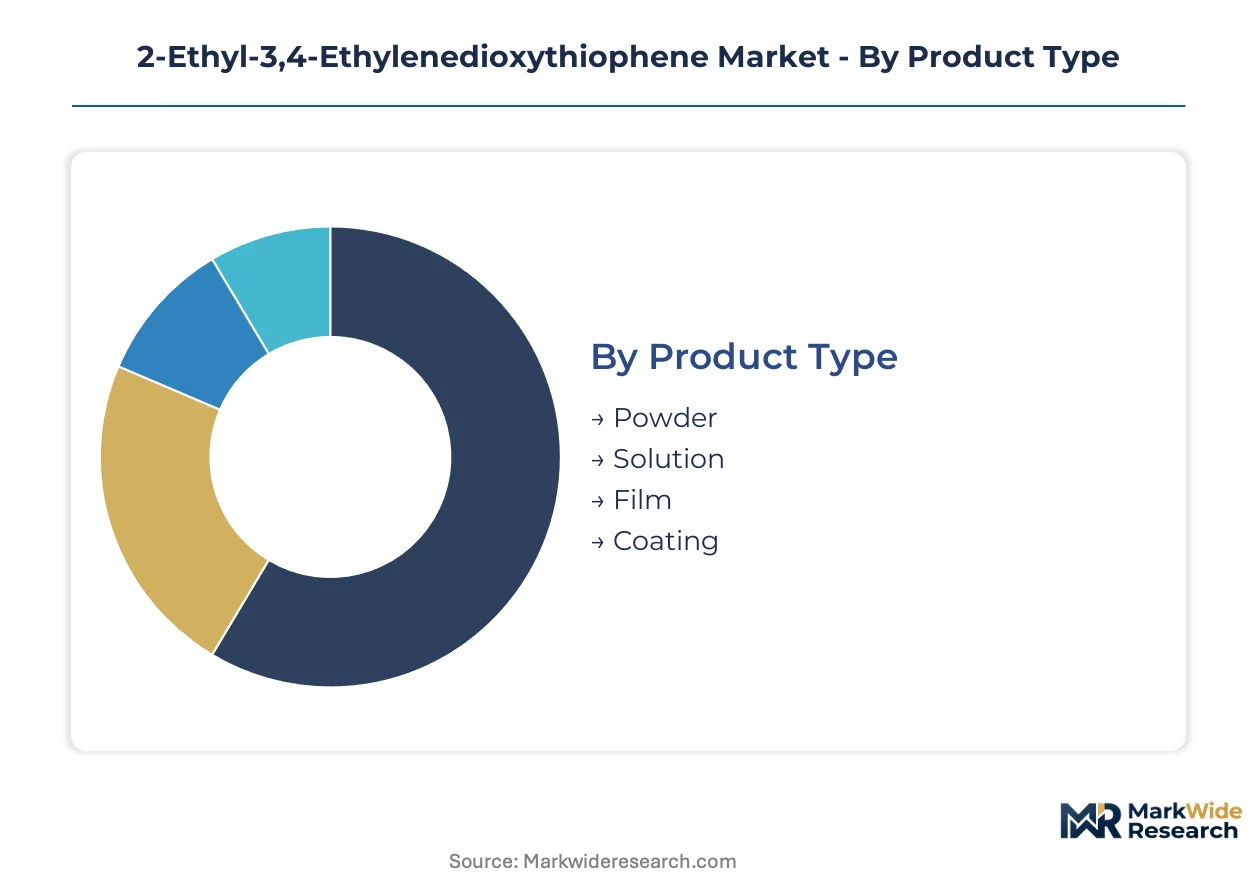
Segmentation in the EEDOT market reveals how purity grades and formulation formats align with distinct manufacturing processes across organic electronics. Understanding these divisions exposes where batch consistency premiums concentrate and which technology platforms drive volume procurement.
Product Type:
Cost tier differentiation separates laboratory-scale purchases from industrial electropolymerization feedstocks.
- Solution:Electropolymerization-grade liquid formulations with dissolved monomer concentrations optimized for inkjet printing and spin-coating protocols. Korean display manufacturers in Suwon and Gumi clusters specify solution formats for roll-to-roll electrochromic backplane production, paying premiums for batch-to-batch viscosity consistency.
- Film:Pre-cast polymer membranes with controlled thickness uniformity for lamination into flexible device architectures. Japanese organic semiconductor researchers at Tsukuba and Osaka corridors favor film formats for rapid device prototyping without in-house polymerization infrastructure.
- Powder:Crystalline monomer for custom formulation by end-users with captive solvent handling capabilities.
- Coating:Ready-to-apply surface treatments for conductive substrate modification in sensor manufacturing.
Solution commands the established base. The steepest expansion runs through Film.
Application:
Functional purpose determines specification stringency from research-grade to medical-device-certified purity levels.
- Conductive Polymers:PEDOT derivative synthesis for transparent electrode and antistatic coating applications. German medical device producers accelerating REACH Article 33 compliance audits are pulling EEDOT-derived conductive polymers into cardiac monitoring electrode specifications ahead of PFAS restriction enforcement.
- Electronics:Organic field-effect transistor channel materials and interconnect layers requiring semiconductor-grade purity. South Korean panel manufacturers expanding flexible display pilot lines are contracting dedicated monomer volumes through multi-year supply agreements.
- Optoelectronics:Light-emitting and light-detecting organic semiconductor architectures.
- Sensors:Electrochemical transduction layers for biosignal detection in wearable metabolite monitors.
Conductive Polymers anchors procurement volumes. Electronics is climbing the fastest on display commercialization timelines.
End Use Industry:
Customer type segmentation maps how regulatory exposure and performance requirements reshape purity specifications.
- Consumer Electronics:Smartphone, tablet, and wearable component manufacturers specifying EEDOT-PSS formulations for flexible circuit substrates. Indian PLI scheme beneficiaries establishing semiconductor packaging capacity are qualifying conductive polymer precursors for local formulation.
- Automotive:Smart glass and interior electrochromic applications with temperature cycling durability requirements.
- Aerospace:Satellite and avionics sensor applications where molecular weight distribution control constraints currently limit EEDOT qualification.
- Renewable Energy:Solid-state battery and organic photovoltaic electrode binders anticipating EU Battery Regulation precursor reclassification.
Consumer Electronics holds the revenue concentration. Renewable Energy is gaining share fastest on solid-state cell architecture transitions.
Technology:
Maturity stage separates established organic electronics from emerging nanoelectronics platforms.
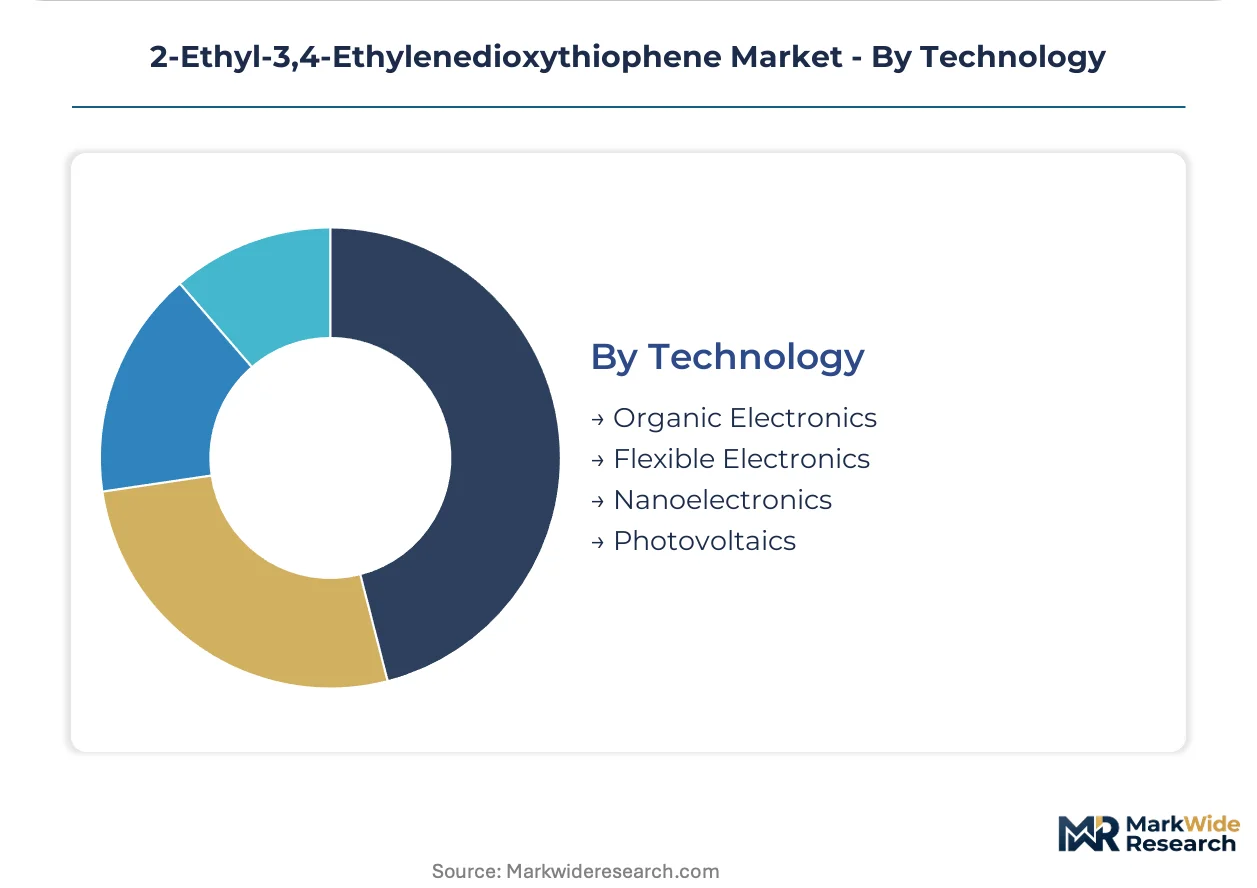
- Organic Electronics:Mature conjugated polymer device architectures with established electropolymerization protocols. Japanese research corridors at AIST and Osaka University are translating laboratory-scale synthesis into pilot-line manufacturing for commercial OFET production.
- Flexible Electronics:Bendable and stretchable device form factors requiring solution-processable materials. German specialty chemical producers retrofitting batch reactors with flow electrochemistry cells are targeting this segment with reduced solvent waste and improved polydispersity indices.
- Nanoelectronics:Molecular-scale sensing and switching platforms representing the frontier of miniaturization.
- Photovoltaics:Organic and perovskite solar cell hole transport layers.
Organic Electronics commands the established base. Nanoelectronics shows the steepest expansion trajectory on biosensor miniaturization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and Japan absorb purity premiums without volume elasticity, while Chinese and Indian procurement teams negotiate aggressively on thiophene feedstock pass-through clauses. European medical device manufacturers occupy the middle ground, trading price sensitivity for REACH documentation completeness.
United States
Electrochromic smart window manufacturers in Michigan and Arizona are scaling pilot production lines for architectural glass applications. EPA Toxic Substances Control Act pre-market review timelines favor established registrants with existing monomer dossiers. The Pacific Northwest corridor around Portland hosts specialized electropolymerization research facilities translating laboratory protocols into manufacturing-ready processes.
Germany
Cardiac monitoring device producers in Baden-Württemberg are accelerating supplier qualification to secure EEDOT-derived conductive polymers ahead of anticipated PFAS restrictions. ECHA REACH Article 33 disclosure mandates are forcing substitution of legacy conductive materials in EU medical electronics. The Rhine-Main industrial cluster around Frankfurt anchors pharmaceutical-grade chemical infrastructure repurposed for high-purity monomer synthesis.
South Korea
Display panel manufacturers in Suwon and Gumi are expanding roll-to-roll coating capacity for flexible electrochromic backplanes, contracting dedicated monomer volumes through multi-year supply agreements. Korean industrial standards for semiconductor-grade materials exceed typical international specifications, creating technical barriers for non-domestic suppliers. Seoul Capital Area electronics OEMs are consolidating procurement authority through single-source agreements with embedded application laboratory provisions.
Japan
Organic field-effect transistor researchers at AIST Tsukuba and Osaka University corridors are translating laboratory-scale electropolymerization into pilot-line manufacturing for commercial polymer semiconductor production. METI technology roadmaps for next-generation electronics are channeling public research funding toward conjugated polymer process development. The Kyushu region's chemical industry base is retrofitting batch reactors with flow electrochemistry modules to serve domestic flexible electronics demand.
China
Integrated thiophene chemistry producers in Jiangsu and Zhejiang provinces dominate intermediate supply for global EEDOT synthesis, though environmental enforcement shutdowns periodically disrupt export schedules. Chinese semiconductor packaging facilities qualifying under domestic substitution programs are specifying local-formulation conductive polymer precursors. The Yangtze River Delta electronics manufacturing cluster is absorbing growing volumes of electropolymerization-grade monomers for printed circuit substrate applications.
2-Ethyl-3,4-Ethylenedioxythiophene Market Competitive Landscape
Capability concentration sits with pharmaceutical-grade chemical specialists; scale advantage sits with integrated thiophene chemistry producers. The market structures around three tiers: multinational life science conglomerates with regulatory dossier libraries, Chinese integrated chemical producers with captive feedstock positions, and research-scale catalog suppliers with broad monomer portfolios. Dominant competitive moves include backward integration into thiophene intermediate production and co-development laboratory partnerships with Korean display OEMs.
Among German-based life science conglomerates, Merck KGaA exemplifies the regulatory-capability tier, leveraging pharmaceutical infrastructure for high-purity monomer supply. Suzhou Yacoo Science Co., Ltd. and Qingdao Fuqiang New Material Technology Co., Ltd. represent the integrated Chinese producer archetype, anchoring regional supply through captive thiophene chemistry. Tokyo Chemical Industry Co., Ltd. and TCI Chemicals occupy positions within the research-scale catalog segment, serving electropolymerization-grade requirements for academic and pilot-line buyers without manufacturing-scale volume commitments.
| Leading Market Players |
|---|
| Suzhou Yacoo Science Co., Ltd. |
| Chem-Impex International, Inc. |
| Merck KGaA |
| Tokyo Chemical Industry Co., Ltd. |
| 3M Company |
| Sigma-Aldrich Corporation |
| Qingdao Fuqiang New Material Technology Co., Ltd. |
| TCI Chemicals |
| Ossila Ltd. |
| Others |
Value Network & Pricing Analysis
Chinese thiophene chemistry infrastructure in Jiangsu and Zhejiang provinces anchors global intermediate supply, concentrating margin capture among integrated producers with captive feedstock positions while forcing downstream formulators to absorb volatility pass-throughs or qualify alternative sourcing corridors.
Pricing Analysis
After-sales technical service contracts with embedded application laboratory provisions drive lifetime value for Korean display OEMs, who pay substantial premiums for batch-to-batch viscosity consistency. Pricing stratifies across electropolymerization-grade, research-grade, and industrial-grade certification tiers. Cost compression in solution formats is intensifying because inkjet-printed electronics manufacturers are consolidating procurement authority through single-source agreements. Academic and pilot-line buyers exhibit highest price sensitivity; semiconductor-grade volume purchasers absorb premiums without elasticity.
Supply Chain Analysis
Extended payment terms from Korean panel manufacturers are squeezing working capital for specialty chemical suppliers, forcing reliance on supply-chain finance facilities. Manufacturing concentrates in China, Germany, and South Korea. The chain draws from 3,4-ethylenedioxythiophene intermediates, thiophene feedstocks, and high-purity solvents. Single-source vulnerability runs through Chinese environmental enforcement shutdowns. Distribution runs through direct long-term offtake agreements with display OEMs and research-scale catalog distributors for academic buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Korean display panel procurement consolidation into single-source agreements with embedded technical service provisions has shifted buyer power decisively toward OEMs, fragmenting supplier negotiating leverage across the value chain.
For Market Incumbents: Build regulatory dossier moats by accelerating REACH Article 33 compliance documentation and ISO 10993 biocompatibility certification ahead of PFAS restriction enforcement in EU medical electronics. Backward integration into thiophene intermediate production in the Rhine-Main cluster defends against Chinese feedstock volatility. Establish captive application laboratories in Suwon and Gumi to match Korean OEM technical service demands. For New Entrants and Emerging Players: Pursue Indian PLI scheme beneficiaries establishing semiconductor packaging capacity as the most penetrable geography, where local formulation capabilities remain underdeveloped. Target biosensor interface miniaturization in wearable metabolite sensors as the fastest-qualifying application segment. Lead with electropolymerization-grade powder formats for custom formulators seeking solvent-handling flexibility. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across flow electrochemistry retrofit segments as German specialty chemical producers digitize quality control protocols. Long-term viability favors acquiring pharmaceutical-grade chemical infrastructure with existing regulatory dossier libraries rather than greenfield research-scale catalog positions. Watch for ECHA Substances of Very High Concern list expansions accelerating substitution demand as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thiophene Intermediates | Captive feedstock supply insulates Merck KGaA and Suzhou Yacoo from crude oil derivative volatility. |
| Flow Electrochemistry Retrofit | German producers reduce solvent waste and improve polydispersity indices for flexible electronics demand. |
| Application Laboratory Partnership | Korean display OEMs in Suwon mandate embedded technical service provisions for formulation co-development. |
| REACH Article 33 Compliance Acceleration | German cardiac monitoring device producers secure EEDOT-derived polymers ahead of PFAS restriction enforcement. |
| Indian PLI Scheme Local Formulation | Semiconductor packaging beneficiaries qualify conductive polymer precursors for domestic substitution programs. |
Research Methodology
A spread of perspectives from electropolymerization process engineers, specialty chemical procurement leads at Korean display OEMs, pharmaceutical-grade synthesis directors, and regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined with secondary validation from ECHA restriction proposals, EPA Toxic Substances Control Act pre-market review timelines, METI technology roadmaps, and customs trade data for thiophene derivative flows. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates.
Demand-supply balance modeling across the projection horizon incorporated grade tier, end-use industry, formulation format, and regional production hub segmentation dimensions. CAGRs were derived from segment-level growth rate synthesis and industry-specific inputs including roll-to-roll coating capacity expansion timelines and biosensor miniaturization adoption curves. The analytical framework tracked electropolymerization scale-up bottlenecks and batch-to-batch reproducibility constraints as volume ceiling factors.
Macroeconomic conditions sit as an overlay; deviation in crude oil derivative pricing, East Asian export license regimes, or semiconductor capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions about REACH enforcement timelines and display commercialization schedules. Regulatory restriction acceleration, electropolymerization breakthroughs, or solid-state battery architecture transitions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
Green Laser Diode Market
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
3D Projector Market
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
Heterojunction Solar Cell Market
Optoelectronics
Light Projector Market
Optoelectronics
Laser Diode Market
Optoelectronics
Cadmium Telluride Photovoltaic Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Algainp Epitaxial Wafers Market
Optoelectronics
Opto-Electronics Device Market
Optoelectronics
Europe Optoelectronics Market