
 IT & Telecom Optoelectronics Market | 2026-2036
IT & Telecom Optoelectronics Market Size, Share, and Industry Trends Forecast 2026-2036
IT & Telecom Optoelectronics Market Insights
High-bandwidth optical interconnect specifications is rotating from niche hyperscaler deployments into mainstream enterprise data center procurement. Samsung Electronics leverages captive semiconductor fabrication to control photonic component supply chains. Sony Corporation anchors image sensor-to-optical module integration for telecom edge devices. Texas Instruments dominates laser driver IC portfolios that interface directly with photodiode arrays.
IT and telecom optoelectronics encompasses solid-state devices that convert electrical signals to light and vice versa, operating across wavelengths from 850 nanometers in multimode fiber to 1550 nanometers in long-haul single-mode systems, with bandwidth densities exceeding one terabit per second per fiber strand in coherent transmission configurations. These components enable the physical layer of modern data networks by encoding digital payloads onto photon streams for low-loss, high-immunity transport. Laser diode and photonic integrated circuit segments carry the fastest expansion as coherent DSP-enabled pluggables displace discrete transponder architectures. Optical fiber demand tracks submarine cable renewal cycles and metro fiber densification, a mature volume category with compressed margins outside specialty hollow-core fibers.
FCC Part 15 emissions rules and the EU F-Gas Regulation constrain refrigerant-dependent thermal management in optical amplification nodes, pushing vendors toward thermoelectric cooling and liquid-cooled rack designs. China's MIIT enforces domestic GB standards for optical module interoperability that favor local photonic integrated circuit foundries. Stakeholders must monitor divergence between IEEE 802.3 standards roadmaps and national spectrum allocation decisions that determine which wavelength bands receive infrastructure investment priority.
Market Dynamics
Coherent digital signal processing is decomposing discrete transponder architectures into pluggable form factors, compressing supplier margins while democratizing access to terabit-class transmission.
Growth Catalysts
- AI workload multiplication:Hyperscaler data centers are procuring 800G optical interconnects at unprecedented scale to feed GPU clusters, pulling demand for laser diodes and photonic integrated circuits.
- EU F-Gas Regulation:Refrigerant phase-down mandates are accelerating thermoelectric and liquid-cooled rack designs in optical amplification nodes, creating retrofit demand across European telecom infrastructure.
- China MIIT domestic standards:GB interoperability requirements for optical modules favor local photonic foundries, concentrating procurement within state-backed 5G and cloud buildouts.
Market Restraints
- Indium phosphide wafer supply:Photonic integrated circuit fabrication depends on limited 3-inch and 4-inch indium phosphide substrates, creating input cost volatility and allocation risk.
- FCC Part 15 emissions compliance:Electromagnetic interference testing for optical transceivers adds certification friction and extends product qualification timelines for US market entry.
- Silicon photonics substitution:CMOS-compatible silicon photonics platforms threaten discrete III-V laser architectures in datacom applications below 2 kilometers.
Strategic Opportunities
- Hollow-core fiber deployment:Submarine cable renewal cycles and metro densification create openings for specialty low-latency fiber in financial trading corridors linking Frankfurt, London, and New York.
- Edge AI inference nodes:Telecom base stations and cable headends are integrating optical interconnects for localized machine learning, expanding addressable market beyond centralized data centers.
- US IRA energy efficiency incentives:Tax credits for efficient data center infrastructure subsidize liquid-cooled optical switching deployments, improving total cost of ownership calculations.
Industry Challenges
- Coherent DSP firmware integration:Vendors must bridge proprietary digital signal processing algorithms with open optical module standards, creating interoperability testing bottlenecks.
- Packaging thermomechanical reliability:High-density co-packaged optics face thermal cycling failures in harsh telecom environments, demanding accelerated qualification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT & Telecom Optoelectronics Market |
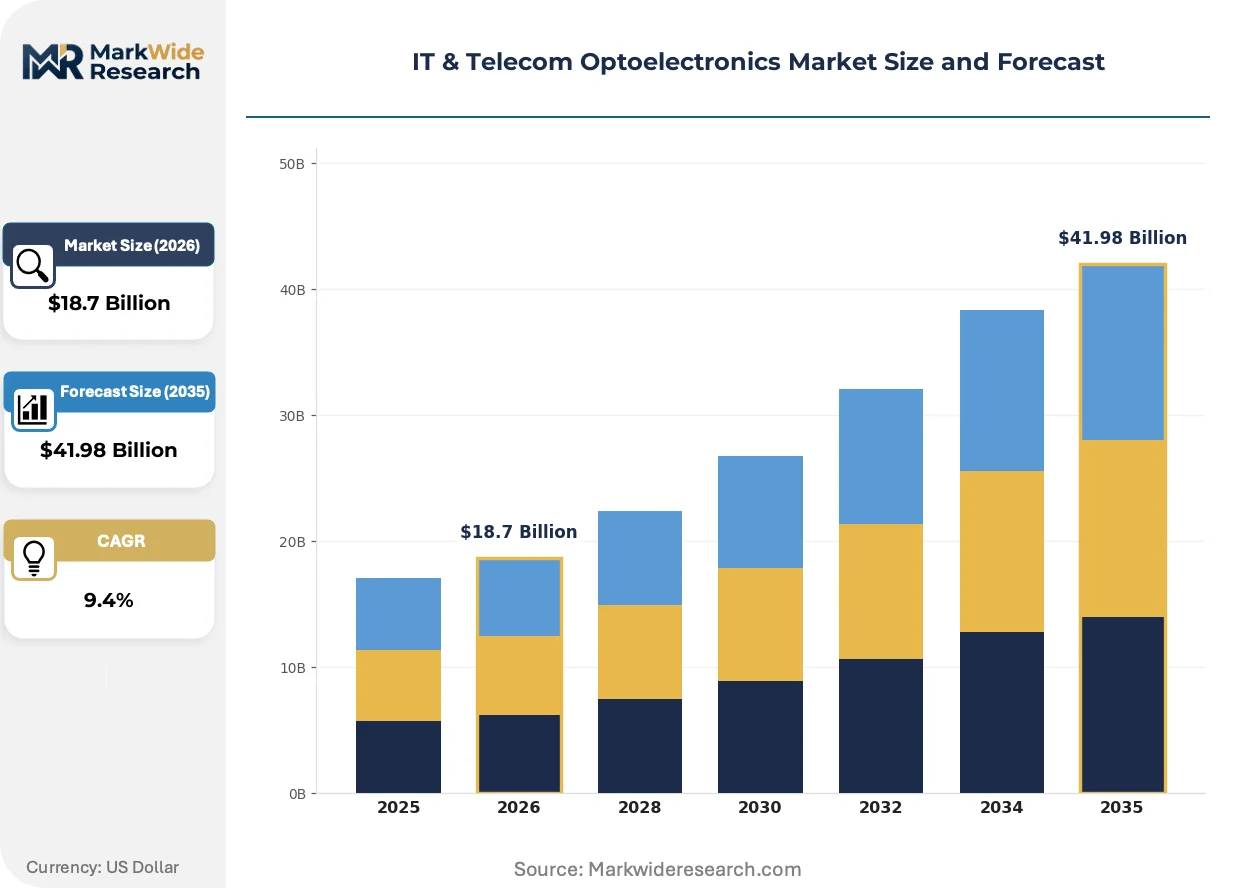
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Laser Diode, Photodiode, Optical Fiber Technology: Active Optical Cable, Wavelength Division Multiplexing, Optical Amplifier, Photonic Integrated Circuit Application: Data Communication, Telecommunications, Video Transmission, Industrial Automation End User: Telecom Providers, Data Centers, Enterprises, OEMs |
| Companies Covered | Samsung Electronics, Sony Corporation, SK Hynix Inc., Omnivision Technologies Inc., Vishay Intertechnology Inc., Panasonic Corporation, Texas Instruments Inc., Huawei Technologies Co. Ltd., Cisco Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT & Telecom Optoelectronics Market Trends and Innovations
Photonic integration is collapsing discrete component boundaries while regulatory energy mandates and buyer procurement centralization are rewriting competitive rules across the value chain.
Co-packaged optics is decomposing traditional pluggable transceiver architectures by embedding lasers and photodetectors directly adjacent to switch ASICs. Cloud operators at Amazon Web Services and Microsoft Azure are piloting 51.2T switch platforms with co-packaged optics in 2024-2025 refresh cycles. This integration is decomposing the merchant optical module supply chain by shifting value capture toward semiconductor packaging houses with advanced substrate capabilities.
The EU AI Act imposes data governance and energy transparency requirements on high-performance computing infrastructure, including optical interconnect systems handling sensitive AI training data. Telecom operators deploying AI-optimized networks must now document energy consumption per data transmission unit and implement audit trails. German and French carriers are responding by procuring optical equipment with embedded power monitoring and cryptographic provenance tracking.
Hyperscaler direct sourcing is consolidating procurement authority previously dispersed through systems integrators and distributor channels. Meta Platforms and Google now issue volume commitments directly to photonic component foundries, bypassing traditional optical module vendors for strategic interconnect categories. This concentration is most visible in the US West Coast data center cluster, where captive specification development is displacing IEEE 802.3 reference designs in favor of proprietary form factors optimized for internal rack architectures.
IT & Telecom Optoelectronics Market Segmentation
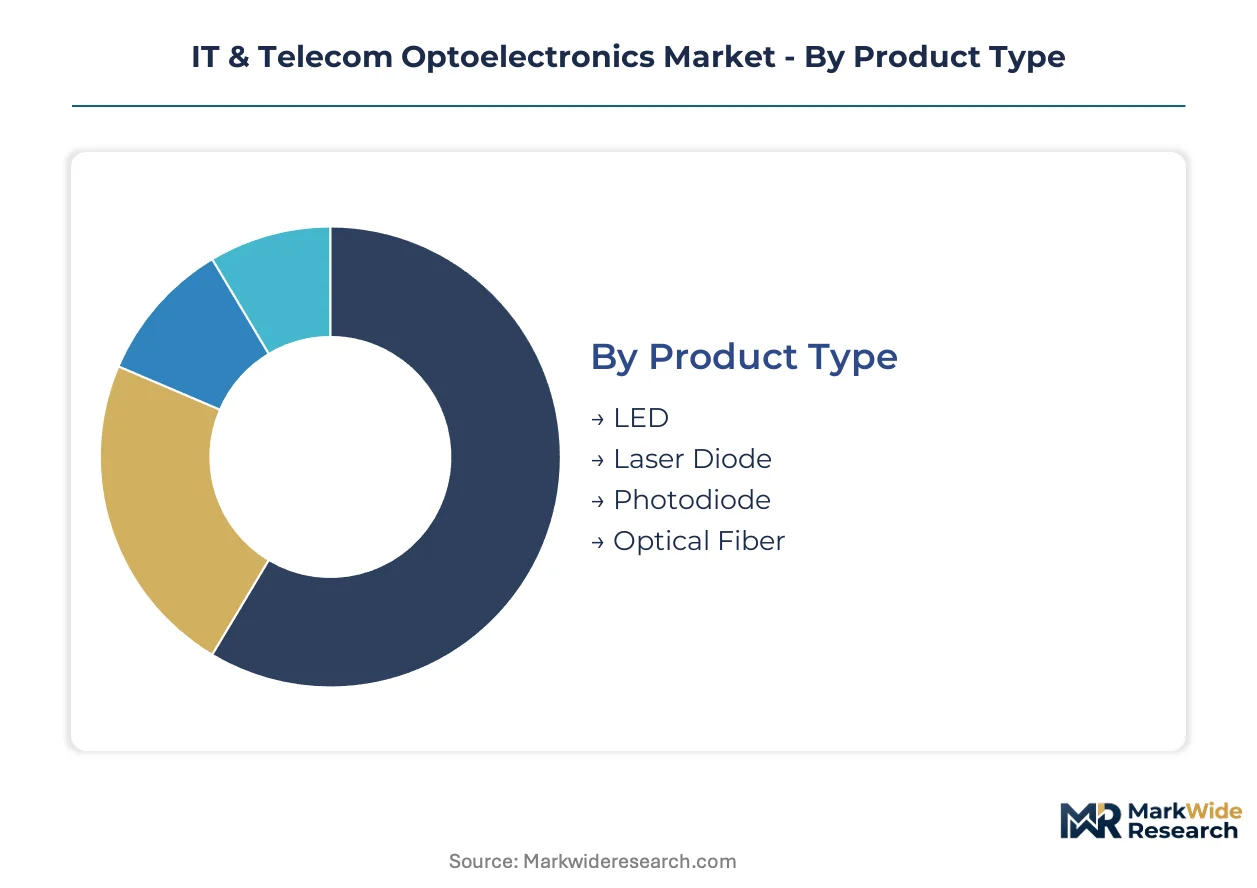
Segmentation in IT and telecom optoelectronics reveals how component specifications diverge across deployment environments. Product architecture, transmission technology, and end-user procurement patterns each create distinct competitive arenas with separate margin profiles and qualification barriers.
Product Type:
Laser diode and LED sourcing concentrates in East Asian manufacturing clusters, while photodiode and specialty fiber production retains European and North American footprints for defense and aerospace certification.
- LED:Visible and infrared emitters serve short-reach multimode fiber links in enterprise LANs and status indicators in telecom equipment. Demand clusters in cost-sensitive Southeast Asian contract manufacturing for consumer electronics integration.
- Laser Diode:Edge-emitting and vertical-cavity surface-emitting lasers generate coherent light at 850nm, 1310nm, and 1550nm wavelengths for high-speed data transmission. Hyperscaler data centers in Virginia and Oregon are pulling 25G and 50G laser diodes at unprecedented scale for AI cluster interconnects.
- Photodiode:PIN and avalanche photodiodes convert optical signals to electrical current with quantum efficiency above 80% in telecom bands.
- Optical Fiber:Single-mode, multimode, and specialty hollow-core fibers guide photon streams with attenuation below 0.2 dB per kilometer.
Laser diode commands the established base. The steepest expansion runs through photodiode arrays for coherent reception.
Technology:
Cost tiers separate legacy discrete assemblies from integrated photonic platforms, with packaging complexity determining which suppliers capture value across the stack.
- Active Optical Cable:Copper-to-fiber conversion modules embed lasers, photodiodes, and retimer electronics within molded cable assemblies. Cloud operators in Frankfurt and Amsterdam are standardizing AOCs for 100G and 400G rack-to-rack connections to simplify procurement and reduce installation errors.
- Wavelength Division Multiplexing:Coarse and dense WDM systems multiply fiber capacity by transmitting multiple wavelengths simultaneously. Submarine cable operators traversing the Pacific corridor between California and Japan are deploying C+L-band WDM for 24 terabit per fiber-pair capacity.
- Optical Amplifier:Erbium-doped fiber amplifiers and semiconductor optical amplifiers boost signal power across long-haul spans.
- Photonic Integrated Circuit:Indium phosphide and silicon photonics platforms integrate lasers, modulators, and detectors on single chips.
Photonic integrated circuit commands the established base. The steepest expansion runs through active optical cable for intra-data center deployment.
Application:
Volume concentration differs sharply between capital-intensive infrastructure buildouts and fragmented enterprise upgrade cycles.
- Data Communication:Optical interconnects for server-to-server and rack-to-rack traffic in hyperscale facilities. Microsoft Azure and Google Cloud campuses in Iowa and Taiwan are driving 800G transceiver demand for next-generation GPU cluster fabrics.
- Telecommunications:Long-haul, metro, and access network transmission equipment for carrier infrastructure. China's three state-owned operators are procuring 50G PON optical line terminals under MIIT domestic standards mandates.
- Video Transmission:Broadcast-quality fiber links for professional media distribution and contribution networks.
- Industrial Automation:Ruggedized optical sensors and communication links for factory floor and process control environments.
Telecommunications commands the established base. The steepest expansion runs through data communication for AI-optimized infrastructure.
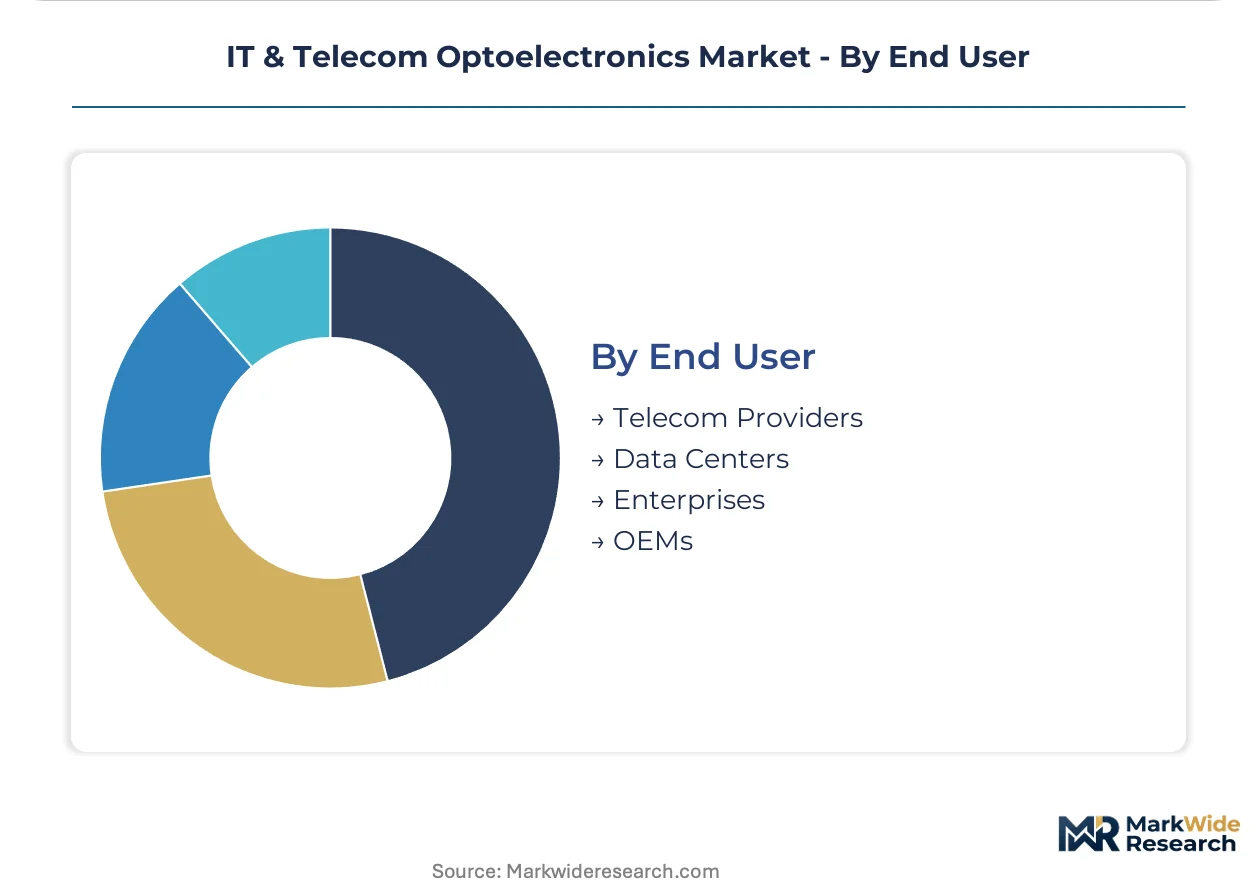
End User:
Customer type determines specification authority, with direct hyperscaler procurement displacing traditional channel structures for strategic interconnect categories.
- Telecom Providers:Tier-1 and regional carriers deploying access, aggregation, and core network infrastructure. Deutsche Telekom and Orange are consolidating optical transport procurement under framework agreements with embedded EU F-Gas compliance requirements.
- Data Centers:Colocation, hyperscale, and enterprise facilities scaling compute and storage interconnect bandwidth. Amazon Web Services and Meta Platforms are issuing direct volume commitments to photonic foundries for proprietary form factors.
- Enterprises:Corporate and institutional networks upgrading campus and building connectivity.
- OEMs:Original equipment manufacturers integrating optical subsystems into servers, storage arrays, and networking gear.
Telecom providers command the established base. The steepest expansion runs through data centers for AI workload acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indium phosphide wafer fabrication concentrates in Japanese and Chinese foundries, while coherent DSP design capabilities cluster in US and European semiconductor houses. Regulatory divergence on energy efficiency and data sovereignty is fragmenting procurement standards across major demand centers.
United States
Hyperscaler data centers in Virginia and Oregon are absorbing 800G optical interconnects at scale for AI cluster expansion. The FCC enforces Part 15 electromagnetic emissions rules that extend product qualification timelines for optical transceiver vendors. Texas Instruments anchors laser driver IC design in Dallas-Fort Worth, interfacing directly with photodiode arrays for coherent transmission systems.
China
Domestic cloud providers and state-backed 5G rollouts are consuming photonic integrated circuits at unprecedented volume. The MIIT enforces GB standards for optical module interoperability that favor local foundries over foreign suppliers. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou dominate indium phosphide wafer processing and optical component assembly.
Germany
Deutsche Telekom and regional carriers are consolidating optical transport procurement under framework agreements with embedded sustainability requirements. The EU F-Gas Regulation mandates refrigerant phase-down in optical amplification nodes, accelerating thermoelectric cooling retrofits. Frankfurt's financial trading corridors are driving hollow-core fiber deployment for latency-sensitive applications linking London and New York.
Japan
Photonic integrated circuit foundries in Kanto and Kansai regions supply precision indium phosphide substrates for global coherent transponder production. METI industrial policy supports domestic optoelectronics manufacturing through targeted R&D consortia. Sony Corporation in Tokyo anchors image sensor-to-optical module integration for telecom edge devices and automotive LiDAR crossover applications.
South Korea
Samsung Electronics leverages captive semiconductor fabrication in Gyeonggi Province to control photonic component supply chains for internal consumption and merchant sales. The country's national spectrum regulator allocates wavelength bands for 5G fronthaul and metro fiber densification projects. Busan-Ulsan industrial complexes specialize in high-volume laser diode packaging for datacom transceivers.
IT & Telecom Optoelectronics Market Competitive Landscape
Concentration sits with diversified electronics conglomerates that have internalized photonic component fabrication. The vendor base stratifies across three tiers: captive semiconductor houses serving internal demand, merchant optical module specialists, and fabless DSP design firms. Strategic moves center on backward integration into indium phosphide wafer supply and co-packaged optics partnerships with switch ASIC vendors.
Among East Asian diversified conglomerates, Samsung Electronics and Sony Corporation exemplify the captive fabrication archetype, while Texas Instruments represents the specialized analog semiconductor model. These three anchors illustrate how competitive positioning depends on whether photonic capabilities are developed in-house, acquired through vertical control, or accessed via merchant supply relationships.
| Leading Market Players |
|---|
| Samsung Electronics |
| Sony Corporation |
| SK Hynix Inc. |
| Omnivision Technologies Inc. |
| Vishay Intertechnology Inc. |
| Panasonic Corporation |
| Texas Instruments Inc. |
| Huawei Technologies Co. Ltd. |
| Cisco Systems, Inc. |
| Others |
Pricing and Supply Chain Analysis
Silicon photonics substitution for indium phosphide transceivers simultaneously redraws manufacturing geography toward CMOS-compatible foundries and compresses pricing premiums historically attached to III-V compound semiconductor fabrication. This displacement dynamic concentrates cost advantage in East Asian economies with mature silicon photonics pilot lines while stranding legacy laser diode suppliers with depreciated InP capacity.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure by embedding refrigerant compliance costs into optical amplification node quotations, separating premium thermoelectric-cooled systems from standard air-cooled alternatives. Pricing stratifies across coherent DSP-enabled pluggables, discrete transponder architectures, and commodity direct-detect modules, with hyperscaler direct procurement compressing margins in the middle tier. Cost compression in merchant optical modules intensifies because captive semiconductor houses internalize component supply for internal consumption. Enterprise data centers exhibit the highest price sensitivity due to budget-constrained refresh cycles, while submarine cable operators demonstrate the lowest sensitivity given latency-critical application requirements.
Supply Chain Analysis
Strait of Malacca transit underwrites the dominant logistics corridor for indium phosphide wafers shipped from Japanese foundries to Chinese assembly clusters. Manufacturing concentration centers on Japan, China, and South Korea for photonic integrated circuit fabrication, with Taiwan anchoring silicon photonics foundry services. Raw material dependencies draw from germanium substrates for photodetectors, rare earth elements for optical amplifiers, and high-purity silica for specialty fiber. Single-source vulnerability concentrates in 3-inch InP wafer supply from limited Japanese vendors. Distribution runs through direct hyperscaler procurement channels that displace traditional optical module vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks the submarine cable renewal cycle, with capital expenditure normalization following a decade of deferred maintenance creating favorable conditions for component suppliers positioned at the optical layer.
For Market Incumbents: Compound defensive moats around coherent DSP firmware integration by acquiring fabless algorithm specialists and securing exclusive packaging partnerships with switch ASIC vendors. Threats from silicon photonics substitution in datacom applications below 2 kilometers demand accelerated investment in indium phosphide wafer supply agreements to lock input allocation. Backward integration into captive photonic foundry capacity represents the critical lever for margin defense against merchant price erosion. For New Entrants and Emerging Players: Lead with hollow-core fiber deployment for financial trading corridors linking Frankfurt, London, and New York, where latency premiums override incumbent supplier relationships. Edge AI inference nodes at telecom base stations offer the most penetrable white space, with optical interconnect integration for localized machine learning expanding addressable market beyond centralized hyperscale facilities. A go-to-market angle anchored to embedded power monitoring and cryptographic provenance tracking satisfies EU AI Act procurement requirements. For Investors and Strategic Acquirers: The market sits at a capital expenditure upswing phase that favors photonic integrated circuit foundries with indium phosphide process expertise and established hyperscaler qualification pathways. Long-term viability over the next decade hinges on positioning upstream of silicon photonics displacement in datacom while capturing submarine cable and metro fiber densification replacement demand. Acquisition targets should exhibit coherent DSP algorithm portfolios and advanced substrate packaging capabilities. The signal to watch is hyperscaler direct sourcing volume commitments to merchant foundries, which indicate procurement authority shifts away from traditional optical module vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Coherent DSP Firmware Acquisition | Proprietary algorithm portfolios differentiate pluggable transceivers from commodity alternatives in hyperscaler procurement. |
| Indium Phosphide Wafer Supply Agreement | Long-term offtake contracts with Japanese substrate vendors mitigate allocation risk during AI-driven demand surges. |
| Co-Packaged Optics Partnership | Integration with switch ASIC vendors like Broadcom or Marvell captures value migrating from merchant optical modules. |
| Hollow-Core Fiber Manufacturing Scale-Up | Specialty low-latency fiber production for financial trading corridors commands pricing premiums over standard single-mode. |
| EU F-Gas Compliance Certification | Thermoelectric cooling validation opens European telecom infrastructure retrofit opportunities under refrigerant phase-down mandates. |
Research Methodology
The analysis maps laser diode and photonic integrated circuit sub-sectors, each validated through hyperscaler procurement executives, optical module vendor product managers, and telecom carrier network architects. Primary interviews with indium phosphide foundry operators and silicon photonics process engineers combined with secondary validation against SEC filings from listed optoelectronics suppliers, IEEE standards committee documentation, and customs trade data for optical component shipments. Bottom-up build-ups of laser diode and photodiode array demand triangulated against top-down infrastructure capex forecasts from major cloud operators.
Consistency checks validated volume and value outputs against hyperscaler disclosed optical interconnect procurement scales and submarine cable system deployment announcements. The analytical framework modeled product type, transmission technology, application, and end-user dimensions across the projection horizon, with CAGRs derived from segment-specific demand elasticities tied to AI workload growth and 5G infrastructure buildout trajectories. Forecast inputs incorporated coherent DSP-enabled pluggable displacement rates and EU F-Gas Regulation compliance retrofit schedules.
Forecasts assume regulatory continuity in FCC Part 15 emissions frameworks and EU F-Gas refrigerant phase-down schedules; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
United States Optoelectronics Market
Optoelectronics
Green Laser Diode Market
Optoelectronics
Opto-Electronics Device Market
Optoelectronics
Thermophotovoltaics Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market
Optoelectronics
3D Projector Market
Optoelectronics
Integrated Circuit Optocouplers Market
Optoelectronics
Quantum Dots Market
Optoelectronics
Global Optoelectronic Components Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Gallium Arsenide Market
Optoelectronics
2-Ethyl-3,4-Ethylenedioxythiophene Market
Optoelectronics
Optoelectronic Development Tools Market
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
China Optoelectronics Market