
 Green Laser Diode Market | 2026-2036
Green Laser Diode Market Size, Share, and Industry Trends Forecast 2026-2036
Green Laser Diode Market Outlook
GaN-on-sapphire epitaxy migration is reconfiguring wafer-level manufacturing economics for green emitters. Nichia Corporation leverages captive crystal growth capacity to sustain margin structures across the 520-560 nm band. Osram Opto Semiconductors anchors European supply through its Regensburg fabrication complex. Coherent Inc competes on VCSEL-to-edge-emitter flexibility for industrial sensing modules.
Green laser diodes are semiconductor devices that generate coherent light between 520 nm and 560 nm wavelength, typically fabricated from indium gallium nitride quantum wells on sapphire or silicon carbide substrates, and serve primarily as precision light sources for medical imaging, laser projection, and materials processing systems. Single-mode devices occupy the premium tier in medical and scientific instrumentation where beam quality dictates system performance. Multi-mode and high-power variants capture expanding volume in industrial automation as fiber-coupled sources replace legacy solid-state lasers. Quantum dot technology extends wavelength tunability while distributed feedback architectures dominate telecommunications pump applications.
Japan's METI enforces JIS standards on laser product safety classifications that constrain import eligibility for uncertified modules. The EU RoHS and REACH frameworks restrict cadmium and lead content in optoelectronic packages, forcing redesigns of legacy green emitter housings. FDA laser product performance standards in the United States mandate specific labeling and emission limits for medical device integrations. Stakeholders must monitor evolving IEC 60825-1 amendments governing eye-safe exposure thresholds as output powers climb across industrial deployments.
Market Dynamics
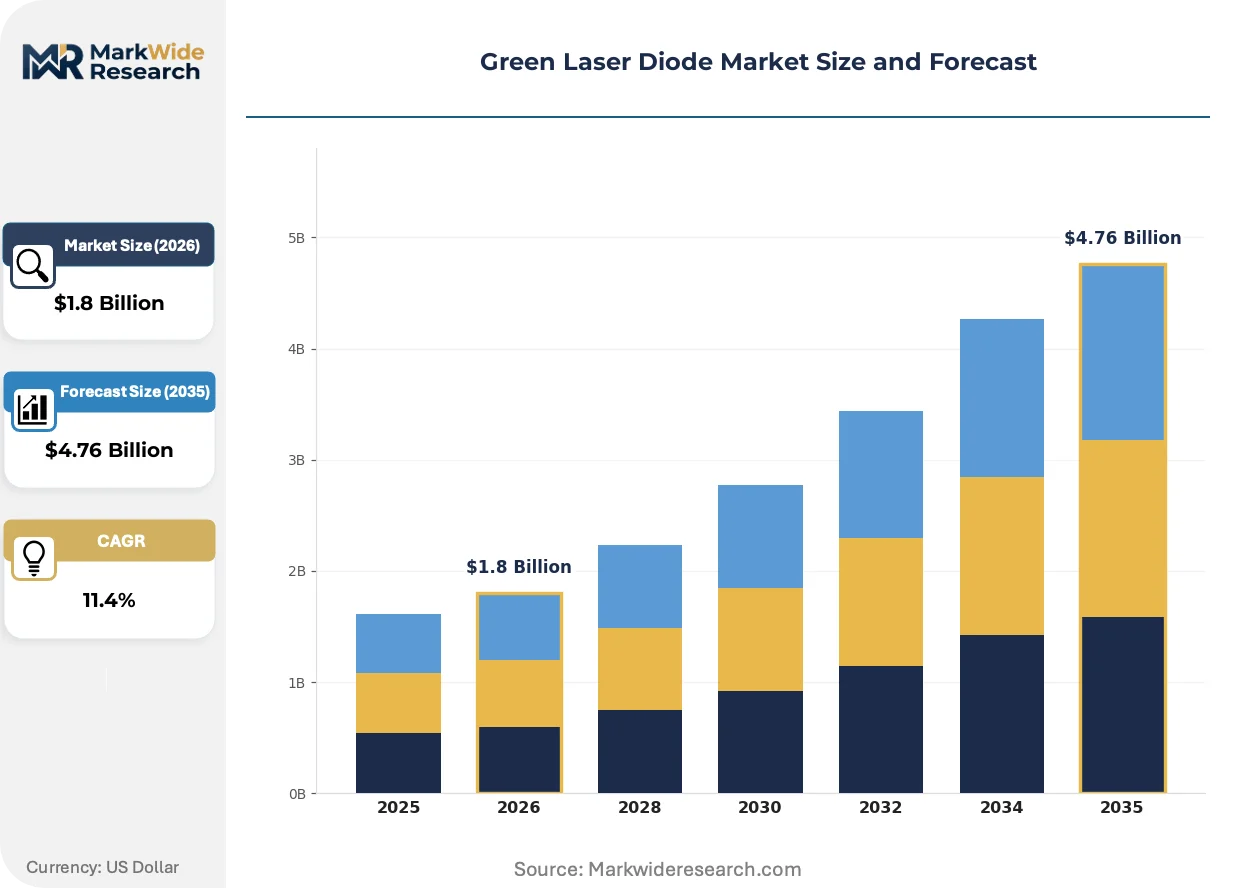
GaN-on-sapphire epitaxy migration is compressing manufacturing costs for 520-560 nm emitters while China's MIIT dual carbon goals force energy efficiency recalibration across optoelectronic fabs. This substrate transition and regulatory tightening together reshape competitive economics for green laser diode production.
Growth Catalysts
- Surgical laser adoption:German medical equipment manufacturers are expanding procurement of high-power variants for precision surgical applications, creating sustained demand pull for single-mode devices.
- MIIT dual carbon compliance:China's tightening energy efficiency standards for optoelectronic component production are accelerating fab modernization and yield improvements across domestic supply chains.
- Industrial fiber-coupled replacement:Multi-mode and high-power variants capture expanding volume in industrial automation as fiber-coupled sources displace legacy solid-state lasers in materials processing.
Market Restraints
- Indium cost volatility:Indium gallium nitride quantum well fabrication depends on indium metal pricing, which fluctuates with mining supply from Chinese and Korean refiners.
- Japanese substrate concentration:High-quality sapphire and silicon carbide substrates concentrate among Japanese crystal growers, creating supply bottleneck risk for non-integrated device manufacturers.
- EU material restrictions:REACH and RoHS frameworks restrict cadmium and lead content in optoelectronic packages, forcing costly redesigns of legacy green emitter housings and thermal management assemblies.
Strategic Opportunities
- Quantum dot wavelength extension:Quantum dot technology extends wavelength tunability beyond conventional InGaN limits, opening biomedical imaging applications requiring precise spectral matching.
- Osaka-Tokyo precision optics cluster:Japan's concentrated demand around Osaka and Tokyo offers geographic anchor points for specialized distribution partnerships and technical service presence.
- IEC 60825-1 amendment preparation:Evolving eye-safe exposure thresholds as output powers climb create first-mover advantage for manufacturers pre-certifying industrial-class modules.
Industry Challenges
- MOCVD technician scarcity:Metal-organic chemical vapor deposition operation and maintenance expertise concentrates among veteran engineers in Japan and Germany, constraining fab expansion timelines.
- Multi-jurisdiction certification complexity:Simultaneous FDA laser product performance standards, METI JIS classifications, and EU CE marking requirements extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Laser Diode Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode, Multi-Mode, High-Power, Compact Application: Consumer Electronics, Medical Equipment, Industrial Automation, Communication End User: Manufacturers, Research Institutes, Hospitals, Telecommunications Technology: Edge Emitting, Vertical-Cavity Surface-Emitting, Distributed Feedback, Quantum Dot |
| Companies Covered | Nichia Corporation, Osram Opto Semiconductors, Coherent Inc, Laser Components GmbH, Thorlabs Inc, IPG Photonics, Sharp Corporation, Jenoptik AG, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Laser Diode Market Strategic Shifts
Active substrate engineering and regulatory harmonization efforts are compressing development cycles while procurement rationalization reshapes vendor relationships across medical and industrial verticals.
Non-polar and semi-polar GaN crystal orientations are migrating from research-phase demonstration to pilot production for green emitters. Medical imaging system integrators in Germany and Japan are qualifying these substrates for surgical navigation modules. The technology is migrating from sapphire-dominant supply chains toward silicon carbide platforms that reduce thermal resistance and enable higher continuous-wave output.
EU RoHS and REACH frameworks are tightening substance restrictions on optoelectronic packages containing legacy solders and coatings. Device manufacturers must reformulate thermal interface materials and housing alloys to maintain market access. Medical device integrations face the steepest compliance burden, with German and Swiss OEMs accelerating supplier audits ahead of 2027 enforcement windows.
Direct procurement from epitaxy houses is displacing traditional component distributor relationships among high-volume industrial laser system builders. Fiber-coupled module buyers in Japan's materials processing sector now negotiate wafer-level supply agreements that bypass standard electronics distribution channels. This consolidation concentrates purchasing power with Osram Opto Semiconductors and Nichia Corporation captive facilities.
Green Laser Diode Market Segmentation
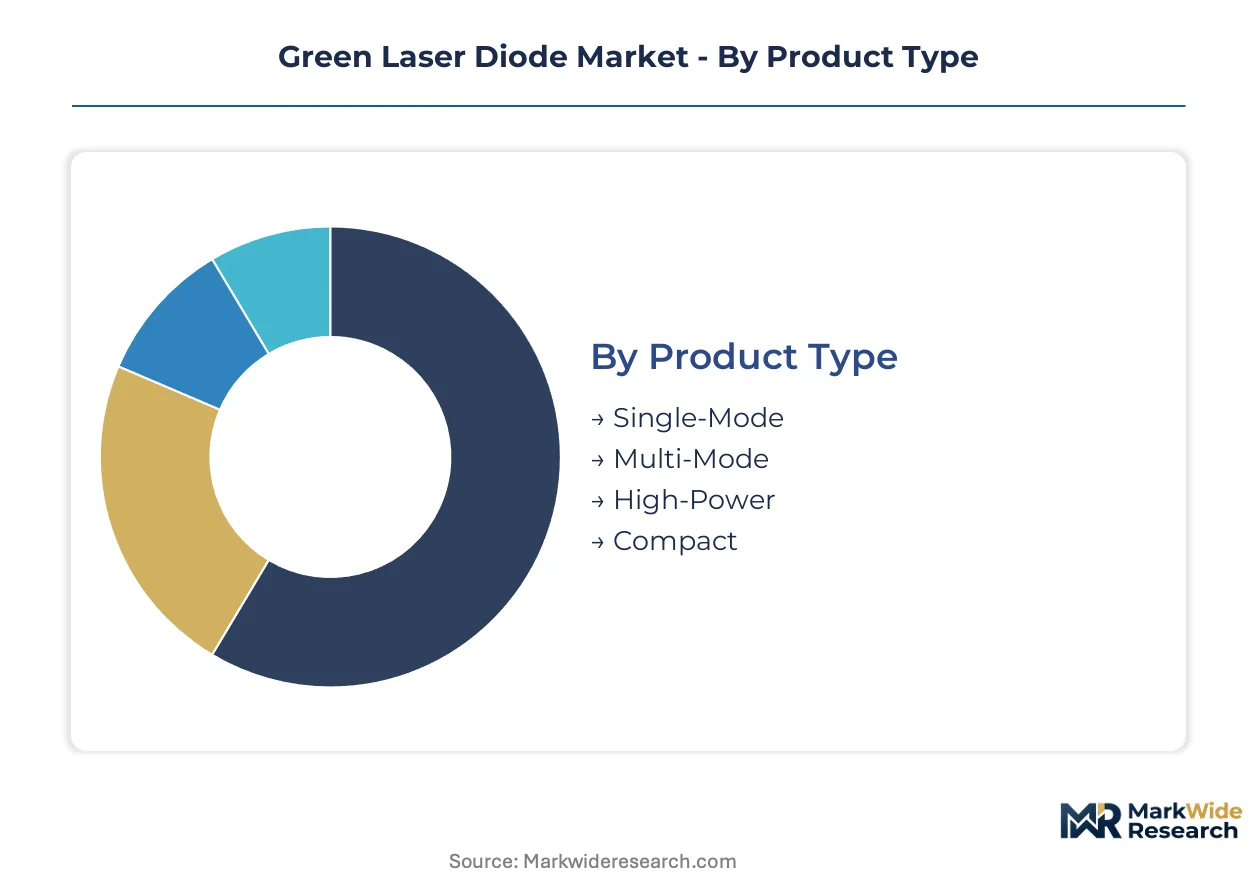
Green laser diode segmentation reflects divergent performance requirements across precision medical systems and high-throughput industrial tools. Device architecture, wavelength stability, and thermal management specifications vary sharply by end-use, creating distinct procurement patterns and margin structures.
Product Type:
Cost tier differentiation separates laboratory-grade precision emitters from volume industrial sources.
- Single-Mode:Devices maintain transverse mode purity with narrow spectral linewidth below 0.1 nm, essential for interferometric measurement and holographic imaging systems. German surgical navigation OEMs in Munich and Stuttgart specify these for fluorescence-guided resection modules. FDA laser product performance standards constrain import eligibility for uncertified variants.
- High-Power:Continuous-wave outputs exceeding 500 mW enable direct materials processing without fiber amplification. Japan's precision optics cluster around Osaka deploys these for semiconductor wafer inspection and micromachining stations. Thermal management complexity limits supplier pool to vertically integrated manufacturers with captive substrate capacity.
- Multi-Mode:Broader beam profiles suit projection and illumination applications where spatial coherence is secondary to lumen output.
- Compact:Miniaturized packages integrate into portable medical devices and handheld industrial sensors with severe form-factor constraints.
Single-Mode holds installed capacity. High-Power is rotating up the share rankings.
Application:
End-use context determines beam quality specifications and regulatory certification pathways.
- Medical Equipment:Surgical lasers and diagnostic imaging systems demand wavelength precision at 532 nm for hemoglobin absorption matching. Swiss and German OEMs in Basel and Tübingen drive procurement of stabilized single-mode emitters. METI JIS safety classifications and FDA emission limits impose dual certification burdens.
- Industrial Automation:Fiber-coupled sources displace legacy solid-state lasers in cutting and welding stations. China's MIIT dual carbon goals accelerate energy efficiency recalibration across domestic materials processing fabs. Multi-mode variants capture volume as system builders consolidate vendor bases.
- Consumer Electronics:Pico-projectors and augmented reality headsets prioritize compactness over absolute power.
- Communication:Distributed feedback architectures serve as pump sources for optical amplification in submarine and terrestrial networks.
Medical Equipment commands premium positioning. Industrial Automation is climbing the fastest.
End User:
Customer type shapes procurement scale, technical support requirements, and contract structure.
- Manufacturers:Industrial laser system builders negotiate wafer-level supply agreements that bypass standard distribution. Japan's materials processing sector concentrates purchasing power with captive epitaxy facilities in Osaka and Tokyo. Direct procurement displaces traditional component distributor relationships.
- Hospitals:Healthcare procurement departments prioritize FDA-cleared devices with established service networks. German hospital chains in Bavaria and North Rhine-Westphalia specify single-mode surgical lasers with 10-year service commitments. Reimbursement coding stability influences capital equipment cycles.
- Research Institutes:Academic and government laboratories drive early adoption of quantum dot and non-polar GaN technologies.
- Telecommunications:Carrier procurement departments emphasize reliability metrics and backward compatibility with existing amplification infrastructure.
Manufacturers dominate volume throughput. Hospitals are gaining share fastest.
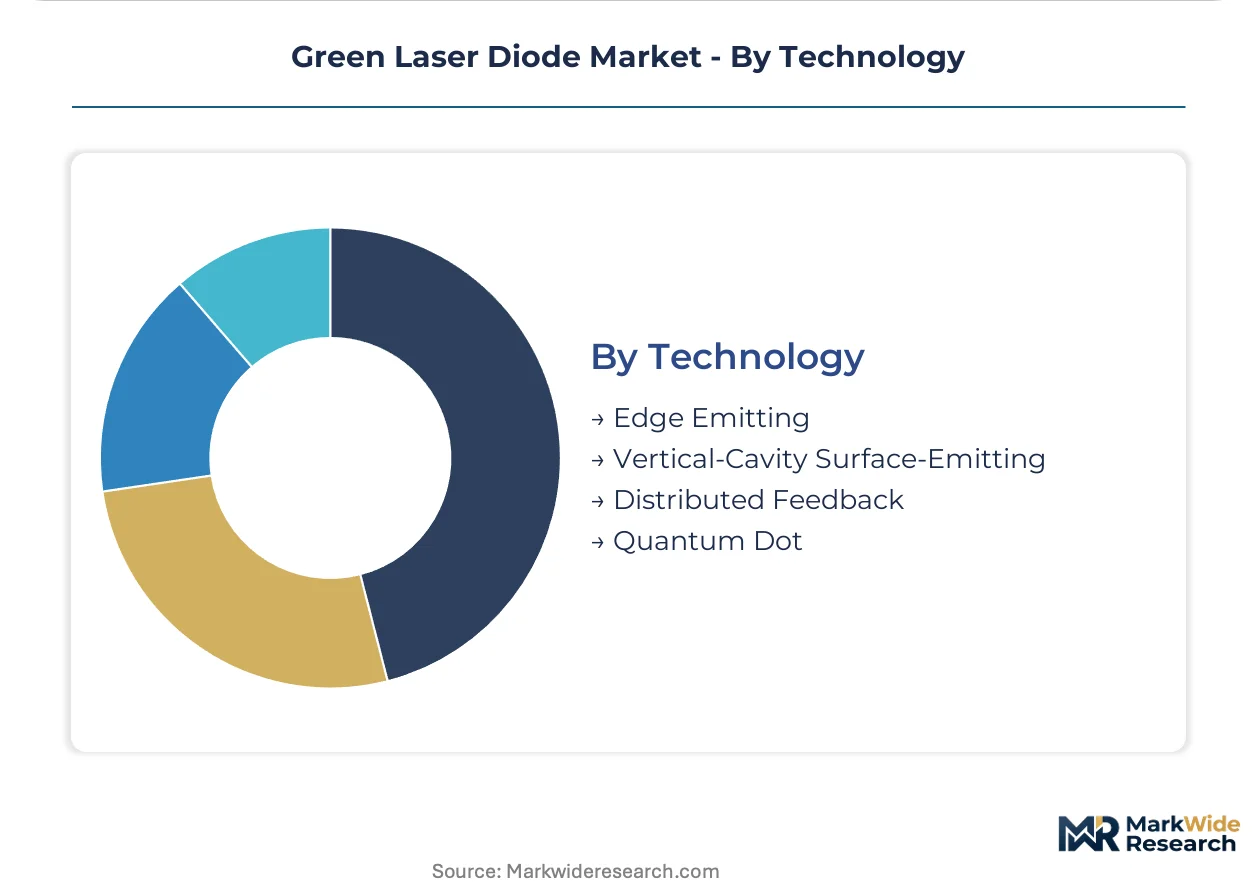
Technology:
Device architecture determines efficiency, beam quality, and integration complexity.
- Edge Emitting:Constrained cavity designs maximize output power density for materials processing applications. Nichia Corporation and Osram Opto Semiconductors anchor supply through Regensburg and Japanese fabrication complexes. GaN-on-sapphire epitaxy migration compresses manufacturing costs across the 520-560 nm band.
- Quantum Dot:Zero-dimensional confinement structures extend wavelength tunability beyond conventional InGaN limits. Biomedical imaging applications in Japan and Germany require precise spectral matching for multiplexed fluorescence detection. Pilot production lines remain concentrated among research-phase facilities.
- Vertical-Cavity Surface-Emitting:Circular output profiles simplify fiber coupling and array configuration for sensing modules.
- Distributed Feedback:Grating-stabilized cavities dominate telecommunications pump applications where wavelength stability exceeds power density priority.
Edge Emitting holds installed capacity. Quantum Dot is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German medical equipment manufacturers import high-power green laser diodes from Japanese crystal growth facilities, while China's MIIT dual carbon regulations redirect domestic fab investment toward energy-efficient epitaxy platforms.
Germany
Surgical navigation OEMs in Munich and Stuttgart drive procurement of stabilized single-mode emitters for fluorescence-guided resection systems. The country's national medical device regulator enforces stringent laser product performance standards alongside EU RoHS substance restrictions. The precision optics cluster around Regensburg anchors Osram Opto Semiconductors fabrication capacity for 520-560 nm band production.
Japan
METI JIS safety classifications constrain import eligibility for uncertified modules while domestic demand concentrates in biomedical imaging and semiconductor inspection equipment. The Ministry of Economy, Trade and Industry enforces evolving IEC 60825-1 amendments governing eye-safe exposure thresholds. The Osaka-Tokyo precision optics corridor hosts vertically integrated manufacturers with captive sapphire and silicon carbide substrate capacity.
China
MIIT dual carbon goals accelerate energy efficiency recalibration across optoelectronic component fabs serving industrial automation and materials processing sectors. The Ministry of Industry and Information Technology tightens emissions standards for metal-organic chemical vapor deposition operations. Yangtze River Delta fabrication complexes modernize yield improvements to meet domestic and export certification requirements.
United States
FDA laser product performance standards mandate specific labeling and emission limits for medical device integrations, shaping procurement patterns among surgical laser system builders. The Food and Drug Administration constrains market entry through 510(k) clearance pathways for fluorescence imaging modules. Greater Boston and Pacific Northwest research institutes pilot quantum dot wavelength extension technologies for multiplexed detection applications.
Switzerland
Swissmedic regulations align with EU MDR frameworks to govern laser-based diagnostic equipment approvals, creating dual certification burdens for surgical OEMs in Basel. The national pharmaceutical and medical device agency enforces post-market surveillance requirements on imported optoelectronic components. Precision manufacturing clusters around Zurich and Geneva qualify non-polar GaN substrates for next-generation surgical navigation platforms.
Green Laser Diode Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated manufacturers with captive crystal growth capacity and captive epitaxy facilities. The vendor base stratifies into three tiers: premium single-mode specialists, high-power industrial suppliers, and component distributors serving research markets. Dominant competitive moves include direct procurement negotiations that bypass traditional electronics distribution channels and strategic partnerships between device manufacturers and medical system integrators.
Among Japanese fabricators, Nichia Corporation and Sharp Corporation exemplify the vertically integrated archetype with in-house substrate production. German GmbH-structured players including Osram Opto Semiconductors and Laser Components GmbH occupy positions bridging European medical device supply chains with industrial automation demand. Coherent Inc represents the flexibility-focused tier competing across VCSEL-to-edge-emitter architectures for sensing modules.
| Leading Market Players |
|---|
| Nichia Corporation |
| Osram Opto Semiconductors |
| Coherent Inc |
| Laser Components GmbH |
| Thorlabs Inc |
| IPG Photonics |
| Sharp Corporation |
| Jenoptik AG |
| Mitsubishi Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
Single-source substrate dependency on Japanese sapphire and silicon carbide crystal growers compresses pricing power for non-integrated device manufacturers while simultaneously forcing three-tier pricing stratification across premium, standard, and economy certification levels. This concentration dynamic rewards vertically integrated fabricators with captive crystal growth capacity and squeezes margin structures for distributors serving research and low-volume industrial segments.
Pricing Analysis
GaN-on-sapphire epitaxy migration versus legacy silicon carbide platforms versus emerging non-polar crystal orientations creates a technology-generation pricing gap that widens with output power requirements. The dominant structure is contract-based long-term offtake agreements with wafer-level pricing for high-volume industrial buyers, while medical device OEMs pay premiums for FDA-cleared and METI JIS-certified single-mode devices. Price differentiation centers on certification grade and volume scale, with German surgical navigation OEMs showing lowest sensitivity due to reimbursement stability and Chinese materials processing buyers driving hardest negotiations. Cost compression in multi-mode industrial tiers is intensifying because MIIT dual carbon compliance investments are being passed through supply chains.
Supply Chain Analysis
Extended payment terms from Japanese materials processing equipment builders to domestic substrate suppliers illustrate how supplier-financing facilities lubricate concentrated upstream relationships. Geographic supply concentrates in Japan, Germany, and China, with raw material dependencies spanning indium metal from Chinese and Korean refiners, high-purity sapphire substrates from Japanese crystal growers, and specialty gases for MOCVD operations. Single-source vulnerability around Japanese substrate capacity represents the dominant structural risk, as non-integrated device manufacturers lack alternative qualified suppliers. Distribution runs through direct wafer-level procurement agreements for high-volume industrial buyers, bypassing traditional electronics distributors, while medical and research segments retain component distributor relationships for technical service and smaller lot sizes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from 10-year surgical laser maintenance commitments and MOCVD technician training contracts is expanding faster than hardware shipments among German hospital chains, transforming capital equipment vendors into recurring-revenue platforms.
For Market Incumbents: Build captive substrate moats through backward integration into sapphire and silicon carbide crystal growth or exclusive long-term supply agreements with Japanese growers. Defend against emerging Chinese epitaxy houses by accelerating FDA and METI JIS certification investments for next-generation non-polar GaN devices, and consolidate channel control through direct procurement relationships with Osaka-Tokyo precision optics cluster manufacturers that bypass distributor margins. For New Entrants and Emerging Players: Establish a beachhead in quantum dot biomedical imaging applications where spectral precision requirements exceed the capabilities of incumbent InGaN devices and regulatory barriers remain lower than surgical laser tiers. Target research institutes in Greater Boston and the Pacific Northwest for pilot production partnerships, and pursue a go-to-market angle based on wavelength customization services for multiplexed fluorescence detection systems that incumbent edge-emitter specialists cannot match. For Investors and Strategic Acquirers: The market sits at a substrate-transition phase that favors vertically integrated specialists with demonstrated MOCVD yield improvements and captive crystal growth capacity. Long-term viability over the next decade hinges on energy-efficient fab modernization and dual carbon compliance positioning for Chinese market access. Watch for inflection signals in MIIT enforcement windows and EU RoHS substance restriction amendments that would accelerate consolidation among non-compliant legacy housing manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Captive sapphire and silicon carbide crystal growth secures margin control against Japanese supply bottlenecks. |
| FDA 510(k) Clearance Pathway Investment | Pre-certification for fluorescence-guided surgical modules creates first-mover lock-in with German OEMs. |
| MIIT Dual Carbon Compliance Program | Energy-efficient MOCVD fab modernization preserves Chinese market access against tightening emissions standards. |
| Quantum Dot Pilot Production Scale-Up | Wavelength tunability beyond InGaN limits opens biomedical imaging white space in multiplexed detection. |
| Direct Procurement Partnership with Osaka-Tokyo Cluster | Wafer-level supply agreements with Japanese materials processing builders displace traditional distributor relationships. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with MOCVD equipment engineers, medical device procurement managers at German hospital chains, industrial laser system integrators in Japan's materials processing sector, and epitaxy house technical directors. Secondary validation drew from FDA 510(k) filings, METI JIS safety classification databases, EU RoHS substance restriction enforcement notices, and SEC filings of publicly traded optoelectronic component manufacturers. Bottom-up triangulation across device shipment data and top-down reconciliation against end-use equipment production estimates ensured cross-verified market sizing.
Calibration against historical capacity utilization rates at Regensburg and Japanese fabrication complexes anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, application end-use, customer type, and technology generation, with particular attention to single-mode versus multi-mode procurement splits and direct versus distributor channel shares. CAGRs were derived from slope analysis of normalized adoption curves in comparable optoelectronic component markets, adjusted for indium cost volatility and substrate supply constraints.
Stress conditions across indium price bands, Japanese substrate export restrictions, and MIIT dual carbon enforcement timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding MOCVD yield improvement trajectories and regulatory harmonization progress. Macroeconomic contraction, unilateral tariff imposition, or breakthrough quantum dot manufacturing scalability would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Algainp Epitaxial Wafers Market
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
Photoluminescent Film Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
Thermophotovoltaics Market
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
Quantum Dot Lasers Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Opto-Electronics Device Market
Optoelectronics
Integrated Circuit Optocouplers Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
3D Projector Market
Optoelectronics
Cadmium Telluride Photovoltaic Market
Optoelectronics
Optoelectronic Development Tools Market