
 Quantum Dot Lasers Market | 2026-2036
Quantum Dot Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Quantum Dot Lasers Market Analytics
Telecommunications infrastructure deployment is consolidating demand among major carriers upgrading fiber-optic backbones. Lumentum Holdings Inc. leverages its vertical integration in optical components to secure long-haul supply contracts. QD Laser Inc. anchors Japan's domestic photonics ecosystem through specialized quantum dot epitaxy capabilities. Coherent Inc. competes across multiple wavelength bands with broad semiconductor laser portfolios.
Quantum dot lasers are semiconductor devices that exploit three-dimensional quantum confinement in nanoscale crystal structures to achieve precise wavelength control and low threshold currents. The active region typically contains InAs or InGaAs quantum dots embedded in GaAs or InP matrices, enabling single-mode operation with linewidths below 1 MHz for coherent optical communications. Continuous Wave product variants dominate current revenue streams due to their deployment in dense wavelength-division multiplexing systems. Mode-Locked configurations represent the fastest-expanding category, driven by precision LiDAR and biomedical imaging applications where ultrashort pulse trains enable superior temporal resolution.
RoHS and REACH frameworks in Europe restrict hazardous substances in semiconductor manufacturing, while FDA 21 CFR Part 1040 governs laser product performance standards in the United States. Japan's METI promotes domestic photonics capabilities through industrial technology roadmaps that prioritize quantum dot device commercialization. Stakeholders must monitor evolving export control classifications for epitaxial growth equipment and assess dual-use technology licensing requirements before expanding fabrication capacity.
Market Dynamics
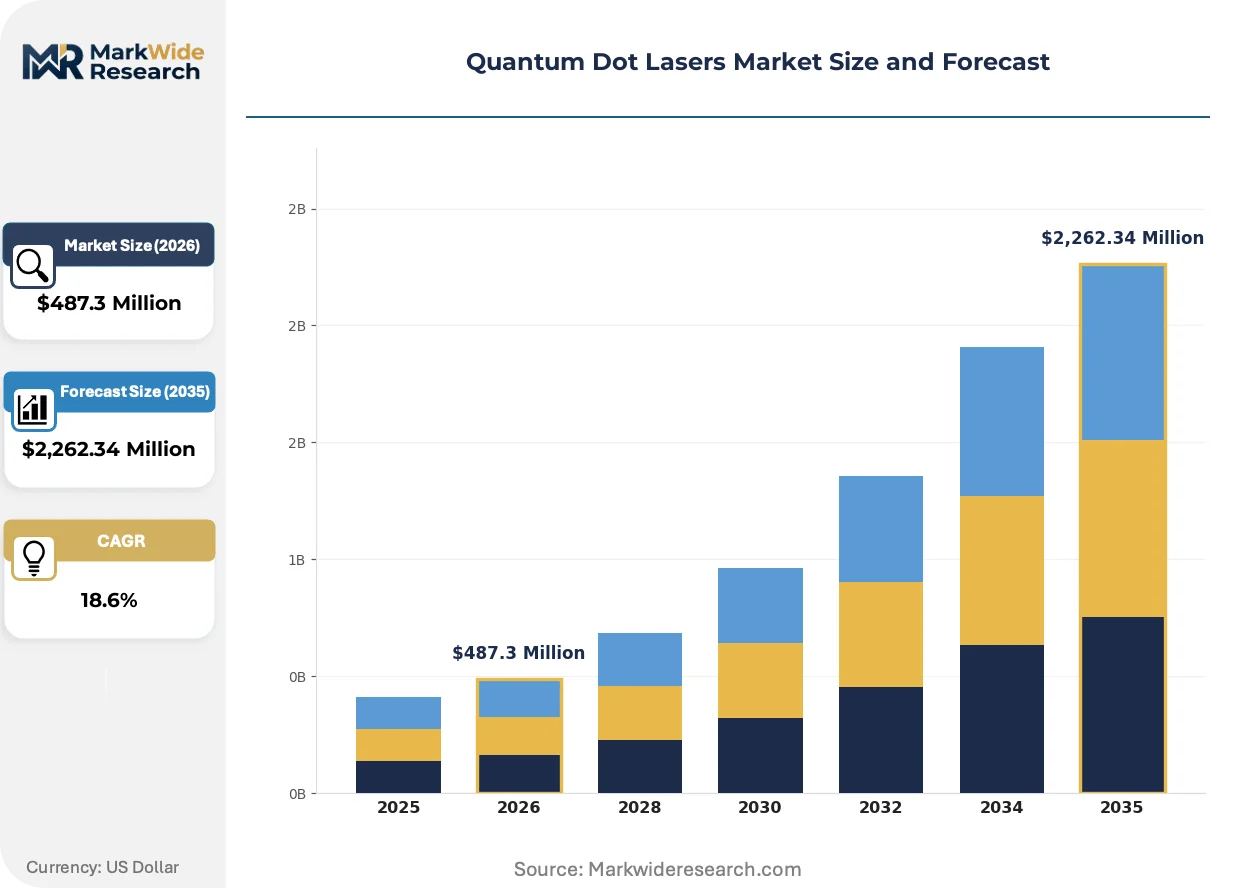
Telecommunications carriers are consolidating optical component procurement around vertically integrated suppliers capable of delivering quantum dot lasers at scale for 800G and 1.6T coherent transceivers. This concentration pressure is reshaping competitive positioning across epitaxial growth, packaging, and test functions.
Growth Catalysts
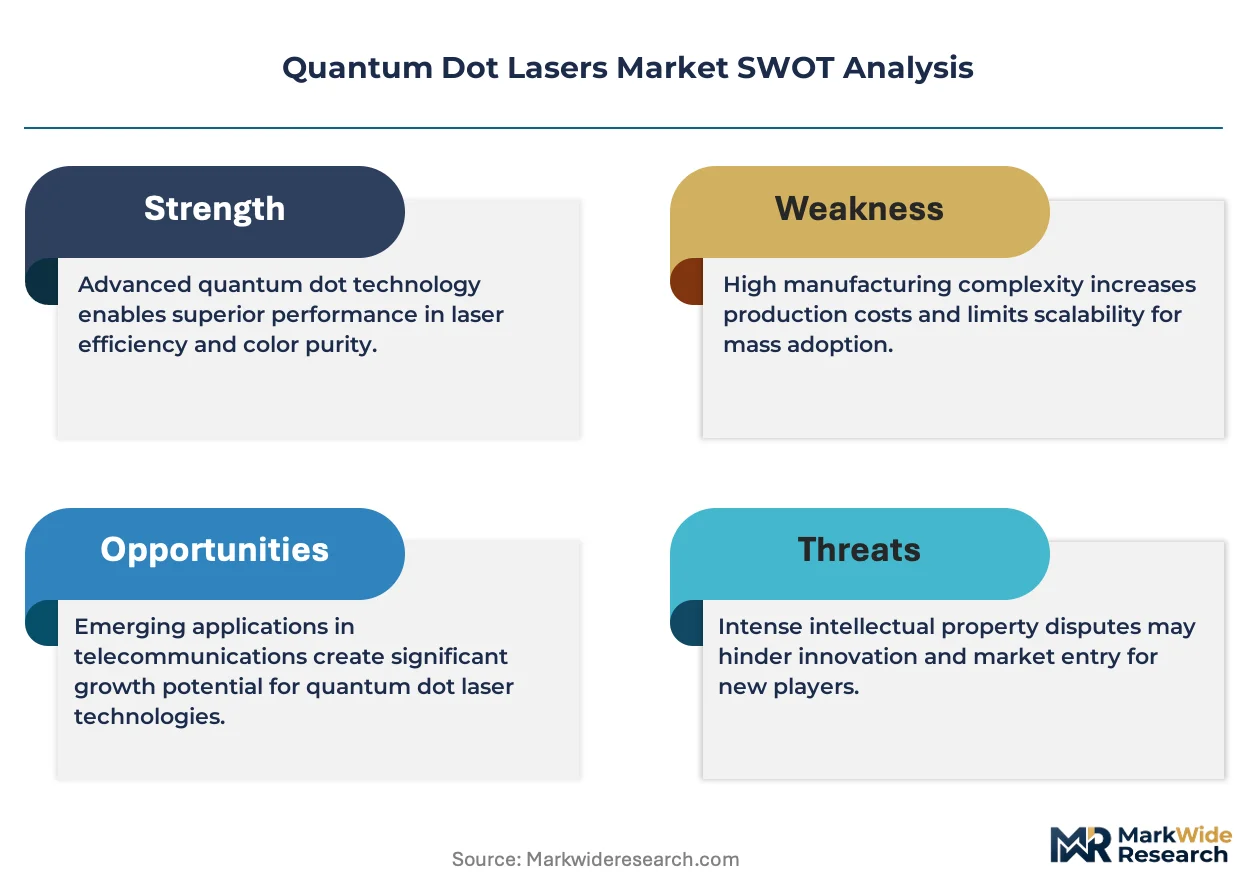
- RoHS and REACH frameworks:European hazardous substance restrictions are accelerating substitution of traditional III-V semiconductor lasers with quantum dot architectures that reduce toxic material content in manufacturing processes.
- Dense wavelength-division multiplexing expansion:Major carriers in Japan and the United States are deploying Continuous Wave quantum dot lasers to increase fiber capacity without laying new cable infrastructure.
- Mode-Locked pulse generation:Precision LiDAR and biomedical imaging applications are pulling ultrashort pulse quantum dot lasers into automotive and clinical diagnostics supply chains.
Market Restraints
- Molecular beam epitaxy equipment concentration:Production of quantum dot active regions depends on specialized MBE systems sourced from a limited supplier base in Germany and Japan.
- Indium price volatility:InAs and InGaAs quantum dot compositions expose manufacturers to raw material cost swings in rare earth metal markets.
- FDA 21 CFR Part 1040 compliance timelines:Laser product performance certifications for medical and industrial applications extend time-to-revenue by 12-18 months for new device introductions.
Strategic Opportunities
- METI industrial technology roadmaps:Japanese government funding priorities for quantum dot commercialization create captive demand for domestic epitaxy and packaging capabilities.
- Silicon photonics convergence:Hybrid integration of III-V quantum dot lasers with silicon waveguides is opening foundry-compatible manufacturing pathways for datacom transceivers.
- Biomedical imaging channel expansion:Direct sales to ophthalmology and dermatology equipment OEMs bypass traditional telecom distributor markups.
Industry Challenges
- Compound semiconductor process engineering talent:Quantum dot epitaxy requires specialized MBE operators and III-V device physicists in short supply across all major manufacturing regions.
- Multi-jurisdictional certification synchronization:Simultaneous FDA, CE marking, and PMDA submissions for medical laser products strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quantum Dot Lasers Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Wave, Pulsed, Mode-Locked, Quantum Cascade Technology: Optical Encoding, Semiconductor, Photonic Integrated Circuit, Hybrid Application: Telecommunications, Biomedicine, Consumer Electronics, Industrial Lasers End User: Telecom Providers, Research Institutions, Healthcare Facilities, Aerospace |
| Companies Covered | QD Laser Inc., Lumentum Holdings Inc., II-VI Incorporated, TOPTICA Photonics AG, Hamamatsu Photonics K.K., Sumitomo Electric Industries, Ltd., Coherent Inc., Princeton Optronics Inc., nLIGHT, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quantum Dot Lasers Market Evolving Landscape
Quantum dot laser architectures are fragmenting across application-specific configurations rather than converging on universal platforms. Suppliers are engineering distinct active region designs for coherent communications, sensing, and biomedical use cases.
Hybrid silicon-III-V integration is modularizing quantum dot laser manufacturing by separating epitaxial growth from photonic circuit fabrication. Datacom transceiver vendors in the United States are adopting this approach to access silicon foundry economics. The technology is compressing capital requirements for new market entrants while shifting value capture toward wafer-bonding and packaging specialists.
Japan's METI has embedded quantum dot device commercialization in national photonics roadmaps with explicit funding mechanisms through 2030. Domestic manufacturers are prioritizing Mode-Locked sources for precision measurement equipment over telecom variants. The policy is accelerating patent filings in ultrafast pulse generation while diverting R&D investment from continuous-wave coherent communications.
Carrier procurement teams are consolidating optical component suppliers into multi-year framework agreements with volume commitments and joint development clauses. Telecom equipment vendors in Japan and the United States are responding by absorbing test and burn-in functions previously outsourced to third parties. This behavior is most visible in 800G transceiver programs where quantum dot laser qualification cycles exceed product lifecycles.
Quantum Dot Lasers Market Segmentation
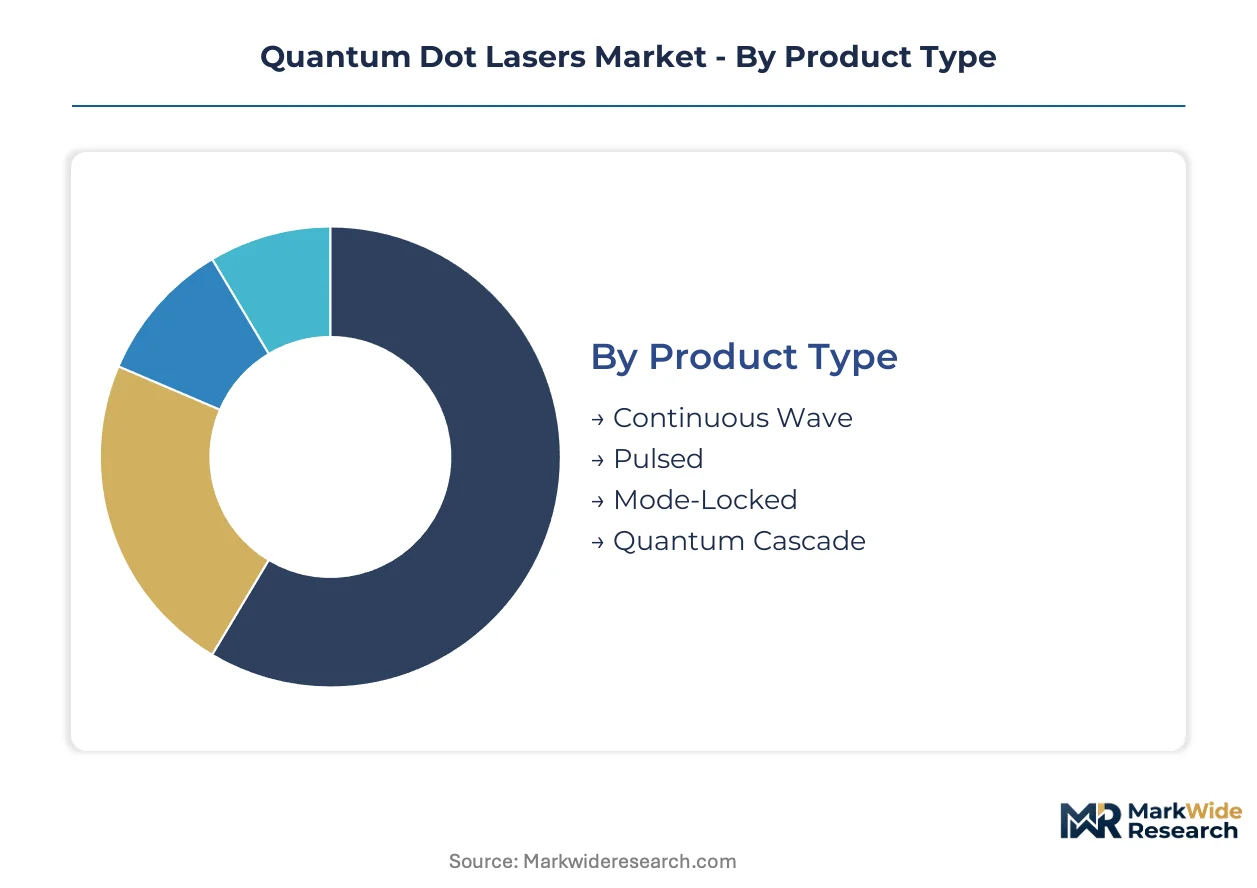
Quantum dot laser architectures fragment across distinct operational regimes and integration approaches. Buyers prioritize wavelength stability, pulse characteristics, or foundry compatibility depending on end-use requirements. Each segmentation dimension reveals divergent value capture patterns across the supply chain.
Product Type:
Buyers in this category differentiate primarily by temporal output requirements and coherence specifications for target applications.
- Continuous Wave:These sources deliver steady-state optical output with linewidths below 1 MHz for coherent communications. Dense wavelength-division multiplexing systems in Japan and the United States absorb the majority of volumes, driven by carrier upgrades to 800G and 1.6T transceivers.
- Mode-Locked:Ultrashort pulse trains with repetition rates tunable across GHz ranges enable precision LiDAR and biomedical imaging. Automotive OEMs and clinical diagnostics manufacturers in Germany and Japan are pulling these devices into next-generation sensing platforms.
- Pulsed:Q-switched or gain-switched configurations provide high peak power for materials processing applications. Industrial laser system integrators specify these for precision marking and micromachining tasks.
- Quantum Cascade:Intersubband emission in mid-infrared wavelengths serves spectroscopic sensing and defense applications. Environmental monitoring agencies and security contractors represent the primary demand concentration.
Continuous Wave leads volumes today; Mode-Locked is gaining share fastest.
Technology:
Cost tier and manufacturing scalability separate buyers selecting between bespoke epitaxial growth and foundry-compatible integration pathways.
- Semiconductor:Discrete III-V quantum dot lasers on native substrates deliver highest performance for telecom and scientific applications. Molecular beam epitaxy specialists in Japan and Germany control the supply base for these devices.
- Hybrid:Wafer-bonded III-V quantum dots on silicon waveguides merge epitaxial performance with CMOS economics. Datacom transceiver vendors in the United States are adopting this approach to access silicon foundry infrastructure.
- Photonic Integrated Circuit:Monolithic integration of lasers with modulators and multiplexers reduces packaging complexity. Co-packaged optics programs at cloud hyperscalers are validating these designs.
- Optical Encoding:Specialized modulation schemes for quantum key distribution and secure communications. Government research laboratories in the United States and European national quantum programs fund development.
Semiconductor dominates revenue today; Hybrid is expanding most quickly.
Application:
Volume scale and certification burden diverge sharply between established telecom procurement and emerging biomedical channels.
- Telecommunications:Coherent transceivers for long-haul and metro fiber networks consume the largest quantum dot laser volumes. Major carriers in Japan and the United States are consolidating procurement around vertically integrated suppliers.
- Biomedicine:Ophthalmology imaging and flow cytometry demand exceptional wavelength stability and low noise. FDA 21 CFR Part 1040 compliance timelines extend development cycles for device manufacturers targeting clinical markets.
- Industrial Lasers:Materials processing and precision measurement equipment incorporate quantum dot sources for improved beam quality. Machine tool OEMs in Germany and Japan specify these for high-value manufacturing cells.
- Consumer Electronics:Emerging applications in augmented reality and sensing modules remain pre-commercial. Consumer device manufacturers are evaluating quantum dot lasers against VCSEL alternatives for future product generations.
Telecommunications leads volumes today; Biomedicine is climbing the fastest.
End User:
Procurement sophistication and technical specification authority vary dramatically across institutional, commercial, and government buyers.
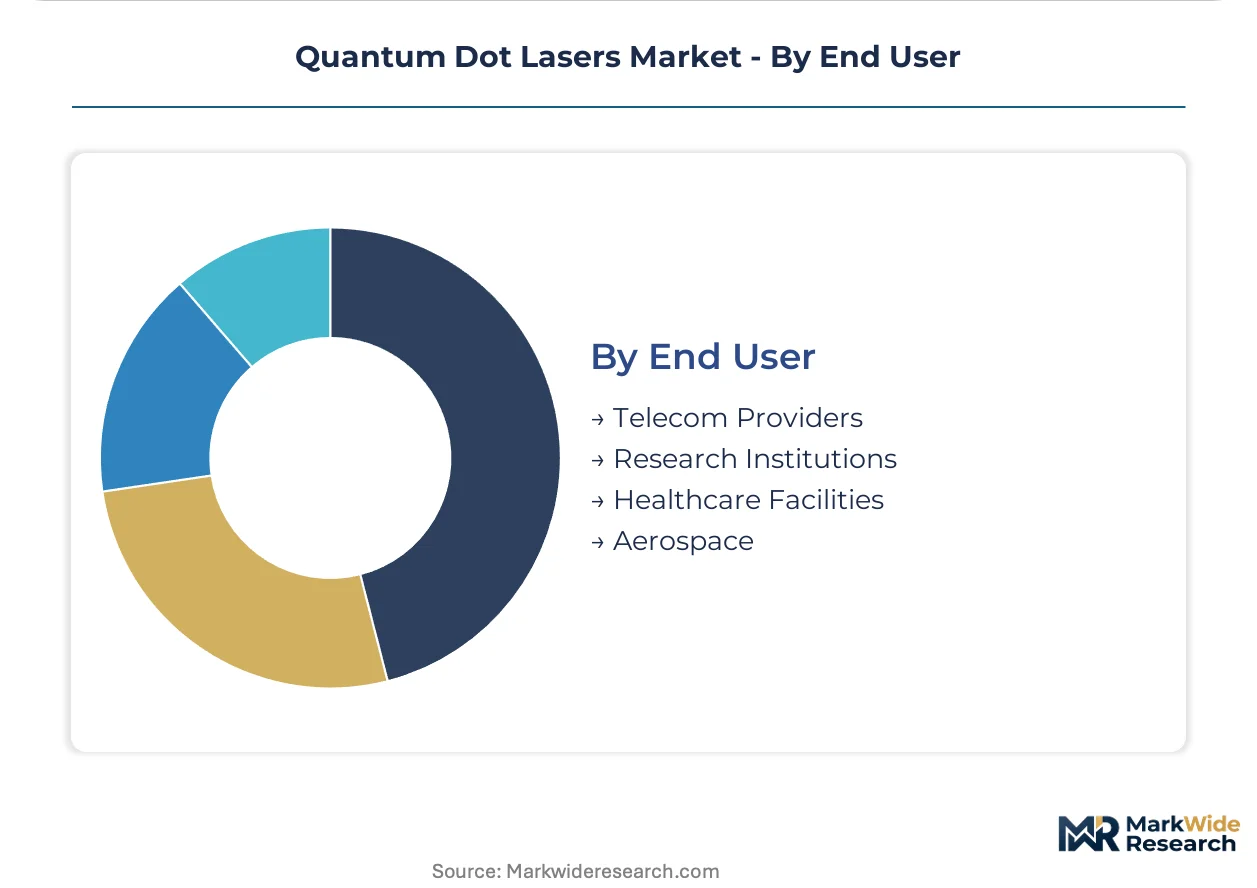
- Telecom Providers:Tier-1 carriers and cloud hyperscalers drive standardization through multi-year framework agreements. These buyers absorb test and burn-in functions previously outsourced to third parties.
- Healthcare Facilities:Hospital systems and clinical laboratories specify quantum dot lasers for diagnostic equipment. Procurement teams prioritize FDA-cleared devices with established service networks.
- Research Institutions:National laboratories and university groups purchase specialized configurations for fundamental studies. Funding from Japan's METI and the U.S. National Science Foundation supports quantum dot device development.
- Aerospace:Satellite communications and sensing platforms demand radiation-hardened and space-qualified devices. Defense contractors and space agencies specify these for next-generation payloads.
Telecom Providers lead volumes today; Healthcare Facilities is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamamatsu anchors the quantum dot laser production ecosystem, with Japan's photonics manufacturing clusters around Tokyo and Hamamatsu driving global supply concentration. National technology roadmaps and carrier procurement patterns are redistributing competitive positioning across four major markets.
Japan
METI industrial technology roadmaps prioritize quantum dot device commercialization through 2030 with explicit funding mechanisms. Domestic manufacturers concentrate Mode-Locked source development for precision measurement equipment in Hamamatsu and Tokyo clusters. QD Laser Inc. anchors the national photonics ecosystem through specialized epitaxy capabilities.
United States
FDA 21 CFR Part 1040 governs laser product performance standards for biomedical and industrial applications, extending certification timelines. Cloud hyperscalers and telecom carriers consolidate optical component procurement around vertically integrated suppliers. Silicon photonics convergence in California and Texas datacom corridors opens foundry-compatible manufacturing pathways.
Germany
RoHS and REACH frameworks restrict hazardous substances in semiconductor manufacturing, accelerating quantum dot architecture adoption. Molecular beam epitaxy equipment suppliers concentrate in German industrial regions, creating supply-side dependencies for active region production. TOPTICA Photonics AG exemplifies precision laser specialists serving research and industrial segments.
China
MIIT standards and national semiconductor self-sufficiency programs reshape import substitution dynamics for optical components. Domestic foundries and packaging houses in Yangtze River Delta and Pearl River Delta regions develop hybrid integration capabilities. Government research laboratories fund quantum key distribution and secure communications laser development.
Quantum Dot Lasers Market Competitive Landscape
Capacity expansion dominates the current landscape as telecom carriers consolidate procurement around suppliers capable of delivering quantum dot lasers at scale for 800G and 1.6T coherent transceivers. The vendor base stratifies across three tiers: vertically integrated optical component giants, specialized III-V epitaxy houses, and silicon photonics integrators. Two dominant competitive moves are reshaping positioning: backward integration into epitaxial growth functions, and strategic partnerships between laser specialists and datacom transceiver vendors.
Among Japan-based fabricators, QD Laser Inc., Hamamatsu Photonics K.K., and Sumitomo Electric Industries, Ltd. occupy positions within the specialized epitaxy and packaging tier. These companies exemplify the national industrial policy alignment where METI funding priorities create captive demand for domestic capabilities. United States-based Lumentum Holdings Inc. and Coherent Inc. represent the vertically integrated optical component archetype, with their corporate structures reflecting multi-decade consolidation across lasers, optics, and test equipment. German precision laser specialist TOPTICA Photonics AG sits within the research and scientific instrumentation segment, serving national laboratory and university demand distinct from telecom procurement channels.
| Leading Market Players |
|---|
| QD Laser Inc. |
| Lumentum Holdings Inc. |
| II-VI Incorporated |
| TOPTICA Photonics AG |
| Hamamatsu Photonics K.K. |
| Sumitomo Electric Industries, Ltd. |
| Coherent Inc. |
| Princeton Optronics Inc. |
| nLIGHT, Inc. |
| Others |
Value Network & Pricing Analysis
Indium price benchmarks on the London Metal Exchange cascade through quantum dot laser manufacturing, compressing margins for InAs and InGaAs epitaxy specialists while forcing tiered pricing stratification across telecom, biomedical, and industrial customer segments.
Pricing Analysis
Input-cost pass-through from indium and gallium arsenide substrates forces contract-based long-term offtake agreements for volume telecom buyers. Price differentiation hinges on FDA 21 CFR Part 1040 certification tier and molecular beam epitaxy wafer scale. Cost compression in standard continuous-wave variants intensifies as silicon photonics integrators access foundry economics. Healthcare facilities exhibit lowest price sensitivity due to reimbursement-protected procurement, while industrial laser OEMs negotiate hardest on unit economics.
Supply Chain Analysis
Freight cost inflation on specialized MBE equipment shipments from Germany and Japan adds 8-12% landed cost burden for new fabrication capacity. Supply concentrates in Japan's Hamamatsu-Tokyo corridor, Germany's precision optics belt, and California's silicon photonics corridor. Active region production draws from indium phosphide substrates, ultra-high-purity metalorganic precursors, and cryogenic cooling systems. Single-source vulnerability pervades molecular beam epitaxy tool supply. Distribution runs through vertically integrated optical component vendors and specialized photonics distributors serving research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quantum dot laser markets offer margin expansion through hybrid silicon-III-V integration cost-down curves and premium-tier mode-locked source adoption in precision sensing applications.
For Market Incumbents: Cement backward integration into indium arsenide epitaxy to offset raw material volatility and lock carrier procurement frameworks. Absorb test and burn-in functions from third-party providers to compress qualification cycles for 800G transceiver programs. Counter silicon photonics entrants by emphasizing linewidth performance in coherent communications specifications.
For New Entrants and Emerging Players: Launch via foundry-partnership models targeting datacom transceiver vendors in Texas and California corridors. Biomedical imaging channels in ophthalmology and dermatology equipment OEMs present the most penetrable white space, bypassing consolidated telecom distributor markups. Prioritize FDA pre-submission pathways to compress time-to-revenue against established clinical laser suppliers.
For Investors and Strategic Acquirers: Consolidation pressure builds where molecular beam epitaxy equipment concentration meets indium price volatility, favoring acquirers with captive raw material sourcing. Target specialized III-V epitaxy houses with METI-funded Japanese domestic demand and mode-locked patent portfolios. Watch silicon photonics foundry utilization rates as the inflection signal for hybrid integration economics tipping toward mainstream adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Growth | Captive InAs quantum dot supply secures carrier procurement frameworks against indium volatility. |
| Hybrid Silicon-III-V Manufacturing Partnership | Wafer-bonding collaborations with TSMC or Intel Foundry Services unlock CMOS economics for datacom transceivers. |
| FDA 21 CFR Part 1040 Certification Investment | Pre-market notification pathways accelerate biomedical imaging revenue capture in ophthalmology segments. |
| Mode-Locked Source R&D Expansion | Ultrafast pulse patents align with METI roadmaps and automotive LiDAR qualification timelines. |
| Multi-Year Carrier Framework Agreements | Volume commitments with NTT or Verizon lock out silicon photonics challengers through joint development clauses. |
Research Methodology
Direct dialogue with molecular beam epitaxy equipment specialists, telecom carrier procurement directors, FDA regulatory affairs consultants, and biomedical laser OEM technical leads grounded qualitative findings. Secondary validation drew from FDA 510(k) and PMA filings, METI industrial technology roadmaps, SEC 10-K disclosures from Lumentum and Coherent, and Japan Patent Office quantum dot device filings. Bottom-up wafer capacity modeling and top-down carrier capex allocation analysis were triangulated against foundry utilization reports.
Segment-level value outputs across the projection horizon reflect product-type splits between continuous-wave and mode-locked architectures, technology tiers spanning semiconductor through photonic integrated circuit, and application concentration across telecommunications and biomedicine. CAGRs were derived from carrier transceiver deployment schedules, datacenter interconnect buildout trajectories, and clinical diagnostic equipment replacement cycles. Indium price elasticity and MBE tool delivery lead times fed supply-side constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control reclassification for epitaxial growth equipment or abrupt indium supply disruptions from primary extraction regions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
Light Projector Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Gallium Arsenide Market
Optoelectronics
EPON ONU Market
Optoelectronics
United States Optoelectronics Market
Optoelectronics
Gaas Photodiode Market
Optoelectronics
Global Shortwave Infrared (SWIR) Market
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
Optocoupler IC Market
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
Taiwan Optoelectronics Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
Ingaas Avalanche Photodiode Market
Optoelectronics
Optoelectronic Transducers Market