
 Qatar PVC Pipe Market | 2026-2036
Qatar PVC Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar PVC Pipe Market Intelligence
The gap between premium chlorinated PVC formulations and standard unplasticized grades is expanding across Qatar's project pipeline. Amiantit Qatar Pipes Company leverages its large-diameter extrusion capacity to dominate infrastructure tenders for water transmission networks. Gulf Plastic Industries W.L.L. sustains cost competitiveness through backward integration into resin compounding operations. Hepworth (Qatar) LLC differentiates via British Standard-certified product lines that command specification preference among European engineering consultants active in the emirate.
PVC pipes are thermoplastic conduits manufactured from polyvinyl chloride resin with stabilizer and filler additives, extruded in schedules ranging from Schedule 40 to Schedule 80 to withstand internal pressures from 6 to 25 bar depending on diameter and wall thickness. These pipes transport pressurized fluids, drain wastewater, and protect electrical cabling across building and civil infrastructure. PVC pressure pipes capture the dominant margin pool due to stringent potable water certification requirements and limited domestic manufacturing alternatives. PVC drainage pipes face commoditization from import competition but retain volume leadership in building construction applications. PVC electrical conduit segments show structural growth tied to Qatar's data center and telecommunications infrastructure buildout.
Kahramaa's Technical Standards for Water and Wastewater Networks mandate specific pressure ratings and joint performance criteria that filter non-compliant imports from project specifications. Qatar Construction Specifications (QCS) and Ministry of Municipality and Environment drainage codes enforce material traceability and UV-stabilization requirements for above-ground installations. Procurement officers must monitor evolving local content thresholds under Qatar National Vision 2030 industrial development frameworks, as domestic compounding and extrusion capabilities determine bid competitiveness on state-funded mega-projects.
Market Dynamics
Kahramaa's escalating pressure-rating mandates for potable water transmission networks are compressing the supplier base, privileging domestic extruders with large-diameter certification over import-reliant distributors.
Growth Catalysts
- Lusail Development Authority infrastructure pipelines:Mega-project water distribution networks specify Schedule 80 chlorinated PVC for high-pressure zones, creating dedicated demand for certified domestic manufacturers.
- Qatar National Vision 2030 local content thresholds:State procurement rules now weight domestic compounding and extrusion capabilities in bid scoring, redirecting volume toward integrated producers.
- Data center electrical conduit specifications:Telecommunications infrastructure buildout in Doha's technology zones is accelerating specification of flame-retardant PVC conduit for cable protection systems.
Market Restraints
- Ethylene and chlorine feedstock volatility:Qatar's petrochemical complex supplies resin precursors, but global chlorine price swings compress margin predictability for domestic compounders.
- Import competition in drainage segments:Unplasticized PVC drainage pipes face price pressure from Saudi and UAE extruders with lower logistics costs to Doha construction sites.
- Pressure-rating certification bottlenecks:Kahramaa's extended testing protocols for new product approvals delay market entry for unproven formulations and joint designs.
Strategic Opportunities
- Al Wakrah and Al Khor municipal expansions:Secondary city water network extensions outside Doha-Lusail corridor offer first-mover positioning for certified suppliers before import channels establish.
- Solar thermal installation integration:Building-integrated renewable energy mandates are creating specification demand for UV-stabilized PVC piping in collector loop applications.
- Direct contractor procurement platforms:Digital tendering systems under Qatar's e-government initiative are shortening distribution layers between extruders and project engineers.
Industry Challenges
- Large-diameter extrusion technician scarcity:Specialized machine operation and die maintenance skills for 600mm+ pressure pipes command premium wages and limit production scale-up.
- Joint integrity testing capacity:Third-party laboratories capable of validating elastomeric seal performance under cyclic pressure remain concentrated in Doha, creating logistics bottlenecks for urgent project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar PVC Pipe Market |
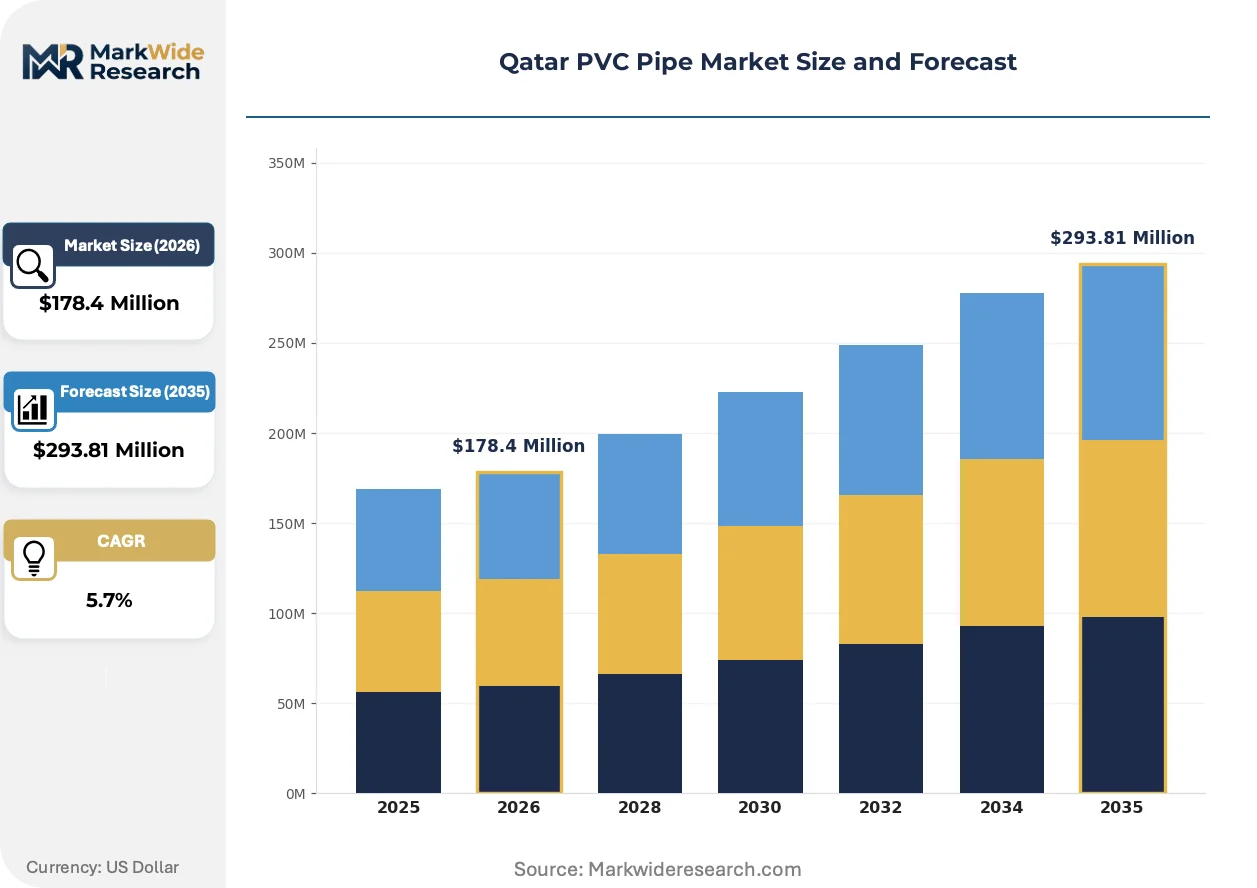
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $293.81 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC Pressure Pipes, PVC Drainage Pipes, PVC Electrical Conduit, PVC Fittings Application: Water Supply, Waste Management, Electrical Installations, Irrigation End User: Construction, Agriculture, Telecommunications, Industrial Manufacturing Distribution Channel: Direct Sales, Retail Outlets, Online Platforms, Wholesale |
| Companies Covered | Amiantit Qatar Pipes Company, Gulf Plastic Industries W.L.L., Hepworth (Qatar) LLC, Qatar Pipeline & Fittings Co. (QPF), Qatar National Plastic Factory (QPLAST), Qatar Plastic Products Company W.L.L., Almuftah Polymer W.L.L., Advanced Plastic Factory, Doha Plastics Co. LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar PVC Pipe Market Strategic Shifts & Innovations
Material formulation advances and procurement digitization are restructuring how specifications propagate from engineering consultants to site installation, compressing traditional distributor influence.
High-impact chlorinated PVC (CPVC) formulations with enhanced temperature resistance are penetrating Qatar's hot-water distribution specifications. Mechanical contractors in Lusail's residential towers specify CPVC for riser applications previously dominated by metal alternatives. This material shift is decentralizing specification authority from civil engineers toward MEP contractors with direct installation experience.
Qatar Construction Specifications 2024 revisions mandate blockchain-traceable material certificates for all pressure-rated piping in state-funded projects. The Ministry of Municipality and Environment now requires digital provenance records linking resin batch to extrusion lot to installation site. Above-ground water transmission networks face the steepest compliance burden, with contractors scrambling to integrate QR-code tracking into existing logistics workflows.
Engineering-procurement-construction firms are consolidating vendor panels around pre-qualified domestic extruders with integrated compounding operations. Tier-one contractors in Doha's stadium and hospitality sectors now bypass import distributors entirely, negotiating direct supply agreements with Amiantit Qatar and Gulf Plastic Industries. This concentration pattern is most visible in mega-project tenders where local content scoring determines bid ranking.
Qatar PVC Pipe Market Segmentation
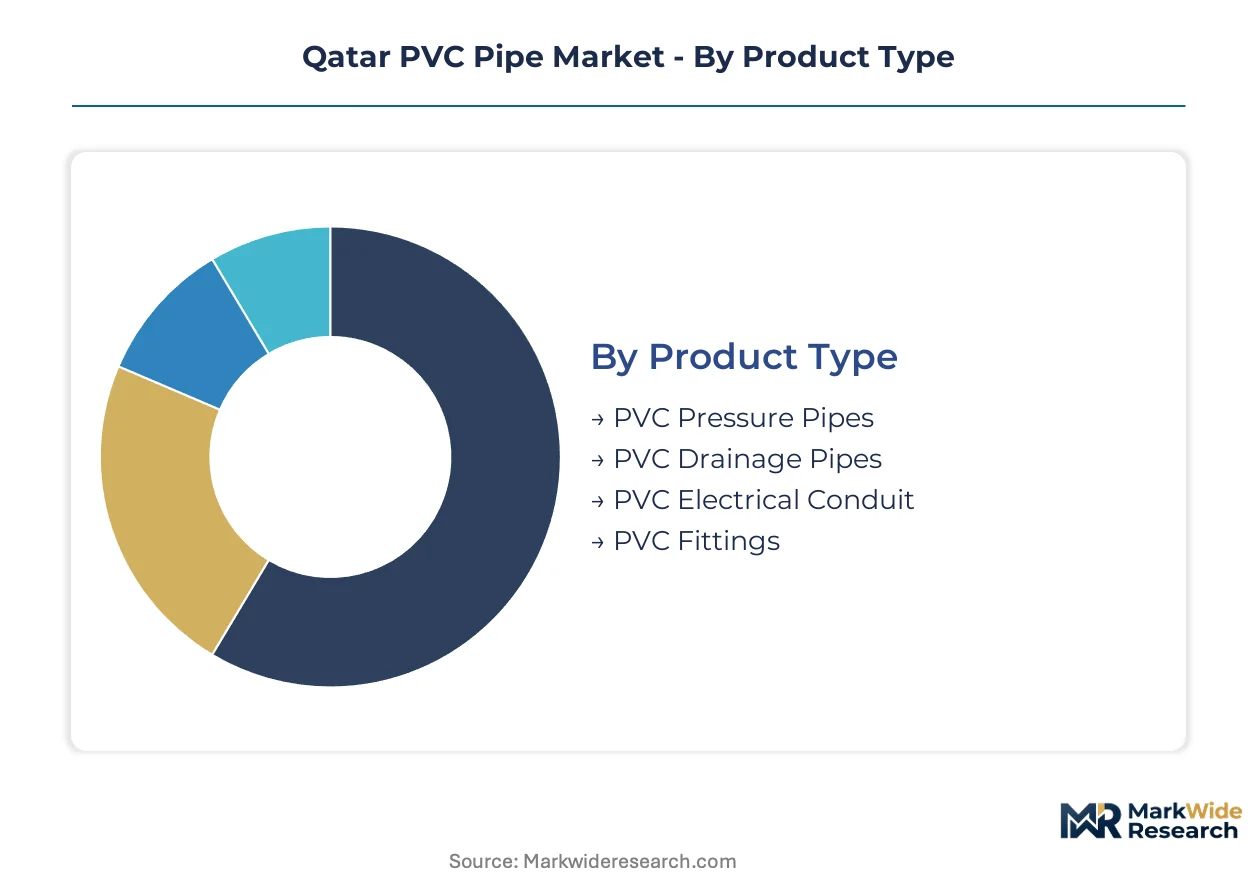
Segmentation in Qatar's PVC pipe market reveals how procurement authority concentrates around certification tiers and project scale. Understanding these divides exposes where specification power sits and how domestic manufacturers defend position against import competition.
Product Type:
Standalone infrastructure systems dominate Qatar's high-value procurement, while building-embedded applications compete on cost efficiency.
- PVC Pressure Pipes:Engineered for 6-25 bar internal pressure with reinforced wall schedules and elastomeric joint systems. Kahramaa's potable water transmission networks in Doha and Lusail specify these exclusively, with local content scoring privileging domestic extruders holding large-diameter certification.
- PVC Drainage Pipes:Unplasticized formulations with gravity-flow profiles and solvent-weld or push-fit joints. Building construction across Al Wakrah and Al Khor municipal zones absorbs volume, though Saudi and UAE imports erode margin through lower logistics costs.
- PVC Electrical Conduit:Flame-retardant formulations protecting low-voltage cabling in commercial and data center infrastructure.
- PVC Fittings:Injection-molded elbows, tees, and reducers completing system integrity for pressure and drainage networks.
PVC drainage pipes lead volumes today; PVC pressure pipes are gaining share fastest through Kahramaa mandate expansion.
Application:
Cost tier stratification separates state-funded mega-projects from private building installations, with specification authority residing at different engineering levels.
- Water Supply:High-pressure transmission and distribution networks requiring potable water certification under Kahramaa Technical Standards. Lusail Development Authority infrastructure pipelines specify Schedule 80 chlorinated PVC for critical zones, creating dedicated demand for certified domestic manufacturers with integrated compounding operations.
- Waste Management:Gravity sewer systems and stormwater drainage governed by Ministry of Municipality and Environment codes. Above-ground installations face UV-stabilization mandates that filter non-compliant imports from project specifications.
- Electrical Installations:Cable protection systems for building infrastructure and telecommunications.
- Irrigation:Landscape and agricultural distribution networks operating at lower pressure ratings.
Water supply dominates value capture; electrical installations are expanding most quickly through data center buildout.
End User:
Customer type determines procurement channel complexity, with state entities demanding direct manufacturer engagement and private contractors tolerating distributor intermediaries.
- Construction:Civil infrastructure and building contractors specifying materials across water, drainage, and electrical systems. Engineering-procurement-construction firms in Doha's stadium and hospitality sectors now consolidate vendor panels around pre-qualified domestic extruders, bypassing import distributors entirely on mega-project tenders.
- Agriculture:Farm operators and landscape developers sourcing lower-specification irrigation piping.
- Telecommunications:Data center and network infrastructure operators requiring flame-retardant conduit specifications.
- Industrial Manufacturing:Process water and chemical handling applications with specialized corrosion requirements.
Construction leads volumes today; telecommunications is climbing the fastest on data center infrastructure mandates.
Distribution Channel:
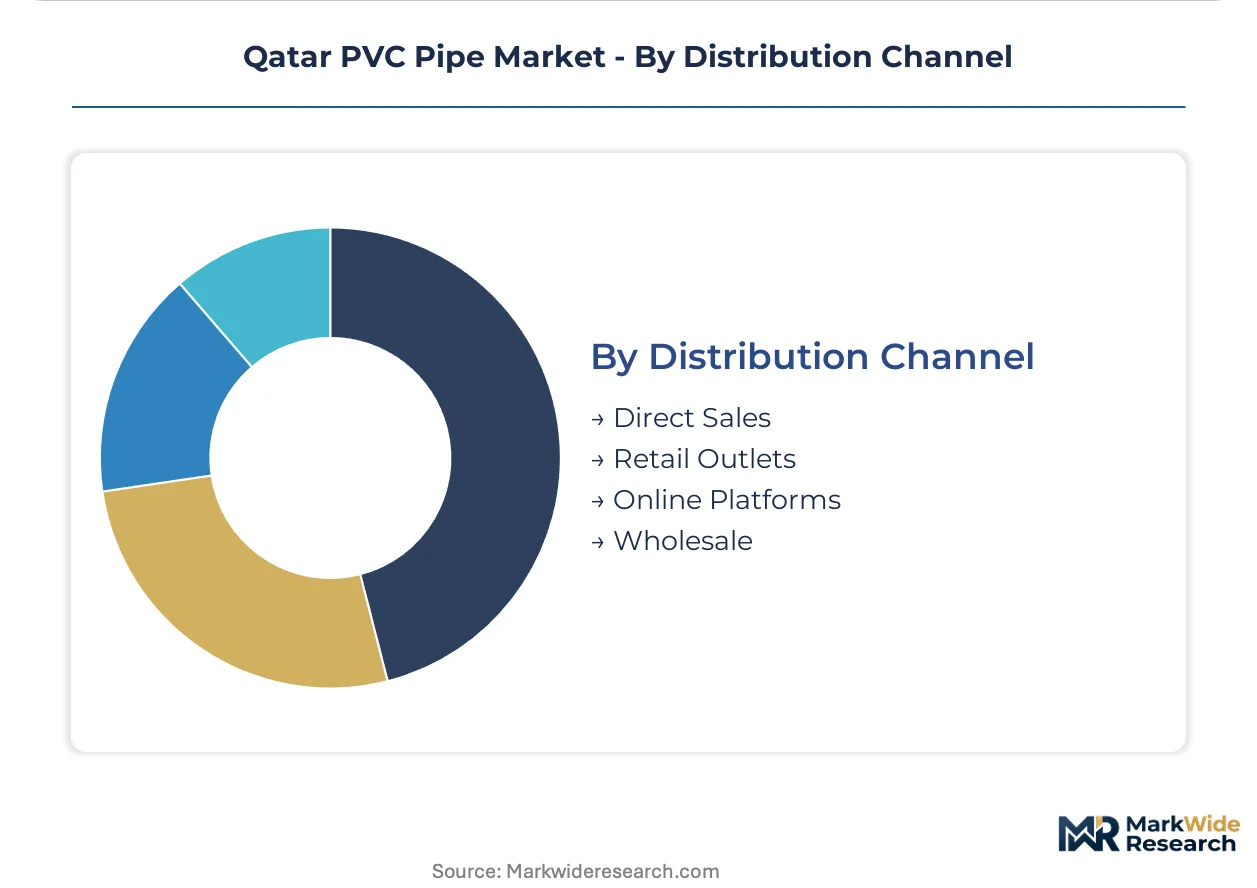
Supply concentration favors direct manufacturer engagement where local content scoring determines bid outcomes, while retail and wholesale serve fragmented private construction.
- Direct Sales:Manufacturer-to-contractor relationships dominating state-funded mega-projects. Qatar National Vision 2030 procurement rules weight domestic compounding and extrusion capabilities in bid scoring, redirecting volume toward integrated producers with established direct channels.
- Retail Outlets:Building material merchants serving small-scale contractors and maintenance operations.
- Online Platforms:Digital tendering systems under Qatar's e-government initiative shortening distribution layers between extruders and project engineers.
- Wholesale:Import distributors holding inventory for drainage segments where price competition from Saudi and UAE extruders pressures margin.
Direct sales leads volumes today; online platforms are gaining share fastest through procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized extrusion technicians and large-diameter certification specialists cluster around Doha's industrial zones, anchoring Qatar's domestic PVC pipe production capacity.
Doha Metropolitan Area
Kahramaa's potable water transmission networks and Lusail Development Authority mega-projects drive specification-grade demand for Schedule 80 chlorinated PVC. The Ministry of Municipality and Environment enforces blockchain-traceable material certificates under Qatar Construction Specifications 2024 revisions. Mesaieed Industrial City hosts integrated compounding and extrusion facilities serving state-funded infrastructure tenders.
Al Wakrah Municipality
Secondary city water network extensions and municipal drainage expansions absorb mid-pressure PVC formulations. Qatar National Vision 2030 local content thresholds filter procurement toward domestic manufacturers with verified extrusion capabilities. The Al Wakrah South development corridor attracts first-mover positioning from certified suppliers before import channels establish.
Al Khor Municipality
Agricultural irrigation systems and coastal infrastructure projects specify lower-pressure PVC drainage grades. Above-ground installations face UV-stabilization mandates under Ministry of Municipality and Environment drainage codes. The Al Thakira industrial zone concentrates fabrication workshops serving northern construction corridors.
Lusail Development Zone
Residential tower MEP contractors specify CPVC hot-water riser applications previously dominated by metal alternatives. Kahramaa Technical Standards mandate specific pressure ratings and elastomeric joint performance criteria. The Lusail Marina district anchors telecommunications infrastructure buildout requiring flame-retardant electrical conduit specifications.
Al Rayyan Municipality
Stadium and hospitality sector mega-projects consolidate vendor panels around pre-qualified domestic extruders. Qatar General Electricity and Water Corporation standards privilege large-diameter certification holders in bid scoring. The Education City technology corridor accelerates data center electrical conduit demand through specialized cable protection specifications.
Qatar PVC Pipe Market Key Industry Players
Top-tier vendors anchor infrastructure-grade pressure piping, while import-reliant distributors compete on drainage commoditization. The supplier base compresses around three strategic tiers: integrated domestic compounders with Kahramaa certification, regional extruders serving price-sensitive building segments, and specialized electrical conduit fabricators. Dominant competitive moves include backward integration into resin compounding operations and direct contractor procurement platform development under Qatar's e-government initiative.
Among Qatar-based integrated manufacturers, Amiantit Qatar Pipes Company and Gulf Plastic Industries W.L.L. represent the certification-heavy infrastructure tier, while Hepworth (Qatar) LLC occupies a position exemplifying British Standard-aligned specification preference. These three anchors illustrate how domestic extrusion capability, local content scoring alignment, and consultant specification relationships stratify competitive positioning across state-funded mega-projects versus private building construction.
| Leading Market Players |
|---|
| Amiantit Qatar Pipes Company |
| Gulf Plastic Industries W.L.L. |
| Hepworth (Qatar) LLC |
| Qatar Pipeline & Fittings Co. (QPF) |
| Qatar National Plastic Factory (QPLAST) |
| Qatar Plastic Products Company W.L.L. |
| Almuftah Polymer W.L.L. |
| Advanced Plastic Factory |
| Doha Plastics Co. LLC |
| Others |
Cost & Logistics Intelligence
Kahramaa's blockchain-traceable material certificate mandates under Qatar Construction Specifications 2024 revisions gate both qualified supply access and premium-tier pricing power for pressure-rated piping systems. Domestic extruders with integrated compounding operations capture margin premiums while import-reliant distributors face qualification barriers that compress their addressable market.
Pricing Analysis
Bundled certification-and-delivery contracts dominate state-funded mega-projects, while unbundled spot purchasing persists in private drainage segments. Three-tier pricing structure across Kahramaa-certified premium, standard domestic, and import economy levels reflects certification investment recovery and local content scoring advantages. Pricing pressure stems from Saudi and UAE extruders undercutting drainage pipe margins through lower logistics costs to Doha construction sites. Small-scale contractors in Al Wakrah and Al Khor municipal zones exhibit highest price sensitivity, whereas Lusail Development Authority procurement officers prioritize certification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Kahramaa and major EPC contractors mandate multi-supplier qualification, forcing extruders to maintain redundant certification portfolios. Geographic supply concentration centers on Qatar's Mesaieed Industrial City for integrated compounding and extrusion, with resin precursor feedstock drawn from Qatar's Ras Laffan petrochemical complex and specialty additives sourced from Germany and Japan. Raw material dependencies on ethylene, chlorine, and calcium carbonate stearate create margin volatility exposure. Supply chain risk rests on single-source vulnerability for large-diameter extrusion die maintenance expertise concentrated in Doha. Distribution runs through direct manufacturer-to-contractor channels for state projects, with wholesale import distributors serving fragmented private construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through CPVC formulation premiums displacing metal alternatives in hot-water riser applications, coupled with local content scoring advantages that reward domestic compounding investment.
For Market Incumbents: Deploy backward integration into resin compounding operations to secure local content scoring advantages on Kahramaa tenders. Amiantit Qatar and Gulf Plastic Industries should extend large-diameter certification coverage to 800mm+ specifications before regional competitors qualify. Certification investment in British Standard and ISO 4422 dual-approval creates specification stickiness against emerging Saudi entrants targeting Lusail infrastructure pipelines. For New Entrants and Emerging Players: Enter via Al Wakrah South and Al Khor municipal water network extensions where first-mover positioning precedes import channel establishment. Target mid-pressure PVC formulations for secondary city drainage expansions where Kahramaa mandates are less stringent than Doha-Lusail corridors. Partner with European engineering consultants active in Qatar to secure specification preference through consultant-approved product lines. For Investors and Strategic Acquirers: Roll-up economics work for regional extruders with dormant Kahramaa certification because local content thresholds under Qatar National Vision 2030 permanently privilege domestic manufacturing capacity. Five-to-ten year viability hinges on integrated compounding capabilities rather than pure extrusion assets. Monitor CPVC penetration rates in residential tower MEP specifications as the inflection signal for material substitution away from metal dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures local content scoring advantages on state-funded mega-projects under Qatar National Vision 2030 procurement rules. |
| Large-Diameter Certification Expansion | Qualifies suppliers for Kahramaa transmission network tenders specifying 600mm+ pressure pipes in Doha and Lusail corridors. |
| CPVC Formulation Development | Displaces copper and steel in Lusail residential tower hot-water riser applications previously dominated by metal alternatives. |
| Blockchain-Traceable Logistics Systems | Complies with Qatar Construction Specifications 2024 mandates for digital provenance records linking resin batch to installation site. |
| Direct Contractor Procurement Platforms | Shortens distribution layers under Qatar's e-government initiative, bypassing wholesale import distributors on state tenders. |
Research Approach
Bottom-up construction sector modeling reconciled against top-down resin consumption tracking forms the analytical core of this study. Primary interviews with extrusion plant managers, EPC procurement officers, Kahramaa technical standards engineers, and Ministry of Municipality and Environment compliance officers were cross-validated against secondary sources including Qatar Central Bank construction sector indices, Kahramaa annual procurement disclosures, customs import records for PVC resin and finished pipe, and Qatar National Vision 2030 industrial development framework documents. Triangulation between demand-side project pipelines and supply-side manufacturing capacity ensures forecast coherence.
Input-output matrix framing connects ethylene and chlorine feedstock availability to extrusion throughput and finished pipe pricing tiers across the projection horizon. Segmentation dimensions modeled include product type (pressure, drainage, electrical conduit), application (water supply, waste management, telecommunications), and end user (state-funded construction, private building, agriculture). CAGRs were derived from project-level demand aggregation and capacity expansion announcements. Industry-specific forecast inputs incorporate Lusail Development Authority infrastructure timelines and Kahramaa technical standards revision schedules.
Inputs from primary fieldwork and Qatar government procurement databases were available through the study window; gaps in real-time resin pricing volatility and unannounced competitor certification achievements introduce uncertainty bands around margin projections. Deviation in Kahramaa's pressure-rating mandate timeline or chlorine feedstock cost spikes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Global Municipal Pipes Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
Pipe and Tube Cutters Market
Pipes and Tubes
Industrial Blast Hoses Market
Pipes and Tubes
Glass Reinforced Epoxy (GRE) Pipes Market
Pipes and Tubes
Steel Tubes Market
Pipes and Tubes
Aluminium Tubes for OPC Drum Market
Pipes and Tubes
Global Polyolefin Pipes Market
Pipes and Tubes
Agricultural Pipes and Tubes Market
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
Global Fiberglass Pipe Market
Pipes and Tubes
Galvanized Steel Tubes Market
Pipes and Tubes
HDPE Pipes Market
Pipes and Tubes
Stainless Steel Welded Pipes Market