
 Steel Tubes Market | 2026-2036
Steel Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Tubes Market Intelligence
REACH is hardening the cost-of-entry calculus for European steel tube exporters, forcing reformulation of epoxy and powder coating systems to eliminate restricted substances. Nucor Corporation leverages its electric arc furnace footprint to supply low-carbon tubulars for energy infrastructure. ArcelorMittal S.A. anchors its position through integrated iron ore-to-tube production across multiple continents. Tenaris S.A. specializes in premium seamless products for sour-service oilfield environments.
Steel tubes are hollow cylindrical sections manufactured from carbon steel, alloy steel, or stainless steel through either seamless extrusion or welded roll-forming processes, typically specified by outer diameter, wall thickness, and yield strength grades for pressure containment or structural load-bearing. Seamless tubes command premium positioning in high-pressure oil and gas applications where weld integrity risks are unacceptable, while welded tubes dominate construction and manufacturing due to cost efficiency at medium diameters. Galvanized coating retains volume leadership in outdoor structural uses, though epoxy-coated alternatives are gaining specification share in corrosive soil and marine environments.
The US EPA enforces strict volatile organic compound limits on coating operations, compelling tube producers to shift toward water-based and high-solids formulations. China's MEE implements dual carbon goals that tighten energy intensity benchmarks for seamless tube rolling mills. India's BIS mandates ISI certification for structural tubulars used in public works, creating compliance barriers for uncertified imports. Stakeholders must monitor how carbon border adjustments and evolving pressure equipment directives reshape sourcing strategies and capital allocation across coating and diameter portfolios.
Market Dynamics
Corrosion-resistant coating chemistry is reshaping procurement specifications as pipeline operators confront sour-service field conditions and regulatory substance restrictions simultaneously. REACH compliance deadlines and EPA volatile organic compound limits are forcing simultaneous reformulation of epoxy and powder systems across multiple continents.
Growth Catalysts
- India's infrastructure buildout:Water distribution networks and structural applications are absorbing welded tube volumes as public works expand under BIS-mandated ISI certification requirements.
- REACH substance restrictions:European coating chemistry reformulation is elevating technical barriers that favor producers with integrated R&D and testing capabilities.
- Sour-service oilfield specifications:Premium seamless tubular demand concentrates in high-pressure environments where weld integrity risks are operationally unacceptable.
Market Restraints
- Scrap and iron ore input volatility:Electric arc furnace and integrated mill feedstock costs fluctuate with commodity cycles, compressing margin predictability for tube producers.
- Chinese seamless rolling concentration:Dual carbon goals enforced by MEE are tightening energy intensity benchmarks and constraining export availability from dominant suppliers.
- Polymer composite substitution:Reinforced thermoplastic pipes are displacing steel in low-pressure water and corrosive chemical applications where flexibility and corrosion immunity outweigh pressure ratings.
Strategic Opportunities
- Carbon border adjustment preparation:European importers are pre-qualifying low-carbon tubular suppliers ahead of phased carbon tariff implementation.
- Hydrogen pipeline certification:Emerging embrittlement-resistant alloy specifications for hydrogen transport infrastructure are creating premium product white space.
- Digital mill channel expansion:Direct-to-fabricator platforms are compressing distributor layers in standardized structural tube categories.
Industry Challenges
- Coating technician scarcity:Water-based and high-solids formulation expertise lags behind solvent-based legacy skill pools, extending qualification timelines.
- Multi-standard certification burden:Simultaneous compliance with API, ASTM, EN, and BIS specifications for cross-border projects strains quality documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Tubes Market |
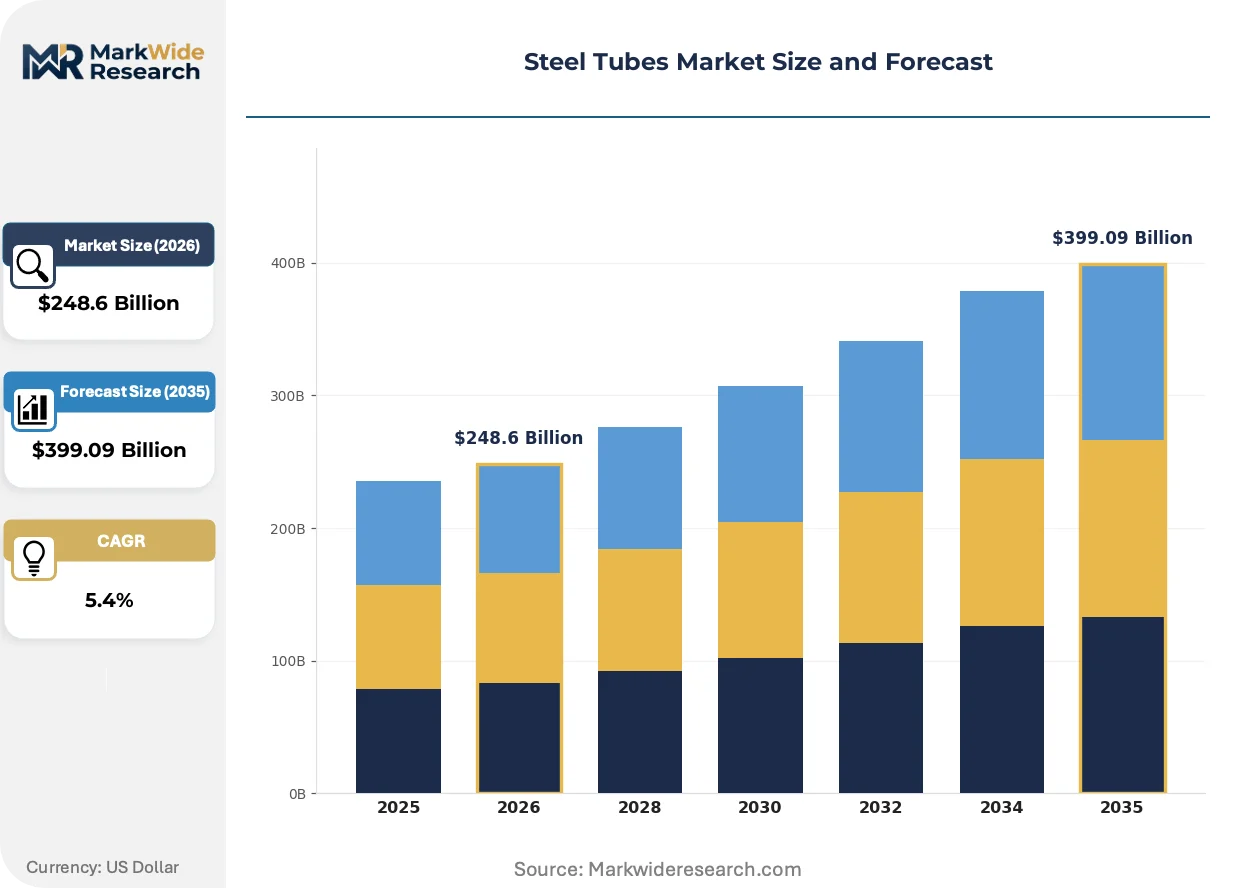
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $399.09 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless, Welded, Fabricated, Special Purpose End User: Construction, Automotive, Oil & Gas, Manufacturing Diameter: Small Diameter, Medium Diameter, Large Diameter, Extra Large Diameter Coating Type: Galvanized, Powder Coated, Epoxy Coated, Uncoated |
| Companies Covered | Nucor Corporation, Borusan Mannesmann Boru Sanayi ve Ticaret A.S., ArcelorMittal S.A., Tata Steel Limited, United States Steel Corporation, Nippon Steel Corporation, China Baowu Steel Group Corp., Ltd., Tenaris S.A., JFE Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Tubes Market Strategic Shifts & Innovations
Manufacturing technology and regulatory chemistry are converging to redefine competitive differentiation in tubular production. Coating systems, metallurgical specifications, and procurement interfaces are all undergoing simultaneous transformation.
Advanced epoxy coating formulations with enhanced adhesion and cathodic disbondment resistance are integrating into sour-service pipeline specifications. Oil and gas majors are specifying these systems for subsea and marshland installations where conventional galvanizing fails. This integration is compressing the viable supplier base to producers with in-house coating lines and qualified applicator networks.
REACH Annex XIV substance restrictions are eliminating chromate-based pretreatment chemistry from European tube coating operations. Producers are migrating to silane and zirconium-based conversion coatings that meet corrosion performance benchmarks without restricted hexavalent chromium. Seamless oilfield tubular exports to Europe face the steepest compliance burden, driving backward integration into captive coating capacity.
Buyer concentration among national oil companies and integrated energy majors is compressing procurement cycles and unbundling after-sales technical support. Long-term framework agreements with embedded volume commitments are displacing spot purchasing for premium seamless categories. This pattern is most visible in Middle Eastern and North American upstream capital programs where project finance requirements favor supplier stability over price optimization.
Steel Tubes Market Segmentation
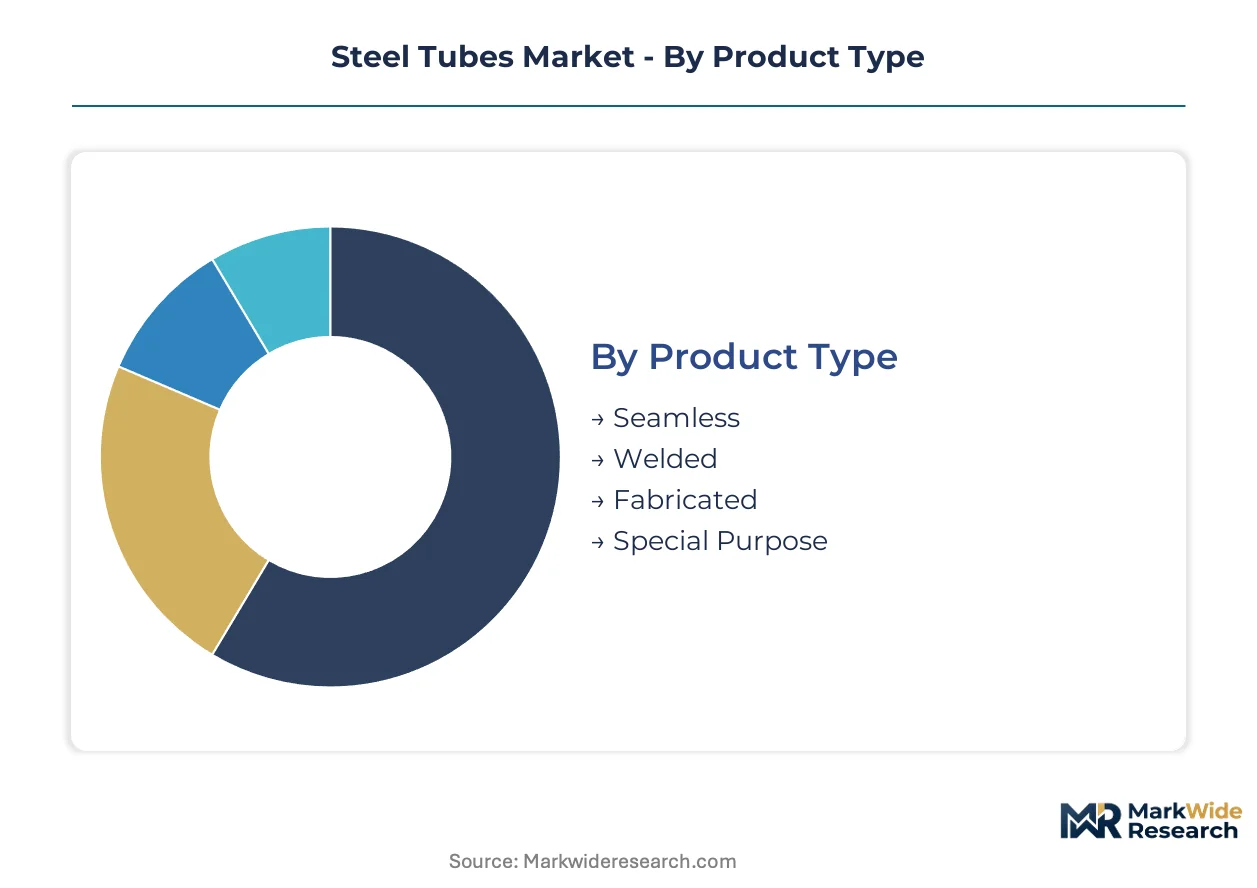
Steel tube procurement patterns diverge sharply across product architecture and end-use stress requirements. Specification-grade seamless tubulars command fundamentally different sourcing logic than commodity welded sections for structural fabrication.
Product Type:
Buyers differentiate primarily by pressure containment risk tolerance and weld integrity requirements rather than unit economics alone.
- Seamless:Extruded from solid billets without longitudinal welds, these tubes withstand burst pressures exceeding welded alternatives by 20-30% in sour-service oilfield environments. Demand concentrates in Permian Basin and North Sea upstream projects where API 5CT specification compliance is non-negotiable for casing and tubing strings.
- Welded:Formed from coiled strip through electric resistance welding or submerged arc processes, offering dimensional flexibility at diameters below 24 inches. India's water distribution infrastructure buildout under BIS ISI certification mandates is absorbing welded volumes for transmission mains and structural piling.
- Fabricated:Value-added processing including bending, flanging, and end-finishing for pre-engineered structural assemblies.
- Special Purpose:Alloy-engineered grades for cryogenic, high-temperature, or hydrogen embrittlement-resistant specifications.
Volume sits with welded tubes; growth tilts toward seamless for premium energy infrastructure.
End User:
Application-specific certification burdens and performance warranties reshape supplier qualification pathways across sectors.
- Construction:Structural hollow sections for building frames and infrastructure dominate tonnage, with Indian public works procurement requiring BIS ISI marking compliance. Fabricators prioritize yield strength consistency and dimensional tolerance for automated welding lines.
- Oil & Gas:Sour-service seamless specifications for hydrogen sulfide-bearing formations command the steepest technical barriers. Tenaris and Vallourec anchor supply relationships through mill-direct framework agreements with national oil companies.
- Automotive:Chassis and powertrain applications demand high-strength low-alloy grades with tight wall thickness control for weight reduction targets.
- Manufacturing:Mechanical tubing for machinery frames, conveyor systems, and material handling equipment.
Construction absorbs the heaviest tonnage; oil and gas generates the steepest margin expansion.
Diameter:
Manufacturing process economics and transportation constraints create distinct competitive arenas across size ranges.
- Large Diameter:Above 16 inches nominal, typically produced through longitudinal submerged arc welding for oil and gas trunk pipelines. Transcontinental projects in North America and Central Asia specify these dimensions for compressor station efficiency.
- Medium Diameter:4-16 inch range capturing water distribution networks and process piping, where spiral-weld and ERW processes compete on lead time and corrosion coating integration.
- Small Diameter:Below 4 inches for instrumentation, heat exchangers, and automotive fluid lines.
- Extra Large Diameter:Above 36 inches for hydroelectric penstocks and submarine outfalls requiring specialized plate rolling and girth welding.
Medium diameters anchor current production volumes; large diameters face supply constraints from plate mill capacity allocation.
Coating Type:
Regulatory chemistry restrictions and field corrosion severity are elevating technical specification complexity faster than cost optimization.
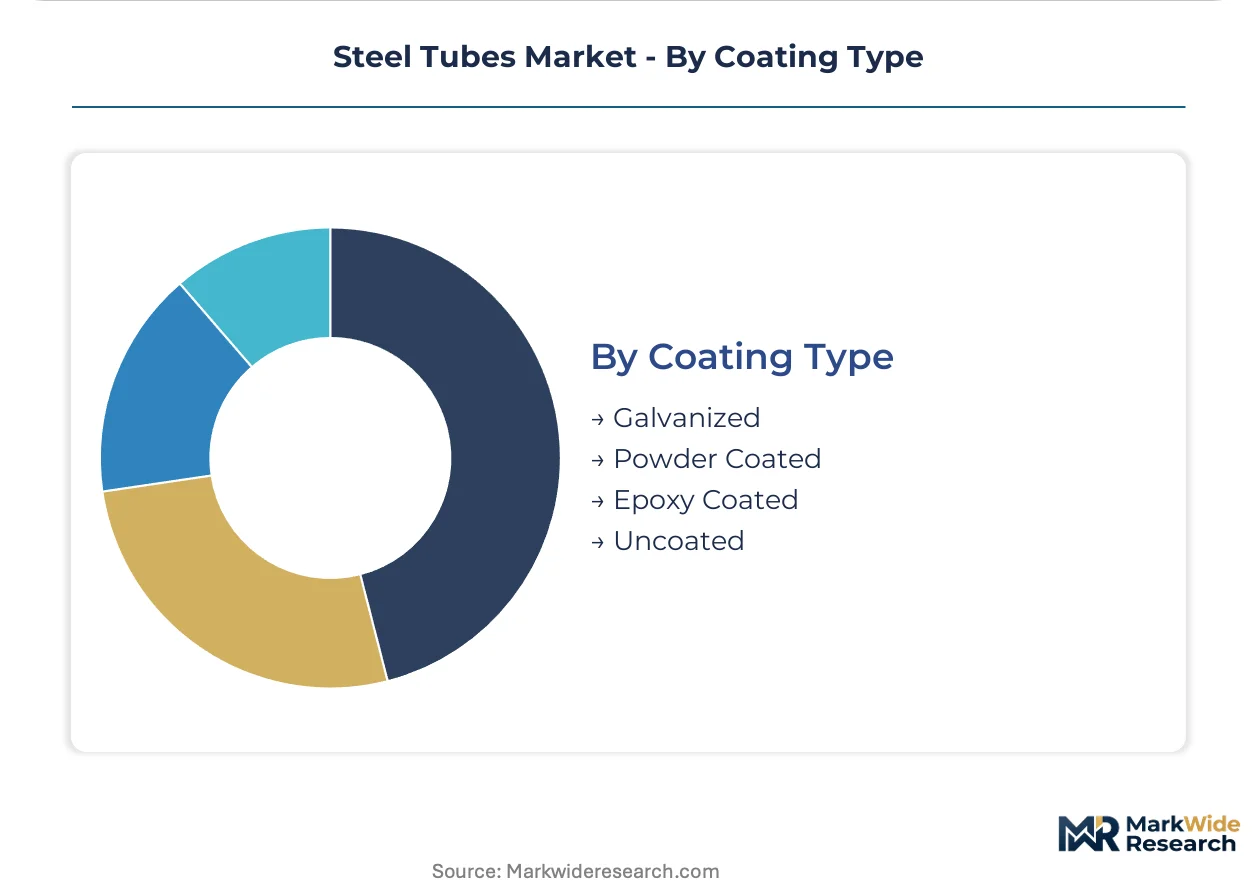
- Epoxy Coated:Fusion-bonded and liquid epoxy systems specified for subsea pipelines and corrosive soil installations where cathodic disbondment resistance is critical. REACH Annex XIV substance restrictions are forcing chromate-free pretreatment migration to silane-based conversion coatings.
- Galvanized:Zinc coating retains volume leadership in outdoor structural applications, though EPA volatile organic compound limits on post-galvanizing chromate quenching are tightening compliance costs.
- Powder Coated:Thermoset polyester and epoxy-polyester hybrids for architectural and manufactured product finishes.
- Uncoated:Bare carbon steel for indoor manufacturing and temporary construction applications with controlled corrosion exposure.
Galvanized coatings maintain installed base dominance; epoxy systems are climbing fastest on pipeline specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Petroleum, Chemicals and Petrochemicals Investment Regions and China's coastal special economic zones concentrate seamless tube capacity for export-oriented energy infrastructure. These designated zones offer tax holidays and duty exemptions that attract integrated steel producers.
United States
Permian Basin upstream operators drive premium seamless tubular consumption for sour-service drilling programs. EPA volatile organic compound limits on coating operations compel producers toward water-based formulation systems. Houston-Gulf Coast industrial corridors host the densest concentration of oilfield tubular stocking and finishing facilities.
Germany
Automotive chassis and powertrain applications absorb high-strength low-alloy welded tubes for lightweighting targets. REACH Annex XIV substance restrictions eliminate chromate-based pretreatment chemistry from coating operations. Ruhr industrial region maintains specialized seamless rolling capacity serving European pressure equipment manufacturers.
China
Dual carbon goals enforced by MEE tighten energy intensity benchmarks for seamless tube rolling mills. Coastal province export zones face constrained availability as domestic infrastructure absorption strengthens. Yangtze River Delta clusters concentrate the largest integrated iron ore-to-tube production complexes.
India
Water distribution networks and structural piling under BIS-mandated ISI certification absorb welded tube volumes from public works expansion. PLI scheme incentives for specialty steel production elevate domestic seamless capacity investments. Gujarat and Maharashtra industrial corridors anchor the fastest-growing structural tubular fabrication clusters.
Saudi Arabia
National oil company framework agreements concentrate premium seamless procurement for high-pressure sour-service fields. SFDA and SASO quality conformance requirements create technical barriers for uncertified imports. Eastern Province industrial cities host the largest Middle Eastern tubular stocking and threading facilities.
Steel Tubes Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across distinct technology and specification tiers. The market exhibits moderate consolidation at the premium seamless segment while structural welded categories fragment across regional fabricators. Three archetypes dominate: integrated mining-to-tube conglomerates with captive raw material control, electric arc furnace specialists with scrap-based flexibility, and regional welded tube fabricators serving construction procurement channels. Capacity expansion and backward integration into coating chemistry represent the dominant competitive moves.
Among North American electric arc furnace operators, Nucor Corporation exemplifies scrap-based flexibility in structural and energy tubular supply. European integrated conglomerates anchor premium positioning, with ArcelorMittal S.A. representing the mining-to-tube archetype across multiple continents. Latin American seamless specialists occupy the premium oilfield tier, where Tenaris S.A. sits within the sour-service specification leadership category.
| Leading Market Players |
|---|
| Nucor Corporation |
| Borusan Mannesmann Boru Sanayi ve Ticaret A.S. |
| ArcelorMittal S.A. |
| Tata Steel Limited |
| United States Steel Corporation |
| Nippon Steel Corporation |
| China Baowu Steel Group Corp., Ltd. |
| Tenaris S.A. |
| JFE Steel Corporation |
| Others |
Cost & Logistics Intelligence
Electric arc furnace adoption among North American producers is compressing scrap-input cost volatility while fragmenting pricing power across regional mill networks. This metallurgical transition simultaneously elevates margin predictability for EAF operators and intensifies spot-price competition with integrated Chinese exporters.
Pricing Analysis
Lead-time premiums dominate transaction economics, with spot inventory commanding discounts against mill-direct orders with 12-16 week delivery windows. Three-tier pricing structure across API-certified seamless, BIS-marked structural welded, and commodity-grade merchant bars separates premium sour-service tubulars from standard construction sections. Cost compression in commodity welded grades is intensifying because Indian and Turkish exporters are absorbing freight differentials to defend volume share. National oil companies exhibit the lowest price sensitivity due to embedded technical service requirements, while Indian public works contractors face rigid budget ceilings that amplify spot-market bargaining power.
Supply Chain Analysis
Direct-to-fabricator digital platforms are compressing traditional distributor layers in standardized structural categories, though oilfield tubulars retain multi-tier stocking networks for technical support. Geographic supply concentration centers on China, India, and the United States for distinct specification tiers—Chinese seamless rolling for export energy infrastructure, Indian welded capacity for domestic water distribution, and US EAF production for regional construction. Raw material flows draw from Australian iron ore, Turkish and US scrap pools, and South Korean hot-rolled coil for welded tube feedstock. Single-source vulnerability runs through Chinese seamless rolling mill concentration under MEE dual carbon enforcement. Distribution runs through mill-direct framework agreements for premium oilfield grades and spot-market merchant channels for structural sections.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The steel tubes sector is navigating a coating-chemistry transition, with REACH-compliant silane-based pretreatments displacing legacy chromate systems and reshaping supplier qualification thresholds.
For Market Incumbents: To counter polymer composite substitution in low-pressure water applications, ArcelorMittal-class integrated producers should deepen backward integration into captive coating capacity for epoxy and powder systems. Tenaris-tier seamless specialists must defend API 5CT certification moats through in-house sour-service testing laboratories that accelerate customer qualification timelines. For New Entrants and Emerging Players: BIS ISI certification mandates in India open a window for domestic welded tube fabricators to capture public works procurement share from uncertified imports. Target medium-diameter water distribution specifications where spiral-weld process entry costs remain accessible, and pursue digital mill-direct platforms to bypass layered distributor margins in standardized structural categories. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty alloy seamless producers with hydrogen embrittlement-resistant patent portfolios. Long-term viability favors targets with demonstrated MEE compliance in China and REACH coating chemistry capabilities in Europe. Monitor carbon border adjustment implementation timelines as the critical inflection signal for low-carbon tubular premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Chemistry | Captive epoxy and powder capacity secures REACH compliance and API specification access for European oilfield exports. |
| Hydrogen Pipeline Alloy Certification | Embrittlement-resistant metallurgical patents create premium positioning ahead of emerging hydrogen transport infrastructure awards. |
| Digital Mill Channel Expansion | Direct-to-fabricator platforms compress distributor margins and capture construction procurement volume through price transparency. |
| Scrap-Based EAF Capacity Addition | Electric arc furnace investments in Texas and Southeast Asia lower carbon intensity for European carbon border adjustment qualification. |
| Multi-Standard Certification Investment | Simultaneous API, ASTM, EN, and BIS compliance documentation enables cross-border project bidding without qualification delays. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this steel tubes analysis. Primary interviews with seamless rolling mill operations directors, oilfield procurement managers at national oil companies, water infrastructure project engineers, and coating chemistry R&D leads combined with secondary validation from World Steel Association production statistics, USITC trade databases, and BIS certification registries. Bottom-up segment sizing across seamless, welded, and fabricated product architectures triangulated against top-down national steel consumption forecasts.
Granularity-level modeling captured diameter ranges, coating type specifications, and end-use industry demand patterns across the projection horizon. The analytical framework derived CAGRs through regression analysis of historical production capacity utilization, trade flow intensity indices, and infrastructure investment commitments. Forecast inputs incorporated MEE dual carbon goal enforcement trajectories, REACH Annex XIV substance restriction phase-in schedules, and PLI scheme incentive disbursement patterns for Indian specialty steel production.
The model assumes a particular technology adoption path; alternative pathways for hydrogen embrittlement-resistant alloy specifications would alter the outlook for premium seamless demand trajectories. Forecasts reflect base-case assumptions regarding carbon border adjustment implementation sequencing and scrap-input cost normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
ESR Tubes Market
Pipes and Tubes
Plastic Pipes and Fittings Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
Metal Pipe Market
Pipes and Tubes
Qatar PVC Pipe Market
Pipes and Tubes
Galvanized Steel Tubes Market
Pipes and Tubes
Industrial Blast Hoses Market
Pipes and Tubes
Stainless Steel Tank Container Market
Pipes and Tubes
HDPE Corrugated Pipe Market
Pipes and Tubes
Cold Drawn Seamless (CDS) Steel Pipes Market
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
GRE Pipes Market
Pipes and Tubes
Global Flexible Pipes Market
Pipes and Tubes
PVDF Pipes Market
Pipes and Tubes
GCC Polyethylene (PE) Pipes Market
Pipes and Tubes
Europe PVC Pipes Market