
 Pipe and Tube Cutters Market | 2026-2036
Pipe and Tube Cutters Market Size, Share, and Industry Trends Forecast 2026-2036
Pipe and Tube Cutters Market Analysis
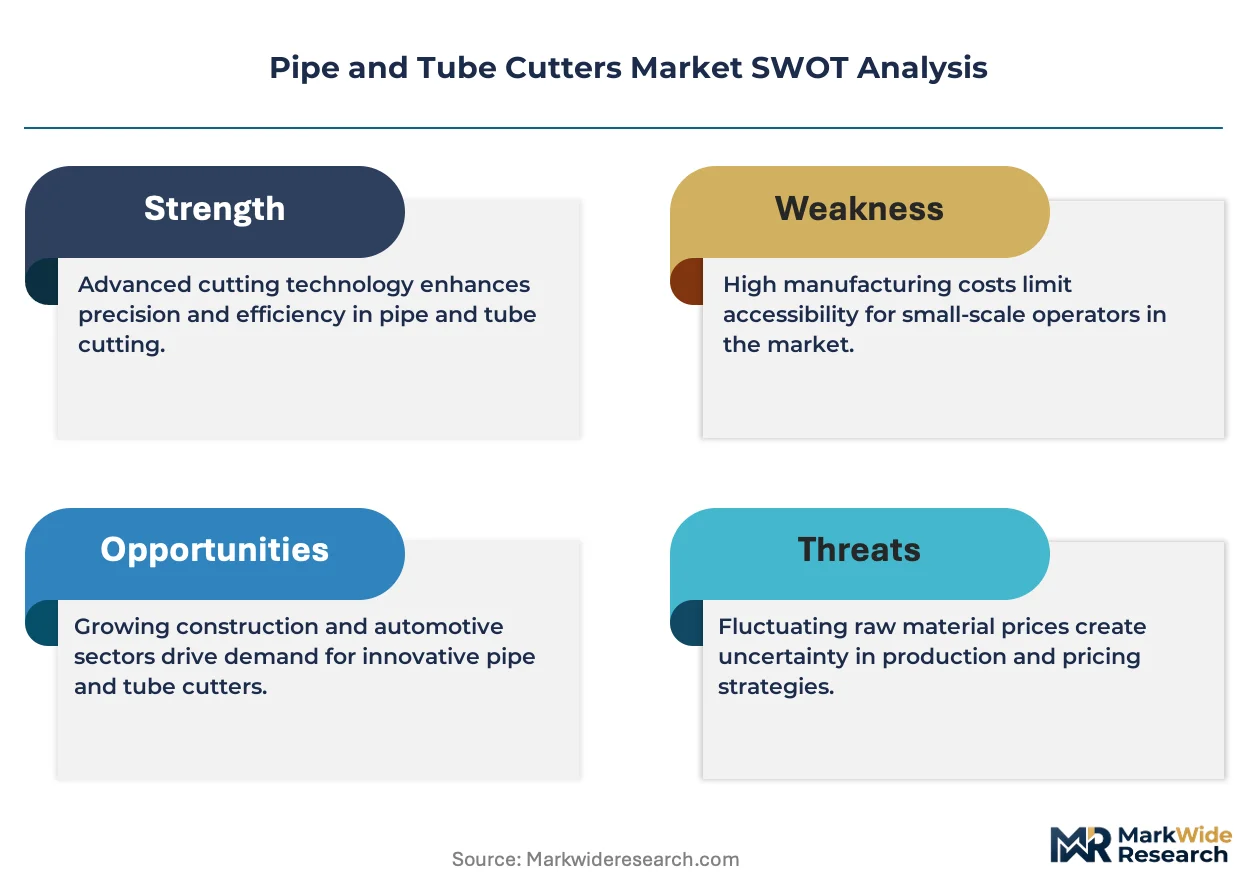
Skilled plumbing and mechanical trade labor shortages across North America and Western Europe is unwinding project timelines and intensifying demand for power-assisted cutting solutions that reduce physical exertion and training requirements. Milwaukee Tool leverages its M18 cordless platform to dominate professional jobsite adoption with battery-integrated pipe cutters. RIDGID sustains brand authority in heavy-duty plumbing infrastructure through specialized copper and soil-pipe cutting systems. Rothenberger competes aggressively in European commercial heating and sanitary installation with precision tube cutting equipment engineered for stainless steel and multi-layer composite piping.
Pipe and tube cutters are precision hand and power tools engineered to sever cylindrical metal or plastic conduit with clean, square, or beveled edges, typically achieving wall-thickness capacity from 1 mm to 10 mm and diameter ranges spanning 3 mm to 300 mm depending on cutter class and drive mechanism. Their primary industrial purpose centers on preparing pipe ends for joining via threading, welding, or press-fitting in construction, manufacturing, and utility maintenance workflows. Manual cutters retain volume leadership in emerging markets and residential plumbing where capital constraints and intermittent use patterns predominate, while power cutters command premium positioning in commercial construction and industrial maintenance applications where throughput speed and repeatability justify higher equipment expenditure. Material-type segmentation shows stainless steel pipe cutting generating the most demanding tool specifications due to work-hardening behavior, creating margin concentration for manufacturers offering carbide-reinforced cutting wheels and reinforced frames.
OSHA workplace ergonomics guidelines and the EPA's lead-safe renovation rules shape product design requirements by mandating reduced-vibration power tools and dust-containment accessories in residential plumbing retrofit work. CE marking under the EU Machinery Directive and REACH substance restrictions constrain alloy compositions in cutting wheel formulations and lubricant systems sold into European channels. Stakeholders must monitor evolving cordless battery interoperability standards and regional trade compliance shifts that could alter component sourcing economics and aftermarket service obligations.
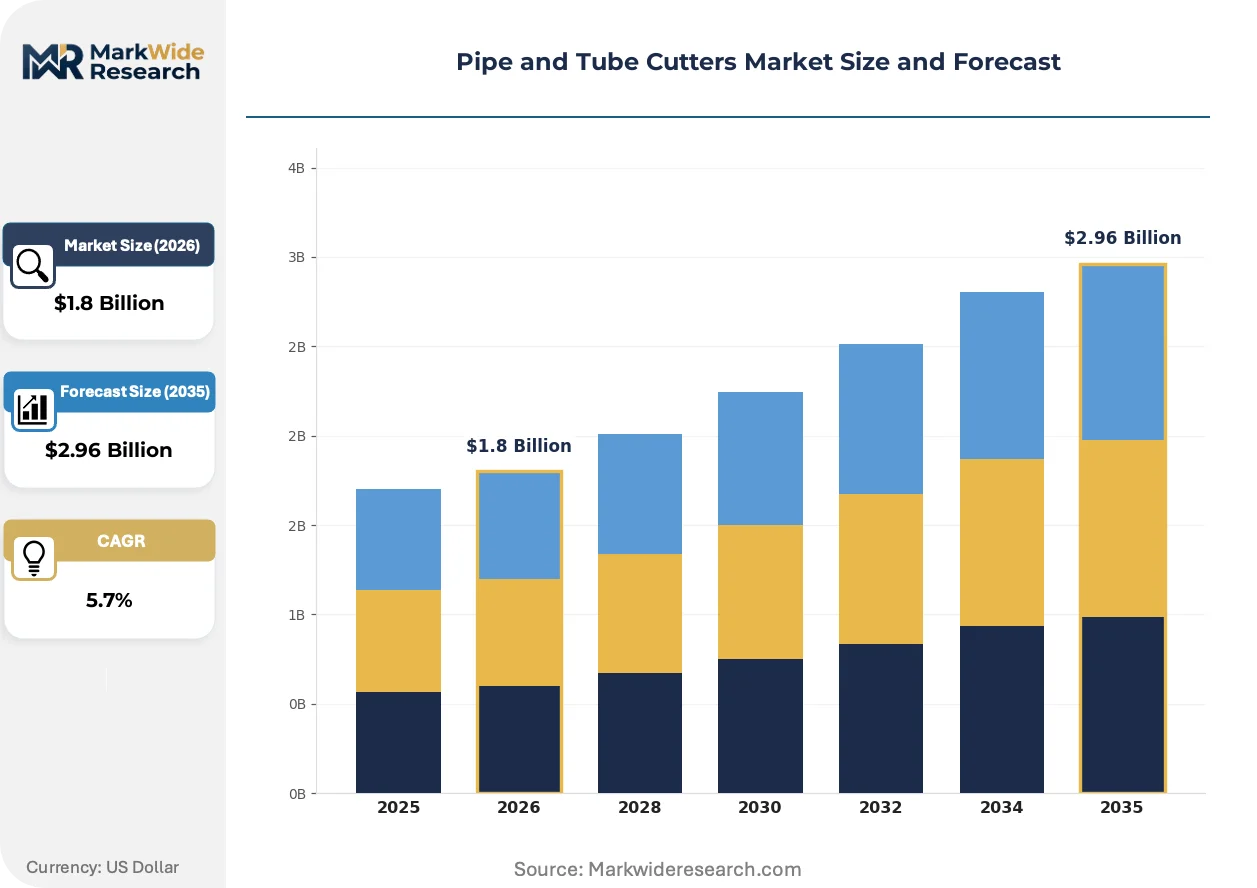
Market Dynamics
Skilled trade labor shortages across North America and Western Europe are accelerating preference for power-assisted pipe cutting tools that compress training curves and reduce physical exertion on commercial jobsites.
Growth Catalysts
- Battery platform consolidation:Cordless power tool ecosystems from established manufacturers are reducing battery interchangeability friction for mechanical contractors upgrading from manual cutting equipment.
- EPA lead-safe renovation rules:Dust containment mandates in residential plumbing retrofit work are driving specification of integrated extraction systems on power cutters used in older housing stock.
- PEX pipe proliferation:Cross-linked polyethylene tubing expansion in North American residential construction is sustaining demand for specialized cutting tools engineered for flexible polymer materials.
Market Restraints
- Lithium-ion cell cost volatility:Battery pack input costs for cordless cutters fluctuate with cathode material pricing and regional mining supply constraints.
- Carbide cutting wheel supply concentration:Sintered tungsten carbide production for heavy-duty pipe cutting wheels clusters in limited East Asian manufacturing basins.
- Manual tool substitution persistence:Emerging market price sensitivity and intermittent residential use patterns sustain competitive pressure from low-cost hand-operated cutters.
Strategic Opportunities
- India infrastructure build-out:Central government urban water and sanitation programs are expanding addressable demand for portable pipe cutting equipment in municipal contractor fleets.
- Press-fit system compatibility:Mechanical joining methods displacing threaded connections in European commercial heating systems require precision square-cut pipe ends that automated cutters deliver.
- Rental channel expansion:Professional tool rental networks are capturing contractors seeking to avoid capital outlay for specialized stainless steel cutting equipment on intermittent projects.
Industry Challenges
- Certified technician scarcity:Pipeline welding and mechanical trade apprenticeship programs are failing to replenish retiring skilled labor pools in Germany and the United States.
- Multi-material cutting complexity:Composite and multi-layer piping systems in European sanitary installations demand cutter wheel formulations that balance wear resistance across divergent material hardness profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipe and Tube Cutters Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Cutters, Power Cutters, Pipe Reamers, Tubing Cutters Material Type: Stainless Steel, Carbon Steel, Alloy Steel, Plastic End User: Construction, Plumbing, Automotive, Manufacturing Application: Industrial Applications, DIY Projects, Maintenance, Repair |
| Companies Covered | RIDGID, Milwaukee Tool, Rothenberger, Apex Tool Group, Irwin, Crescent, KNIPEX, Bosch, Wheeler-Rex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipe and Tube Cutters Market Emerging Trajectories
Electrification of handheld cutting tools is redrawing competitive boundaries between power tool platforms and traditional plumbing specialty equipment, with battery interoperability emerging as a decisive purchase criterion for fleet-standardizing contractors.
Brushless motor technology paired with lithium-ion power packs is bifurcating the professional pipe cutter category into tethered high-torque units for industrial maintenance and compact cordless variants for service plumbing. Commercial mechanical contractors in the United States are adopting M18-compatible cutters at accelerating rates. This technology compression is eroding price premiums historically commanded by pneumatic and hydraulic cutting systems in mid-capacity applications.
REACH substance restrictions under EU chemical policy are constraining cobalt content in cutting wheel binders and lubricant formulations sold into European distribution channels. Manufacturers are reformulating sintered carbide matrices and synthetic cutting fluids to maintain performance while achieving compliance. Stainless steel processing applications in German commercial heating installation are most affected, driving accelerated qualification cycles for alternative alloy compositions.
Mechanical contractors are consolidating supplier relationships around full-service distributors offering tool financing, maintenance, and training bundling rather than transactional equipment procurement. Independent plumbing wholesalers in North America are responding with expanded rental fleets and field service capabilities. This channel transformation is most advanced in metropolitan construction corridors of Texas and Florida where large-scale multifamily development concentrates demand.
Pipe and Tube Cutters Market Segmentation
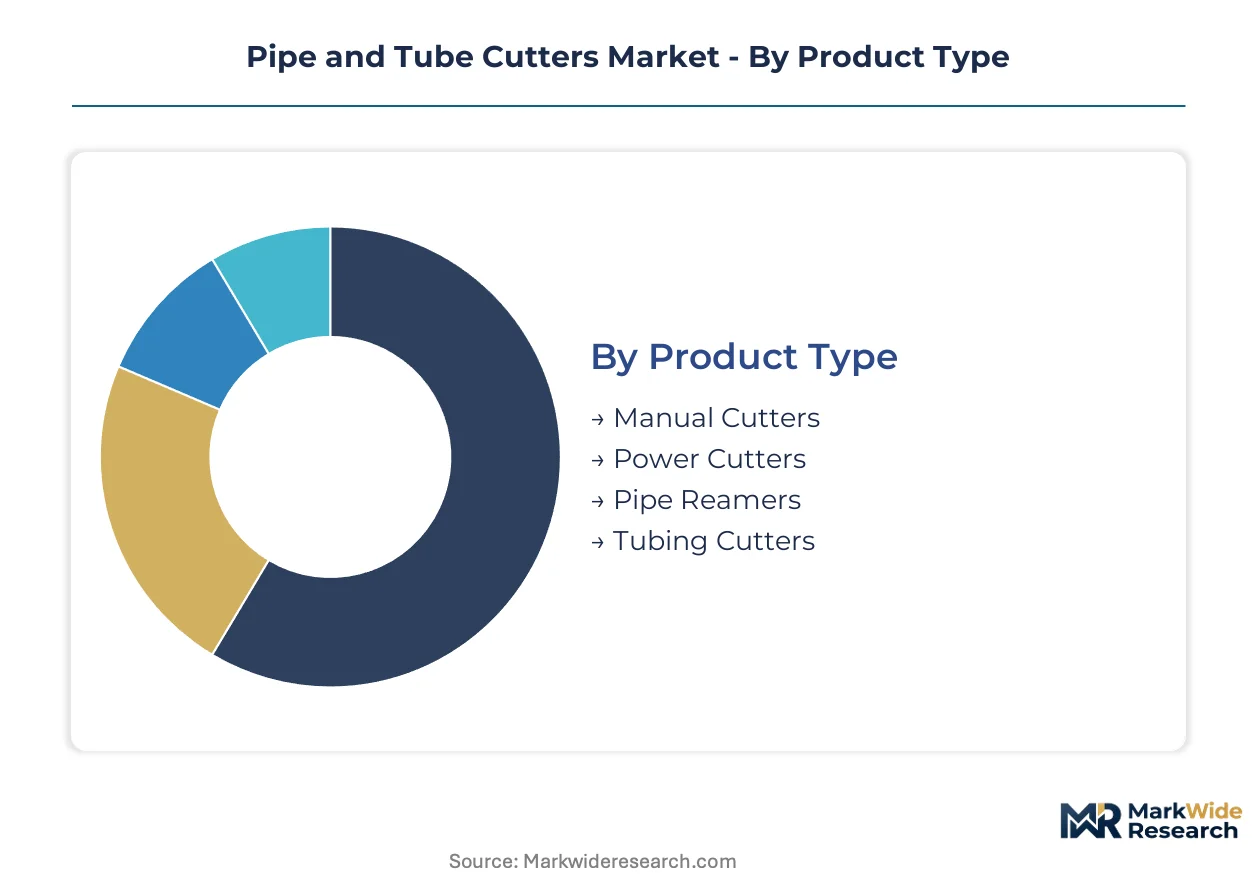
Segmentation in pipe and tube cutters reflects divergent tooling requirements across material hardness, jobsite power availability, and operator skill levels. Manufacturers configure product portfolios around these axes to capture margin concentration in professional-grade power equipment while defending volume positions in manual hand tools.
Product Type:
Power cutters command the widest margin spreads due to battery platform premiums and brushless motor technology integration, while manual cutters defend high-volume positions in price-sensitive procurement channels.
- Manual Cutters:Hand-operated wheel-and-frame mechanisms using hardened steel or carbide cutting wheels achieve clean severing of copper, brass, and plastic tubing up to medium diameters. Demand concentrates in residential plumbing retrofit work across the United States, where intermittent use patterns and capital constraints favor low-acquisition-cost solutions over power tool investment.
- Power Cutters:Cordless lithium-ion and corded electric units deliver rotational cutting force through planetary gear systems, achieving throughput speeds impossible with manual operation. Procurement from German commercial mechanical contractors is accelerating as M18-compatible platforms reduce battery interchangeability friction across mixed tool fleets.
- Pipe Reamers:Deburring and chamfering attachments clean interior and exterior pipe edges post-cutting to ensure proper seal integrity in press-fit and threaded connections.
- Tubing Cutters:Compact wheel-style tools engineered for thin-wall tubing in HVAC refrigeration lines and instrumentation applications, prioritizing portability over heavy-duty capacity.
Manual cutters hold installed capacity in residential maintenance channels. Power cutters are rotating up the share rankings in commercial construction procurement.
Material Type:
Material hardness directly determines cutting wheel specification, frame reinforcement requirements, and replacement part economics, with stainless steel applications generating the most demanding tool performance thresholds.
- Stainless Steel:Austenitic and ferritic grades exhibit work-hardening behavior under cutting stress, demanding carbide-reinforced wheels and reinforced cutter frames to prevent blade deflection. German commercial heating installation contractors specify these tools most intensively, driven by press-fit system proliferation requiring precision square-cut ends.
- Plastic:PEX, PVC, and CPVC tubing sever cleanly with standard steel wheels, though specialized cutters prevent compression deformation in flexible polymer materials. North American residential construction is absorbing volume fastest as cross-linked polyethylene displaces copper in potable water distribution.
- Carbon Steel:Standard plumbing and structural pipe applications with moderate wall thickness, served by mid-range manual and power cutting equipment.
- Alloy Steel:High-strength piping in industrial process applications requiring enhanced cutting wheel durability and elevated torque specifications.
Stainless steel tooling commands premium positioning. Plastic-focused equipment is expanding most quickly in new residential construction segments.
End User:
End-user segmentation tracks capital deployment patterns, with construction and plumbing contractors representing concentrated demand for fleet-standardized power platforms while automotive and manufacturing buyers prioritize precision tolerances.
- Construction:General building contractors require versatile cutting capacity across mixed material jobsites, driving procurement of adjustable manual cutters and mid-range cordless power units. Texas and Florida metropolitan corridors concentrate demand through large-scale multifamily development activity.
- Plumbing:Specialized mechanical contractors demand dedicated copper, soil-pipe, and PEX cutting systems with integrated dust extraction for EPA lead-safe renovation compliance. United States plumbing wholesalers are responding with expanded rental fleets and field service bundling.
- Automotive:OEM and aftermarket exhaust system fabrication requires compact tubing cutters for tight-access repair environments.
- Manufacturing:Process piping fabrication shops specify high-torque stationary and portable power cutters for repetitive production cutting with minimal burr generation.
Construction maintains the broadest tool fleet deployments. Plumbing is gaining share fastest through professional power platform consolidation.
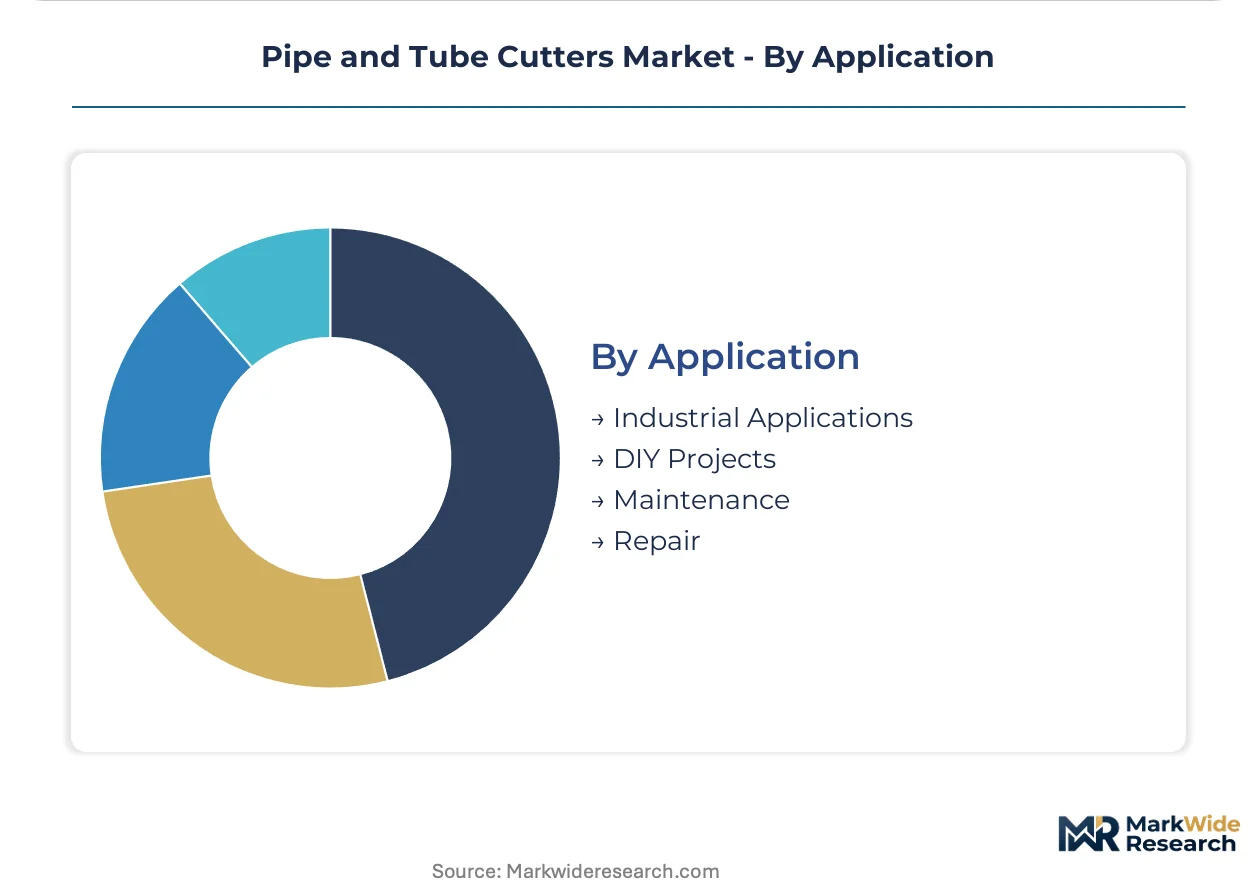
Application:
Application context determines duty cycle intensity and specification stringency, with industrial maintenance demanding maximum durability and DIY channels prioritizing accessibility over performance extremes.
- Industrial Applications:Continuous production environments and scheduled maintenance turnarounds require cutting tools with validated MTBF ratings and rapid cutting wheel replacement protocols. German chemical processing and power generation facilities specify these most rigorously under EU Machinery Directive compliance frameworks.
- Maintenance:Facility management and municipal infrastructure crews need portable, multi-material capable equipment for unplanned repair response. India central government urban water and sanitation programs are expanding addressable demand for portable pipe cutting equipment in contractor fleets.
- DIY Projects:Homeowner and light commercial users purchase entry-level manual cutters through retail hardware channels for intermittent residential repair work.
- Repair:Emergency service plumbing and mechanical contractors require compact cordless solutions with immediate availability from distributor inventory.
Industrial applications anchor premium equipment specifications. Maintenance is climbing the fastest as infrastructure retrofit activity intensifies across aging municipal systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums for professional-grade battery-powered cutters in Germany and the United States sit roughly 40% above comparable equipment in India and Brazil, reflecting divergent labor cost structures and certification requirements. This asymmetry shapes manufacturer portfolio prioritization and distributor margin structures across geographies.
United States
Residential construction in Texas and Florida metropolitan corridors drives concentrated demand for PEX-compatible cutting systems and lead-safe renovation equipment. EPA dust containment mandates under the Lead Renovation, Repair and Painting Rule shape tool specification requirements for contractors working pre-1978 housing stock. Plumbing wholesalers in Houston and Miami are expanding rental fleets to capture fleet-standardizing mechanical contractors.
Germany
Commercial heating installation contractors specify precision square-cut equipment for press-fit system proliferation in Bavaria and North Rhine-Westphalia. CE marking under the EU Machinery Directive and REACH substance restrictions constrain cutting wheel alloy formulations sold through European distribution. Stuttgart and Düsseldorf industrial clusters anchor demand for stainless steel processing tools with carbide-reinforced specifications.
China
Domestic infrastructure build-out and export manufacturing sustain dual demand tracks for manual and power cutting equipment. GB standards and MIIT industrial policy guide domestic product certification and battery safety requirements. Yangtze River Delta fabrication centers in Shanghai and Suzhou concentrate production of carbide cutting wheels for global supply.
India
Central government urban water and sanitation programs are expanding municipal contractor demand for portable pipe cutting equipment. BIS certification requirements and PLI scheme incentives shape domestic manufacturing investment and import substitution patterns. Maharashtra and Gujarat industrial corridors in Mumbai and Ahmedabad concentrate infrastructure equipment procurement activity.
Japan
Precision manufacturing and automotive exhaust system fabrication sustain demand for compact tubing cutters with tight-access capabilities. METI industrial standards and JIS certification frameworks govern tool performance specifications for domestic and export markets. Nagoya and Osaka industrial clusters anchor specialized equipment requirements for process piping applications.
Pipe and Tube Cutters Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with battery platform specialists commanding premium positioning while manual tool fabricators defend volume positions in price-sensitive channels. The market structure bifurcates between consolidated power tool platforms with interoperable battery ecosystems and fragmented specialty equipment providers serving material-specific applications. Three archetypes dominate: cordless platform owners, precision cutting specialists, and regional manual tool manufacturers. Competitive moves center on battery interoperability expansion and rental channel partnerships that reduce contractor capital barriers.
Among North American platform owners, Milwaukee Tool and RIDGID exemplify the cordless consolidation archetype, while Rothenberger occupies a position within the European precision specialist tier. Milwaukee Tool represents the battery ecosystem strategy through M18 platform dominance, RIDGID anchors heavy-duty plumbing infrastructure positioning, and Rothenberger exemplifies stainless steel and multi-layer composite specialization for commercial heating applications.
| Leading Market Players |
|---|
| RIDGID |
| Milwaukee Tool |
| Rothenberger |
| Apex Tool Group |
| Irwin |
| Crescent |
| KNIPEX |
| Bosch |
| Wheeler-Rex |
| Others |
Supply Flow & Price Mechanics
Lithium-ion battery packs replacing nickel-cadmium power sources in cordless pipe cutters are simultaneously shifting procurement geography toward East Asian cell manufacturing and compressing power tool pricing premiums through platform standardization. This substitution dynamic redistributes margin capture from cutting wheel specialists to battery ecosystem owners while exposing buyers to cathode material cost volatility.
Pricing Analysis
The customization-premium spread between configured-to-order stainless steel cutters and standard manual units spans approximately forty percent in German and United States procurement channels. Three-tier pricing structure across premium, standard, and economy levels tracks battery platform compatibility and carbide wheel specification grades. Cost compression in cordless power tiers is intensifying because Milwaukee Tool and RIDGID are absorbing battery R&D across broader tool portfolios. Residential plumbing contractors exhibit highest price sensitivity, while German commercial heating installers demonstrate lowest sensitivity due to press-fit system precision requirements.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell production for cordless cutter battery packs, while Germany and Japan concentrate precision cutting wheel fabrication. Sintered tungsten carbide feedstock draws from limited East Asian powder metallurgy basins, creating single-source vulnerability for heavy-duty wheel specifications. Distribution runs through full-service industrial distributors with tool financing bundling rather than transactional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pipe and tube cutters market sits in early-cycle recovery phase, justified by residential construction permit acceleration in Texas and Florida metropolitan corridors driving PEX installation demand.
For Market Incumbents: Fortify battery platform interoperability advantages through expanded M18-compatible SKU coverage in stainless steel cutting applications. Deepen backward integration into carbide powder sourcing to mitigate East Asian supply concentration risks. Capture rental channel partnerships in Houston and Miami to lock out emerging competitors seeking fleet-standardization contracts.
For New Entrants and Emerging Players: Aftermarket cutting wheel replacement services represent an under-served layer where incumbent power tool manufacturers under-invest. Target municipal contractor fleets in Maharashtra and Gujarat infrastructure programs with portable manual cutter bundles. Pursue distributor co-development agreements with independent plumbing wholesalers seeking private-label power tool expansion.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision cutting specialists with stainless steel application expertise. Long-term viability hinges on press-fit system proliferation in European commercial heating and EPA lead-safe renovation compliance in United States residential retrofit. Watch battery platform switching costs as the inflection signal determining whether cordless ecosystem owners or material-specialist independents capture margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Expansion | M18-compatible cutter proliferation locks mechanical contractors into Milwaukee Tool ecosystem loyalty. |
| Carbide Wheel Backward Integration | In-house tungsten carbide sourcing insulates manufacturers from East Asian powder supply volatility. |
| Rental Channel Partnership | Plumbing wholesaler fleet financing reduces contractor capital barriers for stainless steel equipment. |
| Press-Fit System Certification | CE-marked precision cutters capture German commercial heating specification requirements. |
| Regional Manufacturing Footprint | India PLI scheme incentives enable import substitution for municipal infrastructure procurement. |
Methodological Framework
A standing panel of mechanical contracting fleet managers, plumbing wholesaler procurement directors, and industrial distributor aftermarket service heads provided ongoing calibration throughout the study period. Primary field engagement combined structured interviews with secondary validation against customs trade records, SEC tool manufacturer filings, and EPA enforcement activity databases. Bottom-up segment sizing triangulated against top-down construction spending flow analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, material hardness specification, end-user capital deployment pattern, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves applied to disclosed manufacturer shipment data and construction permit leading indicators.
Forecasts assume regulatory continuity in EPA lead-safe renovation enforcement and EU REACH substance restriction regimes; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in residential construction permit trajectories and battery platform adoption inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Saw Pipes Market
Pipes and Tubes
Hot Dip Galvanized Steel Pipe Market
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
France PVC Pipes Market
Pipes and Tubes
Spain PVC Pipes Market
Pipes and Tubes
Global Titanium Tube Market
Pipes and Tubes
Kuwait PVC Pipes Market
Pipes and Tubes
Global PEX (Cross-Linked Polyethylene) Market
Pipes and Tubes
Plastic Pipe Market
Pipes and Tubes
Industrial Draft Tube Crystallizer Market
Pipes and Tubes
Europe PVC Pipes Market
Pipes and Tubes
Global Cured-In-Place Pipe Market
Pipes and Tubes
North America Hydraulic Fluid Connectors Market
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
PVC Pipes and Fittings Market
Pipes and Tubes
Pipe Market