
 Global Industrial Dust Collector Market | 2026-2036
Global Industrial Dust Collector Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Dust Collector Market Intelligence
The integration of IoT sensors for real-time monitoring and predictive maintenance analytics is reconfiguring the design of industrial dust collection systems. This shift allows for optimized filter life and energy consumption, moving beyond simple particulate capture. Donaldson Company, Inc. leverages its extensive portfolio in filtration media to lead in high-efficiency cartridge systems. Meanwhile, Nederman Holding AB specializes in comprehensive air quality solutions, often for complex applications like metal fabrication.
An industrial dust collector is an air pollution control device designed to capture and remove particulate matter from process air streams. These systems operate by drawing contaminated air through a filtration medium, achieving specific efficiencies often rated in cubic feet per minute (CFM) to ensure compliance and worker safety. Baghouse collectors remain a mature and dominant product type, especially in heavy industries like cement manufacturing. In contrast, cartridge collectors are gaining share, driven by their compact size and suitability for applications like food processing.
Stringent occupational health and environmental regulations are primary market accelerators. Mandates from bodies like the US Occupational Safety and Health Administration (OSHA) on combustible dust and Europe's ECHA on hazardous substances directly influence equipment specifications. Similarly, China's MEE enforces strict emission limits for industrial facilities, compelling investment in advanced filtration. The key decision for operators now centers on balancing upfront capital investment against the long-term operational savings from energy-efficient, smart systems.
Market Dynamics
The industrial dust collector market is defined by a structural tension between regulatory compliance and operational efficiency. Mandates for cleaner air from agencies like the US EPA and China's MEE are now intersecting with IoT-driven analytics, shifting the value proposition from simple particulate capture to intelligent air quality management.
Growth Catalysts
- Combustible Dust Regulations:Stricter enforcement of standards, such as those from the US Occupational Safety and Health Administration (OSHA) on combustible dust, compels investment in certified collection systems within industries like wood processing and grain handling.
- Heavy Industry Expansion:Demand from cement and metal smelting operations, particularly linked to infrastructure projects in India and Southeast Asia, requires large-scale baghouse and electrostatic precipitator installations for process control and emissions compliance.
- Predictive Maintenance Adoption:The integration of sensors to monitor filter pressure, airflow, and emissions provides a clear return on investment through optimized filter life and reduced energy consumption, pulling demand for smart-enabled systems.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for advanced filtration systems, particularly for high-temperature or hazardous applications, acts as a barrier for small and medium-sized enterprises (SMEs).
- Retrofitting Complexity:Integrating modern, often larger, dust collection systems into existing plant layouts with limited space presents significant engineering and logistical hurdles, increasing total project costs and downtime.
- Filtration Media Cost:Price volatility for specialized materials like PTFE membranes and other high-performance synthetic fabrics, which are essential for efficiency, can impact the total cost of ownership and equipment pricing.
Strategic Opportunities
- Battery Manufacturing:The rapid expansion of gigafactories creates a new, high-value application for specialized dust collection systems designed to safely handle hazardous and reactive materials like lithium, cobalt, and nickel dust.
- Pharmaceutical Processing in Asia:Underpenetrated markets in India and Vietnam for pharmaceutical manufacturing offer significant growth potential for compact, high-efficiency cartridge collectors that meet stringent cleanroom and GMP standards.
- Air-as-a-Service Models:A shift towards subscription-based models, where providers offer guaranteed air quality, remote monitoring, and maintenance for a recurring fee, presents an opportunity to capture long-term revenue streams.
Industry Challenges
- Skilled Technician Scarcity:A growing shortage of technicians who possess dual expertise in both traditional mechanical maintenance and the software analytics required to manage modern IoT-enabled dust collection systems hampers service delivery.
- System Integration with Legacy IT:The operational challenge of integrating data from new smart collectors into older factory-level control systems, such as SCADA and MES platforms, can delay the realization of efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Dust Collector Market |
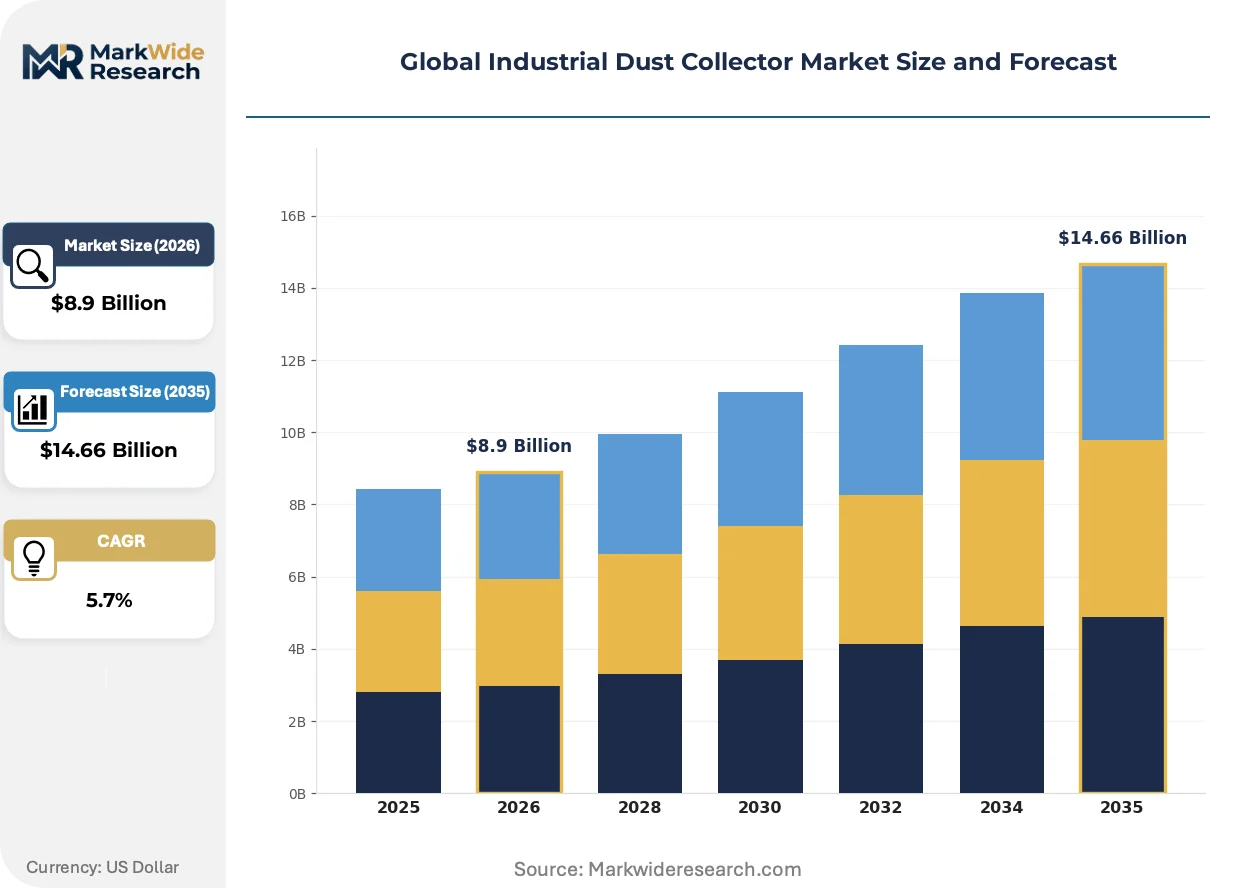
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $14.66 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
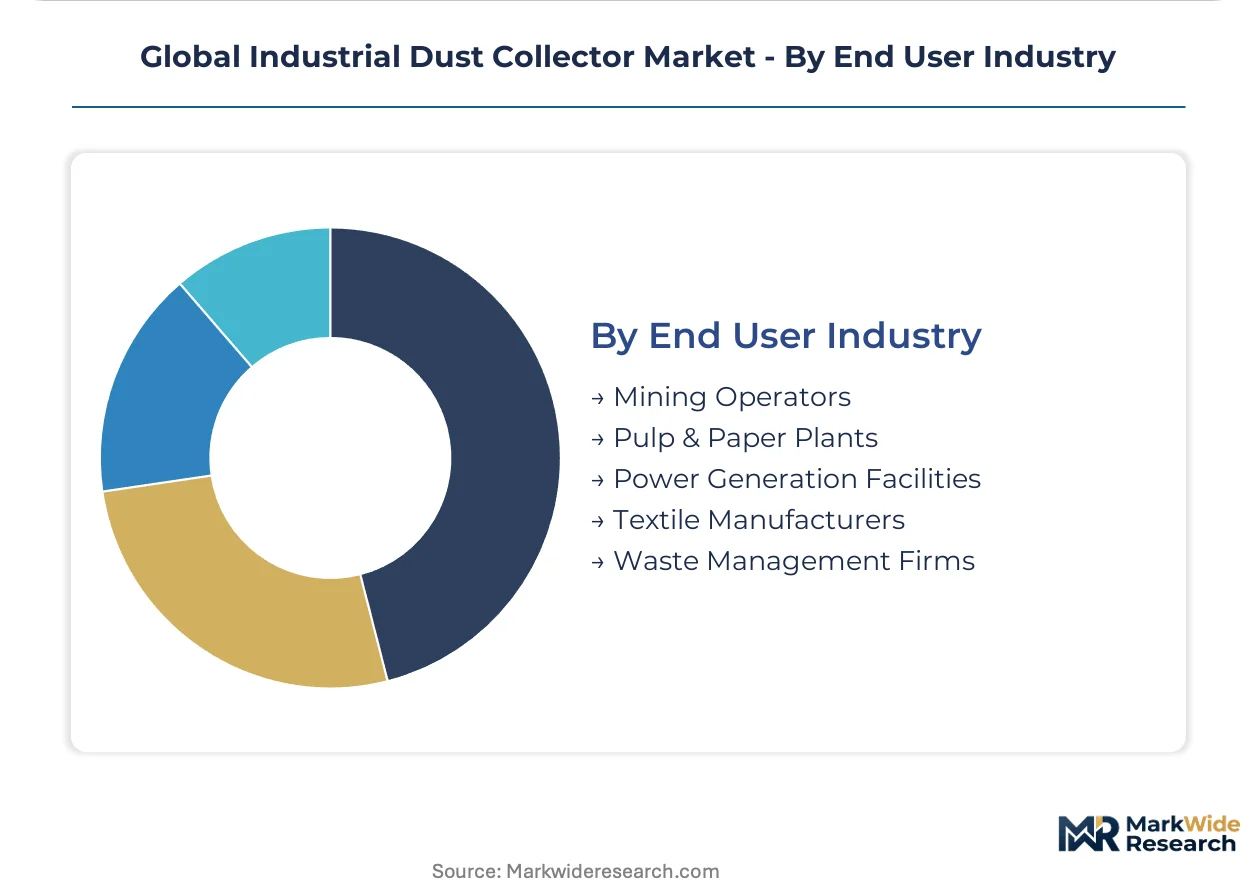
| Segmentation | Product Type: Baghouse, Cartridge Collector, Cyclone, Electrostatic Precipitator, Wet Scrubber Technology: Pulse Jet, Reverse Air, Shaker, Packed Bed, Venturi Scrubber Application: Metal Fabrication, Cement Manufacturing, Food Processing, Chemical Production, Woodworking End User Industry: Mining Operators, Pulp & Paper Plants, Power Generation Facilities, Textile Manufacturers, Waste Management Firms |
| Companies Covered | Parker Hannifin Corporation, Sly Incorporated, Donaldson Company, Inc., Tysum, Munters Group AB, Camfil AB, FLSmidth & Co. A/S, CECO Environmental, Nederman Holding AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Dust Collector Market Strategic Shifts & Innovations
The evolution of industrial dust collection equipment is marked by a clear pivot from being standalone compliance hardware to becoming integrated components of a facility's digital ecosystem. This transformation is driven by advancements in material science, tightening regulatory frameworks, and new customer procurement models.
Nanofiber filtration media provides a surface layer of extremely fine fibers on a substrate, enabling higher particulate capture efficiency at a lower pressure drop. Industries requiring stringent air purity, such as electronics fabrication and pharmaceutical compounding, are early adopters. The market's focus is migrating from rudimentary, time-based filter changes to performance-driven replacements based on real-time data, which this technology facilitates.
Europe's REACH regulation imposes strict controls on the production and use of chemical substances, directly impacting dust management. This framework forces operators in chemical processing and plastics manufacturing to document and control worker exposure to specific hazardous particulates. Consequently, the specialty chemicals segment is investing in higher-efficiency systems with containment features to ensure compliance with substance-specific safety data sheets.
A notable behavioral shift involves end-users moving from outright capital purchases to comprehensive service and maintenance contracts. This model disrupts the traditional sales process by bundling equipment with ongoing monitoring, filter replacement, and compliance reporting services. The trend is most advanced in North American and European food processing plants, where operators seek to outsource non-core functions and guarantee uptime.
Global Industrial Dust Collector Market Segmentation

The industrial dust collector market's segmentation provides a granular view of demand drivers and technological preferences across diverse operational environments. Understanding these distinct segments helps manufacturers tailor solutions to specific particulate challenges and regulatory mandates. Each category reflects unique requirements for air purity, safety, and operational efficiency.
Product Type:
Product type differentiation centers on filtration mechanism and particulate size capability, crucial for meeting varied industrial needs.
- Baghouse:These collectors utilize fabric filter bags to capture dry particulate matter, offering high efficiency for large volumes of dust. Demand concentrates in heavy industries like cement manufacturing and power generation, where robust design handles continuous, high-dust loads for emissions compliance.
- Cartridge Collector:Employing pleated filter cartridges, these systems provide a compact footprint and high filtration efficiency for finer dusts. Food processing plants and pharmaceutical facilities in Asia, particularly India and Vietnam, increasingly adopt cartridge collectors for their space efficiency and ability to meet stringent cleanroom standards.
- Cyclone:Cyclone collectors use centrifugal force to separate larger, heavier dust particles from the air stream, often serving as pre-cleaners.
- Electrostatic Precipitator:These systems remove particles from exhaust gases using an induced electrostatic charge, suitable for fine particulate removal in large-scale operations.
- Wet Scrubber:Wet scrubbers capture dust and gaseous pollutants by contacting the air stream with a liquid, effective for sticky or explosive dusts.
Baghouse technology commands the established base in heavy industries. The steepest expansion runs through cartridge collectors due to their compact design and high efficiency for specialized applications.
Technology:
Operational efficiency defines technology choices, impacting energy consumption and filter lifespan for industrial operators.
- Pulse Jet:This technology uses short bursts of compressed air to clean filter media, enabling continuous operation and optimizing filter life. Industries requiring uninterrupted dust collection, such as metal fabrication and mining, favor pulse jet systems for their efficiency.
- Reverse Air:Reverse air systems clean filter bags by introducing a reverse flow of low-pressure air, suitable for delicate filter media and specific dust characteristics.
- Shaker:Shaker collectors mechanically dislodge dust from filter bags through a shaking mechanism, a simpler and often lower-cost cleaning method.
- Packed Bed:Packed bed scrubbers use a packed tower to facilitate contact between the gas stream and scrubbing liquid, effective for gas absorption and particulate removal.
- Venturi Scrubber:Venturi scrubbers accelerate the gas stream to atomize scrubbing liquid, capturing fine particulates and aerosols with high efficiency. Pharmaceutical manufacturing increasingly adopts venturi scrubbers for critical containment.
Systems like pulse jet offer broad utility across many sectors. Specialized applications increasingly favor venturi scrubbers for enhanced performance in high-containment environments.
Application:
Application scope delineates system requirements, from handling abrasive materials to maintaining sterile processing environments.
- Metal Fabrication:This application generates fine metallic dust and fumes, requiring robust collection systems capable of handling combustible particulates. Strict OSHA regulations on combustible dust compel investment in certified systems for metalworking facilities in North America.
- Cement Manufacturing:Cement production creates large volumes of abrasive particulate matter, necessitating heavy-duty baghouses and electrostatic precipitators for emissions control. Infrastructure projects in India and Southeast Asia drive substantial demand for these large-scale systems.
- Food Processing:Food processing facilities require dust collectors that meet stringent hygiene standards and prevent cross-contamination of ingredients.
- Chemical Production:Chemical plants need specialized dust collection for hazardous or corrosive particulates, often requiring explosion-proof designs and specific material compatibility.
- Woodworking:Woodworking operations generate combustible wood dust, requiring systems designed for explosion protection and efficient particulate capture.
Traditional heavy industries like cement manufacturing drive substantial volume. Emerging specialized needs in metal fabrication demand tailored solutions for safety and compliance.
End User Industry:
Customer type influences procurement patterns and system scale, reflecting diverse operational priorities and regulatory landscapes.
- Mining Operators:Mining operations generate significant quantities of mineral dust, requiring large-scale, durable dust collectors to protect worker health and meet environmental standards. These facilities often deploy baghouses and wet scrubbers to manage fugitive dust emissions.
- Pulp & Paper Plants:These plants produce wood dust and fiber particles, necessitating efficient collection systems to maintain air quality and prevent equipment damage.
- Power Generation Facilities:Power plants, especially coal-fired, require massive dust collection systems like electrostatic precipitators and baghouses to control fly ash emissions. China's MEE enforces strict emission limits on these facilities.
- Textile Manufacturers:Textile production generates lint and fiber dust, requiring systems that can handle fibrous materials and maintain clean production environments.
- Waste Management Firms:Waste management operations, including recycling and incineration, produce diverse particulate matter, demanding flexible and robust dust collection solutions.
Mining operators represent a foundational demand segment due to the inherent dust generation. Growth opportunities expand within power generation facilities due to evolving operational standards and stringent emission mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in global manufacturing hubs defines regional demand for industrial dust collectors. China's extensive manufacturing base and India's infrastructure boom drive significant investment. Stricter air quality regulations worldwide compel advanced filtration system adoption.
China
China's manufacturing hubs demand advanced dust collection systems for emissions control. The Ministry of Ecology and Environment (MEE) enforces strict emission limits for industrial facilities. Industrial investment concentrates in manufacturing clusters across the Yangtze River Delta.
United States
United States industrial facilities require robust systems to comply with safety and environmental mandates. OSHA's stringent regulations on combustible dust compel investment in certified collection systems. Metal fabrication and woodworking operations in the Midwest drive significant demand.
India
India's rapid infrastructure development fuels substantial demand for large-scale dust collectors. Emissions compliance for cement manufacturing operations is a primary driver. Industrial zones in Gujarat and Maharashtra are key areas for baghouse installations.
Germany
German industrial sectors prioritize high-efficiency filtration systems for stringent environmental compliance. Europe's ECHA regulations on hazardous substances directly influence equipment specifications. Specialized manufacturing in Bavaria and North Rhine-Westphalia requires advanced solutions.
Vietnam
Vietnamese pharmaceutical processing plants represent a growing market for compact dust collectors. The country's national pharmaceutical regulator mandates stringent cleanroom and GMP standards. New manufacturing facilities near Ho Chi Minh City seek high-efficiency cartridge systems.
Global Industrial Dust Collector Market Key Industry Players
Channel-controlling players compete with product-specialist players in the global industrial dust collector market. The market exhibits a tiered structure, from diversified industrial conglomerates to specialized filtration providers. Strategic archetypes include full-service solution providers and niche technology innovators. Competitive moves involve strategic partnerships for broader market reach and technology licensing agreements.
Diversified industrial players like Donaldson Company, Inc. exemplify broad portfolio strategies, leveraging extensive filtration media expertise. Swedish-based Nederman Holding AB represents comprehensive air quality solutions for complex applications, often integrating advanced control systems. Danish-headquartered FLSmidth & Co. A/S anchors large-scale heavy industry applications, particularly for process control and emissions compliance in cement manufacturing.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Sly Incorporated |
| Donaldson Company, Inc. |
| Tysum |
| Munters Group AB |
| Camfil AB |
| FLSmidth & Co. A/S |
| CECO Environmental |
| Nederman Holding AB |
| Others |
Cost & Logistics Intelligence
China's manufacturing hubs, particularly the Yangtze River Delta, dictate global pricing leverage for standard industrial dust collectors as their production capacity scales. This concentration influences the cost structure and availability of components for advanced systems.
Pricing Analysis
Cost-plus contract patterns, often indexed to raw material prices, define pricing for large-scale industrial dust collector projects. Price differentiation stems from filtration efficiency grades, specific regulatory certifications like OSHA or MEE compliance, and the level of customization required. Pricing pressure intensifies for standard models due to increased competition and material cost volatility. Small and medium-sized enterprises (SMEs) exhibit higher price sensitivity compared to large industrial conglomerates with extensive capital budgets.
Supply Chain Analysis
Manufacturing concentration for industrial dust collectors largely resides in China for mass production and Germany for specialized, high-efficiency systems. Raw material dependencies include specialized filtration media like PTFE membranes, steel for structural components, and advanced sensors for IoT integration. Filtration media cost volatility represents a significant supply chain risk, impacting total cost of ownership. Distribution runs through a combination of direct sales for major industrial clients and a network of specialized equipment distributors for smaller market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial dust collector market is in an early-cycle expansion phase, driven by the accelerating penetration of smart, IoT-enabled air quality management systems across manufacturing facilities.
For Market Incumbents:Entrench market leadership by investing heavily in R&D for nanofiber filtration media and integrated IoT platforms. Develop comprehensive service and maintenance contracts to counter margin pressure from new entrants offering specialized solutions. Pursue strategic partnerships in emerging manufacturing hubs like Southeast Asia to secure broader market reach. Leverage extensive filtration media portfolios to offer certified solutions meeting stringent regulations like Europe's ECHA.
For New Entrants and Emerging Players:Battery manufacturing gigafactories and pharmaceutical processing facilities in Asia represent the most penetrable entry points for specialized solutions. Focus on compact, high-efficiency cartridge collectors designed for specific hazardous materials or cleanroom standards. A viable go-to-market angle involves offering Air-as-a-Service models, bundling equipment with guaranteed performance and compliance reporting for a recurring fee.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized technology innovators offering advanced filtration media or intelligent monitoring systems. Long-term viability is secured by sustained global regulatory pressure and the ongoing digital transformation of industrial operations. An attractive acquisition target archetype includes regional players with strong footholds in high-growth markets like India and Vietnam. The success of subscription-based air quality management models is a key signal to watch as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand IoT-enabled system portfolio | Enhances predictive maintenance capabilities, optimizing filter life and energy consumption for end-users. |
| Form strategic alliances in Asia | Captures demand from rapid industrialization and stricter environmental mandates in emerging economies. |
| Invest in advanced filtration media R&D | Addresses evolving regulatory requirements and specialized dust challenges in high-tech manufacturing. |
| Develop comprehensive service contracts | Creates recurring revenue streams and strengthens customer loyalty through guaranteed uptime and compliance. |
| Acquire specialized cleanroom technology firms | Penetrates high-value pharmaceutical and electronics sectors with stringent air purity demands. |
Research Approach
The analysis maps industrial dust collector sub-sectors including product type, technology, application, and end-user industry, each validated through extensive primary interviews. We engaged with plant managers, environmental compliance officers, procurement leads, and R&D directors across various industries. Secondary validation drew from US EPA and China MEE regulatory reports, industry association publications, and company annual reports, triangulating data through bottom-up and top-down approaches.
The forecast framework applies a robust analytical methodology across the analysis window, holding macroeconomic stability and current regulatory trajectories fixed while varying technological adoption rates. Segmentation dimensions modeled include product type, cleaning technology, specific application, and end-user industry, alongside regional regulatory stringency. Compound annual growth rates were derived from historical trends and projected impacts of tightening environmental and occupational health mandates, using industrial output indices and infrastructure spending data as key inputs.
Macroeconomic conditions sit as an overlay; deviation in global industrial output or raw material price stability would shift the trajectory. Forecasts reflect assumptions documented through extensive primary and secondary research. Quarterly review of regulatory updates and industrial investment trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
GCC Heat Treating Market
Industrial Materials
Paint Knife Market
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
Global Plastic Fasteners Market
Industrial Materials
Plastic Molds Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
Thermal Spray Guns Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Soil Stabilization Materials Market
Industrial Materials
Pre-Painted Steel Coil Market
Industrial Materials
Magnetic Separator Market
Industrial Materials
Wire Mesh Market
Industrial Materials
Wedge Wire Screen Market
Industrial Materials
Stainless Steel Cable Ties Market
Industrial Materials
Global High Temperature Gaskets Market
Industrial Materials
Industrial Mixers Market