
 Glass Reinforced Epoxy (GRE) Pipes Market | 2026-2036
Glass Reinforced Epoxy (GRE) Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Reinforced Epoxy (GRE) Pipes Market Foresight
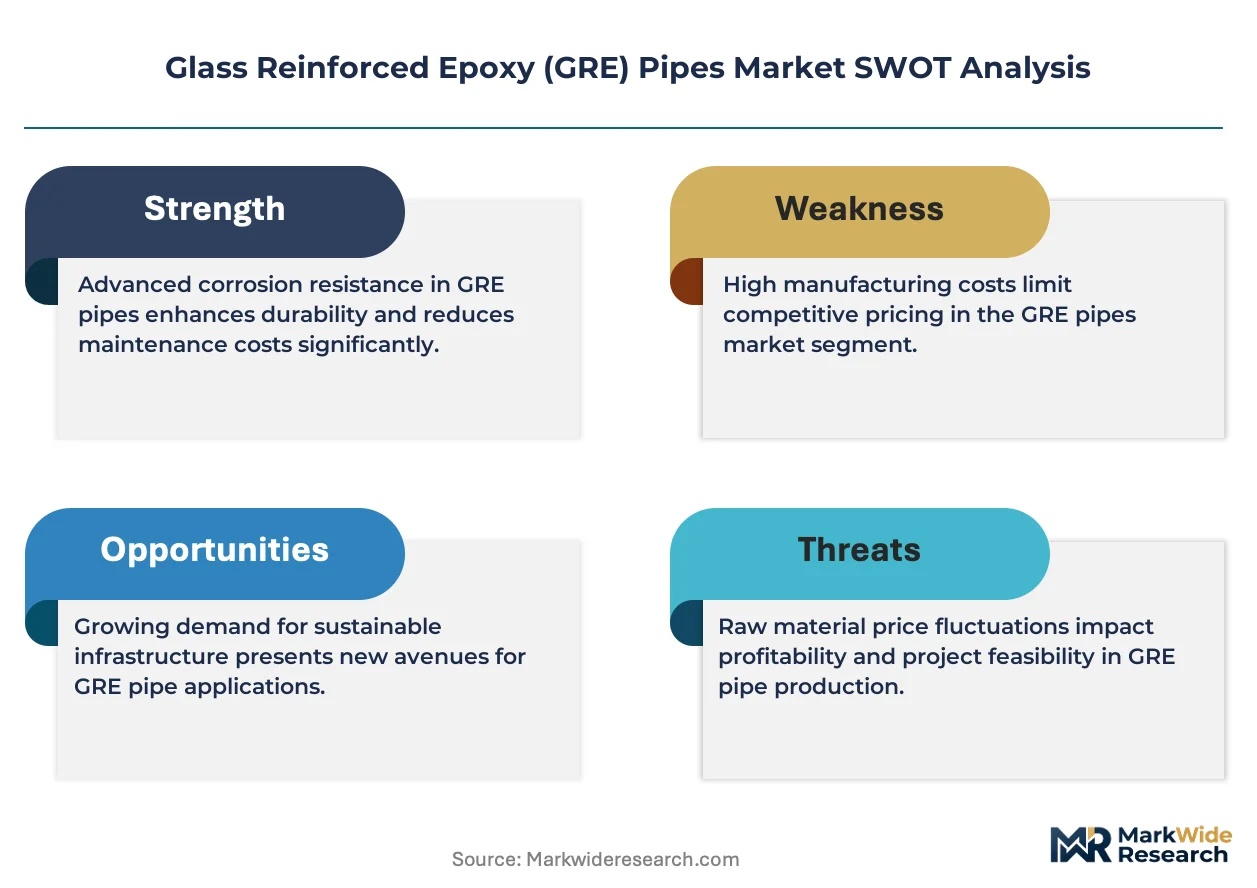
Multi-source procurement for epoxy resin and glass fiber is restructuring supply economics across the GRE pipe industry. National Oilwell Varco leverages its integrated oilfield services platform to bundle pipe systems with offshore project contracts. Future Pipe Industries anchors its position through dedicated manufacturing scale across the Middle East and Southeast Asia. HOBAS competes primarily in municipal water infrastructure, where its product specialization in large-diameter GRE systems creates defensible market positions.
Glass Reinforced Epoxy pipes are filament-wound or centrifugally cast composite structures combining thermosetting epoxy resin with continuous glass fiber reinforcement, typically engineered for operating pressures from 150 psi to over 3000 psi and temperatures up to 93 degrees Celsius depending on resin formulation. The primary industrial purpose centers on fluid transport in corrosive environments where steel suffers degradation, particularly in sour oil service, chemical effluent handling, and saline water injection systems. Standard pipes dominate current volume shipments due to established specifications in oil and gas infrastructure, while custom pipes capture disproportionate margin pools from project-specific engineering requirements in offshore and chemical processing installations. The corrosion resistance application segment leads end-user adoption as operators prioritize lifecycle cost reduction over initial capital expenditure in aggressive service conditions.
The American Petroleum Institute API 15HR and API 15LR standards govern qualification and performance testing for GRE pipes in hydrocarbon service, while ISO 14692 provides international design and installation guidelines that shape product acceptance across export markets. EPA effluent limitation guidelines and OSHA process safety management requirements in the United States further reinforce composite material substitution in chemical processing and wastewater applications. Stakeholders must monitor evolving API revisions and regional carbon-accounting frameworks that could recalibrate material selection criteria between GRE and emerging thermoplastic alternatives.
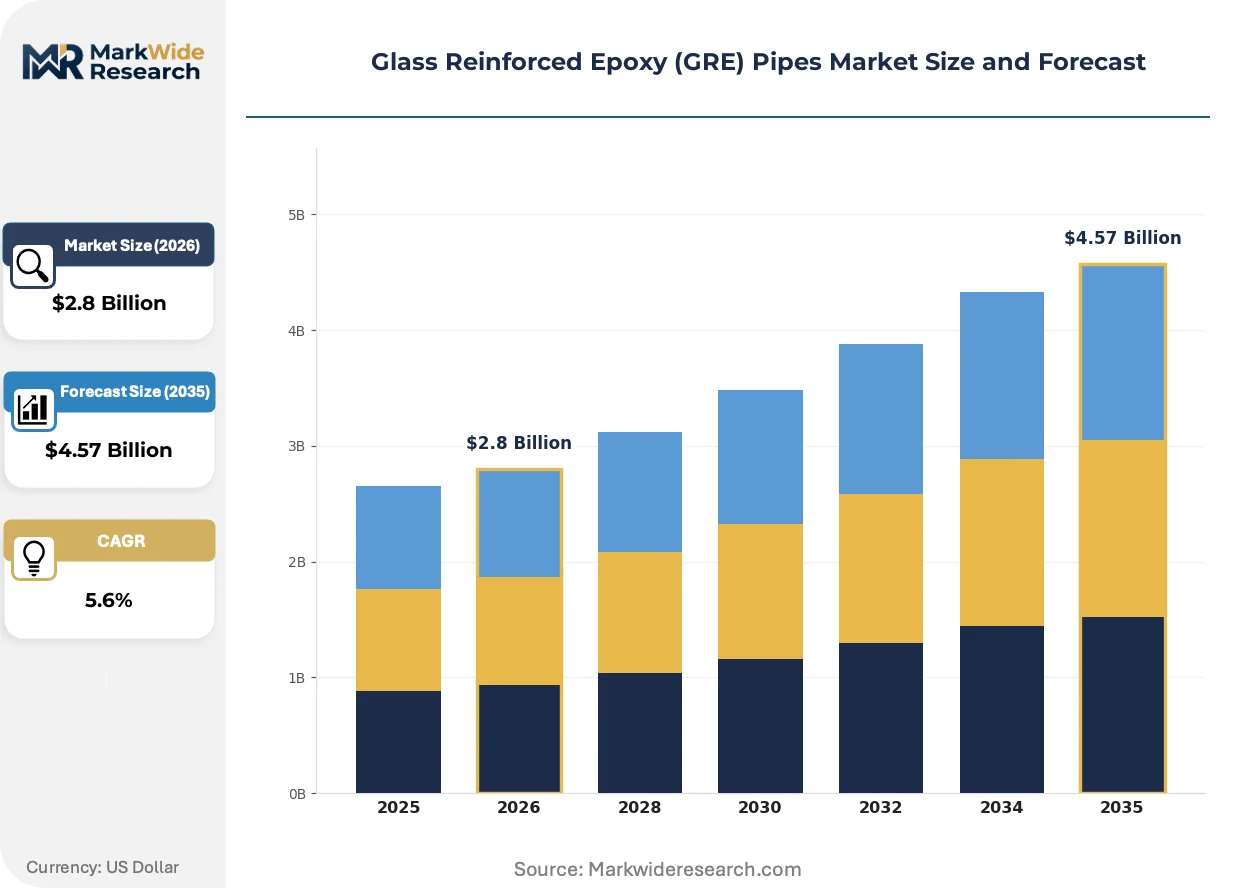
Market Dynamics
Offshore operators in the United States Gulf Coast and Norway's North Sea are accelerating GRE pipe deployment for subsea infrastructure as lifecycle cost economics displace corrosion-prone steel in sour service conditions. The EU F-Gas Regulation and parallel environmental standards in North America and Asia are structurally recalibrating material selection criteria across chemical processing and oilfield applications.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon emissions is compelling chemical processors across Germany and France to substitute metal piping with corrosion-resistant composite alternatives in refrigeration and process cooling loops.
- Offshore decommissioning wave:Aging steel infrastructure in the United Kingdom and Norwegian North Sea fields requires replacement, with GRE riser systems capturing retrofit contracts due to reduced maintenance burden and extended service intervals.
- Epoxy resin formulation advances:High-temperature resin systems now enable GRE pipe deployment in thermal enhanced oil recovery operations previously restricted to metallics, opening new addressable volume in California and Middle East heavy oil fields.
Market Restraints
- Glass fiber supply concentration:Filament-winding-grade E-glass roving production concentrates among Chinese state-owned enterprises, exposing GRE pipe manufacturers to export quota volatility and freight cost spikes.
- API 15HR certification timeline:Qualification testing for high-pressure hydrocarbon service requires 18-24 months of sustained capital commitment before commercial deployment, compressing working capital efficiency for mid-scale producers.
- Thermoplastic composite substitution:Reinforced thermoplastic pipes from SoluForce and Airborne Oil & Gas are displacing GRE in onshore gathering systems where temperature and pressure envelopes permit material flexibility.
Strategic Opportunities
- Saudi Aramco localization mandates:The In-Kingdom Total Value Add program requires foreign contractors to source composite pipe systems from domestic manufacturing joint ventures, creating captive demand for localized GRE production capacity.
- Desalination plant expansion:Seawater reverse osmosis facilities in the United Arab Emirates and Qatar are specifying large-diameter GRE intake and brine discharge lines, opening municipal-scale volume outside traditional oilfield channels.
- Carbon accounting integration:Emerging Scope 3 emissions disclosure requirements under the EU CSRD are positioning GRE's lower embodied carbon versus steel as a procurement differentiator in European refinery maintenance cycles.
Industry Challenges
- Filament-winding technician scarcity:Specialized operators capable of programming multi-axis winding machines for complex offshore joint geometries command premium wages in Houston and Aberdeen, constraining capacity expansion.
- Legacy steel welding culture:Maintenance crews in established oilfield regions resist composite repair protocols, slowing GRE penetration in brownfield retrofit projects despite superior lifecycle economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Reinforced Epoxy (GRE) Pipes Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pipes, Custom Pipes, Fittings, Flanges End User: Oil & Gas, Water Management, Chemical Processing, Construction Installation Type: Above Ground, Below Ground, Offshore, Industrial Application: Fluid Transport, Corrosion Resistance, Waste Disposal, High Pressure Systems |
| Companies Covered | National Oilwell Varco, HOBAS, Future Pipe Industries, Hengrun Group, Amiblu Holding GmbH, Amiantit Fiberglass Industries, Lianyungang Zhongfu Lianzhong Composites Group, Graphite India, Enduro Composites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Reinforced Epoxy (GRE) Pipes Market Shifts & Advancements
Material science advances and regulatory carbon accounting are converging to reposition GRE pipes from niche corrosion solutions to standard infrastructure specifications in aggressive service environments. Three developments are actively reshaping competitive positioning and procurement patterns.
Hybrid epoxy-thermoset formulations incorporating nano-silica modifiers are unifying pressure rating and impact resistance previously requiring trade-offs in conventional GRE systems. Offshore engineering contractors in Norway and Brazil are specifying these enhanced grades for dynamic riser applications where fatigue performance determines field life. The technology is unifying what were separate product categories—standard and high-performance GRE—into a single specification tier, compressing SKU complexity for manufacturers.
REACH authorization requirements for bisphenol-A derivatives are forcing European resin suppliers to reformulate curing agent packages ahead of 2025 sunset dates. German chemical processors must validate alternative epoxy hardener systems for effluent handling lines or face replacement mandates. The regulation is accelerating qualification partnerships between pipe fabricators and specialty chemical producers, with BASF and Huntsman securing multi-year supply agreements for BPA-free formulations.
Integrated service contracting is displacing discrete pipe procurement in major offshore developments. Engineering-procurement-construction firms in the United States Gulf Coast now bundle GRE systems with subsea installation and integrity management, capturing margin pools previously retained by pipe specialists. This consolidation is most visible in ExxonMobil and Chevron deepwater projects, where single-source accountability for flowline performance has become a non-negotiable bid requirement.
Glass Reinforced Epoxy (GRE) Pipes Market Segmentation
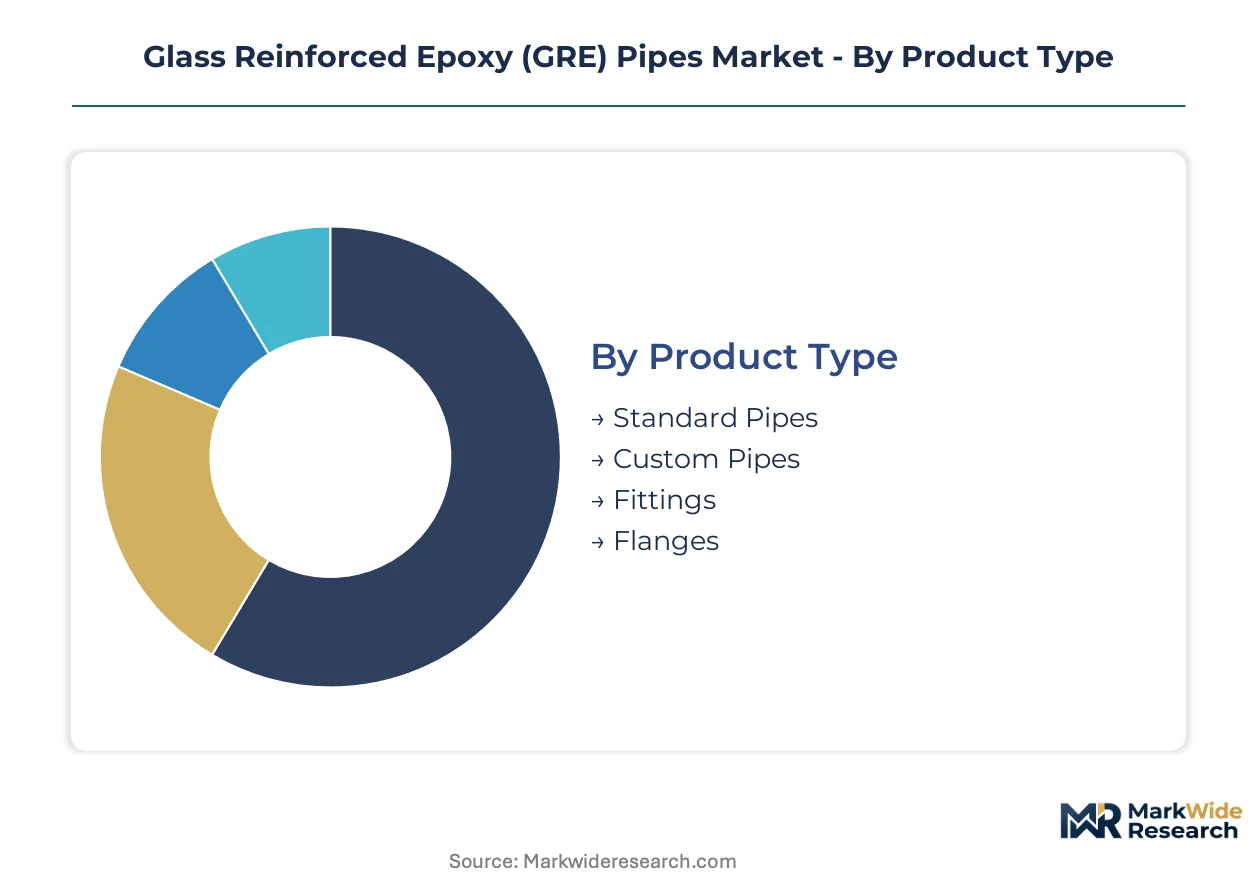
GRE pipe procurement patterns diverge sharply between commodity volume plays and engineered project specifications. Understanding where customization premiums concentrate versus where standard catalog drives margin is essential for capacity planning and sales force deployment.
Product Type:
Standardization dominates high-volume oilfield gathering systems while custom engineering captures premium margin in subsea riser applications.
- Standard Pipes:Filament-wound or centrifugally cast composite structures with fixed dimension catalogs per API 15HR and ISO 14692 specifications. Demand concentrates in United States Permian Basin water injection lines and Saudi Aramco onshore gathering networks where installation crews value interchangeability and rapid replacement availability.
- Custom Pipes:Project-specific engineered geometries with tailored resin formulations, reinforcement schedules, and joint configurations for dynamic riser and high-pressure sour service. Norwegian North Sea operators and Brazil's pre-salt developments specify these systems where fatigue life and collapse resistance determine field economics.
- Fittings:Elbows, tees, and reducers matching standard pipe pressure ratings for modular system assembly.
- Flanges:Composite-to-metallic transition components enabling GRE integration with legacy steel infrastructure.
Leading the category by volume: Standard Pipes. Expanding most quickly: Custom Pipes.
End User:
Capital intensity and corrosion exposure severity determine end-user procurement sophistication and lifecycle cost calculation methods.
- Oil & Gas:Offshore operators in Norway, United States Gulf Coast, and Brazil anchor demand for high-pressure hydrocarbon service. Sour gas production in Kazakhstan and shale water handling in Texas drive replacement cycles away from metallics.
- Water Management:Municipal desalination plants in United Arab Emirates and Qatar specify large-diameter GRE intake systems. Seawater reverse osmosis facilities value corrosion immunity against chloride attack.
- Chemical Processing:German and French processors substitute GRE for steel under EU F-Gas Regulation mandates in refrigeration and cooling loops.
- Construction:Infrastructure projects in coastal zones deploy GRE for drainage and foundation dewatering where saline groundwater accelerates metallic degradation.
Highest procurement sophistication: Oil & Gas. Fastest volume climb: Water Management.
Installation Type:
Environmental exposure conditions dictate resin formulation selection and joint design complexity across installation categories.
- Above Ground:Refinery process piping and chemical plant distribution headers in United States Texas-Louisiana corridor and Rotterdam-Antwerp chemical cluster. UV-stabilized external layers address atmospheric degradation.
- Below Ground:Buried gathering lines in Saudi Arabia's Ghawar field and municipal water distribution in Australia's coastal cities. Soil chemistry and cathodic interference avoidance drive specification.
- Offshore:Subsea flowlines and riser systems in Norway's Johan Sverdrup field and United States Mad Dog development. Dynamic fatigue resistance and hydrostatic collapse rating dominate engineering.
- Industrial:Process cooling and effluent handling within plant battery limits. Chemical processors in Germany's Ludwigshafen cluster value fire resistance and thermal stability.
Deepest technical requirements: Offshore. Broadest volume base: Above Ground.
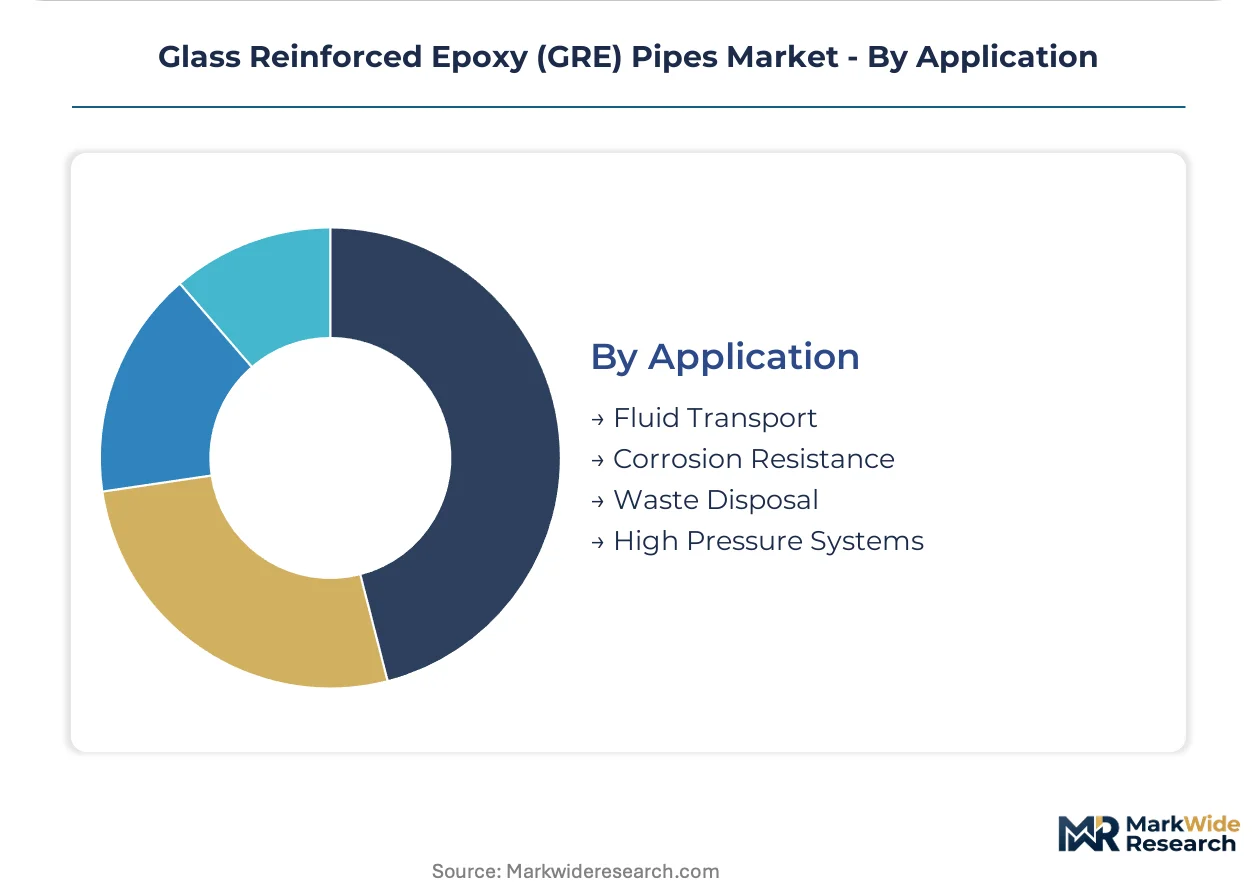
Application:
Functional performance requirements segment the market between commodity fluid movement and specialized containment challenges.
- Fluid Transport:Crude oil, produced water, and injection fluid movement in gathering and distribution networks. Standard pressure ratings from 150 psi to 1500 psi cover majority of onshore oilfield applications.
- Corrosion Resistance:Sour service hydrogen sulfide exposure and chloride-rich environments where steel suffers rapid degradation. Norwegian North Sea operators prioritize lifecycle cost against metallics.
- Waste Disposal:Produced water reinjection and chemical effluent handling. United States EPA effluent guidelines reinforce composite substitution in Permian Basin disposal wells.
- High Pressure Systems:Thermal enhanced oil recovery and deepwater production exceeding 3000 psi. California heavy oil fields and Brazil pre-salt developments stretch resin formulation boundaries.
Widest deployment: Fluid Transport. Steepest specification climb: High Pressure Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-glass roving production concentrates in Chinese state-owned enterprises, anchoring raw material flows for GRE pipe fabricators worldwide. Offshore project clusters in the North Sea, Gulf Coast, and Arabian Gulf drive specification complexity and resin formulation requirements. Regulatory pressure on corrosion-prone steel infrastructure accelerates substitution timelines across coastal refining and chemical processing zones.
United States
Permian Basin water injection networks and Gulf Coast deepwater developments anchor domestic demand. EPA effluent limitation guidelines reinforce composite substitution in produced water handling. Houston hosts the densest concentration of filament-winding fabrication capacity serving offshore engineering contractors.
Norway
North Sea decommissioning waves and Johan Sverdrup field expansion sustain premium-grade GRE procurement. EU F-Gas Regulation accelerates material substitution in offshore refrigeration and process cooling systems. Stavanger and Bergen engineering clusters specify custom riser systems for sour service conditions.
China
Coastal refining zones in Shandong and Guangdong drive large-diameter GRE demand for brine and chemical effluent handling. MIIT industrial standards for composite pressure vessels shape domestic qualification protocols. Lianyungang anchors filament-winding manufacturing scale serving both domestic oilfield and export desalination projects.
Saudi Arabia
In-Kingdom Total Value Add mandates require foreign contractors to source composite pipe systems from domestic manufacturing joint ventures. Saudi Aramco onshore gathering network expansion prioritizes corrosion-resistant alternatives for Ghawar field water injection. Dammam industrial city hosts localization partnerships between international fabricators and state-backed manufacturing entities.
Germany
REACH authorization deadlines for bisphenol-A derivatives force resin reformulation in chemical processing effluent lines. Ludwigshafen chemical cluster operators validate alternative epoxy hardener systems ahead of 2025 sunset dates. BASF and Huntsman secure multi-year supply agreements for BPA-free formulations serving pipe fabricators.
Glass Reinforced Epoxy (GRE) Pipes Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and project-specific engineering capabilities. The vendor base organizes into three tiers: integrated oilfield service platforms bundling pipe with installation contracts, dedicated composite specialists with Middle East and Southeast Asia manufacturing footprints, and municipal water infrastructure players defending positions in large-diameter systems. Dominant competitive moves include capacity localization under Saudi Aramco and ADNOC in-country value programs, plus REACH-driven reformulation partnerships between resin suppliers and pipe fabricators.
Within the integrated service tier, National Oilwell Varco occupies a position exemplifying bundled offshore project contracting. Future Pipe Industries anchors the regional manufacturing archetype through Middle East and Southeast Asia production scale. HOBAS represents the municipal specialization vector, with product focus in large-diameter water infrastructure creating defensible positioning against oilfield-centric competitors. These three patterns—service integration, geographic scale, and application specialization—structure competitive rivalry across procurement channels.
| Leading Market Players |
|---|
| National Oilwell Varco |
| HOBAS |
| Future Pipe Industries |
| Hengrun Group |
| Amiblu Holding GmbH |
| Amiantit Fiberglass Industries |
| Lianyungang Zhongfu Lianzhong Composites Group |
| Graphite India |
| Enduro Composites |
| Others |
Supply & Pricing Matrix
API certification tier divergence between 15HR high-pressure and 15LR low-pressure specifications manifests in both unit economics and raw material sourcing strategies. Premium-grade systems command substantial markups through bundled integrity management and extended warranty terms, while commodity volumes compete on resin cost efficiency and freight optimization to Middle Eastern and Asian project sites.
Pricing Analysis
Warranty and service bundling separates project-based procurement from catalog sales, with offshore contractors demanding 10-year performance guarantees and predictive maintenance packages. Price differentiation rests on API certification level and resin formulation sophistication, with sour-service grades capturing margin premiums. Cost compression in standard pipe tiers intensifies due to Chinese E-glass oversupply and freight rate normalization post-pandemic. Municipal water authorities exhibit highest price sensitivity, while North Sea operators prioritize lifecycle cost over initial capital outlay.
Supply Chain Analysis
Freight cost volatility from Chinese filament-winding centers to Gulf Coast fabrication yards shapes inventory positioning and contract structuring. Manufacturing gravity centers on China, Saudi Arabia, and the United States, with E-glass roving production drawing from state-owned enterprises in Lianyungang and Chongqing. Epoxy resin formulations hinge on bisphenol-A derivatives from German and US chemical majors. Single-source vulnerability concentrates in filament-winding-grade glass fiber export quotas. Distribution runs through engineering-procurement-construction contractors bundling pipe with installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Filament-winding technician scarcity constrains capacity expansion across Houston and Aberdeen engineering clusters, propping pricing power for qualified fabricators. Supply bottlenecks in specialized labor and API certification timelines protect margin structures for incumbents with established training pipelines.
For Market Incumbents: To counter thermoplastic composite substitution in onshore gathering systems, anchor market position through captive E-glass supply agreements with Chinese state-owned enterprises and accelerate API 15HR qualification pipelines for high-pressure thermal EOR applications. Backward integration into epoxy resin formulation protects margin against REACH-driven hardener cost spikes. For New Entrants and Emerging Players: Desalination plant operators in the United Arab Emirates and Qatar represent the most penetrable buyer archetype, with large-diameter intake systems underserved by oilfield-centric incumbents. Target municipal water infrastructure channels through dedicated large-diameter manufacturing scale and NSF/ANSI 61 certification investment. Partner with European engineering firms for carbon-accounting-compliant procurement positioning. For Investors and Strategic Acquirers: Re-rating potential sits with regional fabricators possessing Saudi Aramco In-Kingdom Total Value Add joint venture status given localization mandate enforcement. Long-term viability over a multi-year horizon favors Middle East manufacturing footprints with captive access to domestic oilfield demand. Watch API specification revisions for thermoplastic competitive boundary shifts as inflection indicators for GRE displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| API 15HR Certification Investment | Unlocks high-pressure hydrocarbon service contracts with ExxonMobil and Chevron deepwater projects. |
| Saudi Localization Joint Venture | Satisfies In-Kingdom Total Value Add mandates for Saudi Aramco Ghawar field water injection networks. |
| BPA-Free Resin Reformulation | Aligns with REACH authorization deadlines for German Ludwigshafen chemical cluster effluent handling. |
| Filament-Winding Technician Training Pipeline | Addresses capacity constraints in Houston and Aberdeen offshore engineering clusters. |
| Integrated Service Contracting Capability | Captures margin pools from EPC bundling trends in United States Gulf Coast subsea developments. |
Research Methodology
Independent corroboration across plant managers at GRE fabrication facilities, procurement leads at National Oilwell Varco and Future Pipe Industries, EPC contractors in Stavanger and Houston, and resin supply specialists at BASF and Huntsman underwrites the qualitative findings. Secondary validation draws from API specification documents, EPA effluent limitation guidelines, EU F-Gas Regulation impact assessments, and SEC filings of publicly traded oilfield service providers. Bottom-up project pipeline analysis triangulates against top-down oilfield capital expenditure forecasts.
Rate-of-change decomposition separates volume growth from price realization across standard versus custom pipe tiers, installation type complexity gradients, and regional regulatory enforcement intensity. Segmentation dimensions span product type, end-use industry, installation environment, and application function. CAGRs derive from elasticity-adjusted demand curves and capacity expansion timelines. Forecast inputs incorporate resin formulation advancement trajectories and offshore decommissioning replacement cycles.
Revisions become necessary when API specification updates alter competitive boundaries with thermoplastic alternatives, or when Chinese E-glass export quotas disrupt raw material flows. Forecasts reflect assumptions about regulatory enforcement continuity and labor skill development rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Seamless Pipe Market
Pipes and Tubes
HPLC Fused Silica Tube Market
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
PVDF Pipes Market
Pipes and Tubes
Clad Pipe Market
Pipes and Tubes
ESR Tubes Market
Pipes and Tubes
Global PEX (Cross-Linked Polyethylene) Market
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
Coiled Tubing Manufacturing Market
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
Gas Pipe Fittings Market
Pipes and Tubes
United States Copper Pipes and Tubes Market
Pipes and Tubes
India PVC Pipes Market
Pipes and Tubes
Heat Shrink Tubing Market