
 Waste Plastic Bricks Market | 2026-2036
Waste Plastic Bricks Market Size, Share, and Industry Trends Forecast 2026-2036
Waste Plastic Bricks Market Analysis
South Asian recycled polymer processors is shifting toward construction-grade extrusion capacity as infrastructure ministries formalize green procurement criteria. WES-Tec Global leverages its composite molding expertise to anchor supply contracts in East African public housing schemes. Gjenge Makers Ltd. specializes in interlocking paver systems derived from mixed post-consumer film. Sea2Brick competes through marine plastic recovery networks that sustain feedstock cost advantages against virgin resin benchmarks.
Waste plastic bricks are construction units manufactured from shredded, melted, and compressed post-consumer polymers, typically achieving compressive strengths of 3-6 N/mm² through extrusion or injection molding processes. These units serve primarily as load-bearing or non-load-bearing masonry elements in walls, pavements, and landscaping structures where weight reduction and thermal insulation offset conventional clay or concrete alternatives. Interlocking brick configurations command premium positioning due to reduced mortar requirements and faster assembly cycles in low-rise construction. Solid brick variants dominate volume throughput where compressive performance must meet national building code thresholds. Molded product forms capture margin concentration through design flexibility for architectural facing applications.
India's BIS certification framework for recycled construction materials and Kenya's National Environment Management Authority plastic waste quotas are tightening product standard compliance burdens. The EU Construction Products Regulation and REACH substance restrictions constrain polymer feedstock eligibility for export-oriented producers. Stakeholders must monitor evolving embodied carbon accounting rules in green building certification schemes to anticipate procurement preference shifts.
Market Dynamics
India's BIS certification pathway for recycled construction materials is compressing supply timelines for waste plastic brick manufacturers seeking public infrastructure contracts. Municipal procurement mandates now require documented polymer traceability, forcing processors to restructure feedstock collection networks around verified post-consumer sources.
Growth Catalysts
- Affordable housing mandates:Kenya's national housing program directs development finance toward interlocking plastic brick systems for informal settlement upgrades. Nairobi's county government has integrated these units into standardized construction specifications.
- Marine plastic recovery incentives:Extended producer responsibility frameworks in coastal economies are subsidizing collection infrastructure that channels ocean-bound plastics into construction-grade feedstock streams.
- REACH substance restrictions:The EU's constrained virgin polymer eligibility for export markets is redirecting European construction material distributors toward certified recycled alternatives from South Asian suppliers.
Market Restraints
- Feedstock cost volatility:Post-consumer polyethylene film prices fluctuate with crude oil benchmarks, compressing margin predictability for extrusion-dependent producers.
- Compressive strength limitations:Current thermal processing methods cap waste plastic bricks at 6 N/mm², excluding them from high-load structural applications governed by national building codes.
- Regional supply concentration:East African demand clusters depend on a narrow base of composite molding specialists, creating bottleneck risk during procurement surges.
Strategic Opportunities
- Carbon accounting integration:Green building certification schemes are embedding embodied carbon thresholds that favor recycled polymer masonry over fired clay alternatives.
- Rural road construction:India's Pradhan Mantri Gram Sadak Yojana is expanding eligibility criteria to include plastic-composite paving blocks for low-traffic village networks.
- Hybrid extrusion-injection systems:Convergence of continuous extrusion with precision injection molding is enabling architectural facing products with textured surface finishes.
Industry Challenges
- Polymer sorting expertise shortage:Manual separation of multi-resin post-consumer streams limits throughput consistency for construction-grade output.
- BIS certification timelines:Bureau of Indian Standards review cycles for recycled material approval extend 14-18 months, delaying market entry for new processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waste Plastic Bricks Market |
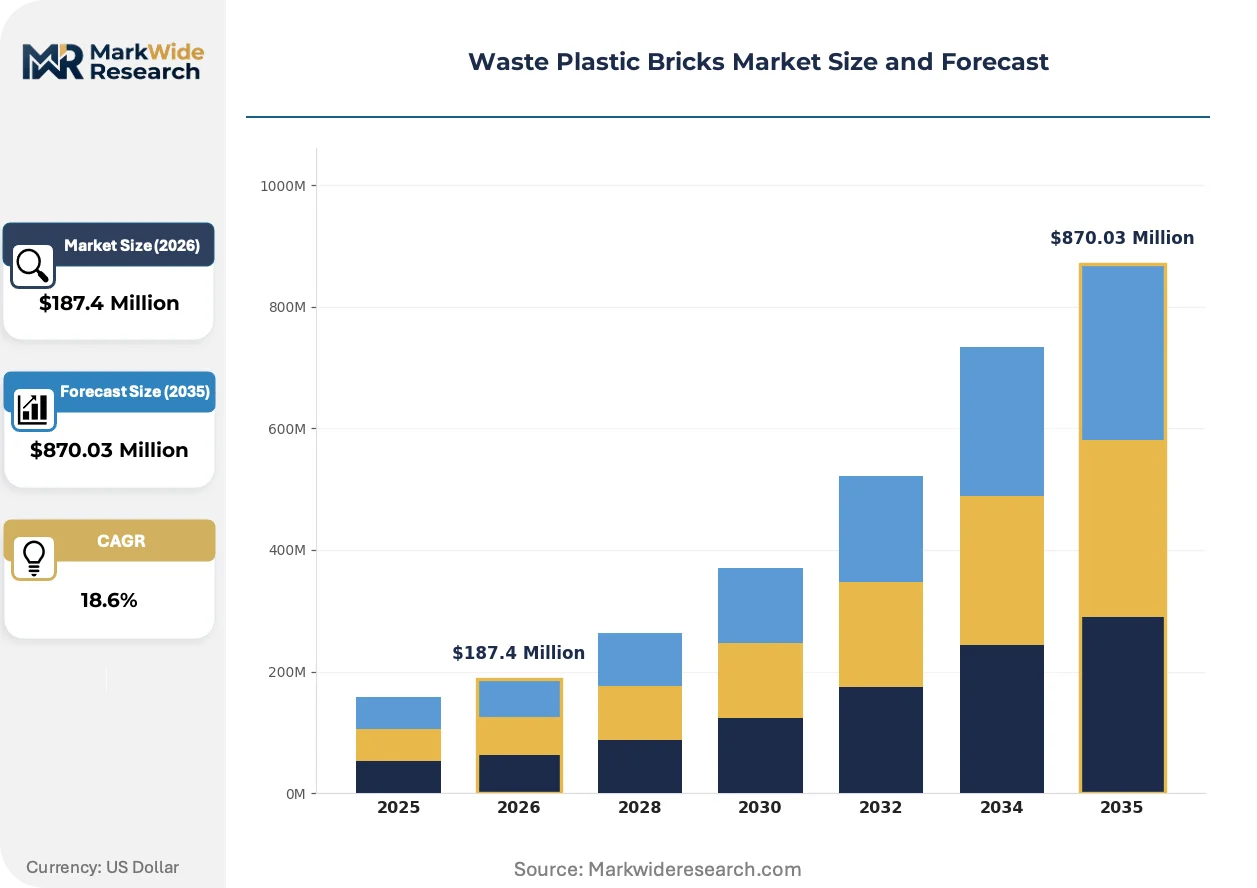
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interlocking Bricks, Hollow Bricks, Solid Bricks, Pavers Application: Construction, Landscaping, Road Surfacing, Retaining Walls Form: Recycled Granules, Extruded Products, Molded Products, Composite Materials Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | WES-Tec Global, Sea2Brick, Gjenge Makers Ltd., Klean Industries, Precious Plastic, Plastic Bottle Bricks, Intec Building Elements, Greenmax, RePlast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waste Plastic Bricks Market Emerging Trajectories
Material processing advances and procurement rule changes are compressing the gap between laboratory-formulated recycled polymers and code-compliant construction products. Three developments are restructuring competitive positioning.
Dual-screw extrusion with inline mineral filler injection is electrifying compressive performance in mixed-polymer feedstocks. Indian infrastructure contractors are specifying these enhanced units for load-bearing partition walls in mid-rise housing. The technology is compressing the performance premium traditionally commanded by single-resin virgin formulations.
India's Plastic Waste Management Rules amendment has mandated extended producer responsibility for brand owners generating multi-layered packaging waste. This regulatory pressure is diverting previously non-recyclable film streams toward construction material processors with advanced delamination capabilities. South Asian extrusion specialists are responding by expanding dedicated collection partnerships with fast-moving consumer goods distributors.
Public works departments are unbundling material procurement from construction contracts, creating direct purchasing relationships with certified brick manufacturers. This channel restructuring displaces traditional masonry supply intermediaries in Kenyan county-level housing projects. The shift is most visible in Nairobi's informal settlement upgrading schemes, where interlocking plastic brick orders now flow through centralized procurement platforms rather than site-based subcontractor networks.
Waste Plastic Bricks Market Segmentation
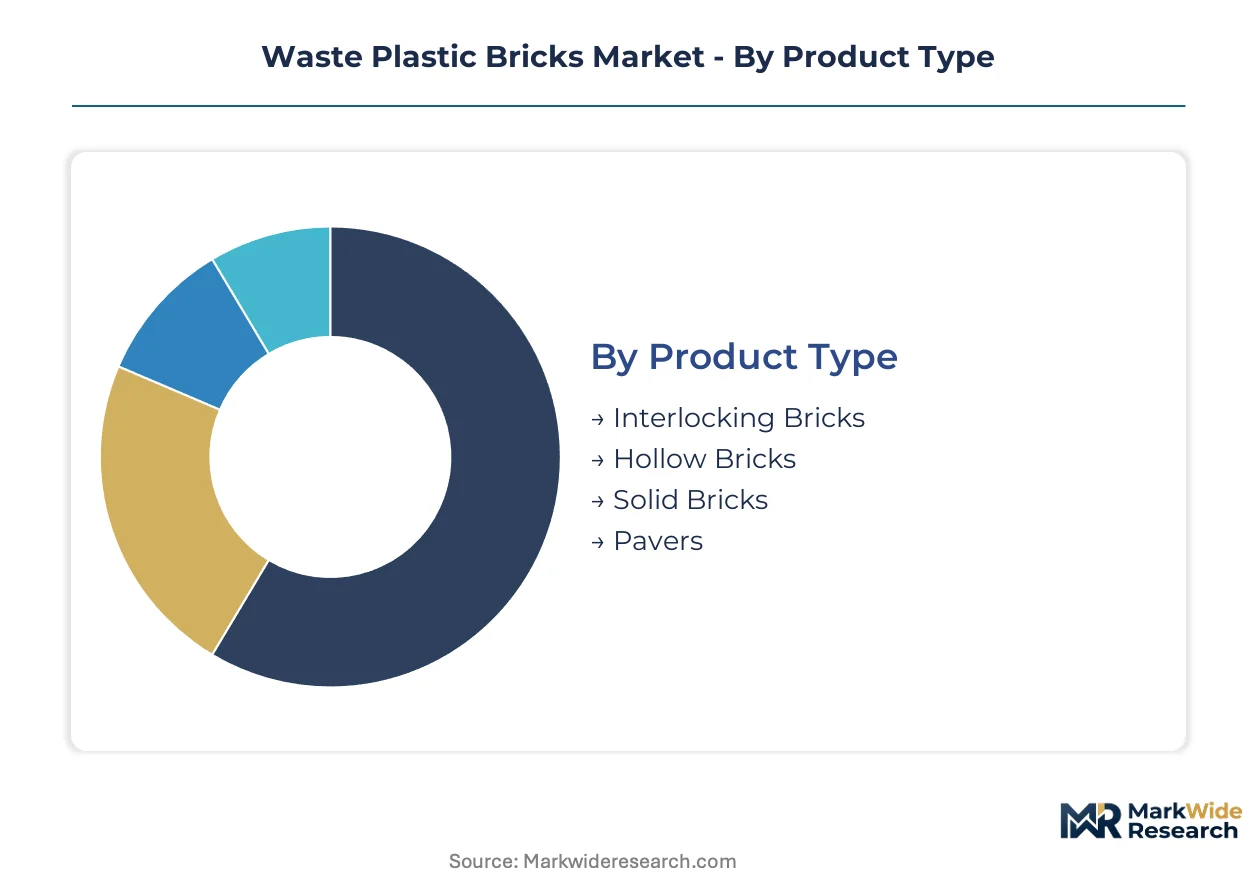
Segmentation in waste plastic bricks reveals how technical specifications, procurement channels, and end-use requirements fragment supply strategies. Buyers prioritize compressive performance for structural applications versus assembly speed for low-rise housing, forcing manufacturers to specialize across incompatible production systems.
Product Type:
Cost tier determines specification trade-offs between mortar elimination, thermal mass, and load-bearing certification.
- Interlocking Bricks:Precision-molded units with tongue-and-groove geometries eliminate vertical mortar joints and accelerate assembly cycles. Nairobi's informal settlement upgrading projects specify these for standardized low-rise housing where labor cost reduction outweighs material premiums.
- Solid Bricks:Dense polymer extrusions achieve maximum compressive strength within current thermal processing limits, typically 5-6 N/mm². Indian mid-rise contractors select these for load-bearing partition walls where BIS certification mandates documented performance thresholds.
- Hollow Bricks:Cavity-core designs reduce material throughput and improve thermal insulation coefficients for non-structural infill applications.
- Pavers:Surface-hardened units for pedestrian and light-vehicle traffic in landscaping and municipal pathways.
Solid bricks lead on scale; interlocking bricks lead on momentum.
Application:
Volume concentration follows public procurement mandates rather than private construction cycles.
- Construction:Structural and non-structural masonry for walls, partitions, and building envelopes. Kenya's affordable housing program channels development finance toward plastic-composite systems, creating procurement concentration in Nairobi county projects.
- Road Surfacing:Paving blocks and curbstones for low-traffic village networks. India's Pradhan Mantri Gram Sadak Yojana expanded eligibility criteria to include plastic-composite materials, opening rural road contracts to certified processors.
- Landscaping:Decorative and functional hardscaping elements where aesthetic flexibility commands premium positioning.
- Retaining Walls:Geotechnical applications requiring interlocking stability and drainage performance.
Construction commands volume concentration; road surfacing shows the steepest expansion trajectory.
Form:
Supply chain position determines margin capture versus feedstock risk exposure.
- Extruded Products:Continuous profile manufacturing delivers consistent cross-sections for structural bricks and linear paving elements. Indian infrastructure contractors favor extruded units for BIS-compliant load-bearing applications where dimensional tolerance affects masonry integrity.
- Molded Products:Compression or injection molding enables complex geometries, surface textures, and architectural facing finishes. Premium positioning in Kenyan interlocking systems reflects design flexibility for standardized housing specifications.
- Recycled Granules:Intermediate feedstock form sold to downstream processors with extrusion or molding capacity.
- Composite Materials:Polymer-mineral hybrid formulations enhancing compressive performance through inline filler injection.
Extruded products dominate volume throughput; molded products gain share fastest in premium architectural segments.
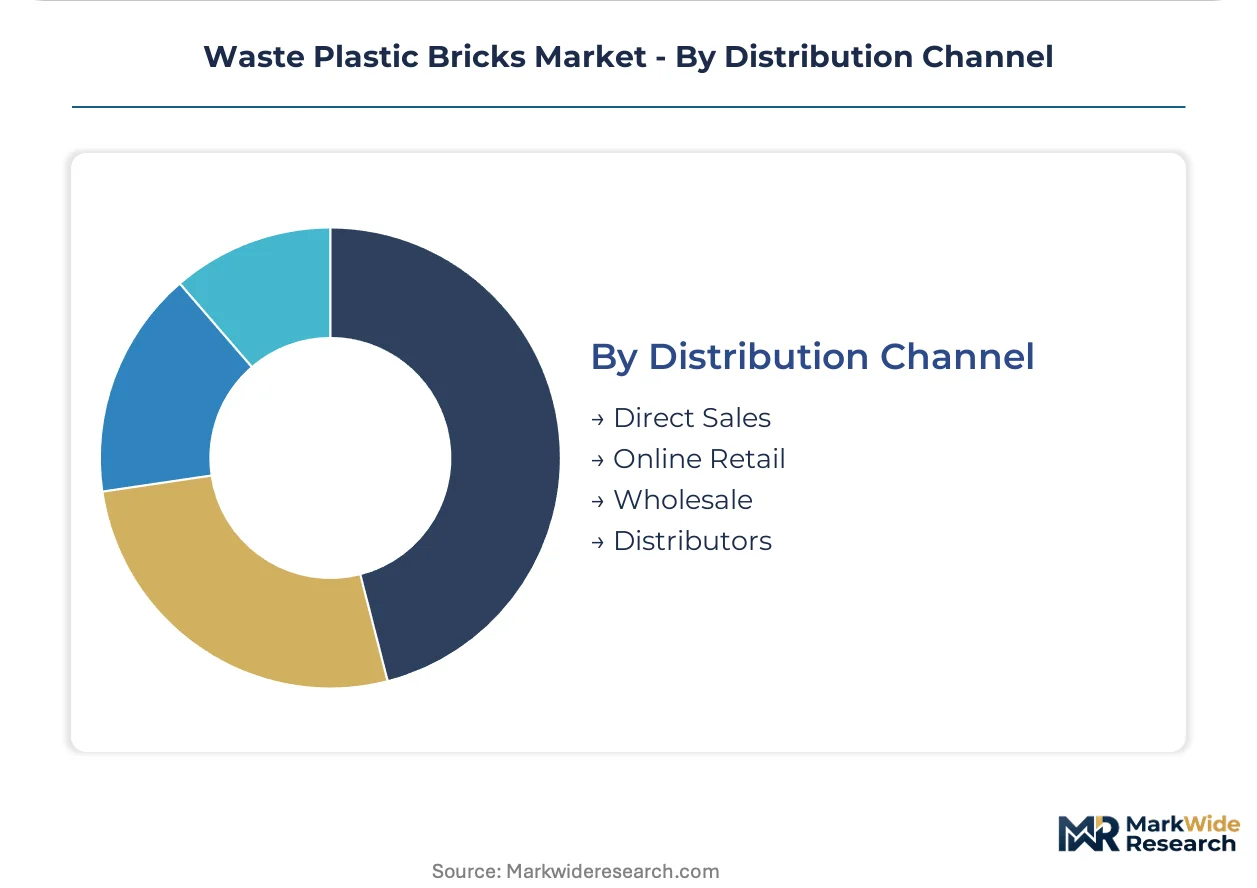
Distribution Channel:
Channel restructuring reflects unbundling of material procurement from construction contracts in public works.
- Direct Sales:Manufacturer-to-contractor relationships bypass traditional masonry supply intermediaries. Nairobi county housing projects route interlocking brick orders through centralized procurement platforms rather than site-based subcontractor networks.
- Distributors:Regional stockists maintain inventory for smaller contractors and rural projects with intermittent demand patterns.
- Wholesale:Volume aggregation for large infrastructure contractors with standardized material specifications.
- Online Retail:Digital platforms serving small-scale landscaping and residential renovation customers.
Direct sales capture procurement reform benefits; distributors maintain reach in fragmented rural demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are channeling production toward jurisdictions with streamlined certification pathways and subsidized feedstock collection infrastructure. Compliance cost differentials between South Asian and East African markets are accelerating processor migration toward construction-grade extrusion capacity.
India
Municipal infrastructure procurement and affordable housing programs are concentrating demand for load-bearing plastic bricks. The Bureau of Indian Standards certification framework mandates documented polymer traceability, compressing supply timelines for public contract eligibility. Gujarat and Maharashtra host the dominant extrusion clusters where processors restructure collection networks around verified post-consumer sources.
Kenya
Nairobi's informal settlement upgrading projects and national housing programs are standardizing interlocking plastic brick specifications. The National Environment Management Authority enforces plastic waste quotas that divert film streams toward construction material processors. Nairobi county government routes orders through centralized procurement platforms, displacing traditional masonry supply intermediaries.
United States
Marine plastic recovery incentives and extended producer responsibility frameworks are subsidizing ocean-bound plastic collection for construction feedstock. EPA guidelines on recycled material procurement influence state-level green building standards. California and Pacific Northwest coastal economies channel recovered polymers toward paving and landscaping applications.
Germany
REACH substance restrictions and EU Construction Products Regulation constrain virgin polymer eligibility, redirecting distributors toward certified recycled alternatives. The EU Green Deal's embodied carbon accounting rules favor recycled polymer masonry in public procurement. North Rhine-Westphalia and Bavaria concentrate composite molding capacity serving export-oriented construction material distribution.
Brazil
Informal recycling sector integration and municipal waste management reforms are expanding post-consumer polymer availability for construction applications. ANVISA and environmental agency coordination shapes feedstock quality standards for building materials. São Paulo's industrial corridor hosts emerging extrusion specialists targeting rural road and low-income housing segments.
Waste Plastic Bricks Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue architectural differentiation and marine plastic specialization. The vendor base stratifies across three tiers: composite molding specialists with public housing supply contracts, marine recovery operators leveraging feedstock cost advantages, and equipment-technology providers licensing extrusion systems. Strategic archetypes include certification-focused processors serving infrastructure ministries, ocean plastic aggregators with coastal collection networks, and hybrid material innovators blending polymers with mineral fillers. Dominant competitive moves encompass backward integration into feedstock collection and technology licensing partnerships for distributed manufacturing.
Among the named participants, WES-Tec Global and Sea2Brick occupy distinct positioning archetypes. WES-Tec Global exemplifies the composite molding specialist category with its anchoring presence in East African public housing schemes. Sea2Brick represents the marine recovery operator model, sustaining feedstock cost structures through coastal plastic collection networks. Gjenge Makers Ltd. sits within the interlocking systems specialization tier, deriving product forms from mixed post-consumer film streams. These three entities collectively illustrate the geographic and technological fragmentation shaping competitive dynamics.
| Leading Market Players |
|---|
| WES-Tec Global |
| Sea2Brick |
| Gjenge Makers Ltd. |
| Klean Industries |
| Precious Plastic |
| Plastic Bottle Bricks |
| Intec Building Elements |
| Greenmax |
| RePlast |
| Others |
Supply Flow & Price Mechanics
Polymer sorting technician clusters in Gujarat and Maharashtra compress labor-cost differentials into pricing-tier spreads, with skilled manual separation commanding premium wage rates that stratify BIS-certified units from uncertified alternatives. Regional wage arbitrage between South Asian extrusion hubs and East African molding operations feeds into interlocking brick premiums in Nairobi's informal settlement projects.
Pricing Analysis
Distributor margin layers absorb 12-18 point spreads between factory gate and county procurement platforms, with direct-to-contractor sales bypassing traditional masonry intermediaries in Kenyan housing schemes. Three-tier pricing structure across architectural facing, structural load-bearing, and basic paving grades reflects BIS certification investment and mineral filler injection complexity. Cost compression in standard extruded bricks intensifies because post-consumer polyethylene film prices track crude oil volatility. Municipal contractors in India exhibit highest price sensitivity due to fixed-budget public works mandates, while premium architectural specifiers in Germany tolerate 40-60 point markups for REACH-compliant textured finishes.
Supply Chain Analysis
Freight cost differentials between coastal marine plastic recovery nodes and inland extrusion clusters in India, Kenya, and Germany shape feedstock routing economics. Raw material dependencies center on post-consumer polyethylene film streams, mixed multi-layer packaging diverted under extended producer responsibility rules, and mineral fillers for compressive performance enhancement. Single-source vulnerability concentrates in Nairobi's narrow base of composite molding specialists serving county housing procurement surges. Distribution runs through centralized public procurement platforms displacing site-based subcontractor networks in East African affordable housing, with regional stockists maintaining rural reach in India's village road programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory momentum into procurement volume, with India's Plastic Waste Management Rules amendment mandating extended producer responsibility for multi-layered packaging waste and diverting previously non-recyclable streams toward construction-grade processors.
For Market Incumbents: Deploy backward integration into verified post-consumer collection networks to defend margin position against feedstock cost volatility threatening extrusion-dependent producers. Anchor BIS certification timelines through pre-submission technical consultations with Bureau of Indian Standards reviewers, compressing 14-18 month approval cycles. Counter emerging marine plastic aggregators by locking long-term offtake agreements with fast-moving consumer goods distributors under extended producer responsibility frameworks.
For New Entrants and Emerging Players: Enter via hybrid extrusion-injection system licensing partnerships targeting India's rural road construction expansion under Pradhan Mantri Gram Sadak Yojana eligibility criteria. White-space concentration sits in architectural facing products with textured surface finishes where design flexibility commands premium positioning above commodity structural grades. Kenya's county-level procurement platform centralization offers direct purchasing relationships bypassing traditional masonry supply intermediaries.
For Investors and Strategic Acquirers: Valuations sit cheapest among marine plastic recovery operators with coastal collection infrastructure sustaining feedstock cost advantages against virgin resin benchmarks. Long-term viability frames around embodied carbon accounting rule integration in green building certification schemes favoring recycled polymer masonry over fired clay alternatives. Acquisition target archetype: composite molding specialists with county-level public housing supply contracts in East Africa. Signal to watch: unbundling of material procurement from construction contracts in additional Indian states beyond current municipal infrastructure pilots.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Captures verified post-consumer feedstock streams under India's BIS traceability mandates. |
| Hybrid Extrusion-Injection Technology Licensing | Enables architectural facing products with textured finishes for premium positioning. |
| BIS Certification Pre-Submission Investment | Compresses 14-18 month review cycles for public infrastructure contract eligibility. |
| Marine Plastic Recovery Infrastructure Expansion | Sustains feedstock cost advantages against virgin polyethylene film benchmarks. |
| County Procurement Platform Direct Registration | Displaces traditional masonry intermediaries in Kenyan informal settlement upgrading. |
Methodological Framework
Multiple input streams — primary interviews with extrusion plant managers, municipal procurement officers, and polymer sorting technicians; secondary validation against Bureau of Indian Standards filings, Kenya National Environment Authority waste quota records, and EU Construction Products Regulation guidance documents; plus customs and trade flow data — were reconciled through bottom-up and top-down triangulation. Stakeholder roles engaged included infrastructure ministry specification writers, county housing procurement coordinators, fast-moving consumer goods sustainability leads, composite molding equipment suppliers, and marine plastic recovery network operators.
Cross-referencing historical capacity installation patterns against expert panel input on regulatory enforcement timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, application, manufacturing form, and distribution channel, with regional regulatory cluster intensity as an industry-specific overlay. CAGRs were derived from elasticity-adjusted demand curves incorporating public procurement mandate acceleration and feedstock availability constraints. Industry-specific forecast inputs included BIS certification queue lengths and extended producer responsibility diversion rate assumptions.
Inputs from Bureau of Indian Standards disclosure registers and Kenya county procurement platform award records were available through the study window; gaps in real-time post-consumer polymer spot pricing introduce uncertainty bands around margin compression scenarios. Forecasts incorporate documented assumptions on regulatory enforcement consistency and infrastructure budget allocation continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Fiber-Reinforced Plastic (FRP) Recycling Market
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Recyclability-Optimized Impact Modifiers for Polyolefins Market
Recycled Plastics
South Korea Recycled Plastics Market
Recycled Plastics
North America Recycled Plastics Market
Recycled Plastics
Iron Recycling Market
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Aluminum Recycling Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
Global Recycled Base Oil Market
Recycled Plastics
Global Recycled Asphalt Market
Recycled Plastics
Recycled Carbon Fiber Market
Recycled Plastics
Asia-Pacific Plastic Waste Management Market
Recycled Plastics
Malaysia Plastics Market
Recycled Plastics
Myanmar Plastics Market