
 Aluminium Tubes for OPC Drum Market | 2026-2036
Aluminium Tubes for OPC Drum Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Tubes for OPC Drum Market Insights
Photocopier OEMs is unwinding legacy supply relationships with generalist metal formers and redirecting volume toward tube specialists certified for OPC drum substrates. Guangzhou A & G Optoelectronics Technology Co., Ltd. dominates precision anodizing for photoconductor substrates in South China. Albéa Group leverages its cosmetic packaging heritage to compete for high-specification surface-finish contracts. ALLTUB anchors European supply through its laminated aluminium expertise.
Aluminium tubes for OPC drums are extruded or drawn cylindrical shells, typically 3003 or 5052 alloy, with controlled surface roughness between 0.2 and 0.8 micrometers Ra to support organic photoconductor layer adhesion in laser printing drums. Anodized aluminium commands premium positioning due to dielectric insulation requirements and wear resistance under corona wire charging cycles. Standard aluminium occupies volume tiers serving refurbished drum aftermarket channels, while alloy aluminium variants sustain margin pools in high-speed copier segments exceeding 60 pages per minute.
China's SAMR enforces GB/T standards for aluminium surface quality in electronic components, while Japan's METI promotes rare-earth recovery from end-of-life drums through its Act on Promotion of Recycling of Small Waste Electrical and Electronic Equipment. REACH restrictions on hexavalent chromium conversion coatings in Europe are forcing suppliers to adopt trivalent or organic coating chemistries. Stakeholders must monitor evolving surface-treatment regulations across manufacturing jurisdictions to preserve market access and avoid reformulation costs.
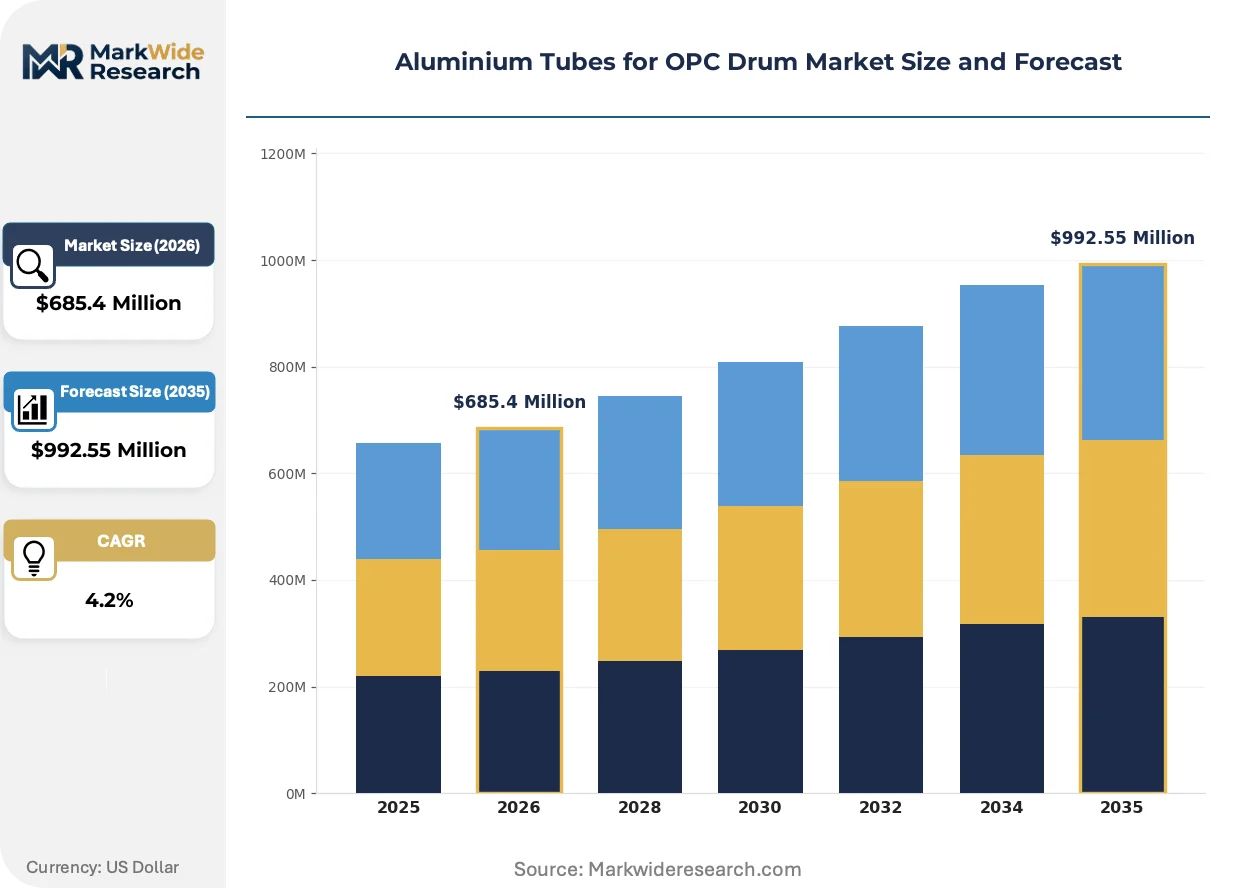
Market Dynamics
Photocopier OEM procurement is consolidating around certified tube specialists as surface-finish specifications tighten under evolving environmental regulations across East Asian manufacturing corridors.
Growth Catalysts
- China's GB/T surface quality standards:SAMR enforcement of aluminium substrate roughness tolerances is disqualifying generalist metal formers and redirecting volume toward precision-certified suppliers.
- High-speed copier segments:Drum substrates sustaining 60-plus pages per minute are requiring 5052 alloy variants with enhanced wear resistance under corona charging cycles.
- Japan's METI circular economy directives:Rare-earth recovery mandates from end-of-life drums are creating certified refurbishment channels that specify traceable aluminium substrate provenance.
Market Restraints
- Aluminium input cost volatility:LME price swings for 3003 and 5052 alloy billets compress margin pools for anodized premium-tier substrates.
- Hexavalent chromium conversion coating phase-out:REACH restrictions in Europe are forcing suppliers into costly trivalent chemistry reformulations without immediate price recovery mechanisms.
- Photoconductor layer substitution threat:Organic polymer drum substrates are displacing aluminium in low-duty-cycle printer segments under 20 pages per minute.
Strategic Opportunities
- India's electronics manufacturing PLI scheme:Subsidized copier and printer assembly corridors in Tamil Nadu and Karnataka are creating demand for localized aluminium tube supply.
- Trivalent anodizing chemistry convergence:Organic coating technologies meeting both REACH and GB standards are opening unified product platforms across European and Chinese markets.
- Aftermarket refurbishment channel expansion:Certified remanufacturing networks in Southeast Asia are specifying segregated aluminium substrate streams for second-life drum programs.
Industry Challenges
- Precision anodizing technician scarcity:Dielectric layer thickness control within 5-micron tolerances requires specialized electroplating expertise concentrated in Guangdong and Kyushu prefectures.
- Dual-certification timeline compression:Simultaneous GB/T and JIS compliance testing for cross-border OEM supply is extending qualification cycles by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Tubes for OPC Drum Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Aluminium, Anodized Aluminium, Alloy Aluminium, Pure Aluminium, Laminated Aluminium Application: Pharmaceutical Packaging, Food Containers, Cosmetic Holders, Chemical Storage, Aerospace Components End User: Manufacturing Units, Packaging Firms, Chemical Plants, Cosmetic Producers, Aerospace Manufacturers Manufacturing Stage: Forming, Printing, Coating, Assembly, Quality Inspection |
| Companies Covered | Guangzhou A & G Optoelectronics Technology Co., Ltd., Tubex Aluminium Tubes, Albéa Group, ALLTUB, LINHARDT Group GmbH, Montebello Packaging, ALPLA, MRK Packaging, Ningbo Everflare Packaging Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Tubes for OPC Drum Market Trends and Innovations
Surface treatment chemistry and procurement specification models are converging to reshape competitive positioning in precision aluminium substrates for photoconductor applications.
Pulsed anodizing with trivalent chromium alternatives is decomposing the historical premium attached to hexavalent conversion coatings. Japanese drum OEMs are adopting these processes at pilot scale ahead of full REACH enforcement. The technology is decomposing incumbent surface-finish margins and enabling new entrants with organic chemistry expertise to capture specification-driven contracts.
China's MEE dual carbon implementation rules are tightening energy-intensity benchmarks for aluminium extrusion operations. Guangdong-based substrate suppliers face power-rationing exposure during peak manufacturing seasons. Anodized tube producers with captive solar generation or hydroelectric sourcing are securing preferential supply allocations from copier OEMs.
Consolidated procurement contracts are displacing fragmented spot purchasing across photocopier OEM supply chains. Kyushu-based precision metal formers are capturing multi-year substrate agreements with volume commitments and embedded quality audits. This concentration is most visible in laser printer segments above 40 pages per minute where drum reliability directly affects warranty exposure.
Aluminium Tubes for OPC Drum Market Segmentation
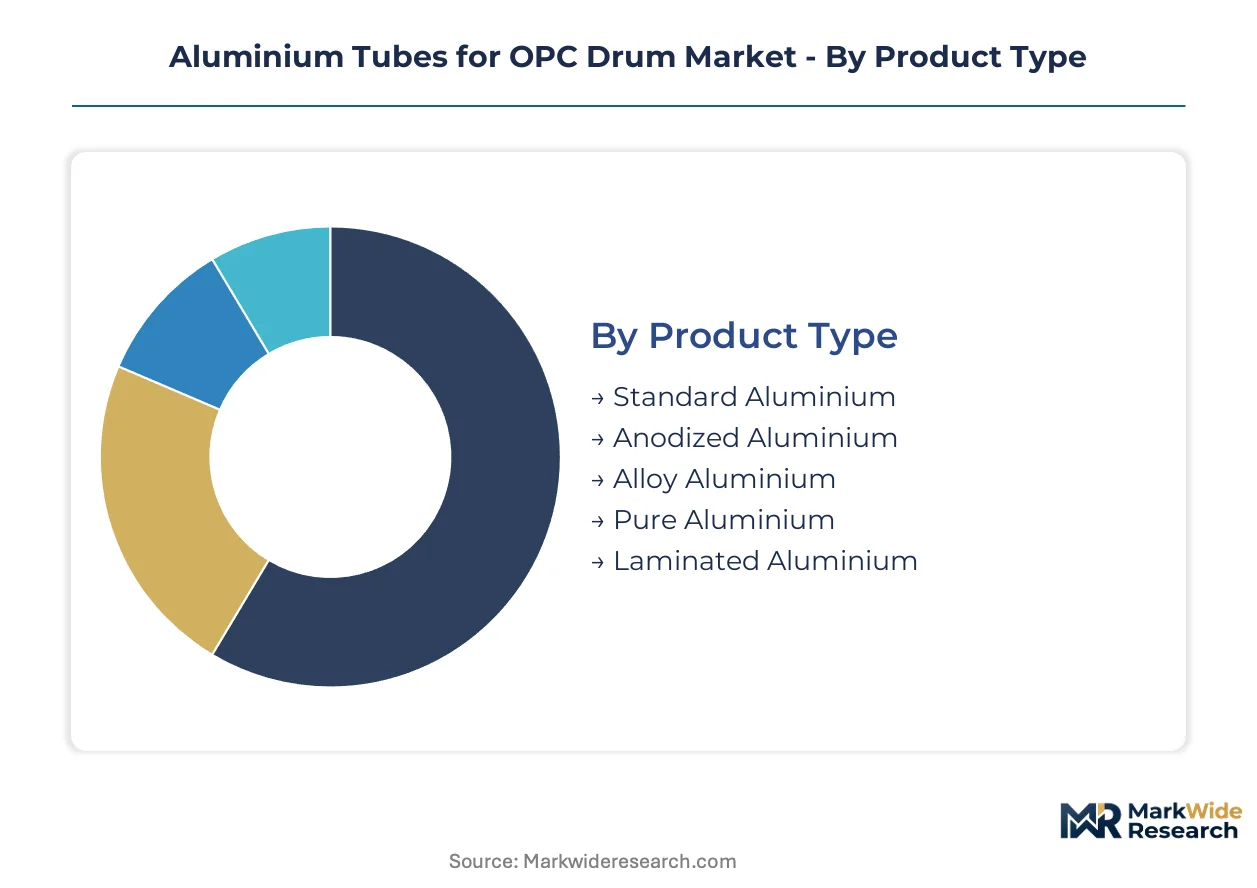
Segmentation in aluminium tubes for OPC drums reveals how regulatory pressure and end-use performance requirements fragment supply into distinct certification tiers. Each category exposes different margin pools and qualification barriers that determine supplier competitiveness.
Product Type:
REACH restrictions on hexavalent chromium and China's GB/T surface quality standards are bifurcating supply between legacy conversion coatings and trivalent or organic alternatives.
- Anodized Aluminium:Dielectric anodized layers between 5-25 microns thickness provide insulation under corona wire charging cycles. Japanese drum OEMs in Kyushu prefecture are consolidating procurement around trivalent-certified suppliers ahead of full REACH enforcement.
- Alloy Aluminium:5052 and 3003 alloy variants with controlled surface roughness between 0.2-0.8 micrometers Ra sustain organic photoconductor adhesion in high-speed copier segments exceeding 60 pages per minute.
- Standard Aluminium:Unanodized substrates serve refurbished drum aftermarket channels where cost minimization outweighs dielectric performance requirements.
- Pure Aluminium:1050 and 1100 grade tubes occupy price-sensitive remanufacturing segments with lower duty-cycle specifications.
- Laminated Aluminium:Polymer-aluminium composite structures address niche barrier requirements in specialty photoconductor configurations.
Anodized aluminium handles the majority of throughput; alloy aluminium is expanding most quickly on share as high-speed copier specifications tighten.
Application:
Surface-finish requirements vary sharply by end-use durability demands and regulatory exposure.
- Pharmaceutical Packaging:Aluminium tubes for drug delivery systems require FDA compliance and barrier properties unrelated to OPC drum functionality.
- Food Containers:FSSAI and FDA food-contact regulations govern surface migration limits for edible product containment.
- Cosmetic Holders:Albéa Group leverages cosmetic packaging heritage to compete for high-specification surface-finish contracts in beauty sector applications.
- Chemical Storage:ECHA REACH compliance for hazardous substance containment drives coated aluminium specifications in industrial chemical handling.
- Aerospace Components:AS9100 quality systems and NADCAP surface-treatment accreditation govern structural aluminium tube applications in aviation.
Cosmetic holders dominate current volume; pharmaceutical packaging is climbing the fastest as barrier specification premiums expand.
End User:
Procurement consolidation patterns differ by buyer scale and technical integration depth.
- Manufacturing Units:Integrated copier OEMs in Guangdong and Kyushu are unwinding legacy relationships with generalist metal formers and redirecting volume toward certified tube specialists.
- Packaging Firms:Contract converters serving multiple drum OEMs face dual-certification timeline compression for simultaneous GB/T and JIS compliance testing.
- Chemical Plants:Industrial users specify corrosion-resistant surface treatments for process equipment unrelated to photoconductor applications.
- Cosmetic Producers:Beauty sector buyers prioritize aesthetic surface finish over dielectric performance metrics.
- Aerospace Manufacturers:Boeing and Airbus tier-1 suppliers impose NADCAP-accredited anodizing requirements with full material traceability.
Manufacturing units command the deepest procurement consolidation; packaging firms are gaining share fastest as OEM outsourcing accelerates.
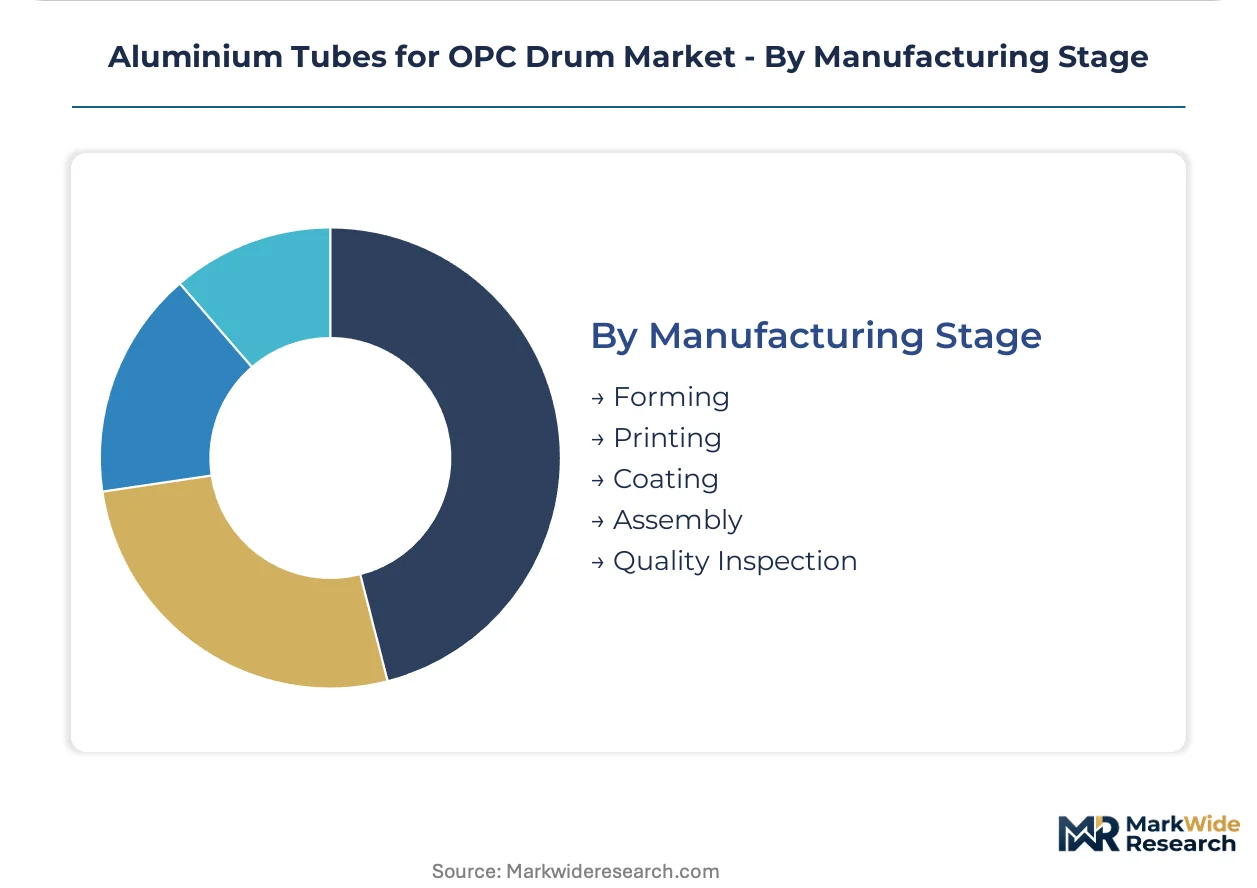
Manufacturing Stage:
Energy-intensity benchmarks under China's MEE dual carbon rules are reshaping stage-specific competitive positioning.
- Forming:Extrusion and drawing operations face power-rationing exposure during peak seasons; producers with captive solar or hydroelectric sourcing secure preferential allocations.
- Printing:Gravure and digital surface marking for drum identification requires alignment with OEM traceability systems.
- Coating:Anodizing and conversion coating stages concentrate technical capability scarcity, with dielectric layer thickness control within 5-micron tolerances requiring specialized electroplating expertise.
- Assembly:Integration of aluminium substrates with photoconductor layers and drive gears occurs at drum OEM facilities or contracted module suppliers.
- Quality Inspection:Surface roughness profilometry and dielectric breakdown testing enforce GB/T and JIS specification compliance before shipment.
Coating represents the most constrained stage on capacity; forming is expanding fastest as energy-resilient capacity comes online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese drum OEMs in Kyushu prefecture source precision aluminium substrates from Guangdong extrusion specialists, creating a transnational supply corridor governed by converging GB/T and JIS surface-quality standards.
China
Guangzhou A & G Optoelectronics Technology Co., Ltd. dominates precision anodizing for photoconductor substrates across South China. SAMR enforces GB/T standards for aluminium surface roughness tolerances between 0.2 and 0.8 micrometers Ra. Guangdong and Zhejiang manufacturing corridors face power-rationing exposure under MEE dual carbon implementation rules.
Japan
Kyushu prefecture clusters host concentrated drum OEM procurement consolidating around certified tube specialists. METI circular economy directives mandate rare-earth recovery from end-of-life drums, creating traceable substrate provenance requirements. Japanese manufacturers are piloting trivalent chromium anodizing ahead of full REACH enforcement.
Germany
LINHARDT Group GmbH anchors European laminated aluminium expertise for barrier-sensitive applications. ECHA REACH restrictions on hexavalent chromium conversion coatings force suppliers toward trivalent chemistry reformulations. Bavaria and North Rhine-Westphalia host precision metal forming operations serving cross-border OEM supply.
India
Electronics manufacturing PLI scheme subsidies are drawing copier and printer assembly corridors into Tamil Nadu and Karnataka. BIS alignment with international surface-quality standards is accelerating local certification requirements. Domestic aluminium tube supply localization remains underdeveloped relative to assembly capacity expansion.
United States
Montebello Packaging and regional converters serve aftermarket refurbishment channels with standard aluminium substrates. FDA compliance requirements for pharmaceutical packaging applications create specification overlap with cosmetic tube producers. Midwest industrial corridors maintain legacy extrusion capacity without precision anodizing specialization.
Aluminium Tubes for OPC Drum Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, creating a bifurcated structure where public companies leverage capital access for capacity expansion while family-owned fabricators defend niche surface-finish expertise. The vendor base stratifies into three archetypes: precision anodizing specialists, laminated barrier experts, and volume extrusion generalists. M&A activity concentrates on acquiring trivalent-certified coating capabilities, while greenfield investments target energy-resilient extrusion capacity under China's dual carbon rules.
Among Chinese precision fabricators, Guangzhou A & G Optoelectronics Technology Co., Ltd. exemplifies the anodizing-specialist archetype, while Ningbo Everflare Packaging Co., Ltd. occupies a position within the volume-oriented tier. European laminated aluminium expertise is represented by LINHARDT Group GmbH and ALLTUB, both anchoring barrier-technology positioning. These named entities represent distinct competitive vectors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Guangzhou A & G Optoelectronics Technology Co., Ltd. |
| Tubex Aluminium Tubes |
| Albéa Group |
| ALLTUB |
| LINHARDT Group GmbH |
| Montebello Packaging |
| ALPLA |
| MRK Packaging |
| Ningbo Everflare Packaging Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day qualification cycles for dual GB/T and JIS certification concentrate procurement leverage among anodizing specialists in Guangdong and Kyushu, compressing margin pools for generalist extruders while amplifying price premiums for trivalent-certified substrate suppliers serving high-speed copier OEMs.
Pricing Analysis
Hexavalent-to-trivalent anodizing chemistry transition gaps separate legacy conversion coating premiums from emerging organic-coating price floors. Three-tier pricing structure across premium anodized, certified alloy, and standard refurbishment tiers tracks certification depth and surface roughness tolerances. Pricing pressure stems from LME aluminium billet volatility feeding into 3003 and 5052 alloy input costs. Aftermarket refurbishment channels exhibit highest price sensitivity; integrated copier OEMs in Kyushu prefecture clusters demonstrate lowest sensitivity due to warranty exposure on drum reliability.
Supply Chain Analysis
China and Japan anchor precision aluminium substrate production for photoconductor applications. Guangdong extrusion corridors feed anodizing specialists while Kyushu prefecture clusters host concentrated drum OEM procurement. Raw material flows draw from LME-linked 3003 and 5052 alloy billet suppliers and rare-earth recovery streams under METI circular economy mandates. Single-source vulnerability concentrates in precision anodizing technician pools across Guangzhou and Fukuoka industrial zones. Distribution runs through consolidated procurement contracts with embedded quality audits displacing fragmented spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified refurbishment channel expansion represents a service-attach opportunity outpacing hardware growth, as traceable substrate provenance requirements under Japan's METI directives create recurring revenue streams from end-of-life drum recovery programs.
For Market Incumbents: Secure multi-year substrate agreements with volume commitments and embedded quality audits to lock out emerging trivalent-certified competitors. Defend against organic polymer drum substitution in sub-20 pages per minute segments by accelerating trivalent anodizing chemistry convergence across GB/T and REACH compliance standards. Prioritize captive solar or hydroelectric sourcing under China's MEE dual carbon rules to secure preferential supply allocations during peak manufacturing seasons. For New Entrants and Emerging Players: Lead with trivalent-certified coating capabilities targeting India's electronics manufacturing PLI scheme corridors in Tamil Nadu and Karnataka where localized aluminium tube supply remains underdeveloped relative to assembly capacity expansion. White-space opportunities concentrate in certified remanufacturing networks across Southeast Asia specifying segregated aluminium substrate streams. Go-to-market positioning should emphasize unified product platforms satisfying both European REACH and Chinese GB standards. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision anodizing operations as energy-resilient capacity under dual carbon rules requires captive renewable generation investments. Long-term viability across the analysis window favors acquisition targets with established trivalent certification and OEM qualification relationships rather than greenfield extrusion assets. The signal to watch is consolidation velocity among Guangdong-based substrate suppliers facing power-rationing exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Trivalent Anodizing Certification Investment | REACH-compliant coating chemistry opens unified access to European and Chinese OEM procurement channels. |
| Backward Integration into Renewable Energy | Captive solar generation secures preferential supply allocations under MEE dual carbon implementation rules. |
| Certified Refurbishment Channel Partnership | Traceable substrate provenance requirements under METI directives create recurring revenue from end-of-life recovery. |
| Dual GB/T and JIS Compliance Qualification | Cross-border OEM supply contracts demand simultaneous surface-quality standard testing extending competitive moats. |
| Localized Supply Capacity in India | Electronics manufacturing PLI scheme subsidies in Tamil Nadu and Karnataka outpace domestic aluminium tube infrastructure. |
Research Methodology
Desk research of customs trade data, SAMR regulatory filings, and METI circular economy directives preceded structured interviews with precision anodizing technicians, copier OEM procurement managers, and aluminium extrusion plant engineers. Primary fieldwork combined with secondary validation against SEC 10-K disclosures from listed packaging specialists and BIS certification databases. Bottom-up volume triangulation across alloy grade, surface treatment tier, and end-use application segments converged with top-down market sizing from trade flow analysis.
Variance decomposition across product type, manufacturing stage, and regional regulatory cluster dimensions shaped the analytical framework throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against macro aluminium demand indicators and electronics manufacturing output projections. Industry-specific forecast inputs incorporated SAMR enforcement timelines for GB/T surface roughness standards and METI rare-earth recovery mandate implementation trajectories.
The analysis sits within stated boundaries; outcomes outside sustained OEM procurement consolidation or accelerated organic polymer substitution would require recalibration. Forecasts reflect assumptions regarding trivalent chemistry adoption velocity and dual carbon rule enforcement intensity. Recalibration cycles align with material shifts in LME aluminium price bands and cross-border certification standard harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Spain PVC Pipes Market
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
Saudi Arabia PVC Pipes Market
Pipes and Tubes
Pipe and Tube Cutters Market
Pipes and Tubes
Stainless Steel Plumbing Pipes Market
Pipes and Tubes
Global Municipal Pipes Market
Pipes and Tubes
Plastic Pipe Market
Pipes and Tubes
China Industrial Hoses Market
Pipes and Tubes
Global Titanium Tube Market
Pipes and Tubes
Global Hydraulic Thermoplastic Hose and Couplings Market
Pipes and Tubes
Water and Wastewater Pipe Market
Pipes and Tubes
Cold Drawn Seamless (CDS) Steel Pipes Market
Pipes and Tubes
Composite Pipes Market
Pipes and Tubes
France PVC Pipes Market
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
Pipes and Fittings Market