
 Global Zinc Stearate Market | 2026-2036
Global Zinc Stearate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Zinc Stearate Market Foresight
Buyer concentration in the polymer processing sector is broadening as mid-sized compounders across Southeast Asia and India gain purchasing power alongside established multinational resin producers. Baerlocher GmbH leverages its backward integration into stearic acid feedstock to control cost volatility across European and Asian plants. Peter Greven GmbH & Co. KG anchors its position through specialized pastille formulations for pharmaceutical-grade applications. Faci S.p.A competes on manufacturing scale at its Italian and Malaysian facilities, supplying both powder and emulsion grades to rubber additive distributors.
Zinc stearate is a zinc salt of stearic acid, typically containing 10–12% zinc content by weight, produced via direct fusion of zinc oxide with stearic acid or precipitation in aqueous media; it functions primarily as a lubricant, release agent, and acid scavenger in polymer processing and personal care formulations. Powder grades dominate volume throughput in plastics compounding, though emulsion forms are capturing faster growth in water-based paint and coating systems where solvent reduction is mandated. Pharmaceutical and personal care applications command premium positioning due to stringency around heavy metal limits and microbial specifications.
REACH registration requirements in Europe, FDA food-contact substance notifications in the United States, and BIS certification protocols in India collectively elevate compliance costs for metallic stearate producers seeking multi-jurisdiction market access. The EU F-Gas Regulation indirectly pressures PVC processors to adopt additives compatible with lower-emission blowing agents, altering lubricant selection criteria in construction profiles. Stakeholders must monitor evolving heavy metal thresholds across pharmacopeias and polymer contact regulations to anticipate reformulation cycles and qualification timelines.
Market Dynamics
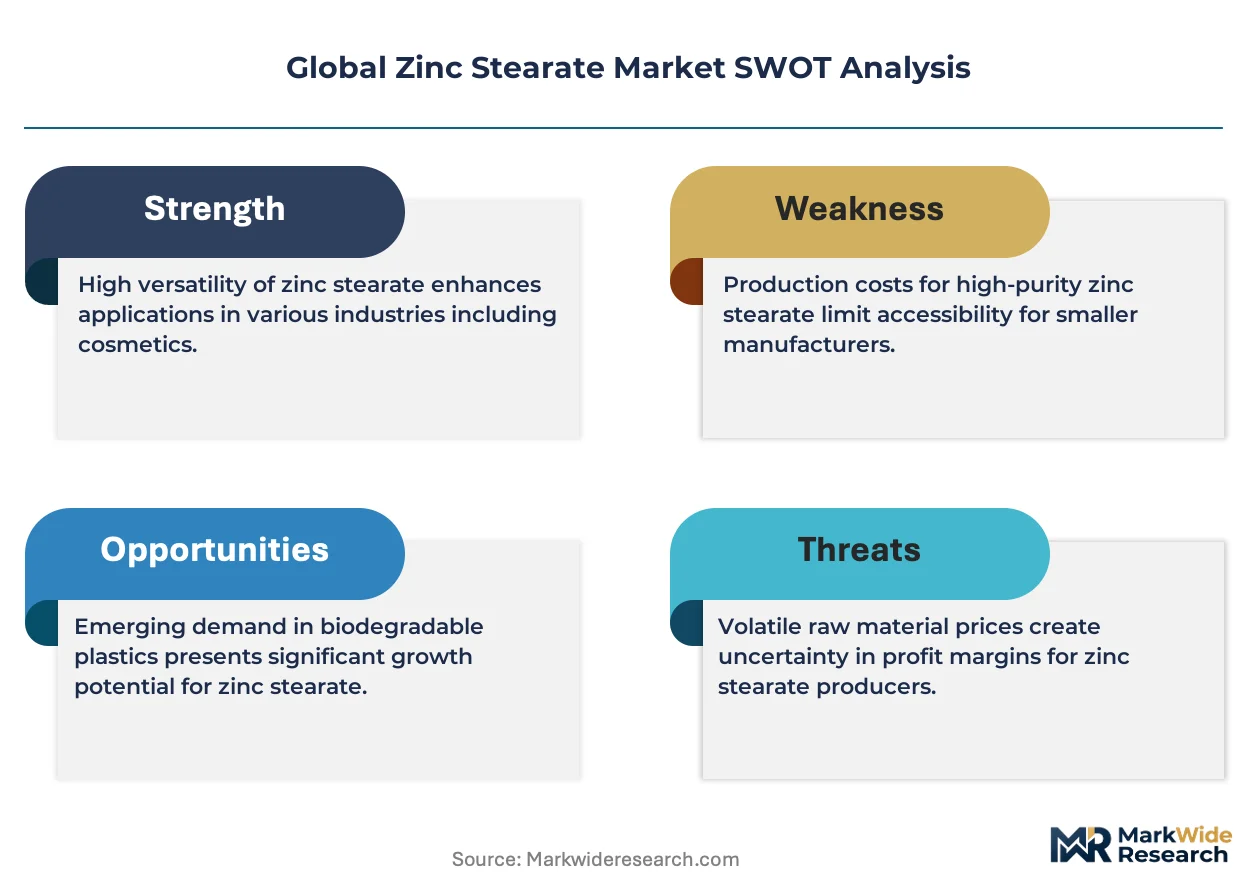
REACH registration deadlines and FDA food-contact substance notifications are compressing qualification timelines for zinc stearate producers, forcing simultaneous investment in heavy metal purification and documentation systems across multi-jurisdiction supply chains.
Growth Catalysts
- PVC stabilization demand:Southeast Asian polymer processors are expanding emulsion-grade consumption for construction profiles and wire insulation, driven by regional infrastructure buildouts.
- REACH compliance thresholds:ECHA's tightening purity specifications for metallic stearates are accelerating replacement of lower-grade alternatives in European pharmaceutical and personal care formulations.
- India's compounding sector:Domestic lubricant and plastics compounding capacity expansions in Gujarat and Maharashtra are concentrating regional demand for powder-grade zinc stearate.
Market Restraints
- Stearic acid feedstock volatility:Palm oil and tallow price swings directly transmit to zinc stearate production economics, compressing margin stability for non-integrated manufacturers.
- European supply concentration:Backward-integrated producers in Germany and Italy control critical feedstock access, creating entry barriers for new entrants in Western Europe.
- Water-based coating substitution:Calcium stearate and synthetic wax alternatives are capturing share in select paint applications where cost sensitivity exceeds performance requirements.
Strategic Opportunities
- Indonesia's underpenetrated rubber sector:Tire and industrial rubber additive distributors are seeking localized emulsion supply to reduce import dependency from Malaysian and European sources.
- EU F-Gas Regulation alignment:PVC processors adapting to lower-emission blowing agent mandates require lubricant reformulation, creating specification windows for qualified additive suppliers.
- Pharmaceutical-grade pastille formats:CDSCO and USP heavy metal limit convergence is opening premium positioning for producers with dedicated GMP production lines.
Industry Challenges
- Multi-jurisdiction certification timelines:BIS, REACH, and FDA notification parallel tracks extend product qualification cycles to 18–24 months for new grade introductions.
- Analytical chemistry capability gaps:ICP-MS heavy metal testing and microbial specification validation require capital investment that mid-tier compounders struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Zinc Stearate Market |
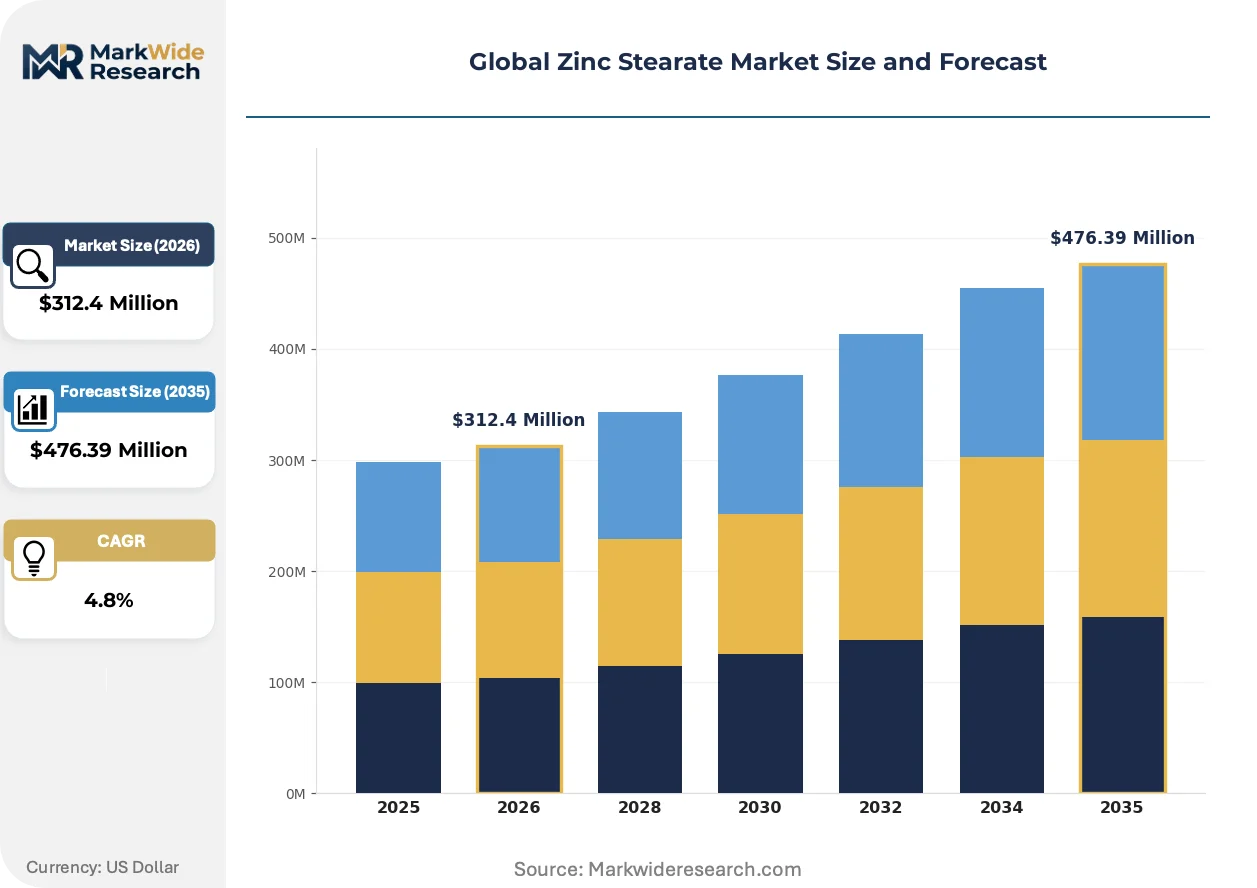
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Emulsion, Granules, Pastilles Application: Plastics, Rubber Additives, Paints & Coatings, Cosmetics, Pharmaceuticals End User Industry: Polymer Processing, Personal Care, Pharmaceutical Manufacturing, Lubricant Production Packaging Type: Bags, Drums, Bulk Containers, Boxes |
| Companies Covered | Baerlocher GmbH, Dover Chemical Corporation, Faci S.p.A, Peter Greven GmbH & Co. KG, Norac Additives LLC, PMC Biogenix, Jiangxi Hongyuan Chemical & Industrial Co., Ltd., Pratham Stearchem, Valtris Specialty Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Zinc Stearate Market Shifts & Advancements
Continuous aqueous precipitation technology and automated pastille forming systems are reshaping production economics, while regulatory convergence on heavy metal limits is compressing the viable supplier base to technically capable producers.
Continuous aqueous precipitation technology replaces batch fusion methods for zinc stearate emulsion production, enabling real-time quality adjustment and reduced energy intensity. Mid-sized Southeast Asian compounders are adopting these systems to meet just-in-time delivery requirements from multinational resin producers. This manufacturing shift is decentralizing supply chain control away from traditional European powder-grade specialists toward regional emulsion producers.
The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon blowing agents in PVC construction profiles, forcing lubricant additive reformulation to maintain process stability with alternative foaming chemistries. German and Italian profile extruders are qualifying new additive packages ahead of 2027 phase-down milestones. Construction-grade zinc stearate specifications are tightening accordingly, with emulsion stability under modified processing conditions becoming a decisive selection criterion.
Long-term supply agreements with fixed pricing clauses are fragmenting as compounders shift toward spot-market purchasing with quality-audit contingencies. Southeast Asian rubber additive distributors and Indian plastics compounders are leading this transition, prioritizing flexibility over volume commitments. Vietnam and Thailand represent the most visible geographies where this purchasing behavior shift is disrupting established distributor relationships.
Global Zinc Stearate Market Segmentation
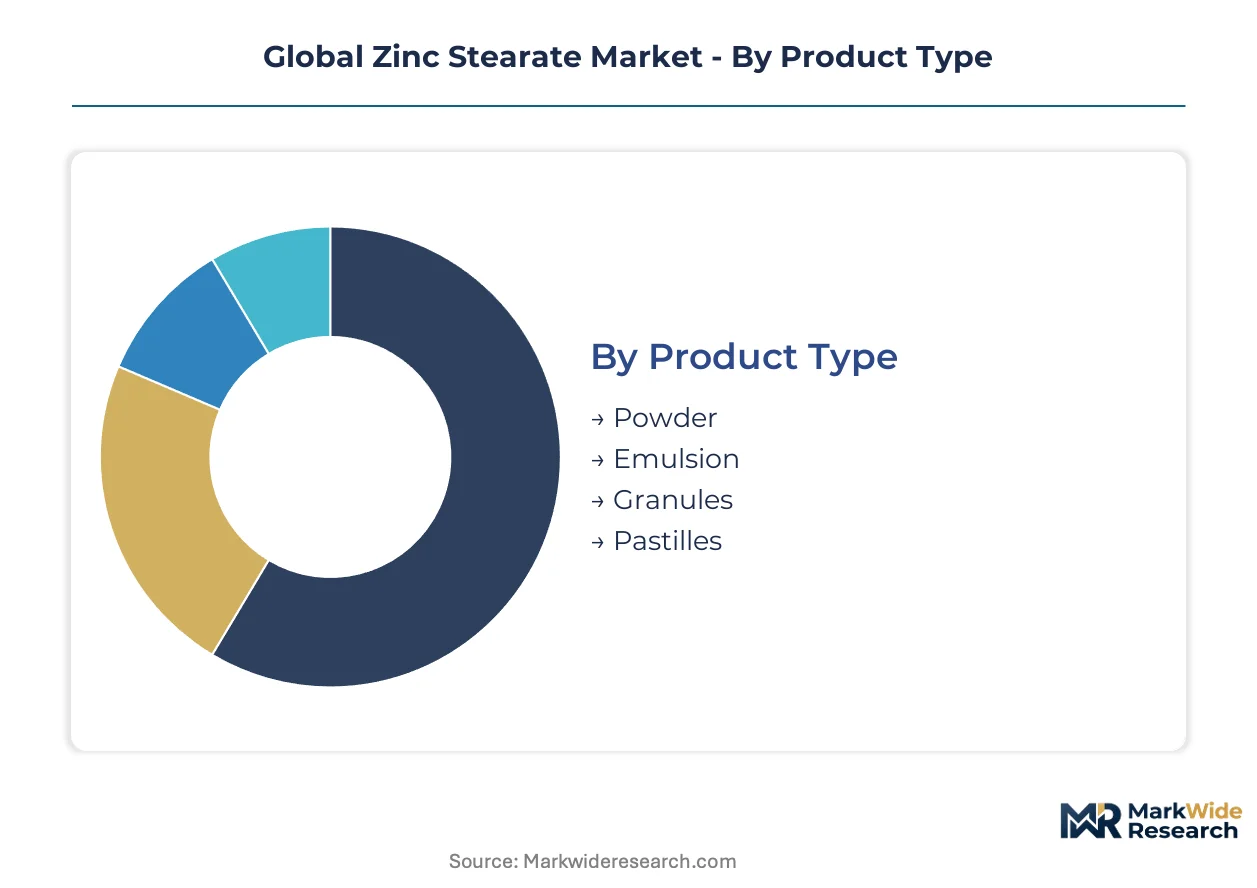
Zinc stearate specifications diverge sharply across processing requirements, with physical form dictating dispersion characteristics and regulatory compliance tiers. Segment boundaries are hardening as REACH and FDA thresholds force technical separation between industrial and pharmaceutical-grade supply chains.
Product Type:
Supply concentration favors powder-grade specialists with captive stearic acid production, while emulsion capacity decentralizes toward Southeast Asian rubber processing clusters.
- Powder:Dry-ground particles with 10–12% zinc content serve as the workhorse lubricant in PVC compounding and polyolefin processing. Demand concentrates in Gujarat and Maharashtra, where domestic plastics compounders scale capacity to serve infrastructure wire and cable markets.
- Emulsion:Aqueous dispersion systems enable water-based incorporation in latex gloves and tire release formulations. Malaysian and Indonesian rubber additive distributors are expanding offtake as regional tire production scales to reduce import dependency from European sources.
- Granules:Low-dust agglomerated forms target automated feeding systems in large-volume polymer plants. German profile extruders specify granule grades for F-Gas Regulation compliance in construction PVC.
- Pastilles:Molded cylindrical shapes command premium positioning in pharmaceutical tablet pressing and cosmetic powder blending. CDSCO and USP heavy metal limit convergence restricts viable supply to GMP-certified producers with dedicated pastille lines.
Today's leader: Powder. Tomorrow's challenger: Emulsion.
Application:
Cost tier stratification separates commodity lubricant applications from certified pharmaceutical and personal care segments requiring dedicated analytical capabilities.
- Plastics:PVC stabilization and polyolefin lubrication consume the largest volume share, with construction profiles and wire insulation driving specifications. Southeast Asian processors are qualifying emulsion grades for water-based additive systems.
- Rubber Additives:Mold release and anti-tack functions in tire manufacturing favor emulsion stability under high-shear mixing conditions. Indonesian distributors seek localized supply to displace Malaysian and European imports.
- Paints & Coatings:Flatting agent and suspension aid functions in water-based architectural coatings are gaining share as solvent reduction mandates expand. Calcium stearate alternatives capture cost-sensitive segments.
- Cosmetics:Micronized powder grades serve as texture modifiers and opacifiers in pressed powders and creams. Heavy metal purification to pharmacopeia standards elevates pricing tiers.
- Pharmaceuticals:Tablet lubrication and mold release in solid dose manufacturing require microbial specification validation and ICP-MS heavy metal documentation. BIS and FDA notification parallel tracks extend qualification timelines.
Volume concentrates in Plastics. Value migrates toward Pharmaceuticals.
End User Industry:
Customer type fragmentation is accelerating as mid-sized compounders gain technical sophistication and direct supplier engagement.
- Polymer Processing:PVC compounders and masterbatch producers specify zinc stearate for acid scavenging and processing lubricity. Just-in-time delivery requirements favor regional emulsion producers with continuous precipitation capability.
- Personal Care:Cosmetic formulators demand micronized grades with tight particle size distribution for skinfeel optimization. Heavy metal thresholds below 10 ppm zinc separate premium from industrial supply tiers.
- Pharmaceutical Manufacturing:Solid dose and topical formulators require USP-NF compliance with dedicated GMP production lines. CDSCO certification is becoming mandatory for Indian domestic supply.
- Lubricant Production:Metalworking fluid and grease compounders utilize zinc stearate as corrosion inhibitor and thickener component. Price volatility in stearic acid feedstock compresses margin stability for non-integrated blenders.
Momentum sits with Polymer Processing. Margin protection depends on Pharmaceutical Manufacturing certification depth.
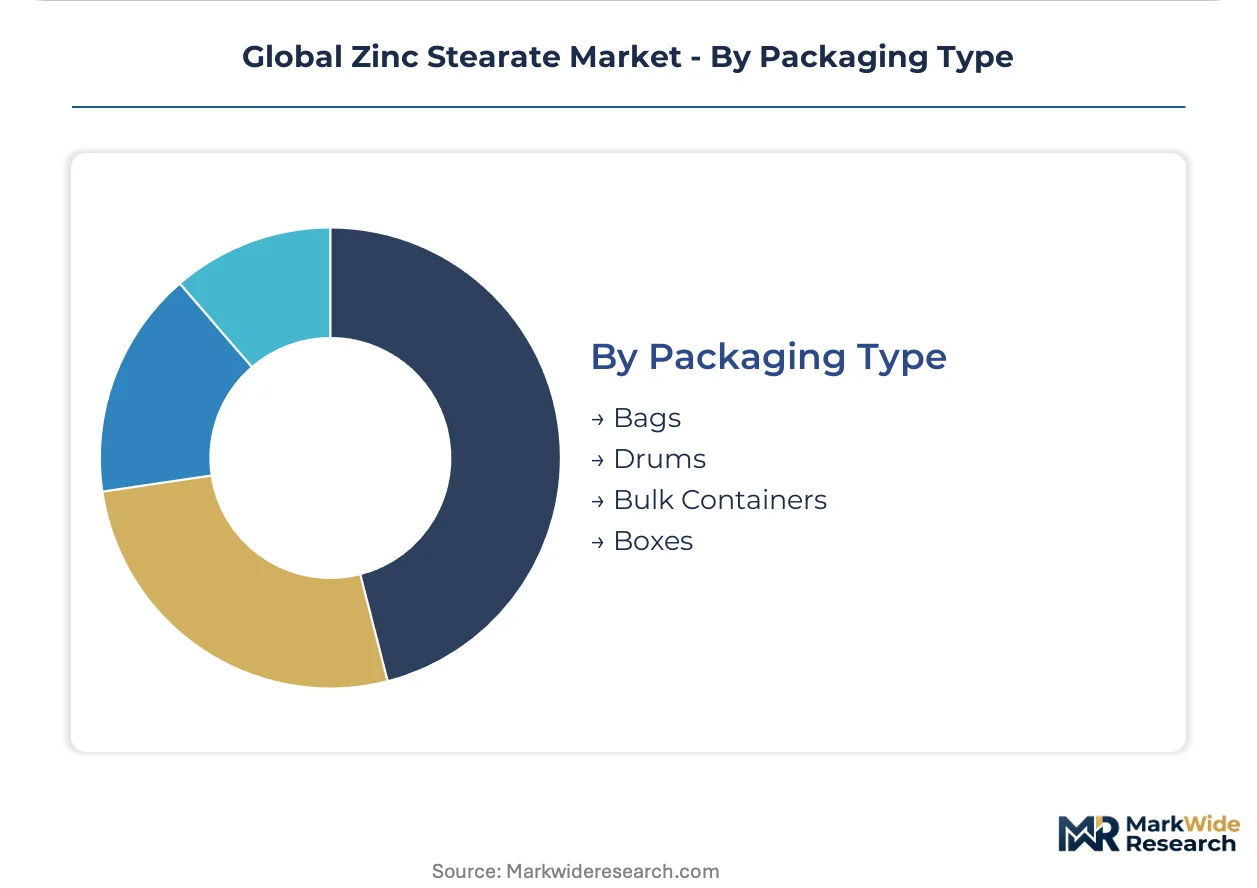
Packaging Type:
Volume scale and handling automation drive packaging selection, with bulk systems penetrating large compounder accounts and unitized formats serving distributed rubber additive channels.
- Bags:Multi-wall paper or PE-lined sacks dominate powder-grade shipment to plastics compounders in India and Southeast Asia. Standard 25 kg units align with manual handling in mid-tier processing facilities.
- Drums:Steel and fiber drums serve emulsion and pastille grades requiring moisture protection and stacking stability. Pharmaceutical distributors specify UN-certified drums for international shipment.
- Bulk Containers:Flexible intermediate bulk containers and tanker deliveries penetrate large-volume polymer processors in Germany and Italy with automated unloading systems.
- Boxes:Corrugated unit packaging supports pharmaceutical and cosmetic sample distribution with lot traceability labeling for GMP compliance.
Bags anchor throughput. Bulk Containers capture efficiency gains at scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical talent pools in polymer chemistry and analytical testing anchor geographic demand concentration. European regulatory expertise and Asian manufacturing scale create complementary regional specializations. Localized emulsion production capability determines competitive access in rubber processing clusters.
Germany
PVC profile extruders in Baden-Württemberg and North Rhine-Westphalia drive lubricant additive specifications. ECHA's REACH registration deadlines force heavy metal documentation upgrades across metallic stearate supply chains. The Cologne-Düsseldorf industrial corridor hosts backward-integrated producers with captive stearic acid production.
United States
Masterbatch compounders in Texas and Ohio specify zinc stearate for polyolefin processing lubricity. FDA food-contact substance notifications compress qualification timelines for pharmaceutical-grade grades. The Gulf Coast petrochemical corridor concentrates demand from wire and cable insulation manufacturers.
India
Domestic plastics compounders in Gujarat and Maharashtra scale capacity for infrastructure cable markets. BIS certification protocols and CDSCO pharmaceutical standards elevate purity thresholds for metallic stearates. The Ahmedabad-Vadodara industrial belt anchors powder-grade consumption for PVC stabilization.
China
Rubber additive distributors in Shandong and Jiangsu provinces seek localized emulsion supply for tire manufacturing. GB standards and environmental compliance inspections filter smaller producers from technical-grade supply tiers. The Yangtze River Delta concentrates personal care formulators demanding micronized powder grades.
Indonesia
Tire producers in Java and Sumatra expand rubber additive consumption to serve regional automotive supply chains. Import substitution policies favor localized emulsion production over Malaysian and European sourcing. The Cilegon industrial zone attracts investment in aqueous precipitation capacity for mold release applications.
Global Zinc Stearate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers. Market structure tilts toward consolidation among European feedstock-integrated producers while Asian emulsion capacity fragments regionally. Three archetypes dominate: backward-integrated chemical majors with captive stearic acid supply, regional emulsion specialists with continuous precipitation systems, and pharmaceutical-grade pastille producers with GMP-certified lines. Capacity expansion and qualification documentation investments represent the dominant competitive moves as multi-jurisdiction certification requirements harden.
Among German chemical producers, Baerlocher GmbH and Peter Greven GmbH & Co. KG exemplify the feedstock-integrated archetype with European manufacturing footprints. Faci S.p.A represents the scale-driven multinational model with Italian and Malaysian production assets. These three entities anchor the supplier base that controls critical stearic acid access and pharmaceutical-grade certification depth.
| Leading Market Players |
|---|
| Baerlocher GmbH |
| Dover Chemical Corporation |
| Faci S.p.A |
| Peter Greven GmbH & Co. KG |
| Norac Additives LLC |
| PMC Biogenix |
| Jiangxi Hongyuan Chemical & Industrial Co., Ltd. |
| Pratham Stearchem |
| Valtris Specialty Chemicals |
| Others |
Supply & Pricing Matrix
Polymer processing compounders in Gujarat and Maharashtra anchor volume procurement, locking in contract-based long-term offtake agreements with backward-integrated producers while spot-market purchasing gains traction among Southeast Asian rubber additive distributors seeking flexibility over price certainty.
Pricing Analysis
Commodity spot pricing for powder-grade zinc stearate diverges sharply from pharmaceutical-grade pastille contracts bundled with certification documentation and ICP-MS heavy metal validation. Three-tier pricing structure across pharmaceutical, industrial, and economy grades reflects certification depth and analytical capability investment. Cost compression in emulsion-grade supply is intensifying as Malaysian and Indonesian producers scale continuous precipitation capacity. Rubber additive distributors in Southeast Asia exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize qualification reliability over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from European PVC profile extruders and Indian plastics compounders require qualification of at least two suppliers per grade tier, fragmenting volume concentration across Germany, Italy, and Malaysia. Stearic acid feedstock draws from palm oil plantations in Indonesia and Malaysia alongside tallow rendering in Europe and North America. Single-source vulnerability concentrates in pharmaceutical-grade pastille supply where GMP-certified production lines remain limited. Distribution runs through regional chemical distributors with technical service capabilities, supplemented by direct mill relationships for large-volume polymer processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe and BIS certification requirements in India create divergent cost structures, rewarding producers with multi-jurisdiction qualification depth.
For Market Incumbents: To counter emulsion-grade price erosion from Southeast Asian continuous precipitation entrants, deepen captive stearic acid integration and accelerate pharmaceutical-grade pastille capacity expansion ahead of CDSCO-USP heavy metal limit convergence. Prioritize long-term offtake renegotiation with Indian infrastructure cable compounders before domestic capacity fully scales. For New Entrants and Emerging Players: A 40-60% price-point gap between European pharmaceutical-grade pastilles and Indian industrial powder grades creates entry space for mid-tier emulsion specialists targeting Indonesian tire manufacturers seeking localized mold release supply. Penetrate the Cilegon industrial zone through technical partnership with established rubber additive distributors rather than direct mill qualification. For Investors and Strategic Acquirers: Specialty chemical conglomerates with existing metallic stearate portfolios are the most active acquirer in this space, seeking GMP-certified pastille production lines to complete pharmaceutical-grade coverage. Five-to-ten-year viability hinges on regulatory certification asset depth rather than volume scale alone. Monitor ECHA heavy metal threshold revision timelines as inflection signal for reformulation-driven supplier switching.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stearic Acid | Baerlocher GmbH's captive feedstock supply insulates margin stability against palm oil volatility. |
| Pharmaceutical-Grade Pastille Capacity Expansion | Peter Greven GmbH & Co. KG's GMP-certified lines capture CDSCO-USP convergence premium positioning. |
| Continuous Precipitation Technology Deployment | Faci S.p.A's Malaysian facility enables real-time quality adjustment for just-in-time rubber additive delivery. |
| Regional Emulsion Production in Indonesia | Localized Cilegon capacity reduces import dependency for Java-based tire manufacturers. |
| Multi-Jurisdiction Certification Investment | Parallel REACH-FDA-BIS qualification extends product introduction timelines but locks in premium tier access. |
Research Methodology
Bottom-up polymer processing demand modeling reconciled against top-down metallic stearate production tracking forms the analytical core of this study. Primary interviews with PVC compounder procurement leads, rubber additive distribution managers, pharmaceutical formulation scientists, and metallic stearate plant operations directors were cross-validated against secondary sources including ECHA registration databases, FDA food-contact substance notifications, BIS certification records, and customs trade flow data. Top-down supply-side validation incorporated capacity announcements from German and Italian feedstock-integrated producers alongside Southeast Asian emulsion specialist expansion disclosures.
Input-output matrices mapped zinc stearate consumption intensity across PVC stabilization, rubber mold release, pharmaceutical tablet lubrication, and paint flatting applications, with segmentation dimensions covering physical form grade, end-use industry, and regional regulatory cluster. CAGRs were derived from trend-line extrapolation of historical consumption patterns adjusted for capacity buildout visibility and qualification timeline constraints. Forecast inputs incorporated EU F-Gas Regulation phase-down milestones and India's infrastructure cable demand projections.
The model assumes a particular technology adoption path; alternative pathways for aqueous precipitation versus batch fusion methods would alter the outlook for regional supply concentration. Forecasts reflect assumptions around REACH registration maintenance, BIS enforcement intensity, and stearic acid feedstock price band stability. Deviation in ECHA heavy metal threshold revision timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Isosorbide Market
Additives
Global UV Stabilizers Market
Additives
Antiscalants/Scale Inhibitors Market
Additives
Green Polymer Additive Market
Additives
Flux Injection System Market
Additives
Tris Nonylphenyl Phosphite Market
Additives
Spain Anti Caking Market
Additives
Thermal Conductive Additives Market
Additives
Feed Additives Market
Additives
Fluoropolymer Additives Market
Additives
Plastic Antioxidants Market
Additives
Weighing Agents Market
Additives
Conditioning Agent Market
Additives
Tackifier Market
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Fuel Additives Market