
 Global Fiberglass Pipe Market | 2026-2036
Global Fiberglass Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fiberglass Pipe Market Analysis
Project finance tied to desalination and oilfield water injection infrastructure is rewriting competitive entry rules for fiberglass pipe suppliers. Future Pipe Industries leverages its integrated manufacturing footprint across the Middle East to sustain cost advantages in large-diameter contracts. Amiblu Holding GmbH specializes in flowtite technology for water and sewer applications, anchoring its position in European municipal markets. Saudi Arabian Amiantit Co. dominates regional petrochemical demand through localized production and captive resin supply.
Fiberglass pipe consists of thermosetting resin matrices reinforced with glass fiber filaments, manufactured through filament winding or centrifugal casting processes to achieve corrosion resistance and strength-to-weight ratios exceeding steel alternatives. Its primary purpose is transporting corrosive fluids, pressurized gases, and abrasive slurries across oilfield, chemical, and water infrastructure networks. Reinforced pipe commands the deepest margin pools in offshore and high-pressure oilfield service, while standard pipe occupies the highest volume tier in municipal water networks. Piping systems applications lead overall value contribution, though waste water management segments are gaining share as utilities prioritize lifecycle cost over initial capital outlay.
API standards for oilfield equipment, EPA corrosion prevention mandates, and ISO 14692 for petroleum and natural gas industries collectively shape product certification requirements and procurement specifications. REACH compliance in Europe and EPA regulations in the United States restrict certain resin chemistries, pushing manufacturers toward vinyl ester and epoxy formulations with lower environmental footprints. Stakeholders must monitor how evolving carbon accounting rules under the EU Green Deal and parallel frameworks affect material selection criteria in infrastructure tenders.
Market Dynamics
Corrosion-resistant mandates from the EPA are accelerating substitution away from metallic piping in oilfield and chemical infrastructure, while Saudi Aramco's water injection programs concentrate large-diameter demand in the Middle East. This regulatory-demand nexus is compressing procurement timelines and favoring suppliers with integrated resin production.
Growth Catalysts
- EPA corrosion prevention mandates:Operators in US oilfields must replace failing steel infrastructure, creating immediate pull for vinyl ester and epoxy formulations in sour service environments.
- Saudi Aramco water injection programs:Large-diameter reinforced piping contracts for oilfield infrastructure are concentrating procurement power with integrated regional manufacturers.
- Filament winding automation:Advanced winding robotics are reducing labor content and enabling consistent wall thickness in high-pressure offshore risers.
Market Restraints
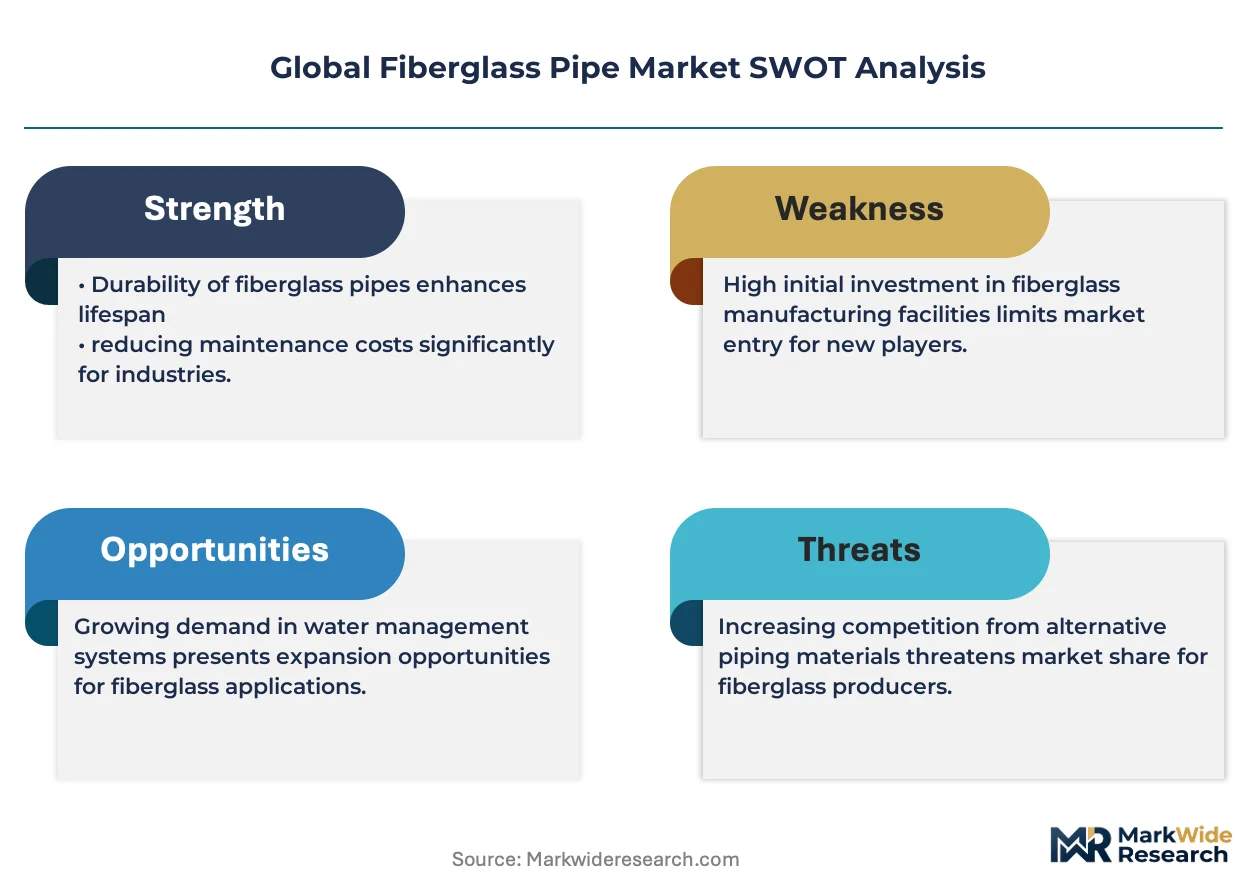
- Resin cost volatility:Epoxy and vinyl ester feedstocks track petrochemical indices, compressing margins when crude prices spike without corresponding pipe price pass-through.
- Glass fiber supply concentration:Three Chinese producers control over half of E-glass roving supply, creating geographic concentration risk for non-integrated pipe manufacturers.
- Steel pipe residual competitiveness:Carbon steel maintains cost advantage in non-corrosive, low-pressure water transmission where lifecycle analysis is not mandated.
Strategic Opportunities
- India municipal water infrastructure:The country's national Jal Jeevan Mission targets universal tap water access, opening volume demand for corrosion-resistant distribution networks.
- Hydrogen transport compatibility:Fiberglass-reinforced thermoset pipes are emerging as viable conduits for hydrogen blending in natural gas networks, a new application vector.
- EU Green Deal carbon accounting:Infrastructure tenders are beginning to weight embodied carbon, favoring lightweight composite pipes over steel in transportation-intensive projects.
Industry Challenges
- API 15HR/15S certification timelines:Qualification testing for high-pressure oilfield service requires 18-24 months, gating supplier entry into premium offshore segments.
- Field joint integrity:Installation quality variability in adhesive-bonded or laminated connections creates warranty exposure and limits adoption in safety-critical sour gas service.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fiberglass Pipe Market |
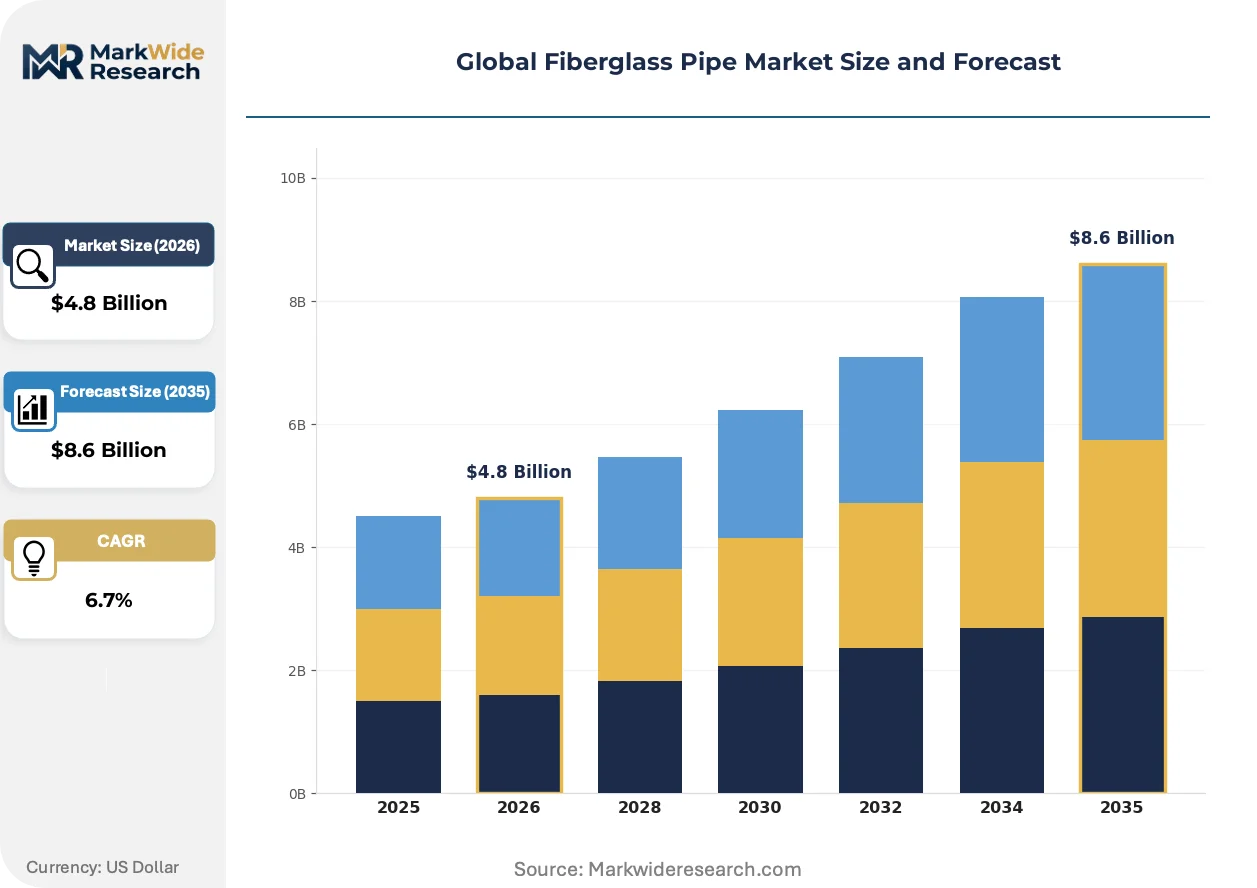
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pipe, Duct Pipe, Reinforced Pipe, Lining Pipe End User: Oil & Gas, Water Treatment, Construction, Chemical Application: Piping Systems, Drainage, HVAC, Waste Water Management Installation: Above Ground, Below Ground, Retrofit, New Construction |
| Companies Covered | Future Pipe Industries, Amiblu Holding GmbH, Saudi Arabian Amiantit Co., NOV, Chemical Process Piping Pvt. Ltd., Fibrex Corporation, Hengrun Group Co., Ltd., Graphite India Limited, Gruppo Sarplast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fiberglass Pipe Market Emerging Trajectories
Material science advances and regulatory carbon accounting are converging to alter specification criteria in infrastructure procurement. Suppliers are responding with formulation innovations and manufacturing automation that compress delivered cost while expanding pressure-temperature envelopes.
Thermoplastic-lined fiberglass pipe is rendering obsolete unlined thermoset alternatives in abrasive slurry service. Mining operators in Chile and Australia are specifying these hybrid constructions for tailings transport, where the thermoplastic barrier extends service life threefold. The technology is compressing maintenance budgets and displacing rubber-lined steel in high-wear applications.
REACH restrictions on styrene emissions are forcing European manufacturers toward closed-mold and vacuum infusion processes. ECHA's 2023 reclassification of unsaturated polyester resin components is accelerating capital deployment in emission-controlled production lines. German and Dutch suppliers are capturing municipal water contracts by leading this environmental compliance transition.
Lifecycle cost modeling is displacing first-cost procurement in Middle Eastern water infrastructure. Saudi utilities now mandate 50-year total cost of ownership analysis, weighting corrosion resistance and installation speed over unit pipe price. This behavioral shift favors integrated suppliers with localized technical service capabilities over trading houses.
Global Fiberglass Pipe Market Segmentation
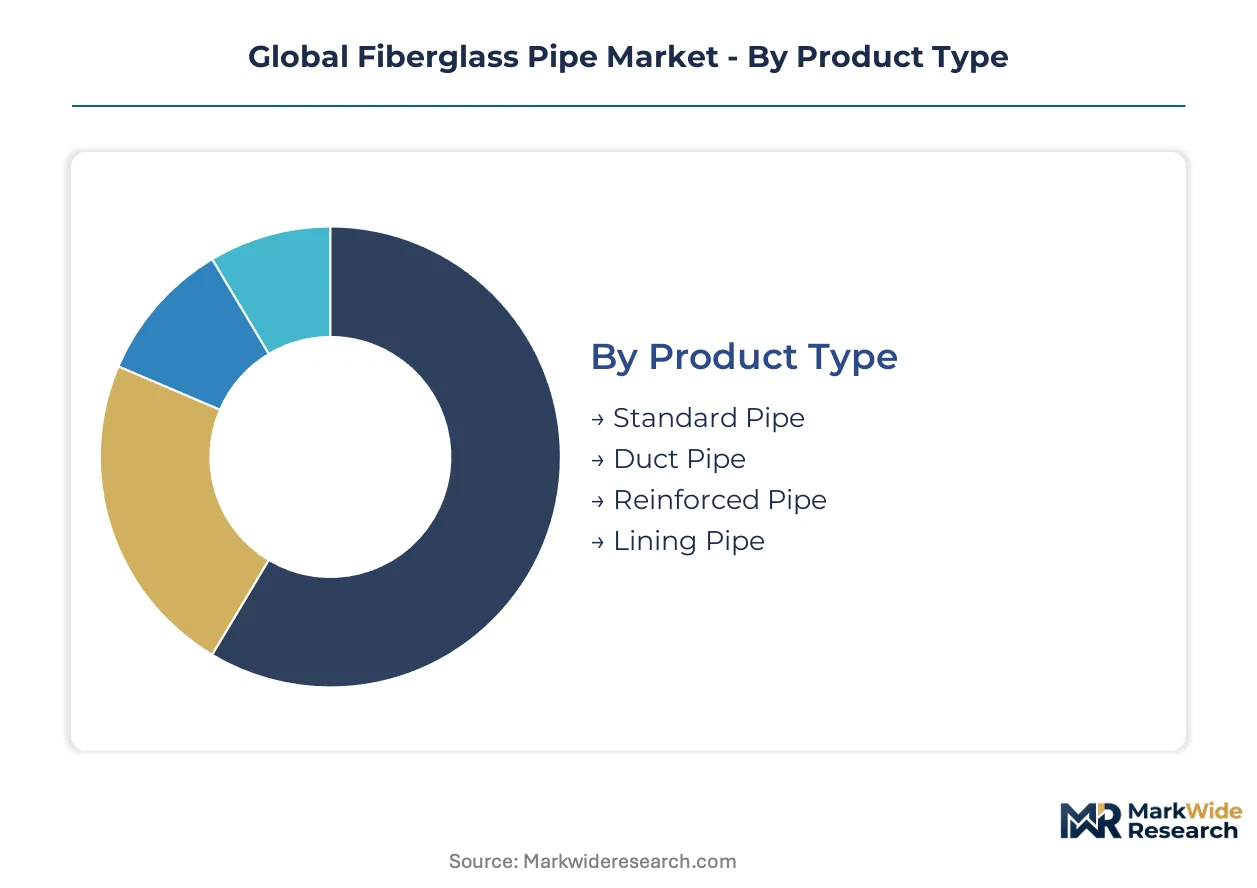
Segmentation in fiberglass pipe markets reveals how corrosion resistance requirements, pressure specifications, and installation constraints fragment demand across incompatible product architectures. Procurement specifications diverge sharply between oilfield operators seeking API-certified high-pressure systems and municipal utilities prioritizing lifecycle cost over initial capital outlay.
Product Type:
Mature commodity formats dominate volume, while engineered reinforced variants command premium positioning in sour service environments.
- Reinforced Pipe:Glass fiber filaments wound at precise angles around thermoset resin cores achieve burst pressures exceeding 1,500 psi. Saudi Aramco's water injection programs concentrate procurement of large-diameter reinforced systems where sour gas compatibility is mandatory.
- Standard Pipe:Filament-wound or centrifugally cast constructions using chopped strand mat and orthophthalic polyester resins serve non-pressurized water transmission. India's Jal Jeevan Mission drives volume demand for corrosion-resistant distribution networks in rural municipalities.
- Duct Pipe:Lower-pressure ventilation and fume extraction systems utilize corrosion-resistant thermoset formulations without structural reinforcement layers. Chemical processing facilities specify these for acid gas handling where metal fatigue risks dominate.
- Lining Pipe:Thermoplastic barrier layers bonded to fiberglass substrates extend service life in abrasive slurry transport. Mining tailings operations in Chile and Australia specify hybrid constructions where threefold wear resistance justifies material premium.
Reinforced pipe handles the majority of throughput in oilfield applications; lining pipe is the fastest mover on share as mining operators retrofit abrasive service infrastructure.
End User:
Cost tier stratification separates capital-intensive energy infrastructure from municipal procurement governed by total lifecycle accounting.
- Oil & Gas:Sour service, water injection, and offshore riser applications demand API 15HR/15S certification with 18-24 month qualification timelines. EPA corrosion prevention mandates accelerate substitution of failing steel infrastructure in US shale basins.
- Water Treatment:Desalination brine handling and reverse osmosis concentrate lines require vinyl ester formulations resistant to chloride attack. Saudi utilities now mandate 50-year total cost of ownership analysis, weighting installation speed over unit pipe price.
- Chemical:Process piping for acids, caustics, and solvents operates across temperature envelopes that degrade thermoplastic alternatives. REACH restrictions on styrene emissions force European manufacturers toward closed-mold production for this segment.
- Construction:Building services and infrastructure projects utilize standard and duct formulations where fire ratings and smoke toxicity specifications govern material selection. German and Dutch suppliers capture contracts by leading environmental compliance transitions.
Oil & gas commands the deepest margin pools; water treatment is expanding most quickly as desalination capacity builds accelerate across water-stressed economies.
Application:
Volume concentration in fluid transport networks contrasts with emerging positioning in thermal and waste management systems.
- Piping Systems:Pressurized and gravity-fed fluid transport across oilfield gathering networks, municipal distribution grids, and industrial process plants constitutes the core value contribution. Filament winding automation reduces labor content and enables consistent wall thickness in high-pressure offshore risers.
- Waste Water Management:Sewer force mains, effluent discharge lines, and industrial wastewater handling prioritize corrosion resistance over pressure rating. Utilities prioritize lifecycle cost over initial capital outlay in this application, favoring integrated suppliers with localized technical service.
- Drainage:Stormwater and agricultural drainage systems utilize lower-cost chopped strand constructions where soil chemistry and UV exposure dictate resin selection.
- HVAC:Chilled water distribution and cooling tower piping in commercial buildings exploit thermal insulation properties and condensation resistance.
Piping systems anchors overall value contribution; waste water management is gaining share fastest as infrastructure aging forces replacement cycles.
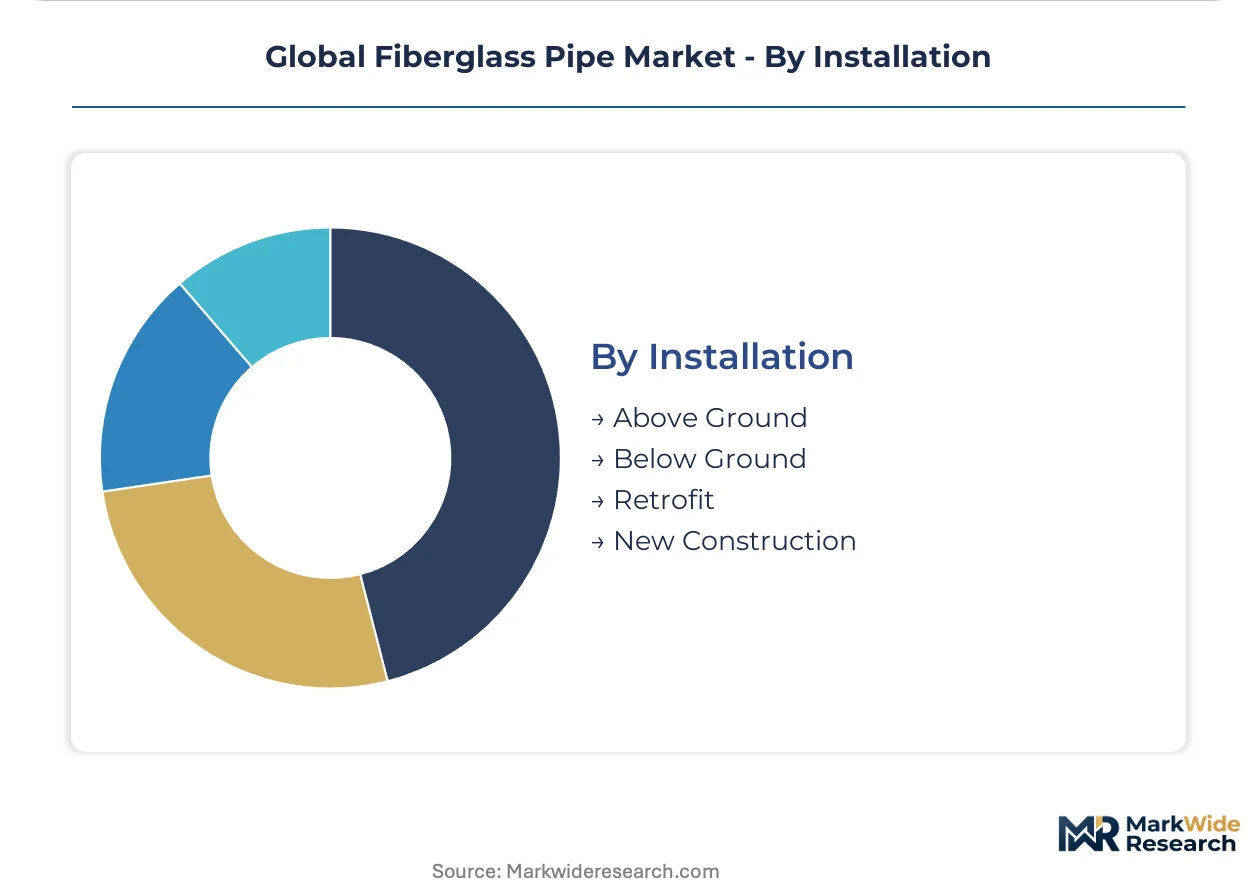
Installation:
Geography and project phase determine specification rigor, with below-ground and retrofit applications imposing stricter joint integrity requirements.
- Below Ground:Buried oilfield flowlines, municipal water mains, and sewer force mains require soil load-bearing calculations and cathodic protection compatibility. Field joint integrity in adhesive-bonded connections creates warranty exposure that limits adoption in safety-critical sour gas service.
- New Construction:Greenfield projects allow integrated design of pipe specifications with pumping and valving infrastructure, optimizing diameter and pressure class selection. Saudi Aramco's infrastructure programs concentrate procurement power with integrated regional manufacturers.
- Above Ground:Process piping, offshore platform risers, and exposed distribution networks prioritize UV resistance and thermal expansion accommodation.
- Retrofit:Slip-lining and pipe bursting applications demand tight dimensional tolerances and flexible joint configurations for insertion through deteriorated host pipes.
Below ground handles the majority of installed length; retrofit is climbing the fastest as aging steel infrastructure reaches replacement thresholds in mature economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Saudi Arabia's oilfield corridors while Indian municipal procurement compresses margins through volume aggregation. This asymmetry shapes where suppliers deploy integrated manufacturing versus trading-house distribution models.
United States
EPA corrosion prevention mandates accelerate steel replacement in Permian and Bakken shale basins. FERC pipeline safety directives tighten material traceability requirements for interstate transmission. Houston-Gulf Coast petrochemical clusters anchor domestic filament winding capacity for sour service applications.
Saudi Arabia
Saudi Aramco water injection and oilfield infrastructure programs concentrate large-diameter reinforced pipe demand. SFDA industrial material standards align procurement with API certification tiers. Eastern Province manufacturing zones host integrated resin-to-pipe operations serving regional petrochemical networks.
Germany
ECHA REACH restrictions on styrene emissions force closed-mold process adoption in chemical process piping. EU Green Deal carbon accounting weights embodied emissions in infrastructure tenders. Ruhr industrial corridors and Bavarian chemical parks specify emission-compliant vinyl ester formulations.
India
Jal Jeevan Mission rural water distribution targets universal tap access, opening volume demand for corrosion-resistant networks. BIS infrastructure standards mandate lifecycle cost analysis for municipal procurement. Gujarat and Maharashtra industrial corridors concentrate filament winding capacity for domestic water projects.
China
MIIT industrial upgrading programs prioritize composite substitution in chemical and offshore applications. GB standards for fiberglass-reinforced plastics tighten pressure vessel certification. Shandong and Jiangsu manufacturing clusters supply E-glass roving to domestic and export pipe fabricators.
Global Fiberglass Pipe Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on resin and roving supply. The vendor base stratifies between integrated manufacturers with captive raw material production and project-specific fabricators bidding on municipal tenders. Two archetypes dominate: regional champions leveraging geographic proximity to oilfield operators, and technology licensors monetizing proprietary winding processes. Competitive moves center on backward integration into resin production and automation of filament winding lines to compress labor content.
Among Middle East-based integrated producers, Saudi Arabian Amiantit Co. anchors regional petrochemical demand through localized manufacturing footprints. German specialists Amiblu Holding GmbH exemplify the technology-licensing archetype in European municipal water markets. Future Pipe Industries represents the multi-regional platform model with manufacturing presence spanning Middle East and Asian growth corridors.
| Leading Market Players |
|---|
| Future Pipe Industries |
| Amiblu Holding GmbH |
| Saudi Arabian Amiantit Co. |
| NOV |
| Chemical Process Piping Pvt. Ltd. |
| Fibrex Corporation |
| Hengrun Group Co., Ltd. |
| Graphite India Limited |
| Gruppo Sarplast |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese E-glass roving production is compressing input costs for integrated pipe manufacturers while squeezing margin buffers for non-captive fabricators across Southeast Asian export corridors. This utilization imbalance rewards suppliers with backward integration into resin and fiber production, enabling price discipline in large-diameter oilfield contracts.
Pricing Analysis
The customization-premium spread between API 15HR-certified reinforced systems and standard municipal water pipe exceeds threefold, with sour service qualification timelines adding eighteen-month carrying costs to configured orders. Price differentiation hinges on certification tier and filament winding automation level, with robotic production lines commanding fifteen-point margin premiums over manual operations. Cost compression in standard pipe intensifies as Indian volume aggregators consolidate procurement under Jal Jeevan Mission tenders. Municipal utilities exhibit highest price sensitivity, while Saudi Aramco's water injection programs prioritize technical compliance over unit economics.
Supply Chain Analysis
Export-control restrictions on advanced filament winding robotics from German and Japanese equipment suppliers limit technology transfer to emerging manufacturing bases in India and Vietnam. Geographic supply concentration centers on China for E-glass roving, Saudi Arabia for vinyl ester resin feedstocks, and Germany for precision winding equipment. Raw material dependencies span epoxy and vinyl ester formulations, borosilicate glass fiber, and thermoplastic barrier layers for lined constructions. Single-source vulnerability in high-modulus glass fiber creates procurement risk for offshore riser fabricators. Distribution runs through integrated regional manufacturers serving oilfield operators directly, with municipal segments served via distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fiberglass pipe market represents early-cycle expansion as hydrogen transport compatibility opens new application vectors in natural gas network retrofits. EPA corrosion mandates and Middle Eastern water injection programs provide durable demand anchors across energy and infrastructure verticals.
For Market Incumbents: Build certification moats through accelerated API 15HR/15S qualification pipelines to gate premium offshore segments against emerging Asian competitors. Prioritize captive resin production in Eastern Province manufacturing zones to defend margin position against vinyl ester feedstock volatility. Field joint integrity warranties represent the primary vulnerability limiting adoption in sour gas service; investment in automated adhesive bonding systems addresses this exposure. For New Entrants and Emerging Players: Municipal water infrastructure in secondary Indian cities offers the most penetrable volume tier, with BIS lifecycle cost mandates favoring corrosion-resistant alternatives over incumbent steel. Target Jal Jeevan Mission distribution networks through partnerships with established EPC contractors possessing localized installation capabilities. Thermoplastic-lined hybrid constructions for mining tailings transport present a technical differentiation angle with limited incumbent specialization. For Investors and Strategic Acquirers: Long-term, this sits as a materials-substitution play because fiberglass pipe displaces steel across corrosive service environments where lifecycle cost analysis governs procurement. Acquisition targets should emphasize integrated manufacturers with captive resin supply and regional oilfield relationships. The signal to watch is carbon accounting integration in EU infrastructure tenders, which would accelerate composite adoption in transportation-intensive projects.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vinyl Ester Resin | Captive supply from Saudi petrochemical feedstocks insulates margin from crude price volatility. |
| Filament Winding Automation Deployment | Robotic production lines reduce labor content and enable consistent wall thickness in high-pressure risers. |
| API 15HR/15S Certification Investment | Qualification for sour service opens premium offshore contracts with Saudi Aramco and Permian operators. |
| Hydrogen Transport Compatibility Testing | Validation for hydrogen blending in natural gas networks creates first-mover positioning in emerging application. |
| Closed-Mold Process Transition | REACH-compliant production lines capture European municipal water contracts under ECHA emission restrictions. |
Methodological Framework
The analysis maps reinforced pipe, standard pipe, duct pipe, and lining pipe sub-sectors, each validated through procurement directors at oilfield operators, municipal water utility engineers, and chemical process plant managers. Primary interviews with filament winding equipment manufacturers and vinyl ester resin suppliers were cross-referenced against customs data, API certification registries, and SEC filings from publicly traded composite manufacturers. Bottom-up volume estimates from regional production clusters were triangulated with top-down demand projections from infrastructure spending databases.
Assumptions held fixed include current EPA corrosion prevention mandate enforcement levels, Saudi Aramco water injection program scale, and REACH emission restriction timelines. The analytical framework models demand across product type, end-use industry, application, and installation method dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical project award data against oilfield capital expenditure and municipal water infrastructure budgets. Key inputs include filament winding capacity utilization rates, E-glass roving spot pricing indices, and API certification pipeline volumes.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed composite manufacturers would shift outcomes beyond modeled ranges. Material shifts in EU carbon accounting implementation timelines or hydrogen transport regulatory frameworks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Seamless Pipe Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
Tapping Sleeves Market
Pipes and Tubes
Piping System and Piping Spools Market
Pipes and Tubes
France PVC Pipes Market
Pipes and Tubes
HPLC Fused Silica Tube Market
Pipes and Tubes
Pipe Market
Pipes and Tubes
GCC PVC Pipes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
Plastic Pipes and Fittings Market
Pipes and Tubes
Reinforced Thermoplastic Pipes Market
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
Plastic Pipe Market
Pipes and Tubes
Perfusion Tubing Systems Market
Pipes and Tubes
HDPE Pipes Market
Pipes and Tubes
Global Cured-In-Place Pipe Market