
 Multibore Tubes Market | 2026-2036
Multibore Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Multibore Tubes Market Analytics
The EU Medical Device Regulation (MDR) is pivoting procurement criteria toward verified biocompatibility and supply chain transparency across European healthcare systems. Medtronic leverages its vertically integrated polymer compounding operations to meet these certification thresholds. B. Braun Melsungen AG anchors its competitive position through proprietary extrusion capabilities in Germany. Terumo Corporation dominates Japanese regulatory submissions with PMDA-aligned quality management systems.
Multibore tubes integrate multiple independent lumens within a single extruded profile, enabling simultaneous fluid transfer, instrument guidance, and suction in catheter-based procedures. Wall thickness, lumen count, and material durometer determine burst pressure ratings and kink resistance under clinical use. Medical tubes command premium positioning due to ISO 10993 biocompatibility validation requirements and cleanroom manufacturing protocols. Composite materials represent the fastest-growing material segment as manufacturers combine polymer flexibility with metal-reinforced torque response for interventional cardiology applications.
FDA 510(k) pathways and EU MDR conformity assessments shape market access timelines for new multibore tube configurations. REACH chemical restrictions and RoHS substance limits constrain plasticizer and additive selection across European and electronics-facing supply chains. PMDA and METI oversight in Japan enforces JIS-standard dimensional tolerances for cardiovascular device integration. Stakeholders must monitor evolving MDR notified body capacity and FDA guidance on material equivalence to anticipate certification bottlenecks.
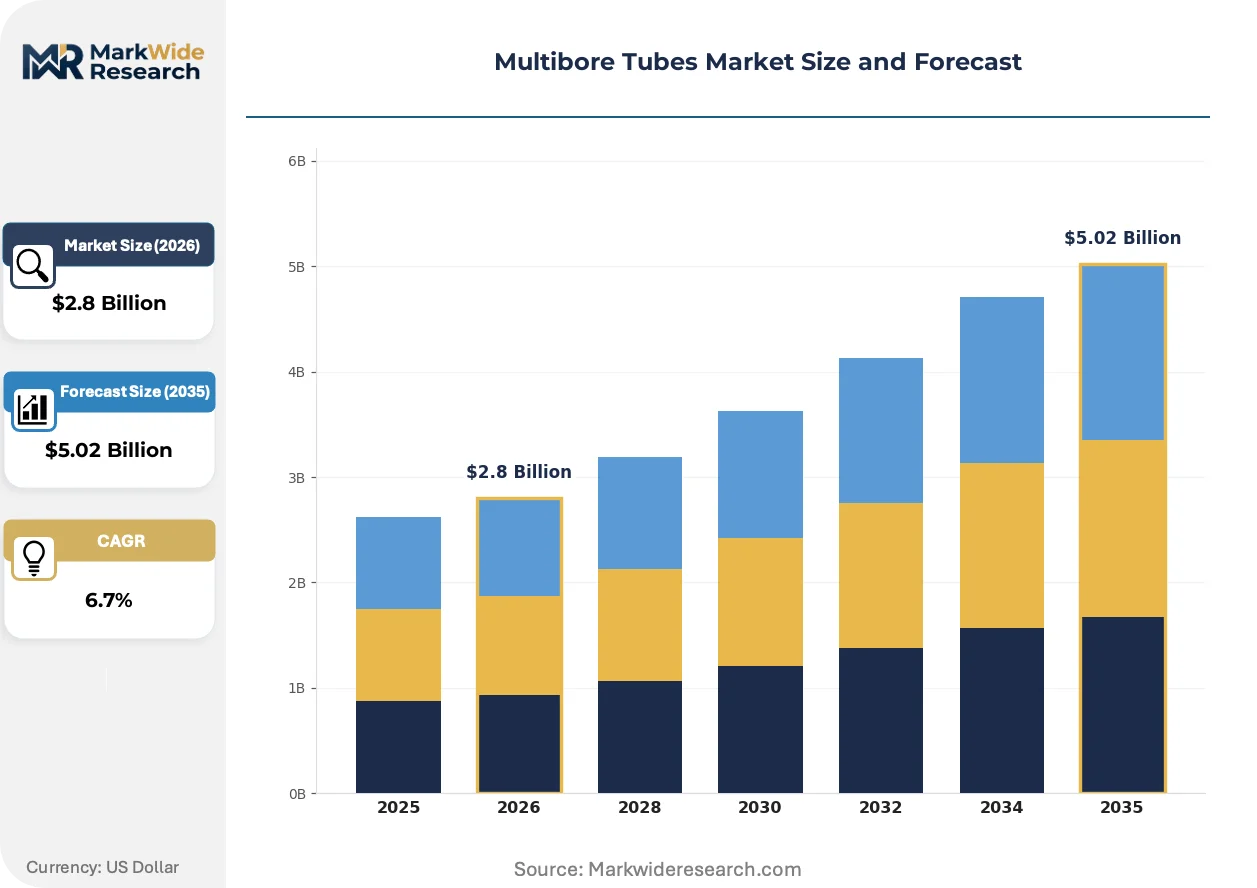
Market Dynamics
Medical device manufacturers are consolidating polymer compounding and extrusion capabilities to satisfy tightening EU MDR biocompatibility traceability mandates, compressing supplier tiers and privileging vertically integrated producers.
Growth Catalysts
- Minimally invasive surgical expansion:Catheter-based interventions across interventional cardiology and neurovascular segments require multilumen configurations for simultaneous fluid, instrument, and suction channels.
- ISO 10993 validation protocols:Standardized biocompatibility testing frameworks reduce regulatory friction for qualified materials, accelerating time-to-market for compliant tube configurations.
- German precision engineering clusters:Stuttgart and Munich corridors concentrate polymer extrusion expertise, cleanroom infrastructure, and metrology capabilities serving European medical device OEMs.
Market Restraints
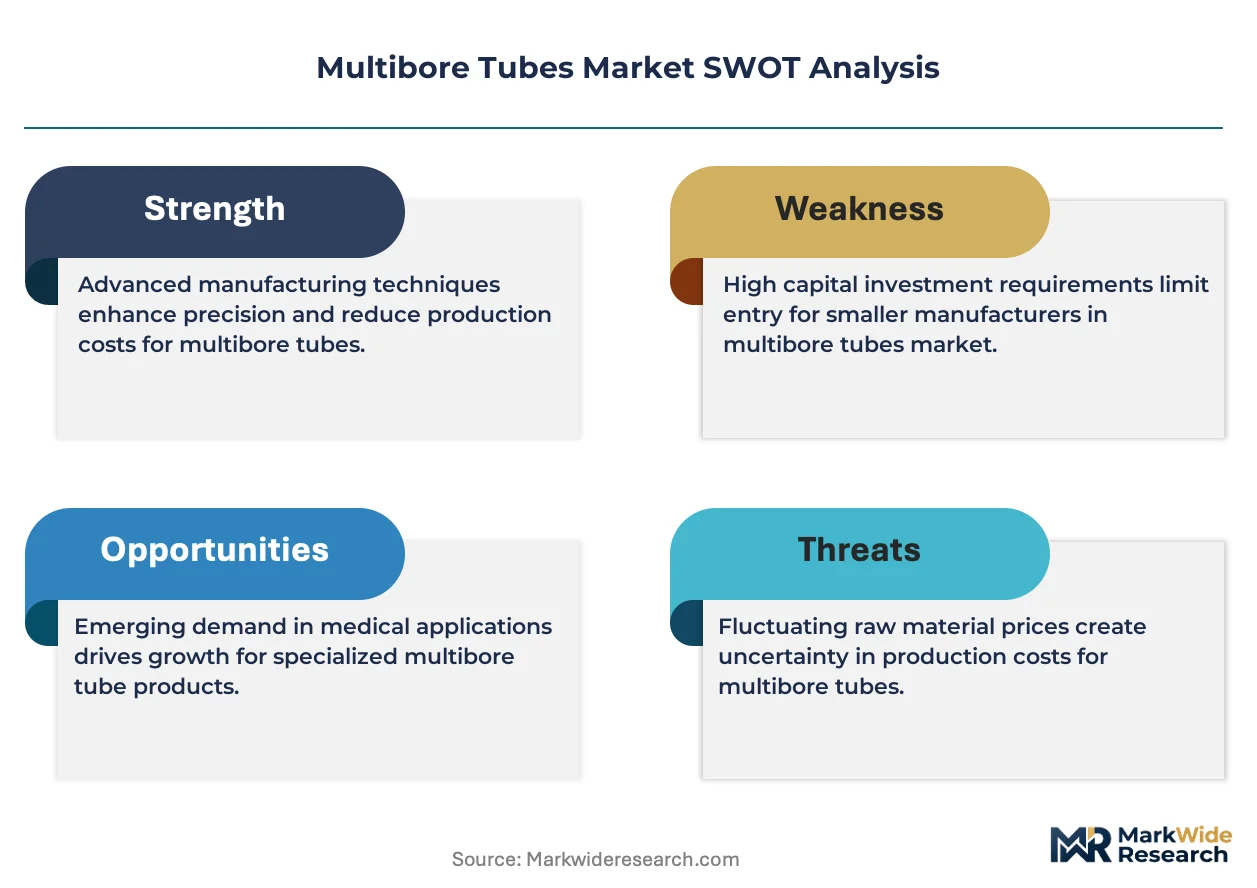
- Specialized polymer feedstock concentration:Medical-grade thermoplastic elastomers and fluoropolymers depend on concentrated petrochemical supply chains vulnerable to input volatility.
- EU MDR notified body capacity constraints:Certification bottlenecks extend conformity assessment timelines, freezing product launches and inventory commitments.
- Metal-reinforced composite substitution:Braided catheter shafts with integrated torque response threaten standalone multibore polymer tubes in high-performance interventional applications.
Strategic Opportunities
- Japanese PMDA-aligned quality systems:Manufacturers with JIS-standard dimensional tolerance capabilities can capture cardiovascular device integration contracts from domestic OEMs.
- Composite material convergence:Polymer-metal hybrid extrusion combining flexibility with torque transmission opens interventional cardiology segments previously closed to pure polymer constructions.
- Cleanroom-as-a-service distribution:Third-party validated logistics providers reduce capital barriers for mid-scale manufacturers entering regulated medical tubing supply chains.
Industry Challenges
- Polymer science and extrusion engineering talent scarcity:Multilumen die design and rheological optimization require specialized expertise concentrated among aging practitioner cohorts.
- ISO 10993 and MDR parallel certification timelines:Overlapping biocompatibility validation and conformity assessment processes strain regulatory affairs bandwidth and working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multibore Tubes Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tubes, Custom Tubes, Medical Tubes, Industrial Tubes Material: Polymer, Metal, Glass, Composite End User: Healthcare, Automotive, Aerospace, Electronics Application: Fluid Transfer, Thermal Management, Electrical Conduits, Structural Support |
| Companies Covered | Medtronic, B. Braun Melsungen AG, Terumo Corporation, Cook Medical, Schunk Carbon Technology, Friedrich & Dimmock Inc, LSP Industrial Ceramics Inc, Thermo Fisher Scientific, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multibore Tubes Market Evolving Landscape
Material science advances and regulatory data requirements are compressing traditional supplier tiers while opening new performance tiers in cardiovascular and surgical applications.
Metal-reinforced polymer composites are absorbing torque transmission functions previously requiring separate braided layers, enabling thinner wall profiles without kink resistance sacrifice. Interventional cardiology device manufacturers are adopting these constructions for guiding catheter applications. The technology is absorbing market share from conventional multilumen polymer tubes in high-flexion anatomical navigations.
REACH chemical restrictions and RoHS substance limits are constraining plasticizer and additive selection across European supply chains, forcing reformulation of legacy PVC and TPU compounds. Manufacturers with in-house polymer compounding capabilities are internalizing substitution R&D to maintain certification continuity. Electronics-facing medical device segments are most affected, with suppliers accelerating halogen-free and phthalate-free material qualifications.
Hospital procurement consolidation is compressing vendor panels and unbundling after-sales technical support from unit pricing. Integrated delivery networks in the United States are negotiating multiyear supply agreements with dedicated engineering collaboration clauses. This concentration is most visible in cardiovascular catheter supply chains, where IDN-scale buyers demand direct manufacturer relationships bypassing traditional distribution intermediaries.
Multibore Tubes Market Segmentation
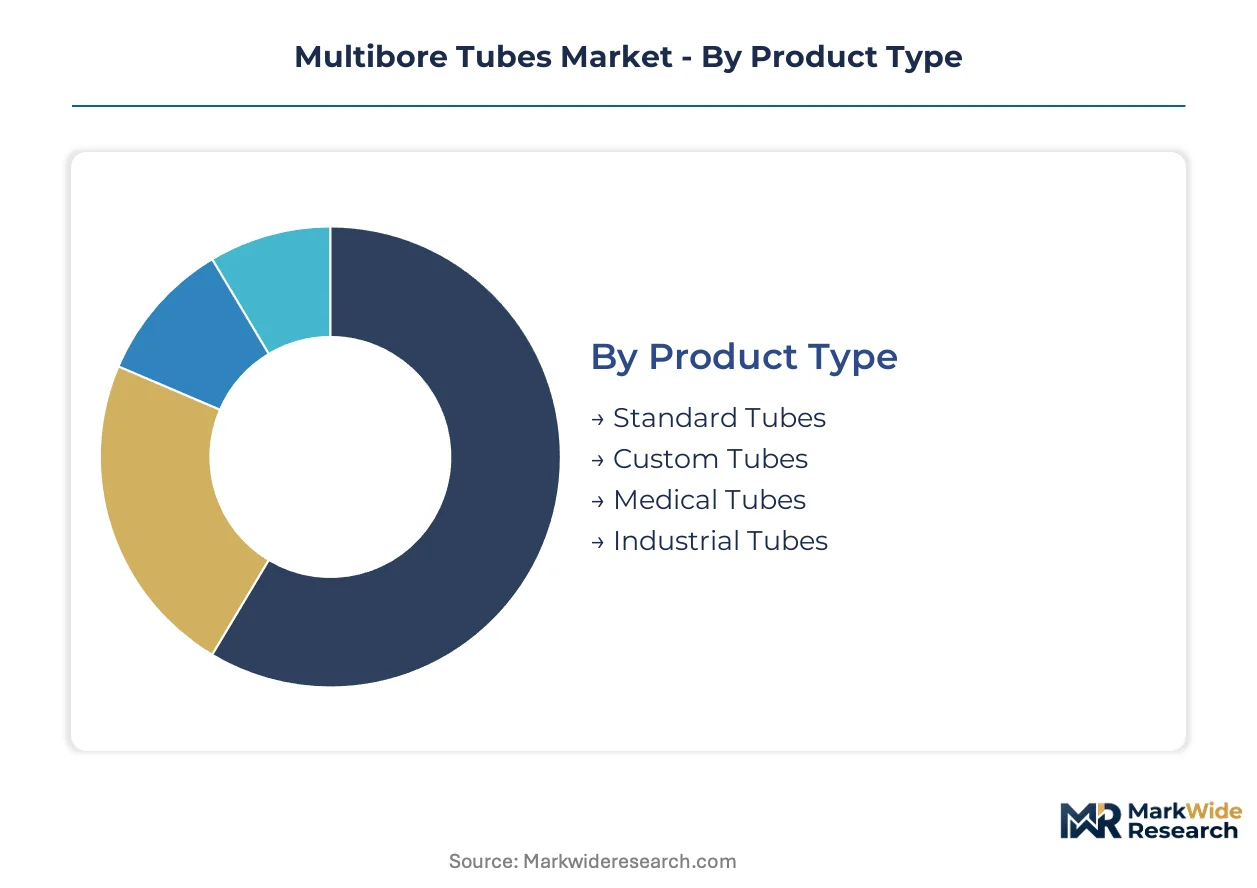
Segmentation in multibore tubing separates commodity extrusion from precision-engineered medical configurations. Material selection and lumen architecture determine regulatory pathways, manufacturing protocols, and margin structures across end-use verticals.
Product Type:
Equipment refresh cycles and regulatory recertification schedules drive upgrade patterns across product tiers, with medical device OEMs prioritizing validated configurations over cost-optimized alternatives.
- Standard Tubes:Off-the-shelf extruded profiles with fixed lumen counts and dimensional tolerances serve industrial fluid transfer and general electrical conduit applications. Demand concentrates in German automotive supply chains where Tier 1 suppliers specify JIS-standard tolerances for thermal management systems.
- Custom Tubes:Application-specific designs with variable lumen geometries, wall thickness gradients, and material blends address unique pressure or flexibility requirements. Stuttgart-area medical device manufacturers commission these configurations for catheter-based surgical instruments requiring simultaneous instrument guidance, irrigation, and suction channels.
- Medical Tubes:ISO 10993-validated constructions manufactured in certified cleanrooms with full batch traceability for biocompatibility compliance.
- Industrial Tubes:High-volume extrusions prioritizing chemical resistance and pressure ratings over regulatory documentation for process equipment and infrastructure.
Standard tubes sit at the top of the volume ranking, with custom tubes climbing the fastest.
Material:
Cost-to-performance ratios stratify material selection, with premium fluoropolymers and engineered composites commanding price multiples over commodity thermoplastics.
- Polymer:Thermoplastic elastomers, polyurethanes, and fluoropolymers dominate flexible medical applications requiring kink resistance and sterilization compatibility. Japanese cardiovascular device manufacturers specify PEEK and Pebax blends for guiding catheter shafts.
- Metal:Stainless steel and nitinol hypotubes provide structural rigidity, torque transmission, and radiopacity for interventional devices. Stuttgart precision engineering clusters specialize in laser-cut hypotube fabrication for neurovascular access systems.
- Glass:Borosilicate multibore capillaries serve chromatography and analytical instrumentation requiring chemical inertness and optical clarity.
- Composite:Polymer-metal hybrid extrusions combine flexibility with reinforced torque response, absorbing functions previously requiring separate braided layers in high-performance cardiovascular applications.
Polymer materials command the greatest shipment volumes, while composite constructions are expanding most quickly in interventional cardiology segments.
End User:
Customer scale and procurement sophistication determine contract structures, with consolidated hospital networks negotiating engineering collaboration clauses unavailable to fragmented industrial buyers.
- Healthcare:Hospitals, outpatient surgical centers, and medical device OEMs demand validated supply chains with MDR-compliant traceability. German IDNs in Bavaria specify direct manufacturer relationships bypassing distribution intermediaries for cardiovascular catheter procurement.
- Automotive:Thermal management and fluid routing in electric vehicle battery packs and powertrain systems. Munich-area automotive suppliers specify multilumen profiles for coolant distribution in high-voltage architectures.
- Aerospace:Lightweight fluid and pneumatic conduits prioritizing weight reduction and fire resistance for cabin and propulsion systems.
- Electronics:Cable protection and thermal management in semiconductor manufacturing equipment, constrained by RoHS substance limits and halogen-free material mandates.
Healthcare generates the highest value per meter, with automotive representing the largest unit volume opportunity.
Application:
Functional requirements dictate lumen architecture, with pressure ratings, chemical compatibility, and flexibility specifications varying sharply across use cases.
- Fluid Transfer:Simultaneous delivery of irrigation, contrast media, and aspiration in catheter-based procedures requires burst-pressure-rated multilumen configurations. Japanese PMDA submissions emphasize validated fluid isolation between channels.
- Thermal Management:Coolant distribution in automotive battery packs and electronics enclosures demands chemical resistance to glycol-based fluids and temperature cycling durability.
- Electrical Conduits:Insulated lumen separation for high-voltage wiring in medical devices and industrial equipment, subject to IEC dielectric standards.
- Structural Support:Torque transmission and pushability in guidewire and catheter shafts, increasingly absorbed by composite constructions replacing standalone polymer tubes.
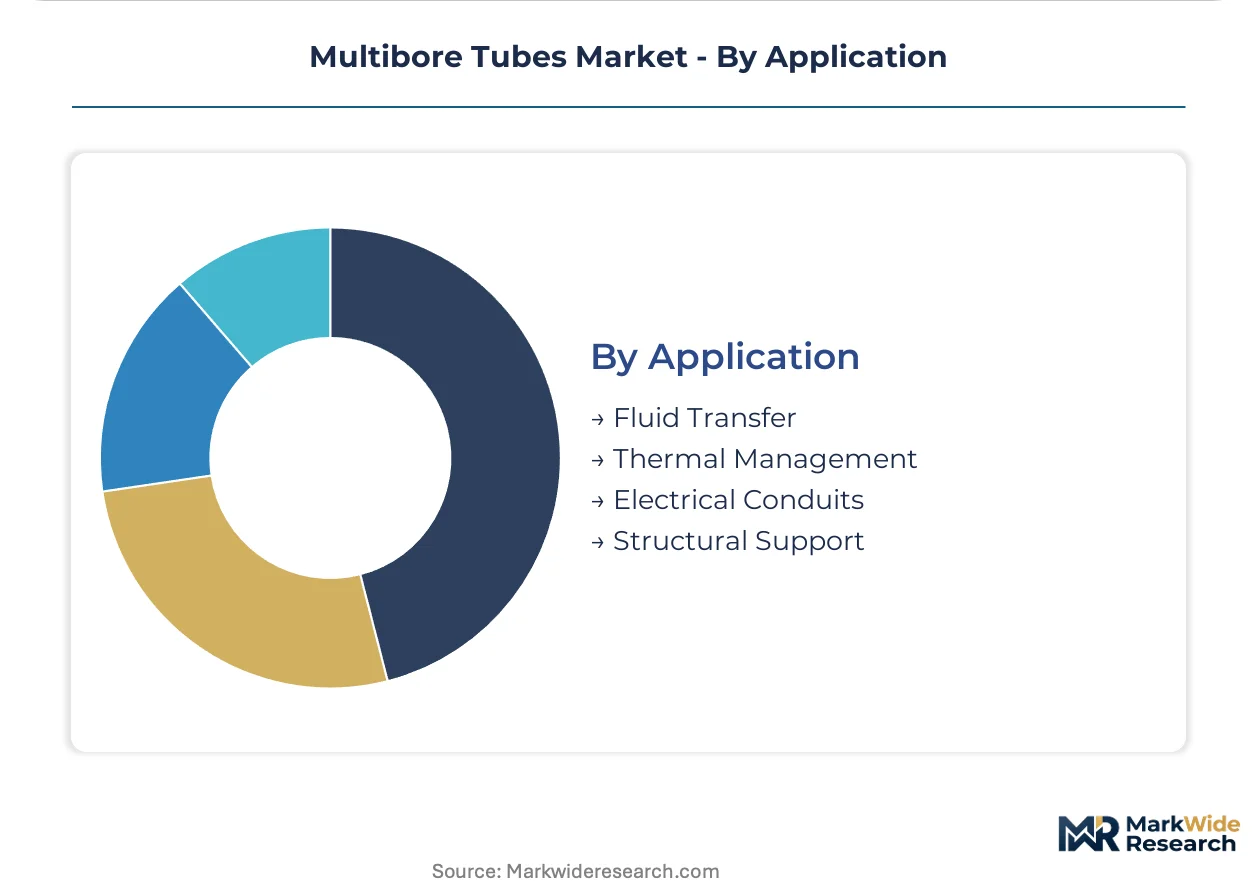
Fluid transfer applications lead in revenue concentration, with thermal management gaining share fastest through electric vehicle production scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision polymer extrusion for medical applications traces its industrial lineage to post-war German engineering clusters, where catheter manufacturing expertise concentrated around Stuttgart and Munich before diffusing to Japanese and North American precision manufacturing centers.
Germany
Cardiovascular device OEMs in Baden-Württemberg commission multilumen configurations for catheter-based surgical instruments requiring simultaneous instrument guidance, irrigation, and suction channels. The EU Medical Device Regulation mandates full batch traceability for biocompatibility compliance across European supply chains. Stuttgart-area manufacturers anchor their competitive position through proprietary extrusion capabilities and cleanroom infrastructure serving domestic medical device producers.
United States
Integrated delivery networks negotiate multiyear supply agreements with dedicated engineering collaboration clauses for cardiovascular catheter procurement. FDA 510(k) pathways shape market access timelines for new multibore tube configurations. Minnesota and Massachusetts medical technology corridors concentrate polymer compounding expertise and regulatory affairs capabilities for North American market entry.
Japan
Domestic cardiovascular device manufacturers specify PEEK and Pebax blends for guiding catheter shafts requiring PMDA-aligned quality management systems. METI oversight enforces JIS-standard dimensional tolerances for cardiovascular device integration. Tokyo-Osaka industrial corridors concentrate precision extrusion capabilities serving domestic OEMs with validated fluid isolation between channels.
China
Domestic medical device manufacturers accelerate adoption of multibore tubing for minimally invasive surgical instruments as healthcare infrastructure expands. NMPA regulatory submissions require alignment with GB standards for medical device classification. Yangtze River Delta manufacturing clusters develop polymer extrusion capabilities for both domestic consumption and export-oriented medical component supply.
Switzerland
Precision engineering firms serve European medical device OEMs with validated polymer compounding and extrusion capabilities. Swissmedic oversight maintains stringent requirements for material traceability and cleanroom manufacturing protocols. Zurich-Basel corridor concentrates metrology expertise and regulatory consulting capabilities supporting MDR conformity assessments for multinational device manufacturers.
Multibore Tubes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the multibore tubes market, with integrated polymer compounders and extruders controlling upstream material validation while specialized device assemblers outsource tube fabrication. The vendor base stratifies across three tiers: multinational medical device conglomerates with captive tube production, mid-scale precision extruders serving regional OEMs, and specialized polymer compounders supplying validated feedstock. Dominant competitive moves include backward integration into polymer compounding to secure MDR-compliant traceability and strategic partnerships with cleanroom logistics providers to reduce capital barriers for mid-scale manufacturers.
Among diversified medical technology conglomerates, Medtronic and B. Braun Melsungen AG exemplify the vertically integrated archetype, while Terumo Corporation occupies a position representing Japanese precision manufacturing specialization. These entities anchor competitive positioning through distinct geographic and regulatory footprints rather than interchangeable commodity supply.
| Leading Market Players |
|---|
| Medtronic |
| B. Braun Melsungen AG |
| Terumo Corporation |
| Cook Medical |
| Schunk Carbon Technology |
| Friedrich & Dimmock Inc |
| LSP Industrial Ceramics Inc |
| Thermo Fisher Scientific |
| Saint-Gobain |
| Others |
Value Network & Pricing Analysis
REACH chemical restrictions gate qualified supply and premium-tier pricing access by forcing reformulation of legacy PVC and TPU compounds across European medical tubing supply chains. Manufacturers with in-house polymer compounding capabilities command pricing premiums while competitors face certification discontinuity risks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-validated medical configurations from industrial extrusions. Price differentiation hinges on biocompatibility certification grade and cleanroom manufacturing protocols. Cost compression in standard industrial tiers intensifies because automotive buyers consolidate vendor panels. Hospital procurement committees show least price sensitivity for cardiovascular catheter applications requiring MDR-compliant traceability.
Supply Chain Analysis
Polymer science and extrusion engineering talent scarcity in Stuttgart and Munich corridors constrains capacity expansion for precision multilumen die fabrication. Supply concentrates in Germany, Japan, and the United States for medical-grade thermoplastic elastomers and fluoropolymers. Raw material flows draw from concentrated petrochemical feedstocks including Pebax, PEEK, and medical-grade TPU. Single-source vulnerability runs through specialized multilumen die manufacturers serving interventional cardiology OEMs. Distribution runs through direct manufacturer relationships with integrated delivery networks bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR compliance costs in Germany create margin capture opportunities for Japanese manufacturers with PMDA-aligned quality systems serving export markets.
For Market Incumbents: Deepen backward integration into polymer compounding to secure MDR-compliant traceability against emerging composite material substitution threats. Expand cleanroom capacity in Baden-Württemberg to anchor supply relationships with Bavarian hospital procurement networks. Prioritize ISO 10993 validation continuity as notified body capacity constraints extend conformity assessment timelines. For New Entrants and Emerging Players: Begin with cleanroom-as-a-service partnerships to bypass capital barriers for mid-scale manufacturers entering regulated medical tubing supply chains. Target Chinese domestic medical device manufacturers accelerating adoption of multibore tubing for minimally invasive surgical instruments. Pursue NMPA-aligned quality system development as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for precision extruders with proprietary multilumen die capabilities because EU MDR mandates are compressing supplier tiers and privileging vertically integrated producers. Focus acquisition screening on mid-scale German and Swiss manufacturers with validated polymer compounding operations. Watch PMDA submission volumes from domestic Japanese cardiovascular device OEMs as inflection indicator for regional demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Conformity Assessment Acceleration | Notified body capacity expansion reduces certification bottlenecks freezing product launches across European supply chains. |
| Composite Material Hybrid Extrusion | Polymer-metal construction absorbs torque transmission functions previously requiring separate braided catheter shaft layers. |
| Cleanroom-as-a-Service Partnership | Third-party validated logistics providers reduce capital barriers for mid-scale manufacturers entering regulated supply chains. |
| PMDA-Aligned Quality System Investment | JIS-standard dimensional tolerance capabilities capture cardiovascular device integration contracts from Japanese OEMs. |
| Halogen-Free Material Qualification | RoHS substance limit compliance opens electronics-facing medical device segments constrained by legacy additive formulations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer extrusion engineers, regulatory affairs specialists at notified bodies, hospital procurement managers, and biomedical device designers with secondary validation against FDA 510(k) filings, EU MDR conformity assessment databases, PMDA submission records, and customs trade data for medical-grade polymer feedstocks. Bottom-up shipment estimates triangulated against top-down market sizing across product type, material, end user, and application dimensions.
Segment-weighting approaches applied differential growth assumptions across medical, automotive, aerospace, and electronics verticals throughout the projection horizon. Analytical frameworks modeled lumen count configurations, material durometer specifications, and cleanroom certification tiers as core segmentation dimensions. CAGRs derived from regression analysis of historical shipment patterns and forward-looking OEM capacity announcements. Forecast inputs incorporated electric vehicle thermal management scaling, interventional cardiology procedure volumes, and MDR implementation timelines.
Several conditions sit outside the modeled scope, including sudden polymer feedstock price shocks, notified body insolvency events, and trade policy disruptions affecting German-Japanese medical device component flows. Forecasts reflect documented assumptions regarding regulatory stability and OEM consolidation trajectories. Material deviation in REACH chemical restriction enforcement or PMDA review cycle acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
Piping System and Piping Spools Market
Pipes and Tubes
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market
Pipes and Tubes
Stainless Steel Welded Pipes Market
Pipes and Tubes
Gas Fittings and Components Market
Pipes and Tubes
India Process Piping Market
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
HPLC Fused Silica Tube Market
Pipes and Tubes
Tapping Sleeves Market
Pipes and Tubes
Water and Wastewater Pipe Market
Pipes and Tubes
France PVC Pipes Market
Pipes and Tubes
Pipes and Fittings Market
Pipes and Tubes
Global Fiberglass Pipe Market
Pipes and Tubes
United States Copper Pipes and Tubes Market
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
Gas Pipe Fittings Market