
 Global Municipal Pipes Market | 2026-2036
Global Municipal Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Municipal Pipes Market Analysis
Stormwater management is pivoting toward higher-capacity pipe networks as climate adaptation budgets expand across municipal procurement offices. JM Eagle leverages its vertically integrated PVC manufacturing footprint to control cost positions in North American water supply contracts. Aliaxis Holdings SA anchors European demand through specialized pressure pipe systems compliant with evolving potable water standards. China Lesso Group Holdings Limited dominates domestic project pipelines through scale advantages in HDPE extrusion capacity.
Municipal pipes are cylindrical conduits manufactured from thermoplastic polymers, ductile iron, or steel alloys, typically engineered to withstand internal pressures ranging from 150 to 350 psi depending on application class and burial depth. These systems transport potable water, sanitary sewage, and storm runoff beneath public rights-of-way, with joint design and corrosion resistance determining operational lifespan. PVC product lines capture volume leadership in residential-scale water distribution due to material cost efficiency and ease of socket fusion. HDPE segments represent the fastest-expanding structural category, driven by trenchless installation demand and flexibility in seismic zones. Ductile iron maintains margin concentration in large-diameter trunk mains where pressure ratings and structural loading requirements exclude polymer alternatives.
The EPA enforces maximum contaminant levels and lead service line replacement mandates that directly shape material specification in US municipal procurement. ECHA's REACH restrictions on heavy metal stabilizers in PVC formulations and the EU F-Gas Regulation's indirect pressure on infrastructure energy intensity compound compliance costs for European suppliers. China's MEE implements surface water quality standards that tighten allowable infiltration rates in sewer networks, favoring joint-performance-tested pipe systems. Stakeholders must monitor regulatory divergence in polymer certification requirements across these jurisdictions to avoid specification lockout in cross-border project bidding.
Market Dynamics
EPA Lead and Copper Rule revisions are forcing wholesale material substitution across US municipal procurement, accelerating displacement of legacy lead service lines with polymer alternatives and rewiring supplier qualification criteria.
Growth Catalysts
- Lead service line replacement mandates:EPA enforcement deadlines compel US municipalities to accelerate pipe material upgrades, creating sustained demand for compliant thermoplastic systems.
- Trenchless rehabilitation adoption:Cured-in-place pipe (CIPP) and horizontal directional drilling methods reduce urban disruption costs, driving specification preference in aging network renewals across Germany and Japan.
- China's tier-two urbanization:Municipal bond financing for sewage and stormwater infrastructure in cities like Chengdu and Xi'an sustains HDPE deployment volumes.
Market Restraints
- Resin price volatility:Ethylene and propylene feedstock fluctuations compress margins for PVC and HDPE extruders, particularly affecting spot-market-dependent processors.
- Ductile iron foundry concentration:Production gravity in India and Brazil creates supply vulnerability for large-diameter pressure-rated trunk main projects in seismic zones.
- REACH compliance friction:ECHA restrictions on heavy metal stabilizers in European PVC formulations extend certification timelines and reformulation costs.
Strategic Opportunities
- Smart pipe sensor integration:Convergence of distributed acoustic sensing with polymer conduits enables real-time leak detection, opening premium specification tiers in water-stressed regions like Australia and Spain.
- EU F-Gas Regulation tailwind:Infrastructure energy intensity standards indirectly favor low-friction HDPE gravity sewer systems in French and Dutch procurement frameworks.
- Direct municipal contracting:Bypass of traditional distributor channels through digital procurement platforms concentrates margin capture with manufacturers in Brazilian and Indonesian markets.
Industry Challenges
- Trenchless technician scarcity:Specialized horizontal directional drilling operators and CIPP installation crews face training pipeline gaps, constraining project velocity in North American urban renewals.
- Polymer joint certification delays:ISO 4427 and EN 12201 fusion qualification protocols extend quality assurance timelines, bottlenecking HDPE deployment for potable water trunk mains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Municipal Pipes Market |
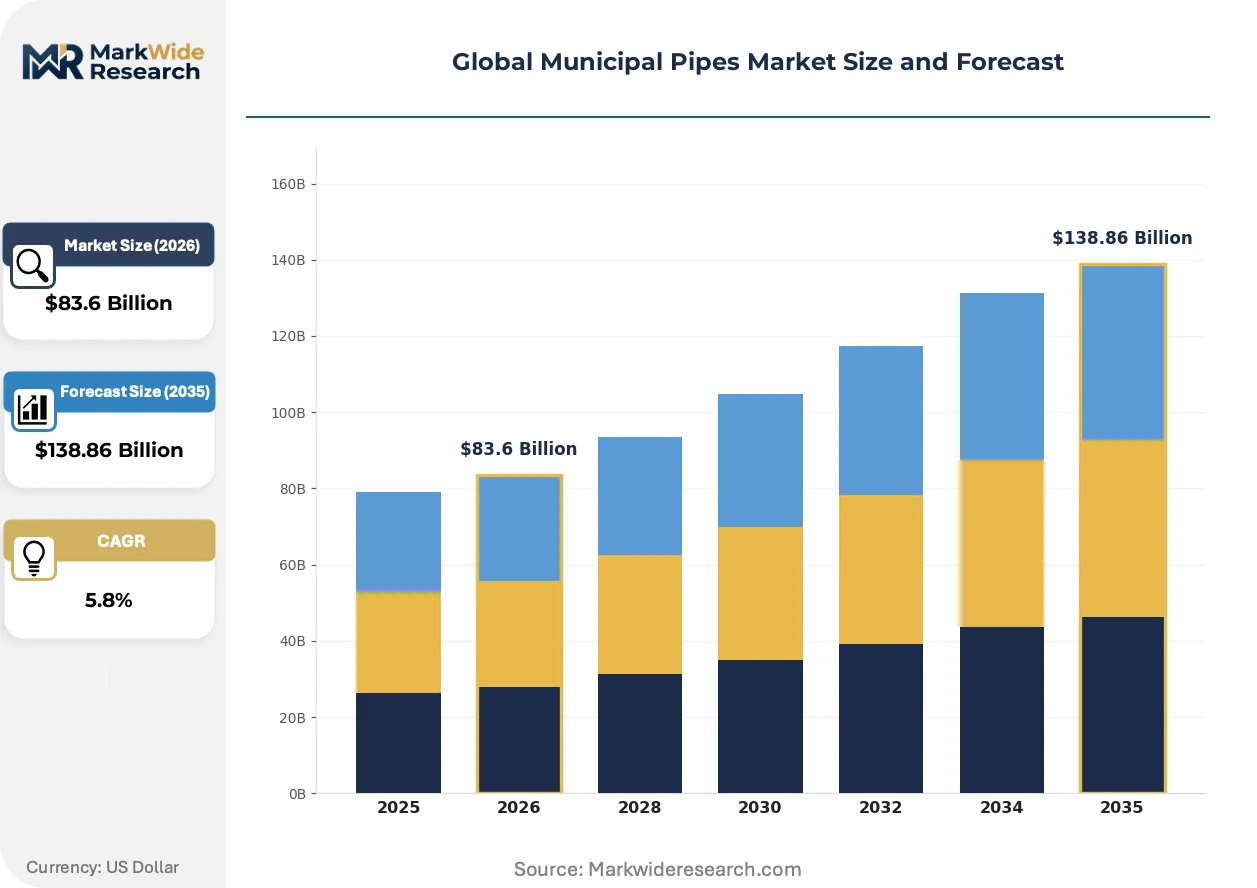
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $138.86 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC, HDPE, Ductile Iron, Steel Application: Water Supply, Sewage, Stormwater, Irrigation End User: Municipalities, Contractors, Developers, Utility Companies Installation Method: Trenching, No-Dig, Above Ground, Prefabricated |
| Companies Covered | Aliaxis Holdings SA, McWane, Inc., JM Eagle, Orbia, Westlake, AMERICAN (American Cast Iron Pipe Company), Georg Fischer, IneOS, China Lesso Group Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Municipal Pipes Market Emerging Trajectories
Material science advances and installation methodology shifts are compressing project timelines while extending asset lifespans. Three developments are restructuring competitive positioning across thermoplastic and metallic pipe categories.
HDPE is overtaking ductile iron in large-diameter water transmission specifications. The material's flexibility accommodates seismic loading and permits trenchless pullback installation beneath existing infrastructure. Municipal engineers in California and Japan now specify HDPE for earthquake-resistant trunk mains, compressing demand for traditional metallic pressure pipe.
REACH restrictions on cadmium and lead stabilizers in European PVC formulations are accelerating calcium-zinc and organotin substitute adoption. Compounders in Germany and the Netherlands face reformulation validation cycles extending twelve to eighteen months. Potable water distribution specifications now exclude legacy-stabilized PVC, forcing inventory obsolescence across continental supply chains.
Performance-based service contracting is displacing traditional material-procurement models in Australian and UK municipal frameworks. Contractors assume twenty-five to fifty-year operational liability for installed networks, shifting specification authority from procurement officers to integrated service providers. This consolidation favors suppliers with in-house trenchless installation capabilities and long-term maintenance infrastructure.
Global Municipal Pipes Market Segmentation
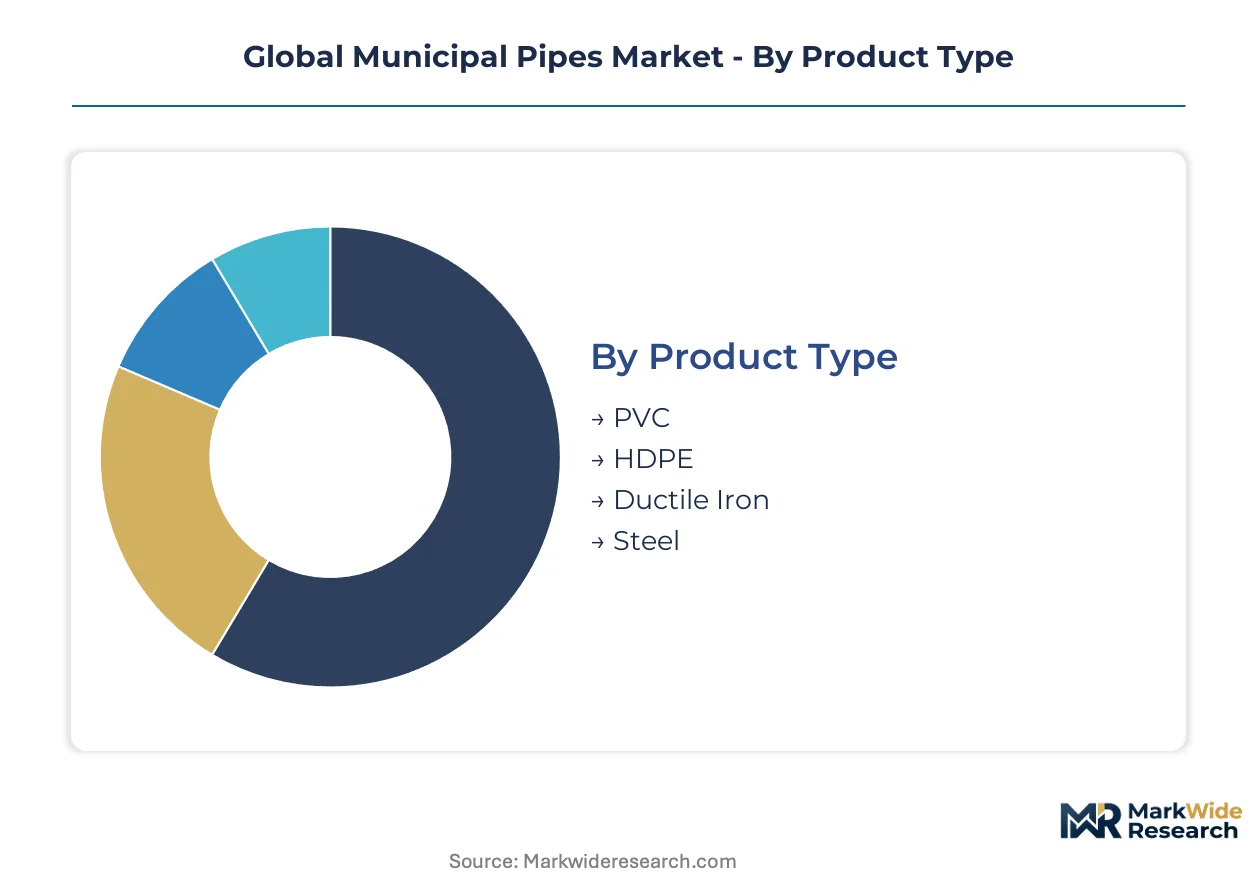
Municipal pipe procurement splits across material chemistry, pressure requirements, and installation constraints. Specification authority varies sharply between legacy trenching contractors and integrated trenchless service providers.
Product Type:
Cost sensitivity and pressure ratings separate buyers across thermoplastic and metallic alternatives.
- PVC:Rigid thermoplastic formulations dominate residential-scale water distribution through socket-fusion jointing and corrosion immunity. Municipal engineers in the United States and Germany specify PVC for gravity sewer and low-pressure potable networks where material cost efficiency outweighs seismic flexibility requirements.
- HDPE:Flexible polyethylene systems accommodate trenchless pullback installation and seismic loading through butt-fusion welded joints. Demand concentrates in California and Japan for earthquake-resistant trunk mains, with China's tier-two cities deploying HDPE for infiltration-resistant sewer networks under MEE surface water quality enforcement.
- Ductile Iron:Centrifugally cast iron alloys retain specification for large-diameter pressure-rated transmission mains exceeding 24-inch nominal diameter.
- Steel:Welded or seamless carbon steel pipes serve specialized high-pressure industrial water feeds and penstock applications.
Volume sits with PVC; growth tilts toward HDPE.
Application:
Regulatory enforcement intensity and climate exposure determine project prioritization across utility functions.
- Water Supply:Potable distribution networks face EPA Lead and Copper Rule mandates accelerating lead service line replacement with polymer alternatives. Procurement offices in Flint, Michigan and Newark, New Jersey drive specification shifts toward HDPE and certified PVC for corrosion-resistant trunk and lateral installations.
- Sewage:Sanitary collection systems prioritize joint integrity to prevent infiltration and exfiltration under tightening environmental discharge permits. Germany's Ruhr region and the Netherlands specify low-leakage PVC and HDPE gravity sewers to meet EU Urban Waste Water Treatment Directive compliance deadlines.
- Stormwater:Climate adaptation budgets in Australia and Spain expand higher-capacity network deployment for intensified precipitation events.
- Irrigation:Agricultural and municipal green space watering systems utilize lower-pressure PVC and polyethylene laterals.
Capital allocation concentrates on water supply renewal; stormwater is climbing the fastest in procurement priority.
End User:
Specification authority and contract duration separate fragmented municipal buyers from consolidated service integrators.
- Municipalities:Direct procurement by city engineering departments dominates volume through design-bid-build frameworks. Brazilian and Indonesian municipalities increasingly bypass distributor channels through digital procurement platforms, concentrating margin capture with manufacturers.
- Contractors:Integrated service providers in Australia and the United Kingdom assume twenty-five to fifty-year operational liability through performance-based contracting, shifting specification authority from procurement officers to installation-capable vendors.
- Developers:Private residential and commercial project sponsors specify utility connections for subdivision build-out.
- Utility Companies:Regional water and wastewater authorities consolidate trunk main procurement across multiple municipal jurisdictions.
Contract volume flows through municipalities; margin expansion favors contractor-led performance contracts.
Installation Method:
Urban density and surface disruption costs drive methodology divergence between established and constrained corridors.
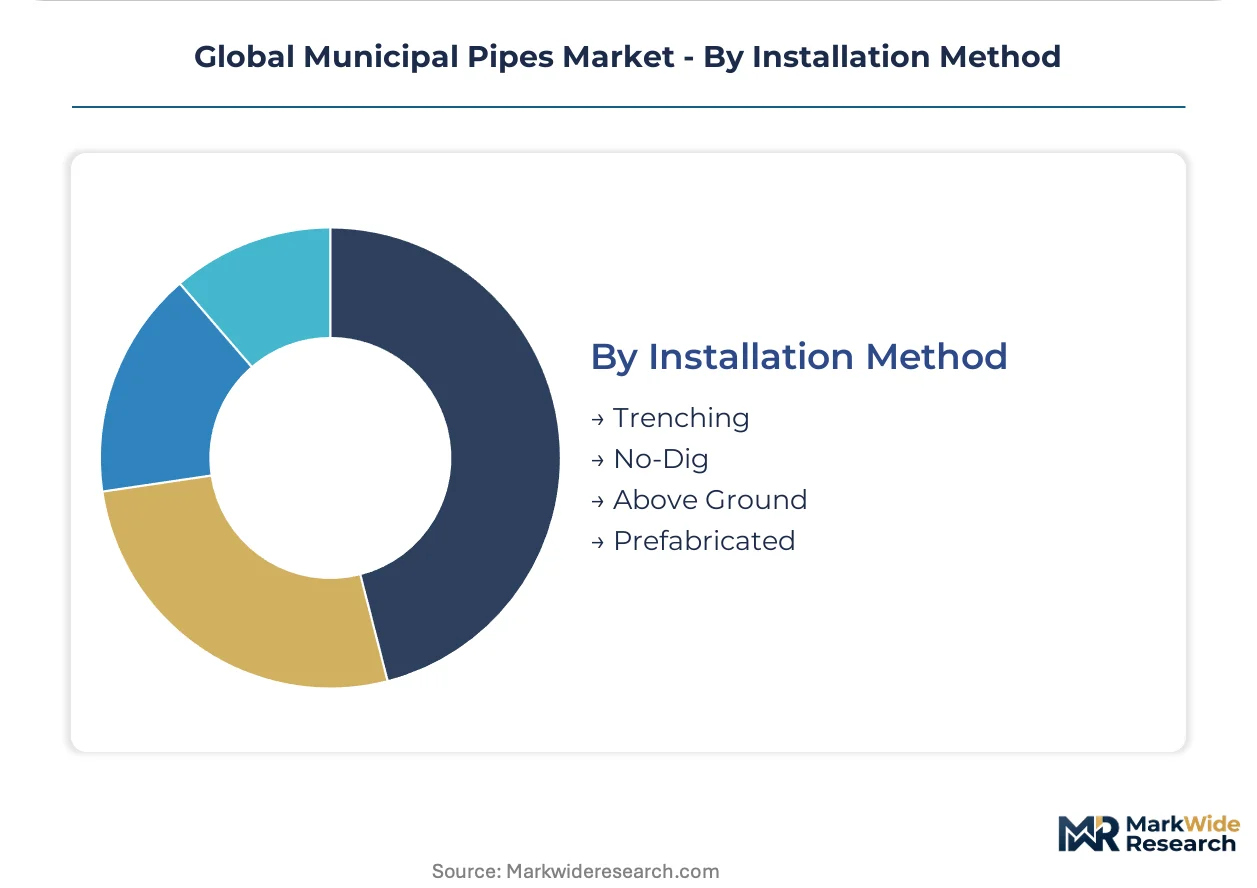
- Trenching:Open-cut excavation retains cost advantage in greenfield developments and unconstrained rights-of-way. China's urbanization corridors in Chengdu and Xi'an deploy trenching for primary network build-out where surface restoration costs remain manageable.
- No-Dig:Horizontal directional drilling and cured-in-place pipe renewal minimize disruption in aging European and Japanese urban cores. CIPP installation crews face training pipeline gaps in North America, constraining project velocity despite specification preference.
- Above Ground:Elevated or surface-mounted piping serves temporary bypass systems and industrial process water feeds.
- Prefabricated:Factory-assembled spool sections reduce field jointing requirements for complex geometric installations.
Trenching commands installed volume; no-dig methods are gaining share fastest in renewal markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in China's Yangtze River Delta concentrate HDPE extrusion capacity serving tier-two urbanization corridors. Germany's Ruhr industrial belt anchors European trenchless rehabilitation equipment manufacturing. India's dedicated infrastructure investment zones accelerate PVC compound production for municipal water networks.
United States
EPA Lead and Copper Rule revisions drive lead service line replacement programs in Flint, Michigan and Newark, New Jersey. Municipal bond issuances in California prioritize HDPE trunk mains for seismic resilience. The Southeast corridor from Atlanta to Charlotte deploys trenchless CIPP methods for aging sewer network renewal.
Germany
ECHA REACH restrictions on cadmium stabilizers force PVC compound reformulation across the Ruhr industrial belt. The Netherlands-German border region specifies low-leakage gravity sewers under EU Urban Waste Water Treatment Directive compliance. Hamburg's port industrial zone concentrates ductile iron foundry capacity for large-diameter pressure applications.
China
MEE surface water quality standards tighten infiltration limits in Chengdu and Xi'an sewer networks. Municipal bond financing in the Sichuan-Chongqing cluster sustains HDPE deployment for stormwater infrastructure. The Pearl River Delta's specialized economic zones house integrated PVC manufacturing from resin to finished pipe.
Japan
METI earthquake-resistant infrastructure codes specify flexible polymer systems for Tokyo and Osaka water transmission. Horizontal directional drilling contractors in the Kanto region face technician training pipeline gaps despite specification preference. Kyushu's industrial corridor manufactures specialized joint systems for seismic zone applications.
Australia
Climate adaptation budgets in New South Wales and Victoria expand higher-capacity stormwater networks for intensified precipitation. Performance-based service contracting shifts specification authority to integrated contractors with twenty-five-year operational liability. Queensland's mining corridor drives specialized high-pressure steel pipe demand for industrial water feeds.
Global Municipal Pipes Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated polymer extruders commanding premium positions in trenchless specifications while regional foundries compete on ductile iron trunk main tenders. The vendor base organizes into three tiers: multinational resin-to-pipe integrators, national distribution-focused extruders, and project-specific installation contractors. Two strategic archetypes dominate competitive dynamics—vertically integrated compounders controlling cost positions and technology-licensed specialists capturing specification premiums. Capacity expansion in Asian resin production and M&A consolidation among European distributors represent the dominant competitive moves reshaping supply structure.
Within the multinational integrator tier, JM Eagle and China Lesso Group Holdings Limited exemplify scale-driven positioning through captive resin supply and continental distribution density. Aliaxis Holdings SA occupies a specialized position among European pressure pipe specialists, anchoring compliance-focused procurement in potable water networks. These three entities represent divergent geographic anchoring—North American, Chinese, and European—each capturing margin through distinct supply chain configurations rather than direct product overlap.
| Leading Market Players |
|---|
| Aliaxis Holdings SA |
| McWane, Inc. |
| JM Eagle |
| Orbia |
| Westlake |
| AMERICAN (American Cast Iron Pipe Company) |
| Georg Fischer |
| IneOS |
| China Lesso Group Holdings Limited |
| Others |
Supply Flow & Price Mechanics
Ethylene and propylene feedstock indices cascade through municipal pipe supply chains, compressing margins for spot-market-dependent PVC and HDPE extruders while rewarding vertically integrated compounders with captive resin supply. Procurement officers in water-stressed municipalities face widening price spreads between certified potable-grade systems and standard utility specifications as certification timelines extend.
Pricing Analysis
Lead-time premiums dominate municipal pipe procurement, with certified HDPE trunk mains commanding substantial markups for sub-90-day delivery against standard 180-day production windows. Pricing stratifies across premium certified potable systems, standard pressure-rated utility grades, and economy-tier non-potable irrigation lines. Price differentiation hinges on ISO 4427 fusion qualification status and geographic freight absorption from extrusion hubs. Cost compression in standard PVC gravity sewer segments is intensifying because of resin volatility and distributor inventory destocking. Municipal contractors exhibit highest price sensitivity on large-diameter trunk projects, while integrated service providers with performance-based contracts show lowest sensitivity due to operational liability transfer.
Supply Chain Analysis
Single-source vulnerability sits with ductile iron foundry capacity concentrated in India and Brazil, creating supply fragility for seismic-zone trunk main projects. HDPE resin production draws from Saudi Arabia, South Korea, and the United States, while PVC compound manufacturing rests on chlorine and ethylene feedstocks from the US Gulf Coast and Northwestern Europe. Tariff exposure on finished pipe imports into North American markets compounds cost uncertainty for non-integrated extruders. Distribution runs through regional stocking distributors serving municipal procurement offices, with direct manufacturer contracting emerging in Brazilian and Indonesian digital procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The municipal pipes sector is navigating a material-transition phase as HDPE trenchless systems displace legacy ductile iron trunk mains in earthquake-prone infrastructure corridors. This technology substitution rewires supplier qualification criteria and procurement authority structures.
For Market Incumbents: Anchor market position through backward integration into resin production or compounding capacity to insulate margin structures from ethylene price volatility. Defend specification authority by investing in ISO 4427 and EN 12201 fusion certification infrastructure to capture premium trenchless project tiers. Prioritize acquisition of horizontal directional drilling contractors to address technician scarcity constraining North American project velocity. For New Entrants and Emerging Players: Launch via direct municipal contracting platforms in Indonesian and Brazilian markets where distributor bypass concentrates margin capture with manufacturers. Target Australia's performance-based service contracting segment, where twenty-five-year operational liability assumptions shift specification authority toward installation-capable vendors. Penetrate through smart pipe sensor integration partnerships with distributed acoustic sensing providers serving water-stressed Spanish and Australian utilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor European PVC compounders facing REACH reformulation cost pressures in Germany and the Netherlands. Long-term viability over the next decade hinges on trenchless installation capability consolidation and smart infrastructure convergence. Monitor EPA Lead and Copper Rule enforcement velocity in US municipalities as the inflection indicator for polymer substitution demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive ethylene supply insulates JM Eagle and China Lesso from feedstock volatility compressing spot-market extruders. |
| Trenchless Installation Capability Acquisition | Horizontal directional drilling crew scarcity in North America creates consolidation premium for qualified CIPP operators. |
| Smart Pipe Sensor Partnership | Distributed acoustic sensing integration opens premium specification tiers in Australian and Spanish water-stressed markets. |
| Direct Municipal Platform Contracting | Brazilian and Indonesian digital procurement channels concentrate margin capture away from traditional distributors. |
| REACH-Compliant Compound Reformulation | Calcium-zinc stabilizer validation cycles in Germany and Netherlands force inventory obsolescence for legacy PVC suppliers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with municipal engineering directors, trenchless installation contractors, HDPE fusion technicians, PVC compounders, and water utility procurement managers. EPA enforcement databases, ECHA REACH substance restrictions, China MEE surface water quality standards, and municipal bond issuance records provided regulatory and demand-side validation. Bottom-up project pipeline tracking across tier-two Chinese cities and top-down resin consumption modeling were triangulated for volume reconciliation.
Segment-level CAGRs were derived through material substitution elasticity modeling, infrastructure depreciation cycle analysis, and regulatory deadline impact assessment across the projection horizon. Dimensions modeled include material chemistry, pressure rating class, installation methodology, application function, and end-user procurement authority. Trenchless adoption curves in Japan and Germany, lead service line replacement velocity in US Rust Belt municipalities, and HDPE penetration rates in Chinese tier-two urbanization corridors served as industry-specific forecast inputs.
Resin price volatility, regulatory certification timeline extensions, and trenchless technician training pipeline gaps are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on EPA enforcement intensity, ECHA reformulation compliance deadlines, and China MEE infiltration standard implementation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
ESR Tubes Market
Pipes and Tubes
Collapsible Metal Tubes Market
Pipes and Tubes
Germany Acid Proof Lining Market
Pipes and Tubes
Steel Tubes Market
Pipes and Tubes
North America Hydraulic Fluid Connectors Market
Pipes and Tubes
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market
Pipes and Tubes
Glass Reinforced Plastic (GRP) Piping Market
Pipes and Tubes
Welded Pipes Market
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
Tapping Sleeves Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
Glass Reinforced Epoxy (GRE) Pipes Market
Pipes and Tubes
FRP Pipe Market
Pipes and Tubes
Cold Drawn Seamless (CDS) Steel Pipes Market
Pipes and Tubes
Pipe Market
Pipes and Tubes
OCTG Pipe Market