
 Global Polypropylene Pipes Market | 2026-2036
Global Polypropylene Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polypropylene Pipes Market Foresight
Middle Eastern resin producers is rebalancing global polypropylene feedstock flows toward pipe-grade copolymers. Pipelife leverages vertical integration across European compounding assets to sustain margin stability. AGRU anchors its position through specialized fusion welding technology leadership. Kalde differentiates via deep penetration of Central European municipal water networks.
Polypropylene pipes are thermoplastic conduit systems manufactured from homopolymer, random copolymer, or block copolymer resins with operating temperatures typically spanning 0°C to 95°C and pressure ratings up to 25 bar, extruded through single-screw or twin-screw processes for fluid transport in pressurized and non-pressurized environments. PP-R formulations dominate residential hot-water plumbing specifications due to superior creep resistance at elevated temperatures, while PP-RT grades capture growing share in underfloor heating and radiator connection applications where flexibility and thermal cycling endurance matter. Industrial piping applications concentrate margin pools in large-diameter custom fabrication, though small-diameter standardized products still occupy volume leadership across agricultural drip-irrigation deployments.
REACH registration requirements in Europe, NSF/ANSI 14 potable water certifications in the United States, and BIS IS 15801 standards in India collectively shape material formulation choices, testing protocols, and market access conditions for pipe producers seeking cross-border contracts. The EU F-Gas Regulation indirectly pressures HVAC contractors toward lower-leakage piping systems, reinforcing specification preference for fusion-jointed polypropylene over mechanical alternatives. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these chemicals historically served critical processing aids in pipe extrusion and their phase-out demands rapid reformulation investment.
Market Dynamics
Specification shifts toward fusion-jointed polypropylene systems in European HVAC retrofits are compressing demand for mechanical joint alternatives and rewiring contractor training investments across the value chain.
Growth Catalysts
- EU F-Gas Regulation:Mandates for lower-leakage refrigeration circuits accelerate specification preference for fusion-welded PP-R piping in commercial HVAC installations across Germany and France.
- India's tier-2 municipal water codes:Centralized plumbing standards in cities like Indore and Lucknow displace legacy galvanized iron with PP-RCT gravity sewer systems.
- PP-RT flexibility advances:Enhanced thermal cycling endurance in random copolymer formulations captures radiator connection and underfloor heating specifications previously served by cross-linked polyethylene.
Market Restraints
- Propylene feedstock concentration:Middle Eastern petrochemical complexes control pipe-grade copolymer resin supply, exposing converters to naphtha-cracking economics and freight rate volatility.
- Per- and polyfluoroalkyl substance restrictions:ECHA proposals to limit PFAS processing aids force rapid extrusion reformulation without proven commercial alternatives.
- Cross-linked polyethylene substitution:PEX-A and PEX-B systems retain installer familiarity in North American residential plumbing, slowing PP-R penetration despite superior temperature ratings.
Strategic Opportunities
- Vietnam's Mekong Delta irrigation:Agricultural modernization programs create first-mover advantage for large-diameter PP-HM corrugated drainage in saltwater intrusion zones.
- Electrofusion welding automation:Convergence of servo-controlled joining equipment with cloud-based weld documentation opens industrial process piping contracts requiring full traceability.
- India's Smart Cities Mission:AMRUT 2.0 funding for non-revenue water reduction mandates corrosion-resistant distribution networks in 100 urban clusters.
Industry Challenges
- Certified fusion technician scarcity:Butt and socket welding competency gaps delay project commissioning in Southeast Asian infrastructure tenders.
- Multi-jurisdictional testing protocols:NSF/ANSI 14 potable water certification timelines diverge from BIS IS 15801 requirements, fragmenting product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polypropylene Pipes Market |
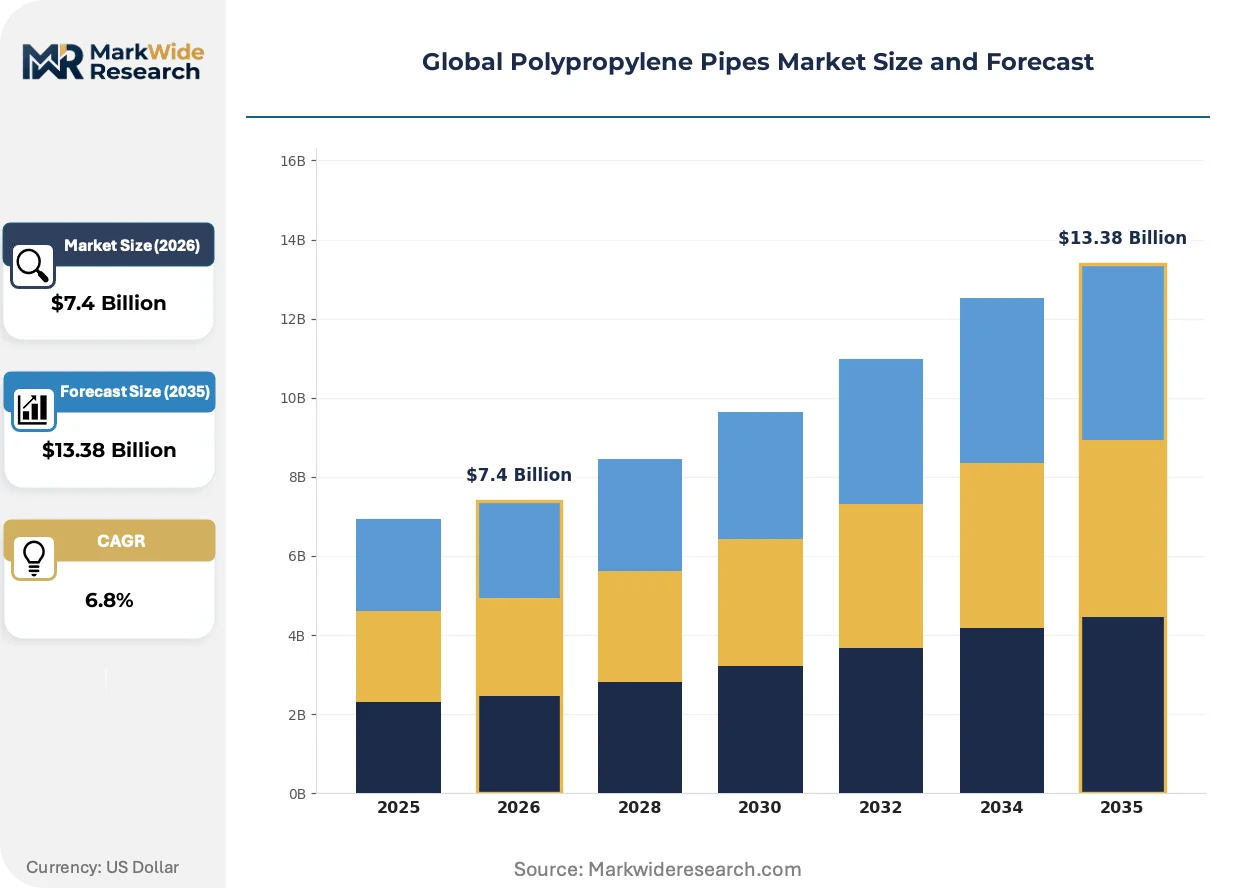
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PP-R, PP-B, PP-H, PP-RT Application: Plumbing, Irrigation, HVAC, Industrial Piping Size: Small Diameter, Medium Diameter, Large Diameter, Custom Size End User: Residential, Commercial, Industrial, Agricultural |
| Companies Covered | Aquatherm, Pipelife, Kalde, Wavin, Aliaxis, AGRU, Pestan, Aquatechnik, LESSO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polypropylene Pipes Market Shifts & Advancements
Active material substitution and regulatory chemistry restrictions are compressing formulation development cycles while elevating in-house compounding capabilities as a competitive differentiator.
Co-extruded PP-R/PP-RCT multilayer pipe with fiberglass or aluminum reinforcement is overtaking solid-wall alternatives in high-pressure hot-water distribution. German and Austrian plumbing contractors specify these composite systems for 16-bar district heating connections. The technology is overtaking conventional extrusion margins by enabling thinner wall designs that reduce resin consumption per meter.
ECHA's proposed PFAS restriction under REACH Annex XVII is forcing reformulation of extrusion lubricants and mold-release compounds by late 2025. Pipe producers with captive laboratory capacity are accelerating alternative additive qualification. Italian and Spanish compounders face the steepest compliance curves due to legacy reliance on fluorinated processing aids.
Engineering-procurement-construction firms in the Middle East are consolidating vendor lists around full-system suppliers capable of delivering pipe, fittings, and automated welding equipment under single-source contracts. Saudi Aramco's in-kingdom total value add requirements amplify this concentration. Local distributors without technical service capabilities are losing specification influence to manufacturer-direct sales organizations.
Global Polypropylene Pipes Market Segmentation
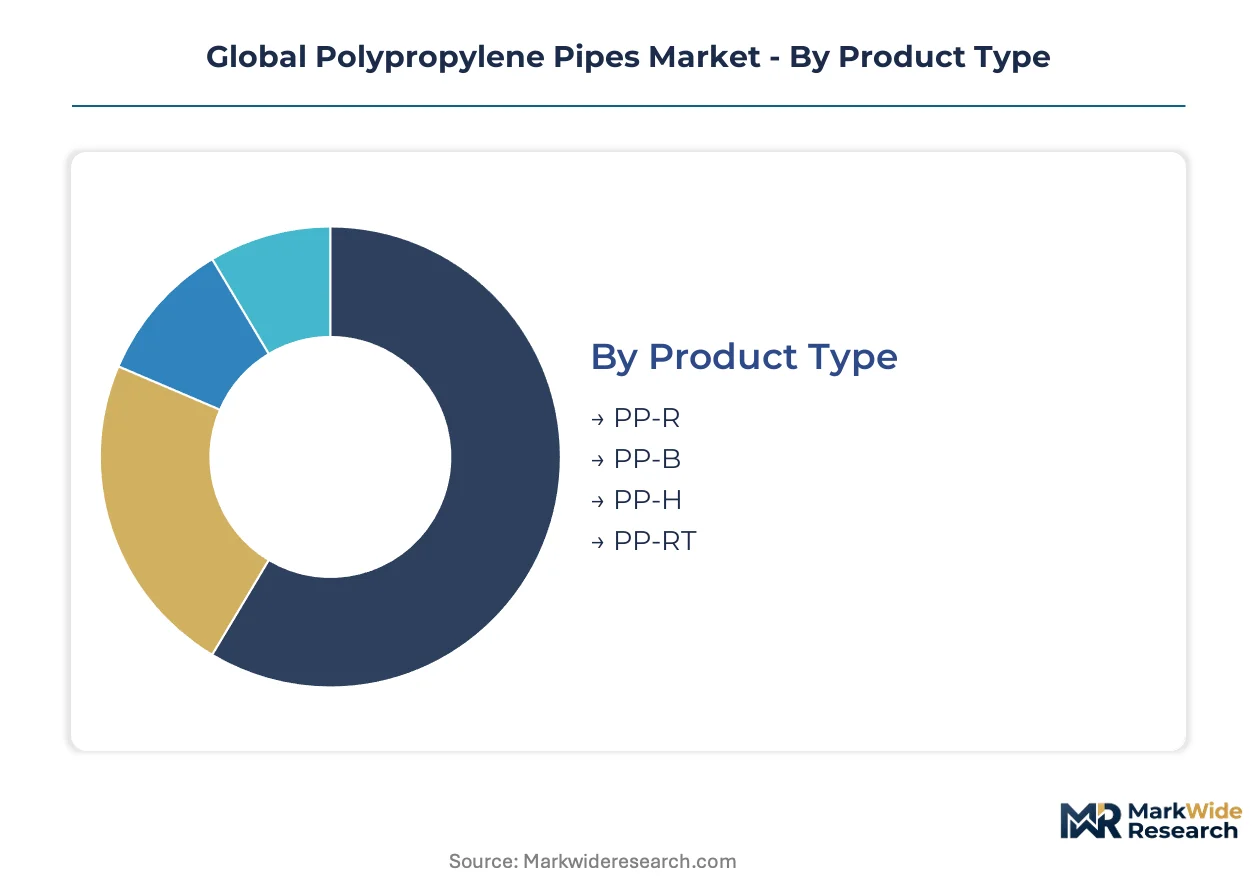
Polypropylene pipe specifications diverge sharply across pressure ratings, thermal envelopes, and jointing protocols. Material-grade selection directly determines which certification pathways producers must navigate and which contractor training investments distributors must underwrite.
Product Type:
Pipe-grade resin supply concentrates among Middle Eastern petrochemical complexes, forcing converters to align formulation strategies with feedstock availability windows.
- PP-R:Random copolymer molecular architecture delivers superior creep resistance at sustained elevated temperatures. Residential hot-water plumbing specifications in Germany and France specify PP-R for 70°C continuous service, driven by EU F-Gas Regulation mandates for lower-leakage HVAC circuits.
- PP-RT:Modified random copolymer with enhanced flexibility withstands thermal cycling stress in underfloor heating and radiator connection applications. Demand is climbing fastest in Austrian and Czech district heating retrofits where installation bend radius requirements favor pliable formulations over cross-linked polyethylene alternatives.
- PP-B:Block copolymer structure balances stiffness with moderate impact resistance for cold-water distribution and drainage gravity systems.
- PP-H:Homopolymer grade maximizes rigidity and chemical resistance for industrial process piping and aggressive fluid transport.
PP-R absorbs the bulk of installed capacity; PP-RT is expanding most quickly.
Application:
Project scale and pressure class requirements fragment procurement patterns across residential, commercial, and heavy industrial channels.
- Plumbing:Potable water distribution and sanitary drainage in residential and commercial buildings. India's tier-2 municipal codes in Indore and Lucknow displace galvanized iron with PP-RCT gravity systems, compressing legacy metal installation volumes.
- HVAC:Chilled water, heating circuits, and refrigeration piping. German contractors specify fusion-welded PP-R for 16-bar district heating connections as F-Gas Regulation tightens leakage tolerance.
- Irrigation:Agricultural drip and sprinkler systems favor small-diameter standardized products with high volume throughput but compressed margin pools.
- Industrial Piping:Chemical processing, food and beverage, and pharmaceutical fluid handling. Large-diameter custom fabrication concentrates margin capture among specialized extruders with in-house welding qualification laboratories.
Plumbing commands the largest share of extrusion output; HVAC specifications are climbing the fastest as building energy codes tighten.
Size:
Diameter class determines extruder capital intensity, tooling amortization schedules, and logistics configuration for coil versus straight-length delivery.
- Small Diameter:Nominal dimensions below 50mm dominate agricultural drip-irrigation and residential plumbing volumes. Standardized coil formats enable containerized export from Chinese and Turkish converters to Southeast Asian distributors.
- Medium Diameter:50mm to 160mm range captures commercial building services and municipal water distribution. AMRUT 2.0 funding in India targets non-revenue water reduction through corrosion-resistant medium-diameter networks in 100 urban clusters.
- Large Diameter:Exceeding 160mm for industrial process lines and drainage trunk sewers. Vietnam's Mekong Delta agricultural modernization creates first-mover openings for PP-HM corrugated drainage in saltwater intrusion zones.
- Custom Size:Project-specific dimensions for engineered process piping. EPC firms in Saudi Arabia consolidate vendor lists around full-system suppliers capable of delivering pipe, fittings, and automated welding equipment under single-source contracts.
Small diameter generates the highest unit volumes; large diameter carries the steepest expansion trajectory in infrastructure tenders.
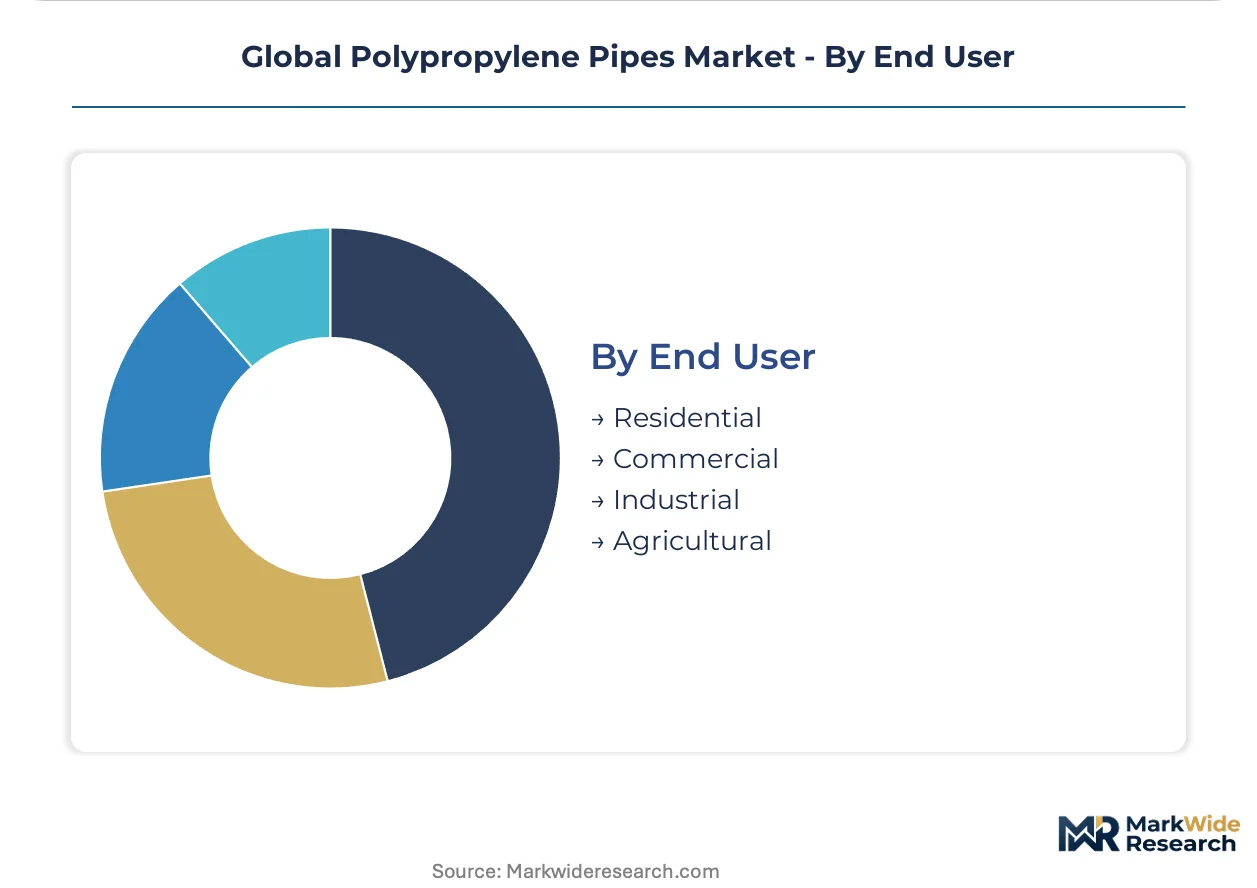
End User:
Customer type dictates specification authority, certification requirements, and channel structure from extruder to installation site.
- Residential:Single-family and multi-family housing plumbing and heating. PEX-A and PEX-B systems retain installer familiarity in US residential plumbing, slowing PP-R penetration despite superior temperature ratings.
- Commercial:Office buildings, hospitals, hotels, and retail complexes. REACH compliance and NSF/ANSI 14 potable water certifications fragment product development roadmaps for producers seeking cross-border contracts.
- Industrial:Manufacturing facilities, chemical plants, and power generation. Electrofusion welding automation with cloud-based weld documentation opens contracts requiring full traceability.
- Agricultural:Farm-level irrigation and drainage systems. Certified fusion technician scarcity delays project commissioning in Southeast Asian infrastructure tenders.
Residential absorbs the majority of compound consumption; industrial specifications are gaining share fastest on automation and traceability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Middle Eastern petrochemical complexes in Saudi Arabia and the UAE anchor pipe-grade copolymer resin supply, redirecting global feedstock flows toward Asian converters and European compounders. This geographic concentration shapes regional procurement strategies and margin structures across downstream markets.
Germany
District heating retrofits in Berlin and Hamburg drive specification shifts toward fusion-welded PP-R systems for 16-bar commercial connections. The EU F-Gas Regulation tightens leakage tolerance for HVAC circuits, mandating lower-leakage refrigeration piping in new builds. Bavarian plumbing contractors now specify co-extruded multilayer composites for high-pressure hot-water distribution.
India
AMRUT 2.0 funding targets non-revenue water reduction across 100 urban clusters, accelerating PP-RCT gravity sewer installations in tier-2 cities. BIS IS 15801 standards displace legacy galvanized iron in municipal codes for Indore and Lucknow. Maharashtra's industrial corridors witness rising demand for corrosion-resistant distribution networks in chemical processing zones.
United States
NSF/ANSI 14 potable water certification timelines fragment product development for cross-border producers seeking North American contracts. PEX-A and PEX-B systems retain installer familiarity in residential plumbing across Texas and Florida, compressing PP-R penetration despite superior temperature ratings. California's building energy codes tighten HVAC leakage standards, indirectly favoring fusion-jointed thermoplastic specifications.
Vietnam
Agricultural modernization programs in the Mekong Delta create first-mover openings for large-diameter PP-HM corrugated drainage in saltwater intrusion zones. Certified fusion technician scarcity delays project commissioning in Ho Chi Minh City infrastructure tenders. Da Nang's industrial zones attract pipe converters seeking proximity to Southeast Asian irrigation export markets.
Saudi Arabia
Saudi Aramco's in-kingdom total value add requirements consolidate vendor lists around full-system suppliers capable of delivering pipe, fittings, and automated welding equipment. Engineering-procurement-construction firms in Riyadh and the Eastern Province favor single-source contracts for industrial process piping. Local distributors without technical service capabilities lose specification influence to manufacturer-direct sales organizations.
Global Polypropylene Pipes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized fabrication and regional certification niches. The vendor base stratifies across three tiers: integrated resin-to-pipe compounders with captive laboratory capacity, mid-scale extruders serving municipal water tenders, and specialized fabricators focused on industrial process piping. Two dominant competitive moves define current positioning: backward integration into compounding assets to secure margin stability, and geographic expansion through distributor acquisition in high-growth Asian markets.
Among European integrated producers, Pipelife and AGRU exemplify the compounding-anchored archetype with upstream control over formulation development. Kalde occupies a position within the municipal water specialization tier, while Aquatherm represents the premium-systems vector targeting commercial HVAC specifications. These named entities illustrate how competitive positioning diverges across resin integration depth, welding technology ownership, and regional certification breadth rather than scale alone.
| Leading Market Players |
|---|
| Aquatherm |
| Pipelife |
| Kalde |
| Wavin |
| Aliaxis |
| AGRU |
| Pestan |
| Aquatechnik |
| LESSO |
| Others |
Supply & Pricing Matrix
Certified fusion technician scarcity in Southeast Asian infrastructure corridors widens pricing-tier spreads between premium bundled-service offerings and commodity pipe-only transactions. Labor-cost differentials between European compounding hubs and Indian extrusion clusters translate into three-tier pricing structures across warranty-backed installation systems.
Pricing Analysis
Warranty and installation-service bundling separates premium European producers from unbundled Asian commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and fusion-welding support depth. Pricing pressure stems from propylene feedstock volatility as Middle Eastern naphtha-cracking economics swing. Municipal contractors in India's tier-2 cities exhibit highest price sensitivity; German district heating EPCs prioritize leakage guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Jebel Ali, and Singapore anchor hub-and-spoke patterns for pipe-grade resin flows. Saudi Arabia, the UAE, and South Korea concentrate pipe-grade copolymer production. Extrusion lubricants, fiberglass reinforcement, and aluminum barrier layers constitute critical input dependencies. Single-source vulnerability to ECHA PFAS restriction timelines threatens reformulation continuity. Distribution runs through manufacturer-direct technical service organizations in Saudi Arabia and distributor networks in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where compounding-asset ownership determines margin stability against feedstock volatility. Players pursue backward integration into pipe-grade resin supply to escape naphtha-cracking economics.
For Market Incumbents: To counter Middle Eastern feedstock concentration, secure long-term offtake agreements with Saudi and UAE petrochemical complexes. Expand in-house testing laboratory capacity to accelerate ECHA PFAS alternative qualification. Deepen penetration of Central European municipal water networks through certified fusion technician training programs. For New Entrants and Emerging Players: Cloud-based weld documentation platforms offer the lowest-friction entry path into industrial process piping contracts. Target Vietnam's Mekong Delta agricultural modernization for large-diameter PP-HM corrugated drainage specifications. Pursue electrofusion welding automation partnerships with Middle Eastern EPC firms seeking single-source suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with specialized fabricators possessing captive welding qualification laboratories given traceability requirements in Saudi Aramco vendor consolidation. Five-to-ten year viability hinges on REACH Annex XVII compliance positioning. Monitor ECHA PFAS restriction implementation timelines as inflection indicator for reformulation-capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compounding Assets | Captive pipe-grade resin production insulates margin stability from naphtha-cracking volatility. |
| Electrofusion Welding Automation | Servo-controlled joining equipment with cloud documentation unlocks industrial traceability contracts. |
| ECHA PFAS Alternative Qualification | In-house laboratory capacity accelerates extrusion lubricant reformulation ahead of Annex XVII deadlines. |
| Regional Distribution Center Expansion | Singapore and Jebel Ali hubs reduce freight exposure for Southeast Asian infrastructure tenders. |
| Certified Fusion Technician Training | Competency programs accelerate project commissioning in India's AMRUT 2.0 urban clusters. |
Research Methodology
Trade databases, customs filings, and petrochemical industry reports formed the secondary backbone for resin flow analysis. Primary interviews with pipe extrusion plant managers, EPC procurement leads, municipal water authority engineers, and fusion welding equipment distributors combined with secondary validation. Bottom-up unit economics triangulated against top-down market sizing across product grades and regional production hubs.
Historical trendline analysis of installed capacity, specification shifts, and certification adoption patterns anchored the projection framework. Segmentation modeling spanned material grade, pressure class, jointing protocol, end-use application, and regional regulatory cluster. CAGRs derived from weighted average of demand elasticity coefficients and supply-side capacity expansion schedules. Feedstock price scenarios and ECHA regulatory timelines served as industry-specific forecast inputs.
The model holds under stable propylene copolymer supply and gradual PFAS phase-out implementation; deviation in Middle Eastern export policy or accelerated ECHA restriction enforcement would shift trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
PVDF Pipes Market
Pipes and Tubes
Kuwait PVC Pipes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market
Pipes and Tubes
Gas Pipe Fittings Market
Pipes and Tubes
Global Fiberglass Pipe Market
Pipes and Tubes
Bahrain PVC Pipes Market
Pipes and Tubes
HPLC Fused Silica Tube Market
Pipes and Tubes
Heat Shrink Tubing Market
Pipes and Tubes
Glass Reinforced Plastic (GRP) Piping Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
Plastic Pipe Market
Pipes and Tubes
PVC Pipes and Fittings Market
Pipes and Tubes
Global Polyethylene Pipes and Fittings Market
Pipes and Tubes
United States Copper Pipes and Tubes Market
Pipes and Tubes
Steel Tubes Market