
 Collapsible Metal Tubes Market | 2026-2036
Collapsible Metal Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Collapsible Metal Tubes Market Analysis
Aluminum is repositioning steel across mid-tier personal care applications due to superior corrosion resistance and lighter transport economics. Albea leverages integrated laminate-to-tube manufacturing across European plants to sustain cost discipline in premium cosmetic segments. Essel Propack Limited anchors South Asian supply chains with high-speed extrusion lines calibrated for pharmaceutical-grade barrier specifications. Hoffmann Neopac AG specializes in small-batch decorative tubes, competing through Swiss precision tooling and rapid color-change capabilities.
Collapsible metal tubes are cylindrical containers fabricated from aluminum, steel, or copper alloys, typically ranging from 10mm to 50mm in diameter, with internal linings or coatings to prevent product-metal interaction; they collapse under finger pressure to dispense viscous contents without air ingress, serving pharmaceutical, cosmetic, and industrial adhesive sectors. Aluminum tubes lead value contribution due to established recycling infrastructure and compatibility with epoxy-phenolic internal coatings, while pharmaceutical applications represent the fastest-expanding segment as barrier-laminated constructions displace conventional plastic alternatives for oxygen-sensitive ointments. Steel occupies mature industrial adhesive channels where puncture resistance outweighs weight considerations, and margin pools concentrate in custom-printed, small-diameter formats for dermatological and ophthalmic preparations.
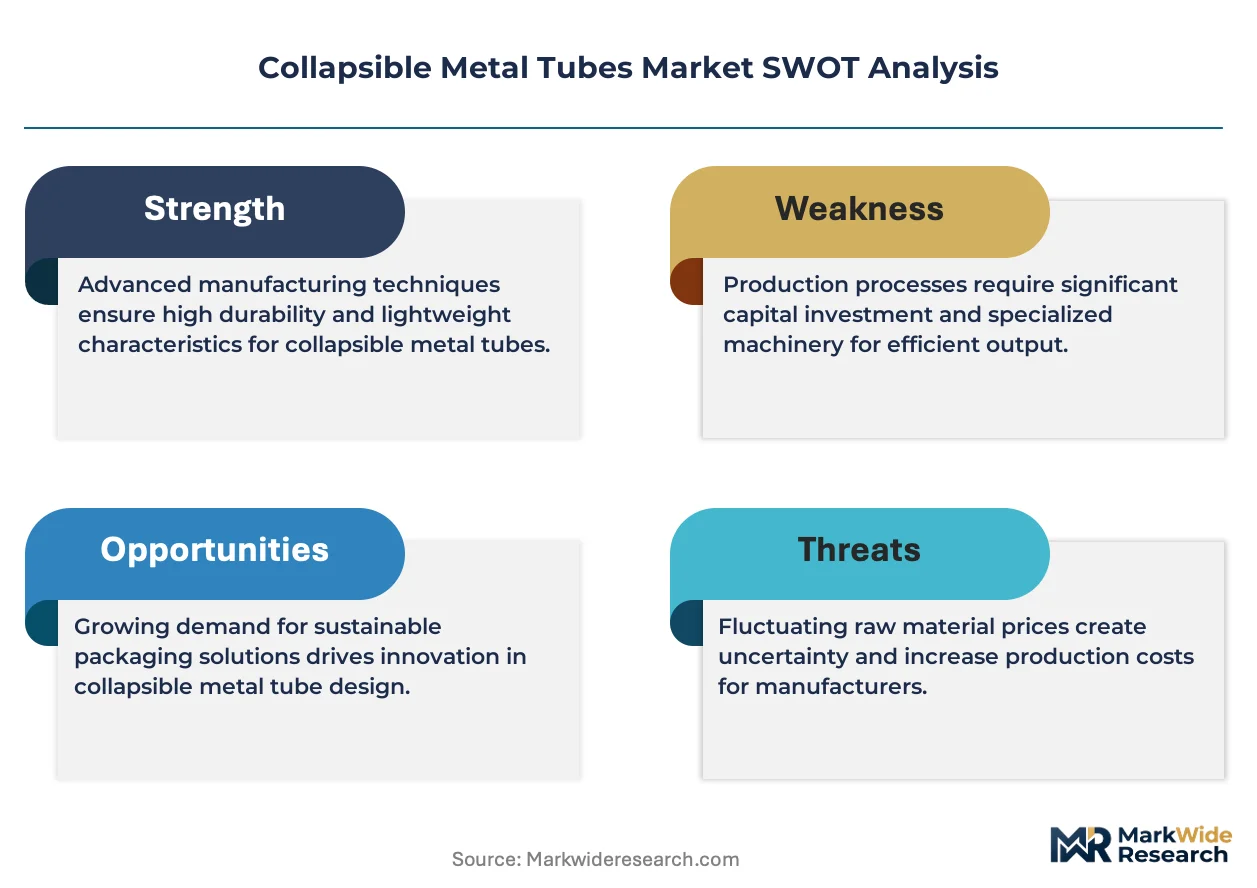
FDA guidelines on pharmaceutical container closure integrity, REACH substance restrictions under ECHA oversight, and India's BIS certification for food-contact metals collectively elevate compliance costs for tube importers while creating protected demand zones for certified domestic manufacturers. The EU Green Deal packaging waste directives are accelerating aluminum recycling rate disclosures across European supply chains. Stakeholders must monitor evolving laminate adhesion standards and regional recycling quota enforcement to align capacity investments with compliance-ready demand corridors.
Market Dynamics
Pharmaceutical-grade barrier laminates are compressing conventional plastic tube demand as oxygen-sensitive ointment manufacturers prioritize container closure integrity under tightening FDA and EMA standards.
Growth Catalysts
- REACH Substance Restrictions:ECHA oversight of epoxy-phenolic coating chemistries is filtering out non-compliant imports, creating protected demand corridors for certified European aluminum tube producers serving dermatological preparations.
- Aluminum Recycling Infrastructure:Established collection and reprocessing networks in Germany and Brazil reduce virgin material dependence for cosmetic tube manufacturers pursuing EU Green Deal packaging waste disclosures.
- Barrier-Enhanced Extrusion:High-speed laminate-to-tube integration enables pharmaceutical contract packagers to meet oxygen transmission rate specifications for ophthalmic and topical hormone formulations.
Market Restraints
- Steel Input Cost Volatility:Thermal coal and iron ore price swings compress margin stability for industrial adhesive tube producers in mature puncture-resistance applications.
- Substitution by Polymer Tubes:Multi-layer plastic laminates with ethylene vinyl alcohol barriers capture mid-tier personal care volumes where weight minimization outweighs recyclability premiums.
- Copper Alloy Supply Concentration:Limited secondary smelter capacity in Chile and Peru constrains small-diameter specialty tube availability for high-viscosity industrial sealants.
Strategic Opportunities
- India's PLI Scheme for Packaging:Production-linked incentives for pharmaceutical manufacturing clusters in Hyderabad and Ahmedabad are pulling domestic tube extrusion capacity expansion for export-ready barrier specifications.
- Sustainable Aviation Fuel Logistics:Collapsible aluminum tubes configured for sealant and adhesive dispensing in aircraft maintenance represent an emerging aerospace aftermarket channel.
- Digital Print Convergence with Barrier Coatings:UV-cured inkjet decoration integrated inline with epoxy-phenolic lining application enables lot-size-one cosmetic tube production without changeover downtime.
Industry Challenges
- Laminate Adhesion Certification Timelines:Extended validation protocols for pharmaceutical container closure integrity under USP <1207> delay new tube supplier qualification by 18-24 months.
- Tooling Skill Scarcity:Swiss and German precision metal-forming expertise for small-batch decorative tube production concentrates among retiring technician cohorts without structured apprenticeship pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collapsible Metal Tubes Market |
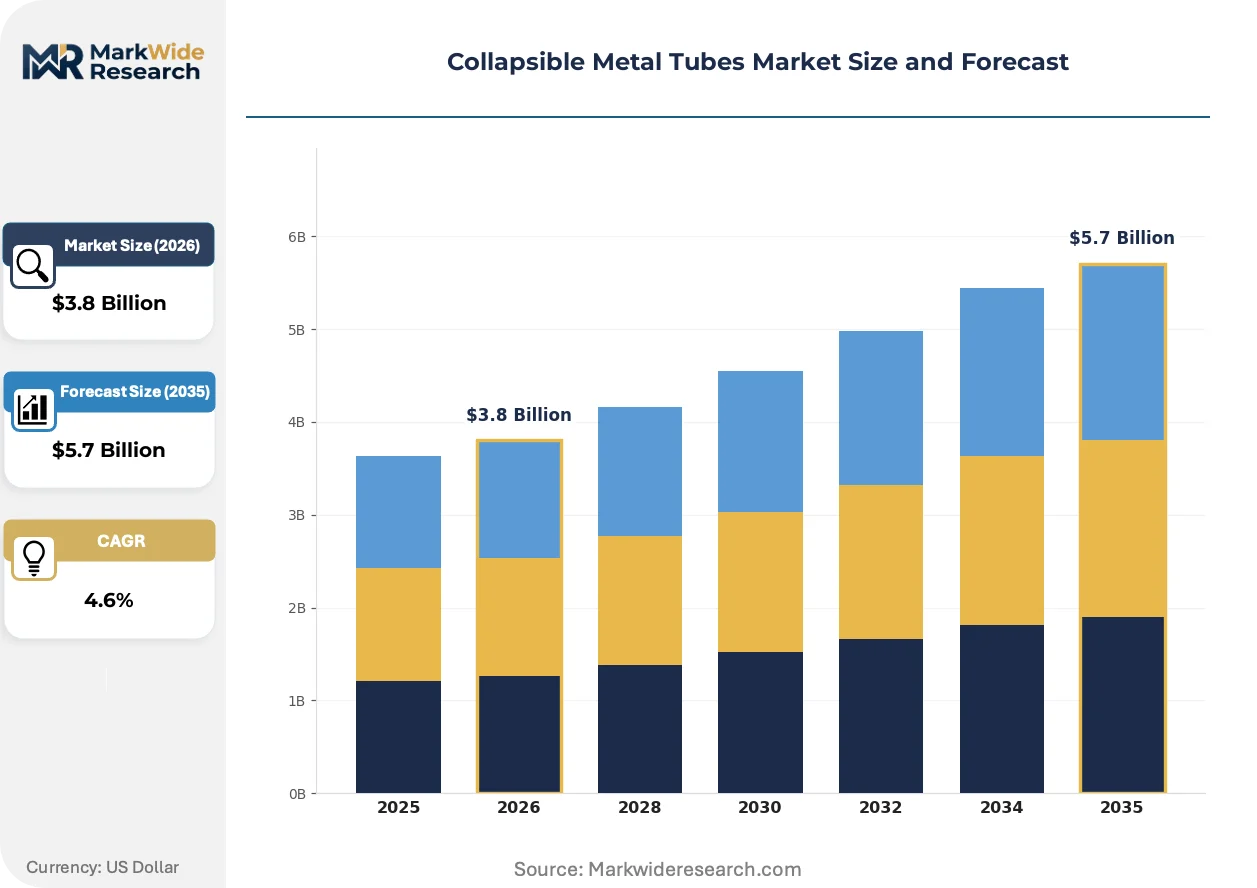
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Aluminum, Steel, Copper Application: Beauty Products, Food Packaging, Pharmaceuticals, Adhesives End User: Consumer Goods, Industrial, Healthcare, Food & Beverage Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Albea, Essel Propack Limited, Amcor Limited, Sonoco Products Company, Hoffmann Neopac AG, Montebello Packaging Inc., LINHARDT GmbH & Co. KG, Huhtamaki Oyj, AptarGroup Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collapsible Metal Tubes Market Emerging Trajectories
Electrochemical coating deposition and inline spectroscopic quality verification are compressing defect rates while enabling thinner aluminum gauges without sacrificing barrier performance.
Ultrathin ceramic-oxide barrier coatings applied via plasma-enhanced chemical vapor deposition are electrifying pharmaceutical tube specifications. Oxygen-sensitive biologic ointment formulators in Switzerland and Denmark are specifying these constructions for 36-month stability requirements. The technology is compressing conventional epoxy-phenolic laminate thicknesses and reducing aluminum gauge weights by 15-20 percent.
EU Green Deal packaging waste directives are mandating aluminum recycling rate disclosures across cosmetic supply chains. Brand owners now require tube suppliers to document post-consumer scrap content through mass-balance certification. Premium skincare marketers in France and Italy are responding by sourcing exclusively from extruders with integrated remelt facilities.
Direct-to-manufacturer procurement platforms are disintermediating traditional packaging distributors for mid-volume pharmaceutical tube buyers. Hospital-system central procurement offices in Germany and the Netherlands are consolidating SKU counts and negotiating specification-standardized contracts directly with Albea and Hoffmann Neopac. This channel compression is most visible in ophthalmic tube volumes where lot traceability requirements favor single-source accountability.
Collapsible Metal Tubes Market Segmentation
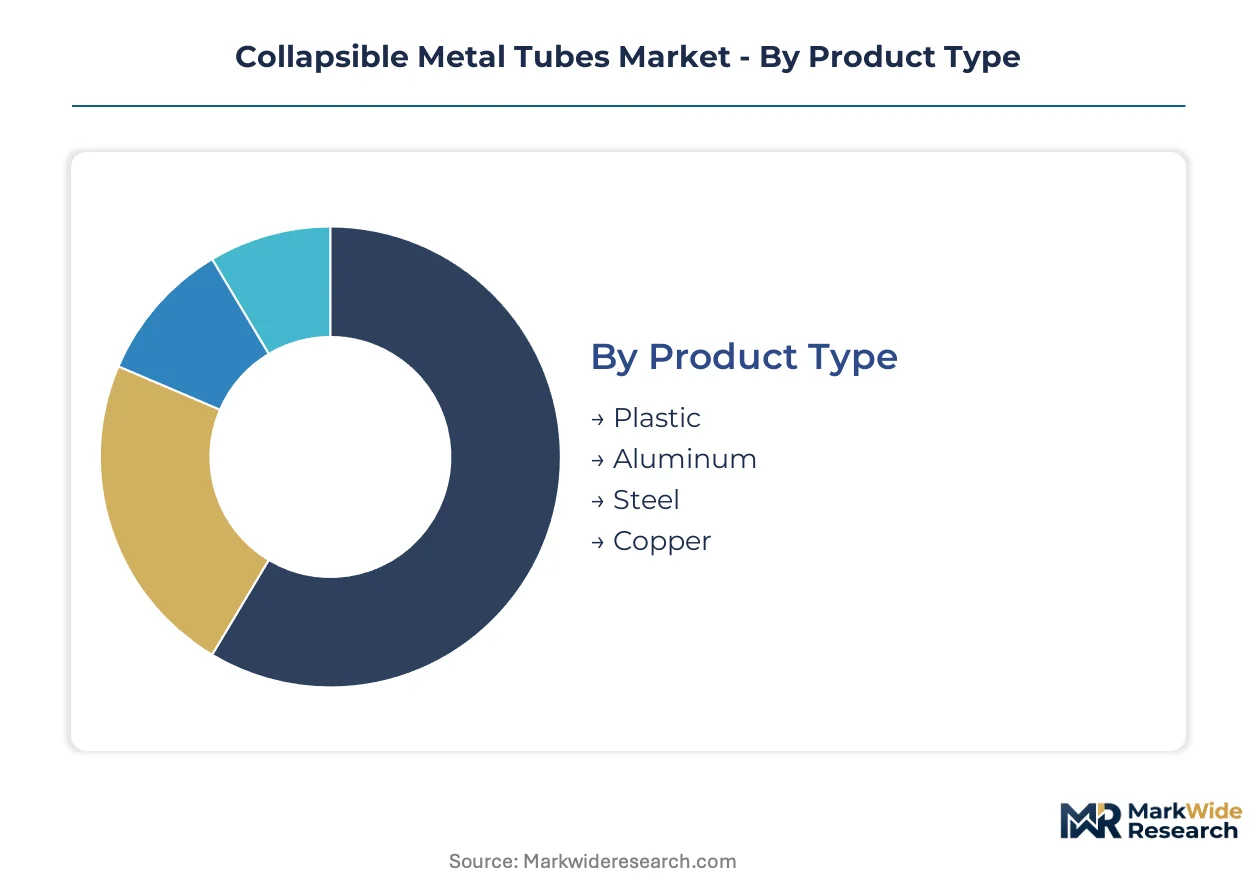
Tube specification varies sharply by barrier requirement, collapse mechanics, and regulatory load. Each segment commands distinct tooling investments and certification timelines that reshape supplier economics.
Product Type:
Supply concentration clusters around aluminum extrusion capacity in Germany and India, where integrated laminate-to-tube lines achieve pharmaceutical-grade oxygen transmission specifications.
- Aluminum:Epoxy-phenolic internal coatings bond to 99.7% pure aluminum substrates, enabling 36-month stability for oxygen-sensitive dermatological preparations. Demand concentrates in Swiss and Danish biologic ointment formulators specifying ultrathin ceramic-oxide barrier constructions. REACH compliance on coating chemistries filters non-European imports, protecting certified domestic producers.
- Steel:Cold-rolled tinplate constructions deliver puncture resistance for high-viscosity industrial adhesives. Thermal coal and iron ore input volatility compress margin stability for producers serving mature puncture-resistance channels in Brazil and Germany.
- Plastic:Multi-layer laminates with ethylene vinyl alcohol barriers capture mid-tier personal care volumes where weight minimization outweighs recyclability premiums.
- Copper:Small-diameter specialty tubes serve high-viscosity industrial sealants; limited secondary smelter capacity in Chile and Peru constrains availability.
Today's leader: Aluminum. Tomorrow's challenger: Steel in aerospace maintenance channels.
Application:
Cost tier stratification separates premium barrier-laminated pharmaceutical tubes from commodity cosmetic and food-contact formats.
- Pharmaceuticals:Barrier-enhanced constructions displace conventional plastic alternatives for oxygen-sensitive ointments under tightening FDA container closure integrity guidelines. USP <1207> validation protocols extend supplier qualification timelines.
- Beauty Products:Custom-printed small-diameter formats command margin concentration in dermatological and ophthalmic preparations; Swiss precision tooling enables rapid color-change capabilities for premium skincare marketers.
- Adhesives:Puncture-resistant steel tubes dominate industrial channels where transport durability outweighs weight considerations.
- Food Packaging:BIS certification requirements for food-contact metals in India create protected demand zones for certified domestic manufacturers.
Pharmaceuticals climb the fastest. Beauty Products defend the deepest margin pools.
End User:
Volume concentration tracks pharmaceutical manufacturing cluster expansion in Hyderabad and Ahmedabad under India's PLI scheme for packaging.
- Healthcare:Hospital-system central procurement offices in Germany and the Netherlands consolidate ophthalmic tube SKU counts, negotiating specification-standardized contracts directly with extruders for lot traceability accountability.
- Consumer Goods:Premium skincare brand owners in France and Italy require mass-balance certification of post-consumer scrap content through integrated remelt facilities.
- Industrial:Sustainable aviation fuel logistics generate emerging demand for sealant-dispensing aluminum tubes in aircraft maintenance aftermarket channels.
- Food & Beverage:EU Green Deal packaging waste directives mandate recycling rate disclosures across cosmetic supply chains, elevating compliance documentation burdens.
Healthcare drives specification intensity. Consumer Goods transmit sustainability premiums upstream.
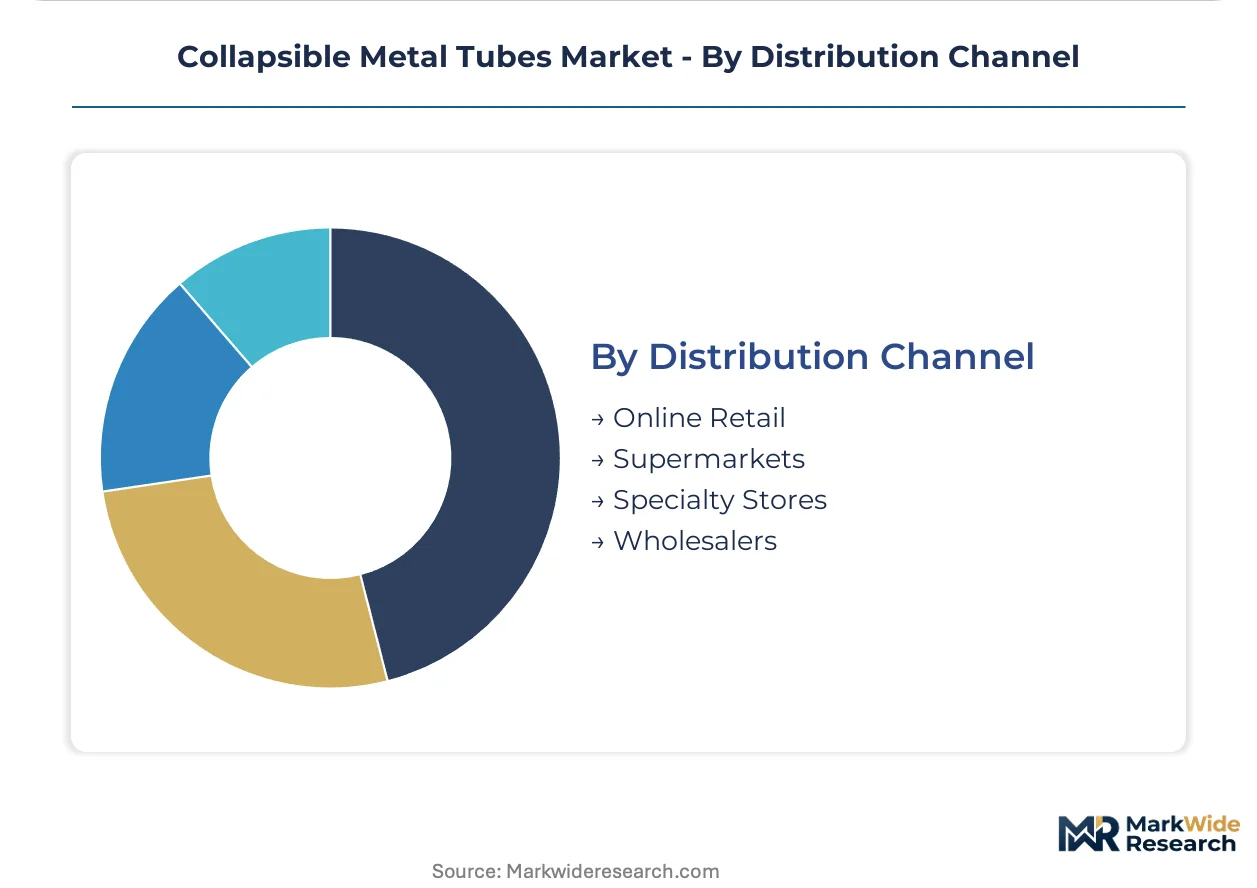
Distribution Channel:
Customer type fragmentation separates direct procurement by hospital-system offices from traditional distributor-mediated personal care volumes.
- Online Retail:Direct-to-manufacturer procurement platforms disintermediate traditional packaging distributors for mid-volume pharmaceutical tube buyers seeking specification standardization.
- Wholesalers:Consolidated contracts with extruders enable volume-scale pricing for regional pharmaceutical contract packagers in Brazil and India.
- Specialty Stores:Small-batch decorative tube sourcing concentrates through Swiss precision tooling networks serving premium cosmetic marketers.
- Supermarkets:Mass-market personal care tube procurement favors high-speed extrusion lines calibrated for barrier specifications at scale.
Online Retail compresses channel layers fastest. Wholesalers retain industrial adhesive volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr corridor concentrates the highest-value aluminum tube extrusion capacity, with integrated laminate-to-tube lines serving Swiss pharmaceutical formulators. Demand disperses across four additional national manufacturing clusters where regulatory load and end-use specifications diverge sharply.
United States
FDA container closure integrity guidelines tighten qualification timelines for oxygen-sensitive ointment tubes. Hospital-system central procurement offices in Greater Boston and the Research Triangle consolidate ophthalmic SKU counts, negotiating direct contracts with extruders for lot traceability. New Jersey and Pennsylvania host contract packaging clusters serving dermatological preparations.
Germany
REACH substance restrictions under ECHA oversight filter non-compliant coating chemistries, protecting certified domestic producers. The EU Green Deal mandates aluminum recycling rate disclosures across cosmetic supply chains. North Rhine-Westphalia and Bavaria anchor integrated remelt facilities supplying premium skincare marketers in France and Italy.
India
BIS certification requirements for food-contact metals create protected demand zones for certified domestic manufacturers. The PLI scheme for packaging pulls extrusion capacity expansion toward Hyderabad and Ahmedabad pharmaceutical clusters. Gujarat and Maharashtra contract packagers calibrate high-speed lines for export-ready barrier specifications.
Brazil
Thermal coal and iron ore input volatility compress margin stability for industrial adhesive tube producers. Established aluminum collection networks reduce virgin material dependence for cosmetic manufacturers. São Paulo and Minas Gerais house regional producers scaling capacity to serve Latin American pharmaceutical and cosmetics clusters.
Switzerland
Swissmedic oversight elevates barrier specifications for biologic ointment formulators specifying 36-month stability. Swiss precision tooling expertise concentrates among small-batch decorative tube specialists. Basel and Zurich regions host contract manufacturers serving ophthalmic and dermatological preparations with rapid color-change capabilities.
Collapsible Metal Tubes Market Vendor Landscape
Capacity expansion dominates the current landscape as regional producers scale extrusion lines to capture pharmaceutical-grade demand. The vendor base separates into three tiers: integrated multinational laminate-to-tube operators, mid-scale national extruders with certified coating capabilities, and precision tooling specialists serving small-batch decorative segments. Two strategic archetypes predominate: backward-integrated aluminum processors controlling remelt-to-tube workflows, and pharmaceutical-focused contract packagers qualifying barrier constructions under USP protocols. Competitive intensity concentrates in M&A activity targeting coating technology assets and geographic expansion into India's PLI-subsidized manufacturing corridors.
Among European-integrated operators, Albea and Hoffmann Neopac AG occupy positions at opposite ends of the volume spectrum. Albea exemplifies the scale-driven archetype with laminate-to-tube integration across multiple national plants. Hoffmann Neopac AG represents the precision-specialist tier, with Swiss-based operations calibrated for rapid color-change cosmetic production. At the Asian scale end, Essel Propack Limited anchors the mid-tier national extruder category, with Indian operations positioned to serve PLI-subsidized pharmaceutical clusters in Hyderabad and Ahmedabad.
| Leading Market Players |
|---|
| Albea |
| Essel Propack Limited |
| Amcor Limited |
| Sonoco Products Company |
| Hoffmann Neopac AG |
| Montebello Packaging Inc. |
| LINHARDT GmbH & Co. KG |
| Huhtamaki Oyj |
| AptarGroup Inc. |
| Others |
Supply Flow & Price Mechanics
Swiss precision tooling expertise concentrated around Basel and Zurich sustains labor-cost premiums that widen spreads between premium cosmetic tubes and commodity pharmaceutical formats. These skill premiums compress margins for small-batch decorative producers while protecting pricing power for barrier-laminated pharmaceutical specifications.
Pricing Analysis
Input-cost pass-through from thermal coal and iron ore volatility compresses margin stability for steel tube producers serving Brazilian industrial adhesive channels. Three-tier pricing structure across premium barrier-laminated, standard epoxy-phenolic, and economy unlined formats separates pharmaceutical-grade certifications from cosmetic commodity volumes. Pricing pressure stems from multi-layer plastic laminate substitution in mid-tier personal care where weight minimization outweighs recyclability premiums. Hospital-system procurement offices exhibit lowest price sensitivity due to USP validation requirements, while mass-market personal care buyers drive hardest bargain negotiation.
Supply Chain Analysis
Regional distribution centers in North Rhine-Westphalia, Bavaria, and São Paulo anchor hub-and-spoke patterns for aluminum tube delivery to European and Latin American pharmaceutical clusters. Geographic supply concentrates in Germany, India, and Brazil where integrated laminate-to-tube lines achieve pharmaceutical-grade oxygen transmission specifications. Raw material dependencies draw from 99.7% pure aluminum ingot, epoxy-phenolic coating chemistries, and cold-rolled tinplate steel. Single-source vulnerability in Swiss precision tooling expertise for small-batch production concentrates risk among retiring technician cohorts. Distribution runs through direct-to-manufacturer procurement platforms for mid-volume pharmaceutical buyers and traditional wholesalers for industrial adhesive volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Collapsible metal tubes function as a stable compounder anchored by pharmaceutical packaging's irreversible shift toward barrier-enhanced aluminum for oxygen-sensitive formulations.
For Market Incumbents: Acquire coating technology assets with validated USP adhesion protocols to compress 18-24 month supplier qualification timelines that currently block new entrant access. Secure backward integration into aluminum remelt facilities to meet EU Green Deal mass-balance certification requirements from French and Italian premium skincare marketers. Defensive positioning requires capacity expansion in India's PLI-subsidized Hyderabad and Ahmedabad corridors before regional producers capture export-ready barrier specification demand. For New Entrants and Emerging Players: Enter via aerospace maintenance aftermarket channels for sealant-dispensing aluminum tubes in sustainable aviation fuel logistics, a white-space segment with minimal incumbent presence. Target India's BIS-certified food-contact metal tube segment where import restrictions create protected demand zones for certified domestic manufacturers. Go-to-market leverage rests on direct procurement platform relationships with hospital-system central purchasing offices seeking specification standardization and lot traceability accountability. For Investors and Strategic Acquirers: Pharmaceutical contract packagers are the most active acquirer in this space, targeting barrier-lamination technology assets to qualify under tightening FDA container closure integrity guidelines. Long-term viability frames around 5-10 year pharmaceutical-grade demand acceleration as biologic ointment formulators displace plastic alternatives. Acquisition target archetype: mid-scale national extruders with certified coating capabilities and pending USP validation. Signal to watch: laminate adhesion certification timeline compression via inline spectroscopic quality verification adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Essel Propack Limited scales high-speed extrusion lines to serve PLI-subsidized Indian pharmaceutical clusters. |
| Backward Integration | Albea's remelt facility investments secure mass-balance certification for EU Green Deal compliance. |
| Regulatory Certification Investment | USP adhesion protocol validation compresses 18-24 month supplier qualification barriers for new market entrants. |
| Long-term Supply Agreement | Direct contracts with German hospital-system procurement offices consolidate ophthalmic tube SKU counts. |
| Acquisition of Specialist Firm | Coating technology assets with validated barrier specifications attract pharmaceutical contract packager buyers. |
Methodological Framework
Direct dialogue with tube extrusion plant managers, pharmaceutical contract packaging procurement leads, cosmetic brand supply planners, and precision tooling technicians grounded qualitative findings in operational reality. Secondary validation drew from ECHA REACH substance restriction filings, FDA container closure integrity guidelines, BIS food-contact metal certifications, EU Green Deal packaging waste directives, and SEC disclosures from listed packaging manufacturers. Bottom-up and top-down triangulation reconciled capacity utilization data with demand-side pharmaceutical cluster expansion patterns.
Bottom-up modeling anchored volume projections to named extrusion line counts and pharmaceutical manufacturing cluster buildouts across the analysis window. Segmentation dimensions spanned material substrate, barrier construction tier, end-use application, and regional regulatory cluster. CAGRs derived from weighted average of capacity expansion schedules and demand pull from oxygen-sensitive ointment formulation trends. Industry-specific inputs included laminate adhesion certification timelines and aluminum recycling rate disclosure trajectories under EU Green Deal mandates.
Inputs from ECHA regulatory filings, FDA guidance documents, and Indian PLI scheme announcements were available through the study window; gaps in real-time capacity utilization data from private extrusion facilities introduce uncertainty bands around near-term supply estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Industrial Tubes Market
Pipes and Tubes
Global Fiberglass Pipe Market
Pipes and Tubes
GRE Pipes Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
Global Butt Weld Fittings Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
HDPE Pipes Market
Pipes and Tubes
Saudi Arabia PPR Pipes Market
Pipes and Tubes
Acid Resistant Pipe Market
Pipes and Tubes
Drum Funnel Market
Pipes and Tubes
Bahrain PVC Pipes Market
Pipes and Tubes
North America PVC Pipes Market
Pipes and Tubes
Saudi Arabia PE Pipes Market
Pipes and Tubes
Compressed Air Pipe Market
Pipes and Tubes
Thermoplastic Pipe Market
Pipes and Tubes
HDPE Corrugated Pipe Market