
 Chemical Feed Systems Market | 2026-2036
Chemical Feed Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Feed Systems Market Analytics
Modular skid packaging is hardening as the default procurement format for large-scale water treatment projects. Grundfos Holding A/S leverages its vertical integration in pump manufacturing to deliver fully integrated chemical feed skids with embedded controllers. ProMinent GmbH anchors its competitive position through specialized electrochemical sensor integration within its dosing systems. Milton Roy sustains technology leadership in high-pressure diaphragm pump architectures for oilfield chemical injection applications.
Chemical feed systems comprise precision-engineered equipment for controlled dosing of treatment chemicals, typically incorporating positive displacement pumps with accuracy tolerances of plus or minus one percent, corrosion-resistant wetted materials such as PVC or 316 stainless steel, and programmable logic controllers for flow-proportional delivery. These systems serve the essential industrial purpose of maintaining chemical concentration within process specifications across water treatment, manufacturing, and agricultural applications. Pumps command the largest product category due to their universal necessity across every installation configuration, while automated technology segments capture expanding margin pools as utilities prioritize remote monitoring and reduced operator intervention. Water treatment applications dominate absolute volume, though pharmaceutical production represents the fastest-growing application segment driven by sterile process validation requirements and clean-in-place protocol expansion.
EPA regulations under the Safe Drinking Water Act and Clean Water Act mandate precise residual disinfectant maintenance, directly shaping pump accuracy specifications and telemetry requirements for municipal end users. EU REACH compliance and the F-Gas Regulation additionally constrain polymer and seal material selections, elevating demand for fluoropolymer-compatible system architectures. Stakeholders must evaluate how emerging per- and polyfluoroalkyl substance restrictions will cascade through seal and gasket supply chains, potentially forcing material transitions that alter system compatibility matrices and maintenance protocols across installed bases.
Market Dynamics
Modular skid packaging is displacing field-fabricated installations as municipal utilities prioritize reduced commissioning timelines and factory-verified calibration accuracy. This shift concentrates procurement power among vertically integrated pump OEMs capable of delivering complete plug-and-play systems.
Growth Catalysts
- EPA residual disinfectant mandates:Safe Drinking Water Act enforcement compels municipal utilities to upgrade manual dosing stations with automated feedback-controlled systems. Small and mid-sized water districts in the US Midwest are accelerating retrofit schedules.
- EU F-Gas Regulation compliance:Fluorinated gas restrictions are forcing seal and gasket material transitions toward perfluoroelastomer alternatives. System OEMs are redesigning wetted component architectures to maintain chemical compatibility.
- Industrial corridor densification:Petrochemical and power generation clusters in China's coastal provinces are standardizing on corrosion-resistant injection packages. State-owned refinery operators specify 316 stainless steel or PVC-wetted systems for sulfuric acid and caustic soda handling.
Market Restraints
- Fluoropolymer feedstock concentration:Perfluoroelastomer seal production concentrates among three specialty chemical suppliers in Western Europe and Japan. PFAS regulatory scrutiny is constraining capacity expansion timelines.
- Precision machining bottleneck:High-pressure diaphragm pump head manufacturing requires five-axis CNC equipment with sub-micron tolerance capabilities. Machine tool lead times from German and Swiss suppliers now exceed fourteen months.
- Skilled commissioning technician scarcity:Factory-authorized service networks for PLC-integrated skids remain thin outside major metropolitan areas. Rural utility operators face six-week minimum wait times for startup support.
Strategic Opportunities
- Pharmaceutical sterile process expansion:Clean-in-place protocol adoption is creating demand for electrochemical sensor-integrated dosing systems. Validation documentation packages now represent a discrete revenue stream.
- Remote telemetry unbundling:Cloud-based monitoring subscriptions are separating from hardware sales. Municipal utilities in Germany and France are procuring ten-year service agreements alongside initial capital equipment.
- India industrial wastewater retrofit:Central Pollution Control Board effluent standards are tightening for textile and tannery clusters. State-level pollution control boards in Gujarat and Tamil Nadu are mandating automated chemical precipitation systems.
Industry Challenges
- Legacy SCADA integration complexity:Brownfield water treatment plants operate proprietary communication protocols from 1990s-era distributed control systems. New skid-mounted PLCs require protocol gateway hardware that extends commissioning timelines.
- Electrochemical sensor calibration drift:Chlorine residual analyzers in high-turbidity source water require biweekly manual verification. Operator labor availability constrains the realized accuracy of automated feedback loops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Feed Systems Market |
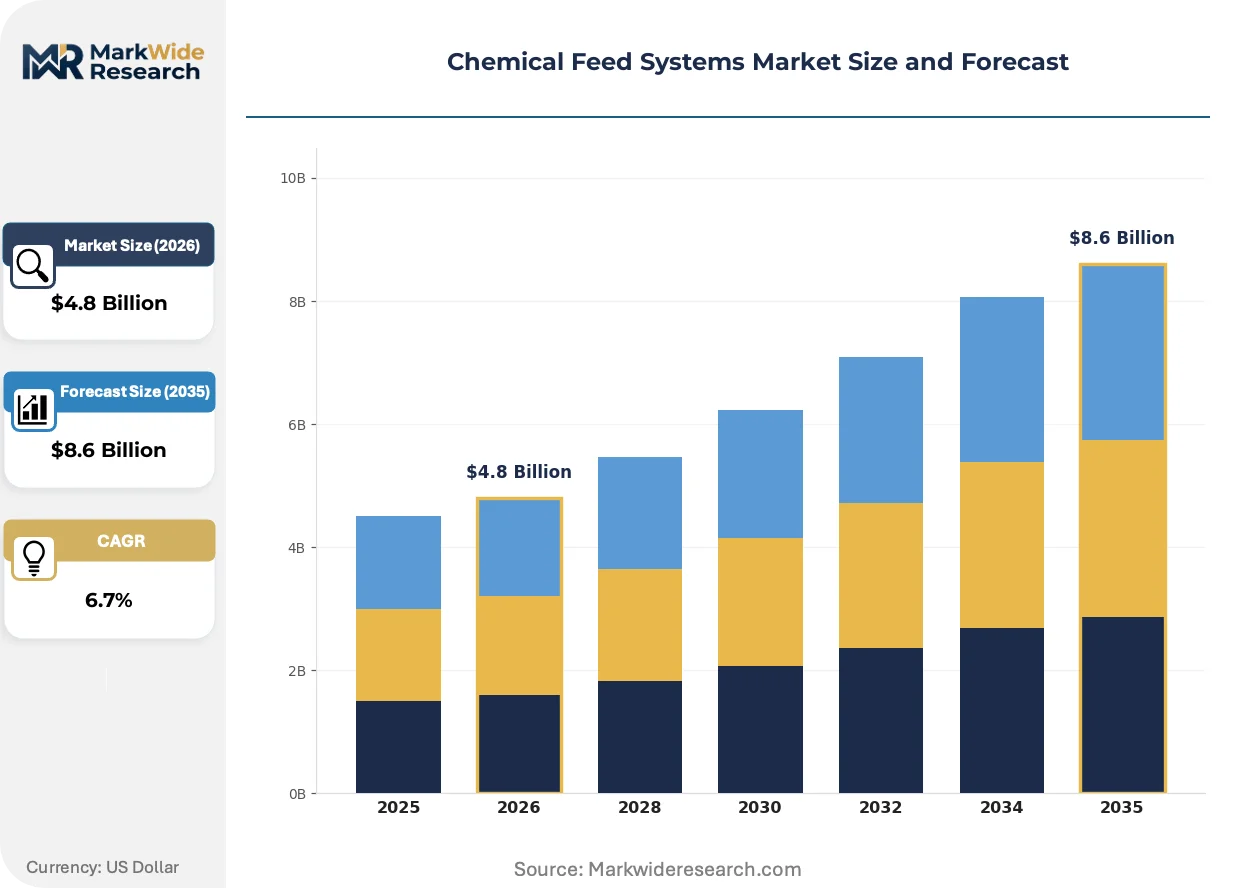
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pumps, Injectors, Controllers, Sensors Application: Water Treatment, Agriculture, Food Processing, Pharmaceutical Production End User: Municipalities, Manufacturing Plants, Farms, Laboratories Technology: Electromechanical, Pneumatic, Hydraulic, Automated |
| Companies Covered | Grundfos Holding A/S, ProMinent GmbH, Milton Roy, Neptune Chemical Pump Company, SEKO S.p.A., IDEX Corporation, Blue-White Industries, Verder Group, LMI Pumps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Feed Systems Market Evolving Landscape
Electrification of pump prime movers is compressing maintenance intervals and enabling variable-speed flow control without mechanical stroke adjustment. This shift is reshaping competitive differentiation around motor-drive integration rather than hydraulic design alone.
Permanent magnet synchronous motors paired with variable frequency drives are electrifying the standard architecture for mid-size chemical feed pumps. Municipal water utilities in California and Texas are specifying these packages for energy efficiency compliance with state-level clean energy mandates. The technology is compressing total cost of ownership calculations by eliminating mechanical seal wear and enabling precise flow turndown ratios.
EU REACH authorization requirements for chromium trioxide in hard chrome plating are forcing pump component manufacturers toward thermal spray ceramic coatings. Diaphragm pump plunger manufacturers in Germany and Italy are qualifying tungsten carbide-cobalt alternatives. High-pressure oilfield injection applications are experiencing extended qualification timelines as coating adhesion testing protocols mature.
Utility procurement departments are unbundling aftermarket consumables from original equipment contracts. Large municipal water authorities in the United Kingdom and Australia are establishing multi-year framework agreements with third-party seal and diaphragm suppliers. This behavior is most visible in metropolitan utilities with centralized maintenance workshops and reverse engineering capabilities.
Chemical Feed Systems Market Segmentation
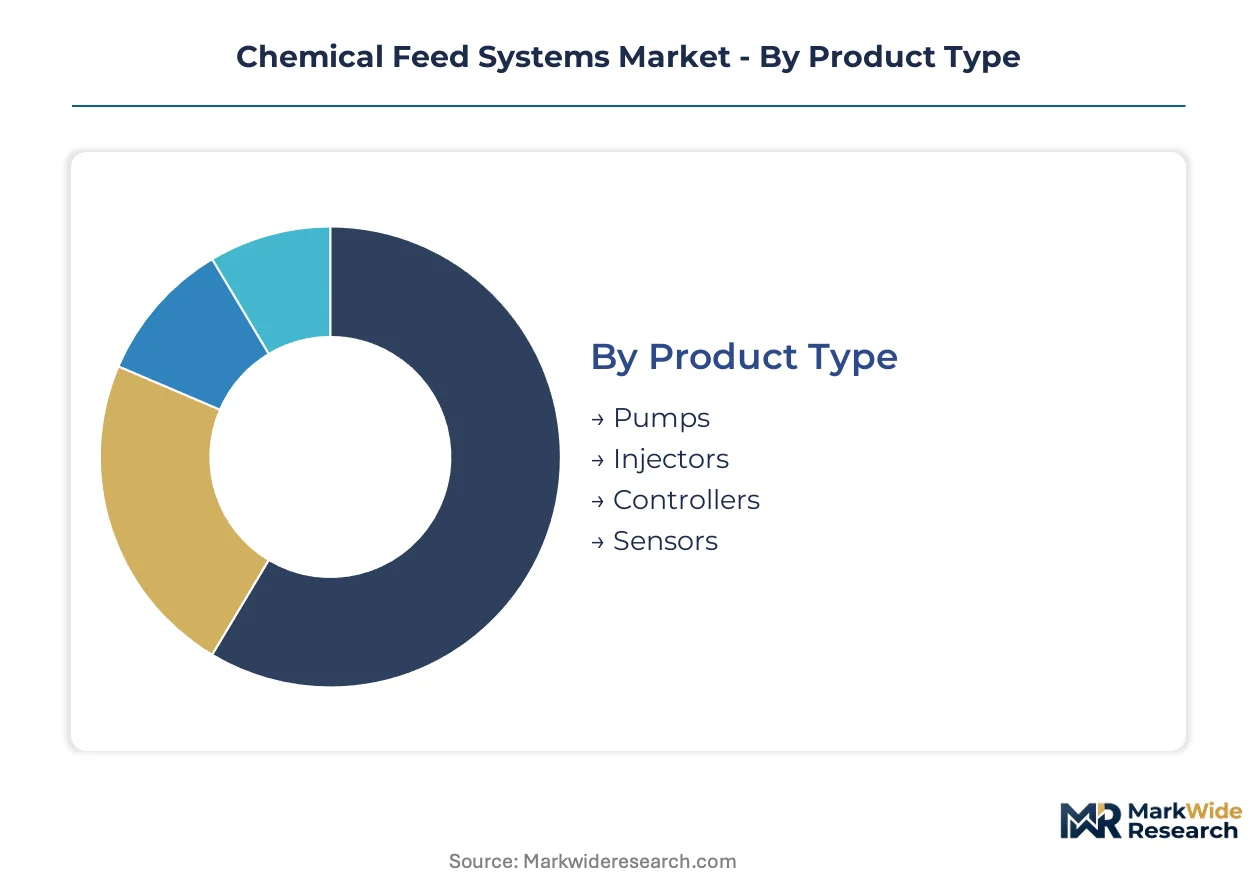
Chemical feed systems serve distinct operational profiles across standalone field installations and embedded process skids. Segmentation reveals how pump specifications, control architectures, and material selections diverge based on integration depth and end-use criticality.
Product Type:
Standalone pump units dominate field-retrofit scenarios, while sensor-integrated controllers anchor embedded skid architectures for greenfield municipal projects.
- Pumps:Positive displacement architectures with plus or minus one percent accuracy tolerances form the universal core of every installation. Municipal water districts in the United States specify these for EPA residual disinfectant compliance, with diaphragm and peristaltic variants selected based on chemical compatibility requirements.
- Controllers:Programmable logic controllers with flow-proportional delivery algorithms enable remote telemetry and reduced operator intervention. German and French utilities are procuring these within ten-year service agreements, unbundling cloud monitoring from hardware capital expenditure.
- Injectors:Venturi-based and quill-style injection points deliver chemicals into pressurized process lines with minimal pressure loss.
- Sensors:Electrochemical chlorine residual analyzers and pH probes provide feedback signals for automated dosing loops, though biweekly manual verification remains necessary in high-turbidity source water conditions.
Pumps lead volumes today; controllers are gaining share fastest.
Application:
Water treatment commands absolute installation counts, while pharmaceutical production carries the steepest specification premiums and validation documentation requirements.
- Water Treatment:Municipal drinking water and wastewater facilities deploy corrosion-resistant PVC or 316 stainless steel systems for sulfuric acid, caustic soda, and chlorine-based disinfection. China's coastal petrochemical clusters and India's textile belt are concentrating demand for automated precipitation and neutralization packages.
- Pharmaceutical Production:Sterile process validation requirements and clean-in-place protocol expansion drive demand for electrochemical sensor-integrated dosing with full documentation packages. This segment captures expanding margin pools as manufacturers qualify systems for FDA and EMA compliance.
- Agriculture:Fertigation systems integrate chemical feed pumps with irrigation infrastructure for precision nutrient delivery.
- Food Processing:Sanitary dosing applications require FDA-compliant wetted materials and cleanable pump head designs.
Water treatment leads volumes today; pharmaceutical production is climbing the fastest.
End User:
Municipal procurement departments prioritize factory-verified skid packages, while manufacturing plants balance customization needs against maintenance standardization.
- Municipalities:Water treatment utilities across the United States Midwest are accelerating retrofit schedules to meet EPA Safe Drinking Water Act enforcement. These operators favor modular skid packaging with embedded controllers to compress commissioning timelines and eliminate field fabrication variables.
- Manufacturing Plants:Petrochemical and power generation facilities in China's coastal provinces specify corrosion-resistant injection architectures for aggressive chemical handling. State-owned refinery operators standardize on 316 stainless steel or PVC-wetted systems.
- Farms:Agricultural operations deploy lower-complexity dosing systems for fertilizer and pesticide application.
- Laboratories:Research and quality control facilities require precision micro-dosing capabilities with calibration traceability.
Municipalities lead volumes today; manufacturing plants are expanding most quickly.
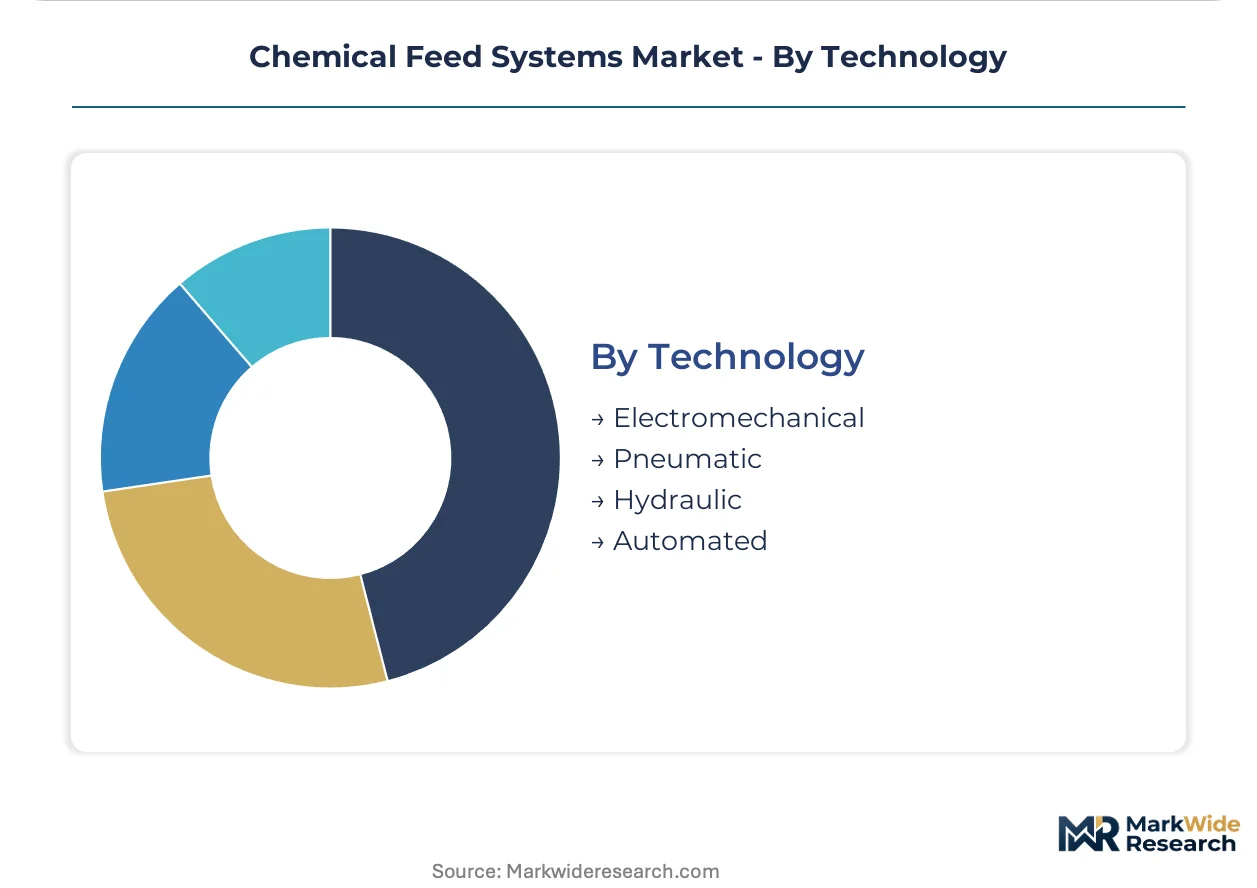
Technology:
Electromechanical systems anchor installed bases, while automated architectures are displacing manual dosing stations through feedback-controlled integration.
- Automated:PLC-integrated skids with variable frequency drives and permanent magnet synchronous motors enable precise flow turndown without mechanical stroke adjustment. California and Texas utilities specify these for state-level clean energy mandates, eliminating mechanical seal wear and compressing total cost of ownership.
- Electromechanical:Traditional motor-driven pump architectures with mechanical stroke adjustment dominate legacy installations and price-sensitive procurement.
- Pneumatic:Air-operated diaphragm pumps serve explosion-rated environments and oilfield chemical injection applications.
- Hydraulic:High-pressure intensifier systems deliver precise dosing against extreme backpressure in specialized industrial processes.
Electromechanical leads volumes today; automated is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical feed systems manufacturing originated in German and Swiss precision engineering clusters during the mid-twentieth century, with diaphragm pump technology scaling through North American municipal water infrastructure investments. Contemporary demand distributes across industrial corridors where water treatment regulations and petrochemical processing concentrate procurement.
United States
Midwestern water districts accelerate automated dosing skid retrofits to meet EPA Safe Drinking Water Act residual disinfectant mandates. Small and mid-sized utilities in Ohio, Illinois, and Michigan prioritize factory-calibrated systems to eliminate field fabrication variables. California and Texas specify permanent magnet synchronous motor packages for state-level clean energy compliance.
Germany
Industrial pump OEMs anchor European supply chains through vertical integration in precision machining and controller manufacturing. EU F-Gas Regulation compliance forces seal material transitions toward perfluoroelastomer alternatives, redesigning wetted component architectures. Bavarian and North Rhine-Westphalian fabricators qualify thermal spray ceramic coatings as chromium trioxide plating faces REACH authorization restrictions.
China
State-owned refinery operators in coastal petrochemical clusters standardize on corrosion-resistant injection packages for sulfuric acid and caustic soda handling. The country's national environmental regulator enforces dual carbon goals that elevate energy-efficient pump specifications. Yangtze River Delta and Pearl River Delta provinces concentrate demand for 316 stainless steel and PVC-wetted systems.
India
Central Pollution Control Board effluent standard tightening drives textile and tannery cluster retrofits in Gujarat and Tamil Nadu. State-level pollution control boards mandate automated chemical precipitation systems for industrial wastewater compliance. Pharmaceutical production expansion in Maharashtra and Karnataka creates demand for sterile process validation documentation packages.
France
Municipal water authorities unbundle cloud-based monitoring subscriptions from hardware capital expenditure through ten-year service agreements. EU Urban Wastewater Treatment Directive enforcement accelerates retrofit demand across regional treatment facilities. Île-de-France and Provence-Alpes-Côte d'Azur utilities specify PLC-integrated skids with embedded electrochemical sensors.
Chemical Feed Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across calibration accuracy and telemetry integration depth. The vendor base concentrates among vertically integrated pump OEMs capable of delivering complete plug-and-play systems, while specialized sensor integrators occupy niche positions. Three archetypes dominate: full-system skid packagers, precision pump specialists, and electrochemical sensor integrators. Competitive moves center on modular packaging standardization and aftermarket consumables unbundling from original equipment contracts.
Within the full-system skid packaging tier, Grundfos Holding A/S and ProMinent GmbH exemplify vertically integrated architectures spanning pump manufacturing through controller integration. Milton Roy occupies a position among precision pump specialists serving high-pressure industrial applications. These three anchors represent distinct strategic postures: Danish and German full-system providers versus American precision pump engineering, with each archetype competing through different vectors of factory calibration accuracy, sensor integration depth, and aftermarket service attachment.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| ProMinent GmbH |
| Milton Roy |
| Neptune Chemical Pump Company |
| SEKO S.p.A. |
| IDEX Corporation |
| Blue-White Industries |
| Verder Group |
| LMI Pumps |
| Others |
Value Network & Pricing Analysis
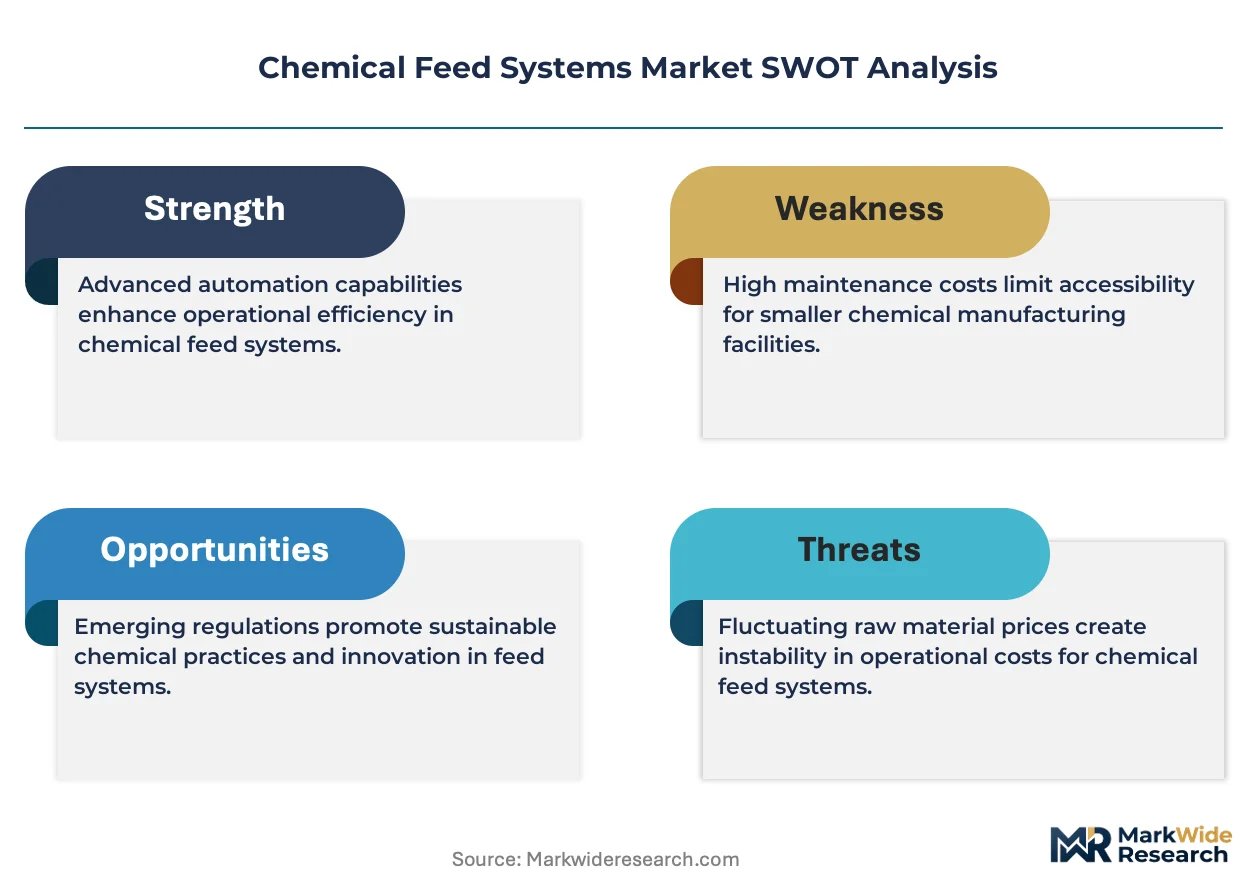
Fluoropolymer feedstock indices cascade through chemical feed system supply chains into three-tier pricing structures across premium, standard, and economy levels. PVC-wetted architectures for municipal water districts occupy economy tiers, while 316 stainless steel systems with embedded PLC controllers command premium positioning in pharmaceutical and petrochemical applications.
Pricing Analysis
Project-based capital equipment sales dominate municipal procurement, though German and French utilities increasingly unbundle cloud monitoring subscriptions through ten-year service agreements. Price differentiation rests on calibration accuracy tolerances and telemetry integration depth, with factory-verified skid packages capturing margin premiums over field-fabricated alternatives. Cost compression in standard-tier diaphragm pumps intensifies as third-party seal suppliers enter aftermarket channels. Municipal water districts in the US Midwest exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize validation documentation over unit economics.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical corridors and China's petrochemical clusters are reshaping sourcing patterns for controller manufacturing and precision machining. Perfluoroelastomer seal production concentrates in Germany, Japan, and Switzerland, while five-axis CNC equipment for high-pressure pump heads sources from German and Swiss machine tool builders. Supply chain risk centers on single-source vulnerability in fluoropolymer feedstock channels. Distribution runs through factory-authorized service networks with thin coverage outside major metropolitan areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chemical feed systems represent a late-cycle quality story as municipal utilities and pharmaceutical manufacturers shift procurement toward factory-calibrated automated skids with embedded telemetry and validation documentation.
For Market Incumbents: Deepen backward integration into electrochemical sensor manufacturing to capture expanding margin pools in pharmaceutical sterile process applications. Defend installed base relationships by qualifying thermal spray ceramic coatings ahead of EU REACH chromium trioxide restrictions. Prioritize capacity expansion in controller manufacturing to meet unbundled subscription demand from German and French utilities. For New Entrants and Emerging Players: EPA Safe Drinking Water Act enforcement in the United States opens a window for specialized commissioning service providers targeting rural Midwestern water districts with six-week factory-authorized wait times. Target India's textile and tannery clusters in Gujarat and Tamil Nadu with corrosion-resistant precipitation skids ahead of Central Pollution Control Board effluent mandate deadlines. Lead with validation documentation packages as a discrete revenue stream to differentiate from established pump OEMs. For Investors and Strategic Acquirers: Asymmetric upside sits with electrochemical sensor integrators possessing FDA and EMA qualification pathways. Long-term viability hinges on exposure to pharmaceutical sterile process expansion and municipal telemetry unbundling trends. Watch for PFAS regulatory cascade effects through seal and gasket supply chains as an inflection indicator for material transition costs and competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captures margin pools in pharmaceutical sterile process validation requirements. |
| Ten-Year Service Agreement Structuring | Aligns with German and French utility procurement unbundling of cloud monitoring. |
| Thermal Spray Ceramic Coating Qualification | Addresses EU REACH chromium trioxide restrictions on diaphragm pump plungers. |
| Rural Commissioning Service Network Buildout | Closes coverage gaps for Midwestern municipal utilities facing technician scarcity. |
| Validation Documentation Package Development | Creates discrete revenue stream from FDA and EMA compliance requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with municipal water utility procurement directors, pharmaceutical plant engineers, petrochemical maintenance managers, and chemical feed system OEM product strategists with secondary validation from EPA enforcement databases, EU ECHA REACH registration filings, SEC 10-K disclosures from listed pump manufacturers, and customs trade data on fluoropolymer feedstock flows. Bottom-up installation counts across water treatment, pharmaceutical, and petrochemical facilities triangulated against top-down market value estimates.
Comparable historical reference periods anchored the projection horizon, with analytical frameworks modeling segmentation across product architecture, application criticality, end-user procurement behavior, and technology integration depth. CAGRs derived from regression analysis of capital expenditure cycles, regulatory enforcement timelines, and industrial corridor development patterns. Industry-specific inputs included EPA residual disinfectant compliance deadlines, EU F-Gas Regulation phase-out schedules, and China dual carbon goal implementation trajectories.
Revisions become necessary when PFAS regulatory restrictions accelerate material transitions, precision machining bottlenecks extend beyond current equipment lead times, or municipal procurement unbundling shifts faster than OEM service infrastructure adaptation. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Performance Chemicals
Asia-Pacific Hydrogen Peroxide Market
Performance Chemicals
Global Oilfield Production Chemicals Market
Performance Chemicals
High Performance Epoxy Market
Performance Chemicals
Mecoprop Market
Performance Chemicals
Global High Performance Polymers Market
Performance Chemicals
Global Reflective Materials Market
Performance Chemicals
High Performance Plastics Market
Performance Chemicals
Global High Performance Polyamides Market