
 HDPE Pipes Market | 2026-2036
HDPE Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
HDPE Pipes Market Intelligence
Consolidation among large municipal and utility buyers is recalibrating the competitive landscape for HDPE pipe manufacturers. Chevron Phillips Chemical Company leverages its backward integration into polyethylene resin production for significant cost control. JM Eagle dominates the North American market through its extensive manufacturing scale and broad distribution network. In Asia, China Lesso specializes in a comprehensive portfolio catering to both construction and agricultural end-users.
High-Density Polyethylene (HDPE) pipes are thermoplastic conduits produced through the extrusion of PE100 or PE80 grade resins. Their primary purpose is the transport of fluids and gases under pressure, valued for exceptional corrosion resistance and flexibility. Pressure pipes for water supply and gas distribution represent the largest application segments by total volume. Demand from municipal authorities remains steady, while the agriculture sector shows strong growth for non-pressure corrugated pipes used in irrigation.
Product quality and performance are governed by international standards like ISO 4427 for drinking water systems. In the United States, EPA guidelines on potable water contact influence material selection, while CE marking is mandatory for market access in Europe. China's GB standards also set strict requirements for domestic infrastructure projects. Stakeholders must navigate these varying regional specifications while optimizing material formulations for enhanced long-term durability.
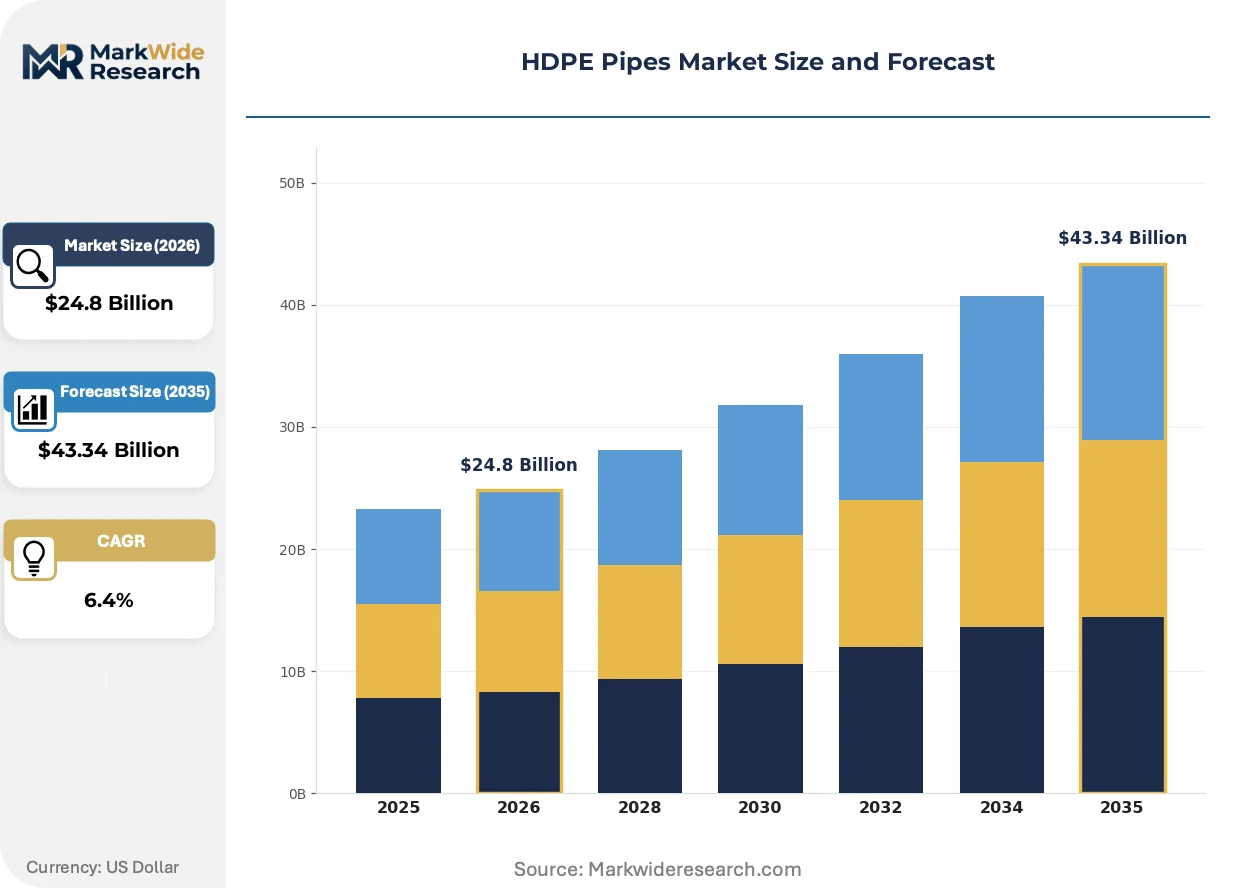
Market Dynamics
The central dynamic in the HDPE pipe market is the push for infrastructure modernization, where demand for replacing aging water and gas networks converges with the pull of process innovations like trenchless installation, which dramatically lowers deployment costs and disruption.
Growth Catalysts
- Urban Infrastructure Renewal:Significant government investment in water supply and sewage system upgrades in countries like India and Brazil creates sustained demand for corrosion-resistant piping solutions.
- Trenchless Technology Adoption:The use of horizontal directional drilling (HDD) allows for faster and less disruptive installation of utility lines, making HDPE pipes a preferred choice for urban and environmentally sensitive areas.
- Agricultural Water Management:A focus on water conservation in the agriculture sector is driving the adoption of HDPE corrugated pipes for efficient drip and sprinkler irrigation systems, often supported by government subsidies.
Market Restraints
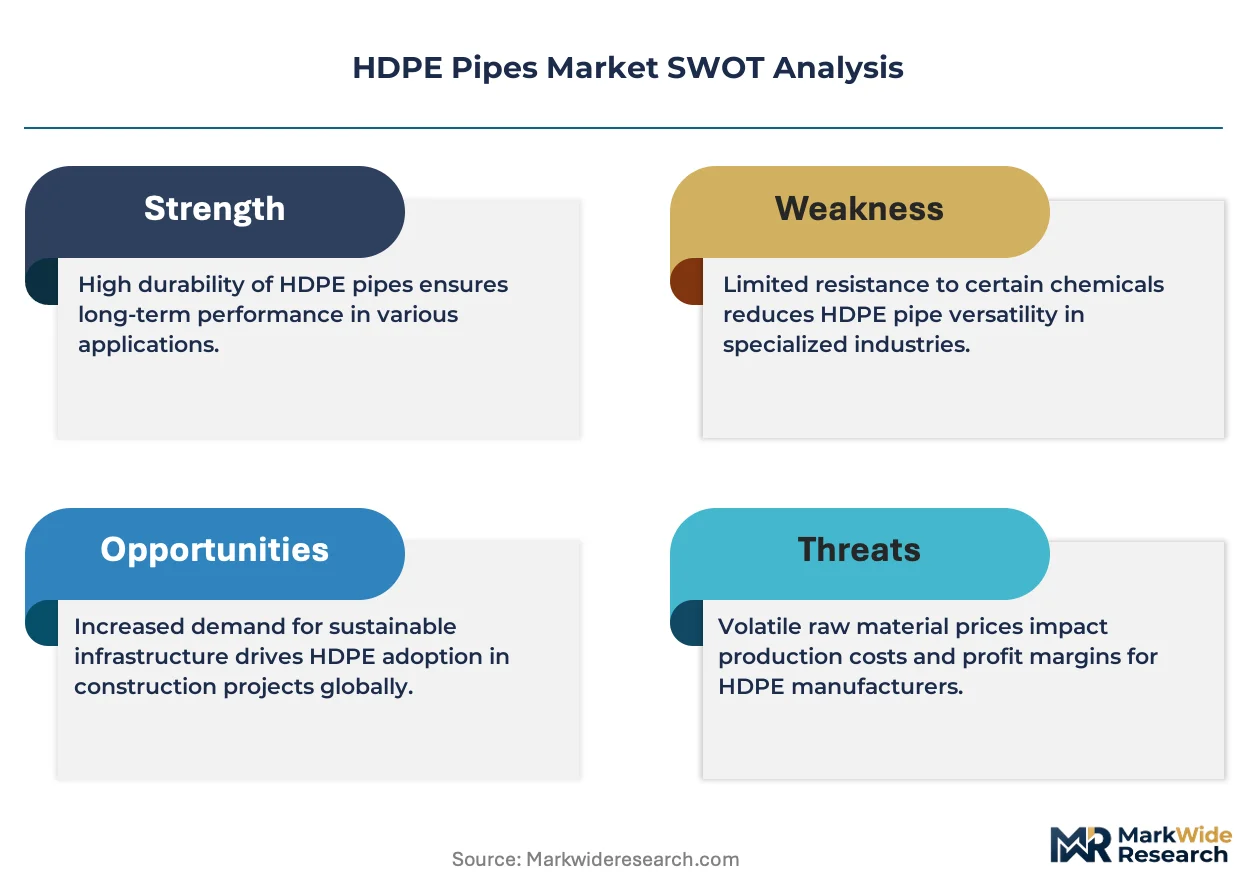
- Raw Material Price Volatility:The cost of PE100 and PE80 resins is directly linked to fluctuating crude oil and natural gas prices, creating margin instability for pipe manufacturers without captive supply.
- Substitution from PVC and Ductile Iron:In certain low-pressure and non-potable water applications, Polyvinyl Chloride (PVC) and ductile iron pipes remain competitive alternatives, particularly in projects where cost is the primary factor.
- Logistics and Handling Costs:Transporting large-diameter HDPE pipes over long distances is expensive and requires specialized equipment, which can limit the geographic reach of manufacturers and add significant project costs.
Strategic Opportunities
- Gas Distribution Expansion:The build-out of natural gas distribution networks in developing Asian and Latin American economies offers a substantial growth avenue for PE100 pipes due to their safety and leak-free performance.
- Renewable Energy Applications:Emerging use cases in geothermal heating and cooling systems, where HDPE pipes circulate heat-transfer fluids, provide a new market aligned with global decarbonization efforts.
- Recycled Content Integration:Mandates for using post-consumer recycled materials, particularly under frameworks like the EU Green Deal, create an opportunity for developing and marketing pipes with certified recycled HDPE content.
Industry Challenges
- Skilled Labor Scarcity:A shortage of technicians certified in butt fusion and electrofusion welding techniques creates project bottlenecks and increases the risk of improper installation, potentially compromising long-term pipeline integrity.
- Complex Certification Requirements:Adhering to varied and stringent regional standards, such as ISO 4427 for potable water, CE marking in Europe, and GB standards in China, requires significant investment and time.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HDPE Pipes Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Pipes, Non-Pressure Pipes, Corrugated Pipes, Ribbed Pipes Application: Water Supply, Gas Distribution, Sewage Systems, Cable Protection End User: Municipal Authorities, Telecom Operators, Construction Firms, Agriculture Sector Installation Type: Trenchless Technology, Open Trench, Horizontal Directional Drilling, Submarine Deployment |
| Companies Covered | Supreme Industries, WL Plastics, Chevron Phillips Chemical Company, Astral Pipes, AGRU, JM Eagle, China Lesso, Jain Irrigation Systems, Advanced Drainage Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HDPE Pipes Market Strategic Shifts & Innovations
Material science and digital fabrication are advancing the performance and installation efficiency of HDPE piping systems. Innovations focus on enhancing long-term durability under stress and streamlining critical on-site processes to ensure network integrity from the outset.
Automated welding equipment represents a significant process evolution. These systems use digital controls and sensor feedback for butt fusion and electrofusion jointing, ensuring consistent heat, pressure, and timing. Utility contractors and large infrastructure developers are the primary adopters, seeking to improve quality control. This technology is automating the historically manual jointing process, reducing human error and ensuring leak-proof performance in high-pressure gas and water mains.
Regulatory mandates targeting water quality are accelerating the replacement of legacy materials. In the United States, EPA rules governing lead and copper levels in drinking water compel utilities to replace aging metallic service lines. This creates a direct pull for inert materials that do not corrode or leach contaminants. Municipal water authorities are most affected, increasingly specifying HDPE as the default material for potable water line renewal projects.
Buyer behavior is evolving from simple transactional purchases toward partnerships focused on total asset lifecycle management. This model disrupts traditional volume-based procurement by incorporating services like installation training, digital traceability of pipe segments, and quality assurance verification. The shift is most prominent among large utilities in North America and Europe that are managing vast and complex underground infrastructure and prioritizing long-term operational reliability.
HDPE Pipes Market Segmentation
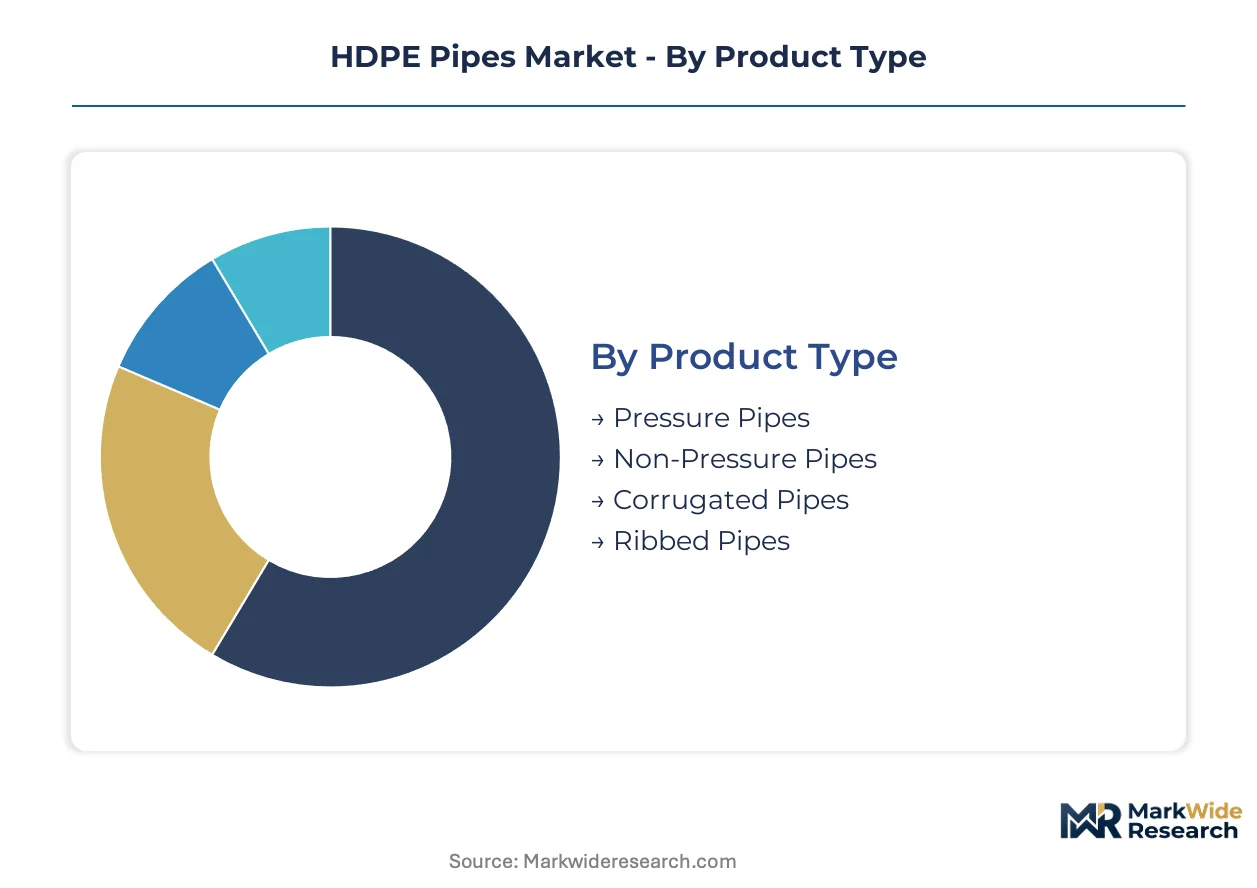
Understanding the distinct segments within the HDPE pipes market is critical for manufacturers to align production capabilities with evolving demand patterns. Each category reveals specific material requirements, application challenges, and end-user preferences. This segmentation analysis provides a structured view of where value is created and captured across the industry.
Product Type:
Supply concentration for HDPE pipe product types often reflects the scale of infrastructure investment and the technical specifications required for high-pressure fluid transport.
- Pressure Pipes:These conduits are designed to transport fluids and gases under significant internal pressure, typically manufactured from PE100 or PE80 grade resins. Demand concentrates in municipal water supply and gas distribution networks, driven by urban infrastructure renewal and the need for leak-free performance.
- Non-Pressure Pipes:Used for gravity-flow applications such as drainage and sewerage systems, these pipes do not require high-pressure resistance. Production focuses on cost-effectiveness for large-volume projects in construction and agricultural land management.
- Corrugated Pipes:Characterized by their ribbed exterior, these pipes offer enhanced structural strength and flexibility for non-pressure applications, particularly in agricultural drainage. The agriculture sector drives demand for efficient water management systems, often supported by government subsidies in regions like India.
- Ribbed Pipes:These pipes feature internal or external ribs, providing increased stiffness and flow characteristics for specific drainage and conduit applications, especially in road construction projects.
Pressure Pipes absorb the bulk of installed capacity; Corrugated Pipes are expanding most quickly.
Application:
Application segments delineate the primary use cases for HDPE pipes, directly influencing material specifications and performance requirements.
- Water Supply:This application involves transporting potable and non-potable water from source to distribution points, requiring pipes compliant with standards like ISO 4427. Municipal authorities in North America and Europe are replacing aging metallic lines with HDPE due to its corrosion resistance and inertness.
- Gas Distribution:HDPE pipes are extensively used for conveying natural gas, valued for their leak-free butt fusion joints and resistance to corrosion, ensuring safety and reliability. The build-out of gas networks in developing Asian economies, such as China and India, offers substantial growth.
- Sewage Systems:These pipes manage wastewater and storm drainage, typically operating under non-pressure or low-pressure conditions. Urbanization projects globally require durable and chemically resistant piping for efficient waste removal.
- Cable Protection:HDPE conduits protect electrical and fiber optic cables from environmental damage and mechanical stress in underground installations. Telecom operators and utility companies utilize these for robust infrastructure development.
Demand for Water Supply remains robust, while Gas Distribution shows significant expansion.
End User:
The end-user base for HDPE pipes reflects diverse procurement needs, from large-scale public works to specialized private sector projects.
- Municipal Authorities:These government bodies are primary buyers for public infrastructure, including water, sewage, and gas utilities. Their procurement is driven by urban infrastructure renewal and regulatory mandates for safe drinking water, particularly in countries like Brazil.
- Agriculture Sector:Farmers and agricultural enterprises utilize HDPE pipes for irrigation, drainage, and water conservation systems. Government subsidies for efficient water management in regions facing water scarcity, such as parts of India, boost adoption.
- Telecom Operators:Companies providing telecommunication services employ HDPE conduits for protecting fiber optic and data cables. Investments in 5G networks and broadband expansion globally drive this demand.
- Construction Firms:General construction companies use HDPE pipes for various building and civil engineering projects, including site drainage, temporary water supply, and utility connections.
Municipal Authorities represent the primary purchasing power, with the Agriculture Sector exhibiting accelerated procurement.
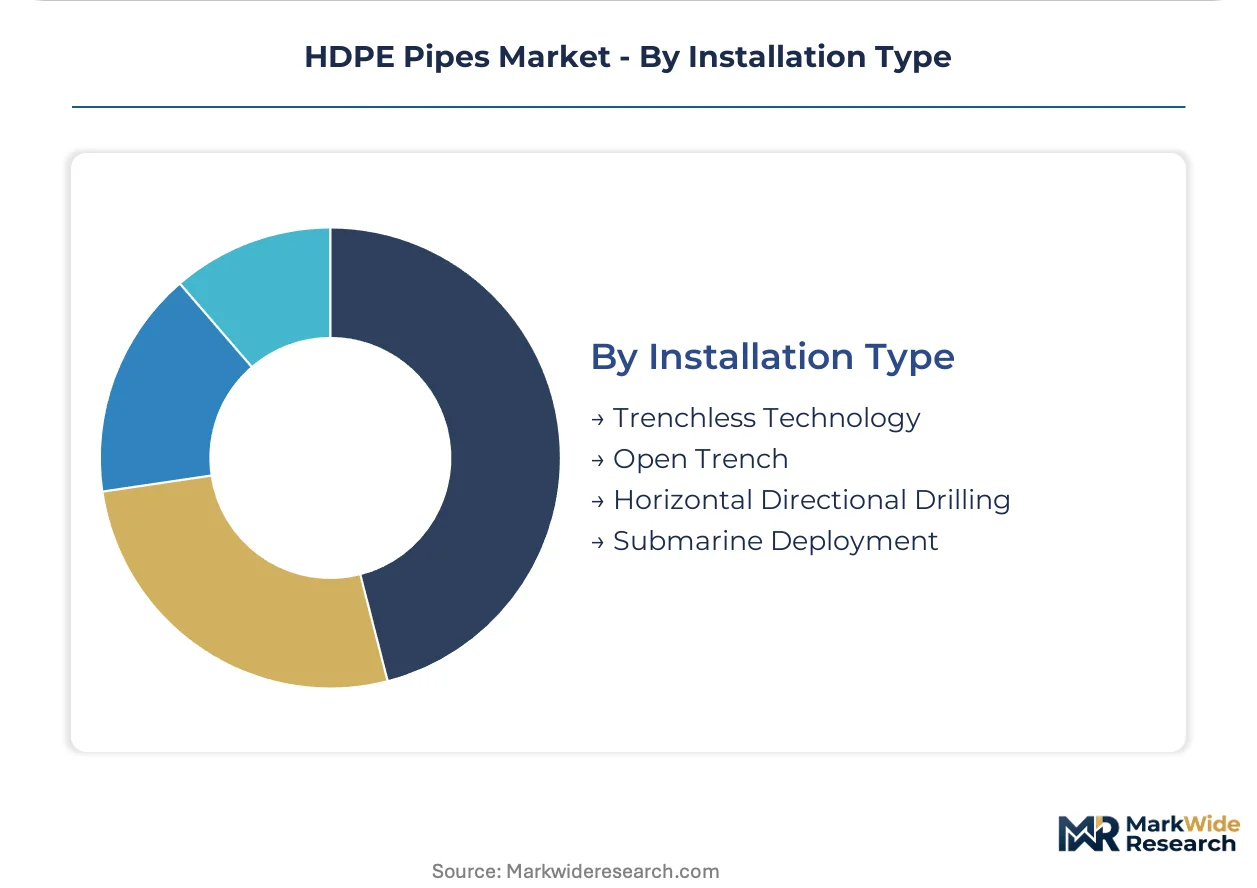
Installation Type:
Installation methods dictate specific pipe characteristics and project logistics, with innovation driving efficiency and reduced environmental impact.
- Trenchless Technology:This method involves installing or rehabilitating underground pipes without extensive excavation, minimizing surface disruption and costs. Utility contractors prefer this for urban areas and environmentally sensitive sites, making HDPE a preferred material due to its flexibility.
- Open Trench:The traditional method of digging a trench, laying the pipe, and backfilling, suitable for new construction in open areas. This technique remains prevalent for large-diameter pipes where space is not a constraint.
- Horizontal Directional Drilling:A specific trenchless technique that uses a steerable drilling rig to create a bore path, then pulls the pipe through. This is crucial for crossing rivers, roads, and other obstacles, favored by gas distribution companies for its precision.
- Submarine Deployment:This specialized method involves laying HDPE pipes underwater for conveying fluids across bodies of water or for offshore applications. Marine engineering firms undertake these complex projects, requiring highly durable and flexible pipes.
Trenchless Technology is foundational to project execution, as Horizontal Directional Drilling gains traction for specialized deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, with its extensive petrochemical infrastructure, anchors the global supply chain for polyethylene resins, influencing HDPE pipe production. Regional demand patterns for HDPE pipes reflect diverse infrastructure development priorities and regulatory landscapes. Significant investments in water and gas infrastructure are driving market expansion across multiple continents.
United States
Demand for HDPE pipes in the United States stems from extensive water supply network upgrades and natural gas distribution projects. EPA guidelines for potable water quality compel utilities to replace aging metallic lines with inert materials like HDPE. Major metropolitan areas like New York and Los Angeles are undertaking large-scale pipe replacement initiatives.
India
India's sustained demand for HDPE pipes is driven by rapid urbanization and government-led agricultural water management programs. The Bureau of Indian Standards (BIS) sets strict quality requirements for infrastructure projects. States like Gujarat and Maharashtra are witnessing significant investment in new irrigation systems and urban water supply networks.
Germany
Germany's HDPE pipe market focuses on replacing aging utility networks and supporting renewable energy applications like geothermal heating systems. CE marking is mandatory for market access, ensuring product quality and safety. The industrial clusters in North Rhine-Westphalia are actively adopting sustainable piping solutions for municipal and industrial uses.
China
China's vast infrastructure development projects, including new urban water systems and expanding gas distribution networks, generate substantial demand for HDPE pipes. Domestic GB standards govern material specifications and installation practices for all major projects. The Yangtze River Delta region is a hub for large-scale construction and utility upgrades.
Brazil
Brazil experiences strong demand for HDPE pipes due to ongoing water and sewage system upgrades and agricultural irrigation expansion. The national sanitation plan, often supported by ANVISA regulations, aims to improve public health infrastructure. Cities like São Paulo are investing heavily in modernizing their underground utility networks.
HDPE Pipes Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized solutions for niche applications. The market structure exhibits a tiered consolidation, with a few large integrated players dominating scale production alongside numerous regional specialists. Strategic archetypes include vertically integrated manufacturers, broad-portfolio providers, and application-specific innovators. Dominant competitive moves involve capacity expansion to meet regional demand and backward integration to control raw material costs.
At the scale-driven end, JM Eagle occupies a position as a major North American player through its extensive manufacturing capabilities and distribution reach. Chevron Phillips Chemical Company represents a vertically integrated archetype, leveraging its upstream control over polyethylene resin production for cost advantages. In Asia, China Lesso exemplifies a broad-portfolio provider, catering to diverse construction and agricultural end-users with a comprehensive product range.
| Leading Market Players |
|---|
| Supreme Industries |
| WL Plastics |
| Chevron Phillips Chemical Company |
| Astral Pipes |
| AGRU |
| JM Eagle |
| China Lesso |
| Jain Irrigation Systems |
| Advanced Drainage Systems |
| Others |
Cost & Logistics Intelligence
Backward integration into polyethylene resin production anchors the supply position for large HDPE pipe manufacturers like Chevron Phillips Chemical. This strategic control over key raw materials directly influences their pricing power and overall market competitiveness.
Pricing Analysis
Warranty and service bundling increasingly differentiate HDPE pipe offerings, moving beyond simple transactional purchases. The dominant pricing model remains project-based, influenced by material grade like PE100, specific certifications such as ISO 4427, and project volume scale. Pricing softness stems from raw material price volatility, particularly for PE100 and PE80 resins, which directly impacts manufacturer margins. Municipal authorities prioritize long-term reliability over initial cost, exhibiting lower price sensitivity, while construction firms and agricultural buyers often seek cost-effective non-pressure solutions.
Supply Chain Analysis
Single-source vulnerability sits with the petrochemical industry for PE100 and PE80 resin feedstocks, primarily concentrated in the United States and the Middle East. The global supply chain draws from crude oil and natural gas prices, creating significant margin instability for pipe manufacturers without captive supply. Logistics and handling costs for large-diameter HDPE pipes pose a structural risk, limiting geographic reach and increasing project expenses. Downstream distribution typically relies on extensive networks established by players like JM Eagle in North America and China Lesso in Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HDPE pipes market is fundamentally a cost-of-compliance story, where adherence to stringent regulations like ISO 4427 for potable water creates a significant barrier to entry for non-compliant players. This regulatory moat favors established manufacturers capable of meeting diverse global standards.
For Market Incumbents: Cement market leadership through strategic backward integration into PE resin production, mitigating raw material price volatility. Invest in automated welding equipment to enhance installation quality and address skilled labor scarcity, a key project bottleneck. Strengthen regional distribution networks to counter logistics challenges and fend off substitution from lower-cost PVC alternatives in non-pressure applications. Prioritize R&D for certified recycled HDPE content, aligning with emerging mandates like the EU Green Deal. For New Entrants and Emerging Players: Begin with specialized offerings for high-growth, underserved niches such as geothermal heating and cooling systems, leveraging specific performance requirements. Target the agriculture sector in regions like India and Brazil with cost-effective corrugated pipes, capitalizing on government subsidies for water management. Focus on providing bundled solutions that include installation training and technical support to overcome skilled labor scarcity and build trust with new utility buyers. For Investors and Strategic Acquirers: Exit pathways concentrate in regional specialists with robust certification portfolios or innovators in process technology, offering strong long-term viability over the next 5-10 years. Look for companies deeply embedded in municipal water supply upgrades or gas distribution network expansion in developing economies. The signal to watch is the accelerating adoption rate of automated welding equipment and certified recycled content, indicating market readiness for advanced solutions.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Meets sustained demand from urbanization and agricultural water management programs in India. |
| Backward Integration into PE Resin | Secures raw material supply and mitigates price volatility for HDPE pipe manufacturers. |
| Investment in Automated Welding | Addresses skilled labor scarcity and ensures leak-free performance for critical gas mains. |
| Certification for Recycled Content | Aligns with EU Green Deal mandates and attracts environmentally conscious municipal buyers. |
| Partnerships for Geothermal Applications | Unlocks new market opportunities in renewable energy aligned with global decarbonization efforts. |
Research Approach
Independent corroboration across EPA guidelines, ISO standards, and BIS specifications underwrites the qualitative findings of this study. Primary interviews with utility procurement managers, pipe manufacturing R&D directors, and agricultural irrigation specialists provided granular insights. This was validated through secondary research, including trade association reports and regulatory documents, employing both bottom-up and top-down triangulation.
Historical performance across comparable periods anchored the forecast framework, extending over the projection horizon. The analytical model segmented the market by product type, application, end user, installation type, and specific resin grade. Compound annual growth rates were derived from a multi-variant regression analysis, incorporating anticipated infrastructure investment cycles and raw material price trends as key inputs.
Geopolitical instability, technological disruption, and shifts in regulatory enforcement are the dominant revision risks for these forecasts, which reflect documented assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Europe Copper Pipes and Tubes Market
Pipes and Tubes
Galvanized Iron Pipes Market
Pipes and Tubes
Steel Pipe Market
Pipes and Tubes
Saudi Arabia PE Pipes Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
OCTG Pipe Market
Pipes and Tubes
Stainless Steel Plumbing Pipes and Fittings Market
Pipes and Tubes
Spain PVC Pipes Market
Pipes and Tubes
Gas Pipe Fittings Market
Pipes and Tubes
Galvanized Steel Tubes Market
Pipes and Tubes
Drum Funnel Market
Pipes and Tubes
Glass Reinforced Plastic (GRP) Piping Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
Steel Pipes and Tubes Market
Pipes and Tubes
Global Fluoropolymer Tubing Market
Pipes and Tubes
Metal Pipe Market