
 Welded Pipes Market | 2026-2036
Welded Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Welded Pipes Market Analysis
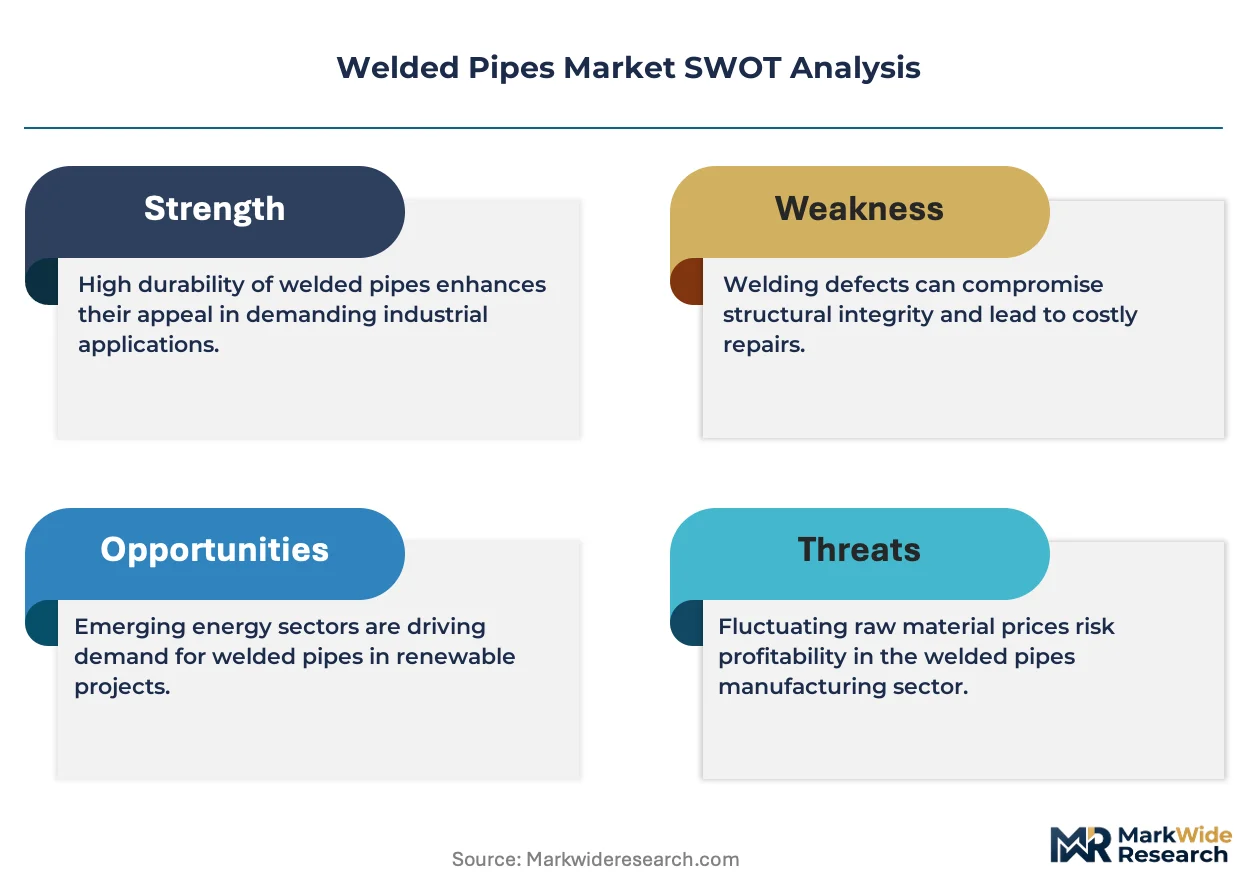
Buyer concentration among oil and gas pipeline operators is pivoting toward fewer mega-contractors with multi-year framework agreements. ArcelorMittal S.A. leverages its integrated flat-rolled steel capacity to supply coil feedstock for longitudinal welded pipe mills. Nippon Steel Corporation anchors high-grade line pipe output for sour service environments through controlled rolling technology. Tenaris S.A. differentiates via seamless-weld hybrid solutions and threading services bundled with pipe supply.
Welded pipes are tubular products fabricated by joining steel plates or coils through electric resistance welding, submerged arc welding, or high-frequency induction processes, typically conforming to specified wall thicknesses and yield strengths for pressure containment. Carbon steel grades dominate transmission pipeline applications where cost efficiency and weldability matter most, while stainless steel segments command premium positioning in corrosive downstream chemical processing. Large diameter pipes capture the majority of project value in cross-border trunk line installations, though small diameter specialty tubing generates higher per-ton margins in automotive fuel injection systems.
API standards govern North American oil and gas pipe specifications, while ISO 3183 harmonizes international line pipe requirements for cross-border projects. China's GB standards and NMPA oversight shape domestic pressure equipment certification, affecting export eligibility for foreign mills. India's BIS marking mandates and PLI scheme incentives for specialty steel are redirecting procurement toward locally certified welded pipe producers. Stakeholders must monitor evolving carbon border adjustment mechanisms and scrap-based electric arc furnace capacity expansions that will reconfigure feedstock economics for welded pipe manufacturing.
Market Dynamics
Oil and gas pipeline operators are consolidating procurement under fewer master service agreements while API 5L and ISO 3183 certification requirements tighten weld integrity standards for high-pressure applications. This dual pressure is compressing supplier margins and elevating technical barriers to market entry.
Growth Catalysts
- API 5L Specification Updates:North American operators are mandating enhanced Charpy impact testing for sour service environments, driving replacement cycles in existing trunk line infrastructure.
- United States Gulf Coast Petrochemical Corridor:Ethylene cracker expansions along the Texas-Louisiana border are generating concentrated demand for large-diameter process piping with specialized metallurgy.
- High-Frequency Induction Welding:Mill operators are deploying HFIW systems for thin-wall precision tubing in automotive fuel injection applications, opening higher-margin specialty segments.
Market Restraints
- Scrap-Derived Steel Cost Volatility:Electric arc furnace operators face margin compression when shredded auto scrap prices spike, transmitting cost instability downstream to coil feedstock pricing.
- China Mill Overcapacity:State-supported capacity expansions in Hebei and Jiangsu provinces are flooding export markets with below-cost line pipe, eroding price realization for compliant producers.
- Seamless Pipe Substitution:Premium offshore applications are migrating toward seamless-weld hybrid solutions where fatigue resistance requirements exceed longitudinal weld capability limits.
Strategic Opportunities
- India PLI Scheme for Specialty Steel:Production-linked incentives are redirecting procurement toward locally certified welded pipe producers serving domestic refinery and power sector projects.
- Hydrogen Pipeline Retrofit Applications:Existing natural gas trunk lines in Germany and the Netherlands require embrittlement-resistant weld overlays for hydrogen blending compatibility.
- Carbon Border Adjustment Mechanisms:EU CBAM implementation is creating first-mover advantage for mills with verified low-carbon production routes and scope 3 emissions documentation.
Industry Challenges
- Certified Welding Inspector Scarcity:API 1104-qualified technicians command premium wages as pipeline construction cycles compress and inspection density requirements intensify.
- Submerged Arc Flux Supply Reconfiguration:Mills are rebuilding supplier relationships as Russian-sourced agglomerated flux becomes unavailable, forcing qualification of alternative chemistries.
- Digital Twin Integration Complexity:Legacy ERP systems at established pipe mills struggle to ingest real-time ultrasonic testing data streams for predictive quality analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welded Pipes Market |
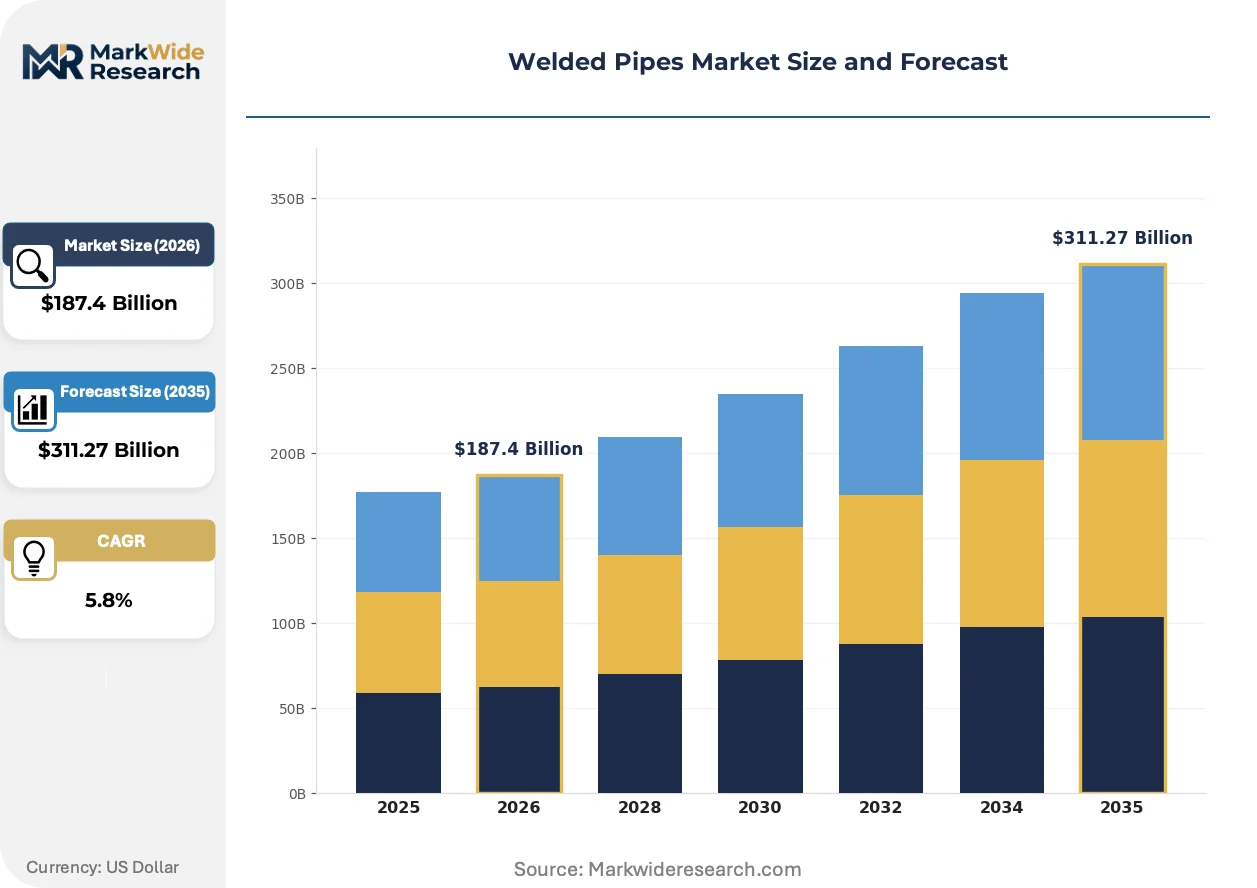
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Steel, Stainless Steel, Alloy Steel, PVC End User: Oil & Gas, Construction, Automotive, Aerospace Installation: Onshore, Offshore, Underground, Above Ground Diameter: Small Diameter, Medium Diameter, Large Diameter, Others |
| Companies Covered | ArcelorMittal S.A., Nippon Steel Corporation, Tenaris S.A., JFE Steel Corporation, Sandvik AB, Hyundai Steel Company, Nucor Corporation, United States Steel Corporation, Marcegaglia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welded Pipes Market Emerging Trajectories
Manufacturing technology and certification protocols are converging to redefine competitive advantage in pressure-containment applications. Process automation and materials traceability are becoming decisive differentiators.
Hybrid laser-arc welding systems are overtaking conventional submerged arc processes for thick-wall offshore line pipe. Norwegian and Brazilian deepwater contractors specify hybrid welds for fatigue-critical riser joints. The technology is compressing defect rates while enabling single-pass deposition that halves heat-affected zone width.
EU Carbon Border Adjustment Mechanism reporting requirements are forcing scope 3 emissions disclosure across the steel value chain. German automotive OEMs now require mill test certificates with embodied carbon declarations for exhaust system tubing. Producers with electric arc furnace-based coil supply are capturing preferential placement in European automotive supplier matrices.
Consolidated procurement desks at supermajor operators are unbundling threading and inspection services from base pipe supply. Saudi Aramco and ExxonMobil negotiate separate master service agreements for premium connections versus commodity line pipe. The unbundling is exposing standalone threading specialists to direct price competition while rewarding pipe mills with captive premium connection capability.
Welded Pipes Market Segmentation
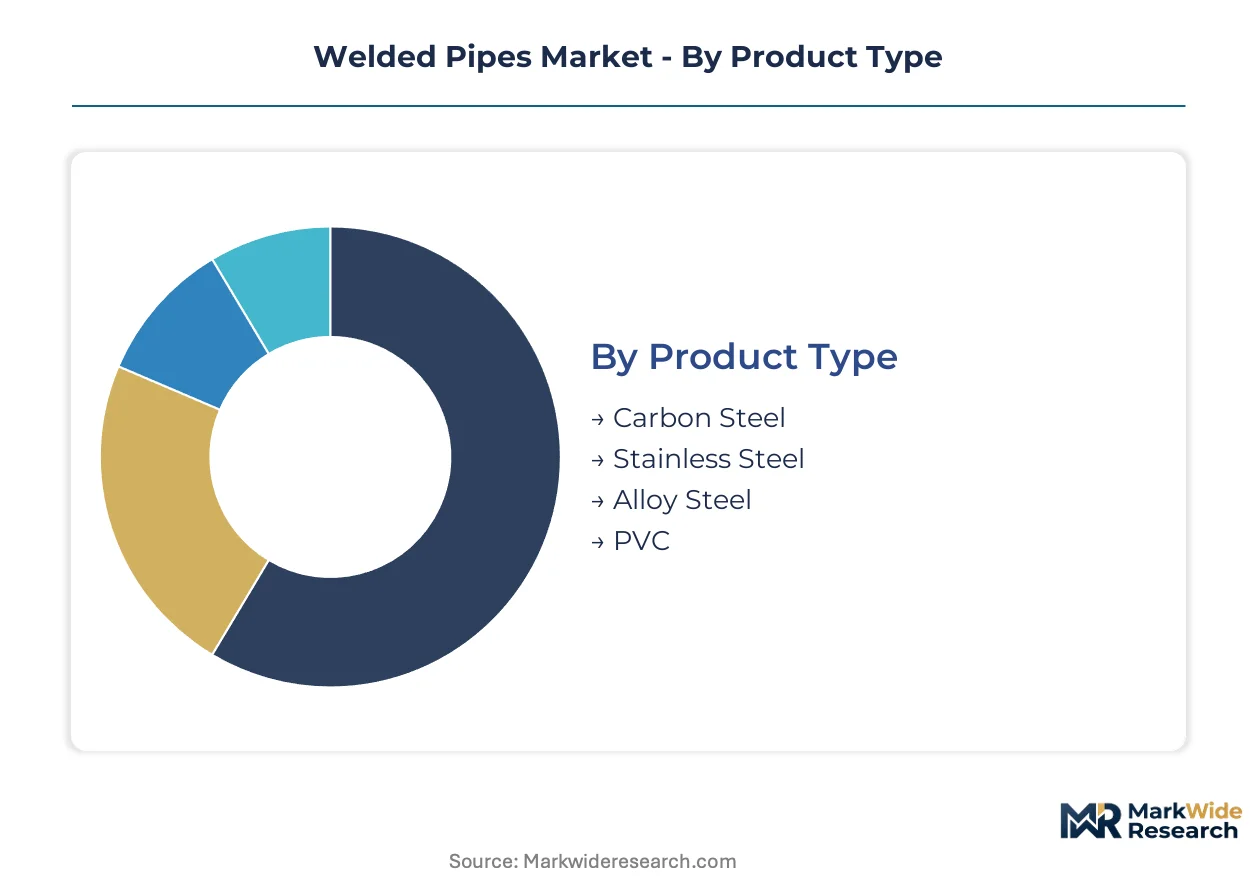
Welded pipe procurement patterns diverge sharply between commodity bulk applications and engineered specialty systems. Specification complexity, certification requirements, and installation constraints create distinct commercial dynamics across each segmentation dimension.
Product Type:
Carbon steel grades dominate standalone transmission infrastructure where specification simplicity enables volume procurement, while stainless and alloy variants embed into process-critical systems demanding metallurgical precision.
- Carbon Steel:Longitudinal submerged arc welded construction using hot-rolled coil feedstock delivers the yield strength and ductility required for high-pressure trunk lines. Demand concentrates in United States Gulf Coast ethylene cracker expansions and Permian Basin gathering systems where API 5L X70 and X80 grades command framework agreement volumes.
- Stainless Steel:Austenitic and duplex grades resist chloride-induced stress corrosion in offshore riser splash zones and refinery hydroprocessing units. German hydrogen pipeline retrofit projects specify 316L overlays for embrittlement resistance, creating premium positioning for mills with cold-pilgered seamless-weld hybrid capability.
- Alloy Steel:Chrome-molybdenum compositions serve elevated-temperature boiler tubing and power sector applications.
- PVC:Thermoplastic extrusions address drainage and non-pressure municipal infrastructure in cost-sensitive developing markets.
Volume placements concentrate in Carbon Steel; the faster expansion belongs to Stainless Steel.
End User:
Cost-tier segmentation separates project-driven capital expenditure cycles from recurring maintenance procurement, with oil and gas supermajors negotiating multi-year master service agreements distinct from construction sector spot purchasing.
- Oil & Gas:Pipeline operators consolidate procurement under fewer mega-contractors, mandating API 5L and ISO 3183 certification with enhanced Charpy testing for sour service. Saudi Aramco and ExxonMobil unbundle threading services from base pipe supply, exposing standalone specialists to direct price competition.
- Construction:Structural hollow sections for commercial building frames and infrastructure projects operate on spot-market pricing with less stringent traceability requirements.
- Automotive:High-frequency induction welded precision tubing serves fuel injection and exhaust systems where German OEMs now require embodied carbon declarations.
- Aerospace:Titanium-grade welded tubing for hydraulic systems demands aerospace material specifications and lot-controlled heat treatment.
Procurement scale peaks with Oil & Gas; margin expansion is steepest in Aerospace.
Installation:
Application context determines weld integrity verification intensity, with subsea and buried environments imposing inspection protocols absent from above-ground installations.
- Onshore:Cross-border trunk lines and gathering networks span Permian Basin, Saudi Eastern Province, and Siberian fields. Pipeline construction cycles compress API 1104-qualified welding inspector availability, elevating labor costs.
- Offshore:Norwegian and Brazilian deepwater contractors specify hybrid laser-arc welds for fatigue-critical riser joints, halving heat-affected zone width versus conventional submerged arc processes.
- Underground:Coating and cathodic protection requirements add specification layers for corrosion prevention in soil environments.
- Above Ground:Process piping within refinery and petrochemical complexes permits easier inspection access and maintenance intervention.
Project value aggregates in Onshore; technical complexity concentrates in Offshore.
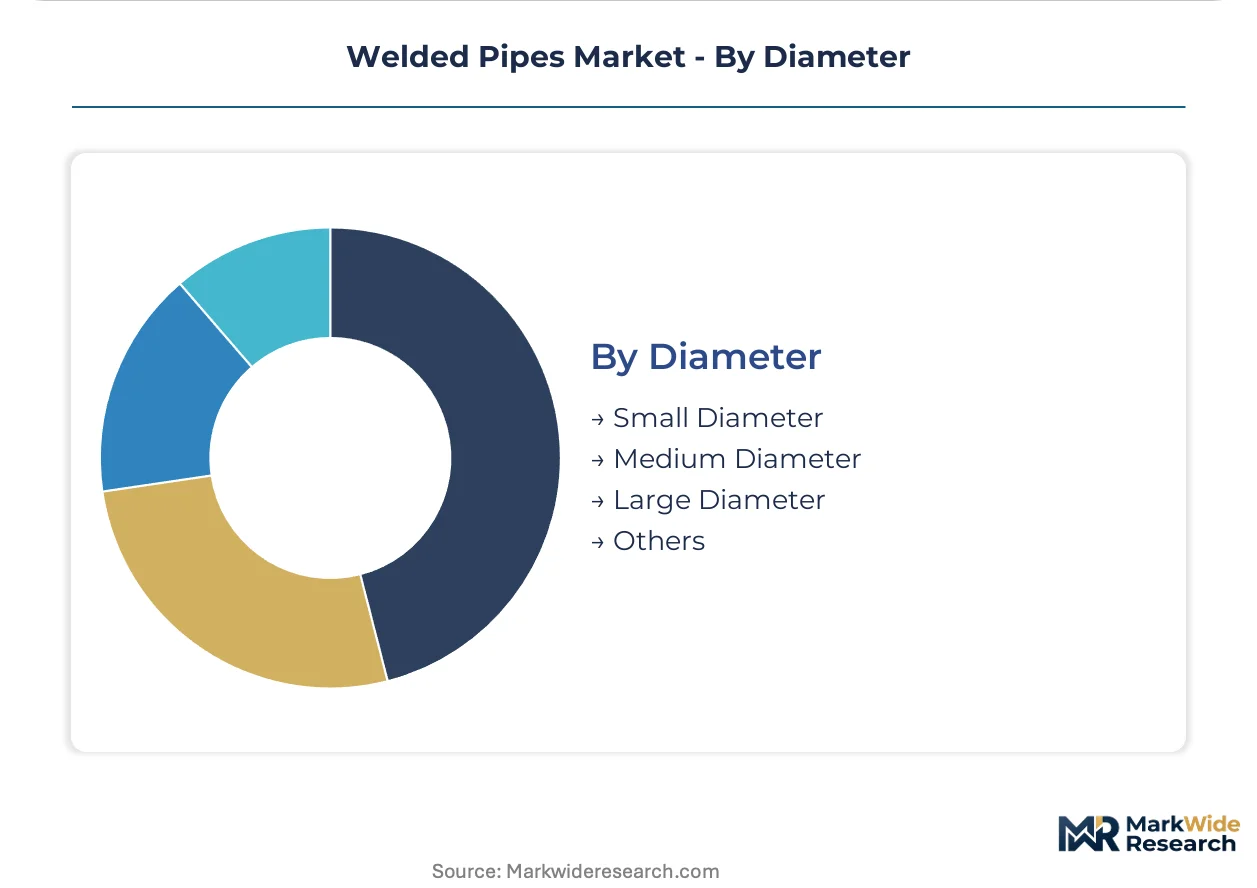
Diameter:
Supply concentration and margin structure invert across the diameter spectrum, with large-diameter trunk lines capturing project value while small-diameter specialty tubing generates superior per-ton economics.
- Large Diameter:Cross-border trunk line installations in Germany, Netherlands, and United States Gulf Coast corridor require spiral or longitudinal welded construction with wall thicknesses exceeding 25 millimeters. China mill overcapacity in Hebei and Jiangsu provinces floods export markets with below-cost line pipe.
- Small Diameter:Precision tubing for automotive fuel injection and instrumentation applications commands specification premiums through tight dimensional tolerances and surface finish requirements.
- Medium Diameter:Distribution pipelines and process headers balance volume and engineering complexity.
- Others:Micro-bore capillary tubing serves specialized analytical and medical applications outside mainstream industrial demand.
Tonnage flows through Large Diameter; profitability concentrates in Small Diameter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oil and gas pipeline procurement concentrates in the United States Gulf Coast petrochemical corridor, while hydrogen infrastructure retrofit demand clusters in Northwestern Europe. API 5L and ISO 3183 certification requirements are tightening weld integrity standards across all major demand centers.
United States
Permian Basin gathering systems and Texas-Louisiana ethylene cracker expansions drive large-diameter line pipe demand. FERC pipeline safety regulations mandate enhanced material traceability for interstate transmission infrastructure. Houston anchors master service agreement negotiations with supermajor operators consolidating procurement under fewer mega-contractors.
Germany
Natural gas trunk line hydrogen retrofit projects require embrittlement-resistant weld overlays for blending compatibility. EU CBAM implementation forces scope 3 emissions disclosure across steel value chains. Ruhr industrial clusters host mills developing low-carbon electric arc furnace feedstock for automotive exhaust system tubing.
China
State-supported capacity expansions in Hebei and Jiangsu provinces flood export markets with below-cost line pipe. NMPA and GB standards shape domestic pressure equipment certification affecting export eligibility. Yangtze River Delta mills serve domestic refinery and power sector projects under import substitution policies.
India
BIS marking mandates and PLI scheme incentives redirect procurement toward locally certified welded pipe producers. CEA power sector regulations drive boiler tubing demand from domestic specialty steel mills. Gujarat refineries and Maharashtra petrochemical complexes anchor regional demand concentration.
Saudi Arabia
Saudi Aramco unbundles threading services from base pipe supply under separate master service agreements. SFDA and national oil company procurement standards enforce API 5L sour service certification. Eastern Province industrial cities host framework agreement negotiations for cross-border trunk line projects.
Welded Pipes Market Vendor Landscape
European and Japanese producers anchor the premium-tier certification segment; Chinese and Indian mills hold volume-driven commodity positioning. Supplier consolidation under fewer mega-contractors compresses margins while elevating technical barriers. Three archetypes dominate: integrated steel majors with captive coil supply, specialized line pipe mills with threading capability, and electric arc furnace operators with scrap-based cost structures. Competitive moves center on captive premium connection capability and low-carbon production route verification.
Within the integrated major tier, ArcelorMittal S.A., Nippon Steel Corporation, and Tenaris S.A. exemplify divergent strategic positions. ArcelorMittal S.A. represents European-based backward integration into flat-rolled steel feedstock. Nippon Steel Corporation anchors Japanese high-grade metallurgy for sour service environments. Tenaris S.A. occupies a position emphasizing seamless-weld hybrid solutions bundled with threading services. These three entities collectively illustrate how geographic origin and structural integration shape competitive archetype differentiation in pressure-containment applications.
| Leading Market Players |
|---|
| ArcelorMittal S.A. |
| Nippon Steel Corporation |
| Tenaris S.A. |
| JFE Steel Corporation |
| Sandvik AB |
| Hyundai Steel Company |
| Nucor Corporation |
| United States Steel Corporation |
| Marcegaglia |
| Others |
Supply Flow & Price Mechanics
EU Carbon Border Adjustment Mechanism compliance documentation gates both qualified supply and premium-tier pricing access, as mills without verified scope 3 emissions data face exclusion from German automotive OEM supplier matrices while certified low-carbon producers capture preferential placement and pricing power.
Pricing Analysis
Volume concentrates in large-diameter carbon steel trunk line contracts where API 5L certification serves as the baseline entry ticket, while margin accumulates in small-diameter precision tubing for automotive and aerospace applications where tight dimensional tolerances command specification premiums. Three-tier pricing structure across premium, standard, and economy levels separates mills with captive premium connection capability from commodity suppliers exposed to China mill overcapacity. Pricing pressure stems from state-supported Hebei and Jiangsu province capacity flooding export markets with below-cost line pipe. Construction sector spot purchasers exhibit highest price sensitivity; oil and gas supermajors negotiating multi-year master service agreements demonstrate lowest sensitivity due to total cost of ownership frameworks.
Supply Chain Analysis
Regional distribution centers in Houston, Rotterdam, and Singapore anchor hub-and-spoke patterns for coil feedstock and finished pipe inventory positioning. Supply concentrates in China, India, and the United States as primary manufacturing locations. Hot-rolled coil, agglomerated submerged arc flux, and premium threading equipment constitute critical input dependencies. Single-source vulnerability persists for Russian-sourced flux following supply reconfiguration, forcing mills to qualify alternative chemistries. Distribution runs through master service agreement channels for oil and gas operators and spot-market procurement for construction sector buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as API 5L and ISO 3183 certification tightening forces weaker players without inspection infrastructure or metallurgical R&D capability toward exit.
For Market Incumbents: Hedge against China mill overcapacity by securing captive electric arc furnace coil supply in low-carbon production routes eligible for EU CBAM preferential placement. Deepen backward integration into premium connection threading capability to defend against Saudi Aramco and ExxonMobil unbundling strategies that expose standalone specialists to direct price competition. Prioritize hybrid laser-arc welding qualification for Norwegian and Brazilian deepwater contractor specifications. For New Entrants and Emerging Players: German hydrogen pipeline retrofit contractors represent an underserved buyer archetype requiring embrittlement-resistant 316L weld overlays for natural gas trunk line blending compatibility. Target India's PLI scheme specialty steel segment where BIS marking mandates redirect procurement toward locally certified producers serving CEA-regulated power sector boiler tubing demand. Establish go-to-market presence through EPC contractor partnerships for refinery and petrochemical complex process piping. For Investors and Strategic Acquirers: Saudi Aramco unbundling of threading services from base pipe supply is the leading indicator that captive premium connection capability will separate acquisition-worthy targets from commodity exposure. Position for five-to-ten year viability around mills with verified low-carbon production routes and scope 3 emissions documentation systems already integrated. Watch for API 1104-qualified welding inspector wage spikes as the signal that construction cycle compression is creating labor bottlenecks favoring automated inspection technology adopters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Supply | ArcelorMittal's captive flat-rolled steel capacity insulates margin from scrap price volatility. |
| Hybrid Laser-Arc Welding Deployment | Norwegian deepwater contractors specify single-pass deposition for fatigue-critical riser joints. |
| Carbon Border Adjustment Mechanism Compliance | German automotive OEMs require embodied carbon declarations for exhaust system tubing procurement. |
| Premium Connection Threading Capability | Tenaris bundles threading services to defend against supermajor unbundling strategies. |
| India PLI Scheme Certification | BIS marking mandates redirect domestic refinery procurement toward locally certified producers. |
Methodological Framework
Trade flow databases, API certification registries, and customs documentation formed the secondary backbone, supplemented by primary interviews with pipeline procurement directors at supermajor operators, EPC contractor project managers, and electric arc furnace mill operations heads. Bottom-up and top-down triangulation validated volume estimates across product type, end user, and installation segmentation dimensions.
Bottom-up modeling anchored in individual project pipeline tracking and mill capacity utilization assessments, while top-down cross-checks drew from energy infrastructure investment databases and petrochemical complex expansion announcements. Segmentation across carbon steel, stainless steel, and alloy grades combined with diameter tier and regional regulatory cluster analysis. CAGRs derived from weighted average of historical trajectory and project-based demand forecasting, with hydrogen pipeline retrofit applications and ethylene cracker expansion timelines serving as key industry-specific inputs.
Revisions become necessary when China export policy shifts, EU CBAM implementation timing changes, or submerged arc flux supply reconfiguration accelerates beyond current alternative chemistry qualification timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
France PVC Pipes Market
Pipes and Tubes
Metal Pipe Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
Compressed Air Pipe Market
Pipes and Tubes
Gas Pipe Fittings Market
Pipes and Tubes
Germany Acid Proof Lining Market
Pipes and Tubes
Global Fiberglass Pipe Market
Pipes and Tubes
US Cold Drawn Seamless Steel Pipes Market
Pipes and Tubes
Glass Reinforced Plastic (GRP) Piping Market
Pipes and Tubes
Industrial Tubes Market
Pipes and Tubes
Spain PVC Pipes Market
Pipes and Tubes
Plastic Pipe Jointing and Welding Market
Pipes and Tubes
Global Fluoropolymer Tubing Market
Pipes and Tubes
Heat Shrink Tubing Market
Pipes and Tubes
Steel Pipe Market
Pipes and Tubes
Saudi Arabia PPR Pipes Market