
 Qatar Paper Packaging Products Market | 2026-2036
Qatar Paper Packaging Products Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Paper Packaging Products Market Intelligence
Qatar's Ministry of Municipality and Environment plastic reduction mandate is hardening compliance timelines for food retail and hospitality supply chains. Ecoleaf Packaging & Printing Co. leverages integrated design-to-print capabilities for quick-service restaurant clients. Gulf Paper Manufacturing Company anchors domestic containerboard supply with an in-house pulp and recycled fiber operation. Al Bayader International LLC differentiates through BRC-certified food-contact packaging lines serving GCC export channels.
Paper packaging products encompass corrugated containers, folding cartons, paper bags, and molded fiber trays engineered from kraft, recycled, or coated paper stocks with specified burst strengths and moisture barriers for product protection and shelf display. Boxes and cartons dominate current volume as industrial logistics and retail shelf-ready formats absorb the majority of domestic board output; e-commerce packaging is expanding fastest as last-mile delivery networks scale across Doha and Al Rayyan. Kraft paper and corrugated paper grades command the largest material share due to structural stacking performance, while coated paper captures premium food-service applications requiring grease resistance.
The Qatar General Organization for Standardization enforces product safety and fiber sourcing transparency under national standards aligned with Gulf Standardization Organization frameworks. The Ministry of Commerce and Industry monitors import quotas on finished packaging to protect domestic converting capacity. The Ministry of Municipality and Environment enforces extended producer responsibility provisions for post-consumer fiber recovery. Stakeholders must track regulatory harmonization with Saudi Standards, Metrology and Quality Organization requirements as Gulf Cooperation Council market integration deepens.
Market Dynamics
Qatar's Ministry of Municipality and Environment single-use plastic restrictions are forcing food retail and hospitality supply chains to reconfigure procurement specifications toward fiber-based alternatives within compressed compliance windows.
Growth Catalysts
- Extended Producer Responsibility mandates:The Ministry of Municipality and Environment post-consumer fiber recovery provisions create obligated demand streams for domestic converters serving food service and logistics verticals.
- E-commerce fulfillment corridor expansion:Last-mile delivery networks scaling across Doha and Al Rayyan generate structural demand for corrugated shipper formats and protective molded fiber inserts.
- Gulf Standardization Organization alignment:Harmonized product safety and fiber sourcing transparency standards reduce technical barriers for Qatar-based exporters accessing Saudi and UAE retail channels.
Market Restraints
- Containerboard input cost volatility:Recycled fiber and kraft pulp price swings compress converter margins, particularly for small-batch food-contact packaging orders.
- Domestic pulp supply concentration:Gulf Paper Manufacturing Company's captive pulp and recycled fiber operation limits alternative sourcing options for independent converters in Ras Laffan industrial zones.
- Coating technology substitution ceiling:Petroleum-derived moisture and grease barriers face technical performance gaps against plastic alternatives in hot-fill food applications.
Strategic Opportunities
- Al Wakrah warehousing cluster penetration:Cold chain and pharmaceutical logistics facilities in this southern corridor remain underserved by BRC-certified folding carton suppliers.
- Quick-service restaurant molded fiber tray adoption:Drive-through and delivery formats in Doha are converting from expanded polystyrene to bagasse and bamboo fiber alternatives.
- Import quota protection window:Ministry of Commerce and Industry finished packaging restrictions create temporary margin shelter for domestic converters investing in automated die-cutting lines.
Industry Challenges
- Food-contact certification timeline compression:BRC and Qatar General Organization for Standardization parallel audit requirements delay new product launches by converters serving GCC export channels.
- Legacy equipment integration friction:Converters retrofitting pre-2015 flexographic presses for water-based ink systems face color consistency and drying capacity constraints.
- Specialized die-making skill scarcity:Precision tooling design for high-speed corrugated converting remains concentrated among a limited pool of technicians in Doha industrial zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Paper Packaging Products Market |
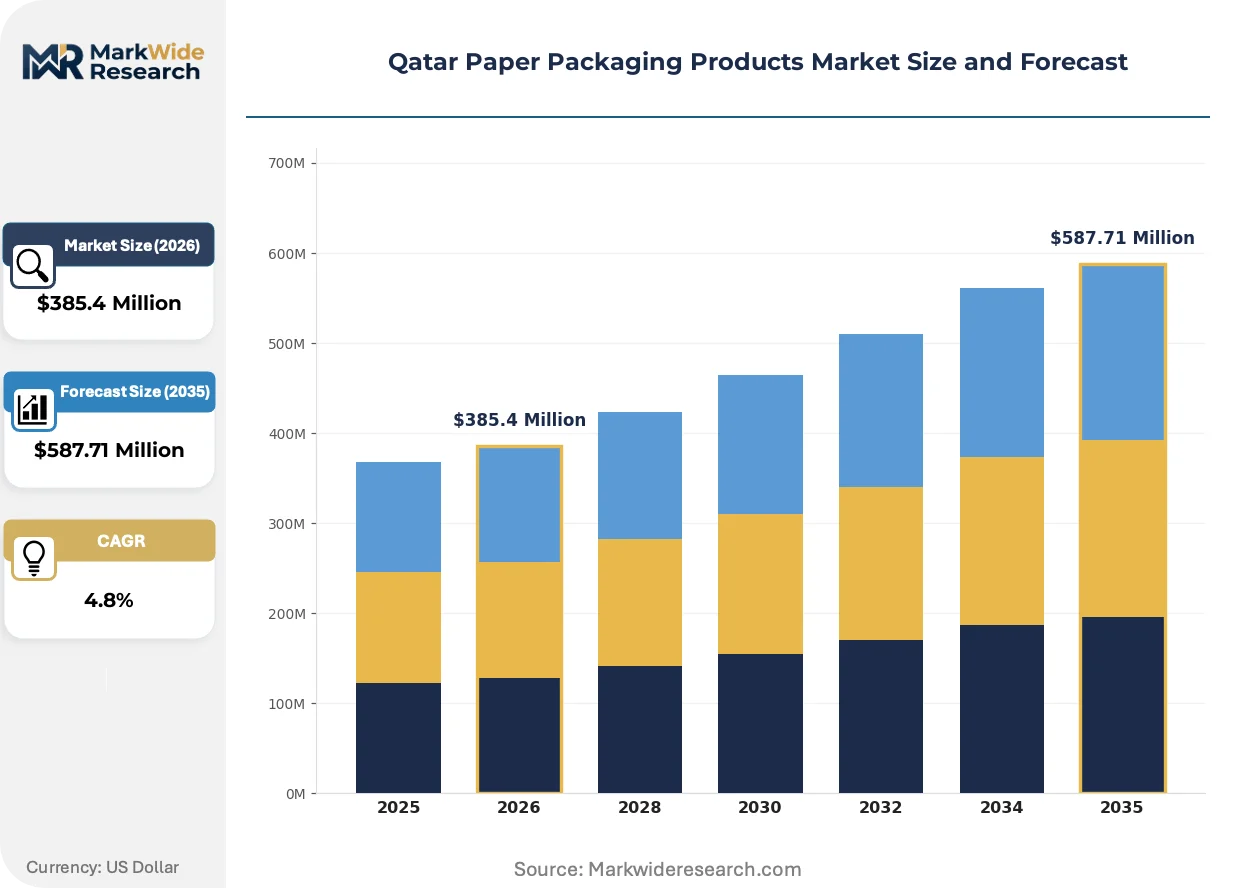
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Cartons, Trays Application: Food Packaging, Retail Packaging, Industrial Packaging, E-Commerce Packaging Material: Kraft Paper, Recycled Paper, Coated Paper, Corrugated Paper End User: Food Service, Retailers, Manufacturers, Distributors |
| Companies Covered | Ecoleaf Packaging & Printing Co., Jana International Co., Al Bayader International LLC, Qatar National Paper Company, Papercut Factory, Al Zaini Converting Industries, Golden Paper Cups Manufacturing Co. LLC, Gulf Paper Manufacturing Company, Breezpack, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Paper Packaging Products Market Strategic Shifts & Innovations
Water-based barrier coatings and digital print integration are compressing production batch minimums while expanding design flexibility for quick-turn food service packaging programs.
Barrier-coated kraft paper engineered with plant-based wax and clay laminates is absorbing moisture-protection demand from polyethylene-lined alternatives in chilled food delivery applications. Doha-based cloud kitchen operators and third-party logistics providers are specifying these formats for two-hour delivery windows. The technology is absorbing volume from legacy plastic-lined paperboard as grease-resistance performance thresholds tighten under Gulf Standardization Organization draft standards.
The Ministry of Municipality and Environment extended producer responsibility framework is mandating post-consumer fiber content minimums in food-contact packaging by 2027. Domestic converters must requalify supply chains and audit recycled fiber provenance to maintain Qatar General Organization for Standardization certification. Quick-service restaurant chains with centralized procurement are pre-emptively reformulating packaging specifications to lock compliant supply ahead of enforcement windows.
Direct-to-restaurant digital procurement platforms are disintermediating traditional distributor networks for standardized corrugated and paper bag formats. Al Rayyan and Al Wakrah food service clusters are piloting vendor-managed inventory programs with real-time consumption tracking. The shift is most visible among mid-scale restaurant groups seeking to reduce working capital tied to packaging inventory while securing volume-tier pricing.
Qatar Paper Packaging Products Market Segmentation
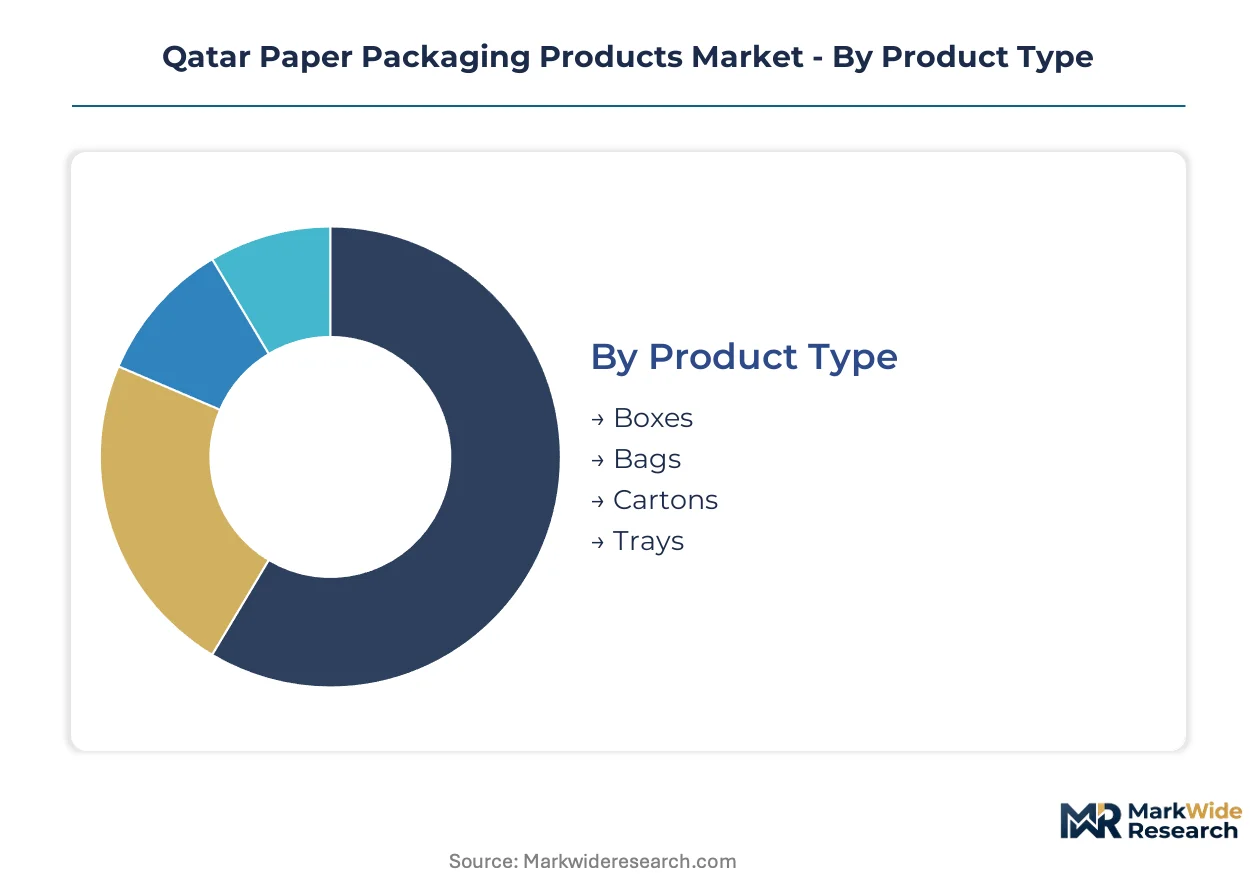
Qatar's paper packaging market segments reveal distinct procurement patterns across food service logistics and industrial supply chains. Material specifications and end-use compliance requirements drive divergent margin structures and supplier qualification barriers across each category.
Product Type:
Standalone packaging formats dominate procurement volumes, while embedded or nested configurations serve specialized protective applications.
- Boxes:Corrugated shippers and rigid containers engineered with specified burst strengths and stacking performance for industrial logistics and e-commerce fulfillment. Demand concentrates in Ras Laffan industrial zone warehousing and Doha last-mile distribution centers, driven by Ministry of Municipality and Environment plastic restriction compliance timelines for bulk goods transport.
- Bags:Flat and gusseted paper sacks with twisted or flat handles, produced from kraft or recycled fiber stocks for retail carryout and food service takeaway. Quick-service restaurant procurement in Al Wakrah and Al Rayyan corridors is converting specifications from polyethylene to fiber-based alternatives under tightened single-use plastic mandates.
- Cartons:Folding cartons with locking tabs and display windows for shelf-ready retail presentation and pharmaceutical cold chain packaging.
- Trays:Molded fiber and die-cut paperboard formats for food service presentation and protective cushioning in electronics logistics.
Boxes lead volumes today; bags are gaining share fastest.
Application:
Cost tier differentiation separates commodity logistics formats from certified food-contact and temperature-controlled packaging specifications.
- Food Packaging:Grease-resistant and moisture-barrier formats for hot-fill, chilled, and frozen food service applications, requiring BRC certification and Qatar General Organization for Standardization compliance. Doha cloud kitchen operators and drive-through chains specify these formats for delivery and takeaway windows under Ministry of Municipality and Environment extended producer responsibility provisions.
- E-Commerce Packaging:Corrugated shipper boxes, protective inserts, and void-fill systems engineered for automated sortation and last-mile handling. Al Rayyan and Al Wakrah fulfillment center expansion is driving specification demand for right-sized packaging and fiber-based protective alternatives to plastic air pillows.
- Retail Packaging:Shelf-ready cartons, display boxes, and branded carry bags for hypermarket and convenience store channels.
- Industrial Packaging:Heavy-duty corrugated and protective formats for manufacturing supply chains and chemical logistics.
Food packaging leads volumes today; e-commerce packaging is expanding most quickly.
Material:
Supply concentration around Gulf Paper Manufacturing Company's captive pulp operation shapes sourcing options and converter margin structures.
- Kraft Paper:Unbleached virgin fiber with high tear resistance and structural integrity for heavy-duty bags and protective wrapping. Industrial logistics procurement across Ras Laffan and Mesaieed manufacturing corridors specifies these grades for load-bearing applications where recycled fiber performance falls short.
- Corrugated Paper:Fluted medium and linerboard combinations engineered for stacking strength and crush resistance in shipping applications. E-commerce fulfillment networks scaling across Doha and Al Rayyan absorb the majority of domestic corrugated output for shipper and protective insert formats.
- Recycled Paper:Post-consumer fiber stocks reprocessed for molded fiber trays, secondary packaging, and non-food-contact applications.
- Coated Paper:Clay or polymer-barrier treated surfaces for premium print quality and moisture resistance in food-contact and retail display formats.
Corrugated paper leads volumes today; coated paper is climbing the fastest on food service barrier specification demand.
End User:
Customer type determines certification burden, with centralized procurement chains imposing stricter compliance than fragmented distributor networks.
- Food Service:Quick-service restaurants, cloud kitchens, catering operators, and institutional food providers requiring BRC-certified, food-contact compliant packaging with grease and moisture barriers. Centralized procurement at Doha-based restaurant groups is pre-emptively reformulating specifications to lock compliant supply ahead of Ministry of Municipality and Environment enforcement windows.
- Retailers:Hypermarkets, convenience stores, and specialty retail chains specifying shelf-ready cartons and branded carry bags for consumer-facing presentation.
- Manufacturers:Industrial producers across chemicals, pharmaceuticals, and consumer goods requiring protective and bulk transport packaging.
- Distributors:Third-party logistics providers and packaging wholesalers serving fragmented small-business demand across Qatar's commercial corridors.
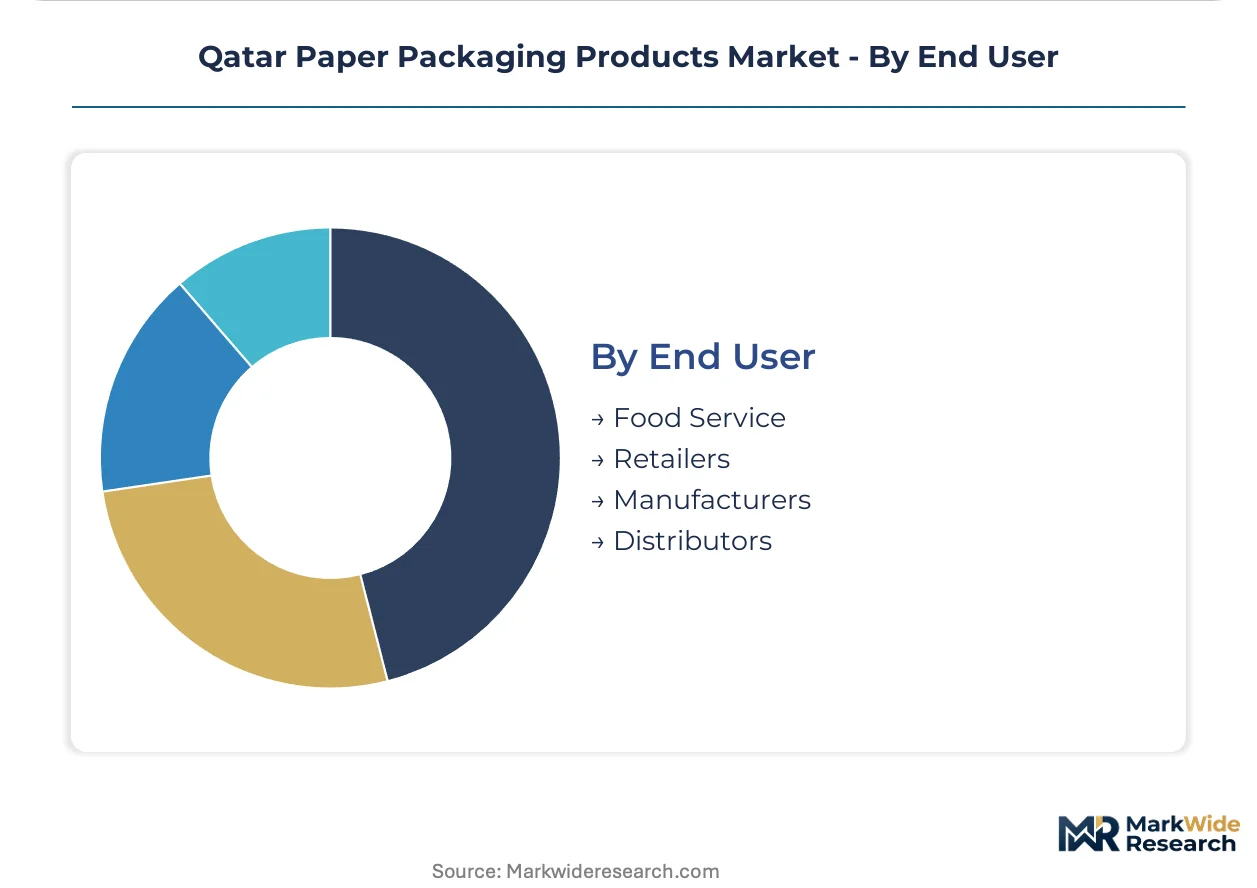
Food service leads volumes today; retailers are gaining share fastest on private-label packaging program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled converting technicians and die-making specialists cluster around Doha's industrial zones, anchoring domestic production capacity for corrugated and food-contact formats.
Doha
Cloud kitchen operators and quick-service restaurant chains drive specification demand for grease-resistant folding cartons and molded fiber trays. Qatar General Organization for Standardization certification requirements compress new product launch timelines for converters serving centralized procurement accounts. The Mesaieed and New Industrial Area corridors concentrate automated die-cutting and flexographic printing capacity for e-commerce and food service verticals.
Al Rayyan
Last-mile fulfillment networks and pharmaceutical cold chain facilities absorb corrugated shipper and protective insert volumes. Ministry of Municipality and Environment extended producer responsibility provisions mandate post-consumer fiber content minimums by 2027, forcing supply chain requalification. The warehousing clusters along Salwa Road and Industrial Area Street host vendor-managed inventory programs with real-time consumption tracking for mid-scale restaurant groups.
Al Wakrah
Third-party logistics providers and cold storage operators generate structural demand for BRC-certified folding cartons in underserved pharmaceutical corridors. Ministry of Commerce and Industry import quotas on finished packaging create temporary margin shelter for domestic converters investing in automated lines. The southern warehousing cluster around Hamad Port remains underpenetrated by certified food-contact suppliers despite expanding perishables throughput.
Ras Laffan
Petrochemical and heavy industrial logistics specify heavy-duty corrugated and protective formats with load-bearing performance requirements. Gulf Paper Manufacturing Company's captive pulp operation limits alternative sourcing options for independent converters seeking virgin fiber grades. The industrial zone's manufacturing supply chains absorb the majority of domestic kraft paper output for bulk chemical transport applications.
Qatar Paper Packaging Products Market Key Industry Players
Capital-heavy producers compete with asset-light designers across Qatar's paper packaging sector. Integrated mills with captive pulp supply anchor volume positions in containerboard and kraft grades, while independent converters specialize in quick-turn food-contact and retail display formats. Two strategic archetypes dominate: vertically integrated manufacturers controlling fiber-to-finished-goods pipelines, and agile specialists leveraging digital print and short-run flexibility. Competitive moves concentrate on automated die-cutting line investments and BRC certification acquisition for GCC export access.
Within the integrated manufacturing tier, Gulf Paper Manufacturing Company and Qatar National Paper Company occupy positions defined by captive fiber supply and scale-driven cost structures. Among specialized converters, Ecoleaf Packaging & Printing Co. and Al Bayader International LLC exemplify the design-to-print capability archetype serving quick-service restaurant and retail channels. These named entities anchor industry commentary without implying specific strategic actions or market shares beyond their evident structural positions.
| Leading Market Players |
|---|
| Ecoleaf Packaging & Printing Co. |
| Jana International Co. |
| Al Bayader International LLC |
| Qatar National Paper Company |
| Papercut Factory |
| Al Zaini Converting Industries |
| Golden Paper Cups Manufacturing Co. LLC |
| Gulf Paper Manufacturing Company |
| Breezpack |
| Others |
Cost & Logistics Intelligence
Die-making specialists concentrated in Doha's New Industrial Area command wage premiums that compress margins for small-batch converters while widening spreads between premium BRC-certified food-contact lines and economy-grade logistics formats. Labor-cost differentials between certified precision technicians and general converting operators translate directly into tiered pricing structures across Qatar's paper packaging sector.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates BRC-certified food-contact packaging with Gulf Paper Manufacturing Company captive fiber supply from standard-grade corrugated formats and import-dependent economy lines. Price differentiation hinges on certification grade and vertical integration depth, with Gulf Paper Manufacturing Company's in-house pulp operation insulating premium tiers from recycled fiber cost swings. Cost compression in standard-grade corrugated is intensifying because Ministry of Commerce and Industry import quotas on finished packaging create temporary shelter for domestic converters investing in automated die-cutting lines. Quick-service restaurant chains with centralized procurement exhibit lowest price sensitivity due to compliance-driven specification lock-in, while fragmented distributor-served small businesses in Al Wakrah commercial corridors remain most price-sensitive.
Supply Chain Analysis
Post-consumer fiber recovery flows under Ministry of Municipality and Environment extended producer responsibility provisions are creating reverse-logistics infrastructure requirements that domestic converters must absorb into cost structures. Virgin pulp supply concentrates in Qatar through Gulf Paper Manufacturing Company's captive operation, while recycled fiber sourcing draws from UAE and Saudi Arabian reprocessing facilities. Raw material dependencies rest on kraft pulp imports, clay barrier coatings, and water-based ink chemistries. Single-source vulnerability around Gulf Paper Manufacturing Company's fiber supply creates structural risk for independent converters in Ras Laffan industrial zones. Distribution runs through third-party logistics providers and direct-to-restaurant digital procurement platforms disintermediating traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's paper packaging sector functions as a geographic-arbitrage play where Gulf Standardization Organization harmonization allows domestic converters to access Saudi and UAE retail channels at lower regulatory compliance cost than European or Asian exporters.
For Market Incumbents: Extend BRC certification coverage into Al Wakrah pharmaceutical cold chain corridors before specialized competitors establish footholds. Add automated die-cutting capacity in Mesaieed industrial zones to capture volume-tier pricing from mid-scale restaurant groups shifting to vendor-managed inventory programs. Gulf Paper Manufacturing Company's captive fiber supply advantage must be leveraged to compress delivery timelines for quick-service restaurant chains facing Ministry of Municipality and Environment compliance deadlines.
For New Entrants and Emerging Players: Water-based barrier coating technology offers entry wedge into Doha cloud kitchen grease-resistant packaging specifications where incumbent converters rely on legacy petroleum-derived moisture barriers. Target Al Wakrah cold storage and pharmaceutical logistics facilities remain underserved by BRC-certified folding carton suppliers despite expanding perishables throughput through Hamad Port. Go-to-market angle should emphasize direct digital procurement platform integration with real-time consumption tracking for mid-scale restaurant groups.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent converters with design-to-print capabilities but without captive fiber supply, as input cost volatility compresses near-term margins while Gulf Paper Manufacturing Company integration premium expands. Long-term viability framing centers on 5-10 year Gulf Cooperation Council market integration deepening and extended producer responsibility enforcement hardening compliance barriers. Acquisition target archetype: agile specialists with digital print integration and existing Qatar General Organization for Standardization certification. Signal to watch: Ministry of Commerce and Industry import quota relaxation timeline as indicator of competitive pressure inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| BRC Certification Acquisition | Unlocks GCC export access to Saudi Standards, Metrology and Quality Organization regulated retail channels. |
| Automated Die-Cutting Line Investment | Captures volume-tier pricing from Doha restaurant groups under Ministry of Commerce and Industry quota protection. |
| Water-Based Barrier Coating Development | Absorbs grease-resistance demand from polyethylene-lined alternatives under Gulf Standardization Organization draft standards. |
| Vendor-Managed Inventory Partnership | Reduces working capital burden for Al Rayyan mid-scale restaurant clusters through real-time consumption tracking. |
| Post-Consumer Fiber Supply Requalification | Maintains Qatar General Organization for Standardization certification under Ministry of Municipality and Environment 2027 content minimums. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at Ras Laffan industrial zone converters, procurement leads at Doha-based quick-service restaurant chains, distribution channel partners in Al Wakrah warehousing clusters, and technical R&D directors at barrier coating suppliers with secondary validation. Secondary sources included Qatar General Organization for Standardization regulatory filings, Ministry of Municipality and Environment enforcement documentation, Gulf Standardization Organization harmonization protocols, and customs records on finished packaging imports. Bottom-up volume estimates from converter capacity utilization triangulated against top-down demand aggregation from food service and logistics verticals.
Historical reference periods anchored the projection horizon to pre-enforcement baselines and initial plastic restriction implementation phases, with modeled segmentation spanning product type, application vertical, material grade, and end-user procurement structure. CAGRs derived from slope analysis of segment-specific volume trajectories calibrated against input cost elasticity and regulatory compliance timeline acceleration. Industry-specific forecast inputs included Ministry of Municipality and Environment extended producer responsibility phase-in schedules and e-commerce fulfillment center buildout pipelines across Doha and Al Rayyan.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Gulf Paper Manufacturing Company capacity expansion decisions and Gulf Cooperation Council tariff harmonization negotiations. Forecasts reflect documented assumptions on regulatory enforcement intensity and fiber input cost trajectories. Practitioners should monitor Ministry of Commerce and Industry import quota announcements and Qatar General Organization for Standardization audit backlog indicators for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Machine Glazed Kraft Paper Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Japan Paper Packaging Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Ultraflute Paper Market
Paper & Paperboard Packaging
Global Multi Depth Corrugated Boxes Market
Paper & Paperboard Packaging
Display Paper Box Market
Paper & Paperboard Packaging
Vietnam Paper Packaging Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Paper Band Market
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Paper Coaster Market
Paper & Paperboard Packaging
Recycled Paper Packaging Market